
 Global Automotive Gasket and Seal Market | 2026-2036
Global Automotive Gasket and Seal Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Gasket and Seal Market Analysis
Electric vehicle OEMs are reorganizing supplier qualification protocols around thermal-interface sealing and battery-pack ingress protection. Freudenberg Sealing Technologies leverages its fluoroelastomer compound library to anchor high-voltage sealing contracts with European EV platforms. Parker Hannifin Corporation competes through integrated motion-and-seal system architectures that extend its industrial fluid-power expertise into electrified drivetrains. ElringKlinger AG specializes in metal-elastomer composite gaskets for fuel-cell stacks, positioning its German manufacturing base at the center of hydrogen powertrain development.
Automotive gaskets and seals are precision-engineered static and dynamic closure devices, typically manufactured from rubber compounds, stamped metals, or fiber-reinforced composites, designed to maintain fluid or gas containment under cyclic pressure and temperature loads between mating surfaces. Their primary commercial purpose is to guarantee functional integrity of powertrain, thermal-management, and emission-control systems while minimizing warranty exposure from leakage-related failures. Metal-composite gasket architectures dominate engine applications where combustion pressures exceed 150 bar, while rubber O-rings capture the fastest growth trajectory in battery thermal-management circuits where coolant compatibility with ethylene-glycol blends is non-negotiable. Aftermarket channels for seals and gaskets retain durable margin pools due to fleet-aging dynamics and the fragmented, price-sensitive repair-shop landscape across mature vehicle parcs.
The US EPA and NHTSA coordinate Corporate Average Fuel Economy and emission standards that directly dictate seal durability testing protocols for engine and exhaust-system suppliers. REACH and the EU F-Gas Regulation constrain fluoropolymer feedstock availability, forcing compounders to validate alternative elastomer formulations or absorb higher base-material costs. China's GB standards and MIIT new-energy-vehicle technical rules impose localized testing and certification requirements that filter market access for non-domestic seal producers. Stakeholders must monitor regulatory divergence between emission-reduction timelines and material-restriction frameworks when situating R&D and production assets.
Market Dynamics
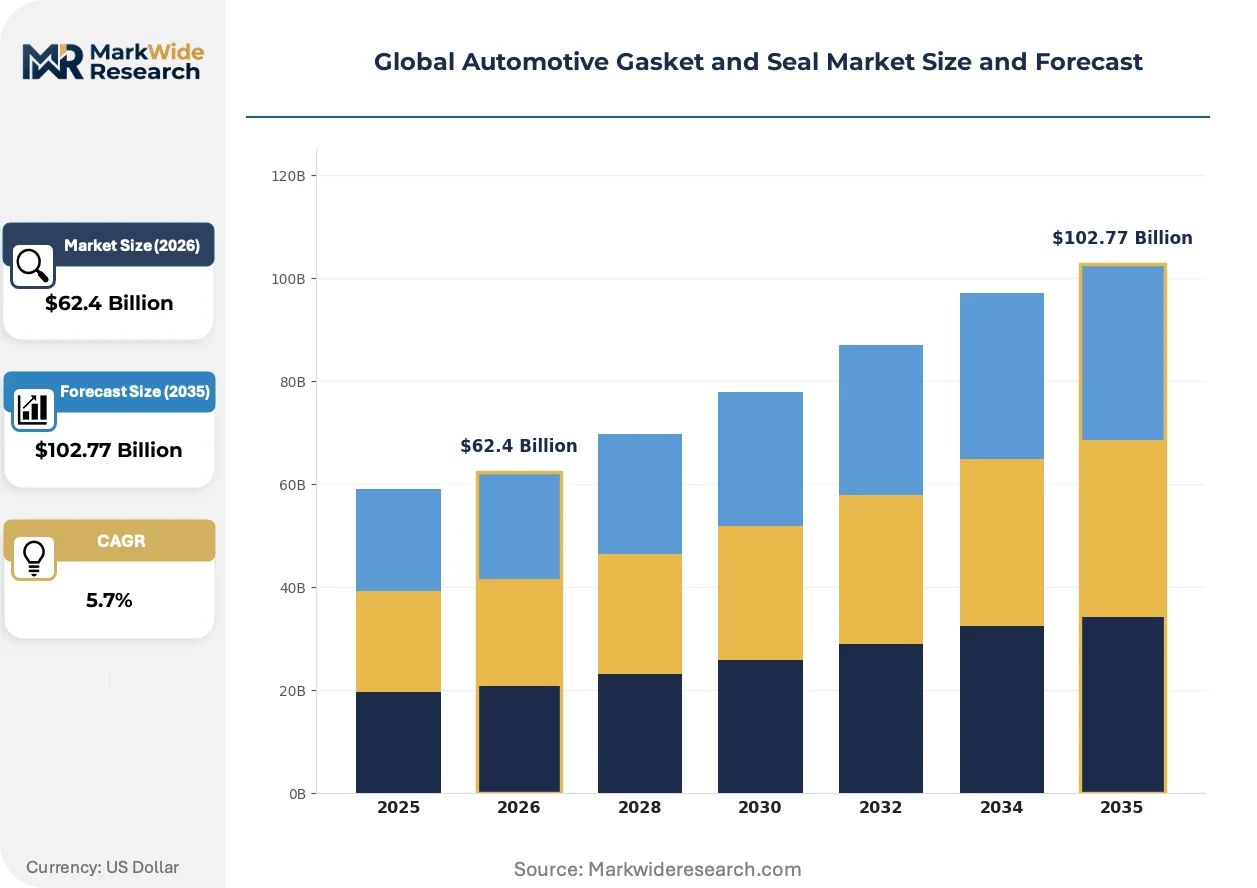
Powertrain electrification is compressing supplier validation cycles while simultaneously fragmenting material specifications across thermal-management, battery-pack, and fuel-cell sealing architectures. OEMs now demand parallel qualification tracks for combustion and electric platforms, forcing compounders to maintain dual R&D streams without volume guarantees from either.
Growth Catalysts
- EU F-Gas Regulation phase-down:Fluoropolymer scarcity is accelerating validation of hydrogenated nitrile and ethylene-acrylate alternatives for high-temperature engine seals, opening formulation contracts to non-incumbent compounders.
- China MIIT NEV technical rules:Localized ingress-protection testing mandates for battery packs are concentrating domestic procurement with certified suppliers, creating captive demand pools for compliant seal producers.
- Metal-elastomer composites:Fuel-cell stack manufacturers require multi-layer gasket architectures that bond stamped stainless steel with precision-molded elastomer beads, driving specialized tooling investments.
Market Restraints
- Fluoroelastomer feedstock concentration:Three chemical conglomerates control global FKM polymer supply, exposing seal manufacturers to price volatility when REACH restrictions tighten raw-material availability.
- Cylinder-head gasket durability thresholds:Combustion pressures above 180 bar in downsized turbocharged engines exceed the fatigue limits of fiber-reinforced composites, forcing continued reliance on expensive multi-layer steel architectures.
- Extended EV platform lifecycles:Battery-electric vehicle architectures freeze sealing specifications for 7-10 years, compressing aftermarket replacement demand compared to internal-combustion parc turnover.
Strategic Opportunities
- India automotive production expansion:Maruti Suzuki and Tata Motors are localizing powertrain manufacturing, creating demand for seal suppliers willing to establish compounding operations near Chennai and Pune industrial corridors.
- Thermal-interface materials convergence:Battery pack designers are integrating phase-change materials with liquid-coolant sealing, requiring suppliers to master both elastomer chemistry and thermal-conductivity engineering.
- US Inflation Reduction Act domestic content rules:Battery component sourcing incentives are pulling seal production back to North American manufacturing zones, rewarding early facility commitments.
Industry Challenges
- Multi-physics simulation talent scarcity:Fewer than two dozen specialized engineers globally can simultaneously model fluid-structure interaction, thermal cycling, and chemical degradation in sealing interfaces.
- Euro 7 certification timeline compression:OEMs require complete leakage-rate validation data within 18-month windows, straining testing-lab capacity and compressing design iteration cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Gasket and Seal Market |
| Market Size in 2026 | $62.4 Billion |
| Market Size in 2035 | $102.77 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: O-Rings, Gaskets, Seals, Diaphragms Material: Rubber, Metal, Plastic, Composites Application: Engine, Transmission, Exhaust, Cooling Systems End User: OEMs, Aftermarket, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Trelleborg AB, SKF Group, Freudenberg Sealing Technologies, Garlock Sealing Technologies, Parker Hannifin Corporation, ElringKlinger AG, Federal-Mogul Corporation, John Crane, Dana Holding Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Gasket and Seal Market Emerging Trajectories
Material science advances and regulatory chemistry restrictions are converging to reshape competitive positioning in high-performance sealing. Suppliers must now validate alternatives to legacy fluoropolymer formulations while maintaining performance parity under extreme thermal and pressure loads.
Perfluoroelastomer compounds with tailored glass-transition temperatures are fragmenting the high-voltage sealing market. Battery OEMs specify these materials for junction-box and coolant-line interfaces where ethylene-glycol compatibility and electrical insulation must coexist. Parker Hannifin and Freudenberg are deploying compound libraries developed for semiconductor fabrication to automotive thermal-management contracts, compressing margins for generalist rubber molders.
REACH authorization requirements for per- and polyfluoroalkyl substances are forcing reformulation of cylinder-head gasket coatings. European compounders must submit alternative chemistries for ECHA review by 2026, with interim supply chain disruptions already visible in specialty lubricant-additive availability. German OEMs are accelerating qualification of graphite-based release coatings to preempt regulatory friction.
Consolidated procurement desks at Volkswagen Group and Stellantis are unbundling seal sourcing from historical tiered supply hierarchies. Direct material-specification authority now rests with platform chief engineers, compressing the traditional Tier-1 intermediary role. Japanese keiretsu suppliers are responding by offering integrated thermal-management modules that internalize sealing functions, visible in Toyota's bZ battery platform sourcing structure.
Global Automotive Gasket and Seal Market Segmentation
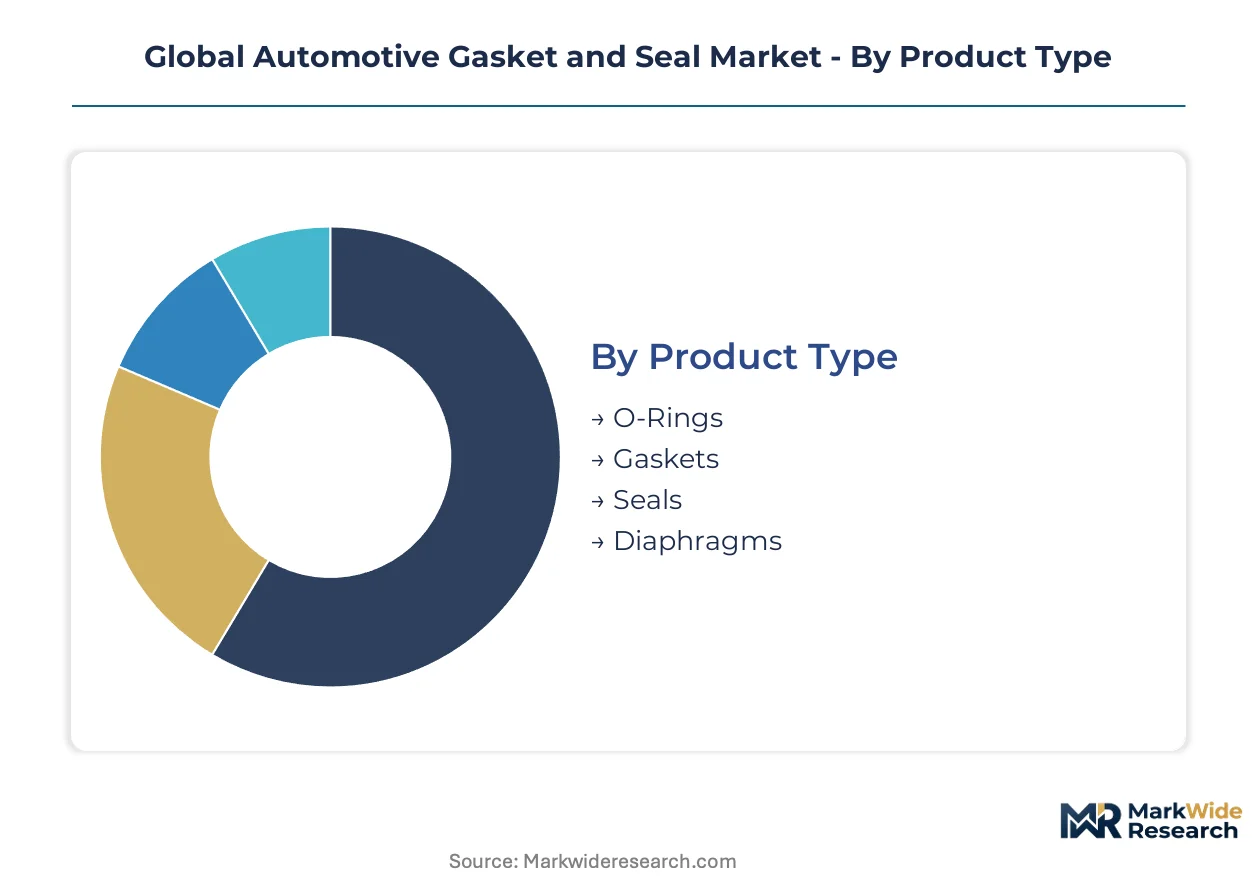
Segmentation in the automotive gasket and seal market reveals divergent technical requirements across electrification pathways. OEM procurement teams now qualify suppliers against parallel combustion and battery-electric specifications, fragmenting volume concentration and margin structures.
Product Type:
Substitution pressure from integrated module designs threatens standalone sealing components most acutely in battery-pack architectures, where multi-function thermal-interface assemblies absorb traditional discrete seal roles.
- O-Rings:Circular elastomer profiles compressed into grooves to prevent fluid or gas leakage under radial or axial loads. Demand concentrates in battery thermal-management circuits across Germany and Japan, where ethylene-glycol coolant compatibility requirements disqualify generalist compounders.
- Gaskets:Static sealing elements manufactured from stamped metals, fiber composites, or elastomer-coated substrates to maintain pressure containment between mating flanges. Cylinder-head applications in downsized turbocharged engines from Stuttgart and Detroit engineering centers sustain multi-layer steel specification dominance despite cost premiums.
- Seals:Dynamic closure devices accommodating rotational or reciprocating motion while maintaining lubricant retention and contaminant exclusion.
- Diaphragms:Flexible membrane elements transmitting pressure or motion in pneumatic and hydraulic actuation systems.
Gaskets anchor the volume base while O-Rings gain share at the steepest rate.
Material:
Cost tier stratification separates commodity elastomer formulations from engineered compounds commanding qualification premiums in high-voltage and fuel-cell applications.
- Rubber:Elastomer formulations spanning natural rubber, nitrile, hydrogenated nitrile, ethylene-acrylate, and fluoroelastomer chemistries tailored to fluid compatibility and temperature exposure. Hydrogenated nitrile alternatives displace fluoropolymer content in EU-bound engine seals as REACH phase-downs tighten feedstock availability.
- Metal:Stamped stainless steel, carbon steel, and coated alloys forming structural gasket cores or standalone sealing surfaces. Multi-layer steel architectures from Japanese and German stamping operations capture fuel-cell stack contracts requiring precision-compression characteristics.
- Plastic:Thermoplastic and thermoset polymer formulations for low-pressure, chemically resistant sealing environments.
- Composites:Fiber-reinforced elastomer or metal-elastomer hybrid constructions combining structural rigidity with conformable sealing surfaces.
Metal formulations dominate revenue concentration while rubber compounds expand most quickly through thermal-management diversification.
Application:
Application-based demand distribution tracks powertrain electrification intensity across OEM engineering centers, with thermal-management circuits displacing traditional engine-bay specification volumes.
- Engine:Cylinder-head, intake manifold, oil pan, and front-cover sealing applications subject to combustion pressures, thermal cycling, and chemical exposure. Combustion pressures exceeding 180 bar in Stuttgart-developed downsized turbocharged engines force continued reliance on expensive multi-layer steel gasket architectures.
- Transmission:Gearbox sealing for fluid retention, pressure maintenance, and contaminant exclusion across manual, automatic, and electrified driveline configurations. Dual-clutch and e-axle programs in Munich and Toyota City sustain demand for high-speed rotary seal specifications.
- Exhaust:Emission-control system sealing for turbocharger interfaces, EGR circuits, and aftertreatment modules.
- Cooling Systems:Radiator, heater core, and battery-pack thermal-management sealing for coolant and refrigerant containment.
Engine applications retain the largest installed base while cooling systems climb the fastest on battery-electric vehicle penetration.
End User:
Customer-type segmentation exposes divergent procurement authority structures, with platform chief engineers at consolidated OEMs disintermediating traditional tiered supply hierarchies.
- OEMs:Original equipment manufacturers specifying seal materials and architectures at platform level, increasingly unbundling sourcing from historical Tier-1 intermediaries. Volkswagen Group and Stellantis procurement desks in Wolfsburg and Amsterdam now direct material qualification authority to powertrain engineering centers.
- Aftermarket:Independent repair channels and service networks supplying replacement seals for vehicle parc maintenance. Fleet-aging dynamics across the United States sustain durable margin pools despite price-sensitive repair-shop fragmentation.
- Vehicle Assemblers:Contract manufacturing operations assembling complete vehicles or major subsystems under OEM direction.
- Tier-1 Suppliers:Integrated system suppliers incorporating seals into larger powertrain, thermal-management, or emission-control modules.
OEMs command specification authority while aftermarket channels defend margin stability through parc-aging economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European seal logistics, while the Shanghai Yangshan Deep Water Port handles the largest volume of elastomer feedstock imports for Asian compounding operations. These maritime gateways underwrite regional manufacturing specialization in precision sealing components.
United States
Detroit's powertrain engineering centers drive multi-layer steel gasket specifications for downsized turbocharged engines. The EPA and NHTSA coordinate Corporate Average Fuel Economy standards that dictate seal durability testing protocols. Michigan-based stamping operations supply cylinder-head architectures to domestic OEM validation cycles.
Germany
Stuttgart and Munich anchor OEM qualification protocols for both combustion and electric powertrain sealing. The EU F-Gas Regulation and REACH authorization requirements constrain fluoropolymer feedstock availability for compounders. Baden-Württemberg manufacturing clusters specialize in metal-elastomer composites for fuel-cell stack applications.
China
MIIT new-energy-vehicle technical rules impose localized ingress-protection testing mandates for battery-pack seals. The Yangtze River Delta concentrates domestic procurement with certified suppliers near Shanghai. GB standards filter market access for non-domestic seal producers seeking NEV platform contracts.
Japan
Toyota City and Nagoya sustain demand for high-speed rotary seal specifications in dual-clutch and e-axle programs. METI industrial policy supports hydrogen powertrain development requiring specialized fuel-cell gasket architectures. Japanese keiretsu suppliers offer integrated thermal-management modules that internalize sealing functions.
India
Maruti Suzuki and Tata Motors localize powertrain manufacturing near Chennai and Pune industrial corridors. BIS standards govern material certification for automotive sealing components. Tamil Nadu and Maharashtra industrial zones attract seal suppliers establishing compounding operations to serve domestic OEM procurement desks.
Global Automotive Gasket and Seal Market Vendor Landscape
Concentration sits with diversified industrial conglomerates possessing captive elastomer compounding capabilities and precision metal stamping operations. The vendor base spans three tiers: integrated motion-and-seal system architects, specialized metal-elastomer composite fabricators, and regional rubber molding operations serving aftermarket channels. Strategic moves center on backward integration into fluoropolymer feedstock sourcing and geographic expansion through joint ventures with domestic compounders in high-growth vehicle production zones.
Among European sealing specialists, Freudenberg Sealing Technologies and ElringKlinger AG occupy positions defined by proximity to German OEM engineering centers. Parker Hannifin Corporation exemplifies the industrial conglomerate archetype, leveraging fluid-power expertise across electrified drivetrain applications. These three entities represent distinct competitive vectors: compound library depth, fuel-cell specialization, and integrated system architecture respectively.
| Leading Market Players |
|---|
| Trelleborg AB |
| SKF Group |
| Freudenberg Sealing Technologies |
| Garlock Sealing Technologies |
| Parker Hannifin Corporation |
| ElringKlinger AG |
| Federal-Mogul Corporation |
| John Crane |
| Dana Holding Corporation |
| Others |
Supply Flow & Price Mechanics
EU REACH authorization requirements for per- and polyfluoroalkyl substances simultaneously gate supplier qualification and stratify price tiers, forcing compounders to absorb reformulation costs or pass them downstream to OEM procurement desks. This regulatory architecture concentrates pricing power with incumbents possessing validated alternative chemistries while squeezing margins for generalist molders locked into legacy fluoropolymer supply contracts.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates validated fluoroelastomer compounds from hydrogenated nitrile alternatives and commodity rubber formulations. Price differentiation rests on REACH compliance certification and OEM platform qualification status rather than raw material cost alone. Cost compression in standard-tier engine seals is intensifying because Tier-1 suppliers face dual R&D streams without volume guarantees from either combustion or electric platforms. Fleet operators and independent repair shops exhibit the highest price sensitivity, while German OEM engineering centers prioritize performance validation over unit cost.
Supply Chain Analysis
Inventory buffers for fluoropolymer feedstock have compressed to eight-week horizons as three chemical conglomerates control global FKM polymer supply. Raw material sourcing draws from German specialty chemical operations, Japanese fluoroelastomer compounding facilities, and Chinese hydrogenated nitrile production clusters. Single-source vulnerability in high-performance elastomer feedstock exposes seal manufacturers to price volatility when regulatory restrictions tighten availability. Distribution runs through Tier-1 system integrators in Stuttgart, Detroit, and Toyota City before reaching OEM platform engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a regulatory-entrenchment story where REACH compliance and OEM qualification protocols create switching costs that lock out unvalidated competitors. The defensive moat widens as Euro 7 and China's MIIT NEV rules compress certification timelines beyond the reach of resource-constrained entrants.
For Market Incumbents: Secure captive fluoroelastomer feedstock arrangements through backward integration or long-term offtake contracts before REACH phase-downs intensify raw-material scarcity. Fortify German and Japanese engineering center relationships by embedding technical staff within OEM platform teams to accelerate qualification cycles and preempt substitute material trials.
For New Entrants and Emerging Players: Aftermarket thermal-management seal refurbishment for aging European and North American vehicle parcs represents the most penetrable white space where OEM qualification barriers do not apply. Target battery-pack ingress-protection testing services as a service-layer entry point, leveraging China's MIIT certification requirements to build domestic regulatory expertise before expanding into compound supply.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across fuel-cell stack gasket manufacturing as multi-layer metal-elastomer tooling requirements escalate. Five-to-ten-year viability favors compounders with demonstrated hydrogen powertrain traction over generalist rubber molders. Watch for OEM unbundling announcements at Volkswagen Group or Stellantis as signals that direct material-specification authority is shifting toward platform chief engineers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Feedstock | Mitigates REACH supply risk for Freudenberg and Parker Hannifin compound libraries. |
| Fuel-Cell Stack Gasket Manufacturing Scale-Up | Positions ElringKlinger to capture Baden-Württemberg hydrogen powertrain contracts. |
| India Compounding Joint Venture | Maruti Suzuki localization demands near-Chennai seal production for domestic content compliance. |
| Thermal-Interface Material Convergence R&D | Battery pack designers at Toyota City require phase-change material integration expertise. |
| Aftermarket Channel Control Expansion | Fleet-aging economics in the United States sustain margin pools for independent repair networks. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs/trade data, vehicle production databases, SEC 10-K filings, and IHS Markit registration data across OEM and Tier-1 supplier operations. Interviews with platform engineers at Stuttgart and Detroit engineering centers, Tier-1 procurement leads, aftermarket distributors, and compounder R&D directors informed demand-side assumptions. Bottom-up volume triangulation from vehicle production forecasts and content-per-vehicle estimates was cross-checked against top-down market sizing from trade flow analysis.
Segmentation dimensions modeled span propulsion architecture, material chemistry tier, application thermal load, and regional regulatory cluster across the projection horizon. CAGRs were derived from elasticity-adjusted volume forecasts incorporating OEM platform lifecycle transitions. Industry-specific inputs include battery-electric vehicle penetration curves, Euro 7 leakage-rate threshold implementation timing, and fluoroelastomer feedstock availability scenarios from ECHA regulatory filings.
Underlying assumptions cover OEM qualification timeline compression and REACH alternative-chemistry validation success, with deviation risk concentrated in regulatory delay or faster-than-expected fuel-cell commercialization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Engine Cam Cover Market
Automotive Parts
Variable Valve Timing (VVT) Market
Automotive Parts
Europe Motorcycle Parts and Accessories Market
Automotive Parts
Suspension Bump Stopper Market
Automotive Parts
Engine Bearings Market
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Argentina Automotive Parts Aluminium Die Casting Market
Automotive Parts
Fuel Injection Cleaning Machine Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Aluminum Parts Gravity Die Casting Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Automotive Spacer Ring Market
Automotive Parts
Automotive Hydroformed Parts Market
Automotive Parts
Thin-Section Ball Bearings Market
Automotive Parts
Global Aerodynamic Automotive Market