
 Automotive Trim Part Market | 2026-2036
Automotive Trim Part Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Trim Part Market Insights
The split between premium cabin experiences and cost-optimized commodity interiors is recalibrating procurement priorities across the supply base. Grupo Antolin leverages its vertical integration in soft trim to sustain margin pools in leather-wrapped cockpit modules. Toyota Boshoku Corporation anchors its position through R&D intensity in acoustic and thermal management materials for electrified platforms.
Automotive trim parts encompass decorative and functional interior and exterior components manufactured through injection molding, thermoforming, compression molding, and slush molding processes using polymers, natural fibers, metals, and coated textiles to enhance occupant comfort, vehicle aesthetics, and brand differentiation. Dashboard assemblies and door panels dominate value contribution due to their surface area and electronics integration requirements, while center console segments capture expanding margin pools from wireless charging and human-machine interface embedding. Plastic and leather materials lead volume, though fabric alternatives are gaining ground in sustainability-driven procurement.
EPA, NHTSA, and EU REACH frameworks shape material selection, recyclability mandates, and volatile organic compound emissions limits that directly alter supplier qualification criteria. OEMs and Tier-1 suppliers must monitor regulatory divergence between North American fuel economy rules and European chemical restrictions when configuring global trim platforms. Stakeholders should prioritize material passport traceability and biobased feedstock qualification to maintain access across regulatory jurisdictions.
Market Dynamics
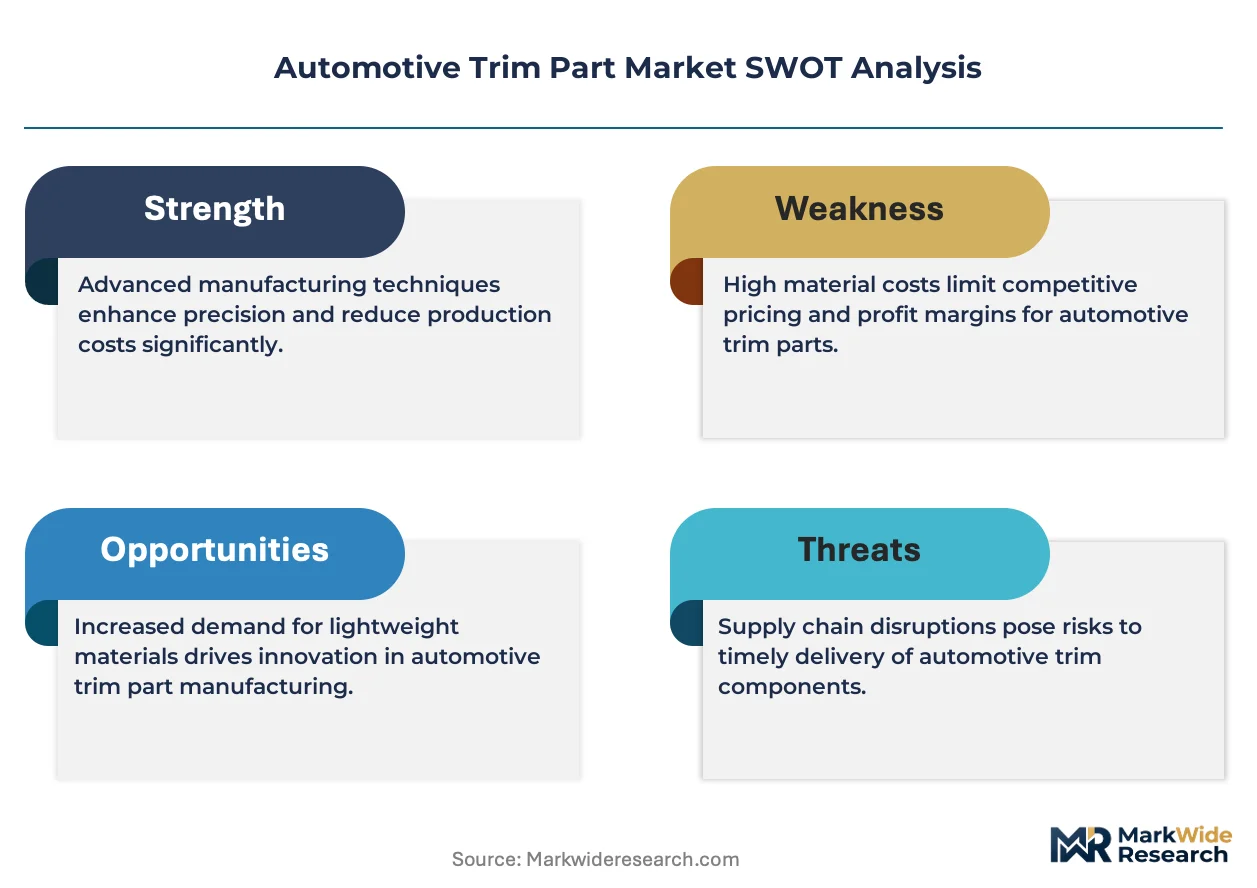
Lightweighting mandates for electrified platforms are compressing material specifications across cockpit and exterior assemblies, forcing suppliers to requalify polymers and natural fiber composites under tighter thermal and acoustic performance thresholds.
Growth Catalysts
- EPA Fuel Economy Standards:Corporate Average Fuel Economy targets drive substitution of metal trim with recycled polymer alternatives in door panels and dashboard carriers across Detroit Three platforms.
- China Cabin Quality Upgrades:Domestic OEMs and joint ventures in the Chinese market are upgrading soft-touch surfaces and ambient lighting systems to compete with European and Korean import interiors.
- Slush Molding Advancement:Improved surface finish capabilities in thermoplastic elastomer slush molding enable cost-competitive leather-grain aesthetics for mass-market instrument panels.
Market Restraints
- Polypropylene Feedstock Volatility:Propylene monomer price swings compress margin pools for injection-molded interior components, particularly in commodity door panel and pillar trim segments.
- Tooling Concentration in East Asia:Mold fabrication capacity concentrates in Chinese and Korean supplier networks, creating lead time vulnerability for North American and European trim platform launches.
- REACH Chemical Restrictions:EU ECHA substance candidate list expansions limit phthalate plasticizer options for PVC skin applications, forcing reformulation cycles that delay program approvals.
Strategic Opportunities
- India Premiumization Wave:Maruti Suzuki and Hyundai Motor India are expanding local leather-wrapped steering wheel and shift boot capacity to capture ascending middle-class buyers.
- Wireless Charging Integration:Center console architectures are embedding inductive charging pads and cooled storage, creating new margin pools from electronics-thermoplastics convergence.
- EU Green Deal Procurement:Biobased polyamide and recycled carbon fiber qualification under EU taxonomy criteria opens preferential sourcing channels for sustainable trim platforms.
Industry Challenges
- Acoustic Engineer Scarcity:Electrified powertrains expose road and wind noise that legacy NVH materials cannot absorb, yet qualified acoustic polymer formulation talent remains concentrated at Tier-1 suppliers.
- Homologation Timeline Compression:Dual certification to NHTSA FMVSS 302 flammability and EU 95/28/EC burning behavior standards extends validation cycles for global platform trim suppliers.
- Legacy Press Integration:Compression molding equipment for natural fiber composites requires retrofitting to achieve cycle times compatible with high-volume automotive sequencing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Trim Part Market |
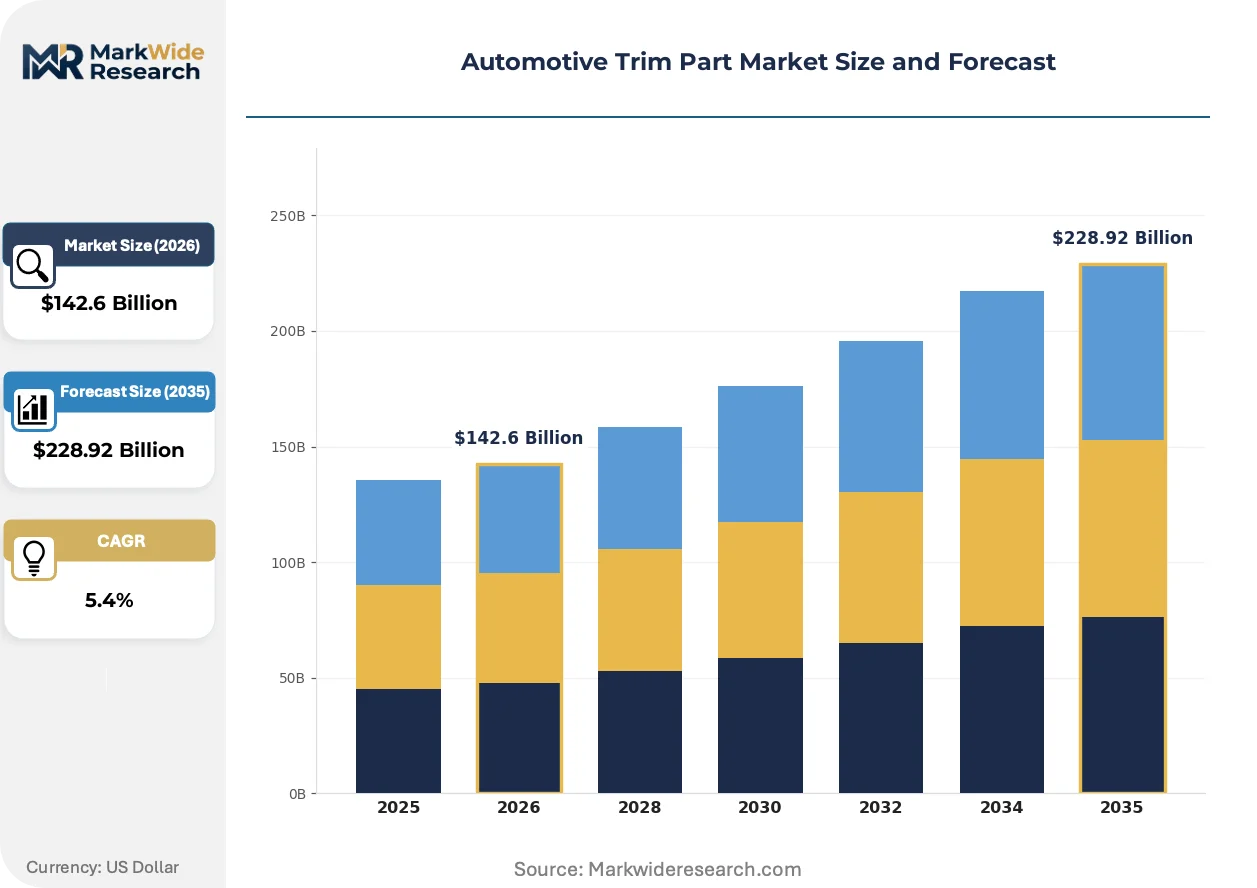
| Market Size in 2026 | $142.6 Billion |
| Market Size in 2035 | $228.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dashboard, Door Panel, Center Console, Bumper Material: Plastic, Leather, Fabric, Metal End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Design Complexity: Simplistic, Intermediate, Complex, Customized |
| Companies Covered | International Automotive Components (IAC) Group, Grupo Antolin, Faurecia, Magna International, Toyota Boshoku Corporation, Lear Corporation, Yanfeng Automotive Interiors, Adient, Continental AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Trim Part Market Trends and Innovations
Digital manufacturing and closed-loop material systems are converging to redefine how trim suppliers manage surface quality, regulatory compliance, and end-of-life recovery obligations across global production networks.
Automated optical inspection systems are automating defect detection in leather and synthetic hide slush-molded skins, enabling Tier-1 suppliers to reduce manual sorting labor while maintaining Class A surface standards for visible cockpit components. BMW Group and Mercedes-Benz AG have deployed these systems at their seating and instrument panel supply bases. This technology is automating quality gate throughput, compressing inspection cycle times from hours to minutes for high-mix trim configurations.
EU REACH Annex XVII restrictions on intentionally added microplastics are forcing reformulation of polyurethane spray coatings used on steering wheels and armrests, with ECHA enforcement timelines accelerating supplier transition to waterborne alternatives. The regulation's industrial consequence falls heaviest on Italian and Spanish trim specialists serving premium European OEMs, who must revalidate tactile durability under accelerated weathering protocols before 2027 compliance deadlines.
Fleet procurement departments at ride-hailing operators are unbundling interior durability specifications from OEM standard catalogs, demanding accelerated wear testing for seat fabrics and touch surfaces that exceed private-vehicle duty cycles. This specification divergence is creating parallel trim product lines at suppliers like Adient and Lear Corporation, with distinct material stacks for high-utilization commercial interiors versus retail passenger vehicles. The behavioral shift is most visible in North American and European urban mobility markets where Uber and Lyft fleet aggregators command direct supplier negotiations.
Automotive Trim Part Market Segmentation
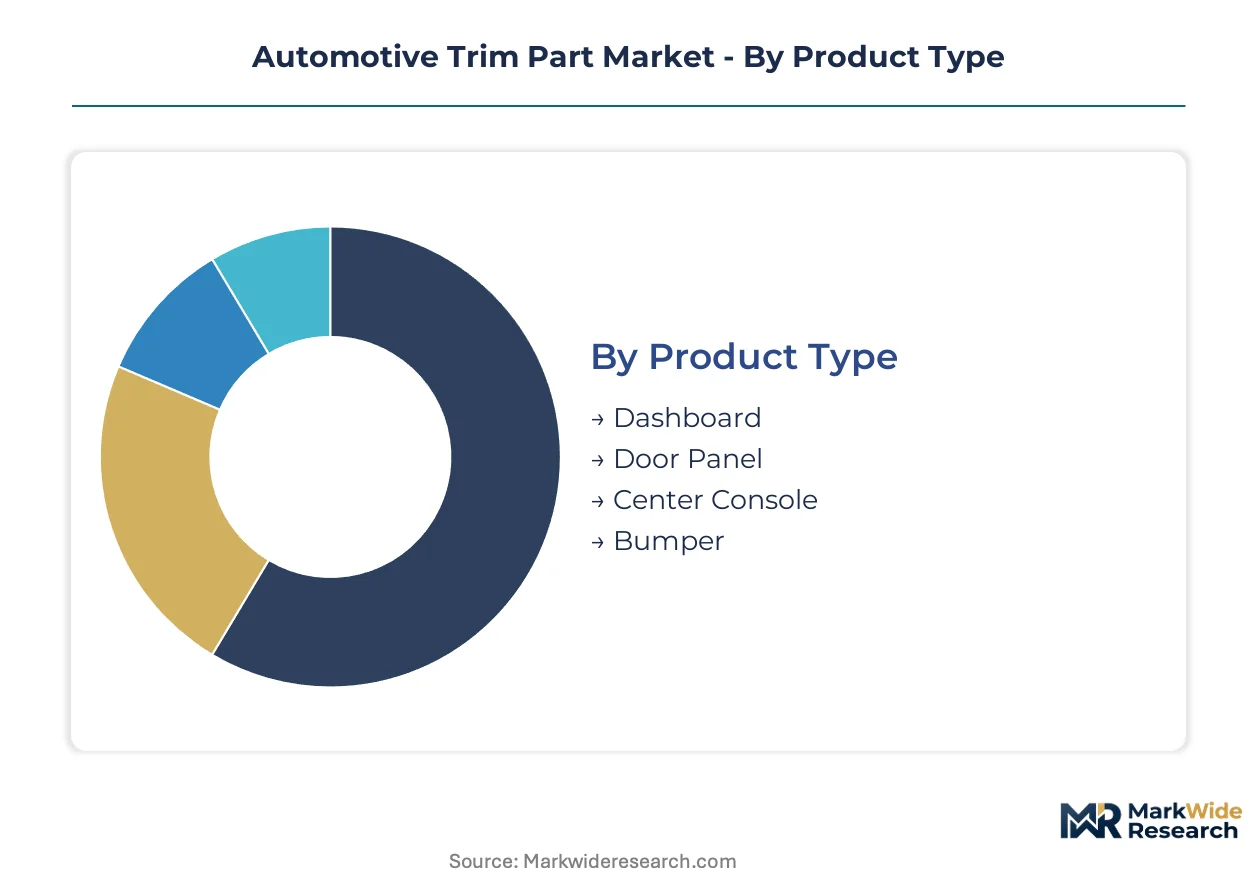
Segmentation in automotive trim parts reveals how procurement priorities diverge between visible cabin surfaces and hidden structural carriers. Understanding these splits helps suppliers align R&D investments with where OEMs concentrate cost and quality differentiation.
Product Type:
Standalone modules command premium engineering resources while embedded subassemblies integrate deeper into vehicle electronics architectures.
- Dashboard:Large-surface instrument panel assemblies integrate airbag housings, HVAC vents, and infotainment bezels in slush-molded TPO or leather-wrapped substrates. Demand clusters in China where domestic OEMs upgrade soft-touch finishes to match European import interiors.
- Door Panel:Upper and lower trim sections combine decorative skins with map pocket structures and armrest substrates, absorbing the highest polymer volumes in passenger cabins. Detroit Three platforms are substituting metal carriers with recycled polypropylene alternatives under EPA fuel economy mandates.
- Center Console:Shifter surrounds and cup holder assemblies.
- Bumper:Exterior fascias and lower cladding components.
Volume placements concentrate in Door Panel; the faster expansion belongs to Dashboard.
Material:
Cost tiers separate commodity feedstocks from specification-grade alternatives that carry regulatory compliance burdens.
- Plastic:Polypropylene, ABS, and polycarbonate blends dominate injection-molded interior carriers through cost efficiency and design flexibility. REACH Annex XVII restrictions on phthalate plasticizers are forcing PVC skin reformulations that delay program approvals at Italian and Spanish trim specialists.
- Leather:Full-grain and corrected-grain hides deliver premium tactile surfaces for steering wheels, shift boots, and seat bolsters. Maruti Suzuki and Hyundai Motor India are expanding local leather-wrapped capacity to capture ascending middle-class buyers.
- Fabric:Woven and knitted textiles for seat inserts and headliners.
- Metal:Aluminum and steel stampings for structural reinforcement.
Plastic captures the highest shipment volumes; leather gains share fastest in premium cabin configurations.
End User:
Customer type determines whether trim parts flow through captive supply chains or open market distribution.
- OEMs:Vehicle manufacturers specifying complete cockpit modules through direct supplier contracts.
- Aftermarket Providers:Independent distributors serving collision repair and customization channels.
- Vehicle Assemblers:Contract manufacturing operations integrating trim at final assembly.
- Tier-1 Suppliers:Antolin, Toyota Boshoku, and Lear Corporation managing subsystem delivery to multiple OEM platforms.
Tier-1 Suppliers manage the greatest contract value; Aftermarket Providers show the steepest expansion trajectory in fleet refurbishment.
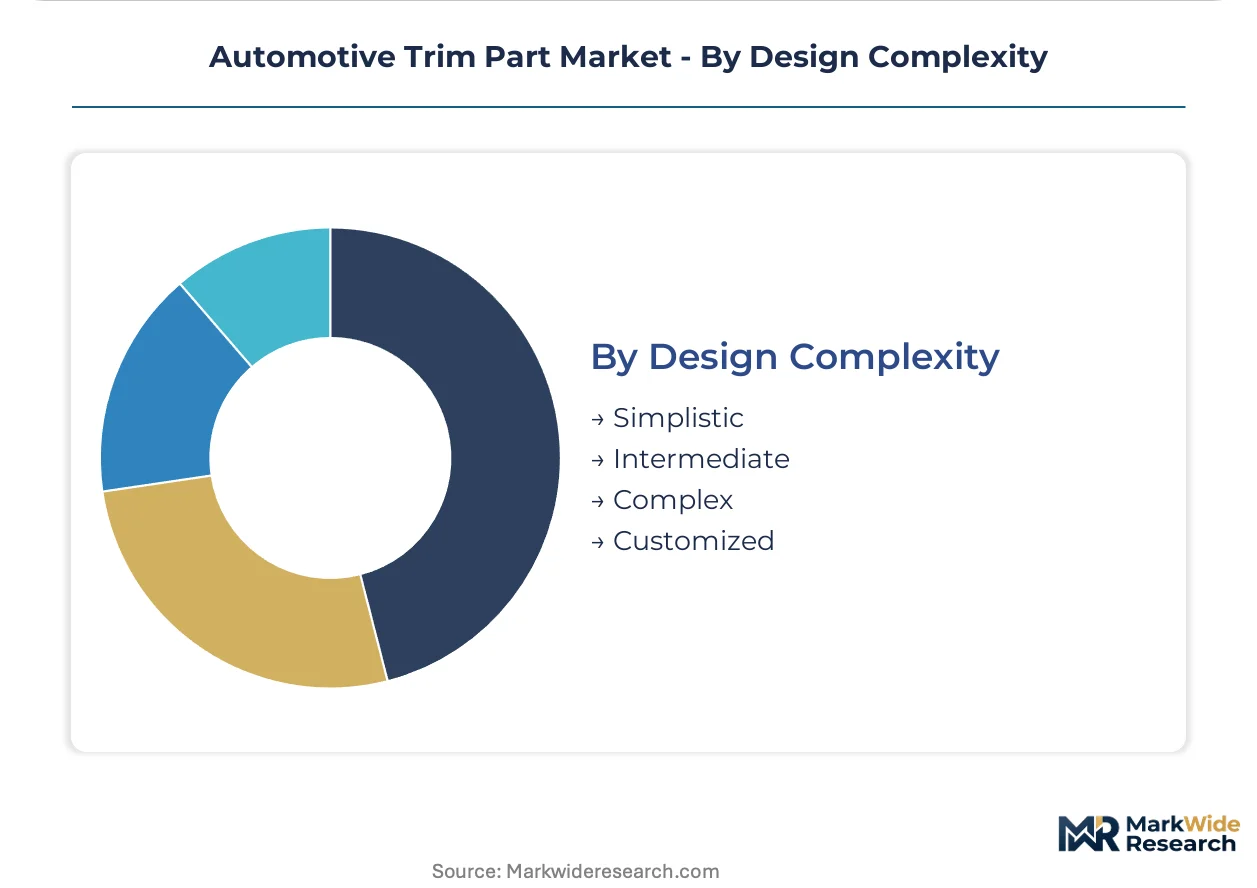
Design Complexity:
Engineering intensity scales with surface visibility and functional integration requirements.
- Simplistic:Single-material covers and basic geometric forms for hidden pillar trim and under-dash panels.
- Intermediate:Multi-component assemblies combining soft-touch surfaces with structural substrates.
- Complex:Integrated modules embedding lighting, sensors, and human-machine interfaces.
- Customized:Bespoke configurations for limited-production vehicles and fleet-specific durability specifications demanded by Uber and Lyft procurement departments.
Intermediate designs absorb the majority of engineering hours; Customized segments are climbing the fastest as mobility fleets unbundle from OEM standard catalogs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Detroit anchors North American trim production through the Michigan-Ontario corridor, where EPA Corporate Average Fuel Economy mandates drive recycled polymer substitution in door panels and dashboard carriers.
China
Domestic OEMs and joint ventures upgrade soft-touch surfaces and ambient lighting systems to match European import interiors. MIIT dual carbon goals accelerate lightweight material qualification in cockpit modules. Shanghai and Guangzhou clusters concentrate slush-molding capacity for instrument panel skin production.
Germany
Premium OEMs deploy automated optical inspection systems at seating and instrument panel supply bases to maintain Class A surface standards. EU REACH Annex XVII restrictions on phthalate plasticizers force PVC skin reformulations. Stuttgart and Munich corridors host acoustic polymer formulation talent for electrified platforms.
United States
NHTSA FMVSS 302 flammability standards compress homologation timelines for global platform trim suppliers. Ride-hailing fleet procurement departments unbundle durability specifications from OEM catalogs. Southeast assembly corridors expand capacity for high-utilization commercial interior configurations.
India
Maruti Suzuki and Hyundai Motor India expand local leather-wrapped steering wheel and shift boot capacity for ascending middle-class buyers. BIS quality mandates tighten supplier qualification criteria. Tamil Nadu and Gujarat industrial corridors attract Tier-1 subsystem investments.
South Korea
Hyundai-Kia platforms integrate wireless charging and cooled storage into center console architectures. MFDS-aligned material traceability requirements shape biobased feedstock procurement. Busan-Ulsan manufacturing clusters specialize in thermoplastic elastomer surface finishing.
Automotive Trim Part Market Competitive Landscape
Premium-margin players sit above commodity-margin players across material sophistication and regulatory compliance capability. The supplier base organizes into three tiers: integrated cockpit module specialists, component-focused fabricators, and regional injection molders. Two strategic archetypes dominate competitive positioning—backward-integrated soft trim producers controlling leather-wrapped surface supply, and R&D-intensive acoustic material formulators serving electrified platforms. Consolidation concentrates among cockpit module integrators, while fragmentation persists in commodity door panel and pillar trim segments. Geographic expansion and technology licensing represent the dominant competitive moves as suppliers seek to qualify recycled polymer formulations across multiple regulatory jurisdictions.
Among the named participants, Grupo Antolin and Toyota Boshoku Corporation occupy distinct archetype positions within the competitive structure. Grupo Antolin exemplifies the backward-integrated soft trim specialist with captive control over leather-wrapped surface production. Toyota Boshoku Corporation represents the R&D-intensive material formulator anchored in acoustic and thermal management technologies for battery-electric platforms. Lear Corporation sits within the scale-driven module integration tier, managing subsystem delivery across multiple OEM platforms. These three companies illustrate how competitive positioning stratifies across integration depth, material specialization, and global platform coverage rather than geographic origin alone.
| Leading Market Players |
|---|
| International Automotive Components (IAC) Group |
| Grupo Antolin |
| Faurecia |
| Magna International |
| Toyota Boshoku Corporation |
| Lear Corporation |
| Yanfeng Automotive Interiors |
| Adient |
| Continental AG |
| Others |
Pricing and Supply Chain Analysis
Propylene monomer feedstock costs cascade through injection-molded interior component pricing, compressing margin pools for commodity door panel and pillar trim suppliers while concentrating value capture among leather-wrapped cockpit module specialists with captive hide processing.
Pricing Analysis
Surface finish quality anchors value-based pricing tiers across slush-molded instrument panel skins, with Class A tactile standards commanding premium placement against commodity TPO alternatives. Price differentiation separates REACH-compliant biobased formulations from legacy phthalate-plasticized PVC skins facing regulatory obsolescence. Cost compression in recycled polypropylene carriers is intensifying because Detroit Three platforms are substituting metal substrates under EPA fuel economy mandates. Fleet procurement departments at ride-hailing operators exhibit the highest price sensitivity, demanding accelerated wear specifications at volume scale, while premium OEMs remain least sensitive to leather-wrapped steering wheel and shift boot premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand for complete cockpit module assemblies, while aftermarket distributors serve collision repair and fleet refurbishment segments through independent networks. Tooling fabrication capacity concentrates in China, South Korea, and Taiwan, creating lead time vulnerability for North American and European platform launches. Polypropylene resin, leather hides, and thermoplastic elastomer pellets constitute the critical input trinity, with supply anchored in petrochemical complexes and tannery clusters across East Asia and South America. Single-source vulnerability concentrates in mold fabrication networks, where Chinese and Korean supplier dominance exposes trim platform launches to geopolitical disruption and logistics chokepoint risk.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH Annex XVII chemical restrictions erect a compliance moat that favors incumbent suppliers with qualified biobased feedstock portfolios and material passport traceability systems, marginalizing commodity molders lacking reformulation R&D capacity.
For Market Incumbents: Extend acoustic polymer formulation capabilities to capture electrified platform thermal management demand, while consolidating leather-wrapped surface production through backward integration into hide processing. Threat substitution from natural fiber composite alternatives demands capacity retrofitting for compression molding cycle time compatibility. Certification investment in EU taxonomy-aligned recycled carbon fiber qualification represents the priority lever for preferential sourcing channel access. For New Entrants and Emerging Players: Tier-2 subsystem suppliers present the most penetrable channel partner type for wireless charging-embedded center console architectures, offering electronics-thermoplastics convergence without incumbent cockpit module integration burden. White-space targets concentrate in India premiumization wave leather-wrapped capacity and fleet-specific durability specification unbundling from OEM standard catalogs. A go-to-market angle anchored in rapid prototype tooling for high-mix mobility fleet configurations bypasses incumbent scale advantages. For Investors and Strategic Acquirers: ECHA enforcement timeline acceleration for waterborne polyurethane spray coating alternatives is the leading indicator that Italian and Spanish trim specialist distress will create acquisition opportunities ahead of 2027 compliance deadlines. Long-term viability over the analysis window favors backward-integrated soft trim producers with captive leather supply and acoustic material formulators serving battery-electric thermal management demand. The acquisition target archetype combines REACH-compliant formulation libraries with OEM platform qualification depth. Signal to monitor: fleet procurement department direct supplier negotiation mandates at Uber and Lyft aggregators.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Material Reformulation | ECHA Annex XVII restrictions force PVC skin transitions ahead of 2027 enforcement timelines. |
| Wireless Charging Module Integration | Center console architectures embed inductive pads and cooled storage for electronics-thermoplastics margin capture. |
| Automated Optical Inspection Deployment | BMW Group and Mercedes-Benz AG suppliers compress Class A surface quality gate cycle times. |
| Natural Fiber Composite Capacity Retrofit | Compression molding equipment upgrades achieve high-volume automotive sequencing compatibility. |
| India Leather-Wrapped Capacity Expansion | Maruti Suzuki and Hyundai Motor India localize steering wheel and shift boot production for ascending middle-class demand. |
Research Methodology
Vehicle production databases, IHS Markit registration data, and SEC filings from listed Tier-1 suppliers formed the secondary backbone, cross-referenced with customs records on polymer resin trade flows and EPA fuel economy compliance documentation. Primary interviews with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributors, and dealership operations specialists validated demand assumptions and pricing dynamics. Bottom-up and top-down triangulation reconciled segment-level shipment estimates with aggregate market value outputs.
Bottom-up modeling anchored forecasts in content-per-vehicle analysis across dashboard, door panel, and center console assemblies, segmented by propulsion architecture, vehicle class, and regional production cluster. Top-down validation drew from macroeconomic automotive production outlooks and OEM platform launch schedules. CAGRs were derived from fitted growth curves across the projection horizon, with electrification penetration rates and lightweighting intensity serving as primary demand drivers. Sensitivity analysis tested recycled polymer substitution elasticity against metal carrier retention scenarios.
Caveats apply where polypropylene feedstock volatility, REACH regulatory expansion timelines, or tooling capacity relocation patterns could materially shift the outlook. Forecasts reflect assumptions on OEM platform standardization trajectories and fleet procurement specification divergence durability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
US Automotive Airfilters Market
Automotive Parts
UK Automotive Actuators Market
Automotive Parts
Car Rack Market
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
Rammer Market
Automotive Parts
Automotive Coolant Pump Market
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Automotive Electric Parking Brakes Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Global Climate Control System for Commercial Vehicle Market
Automotive Parts
Automotive Piston Engine System Market
Automotive Parts
Italy Automotive Parts Zinc Die Casting Market
Automotive Parts
Industrial Roller Chain Drives Market
Automotive Parts
Electromagnetic Clutches Market