
 Europe Automotive Aftermarket Spare Parts Market | 2026-2036
Europe Automotive Aftermarket Spare Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Aftermarket Spare Parts Market Insights
Subscription-based predictive maintenance programs are repositioning how spare parts reach end users, bundling component replacement with remote vehicle monitoring. Robert Bosch GmbH leverages its diagnostic software ecosystem to anchor recurring parts revenue streams. Continental AG sustains competitive density through in-house production of sensor-integrated brake modules. Valeo Group specializes in thermal management parts that align with electrified powertrain service needs.
Europe automotive aftermarket spare parts comprise replacement components, consumables, and repair assemblies manufactured to original or equivalent specifications for vehicles post-initial sale. These parts must meet ISO 9001 quality management and ECE R90 brake lining standards to ensure functional parity with original equipment. Brake parts and filters retain the largest volume share as high-wear categories with predictable replacement cycles. Electrical components represent the fastest-expanding margin pool as advanced driver-assistance systems proliferate across European vehicle fleets. Passenger cars dominate vehicle-type demand, though heavy trucks generate superior per-unit parts value due to extended duty cycles.
REACH and RoHS frameworks restrict hazardous substances in coatings and electronic components, forcing suppliers to reformulate materials or sacrifice market access. The EU Green Deal's circular economy mandates accelerate remanufacturing certification requirements across member states. ECE regulations administered by national type-approval authorities govern lighting and braking component interoperability. Stakeholders must weigh compliance investment against the fragmentation risk from divergent national enforcement timelines.
Market Dynamics
The EU Green Deal's circular economy mandates are compressing remanufacturing certification timelines while fleet operators accelerate procurement of sensor-integrated components. This dual pressure from policy pull and buyer sophistication is restructuring supplier competitive positioning across the region.
Growth Catalysts
- REACH substance restrictions:Hazardous material bans in coatings are forcing incumbent suppliers to reformulate product lines, opening procurement slots for compliant alternatives in brake and electrical categories.
- Fleet telematics penetration:Connected vehicle platforms enable predictive parts replacement scheduling, converting unplanned maintenance into contracted recurring revenue streams for authorized service networks.
- Poland and Romania:Vehicle fleet density in these markets is expanding faster than Western European saturation rates, creating distribution infrastructure investment incentives for parts suppliers.
Market Restraints
- Rare earth magnet supply:Permanent magnet dependencies for electric motor remanufacturing concentrate in single-source geographies, exposing sensor-integrated drivetrain parts to input cost volatility.
- ECE R90 type-approval fragmentation:Divergent national enforcement timelines across member states force suppliers to maintain multiple brake lining certification pathways, inflating compliance overhead.
- 3D-printed polymer substitutes:Additive manufacturing of non-structural interior and trim components threatens volume-based business models in low-wear replacement categories.
Strategic Opportunities
- Bulgaria and Croatia:Authorized service center networks remain underpenetrated relative to vehicle parc density, offering first-mover advantages for diagnostic-enabled parts distribution partnerships.
- F-Gas Regulation phase-down:Thermal management component suppliers can capture retrofit demand from independent repair shops seeking compliant refrigerant handling equipment and replacement parts.
- AI-driven inventory forecasting:Machine learning convergence with legacy warehouse management systems enables independent distributors to match OEM-tier fill rates without captive manufacturing assets.
Industry Challenges
- ADAS calibration technician scarcity:Sensor-integrated brake and steering modules require specialized diagnostic competencies that vocational training pipelines have not scaled to match replacement part complexity.
- Remanufacturing certification timelines:ISO 14001 environmental management and EU-specific circular economy verification processes extend new product introduction cycles by twelve to eighteen months.
- Legacy vehicle CAN bus incompatibility:Pre-2015 vehicle fleets lack standardized diagnostic ports, fragmenting software-enabled parts strategies across incompatible electrical architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Aftermarket Spare Parts Market |
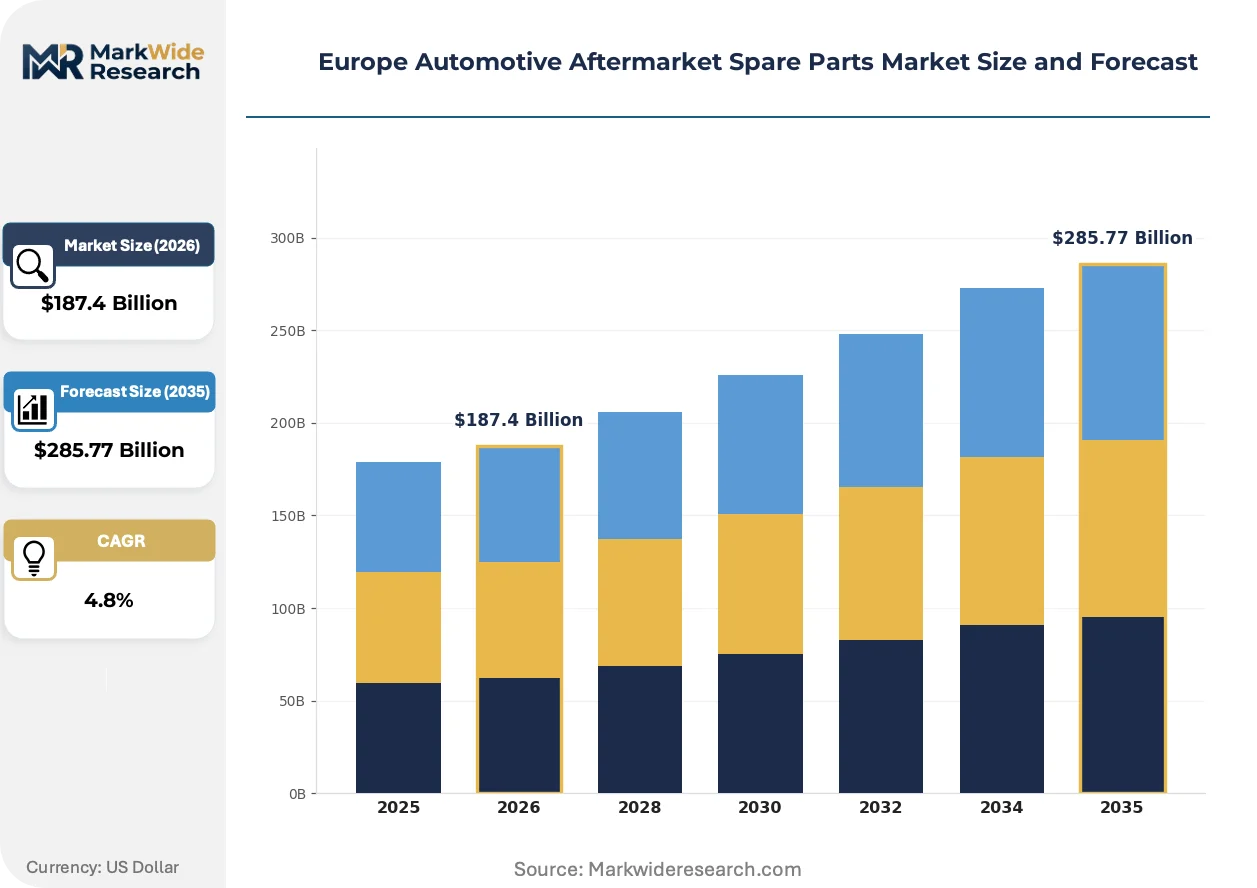
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $285.77 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Part Type: Brake Parts, Filters, Exhaust Systems, Electrical Components Distribution Channel: Online Retail, Brick-and-Mortar Stores, Wholesale Distributors, Direct Sales Vehicle Type: Passenger Cars, Commercial Vehicles, Two-Wheelers, Heavy Trucks Service Type: Maintenance Services, Repair Services, Customization Services, Performance Enhancements |
| Companies Covered | HELLA KGaA Hueck & Co., Forvia, Continental AG, Aptiv PLC, Mahle GmbH, Robert Bosch GmbH, Valeo Group, ThyssenKrupp AG, ZF Friedrichshafen AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Aftermarket Spare Parts Market Trends and Innovations
Digital diagnostics integration is compressing traditional parts distribution hierarchies while regulatory material bans force simultaneous product reformulation. These intersecting pressures favor suppliers with captive software ecosystems and reformulated material portfolios.
Sensor-integrated brake modules embed wear-state telemetry directly into friction material substrates. Fleet operators with predictive maintenance contracts are adopting these components at twice the rate of independent retail buyers. This telemetry-enabled hardware is overtaking conventional passive brake pads in commercial vehicle procurement specifications.
EU F-Gas Regulation mandates an eighty percent reduction in fluorinated greenhouse gas emissions by 2030. Thermal management suppliers must redesign compressor seals, hoses, and service couplings for alternative refrigerant chemistries. Independent repair shops in Germany and France face the steepest retooling requirements due to dense air-conditioning service volumes.
Subscription-based parts bundling replaces transactional component sales with contracted replacement schedules tied to remote vehicle monitoring. Authorized service centers in Italy and Spain are consolidating procurement through these programs, displacing traditional wholesale distributor relationships. Fleet operators with centralized maintenance budgets demonstrate the strongest preference for this model.
Europe Automotive Aftermarket Spare Parts Market Segmentation
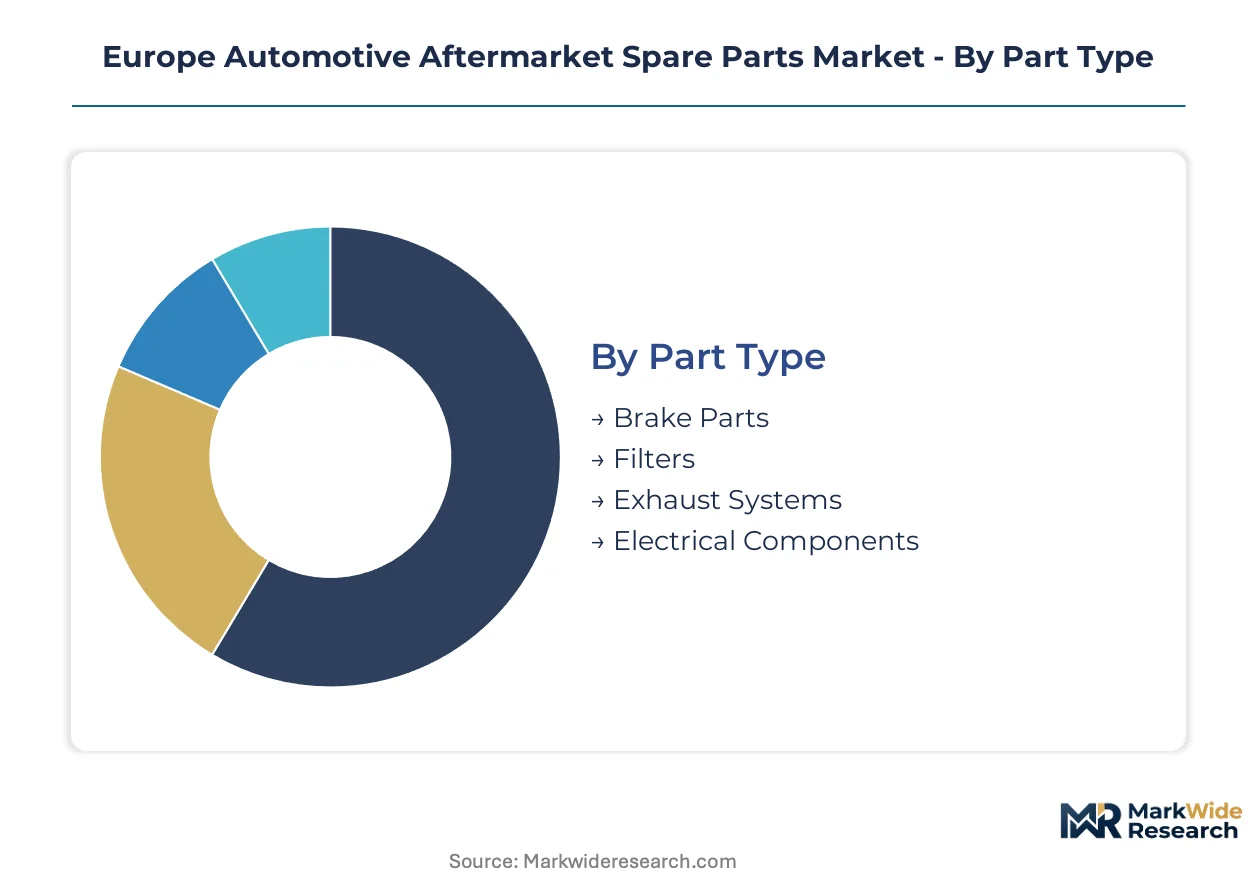
Spare parts procurement patterns in Europe diverge sharply across vehicle duty cycles and service delivery models. Understanding these fault lines reveals where diagnostic-enabled components displace conventional replacements and where distribution infrastructure investments yield captive channel control.
Part Type:
Replacement-cycle intensity and regulatory compliance burden determine margin architecture across component categories.
- Brake Parts:Friction materials and hydraulic assemblies face mandatory ECE R90 type-approval for aftermarket circulation in Germany and France. Fleet operators with predictive maintenance contracts specify sensor-integrated brake modules at accelerating rates, compressing traditional passive pad volumes.
- Filters:Engine air, oil, and cabin filtration elements retain the highest replacement frequency with predictable 10,000-15,000 kilometer service intervals. Independent repair shops in Italy and Spain consolidate procurement through subscription programs, displacing spot-market purchasing.
- Exhaust Systems:Catalytic converters and diesel particulate filters confront tightening EURO 7 emission verification requirements.
- Electrical Components:Sensor arrays and control modules for advanced driver-assistance systems demand specialized calibration competencies scarce in vocational training pipelines.
Volume placements concentrate in Filters; the faster expansion belongs to Electrical Components.
Distribution Channel:
Channel selection reflects buyer sophistication tiers and the urgency of diagnostic data integration.
- Online Retail:Digital platforms capture growing share in standardized consumables where specification clarity eliminates physical inspection needs. Poland and Romania show steepest channel shift as fleet density expands faster than traditional distribution infrastructure.
- Brick-and-Mortar Stores:Counter-based purchasing retains dominance in emergency repair scenarios requiring immediate component verification.
- Wholesale Distributors:Independent networks face margin compression from subscription-based bundling programs anchored by authorized service centers.
- Direct Sales:Component manufacturers bypass intermediaries for high-volume fleet contracts with centralized procurement functions.
Procurement gravity rests with Wholesale Distributors; channel share is climbing fastest in Online Retail.
Vehicle Type:
Per-unit parts value and electrification exposure differentiate service opportunity profiles.
- Passenger Cars:Densest vehicle parc generates absolute volume but confronts electrification-driven powertrain simplification. Battery electric vehicle thermal management parts represent emerging margin pools distinct from internal combustion legacy categories.
- Commercial Vehicles:Extended duty cycles and centralized fleet maintenance create superior contract value for predictive parts programs.
- Two-Wheelers:Fragmented owner base and lower per-vehicle service spend limit organized channel development.
- Heavy Trucks:Telematics penetration enables remote diagnostics with highest parts revenue per vehicle kilometer operated.
Absolute volumes aggregate in Passenger Cars; value expansion is steepest in Heavy Trucks.
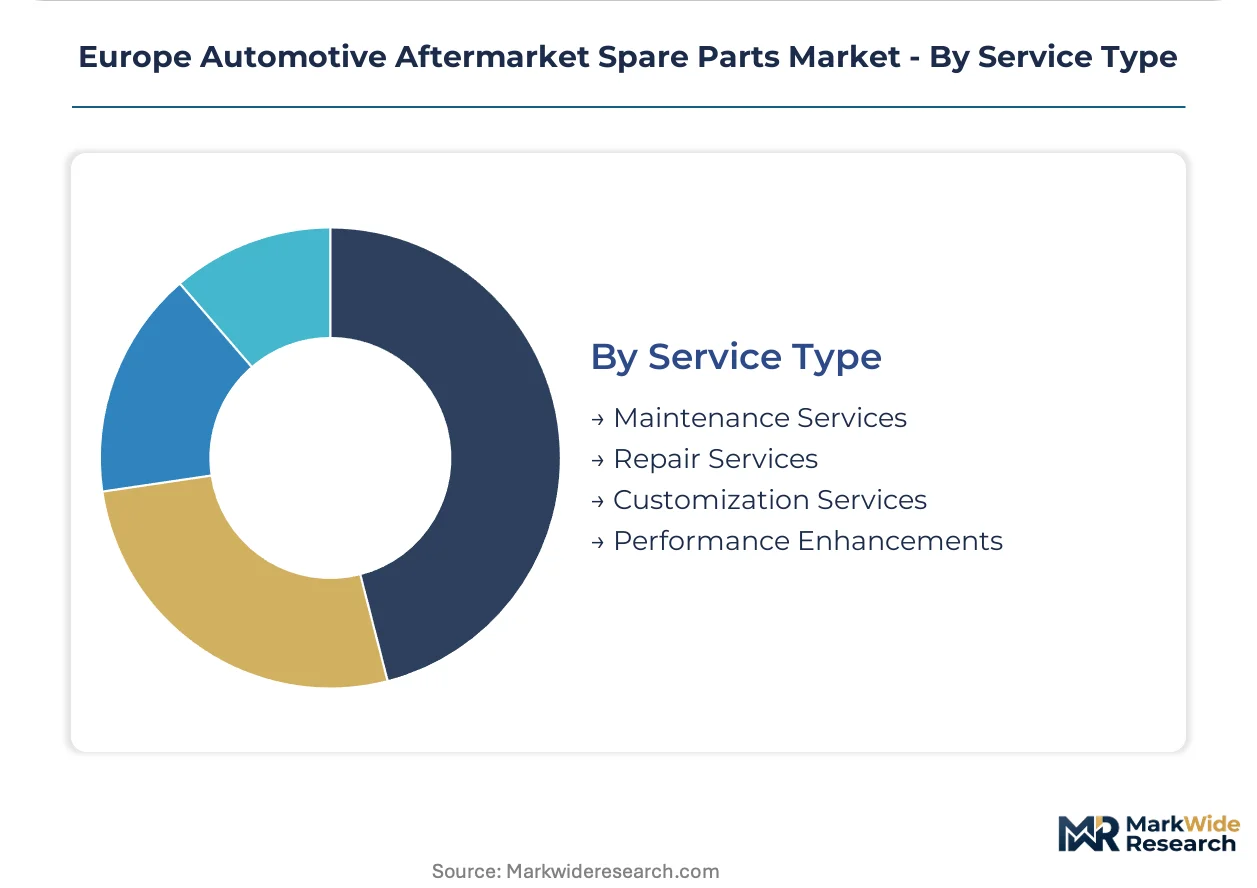
Service Type:
Service delivery models determine parts bundling structures and technician competency requirements.
- Maintenance Services:Scheduled preventive work follows manufacturer-prescribed intervals with predictable component demand. Subscription-based predictive programs in Germany convert fixed schedules to condition-based replacement, altering inventory velocity patterns.
- Repair Services:Unscheduled failure response requires flexible parts availability and diagnostic troubleshooting capabilities.
- Customization Services:Aesthetic and performance modifications operate outside regulatory compliance frameworks governing safety-critical components.
- Performance Enhancements:Powertrain and suspension upgrades face divergent national enforcement of type-approval requirements across member states.
Revenue concentration sits with Repair Services; the steepest trajectory belongs to Maintenance Services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parts manufacturing concentrates in Germany and France while consumption spreads across Southern and Eastern Europe. Distribution infrastructure lags fleet expansion in Poland and Romania. Regulatory enforcement timelines diverge between Western certification maturity and Eastern adoption curves.
Germany
KBA type-approval requirements for brake linings and lighting components create compliance barriers for non-domestic suppliers. The EU Green Deal's circular economy mandates accelerate remanufacturing certification through national environmental agencies. Stuttgart and Wolfsburg anchor dense clusters of authorized service centers deploying predictive maintenance programs for commercial fleets.
France
ANSM and CNIL oversight intersect with automotive data governance as telematics penetration deepens in fleet procurement. F-Gas Regulation enforcement targets the densest air-conditioning service volumes in Paris and Lyon metropolitan corridors. Independent repair shops in these clusters face steep retooling requirements for alternative refrigerant handling equipment.
Italy
Subscription-based parts bundling consolidates procurement through authorized service networks in Milan and Turin. REACH substance restrictions force coating reformulation across brake and electrical categories manufactured in Northern industrial zones. The lag between certification completion and market access approval compresses supplier margins.
Poland
Vehicle fleet density expands faster than traditional distribution infrastructure can match. ECE R90 brake lining standards apply with shorter national adaptation periods than Western counterparts. Warsaw and Krakow emerge as logistics hubs for diagnostic-enabled parts distribution targeting underpenetrated service networks.
Spain
Barcelona and Madrid concentrate independent repair shop consolidation through predictive maintenance contract adoption. RoHS frameworks restrict hazardous substances in electronic components sourced for ADAS calibration equipment. Technician training pipelines have not scaled to match sensor-integrated module complexity.
Europe Automotive Aftermarket Spare Parts Market Competitive Landscape
Top-tier vendors anchor diagnostic-integrated hardware ecosystems, while mid-scale specialists compete on material compliance speed. The supplier base stratifies across captive software platforms, in-house sensor production, and reformulated material portfolios. Three archetypes dominate: integrated system architects, component specialists with captive manufacturing, and compliance-first material reformulators. Competitive moves concentrate on M&A for diagnostic software assets and strategic partnerships for remanufacturing certification acceleration.
Within the integrated system tier, Robert Bosch GmbH and Continental AG exemplify divergent platform strategies. Valeo Group occupies a position emphasizing thermal management specialization aligned with electrified powertrain service requirements. These three entities represent the competitive density that smaller suppliers must navigate through certification speed or geographic niche focus.
| Leading Market Players |
|---|
| HELLA KGaA Hueck & Co. |
| Forvia |
| Continental AG |
| Aptiv PLC |
| Mahle GmbH |
| Robert Bosch GmbH |
| Valeo Group |
| ThyssenKrupp AG |
| ZF Friedrichshafen AG |
| Others |
Pricing and Supply Chain Analysis
Captive in-house production of sensor-integrated brake modules by Continental AG and diagnostic software ecosystems at Robert Bosch GmbH anchor supply positions while simultaneously defending pricing power against commodity alternatives. This vertical integration pattern concentrates margin capture among tier-one system architects, leaving independent distributors exposed to cost-down pressure from subscription-based fleet procurement programs.
Pricing Analysis
Cost-down pressure on standard brake pads and passive filtration elements accelerates because fleet operators consolidate procurement through predictive maintenance contracts with authorized service networks. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels differentiates offerings, with ECE R90 type-approval and ISO 9001 certification commanding measurable premiums over uncertified alternatives. Independent repair shops in Poland and Romania exhibit highest price sensitivity due to thinner margin structures, while commercial fleet procurement functions in Germany demonstrate lowest sensitivity when diagnostic integration reduces total cost of ownership.
Supply Chain Analysis
Dual-sourcing mandates from German and French OEM procurement functions require Tier 1 suppliers to qualify secondary component vendors for sensor arrays and friction material substrates. Manufacturing concentrates in Germany, Czech Republic, and Poland for brake modules; rare earth magnet processing for electric motor remanufacturing draws from concentrated single-source geographies. Permanent magnet supply concentration creates input cost volatility exposure for sensor-integrated drivetrain parts. Distribution runs through authorized service center networks in Western Europe and emerging wholesale hubs in Warsaw and Krakow targeting underpenetrated Eastern European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Remanufacturing certification bottlenecks compress available compliant component supply, propping pricing for verified circular economy parts above commodity alternatives. Technician training pipeline lags relative to ADAS calibration complexity, constraining service capacity expansion.
For Market Incumbents: Extend diagnostic software platform penetration to lock in recurring parts revenue streams through subscription-based predictive maintenance contracts. Accelerate remanufacturing certification investments ahead of EU Green Deal circular economy mandate timelines to capture retrofit demand from independent repair shops facing compliance deadlines. Defend against additive manufacturing substitutes by emphasizing ECE type-approval and sensor integration that 3D-printed polymers cannot replicate. For New Entrants and Emerging Players: Begin with thermal management component specialization targeting F-Gas Regulation retrofit demand from independent repair shops in France and Italy seeking compliant refrigerant handling equipment. Bulgaria and Croatia offer first-mover advantages for diagnostic-enabled parts distribution partnerships where authorized service center networks remain underpenetrated relative to vehicle parc density. Pursue AI-driven inventory forecasting partnerships with independent distributors to match OEM-tier fill rates without captive manufacturing assets. For Investors and Strategic Acquirers: Exit pathways concentrate in diagnostic software asset acquisitions by tier-one system architects seeking to complete predictive maintenance ecosystems. Long-term viability favors suppliers with captive reformulated material portfolios compliant with REACH substance restrictions and F-Gas phase-down requirements. Target acquisition archetypes include mid-scale thermal management specialists and remanufacturing certification accelerators. Watch technician training pipeline scaling as the signal indicating whether ADAS-enabled parts demand outruns service capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Remanufacturing Certification Acceleration | EU Green Deal mandates compress timelines, rewarding early compliant suppliers with preferential fleet procurement access. |
| Diagnostic Software Platform Integration | Robert Bosch GmbH leverages ecosystem lock-in to convert transactional parts sales into recurring subscription revenue streams. |
| Thermal Management Portfolio Reformulation | Valeo Group captures F-Gas Regulation retrofit demand through alternative refrigerant-compatible compressor seals and service couplings. |
| AI-Driven Inventory Forecasting Partnership | Machine learning convergence enables independent distributors to match OEM-tier fill rates without captive manufacturing. |
| Eastern European Distribution Hub Establishment | Warsaw and Krakow logistics infrastructure targets underpenetrated service networks in Poland and Romania. |
Research Methodology
Independent corroboration across Tier 1 supplier procurement executives, aftermarket distributor operations heads, fleet maintenance managers, and independent repair shop owners underwrites the qualitative findings. Primary fieldwork combined with secondary validation from vehicle production databases, IHS Markit registration data, EU regulatory filings, and national type-approval authority records. Bottom-up segmentation modeling triangulates against top-down market sizing from trade association disclosures and customs records.
Comparable-period anchoring to historical fleet expansion rates and replacement cycle intensities structures the projection horizon. The analytical framework models part type, vehicle class, distribution channel, and service delivery mode dimensions throughout the forecast period. CAGRs derive from replacement cycle elasticity, electrification penetration curves, and regulatory compliance adoption rates. Forecast inputs include telematics penetration trajectories and remanufacturing certification velocity assumptions.
REACH substance restriction enforcement delays, F-Gas Regulation phase-down acceleration, and rare earth supply disruption are the dominant revision risks. Forecasts reflect assumptions regarding technician training pipeline scaling and fleet operator contract adoption curves. Deviation in remanufacturing certification timeline adherence would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
India Automotive Hydraulic Actuators Market
Automotive Parts
North America Automotive Parts Aluminum Die Casting Market
Automotive Parts
Engine Bearings Market
Automotive Parts
Automotive Belts Market
Automotive Parts
Vehicle Transfer Case Market
Automotive Parts
Variable Valve Timing (VVT) Market
Automotive Parts
Automotive Thermostat Market
Automotive Parts
Automotive Winches System (AWS) Market
Automotive Parts
Morocco Commercial Vehicles Lubricants Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Electric Brake Booster Market
Automotive Parts
North America Very Narrow Aisle Trucks (VNA Truck) Market
Automotive Parts
Automotive Exhaust Heat Recovery System Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
United States Automotive Glass Market
Automotive Parts
Global Intelligent Steering System Market