
 Commercial Vehicle Brake Chambers Market | 2026-2036
Commercial Vehicle Brake Chambers Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Vehicle Brake Chambers Market Analysis
Modular brake chamber kits bundling spring and service functions is consolidating buyer preference across fleet procurement departments. Knorr-Bremse AG leverages its integrated air processing portfolio to anchor European OEM supply relationships. Bendix Commercial Vehicle Systems LLC sustains North American manufacturing scale through captive foundry operations. Haldex competes aggressively on aftermarket channel density, particularly among independent distributors serving regional trucking fleets.
Commercial vehicle brake chambers are pneumatic actuators converting compressed air pressure into mechanical force to engage foundation brakes, typically manufactured from cast iron housings with rubber diaphragms rated for operating pressures between 80 and 120 psi. Spring brake chambers incorporate an internal mechanical spring that applies emergency and parking brake force independent of air supply, while service brake chambers rely exclusively on air pressure for actuation during normal driving cycles. Cast iron and aluminum material segments dominate OEM specifications where thermal cycling resistance and corrosion protection determine replacement intervals, though composite housings are gaining traction in weight-sensitive trailer applications. Double chamber configurations lead unit volume in heavy-duty truck installations where combined service and spring functions reduce mounting complexity, while single chamber variants sustain aftermarket demand in older trailer fleets with simpler braking architectures.
NHTSA Federal Motor Vehicle Safety Standard 121 mandates automatic brake adjusters and specific chamber stroke limits for air-braked commercial vehicles operating in the United States. EPA heavy-duty engine and vehicle greenhouse gas standards indirectly shape brake chamber demand through associated driveline and chassis weight optimization requirements. FMCSA inspection protocols enforce out-of-service criteria for excessive pushrod stroke, creating predictable replacement demand cycles. Stakeholders must monitor how California Air Resources Board fleet electrification timelines alter air brake system specifications for hybrid and battery-electric commercial vehicle platforms.
Market Dynamics
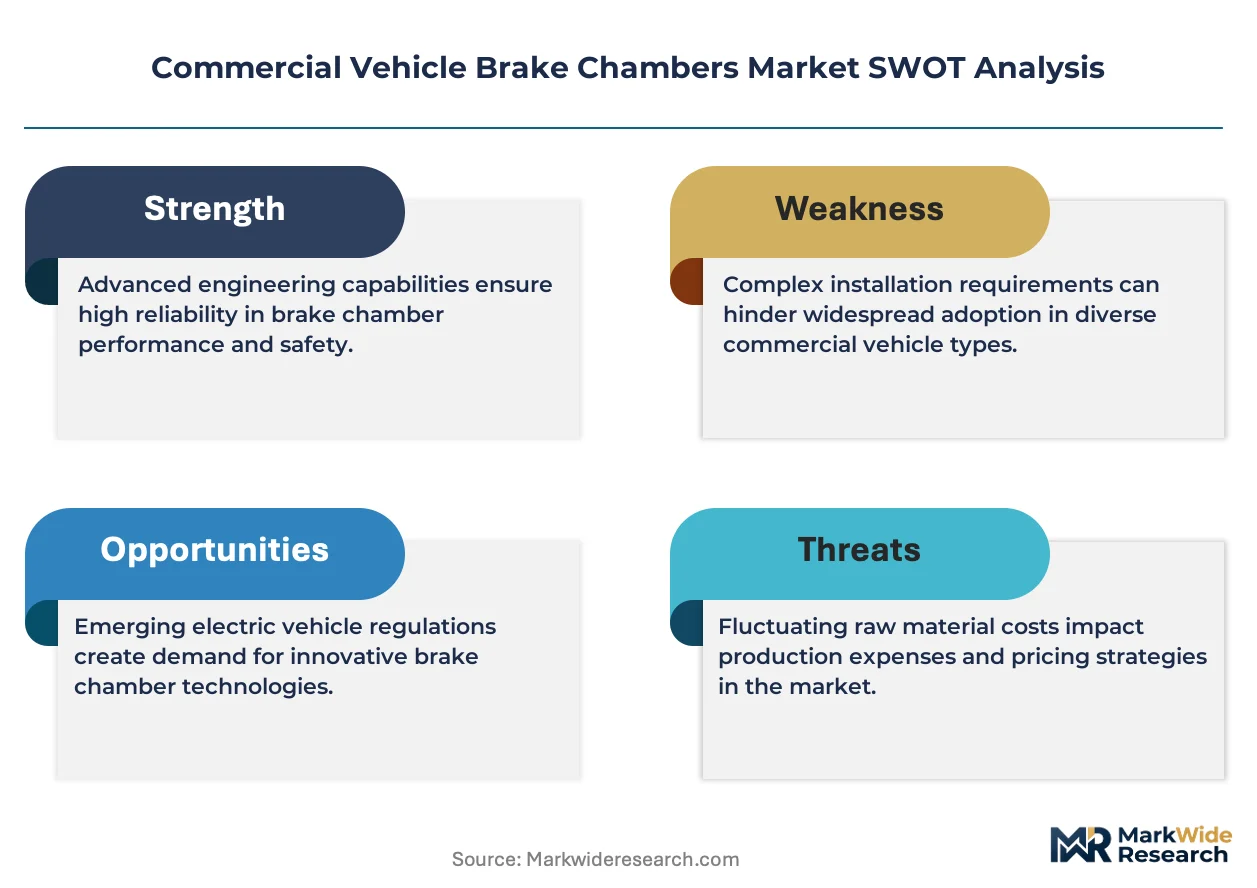
Fleet electrification timelines from California Air Resources Board are forcing brake chamber suppliers to redesign pneumatic actuators for compatibility with regenerative braking architectures on battery-electric heavy-duty platforms.
Growth Catalysts
- NHTSA Stopping-Distance Mandates:Updated Federal Motor Vehicle Safety Standard 121 requirements for reduced heavy-duty tractor stopping distances are accelerating replacement cycles for outdated air brake systems across US Class 8 fleets.
- Cast Iron Thermal Cycling:Advanced metallurgical formulations in OEM brake chamber housings are extending service intervals and reducing total cost of ownership for high-mileage linehaul operations.
- Trailer Weight Optimization:Composite brake chamber housings are displacing traditional materials in refrigerated and flatbed trailer segments where every pound of unladen weight reduction translates to payload revenue.
Market Restraints
- Aluminum Input Volatility:Primary aluminum price swings tied to energy costs in smelting regions are compressing margin structures for manufacturers of lightweight brake chamber variants specified by weight-sensitive OEMs.
- Diaphragm Rubber Supply Concentration:Specialty elastomer compounds rated for 120 psi operating pressures depend on concentrated petrochemical feedstock suppliers in Gulf Coast refining corridors.
- Spring Brake Mechanical Limitations:Internal coil spring fatigue in emergency brake chambers imposes hard replacement intervals regardless of service brake diaphragm condition, creating inventory complexity.
Strategic Opportunities
- India Commercial Vehicle Modernization:Bharat Stage VI emission enforcement and associated chassis weight reduction mandates are opening specification windows for aluminum brake chambers in medium-duty truck platforms.
- Telematics-Integrated Predictive Maintenance:Convergence of brake stroke sensors with fleet management platforms enables condition-based replacement scheduling, shifting aftermarket revenue from reactive to proactive service models.
- European Green Deal Procurement Incentives:EU member state fleet renewal subsidies tied to CO2 performance criteria favor brake system suppliers offering documented lifecycle carbon footprints through EPD certification.
Industry Challenges
- Air Brake System Integration Complexity:Electrified commercial vehicle platforms require redesigned pneumatic architectures that interface with electronically controlled braking systems, demanding new calibration competencies from field technicians.
- FMCSA Out-of-Service Compliance:Inspection protocols enforcing pushrod stroke limits create unpredictable demand spikes that strain distributor inventory positioning across dispersed regional trucking networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Vehicle Brake Chambers Market |
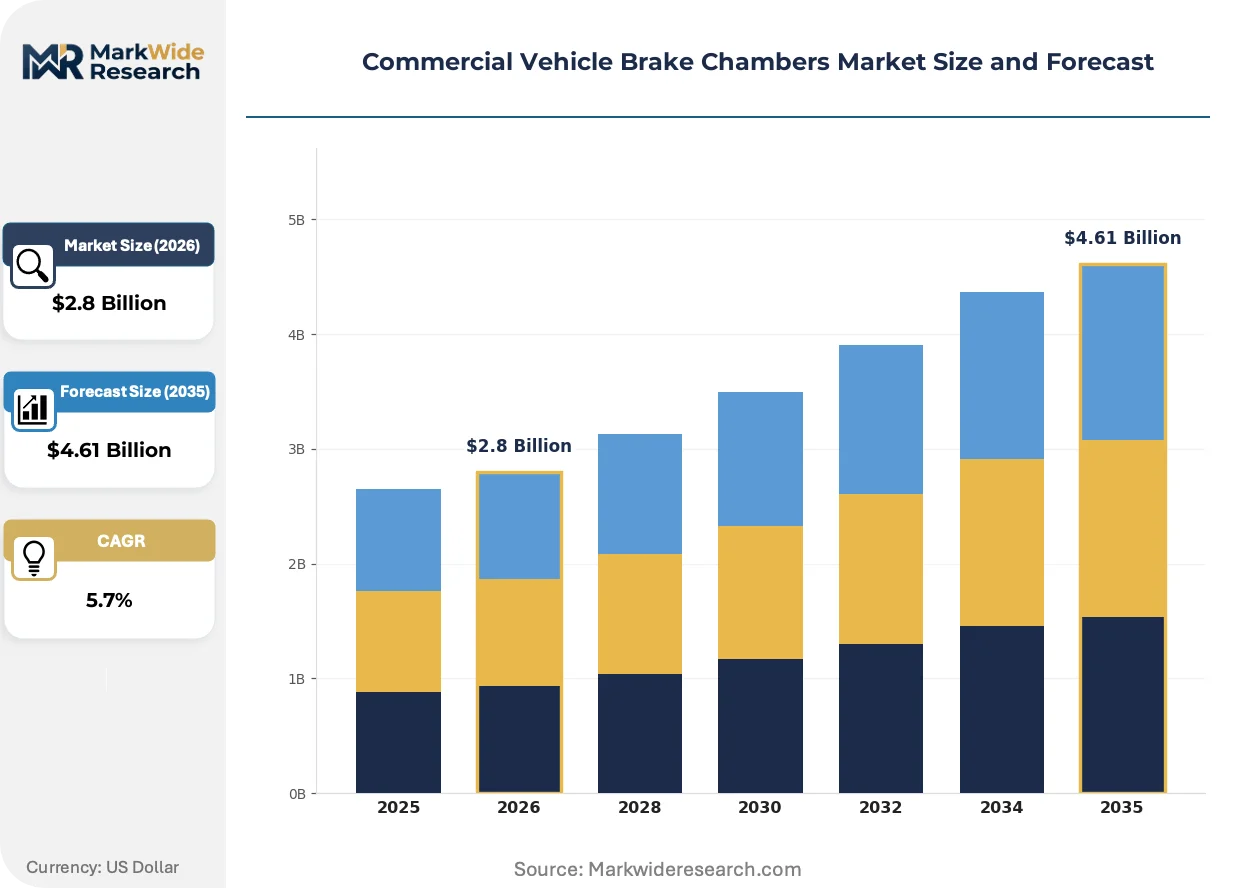
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Spring Brake, Service Brake, Single Chamber, Double Chamber Material: Aluminum, Cast Iron, Composite, Steel End User: OEMs, Aftermarket Providers, Fleet Operators, Distributors Application: Heavy-Duty Trucks, Buses, Trailers, Commercial Vans |
| Companies Covered | TSE Brakes, TBK Co., Ltd., Knorr-Bremse AG, Bendix Commercial Vehicle Systems LLC, Nabtesco Automotive Corporation, WABCO Holdings Inc., Meritor, Inc., Sealco Air Controls, Haldex, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Vehicle Brake Chambers Market Emerging Trajectories
Brake chamber technology is converging with vehicle electrification and connected fleet infrastructure, compressing product lifecycles while expanding the scope of what pneumatic actuators must communicate to central vehicle networks.
Integrated brake chamber kits combining service and spring functions in unified cast housings are modularizing procurement patterns across North American fleet maintenance departments. Large trucking operators now specify pre-assembled double chamber configurations that reduce installation labor and inventory SKU complexity. This standardization is compressing demand for standalone single chamber variants traditionally stocked by independent distributors.
California Air Resources Board fleet electrification mandates are reshaping air brake system specifications for hybrid and battery-electric commercial vehicle platforms. Manufacturers must engineer pneumatic actuators compatible with blended friction-regenerative braking profiles while maintaining FMCSA compliance for emergency stopping performance. Heavy-duty tractor OEMs operating in California are accelerating validation programs for redesigned chamber geometries.
Aftermarket procurement patterns among regional trucking fleets are fragmenting as digital procurement platforms displace traditional distributor relationships. Independent operators now compare brake chamber specifications and pricing through consolidated e-commerce channels rather than relying on single-source distributor relationships. This channel shift is most visible in the US Southeast where dispersed fleet footprints previously sustained dense independent distributor networks.
Commercial Vehicle Brake Chambers Market Segmentation
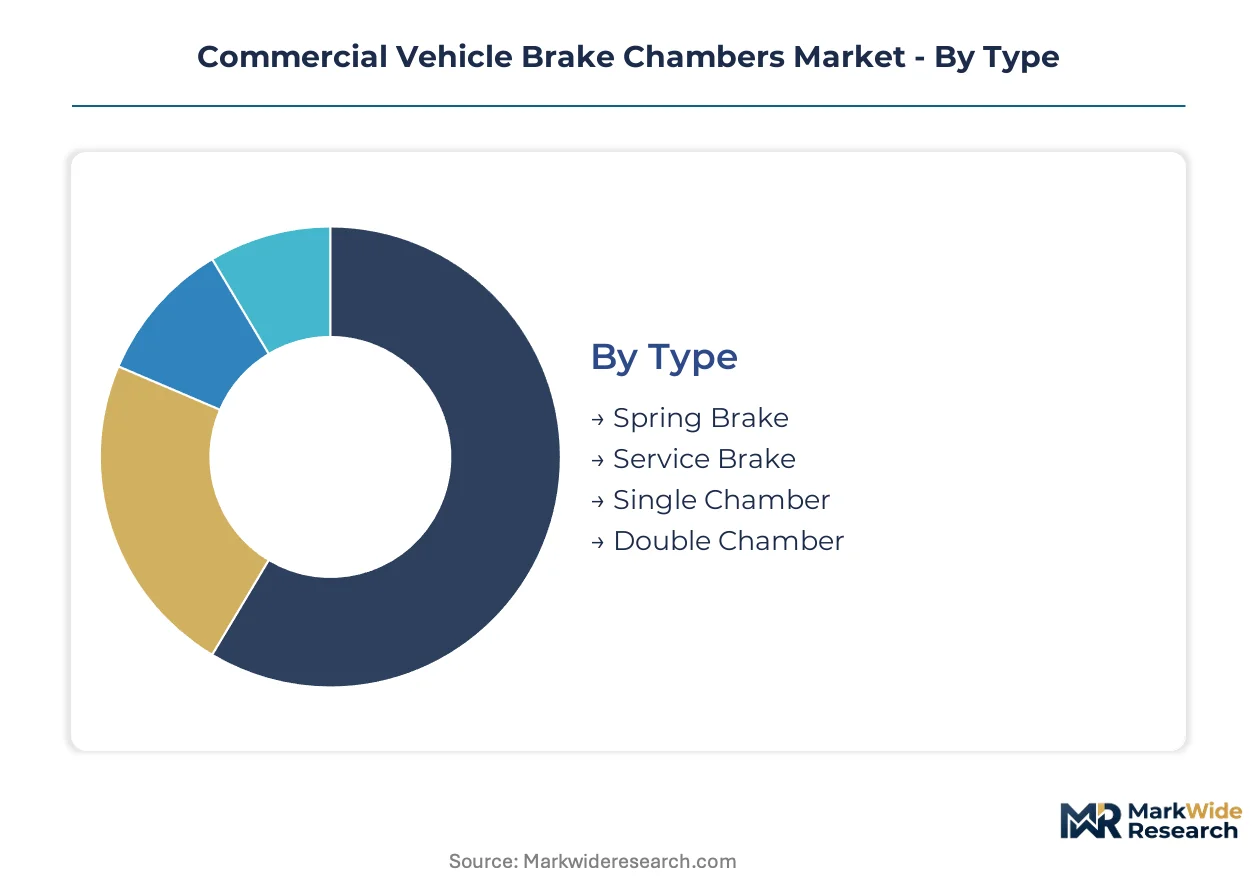
Brake chamber segmentation reveals how replacement cycles and specification pressures concentrate demand across distinct technical configurations. Understanding these partitions exposes where procurement budgets flow and which material and design choices dominate fleet decision-making.
Type:
Upgrade schedules for air brake systems vary sharply by chamber configuration, with combined-function designs capturing procurement preference in modern fleet specifications.
- Spring Brake:These chambers integrate mechanical coil springs that engage parking and emergency braking independent of air supply, rated for 120 psi maximum operating pressure. Demand concentrates in United States Class 8 tractor builds where NHTSA stopping-distance mandates mandate reliable emergency performance across all operating conditions.
- Service Brake:Pure pneumatic actuators relying exclusively on compressed air for normal driving cycles, manufactured with multi-ply rubber diaphragms for 80-120 psi service ranges. Fleet operators in high-mileage linehaul corridors specify these for predictable replacement intervals tied to FMCSA stroke-limit enforcement.
- Single Chamber:Simplified architectures serving older trailer fleets with separate service and spring mounting points.
- Double Chamber:Unified housings consolidating both functions reduce installation labor and inventory complexity for large fleet maintenance departments.
Double Chamber sits at the top of the volume ranking, with Composite variants in other categories climbing the fastest.
Material:
Material selection pivots on thermal cycling demands and weight optimization pressures that reshape total cost calculations across duty cycles.
- Cast Iron:Traditional OEM specification dominating heavy-duty truck installations where thermal mass withstands repeated heat-soak cycles from foundation brake engagement. Foundry capacity in industrial Midwest corridors supplies captive operations at major North American manufacturers.
- Aluminum:Lightweight alternative specified by weight-sensitive OEMs seeking chassis mass reduction for fuel efficiency compliance, though primary metal price volatility compresses margin structures.
- Composite:Polymer-reinforced housings penetrating refrigerated and flatbed trailer segments where unladen weight reduction translates directly to payload revenue capacity.
- Steel:Cost-focused specification sustaining aftermarket demand in price-sensitive independent fleet segments.
Cast Iron retains dominant share in value terms, while Composite gains share fastest in unit volume.
End User:
Procurement authority patterns determine how technical specifications flow from vehicle assembly through replacement cycles to operating fleets.
- OEMs:Original equipment manufacturers specify brake chambers during Class 8 truck and trailer assembly, with procurement decisions locked years ahead of production ramp.
- Aftermarket Providers:Independent distributors and service chains manage replacement inventory positioned for FMCSA inspection-driven demand spikes.
- Fleet Operators:Large trucking companies with captive maintenance facilities increasingly specify pre-assembled modular kits to compress installation time.
- Distributors:Regional parts networks sustain single-chamber inventory for legacy trailer fleets with simpler braking architectures.
Fleet Operators command the steepest expansion trajectory as direct procurement bypasses traditional distribution tiers.
Application:
Vehicle duty cycles and regulatory exposure create divergent performance requirements across commercial platform types.
- Heavy-Duty Trucks:Class 8 tractors subject to NHTSA Federal Motor Vehicle Safety Standard 121 stopping-distance mandates, driving specification of advanced double-chamber configurations with automatic brake adjusters.
- Buses:Transit and motorcoach applications with frequent stop-start cycles demanding enhanced thermal management in brake chamber material selection.
- Trailers:Weight-optimized platforms where composite housing adoption concentrates in refrigerated and flatbed segments.
- Commercial Vans:Light-duty platforms with simpler single-chamber architectures and extended replacement intervals.
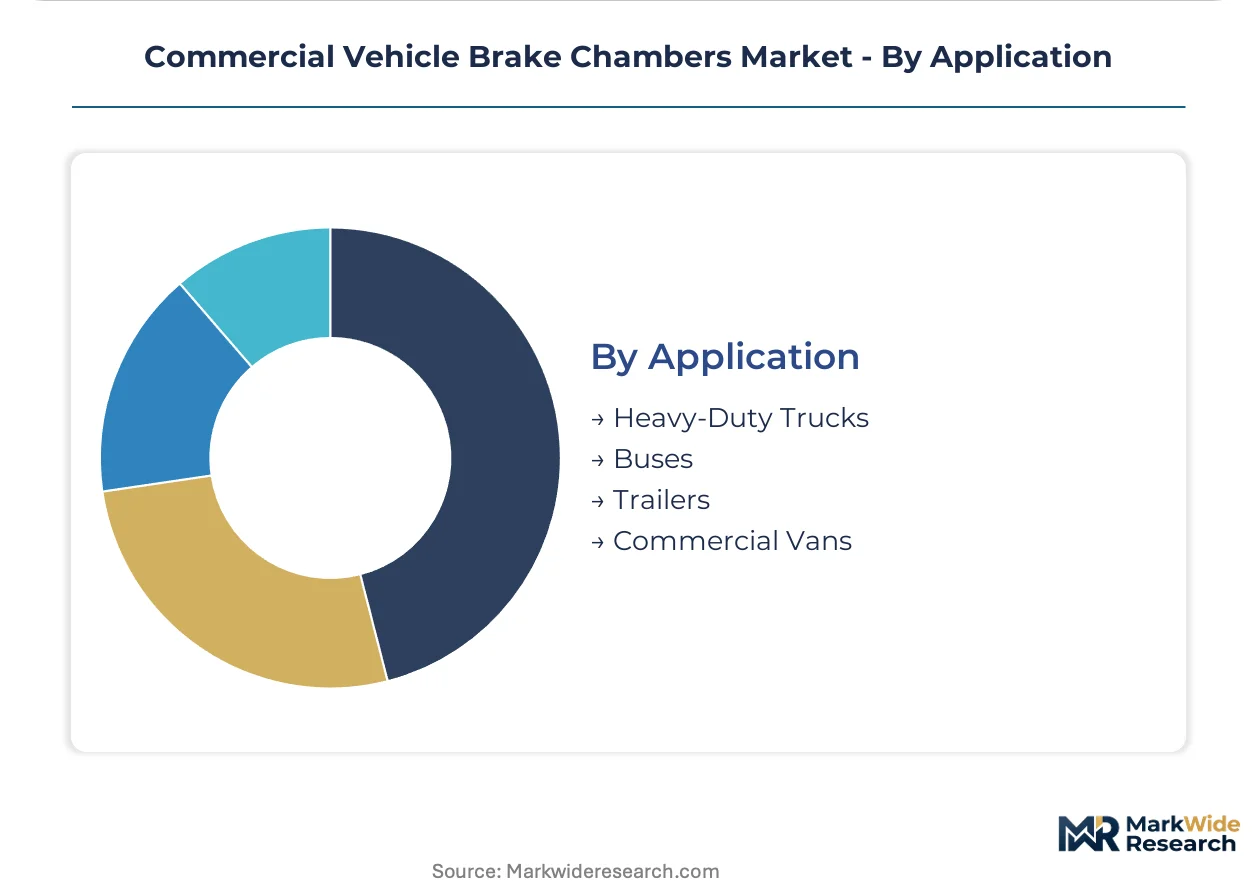
Heavy-Duty Trucks anchor volume concentration, with Trailers expanding most quickly through weight-driven specification shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial vehicle brake chamber manufacturing traces its industrial origins to German foundry districts and the American Midwest automotive corridors, where thermal metallurgy expertise developed alongside heavy-duty truck production. These historical clusters continue to shape global supply patterns.
United States
Class 8 truck production in Michigan and Ohio sustains OEM brake chamber procurement at scale. NHTSA Federal Motor Vehicle Safety Standard 121 mandates automatic brake adjusters and stroke limits for air-braked vehicles. Detroit-area manufacturing clusters supply captive foundry operations for integrated brake system producers.
Germany
Advanced thermal cycling formulations from Baden-Württemberg metallurgical facilities serve European OEM specifications. EU Green Deal procurement incentives favor suppliers with documented lifecycle carbon footprints through EPD certification. Stuttgart industrial corridors anchor integrated air processing portfolio development for premium braking architectures.
China
Domestic heavy-duty truck assembly lines in Shandong and Hubei provinces drive specification demand for cast iron brake chambers. GB standards for commercial vehicle braking systems align with NHTSA-equivalent performance thresholds. Yangtze River Delta manufacturing bases supply both domestic OEMs and export markets.
India
Bharat Stage VI emission enforcement and chassis weight reduction mandates open specification windows for aluminum brake chambers in medium-duty platforms. BIS certification requirements for automotive braking components standardize quality thresholds. Tamil Nadu and Maharashtra automotive corridors concentrate foundry capacity for domestic and export supply.
Japan
Precision casting expertise in Aichi and Shizuoka prefectures supports high-cycle brake chamber specifications for export markets. JIS standards for automotive braking components establish dimensional and performance baselines. Nagoya industrial clusters integrate brake chamber production with broader commercial vehicle component portfolios.
Commercial Vehicle Brake Chambers Market Vendor Landscape
Premium-margin players sit above commodity-margin players across material specialization and thermal metallurgy capabilities. The vendor base organizes into three tiers: integrated braking system architects with captive foundry operations, standalone chamber specialists serving aftermarket channels, and regional fabricators competing on price-sensitive specifications. Consolidation pressures favor scale-driven manufacturers with backward integration into aluminum and cast iron raw material processing. Strategic moves center on modular kit standardization and telematics-integrated predictive maintenance platform development.
Within the integrated system architect tier, Knorr-Bremse AG and Bendix Commercial Vehicle Systems LLC exemplify premium positioning through captive manufacturing scale and OEM supply relationships. TBK Co., Ltd. occupies a position among Asia-Pacific-based specialists serving both domestic assembly lines and export replacement markets. These three companies represent divergent geographic anchoring strategies—European, North American, and Japanese manufacturing heritage respectively—while converging on modular brake chamber kit standardization.
| Leading Market Players |
|---|
| TSE Brakes |
| TBK Co., Ltd. |
| Knorr-Bremse AG |
| Bendix Commercial Vehicle Systems LLC |
| Nabtesco Automotive Corporation |
| WABCO Holdings Inc. |
| Meritor, Inc. |
| Sealco Air Controls |
| Haldex |
| Others |
Supply Flow & Price Mechanics
Family-owned Midwest foundry operators anchor cast iron brake chamber production, anchoring supply discipline through captive vertical integration while insulating premium-tier pricing from commodity volatility.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates OEM-certified suppliers from aftermarket distributors and regional fabricators. Price differentiation centers on FMCSA compliance certification and thermal cycling performance grade. Cost compression in aluminum variants is intensifying because primary metal price volatility feeds directly into lightweight chamber margins. Independent fleet operators exhibit highest price sensitivity, while Class 8 OEM procurement teams prioritize certified performance over unit cost.
Supply Chain Analysis
Domestic-content mandates in US federal procurement and India's PLI scheme for automotive components are reshaping sourcing patterns for brake chamber assemblies. Manufacturing concentrates in the United States, Germany, and China, with each hub serving distinct OEM specification regimes. Raw material flows draw from Gulf Coast petrochemical corridors for specialty elastomer diaphragms, Midwest foundry districts for cast iron housings, and Yangtze River Delta smelters for aluminum alloys. Single-source vulnerability concentrates in diaphragm rubber compounds rated for 120 psi operating pressures. Distribution runs through captive OEM supply chains for new vehicle assembly and independent distributor networks for aftermarket replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where NHTSA stopping-distance mandates generate predictable replacement demand cycles across US Class 8 fleets.
For Market Incumbents: Cement captive foundry capacity in industrial Midwest corridors to defend margin structures against aluminum price volatility. Deepen backward integration into specialty elastomer compounding to reduce Gulf Coast petrochemical feedstock exposure. Prioritize telematics-integrated chamber development to capture predictive maintenance revenue streams before aftermarket digital platforms consolidate buyer relationships.
For New Entrants and Emerging Players: Regional trucking fleets with dispersed footprints across the US Southeast represent the most penetrable buyer archetype currently underserved by integrated kit suppliers. Target composite housing specifications for refrigerated trailer segments where weight-driven payload economics justify premium positioning. Pursue direct e-commerce channels to bypass established distributor tiers and capture price-transparent procurement shifts.
For Investors and Strategic Acquirers: Valuations sit cheapest among standalone aftermarket distributors lacking telematics integration capabilities or modular kit assembly capacity. Long-term viability hinges on exposure to electrification-resistant heavy-duty tractor segments versus vulnerable trailer applications facing composite displacement. Monitor California Air Resources Board fleet electrification timeline acceleration as the critical inflection signal for pneumatic actuator demand trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Kit Standardization | Pre-assembled double chamber configurations reduce installation labor for fleet maintenance departments. |
| Telematics Integration Development | Brake stroke sensor convergence with fleet management platforms enables condition-based replacement scheduling. |
| Composite Housing Scale-Up | Polymer-reinforced variants penetrate refrigerated trailer segments where unladen weight reduction drives payload revenue. |
| Captive Foundry Expansion | In-house cast iron production insulates margin structures from commodity price volatility in lightweight alternatives. |
| Regulatory Certification Investment | EPD documentation for lifecycle carbon footprints secures EU Green Deal procurement incentive eligibility. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged brake system procurement managers at Class 8 OEMs, aftermarket distribution channel heads, fleet maintenance directors, foundry operations executives, and regulatory compliance officers at NHTSA and FMCSA. Secondary sources incorporated vehicle production databases, customs and trade flow records, SEC filings from listed brake system suppliers, and NHTSA Federal Motor Vehicle Safety Standard documentation. Bottom-up unit volume estimates triangulated against top-down value projections.
Rate-of-change decomposition across the analysis window segments growth by chamber type, material specification, end-user procurement authority, and vehicle application duty cycle. Modeled dimensions include spring versus service function configuration, cast iron versus aluminum versus composite housing material, OEM versus aftermarket versus fleet direct procurement channel, and heavy-duty truck versus bus versus trailer application. CAGRs derived from historical replacement cycle analysis projected against regulatory mandate enforcement timelines and fleet electrification penetration curves. Industry-specific inputs encompass FMCSA out-of-service inspection frequency data and Class 8 truck build rate forecasts.
Underlying measurement precision varies by segment; OEM procurement volumes carry tighter precision than fragmented aftermarket demand. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and fleet electrification adoption pacing. Electrification timeline acceleration or deceleration, aluminum price volatility spikes, and diaphragm rubber supply disruptions represent primary revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
France Automotive Parts Magnesium Die Casting Market
Automotive Parts
Garage Body Shop Equipment Market
Automotive Parts
Wheel Arch Liner Market
Automotive Parts
Electric Brake Booster Market
Automotive Parts
Automotive Control Arms Market
Automotive Parts
North America Automotive Parts Zinc Die Casting Market
Automotive Parts
Automotive Electric Drive Axle Market
Automotive Parts
Automotive Tonneau Market
Automotive Parts
Colombia Automotive Lubricants Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
India Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Aluminum Parts High Pressure Die Casting (HPDC) Market
Automotive Parts
Global Automotive Auxiliary Brake Market
Automotive Parts
Bumper Beam Market
Automotive Parts
India Brake Pads Market
Automotive Parts
Nigeria Automotive Engine Oils Market