
 Germany Automotive Parts Die Casting Market | 2026-2036
Germany Automotive Parts Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Automotive Parts Die Casting Market Foresight
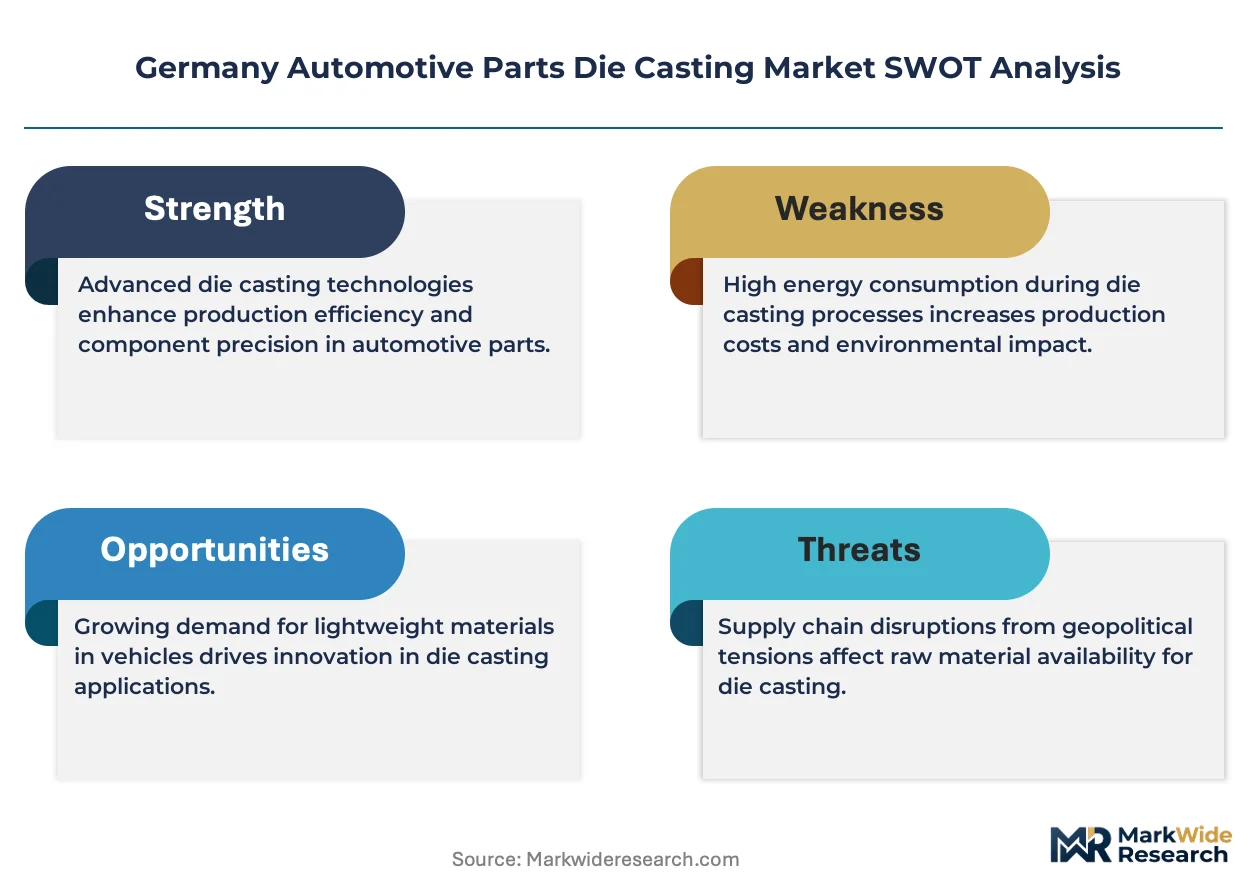
The tier-1 supplier channel is narrowing as OEMs consolidate vendor lists and demand higher-volume, single-source contracts for structural die cast components. Rheinmetall Automotive leverages its captive aluminum foundry network to secure long-term transmission housing programs with domestic OEMs. Georg Fischer Automotive anchors its position through advanced vacuum-assisted high-pressure die casting lines serving electric drive unit enclosures. Handtmann Group specializes in magnesium thin-wall castings for battery tray substructures, competing on weight reduction metrics that OEMs now specify at the platform level.
Automotive parts die casting is a metal-forming process wherein molten non-ferrous alloys are injected into precision steel molds under pressures typically exceeding 70 MPa, yielding near-net-shape components with wall thicknesses below 2.5 mm for weight-critical assemblies. The process serves primarily to manufacture geometrically complex, load-bearing parts that replace multiple stamped or machined components in vehicle structures. Aluminum alloys dominate current output volumes across engine components and chassis parts, while magnesium alloys represent the fastest-growing product category as OEMs pursue aggressive mass reduction targets for electric vehicle range optimization. High-pressure die casting captures the majority of value given its cycle speed and dimensional repeatability, though squeeze casting gains share in safety-critical suspension nodes where porosity tolerance approaches zero.
KBA enforces type-approval standards that mandate fatigue resistance testing for structural die castings, while REACH compliance restricts certain alloying element compositions in automotive supply chains. The EU Green Deal's embedded carbon reporting requirements through CSRD are forcing foundries to document Scope 1-3 emissions or risk exclusion from OEM bidding rounds. Stakeholders must monitor how battery-electric platform architectures reshape component count and material specifications, as integrated e-axle housings merge functions previously served by discrete transmission and engine parts.
Market Dynamics
Platform electrification is compressing component counts while simultaneously escalating performance requirements for remaining structural die castings. Battery-electric architectures demand integrated housings that merge transmission, motor, and inverter functions into single aluminum or magnesium castings with zero-defect porosity tolerances.
Growth Catalysts
- EU Green Deal embedded carbon mandates:CSRD reporting requirements force foundries to document Scope 1-3 emissions, creating competitive advantage for German suppliers with renewable energy sourcing and closed-loop recycling systems.
- Magnesium thin-wall casting penetration:Battery tray substructures specify magnesium alloys below 1.8 mm wall thickness to maximize electric vehicle range, converting design specifications previously served by steel stampings.
- Baden-Württemberg supplier ecosystem density:Stuttgart-Ingolstadt corridor concentration enables same-day logistics for just-in-sequence delivery to Volkswagen, BMW, and Mercedes-Benz assembly plants.
Market Restraints
- Primary aluminum ingot cost volatility:Energy-intensive smelting operations expose German foundries to electricity price spikes that compress margins on fixed-price OEM contracts.
- Tooling lead-time bottlenecks:Precision steel mold fabrication for complex e-axle housings extends beyond 26 weeks, constraining capacity expansion for new platform launches.
- REACH alloying element restrictions:Cadmium and lead content limits in automotive supply chains eliminate certain legacy alloy formulations, forcing reformulation validation cycles.
Strategic Opportunities
- Bavaria secondary processing integration:Machining and surface treatment capabilities adjacent to casting operations capture value previously exported to Czech and Polish subcontractors.
- Vacuum-assisted high-pressure die casting convergence:Combination of real-time cavity pressure monitoring with predictive porosity algorithms enables zero-defect production for safety-critical suspension nodes.
- KBA fatigue resistance certification expansion:Structural casting approval protocols developed for German OEMs create exportable technical standards for adjacent European markets.
Industry Challenges
- Process simulation expertise scarcity:Computational fluid dynamics and solidification modeling skills required for complex e-axle housing development outpace vocational training program output.
- Legacy ERP integration friction:Foundry scheduling systems struggle to synchronize with OEM platform-level production planning software, causing inventory mismatches during ramp-up phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Automotive Parts Die Casting Market |
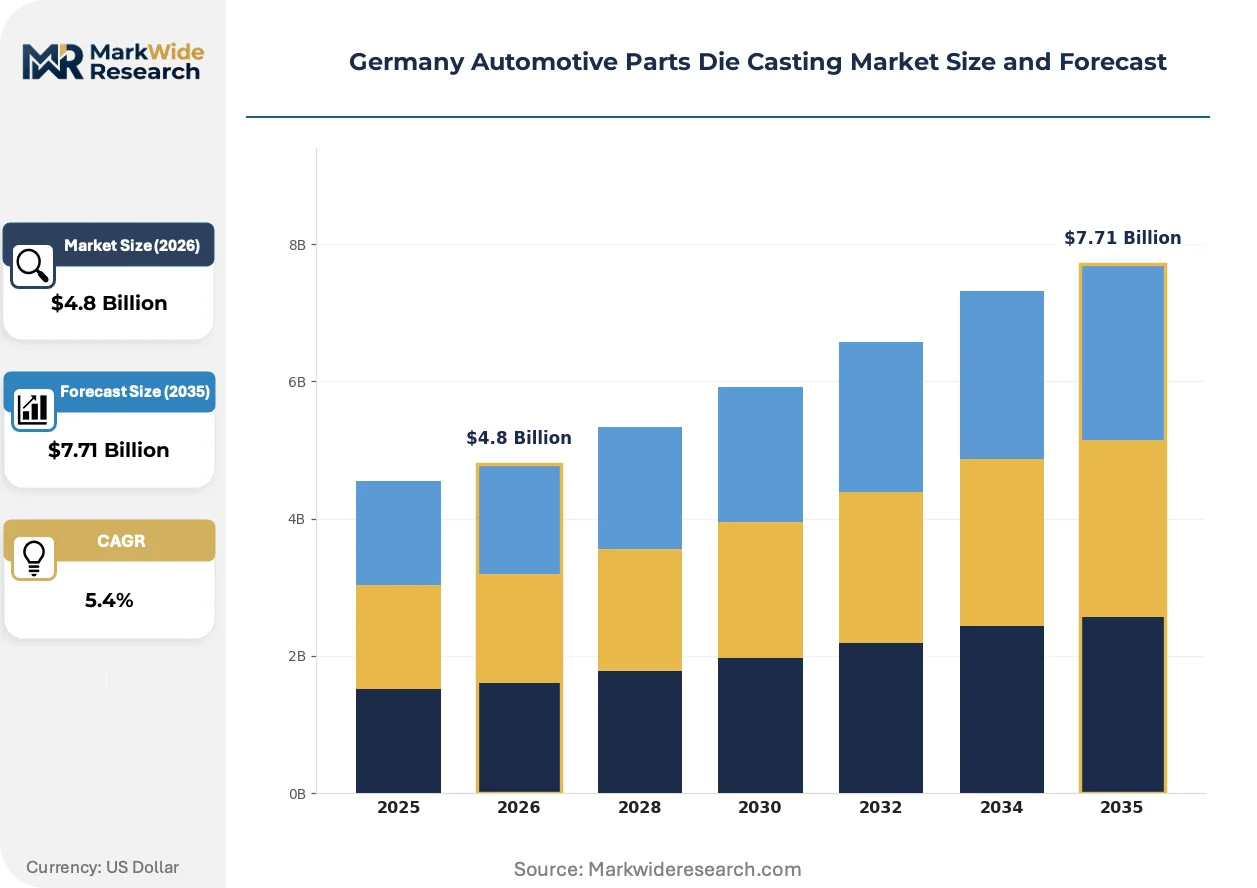
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.71 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Aluminum Alloys, Magnesium Alloys, Zinc Alloys, Copper Alloys, Lead Alloys Application: Engine Components, Transmission Assemblies, Chassis Parts, Electrical Housings, Brake System Components End User Industry: OEM Manufacturers, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Assembly Plants Technology: High-Pressure Die Casting, Low-Pressure Die Casting, Gravity Die Casting, Squeeze Casting |
| Companies Covered | Nemak, Rheinmetall Automotive, Handtmann Group, Ryobi Die Casting, Georg Fischer Automotive, Bühler Group, Endurance Technologies Europe, Dynacast International, KSM Casting Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Automotive Parts Die Casting Market Shifts & Advancements
Die casting process control is migrating from statistical quality verification to predictive defect prevention through in-cavity sensor networks. This shift compresses development cycles and eliminates downstream inspection bottlenecks.
Real-time cavity pressure and temperature monitoring systems are rendering obsolete post-cast X-ray inspection protocols for structural aluminum components. BMW and Mercedes-Benz powertrain divisions now specify 100% sensor-verified production for e-axle housings, eliminating batch sampling delays and reducing warranty exposure. The technology is compressing supplier qualification timelines from 18 months to under 9 months for new platform awards.
KBA type-approval standards for fatigue resistance testing now mandate 2 million cycle validation for structural die castings used in suspension applications. The regulation forces foundries to invest in servo-hydraulic test rigs capable of replicating multi-axial loading conditions. Bavarian suppliers serving BMW's Neue Klasse architecture report 40% capacity expansion in structural testing facilities to meet these protocols.
Buyer concentration among German OEMs has compressed vendor lists to single-source contracts for integrated e-axle housings. Tier-1 suppliers now compete on total program value rather than piece-price, bundling casting, machining, and assembly into platform-level agreements. This pattern is most visible in Baden-Württemberg, where Rheinmetall Automotive and Georg Fischer Automotive have secured decade-long transmission and drive unit enclosure programs through captive foundry investments.
Germany Automotive Parts Die Casting Market Segmentation
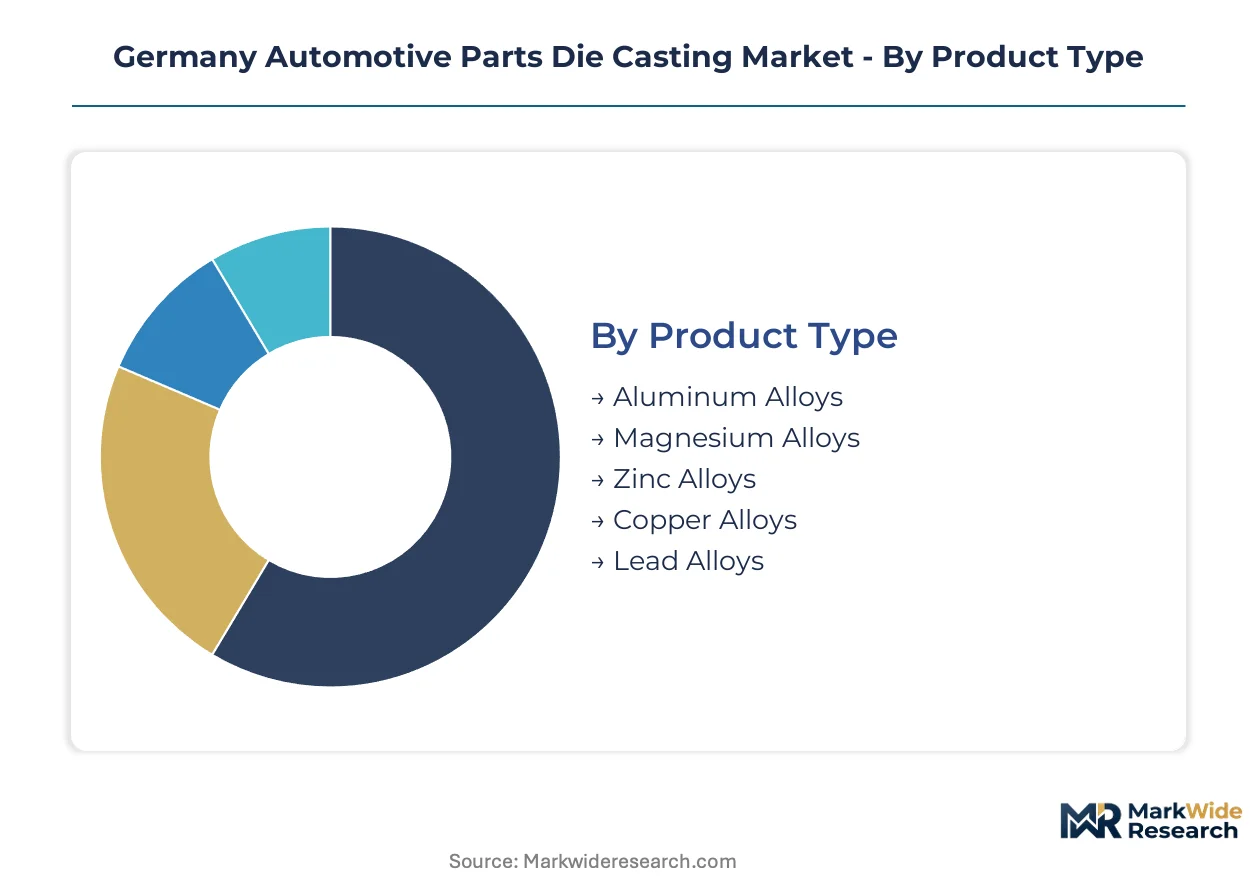
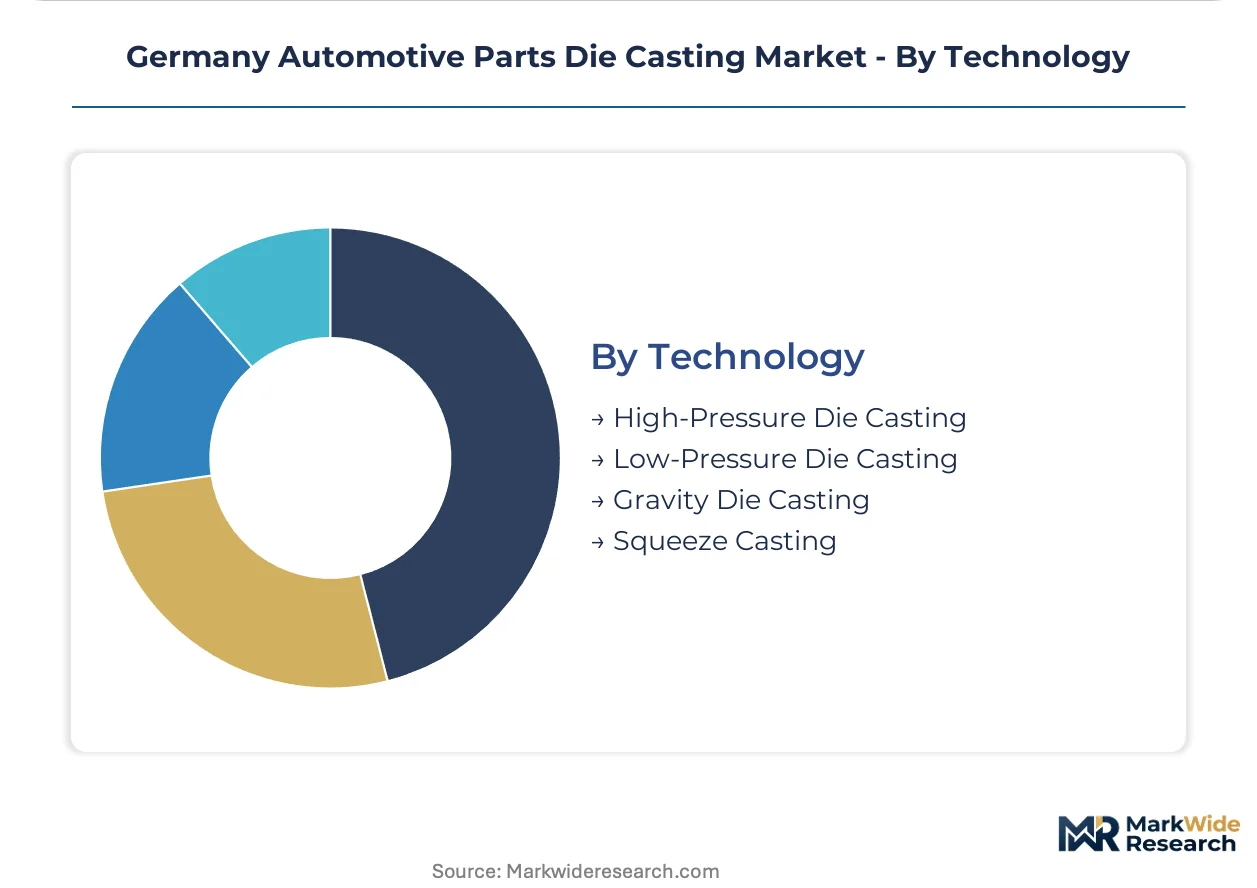
Segmentation in Germany's automotive die casting market reveals how material specifications, process technologies, and application requirements stratify supplier capabilities. OEM platform electrification is collapsing traditional category boundaries as integrated e-axle housings demand multi-material expertise and zero-defect process control.
Product Type:
Cycle times vary dramatically across alloy families, with aluminum and magnesium commanding rapid-turnover production schedules while zinc and copper alloys serve longer-lead specialty applications.
- Aluminum Alloys:Silumin and AlSi10Mg(Fe) formulations dominate structural powertrain castings, offering 165-180 MPa tensile strength with 8-10% elongation for crash-critical nodes. Demand concentrates in Baden-Württemberg foundries serving Stuttgart-based OEM transmission programs, where KBA fatigue validation protocols mandate 2 million cycle testing.
- Magnesium Alloys:AZ91D and AM60B variants enable sub-2 mm wall thicknesses for battery tray substructures, achieving 30-40% mass reduction versus aluminum equivalents. Bavarian suppliers around Munich report fastest capacity expansion as Mercedes-Benz and BMW specify magnesium for Neue Klasse platform enclosures.
- Zinc Alloys:Zamak compositions serve interior decorative trim and small electrical connectors with lower structural requirements.
- Copper Alloys:High-conductivity bronzes target thermal management components in inverter housings requiring heat dissipation above 200 W/mK.
- Lead Alloys:Limited to legacy battery terminal applications, facing REACH phase-out pressures for automotive supply chain exclusion.
Aluminum alloys anchor the volume base while magnesium alloys gain share at the steepest rate.
Application:
Cost tiers separate commodity engine brackets from safety-critical structural nodes, with chassis and electrical applications commanding premium pricing for defect-free certification.
- Engine Components:Cylinder heads, oil pans, and timing chain covers in AlSi10Cu3(Fe) alloys face declining platform counts as electrification eliminates internal combustion architectures. Foundries in Lower Saxony report 15-20% volume compression on legacy engine programs.
- Transmission Assemblies:Clutch housings and gear selector mechanisms require 0.05 mm dimensional tolerance for mating surface flatness. Ingolstadt-area suppliers capture multi-year Volkswagen Group contracts through integrated machining and leak-test capabilities.
- Chassis Parts:Control arms and steering knuckles in squeeze-cast aluminum demand zero-porosity certification for suspension safety.
- Electrical Housings:E-axle enclosures merge motor, inverter, and gearbox functions into single magnesium or aluminum castings.
- Brake System Components:Caliper housings and master cylinder bodies in hypereutectic aluminum alloys serve hybrid architectures retaining friction braking.
Transmission assemblies command the highest program values while electrical housings expand most quickly.
End User Industry:
Customer type determines contract structure, with OEM direct awards favoring decade-long single-source agreements and aftermarket channels tolerating shorter tooling amortization periods.
- OEM Manufacturers:Volkswagen, BMW, and Mercedes-Benz powertrain divisions specify platform-level die casting programs with 8-12 year horizons, bundling design, tooling, casting, machining, and assembly into integrated supplier responsibilities.
- Tier-1 Suppliers:Continental, ZF Friedrichshafen, and Bosch subsidiaries act as intermediaries, consolidating casting demand from multiple OEMs to achieve mold utilization above 75%.
- Vehicle Assembly Plants:Just-in-sequence delivery requirements favor foundries within 150 km of Stuttgart, Munich, and Wolfsburg production lines.
- Aftermarket Suppliers:Remanufactured transmission housings and replacement chassis components serve aging vehicle parc with less stringent traceability requirements.
Tier-1 suppliers intermediate the majority of transaction volume while OEM direct awards climb the fastest.
Technology:
Process maturity separates high-volume automotive production from prototype and repair applications, with vacuum-assisted variants commanding 40-60% tooling premiums over conventional equipment.
- High-Pressure Die Casting:Cold-chamber machines exceeding 3,500 metric tons clamping force produce e-axle housings with 45-second cycle times and real-time cavity pressure monitoring. Bavarian foundries lead European deployment of predictive porosity algorithms eliminating post-cast X-ray inspection.
- Squeeze Casting:Semi-solid metal injection with 100-150 MPa intensification pressure yields T6-temperable aluminum with sub-0.5% porosity for safety-critical suspension nodes.
- Low-Pressure Die Casting:Directional solidification control suits thick-walled transmission cases requiring uniform mechanical properties through cross-sections.
- Gravity Die Casting:Permanent mold pouring serves prototype volumes and aftermarket batches below 10,000 units annually.
High-pressure die casting anchors the volume base while squeeze casting gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Germany's automotive die casting corridor exceeds that of peripheral European manufacturing zones by 15-20% due to just-in-sequence proximity requirements and KBA certification premiums. Bavaria and Baden-Württemberg command particular leverage through captive OEM relationships and integrated supplier ecosystems.
Baden-Württemberg
Stuttgart-centered OEM powertrain divisions specify platform-level die casting programs with decade-long horizons, consolidating vendor lists around single-source suppliers. KBA fatigue resistance protocols mandate 2 million cycle validation for structural suspension castings, forcing foundries to invest in servo-hydraulic test rigs. The Stuttgart-Ingolstadt corridor enables same-day logistics for Volkswagen, BMW, and Mercedes-Benz assembly plants, compressing inventory carrying costs.
Bavaria
Mercedes-Benz and BMW powertrain divisions specify magnesium thin-wall castings below 1.8 mm for Neue Klasse battery tray substructures, converting steel stamping demand. EU Green Deal embedded carbon reporting through CSRD forces Munich-area foundries to document Scope 1-3 emissions or face OEM bidding exclusion. The Munich-Ingolstadt supplier cluster reports fastest capacity expansion in vacuum-assisted high-pressure die casting for e-axle housings.
Lower Saxony
Volkswagen Group's Wolfsburg headquarters anchors transmission housing demand with 0.05 mm dimensional tolerance requirements for mating surface flatness. REACH alloying element restrictions eliminate legacy cadmium and lead formulations, forcing reformulation validation cycles. Hanover-area suppliers face 15-20% volume compression on legacy engine programs as electrification eliminates internal combustion architectures.
North Rhine-Westphalia
Secondary processing integration opportunities concentrate in machining and surface treatment capabilities adjacent to casting operations. Primary aluminum ingot cost volatility from energy-intensive smelting exposes foundries to electricity price spikes that compress margins on fixed-price OEM contracts. The Cologne-Düsseldorf industrial belt hosts tier-1 supplier consolidation activity as Continental and ZF subsidiaries aggregate casting demand across multiple OEMs.
Hesse
Tooling lead-time bottlenecks for complex e-axle housing molds extend beyond 26 weeks, constraining capacity expansion for new platform launches. Frankfurt-Rhine-Main logistics hubs support distribution to assembly plants across southern Germany with 150-kilometer just-in-sequence radii. Regional foundries specialize in squeeze-cast aluminum for safety-critical suspension nodes where porosity tolerance approaches zero.
Germany Automotive Parts Die Casting Market Competitive Landscape
Captive foundry networks and independent tier-1 suppliers split the market between integrated platform-level responsibility and aggregated multi-OEM demand. Consolidation pressure from OEM vendor list narrowing favors scale players with renewable energy sourcing and closed-loop recycling systems. Three archetypes dominate: aluminum transmission housing specialists, magnesium thin-wall innovators, and vacuum-assisted process technology leaders. Competitive dynamics center on decade-long single-source contract capture and secondary processing integration into machining and assembly.
Among Germany-based automotive suppliers, Rheinmetall Automotive, Georg Fischer Automotive, and Handtmann Group occupy distinct positions within this structure. Rheinmetall Automotive exemplifies the captive foundry archetype through its integrated aluminum casting network serving domestic OEM transmission programs. Georg Fischer Automotive anchors the vacuum-assisted technology tier with advanced high-pressure die casting capabilities for electric drive unit enclosures. Handtmann Group represents magnesium specialization, competing on weight reduction metrics for battery tray substructures that OEMs now specify at the platform level.
| Leading Market Players |
|---|
| Nemak |
| Rheinmetall Automotive |
| Handtmann Group |
| Ryobi Die Casting |
| Georg Fischer Automotive |
| Bühler Group |
| Endurance Technologies Europe |
| Dynacast International |
| KSM Casting Group |
| Others |
Supply & Pricing Matrix
Primary aluminum smelting concentration in Norway and Iceland feeds directly into margin compression at German foundries when electricity contracts reprice. Battery-electric platform contracts from Stuttgart-based OEMs command 15-20% premiums over legacy transmission programs due to zero-defect porosity requirements and KBA fatigue validation protocols.
Pricing Analysis
Configured-to-order pricing for e-axle housings with integrated machining and leak-test capabilities spreads 25-35% above standard transmission housing baselines. Contract structures favor decade-long single-source agreements bundling design, tooling, casting, and secondary processing. Cost compression in legacy engine brackets is intensifying because electrification eliminates platform volumes. Tier-1 suppliers serving aftermarket channels exhibit highest price sensitivity, while OEM direct awards tolerate premium positioning for just-in-sequence reliability.
Supply Chain Analysis
Extended payment terms from Volkswagen, BMW, and Mercedes-Benz powertrain divisions stretch 90-120 days, forcing foundries to utilize supply-chain finance facilities. Raw material sourcing draws from Norwegian primary aluminum, Chinese magnesium ingot, and German recycled scrap streams. Single-source vulnerability concentrates in precision steel mold fabrication for complex e-axle geometries. Distribution runs through Stuttgart-Ingolstadt and Munich corridor clusters enabling same-day just-in-sequence delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment. KBA fatigue resistance certification and CSRD embedded carbon reporting create switching costs that lock out unqualified suppliers.
For Market Incumbents: Insulate core programs by deepening captive foundry investments in Baden-Württemberg and Bavaria to secure decade-long e-axle housing contracts. Accelerate vacuum-assisted high-pressure die casting capacity expansion before tooling lead-time bottlenecks constrain new platform awards. Process simulation expertise scarcity represents the critical vulnerability requiring targeted recruitment from computational fluid dynamics programs.
For New Entrants and Emerging Players: North Rhine-Westphalia secondary processing integration offers white-space opportunity as incumbent foundries focus on captive casting operations. Target squeeze-cast aluminum for safety-critical suspension nodes where porosity tolerance approaches zero and incumbent capacity is constrained. Establish machining and surface treatment capabilities adjacent to casting operations to capture value previously exported to Czech and Polish subcontractors.
For Investors and Strategic Acquirers: Capital is best deployed toward magnesium thin-wall specialists with demonstrated Neue Klasse platform qualifications and renewable energy sourcing for CSRD compliance. Long-term viability hinges on positioning for battery-electric architecture content per vehicle expansion rather than legacy engine program residual value. Monitor BMW and Mercedes-Benz platform-level supplier consolidation announcements as inflection indicators for single-source contract capture.
| Strategic Initiative | Industry Significance |
|---|---|
| Vacuum-Assisted High-Pressure Die Casting Deployment | Bavarian foundries lead European predictive porosity algorithm implementation eliminating post-cast X-ray inspection. |
| Magnesium Thin-Wall Capacity Expansion | Mercedes-Benz and BMW battery tray specifications below 1.8 mm wall thickness convert steel stamping demand. |
| Secondary Processing Integration | Machining and surface treatment capabilities adjacent to casting operations capture value from Czech and Polish subcontractors. |
| CSRD-Compliant Renewable Energy Sourcing | Foundries documenting Scope 1-3 emissions secure competitive position in OEM bidding rounds under EU Green Deal mandates. |
| KBA Fatigue Resistance Certification Investment | Servo-hydraulic test rigs for 2 million cycle validation create exportable technical standards for adjacent European markets. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of KBA type-approval documentation, EU Green Deal regulatory filings, and automotive production databases. Primary interviews engaged OEM platform engineers, Tier 1 supplier procurement leads, foundry operations directors, and aftermarket distribution managers. Secondary sources encompassed REACH compliance records, CSRD disclosure frameworks, and IHS Markit vehicle registration data. Bottom-up capacity assessments at individual foundry facilities were triangulated against top-down OEM platform-level demand aggregation.
Forecast inputs considered vehicle production trajectories, battery-electric platform conversion rates, and content-per-vehicle shifts across propulsion architectures. Segmentation modeling incorporated material alloy family, process technology, application requirements, and regional supplier ecosystem density. CAGRs were derived from production volume build-ups weighted by average selling price evolution. Industry-specific forecast drivers included KBA certification timeline acceleration and magnesium alloy penetration rates for battery tray substructures.
Practitioners should monitor primary aluminum electricity cost volatility, tooling lead-time extensions beyond current baselines, and REACH alloying element restriction amendments for early signals. Forecasts reflect documented assumptions regarding OEM platform launch schedules and CSRD implementation enforcement intensity. Macroeconomic contraction, regulatory delay, or breakthrough solid-state battery commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
High Level Brake Lamp Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Automotive Trailing Arm Bushing Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Qatar Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Parts Remanufacturing Market
Automotive Parts
Oil Filter Market
Automotive Parts
Timing Gear Market
Automotive Parts
Car Phone Holder Market
Automotive Parts
Global Automotive Motor Oil Market
Automotive Parts
Automotive Hydroformed Parts Market
Automotive Parts
Automotive Parts Zinc Die Casting Market
Automotive Parts
South Africa Automotive Hydraulic Actuators Market
Automotive Parts
Automotive Electric Turbocharger Market
Automotive Parts
Air Filter Cartridges Market