
 Automotive Brake Friction Materials Market | 2026-2036
Automotive Brake Friction Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Brake Friction Materials Market Analytics
Modular brake pad kits bundling shims, sensors, and hardware is expanding buyer choice across both OEM and aftermarket channels. Brembo S.p.A. leverages its motorsport heritage to anchor premium positioning in high-performance segments. Nisshinbo Holdings Inc. sustains manufacturing scale across ceramic and non-asbestos organic formulations. Tenneco Inc. competes through integrated coverage of both original equipment and service channels.
Automotive brake friction materials are composite formulations—typically integrating binders, fibers, fillers, and functional modifiers—engineered to convert kinetic energy into thermal energy through controlled surface interaction while maintaining coefficient stability across temperature ranges. Pads dominate product-type revenue due to replacement frequency, while ceramic material grades command margin premiums in passenger car applications where noise and dust reduction drive purchasing decisions. OEM end-user contracts concentrate volume, though aftermarket channels deliver higher per-unit profitability through fragmented regional distribution.
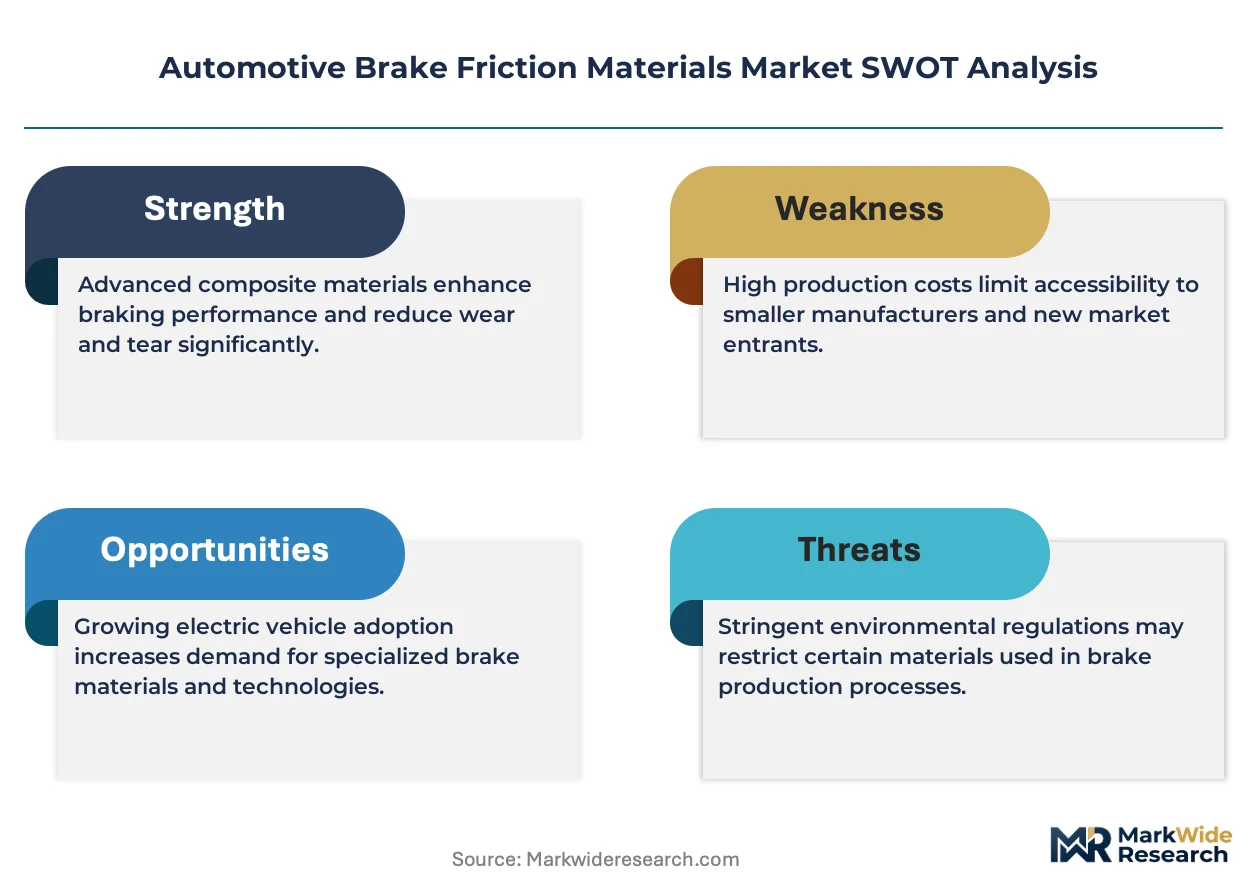
EPA regulations in the United States restrict copper content in brake formulations to protect aquatic ecosystems, compelling suppliers to reformulate with alternative sulfides and oxides. ECHA's REACH framework in Europe enforces similar substance restrictions, while China's GB standards govern friction performance testing protocols for domestic vehicle certification. Stakeholders must monitor evolving material compliance timelines and calibrate R&D allocation between copper-free chemistries and next-generation thermal management architectures.
Market Dynamics
Copper-free formulation mandates from EPA and ECHA are compressing legacy material supply chains while forcing simultaneous R&D investment across multiple alternative chemistries.
Growth Catalysts
- REACH substance restrictions:ECHA's framework is eliminating heavy metal content from European brake formulations, creating replacement demand for copper-free alternatives.
- Electric vehicle brake architectures:EV manufacturers require friction materials optimized for regenerative braking integration and reduced particulate emissions.
- Germany's manufacturing corridor:Tier-1 supplier consolidation around low-emission brake platforms is concentrating procurement volumes in Baden-Württemberg and Bavaria.
Market Restraints
- Phenolic resin cost volatility:Binder chemistry inputs face petrochemical price swings that compress margin predictability for formulation producers.
- Technical performance gaps:Copper-free alternatives struggle to match thermal conductivity and wear characteristics of legacy formulations in heavy-duty applications.
- Regulatory timeline fragmentation:Misaligned compliance deadlines between EPA state-level implementation and EU REACH phase-outs create inventory stranding risks.
Strategic Opportunities
- India's vehicle parc expansion:Domestic passenger car production growth is creating first-fit demand for non-asbestos organic formulations without legacy infrastructure lock-in.
- Sensor-integrated brake modules:Smart friction systems with embedded wear monitoring are opening aftermarket service revenue streams beyond commodity pad replacement.
- China GB standard alignment:Convergence of domestic friction performance testing with international protocols is reducing certification duplication costs for exporters.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in ceramic matrix and sulfide-oxide alternative development is concentrated among retiring technical workforces in Japan and Germany.
- Dual certification burden:Simultaneous SAE J2522 and AK-Master testing requirements for OEM qualification extend product development cycles by 8-14 months.
- Legacy fleet compatibility:Copper-free materials exhibit coefficient mismatch with older brake system designs, complicating aftermarket inventory management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Brake Friction Materials Market |
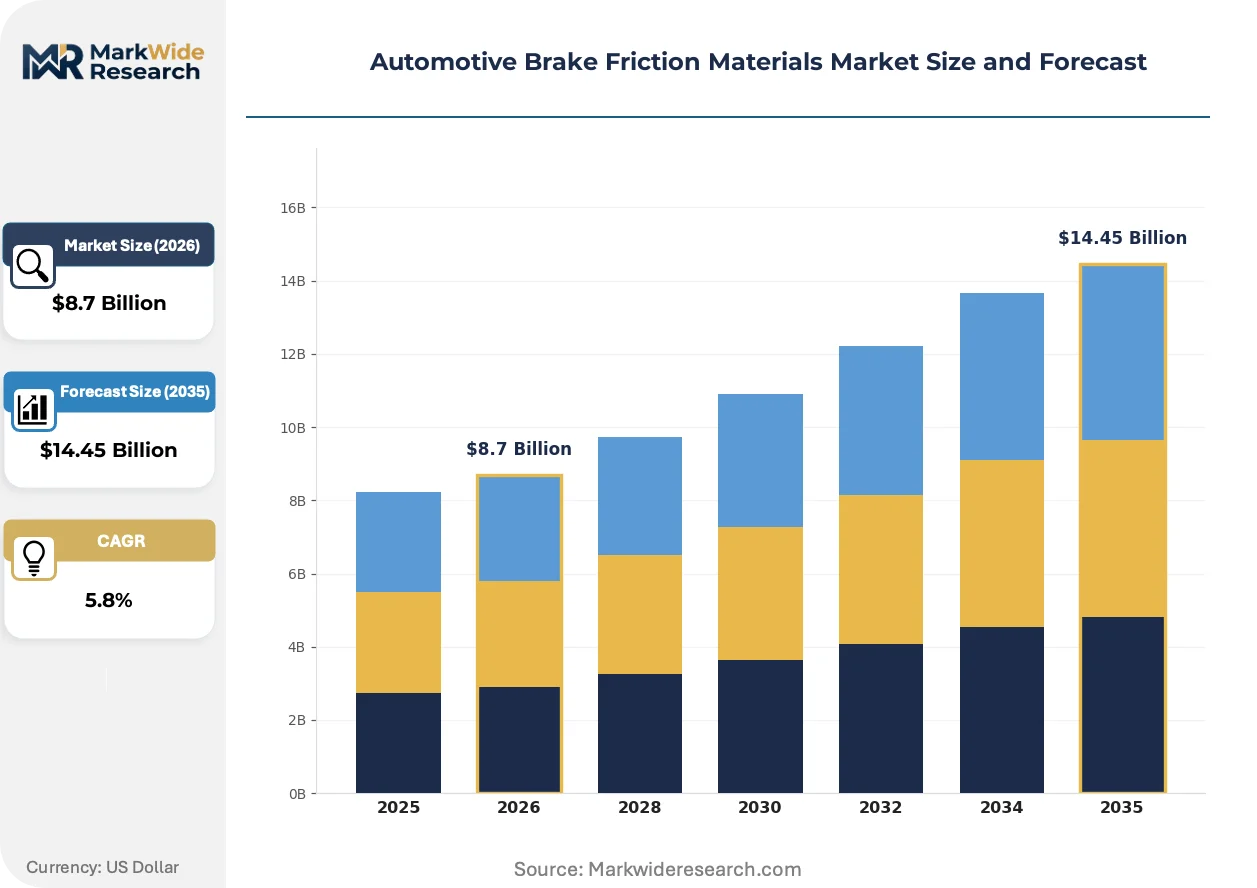
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pads, Shoes, Discs, Linings Material: Polymeric, Metallic, Ceramic, Composite End User: OEMs, Aftermarket, Vehicle Assemblers, Tier-1 Suppliers Application: Passenger Cars, Commercial Vehicles, Motorcycles, Heavy Machinery |
| Companies Covered | Brembo S.p.A., Nisshinbo Holdings Inc., Tenneco Inc., Akebono Brake Industry Co. Ltd., Aisin Corporation, ZF Friedrichshafen AG, Continental AG, Robert Bosch GmbH, Federal-Mogul Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Brake Friction Materials Market Evolving Landscape
Material science advances and regulatory phase-outs are converging to restructure how friction formulations are engineered, tested, and procured across passenger and commercial vehicle segments.
Ceramic matrix composites containing potassium titanate and aramid fibers are absorbing thermal loads previously managed by copper sulfide additives. Premium passenger car OEMs in Germany and Japan have adopted these formulations for 2024-2026 model year platforms. The technology is absorbing development budgets that previously funded incremental semi-metallic improvements, compressing legacy product lifecycles.
EPA's copper reduction mandates under the Brake Pad Partnership agreement are forcing reformulation roadmaps with 2025 and 2021 compliance deadlines for different manufacturer tiers. Suppliers must substitute copper with bismuth sulfide, tin compounds, or engineered oxides while maintaining friction stability. Aftermarket distributors in California and Washington face earliest inventory turnover requirements as state-level implementation precedes federal harmonization.
Fleet operators and large aftermarket buying groups are consolidating supplier relationships around certified low-emission product lines with documented lifecycle particulate data. Traditional jobber distribution is losing share to direct manufacturer agreements with national service chains. This concentration is most visible in the United States, where Monro, Midas, and corporate fleet managers are qualifying single-source brake pad suppliers for multi-year contracts.
Automotive Brake Friction Materials Market Segmentation
Friction material specifications diverge sharply across vehicle architectures and procurement channels. OEM qualification protocols, aftermarket replacement cycles, and regional regulatory mandates each reshape formulation priorities within segment boundaries.
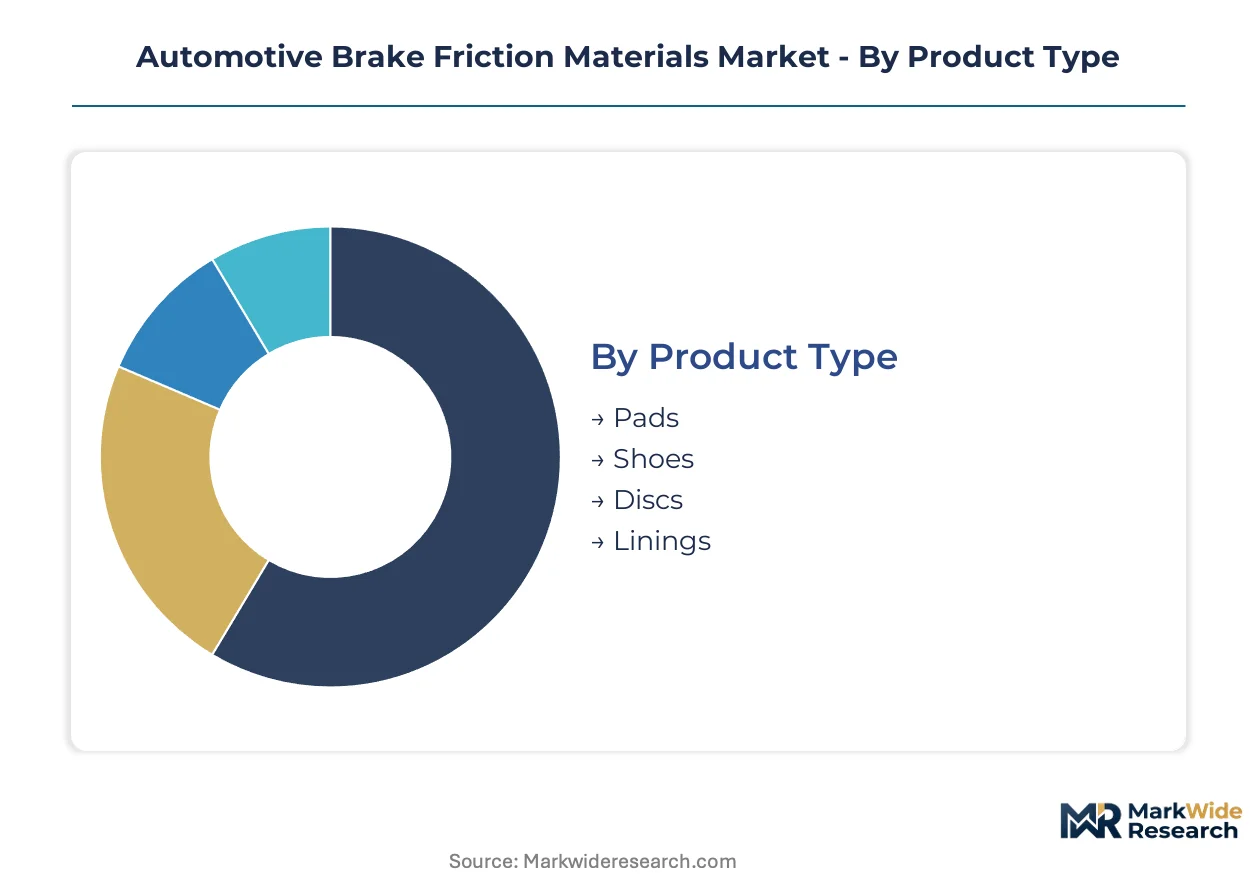
Product Type:
Replacement frequency and thermal load capacity separate buyers across these hardware categories.
- Pads:Composite formulations integrating binders, fibers, and functional modifiers dominate unit volume. Passenger car OEMs in Germany's manufacturing corridor specify ceramic-enhanced grades for noise-sensitive platforms.
- Shoes:Curved friction elements for drum brake architectures persist in cost-optimized vehicle segments and commercial fleet applications. India's expanding vehicle parc sustains first-fit demand for drum-compatible formulations without legacy infrastructure displacement.
- Discs:Rotor surfaces requiring compatible pad pairing for thermal management. Heavy machinery operators prioritize wear-rate consistency over initial friction coefficients.
- Linings:Large-surface friction materials for clutch and transmission applications. Commercial vehicle rebuilders specify these for powertrain durability in high-torque configurations.
Volume sits with Pads; growth tilts toward Discs as disc-brake architectures displace drum systems in emerging vehicle segments.
Material:
Cost position and regulatory compliance timeline determine procurement decisions across chemistry classes.
- Polymeric:Non-asbestos organic binders with aramid and glass fiber reinforcement. EPA copper restrictions are compressing market share as reformulation costs erode cost advantages.
- Metallic:Steel and copper fiber matrices delivering thermal conductivity for heavy-duty cycles. REACH substance restrictions in Europe are forcing substitution with tin compounds and engineered sulfides.
- Ceramic:Potassium titanate and copper-free formulations command margin premiums. Japan's passenger car OEMs have adopted these for reduced particulate emissions and extended service intervals.
- Composite:Hybrid architectures blending ceramic thermal performance with metallic structural integrity. Tier-1 suppliers consolidate procurement around these platforms for multi-vehicle program compatibility.
Procurement concentrates in Composite formulations; steepest expansion trajectory belongs to Ceramic as copper-free mandates accelerate.
End User:
Contract structure and technical qualification requirements fragment the customer base across procurement channels.
- OEMs:Original equipment manufacturers specify friction materials during vehicle platform development. Dual SAE J2522 and AK-Master testing extends qualification cycles.
- Aftermarket:Independent service channels deliver higher per-unit margins through fragmented regional distribution. California and Washington face earliest copper-free inventory turnover under state-level EPA implementation.
- Vehicle Assemblers:Contract manufacturers requiring certified low-emission product lines with documented lifecycle particulate data.
- Tier-1 Suppliers:Brake system integrators consolidating procurement around low-emission platforms in Baden-Württemberg and Bavaria.
Contract value aggregates with OEMs; margin expansion favors Aftermarket as direct manufacturer agreements displace traditional jobber networks.
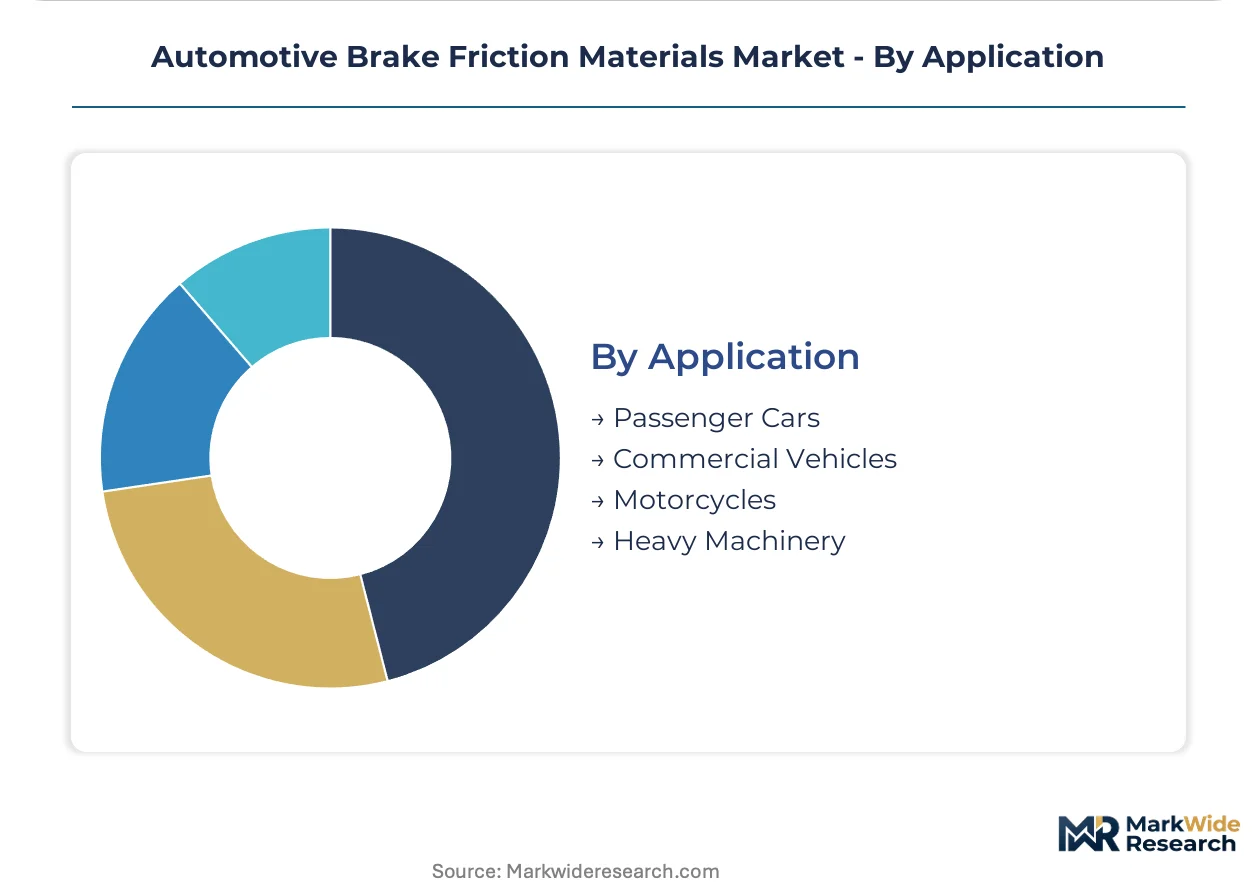
Application:
Operating duty cycle and brake thermal regime dictate formulation specification across vehicle classes.
- Passenger Cars:Noise and dust reduction drive purchasing decisions in premium segments. Ceramic grades absorb development budgets previously allocated to semi-metallic improvements.
- Commercial Vehicles:Heavy-duty thermal loads require copper-free alternatives to match legacy conductivity characteristics. Fleet operators consolidate supplier relationships around certified low-emission lines.
- Motorcycles:Compact brake architectures with exposed friction surfaces. Performance-oriented buyers in Japan and Italy specify sintered metallic formulations.
- Heavy Machinery:Mining and construction equipment requiring extended service intervals under abrasive operating conditions. Coefficient stability across temperature ranges outweighs initial friction performance.
Unit volume concentrates in Passenger Cars; technology investment flows toward Commercial Vehicles as copper-free thermal conductivity gaps close.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's automotive manufacturing corridor concentrates brake friction procurement through Tier-1 supplier consolidation around low-emission platforms. Germany's manufacturing belt anchors European demand as REACH substance restrictions eliminate heavy metal content from formulations.
United States
California and Washington state-level EPA implementation precedes federal harmonization, forcing earliest copper-free inventory turnover among aftermarket distributors. The Brake Pad Partnership agreement mandates reformulation roadmaps with tiered compliance deadlines. Detroit's supplier ecosystem is absorbing ceramic matrix development costs previously allocated to semi-metallic incremental improvements.
Germany
Baden-Württemberg and Bavaria concentrate procurement volumes as brake system integrators consolidate around certified low-emission product lines. ECHA's REACH framework enforces heavy metal elimination from European formulations. Stuttgart's Tier-1 suppliers are dual-testing products under SAE J2522 and AK-Master protocols, extending qualification cycles by 8-14 months.
China
Domestic passenger car production growth is creating first-fit demand for non-asbestos organic formulations without legacy infrastructure displacement. GB standards govern friction performance testing protocols for vehicle certification. Yangtze River Delta manufacturing clusters are aligning domestic testing with international protocols, reducing certification duplication costs for exporters.
Japan
Passenger car OEMs have adopted potassium titanate ceramic formulations for reduced particulate emissions and extended service intervals. METI oversees industrial standards alignment with international brake friction protocols. Nagoya's automotive suppliers face formulation chemist scarcity as specialized expertise in ceramic matrix development concentrates among retiring technical workforces.
India
Domestic vehicle parc expansion is generating first-fit demand for non-asbestos organic formulations without legacy infrastructure lock-in. BIS standards govern friction material certification for domestic vehicle programs. Maharashtra and Tamil Nadu manufacturing corridors are absorbing copper-free thermal management architectures as commercial fleet operators consolidate supplier relationships.
Automotive Brake Friction Materials Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation chemistry and hardware integration tiers. Market structure tilts toward consolidation as fleet operators and national service chains displace fragmented jobber distribution with direct manufacturer agreements. Three archetypes dominate: integrated brake system suppliers with captive friction production, standalone material formulators serving multiple hardware integrators, and motorsport-heritage brands anchoring premium aftermarket positioning. Competitive moves concentrate on backward integration into ceramic fiber supply and multi-year sole-source contracting with corporate fleet managers.
Among European-headquartered system integrators, Continental AG and ZF Friedrichshafen AG exemplify diversified conglomerates with captive friction material production integrated into brake system platforms. Brembo S.p.A. occupies a distinct position, leveraging motorsport heritage to anchor premium positioning in high-performance segments where ceramic grades command margin premiums. These three represent the competitive spectrum from scale-driven integrated supply to brand-differentiated specialty positioning.
| Leading Market Players |
|---|
| Brembo S.p.A. |
| Nisshinbo Holdings Inc. |
| Tenneco Inc. |
| Akebono Brake Industry Co. Ltd. |
| Aisin Corporation |
| ZF Friedrichshafen AG |
| Continental AG |
| Robert Bosch GmbH |
| Federal-Mogul Corporation |
| Others |
Value Network & Pricing Analysis
Captive integration into ceramic fiber supply anchors pricing power for Tier-1 brake system suppliers in Germany and Japan. This upstream control over potassium titanate and aramid fiber sourcing insulates margin positions from petrochemical volatility while enabling premium positioning for copper-free formulations demanded by EPA and ECHA mandates.
Pricing Analysis
Short lead-time premiums command pricing power from aftermarket distributors facing California and Washington state-level EPA compliance deadlines. Three-tier pricing structure across ceramic premium, composite standard, and polymeric economy levels segments buyer sensitivity. OEM procurement contracts compress margins through volume concentration, while fragmented aftermarket channels absorb higher per-unit pricing for certified low-emission inventory. Fleet operators consolidating around national service chains exert countervailing price pressure through multi-year sole-source negotiations.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale procurement from Baden-Württemberg and Bavaria manufacturing clusters. Raw material sourcing draws from China for processed ceramic fibers, Germany for phenolic resin binders, and Japan for potassium titanate feedstock. Single-source vulnerability concentrates in ceramic matrix precursor supply from Nagoya-area specialty chemical producers. Distribution runs through Tier-1 brake system integrators consolidating procurement around certified low-emission platforms, displacing traditional jobber networks with direct manufacturer agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Copper-free ceramic formulations are displacing legacy semi-metallic and metallic friction materials across passenger and commercial vehicle segments. This technology transition compresses legacy product lifecycles while opening margin expansion for suppliers mastering alternative sulfide and oxide chemistries.
For Market Incumbents: Cement backward integration into ceramic fiber supply to defend margin positions against petrochemical binder cost volatility. Lock in multi-year sole-source contracts with corporate fleet operators and national service chains before channel consolidation completes. Prioritize dual SAE J2522 and AK-Master certification investment to extend qualification cycle barriers against emerging competitors. For New Entrants and Emerging Players: Aftermarket distributors in India and Southeast Asia offer the most penetrable channel entry point without legacy infrastructure displacement. Target first-fit demand from domestic vehicle parc expansion in Maharashtra and Tamil Nadu manufacturing corridors. Lead with non-asbestos organic formulations priced below ceramic premiums while meeting BIS certification requirements for commercial fleet procurement. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by diversified brake system integrators seeking captive friction production. Five-to-ten year viability favors suppliers with demonstrated ceramic matrix expertise and established OEM qualification relationships. Monitor EPA state-level implementation timelines as the inflection signal for aftermarket inventory turnover velocity and working capital intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ceramic Fiber Supply | Captive sourcing of potassium titanate from Nagoya-area producers insulates margin from commodity volatility. |
| Dual Certification Investment | Simultaneous SAE J2522 and AK-Master qualification extends product development barriers against emerging competitors. |
| Fleet Operator Direct Contracting | Multi-year sole-source agreements with Monro and Midas displace fragmented jobber distribution channels. |
| Copper-Free Formulation R&D Scale-Up | Bismuth sulfide and engineered oxide development addresses EPA Brake Pad Partnership compliance deadlines. |
| India Manufacturing Footprint Expansion | Maharashtra and Tamil Nadu production absorbs first-fit demand from domestic vehicle parc growth without legacy lock-in. |
Research Methodology
Document review covered vehicle production databases, EPA regulatory filings, and ECHA substance restriction updates, complemented by interviews with Tier-1 supplier procurement managers, OEM platform engineers, aftermarket distribution heads, and ceramic matrix R&D directors. Secondary validation drew from customs trade data, SEC brake component supplier filings, and IHS Markit registration statistics. Bottom-up formulation demand estimates triangulated against top-down automotive production forecasts across the analysis window.
Historical volume trajectories cross-referenced against expert panel input on copper-free adoption timelines shaped the analytical framework. Segmentation dimensions modeled include product type, material chemistry class, end-user channel structure, and vehicle application duty cycle. CAGRs derived from regression analysis of replacement cycle frequencies and content-per-vehicle shifts across propulsion architectures. Industry-specific inputs incorporated REACH phase-out schedules and state-level EPA implementation tiering.
Caveats apply where ceramic matrix thermal conductivity gaps in heavy-duty applications or phenolic resin cost spikes could materially shift the outlook. Forecasts embed assumptions regarding regulatory timeline adherence and OEM platform adoption rates for copper-free architectures. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Ball Bearing Market
Automotive Parts
Tire Mold Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market
Automotive Parts
China Automotive Lubricants Market
Automotive Parts
Global Car Air Filter Market
Automotive Parts
Turkey Passenger Vehicles Lubricants Market
Automotive Parts
Road Marking Machine Market
Automotive Parts
Global Auto Parts and Accessories Market
Automotive Parts
Indonesia Automotive Engine Oils Market
Automotive Parts
Plastic Fuel Tanks Market
Automotive Parts
Bearing Steel Balls for New Energy Vehicles Market
Automotive Parts
Air Filter for Automotive Market
Automotive Parts
Nigeria Automotive Engine Oils Market
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
Automotive Bellows Market
Automotive Parts
Europe Automotive Parts Die Casting Market