
 Automotive Bearing Seals Market | 2026-2036
Automotive Bearing Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Bearing Seals Market Analysis
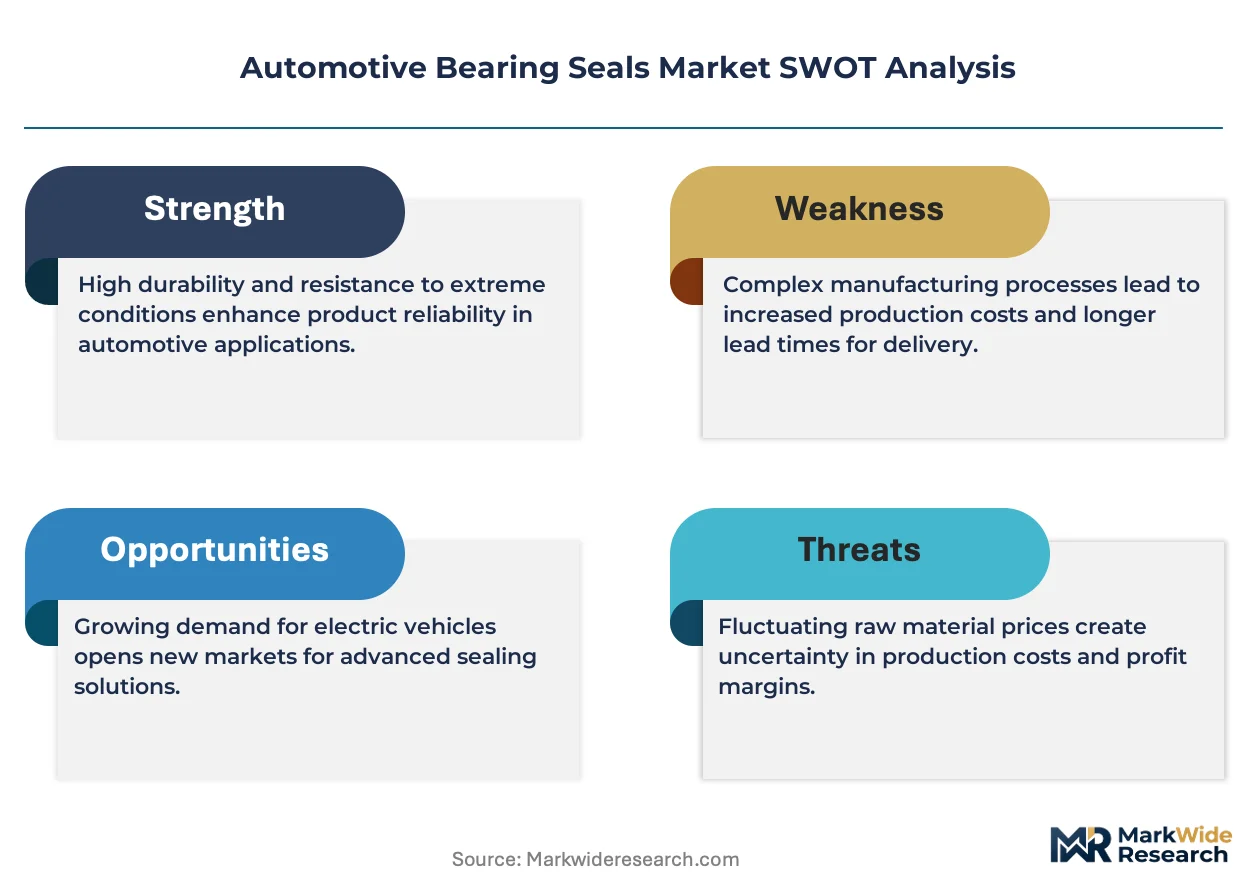
China is tilting toward expanded domestic capacity in precision elastomer components for drivetrain applications. SKF leverages integrated seal-bearing assembly expertise to anchor European OEM supply relationships. Freudenberg Sealing Technologies sustains polymer chemistry leadership that differentiates its fluoroelastomer formulations against commodity alternatives.
Automotive bearing seals are engineered elastomeric or composite closures installed at bearing interfaces to exclude contaminants and retain lubricants under rotational stress, typically rated for operating temperatures spanning negative forty to two hundred degrees Celsius and pressure differentials up to fifteen bar. Radial seals dominate volume given their deployment across wheel hubs, transmissions, and axle differentials, while labyrinth seals command premium positioning in heavy machinery and commercial vehicle applications where abrasive environments demand non-contact sealing architectures. Composite materials represent the fastest-expanding material category as OEMs pursue weight reduction targets without sacrificing chemical resistance against synthetic lubricants.
FDA regulations on per- and polyfluoroalkyl substances constrain fluoroelastomer formulations in seals destined for North American passenger vehicle platforms, while REACH compliance in Europe mandates substitution of specific plasticizers and curatives in rubber compounds. China's GB standards and MIIT directives on new energy vehicle component reliability are accelerating validation protocols for seal suppliers targeting domestic EV manufacturers. Stakeholders must monitor regulatory divergence between EPA, ECHA, and NMPA frameworks when allocating R&D budgets across regional product lines.
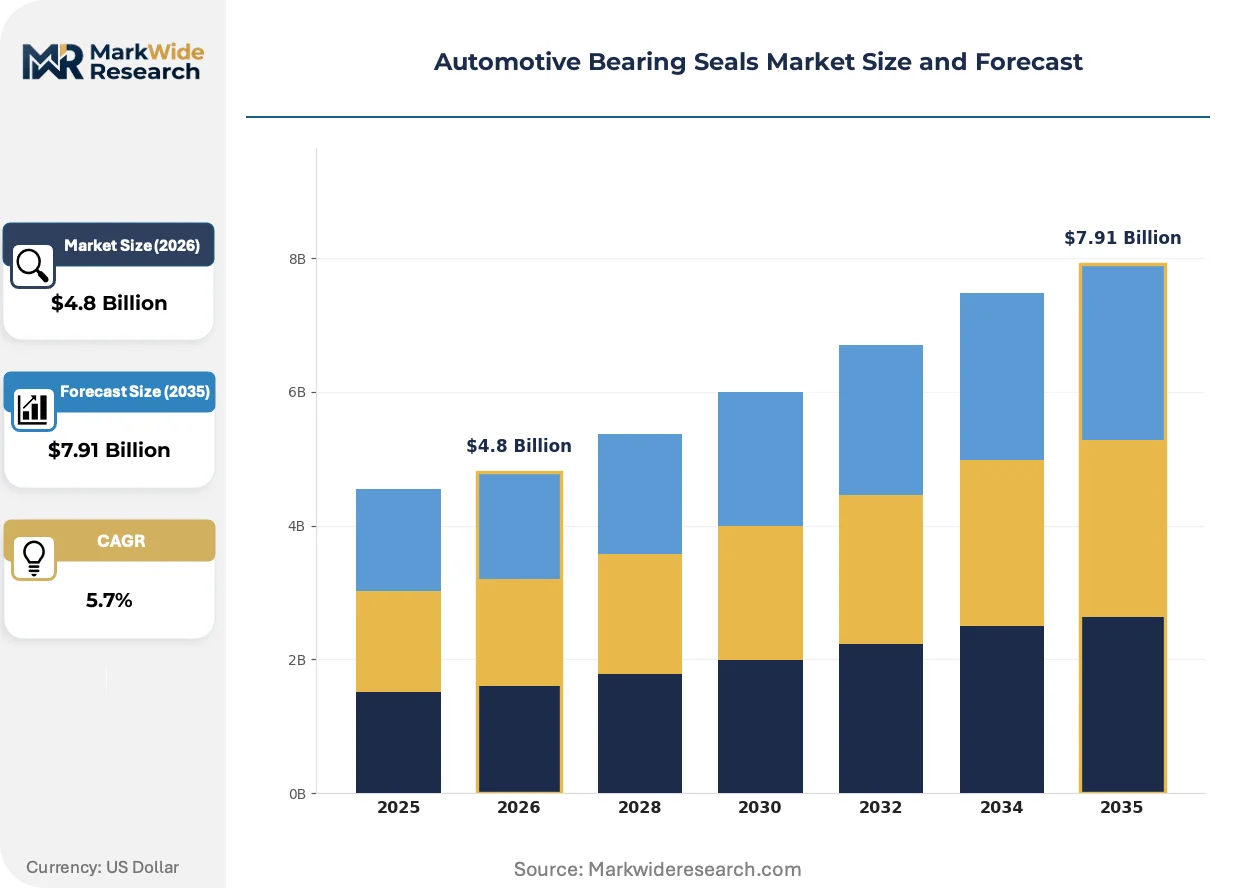
Market Dynamics
Electric vehicle powertrain architectures are eliminating traditional transmission seals while creating demand for high-speed motor bearing seals rated for 20,000+ RPM operation, forcing suppliers to reallocate R&D from mature ICE applications.
Growth Catalysts
- China's NMPA vehicle safety protocols:Accelerated validation timelines for seal suppliers targeting domestic EV manufacturers are compressing product development cycles and favoring established compounders with in-house testing facilities.
- Composite material substitution:OEM weight reduction mandates are expanding PTFE-aramid hybrid seal adoption in axle and hub applications previously served by solid rubber designs.
- Germany's automotive manufacturing corridor:Precision component sourcing concentration for premium drivetrains sustains demand for labyrinth seal architectures in heavy commercial platforms.
Market Restraints
- Fluoroelastomer feedstock volatility:Per- and polyfluoroalkyl substance regulatory scrutiny under FDA and REACH frameworks is constraining FKM compound availability and elevating raw material costs for North American and European suppliers.
- Supply concentration in precision elastomer processing:China's expanded domestic capacity for drivetrain seals is displacing import-dependent sourcing patterns and pressuring margin structures for non-integrated competitors.
- Technical ceiling in high-speed rotary sealing:Contact seal architectures face fundamental friction-heat limitations above 15,000 RPM, capping addressable market share in performance EV motor applications.
Strategic Opportunities
- India's commercial vehicle upfit market:Underpenetrated aftermarket replacement demand for wheel hub and differential seals offers white space for suppliers establishing localized compounding and molding operations.
- Sensor-integrated smart seals:Convergence of elastomer sealing with embedded wear-monitoring electronics creates premium positioning for predictive maintenance contracts in fleet operator procurement.
- EU F-Gas Regulation phase-down:Refrigerant containment seal demand for electric vehicle thermal management systems represents a regulatory tailwind distinct from powertrain applications.
Industry Challenges
- Compound formulation expertise scarcity:Qualified polymer chemists capable of balancing chemical resistance, compression set, and dynamic friction properties remain concentrated at incumbent suppliers, constraining new entrant scale-up.
- Dual certification timeline compression:Simultaneous GB standard validation for China and REACH compliance for Europe extends product qualification cycles by 18-24 months, freezing working capital in pre-revenue development programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Bearing Seals Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Seals, Axial Seals, Labyrinth Seals, Rotary Seals Material: Rubber, Polyurethane, Metal, Composite End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Vehicles, Commercial Vehicles, Two-Wheelers, Heavy Machinery |
| Companies Covered | SKF, Timken, NSK, NTN, Schaeffler, JTEKT, Freudenberg Sealing Technologies, Trelleborg Sealing Solutions, C&U, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Bearing Seals Market Emerging Trajectories
Material science advances and regulatory chemistry constraints are bifurcating the seal market into commodity elastomer volumes and premium fluoropolymer specialties, with manufacturing process innovation determining competitive position.
PTFE-impregnated fabric composite seals are penetrating wheel hub and transmission applications where nitrile rubber previously dominated thermal and chemical resistance specifications. Tier 1 suppliers in Germany and Japan are qualifying these architectures for 300,000-kilometer service intervals. This material transition is rendering obsolete conventional lip seal designs in synthetic lubricant environments.
REACH authorization requirements for specific plasticizers and curatives are forcing European compounders to reformulate legacy nitrile and hydrogenated nitrile recipes ahead of sunset dates. The industrial consequence is elevated R&D expenditure and extended validation timelines for replacement chemistries. Passenger vehicle platforms destined for EU markets are experiencing the most acute certification bottlenecks, with suppliers dual-tracking GB standard compliance for parallel China market entry.
Fleet operators and commercial vehicle OEMs are consolidating seal procurement under long-term lubricant system supplier contracts rather than discrete component sourcing. This channel consolidation is compressing supplier direct relationships and elevating lubricant formulators to gatekeeper status. The shift is most visible in North American heavy-duty trucking, where integrated drivetrain service agreements now specify seal performance as a subsystem warranty element rather than independent component specification.
Automotive Bearing Seals Market Segmentation
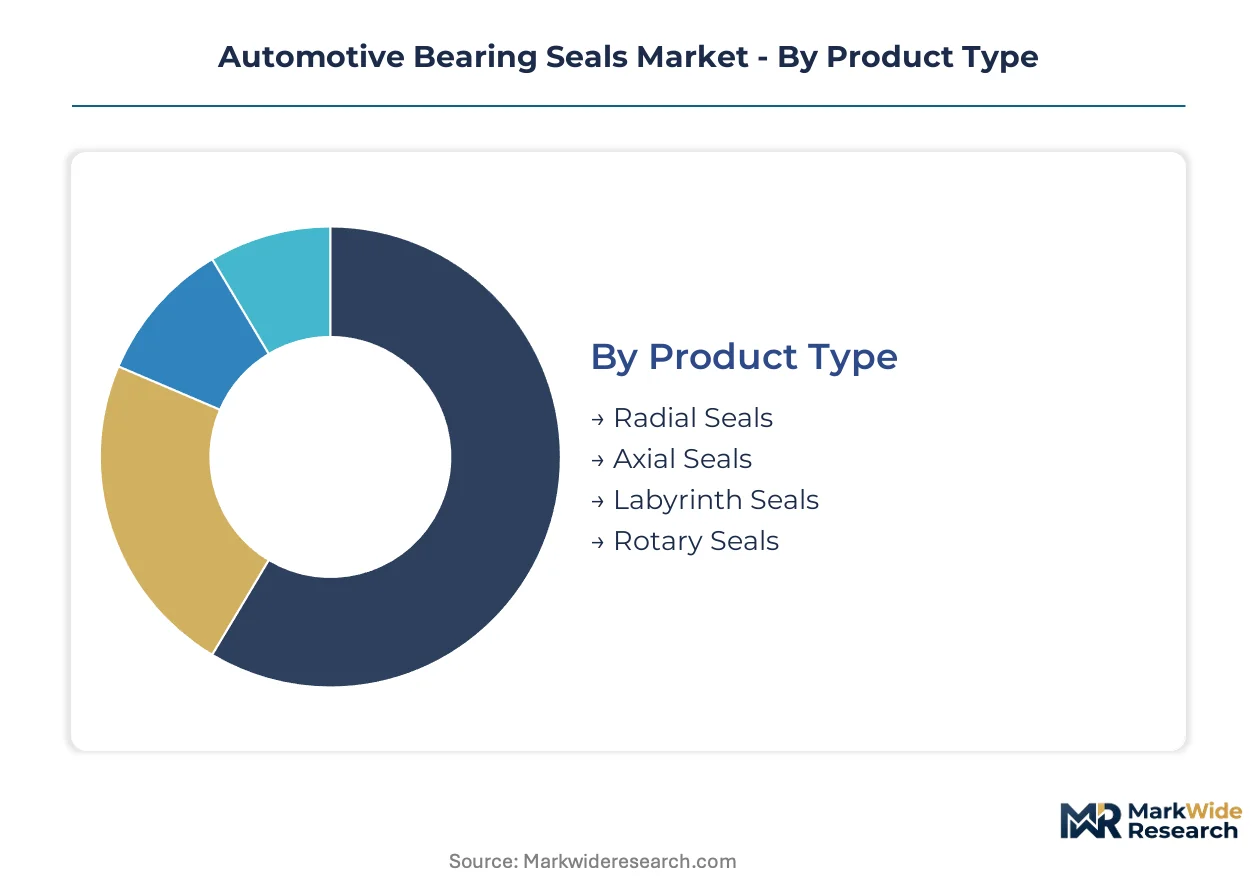
Automotive bearing seals serve divergent mechanical stresses across powertrain architectures. Segmentation reveals how material science and application requirements partition procurement budgets and supplier capabilities.
Product Type:
Use-case spectrum spans contact-based exclusion seals to non-contact architectures for abrasive environments.
- Radial Seals:Elastomeric lip designs with spring-loaded garter springs maintain lubricant retention in rotating shafts. Wheel hub and transmission applications in Germany's automotive manufacturing corridor sustain volume concentration as OEMs specify 300,000-kilometer service intervals.
- Labyrinth Seals:Non-contact geometries employing tortuous path designs exclude contaminants without friction wear. Heavy commercial platforms in mining and construction specify these architectures where abrasive dust penetration risks bearing failure.
- Axial Seals:Face-sealing configurations address thrust-loaded bearing arrangements in axle differentials.
- Rotary Seals:High-speed variants rated for 15,000+ RPM operation serve electric motor bearings in EV powertrains.
The dominant share belongs to Radial Seals, while Labyrinth Seals is closing the gap fastest in commercial vehicle procurement.
Material:
Cost tier stratification separates commodity elastomer volumes from fluoropolymer specialties with chemical resistance premiums.
- Composite:PTFE-aramid hybrid constructions deliver weight reduction without sacrificing thermal stability. OEM mandates for axle and hub lightweighting are accelerating substitution of solid rubber in synthetic lubricant environments.
- Rubber:Nitrile and hydrogenated nitrile compounds dominate legacy ICE applications with proven compression set performance. REACH authorization timelines for specific plasticizers are forcing European compounders into reformulation cycles.
- Polyurethane:Castable formulations offer abrasion resistance in construction equipment hydraulics.
- Metal:Stainless steel and aluminum housings provide structural rigidity in high-pressure differentials.
Composite materials command the steepest expansion trajectory as weight targets tighten, though Rubber retains volume leadership in cost-sensitive platforms.
End User:
Customer type determines specification authority and contract structure across the value chain.
- OEMs:Direct powertrain engineering teams specify seal performance as subsystem warranty elements. Integrated drivetrain service agreements in North American heavy-duty trucking now embed seal requirements within lubricant system contracts.
- Tier-1 Suppliers:Drivetrain integrators consolidate component procurement under long-term supply agreements. SKF and Freudenberg leverage integrated seal-bearing assembly expertise to anchor these relationships.
- Aftermarket Providers:Independent distributors serve replacement demand in vehicle parc maintenance.
- Vehicle Assemblers:Final assembly operations specify seals for chassis and auxiliary systems.
OEMs retain specification control, while Tier-1 Suppliers are consolidating procurement influence through subsystem integration.
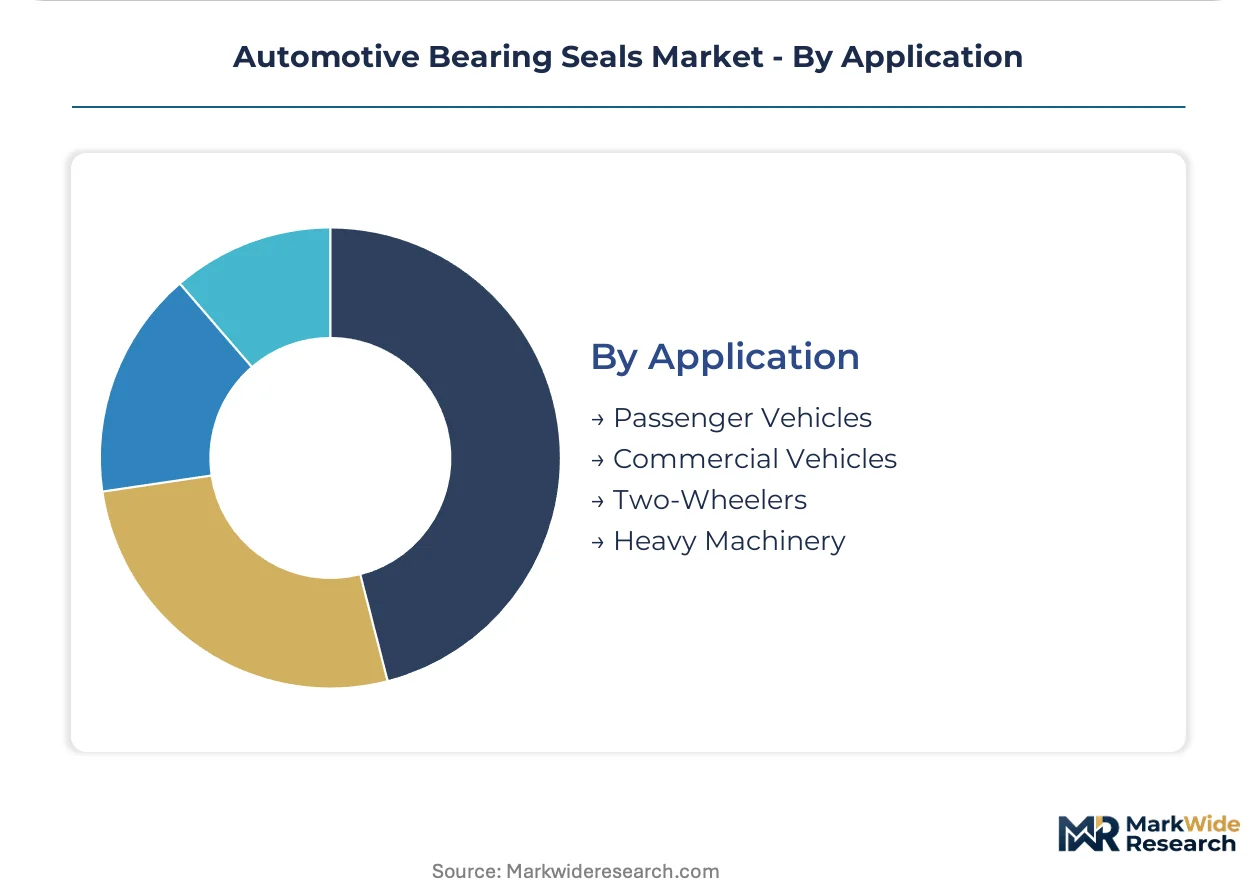
Application:
Volume concentration maps to vehicle production geography and powertrain electrification pace.
- Passenger Vehicles:High-volume platforms specify nitrile rubber seals for wheel hubs and transmissions. China's NMPA validation protocols for new energy vehicles are compressing supplier qualification timelines for domestic EV manufacturers.
- Commercial Vehicles:Heavy-duty specifications demand labyrinth architectures and extended service intervals. Fleet operator consolidation under lubricant system contracts is elevating formulators to gatekeeper status.
- Two-Wheelers:Cost-optimized radial seals serve high-volume emerging market production.
- Heavy Machinery:Mining and construction equipment specifies abrasion-resistant polyurethane and metal-reinforced designs.
Passenger Vehicles anchor procurement volume, while Commercial Vehicles generates premium pricing through performance specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. Germany prioritizes precision-engineered seals for extended service intervals, while China sources high-volume elastomer components for domestic EV platforms. India's aftermarket replacement cycles run shorter than OEM specifications elsewhere.
Germany
Premium drivetrain manufacturing concentrates demand for labyrinth seal architectures in heavy commercial platforms. REACH authorization timelines for specific plasticizers and curatives force compounders into reformulation cycles ahead of sunset dates. The Stuttgart-Munich manufacturing corridor anchors precision component sourcing for 300,000-kilometer service interval specifications.
China
Domestic EV powertrain expansion drives demand for high-speed rotary seals rated beyond 15,000 RPM. NMPA vehicle safety protocols and evolving GB standards compress supplier validation timelines for seal manufacturers targeting BYD, NIO, and domestic OEMs. Yangtze River Delta industrial clusters concentrate precision elastomer processing capacity that displaces import-dependent sourcing.
United States
Heavy-duty trucking fleet consolidation shifts procurement toward integrated drivetrain service agreements rather than discrete component sourcing. FDA regulations on per- and polyfluoroalkyl substances constrain fluoroelastomer formulations for passenger vehicle platforms. Michigan and Ohio manufacturing corridors sustain demand for nitrile rubber seals in legacy ICE transmission applications.
India
Commercial vehicle upfit markets present underpenetrated aftermarket replacement demand for wheel hub and differential seals. BIS certification requirements and PLI scheme incentives for automotive component manufacturing accelerate localized compounding investments. Maharashtra and Gujarat industrial zones concentrate emerging molding operations serving domestic CV parc maintenance.
Japan
Hybrid powertrain architectures sustain demand for dual-compatibility seals serving both electric motor and thermal management systems. METI directives on new energy vehicle component reliability align with JIS standards for seal performance validation. Nagoya and Tokyo manufacturing basins concentrate tier-1 supplier relationships with integrated seal-bearing assembly expertise.
Automotive Bearing Seals Market Vendor Landscape
Capability concentration sits with integrated seal-bearing assembly specialists; scale advantage sits with diversified elastomer compounders with captive polymer chemistry expertise. The vendor base separates into three tiers: multinational integrated system suppliers, regional compounders with formulation specialization, and commodity fabricators serving aftermarket replacement cycles. Consolidation pressure runs through long-term lubricant system contracts that elevate formulators to procurement gatekeepers. Geographic expansion and backward integration into polymer feedstock represent dominant competitive vectors.
Among integrated system suppliers, SKF and Freudenberg Sealing Technologies exemplify the capability-intensive tier where seal-bearing assembly expertise anchors European OEM relationships. NSK occupies a position within the precision engineering archetype serving high-speed rotary applications. These three companies represent contrasting geographic origins—Swedish, German, and Japanese respectively—while each sits within distinct competitive positioning around formulation chemistry versus integrated assembly expertise.
| Leading Market Players |
|---|
| SKF |
| Timken |
| NSK |
| NTN |
| Schaeffler |
| JTEKT |
| Freudenberg Sealing Technologies |
| Trelleborg Sealing Solutions |
| C&U |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta industrial clusters anchor global capacity for precision elastomer seals, concentrating compound formulation expertise that translates into asymmetric pricing power for integrated suppliers serving high-speed EV motor applications. This geographic concentration of PTFE-aramid hybrid processing capability allows established compounders to maintain margin premiums while commodity nitrile rubber fabricators face cost compression from China's expanded domestic production.
Pricing Analysis
Price spreads between European REACH-compliant formulations and Chinese domestic-grade compounds have widened as regulatory divergence intensifies. Three-tier pricing structure across premium fluoropolymer, certified hydrogenated nitrile, and economy nitrile segments reflects certification burden and thermal performance ratings. Pricing pressure stems from China's NMPA-accelerated validation timelines compressing premium tier durability premiums. Aftermarket distributors exhibit highest price sensitivity, while OEM platform engineers prioritize performance guarantees over unit cost.
Supply Chain Analysis
Fluoroelastomer feedstock supply concentrates in Germany, Japan, and the United States, with FKM polymer production tethered to specialty chemical complexes subject to EPA and REACH authorization constraints. Raw material dependencies span fluoropolymer resins, aramid fiber reinforcements, and metal garter spring components. Single-source vulnerability runs through specialty curative additives facing sunset dates under European chemical regulations. Distribution runs through Tier 1 drivetrain integrators consolidating procurement under lubricant system contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive bearing seals sit in early-cycle expansion as electric vehicle powertrain architectures create fresh demand for high-speed rotary sealing solutions absent from legacy ICE platforms. Penetration headroom concentrates in sensor-integrated smart seal categories where predictive maintenance contracts remain underdeveloped.
For Market Incumbents: Insulate European OEM relationships by accelerating backward integration into fluoropolymer resin production, countering feedstock volatility that threatens FKM compound margins. Anchor certification advantages through dual-track GB standard and REACH compliance investments that freeze competitor qualification timelines. Prioritize labyrinth seal architecture R&D for heavy commercial platforms where abrasive environment specifications sustain premium positioning. For New Entrants and Emerging Players: India's commercial vehicle upfit aftermarket presents underpenetrated replacement demand for wheel hub and differential seals, with BIS certification requirements creating manageable entry barriers against established suppliers. Localized compounding investments in Maharashtra and Gujarat industrial zones capture domestic CV parc maintenance cycles. Lead with price-competitive nitrile rubber formulations for cost-optimized two-wheeler production serving emerging market volume. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because regulatory chemistry constraints and dual-certification timelines favor compounders with captive formulation expertise over commodity fabricators. Target acquisition archetypes include regional European compounders with REACH-authorized recipes and underutilized testing facilities. Watch for inflection in EV motor bearing seal qualification volumes at Chinese domestic OEMs as signal of share shift toward high-speed rotary specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Resin Production | Captive FKM supply insulates margin structure from REACH authorization bottlenecks at European chemical suppliers. |
| Dual-Certification Testing Facility Investment | In-house GB standard and REACH validation capability compresses product development cycles for China-Europe parallel launches. |
| Sensor-Integrated Smart Seal Development | Embedded wear-monitoring electronics unlock predictive maintenance contracts with North American heavy-duty fleet operators. |
| Localized Compounding Operations in India | Maharashtra and Gujarat production footprint captures commercial vehicle aftermarket replacement demand under PLI scheme incentives. |
| Long-Term Lubricant System Supplier Partnership | Integration into consolidated procurement contracts elevates seal specification to subsystem warranty tier with formulator gatekeepers. |
Methodological Framework
A spread of perspectives from OEM platform engineers, Tier 1 drivetrain procurement leads, aftermarket distribution managers, and polymer compound R&D directors converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation against vehicle production databases, customs and trade flow records, IHS Markit registration data, and SEC filings from listed automotive component suppliers. Bottom-up segmentation modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Demand-supply balance dynamics across the projection horizon shaped the analytical framework, with segmentation modeling spanning seal architecture type, material grade tier, propulsion architecture compatibility, and regional production cluster concentration. CAGRs derived from fitted growth curves applied to disclosed OEM platform volumes and EV penetration assumptions. Industry-specific forecast inputs included NMPA validation timeline compression effects and REACH authorization sunset schedules for plasticizer compounds.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese domestic compounders or accelerated FKM feedstock substitution would shift outcomes beyond modeled ranges. Cross-checking against IHS Markit vehicle production forecasts and disclosed Tier 1 supplier order backlogs is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Steel Cords for Radial Tyres Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Fuel Supply System Market
Automotive Parts
Gasoline Direct Injection Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Middle East Automotive Engine Oils Market
Automotive Parts
AWD Coupling System Market
Automotive Parts
Automotive Suspension Control Arms Market
Automotive Parts
Automotive Roller Bearing Market
Automotive Parts
Struts System Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Ceramic Matrix Composite Disc Brakes (CMC Brake Disc) Market
Automotive Parts
South America Automotive Engine Oils Market
Automotive Parts
Battery Jump Starters Market
Automotive Parts
Autocatalyst Market