
 Italy Automotive Parts Magnesium Die Casting Market | 2026-2036
Italy Automotive Parts Magnesium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Automotive Parts Magnesium Die Casting Market Foresight
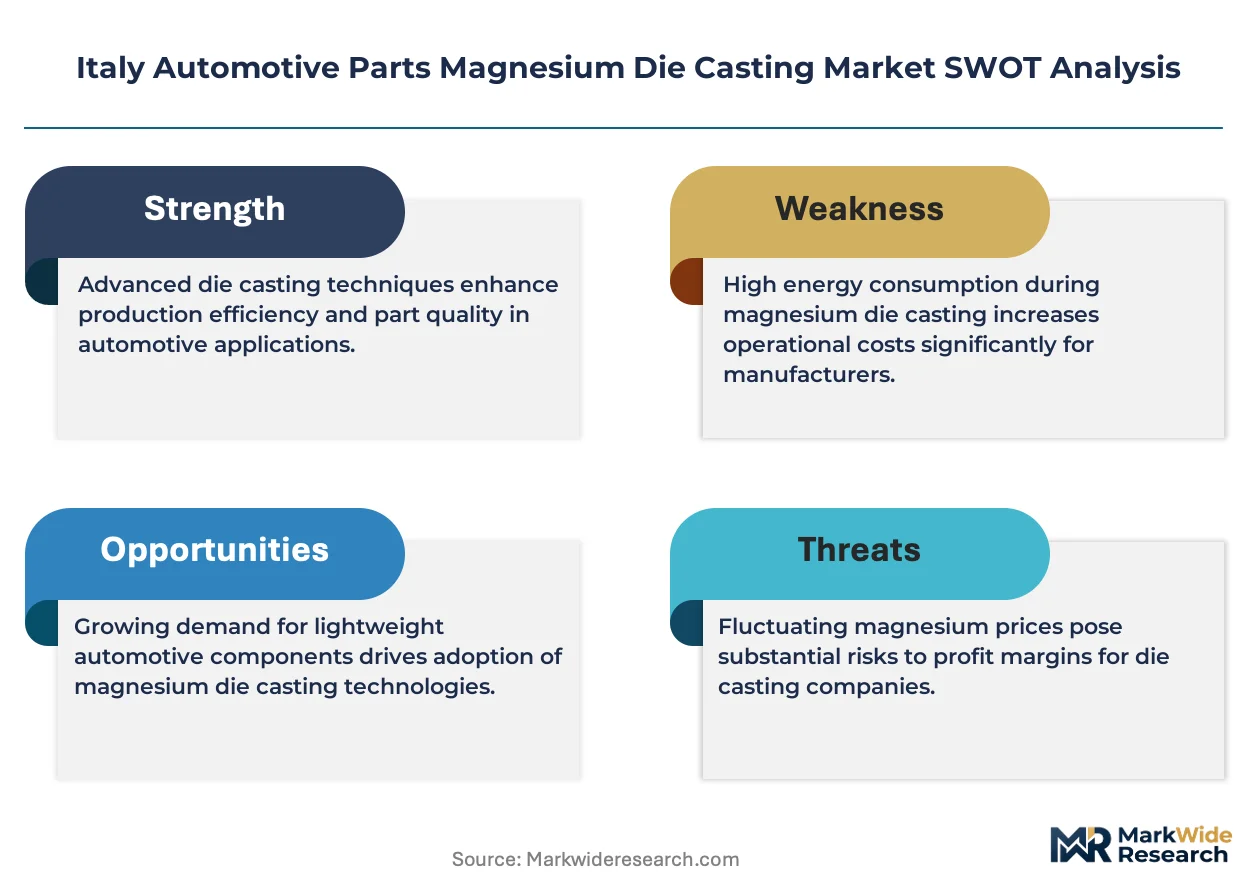
Italy is fragmenting its automotive magnesium die casting capacity across the industrial triangle of Turin, Milan, and Bologna as electrification reshapes component sourcing. Georg Fischer AG leverages its Swiss-Italian engineering footprint to sustain high-pressure die casting leadership for powertrain applications. Meridian Lightweight Technologies anchors North American lightweighting expertise into Italian OEM supply chains through specialized structural part production.
Automotive parts magnesium die casting involves injecting molten magnesium alloy—typically AZ91D or AM60B with density of 1.8 g/cm³—into steel molds under pressures exceeding 1,000 bar to produce complex, thin-walled components with superior stiffness-to-weight ratios for vehicle mass reduction. Engine components dominate current output volumes, while structural parts capture expanding margin pools as crashworthiness requirements intensify for battery electric platforms. High-pressure die casting leads technology deployment, though gravity die casting retains niche positions in prototype and low-volume finishing stages where surface integrity demands exceed cycle speed priorities.
Italy's Ministry of Enterprise and Made in Italy (MIMIT) coordinates with EU REACH compliance frameworks and CE marking directives to enforce alloy purity standards and workplace exposure limits in foundry operations. The EU Green Deal's embedded carbon border adjustments reshape sourcing economics for imported magnesium feedstock, pressuring domestic recyclers to scale secondary alloy recovery. Stakeholders must monitor how the EU Critical Raw Materials Act reclassifies magnesium supply security and whether Italian foundries secure preferential access to European smelter allocations.
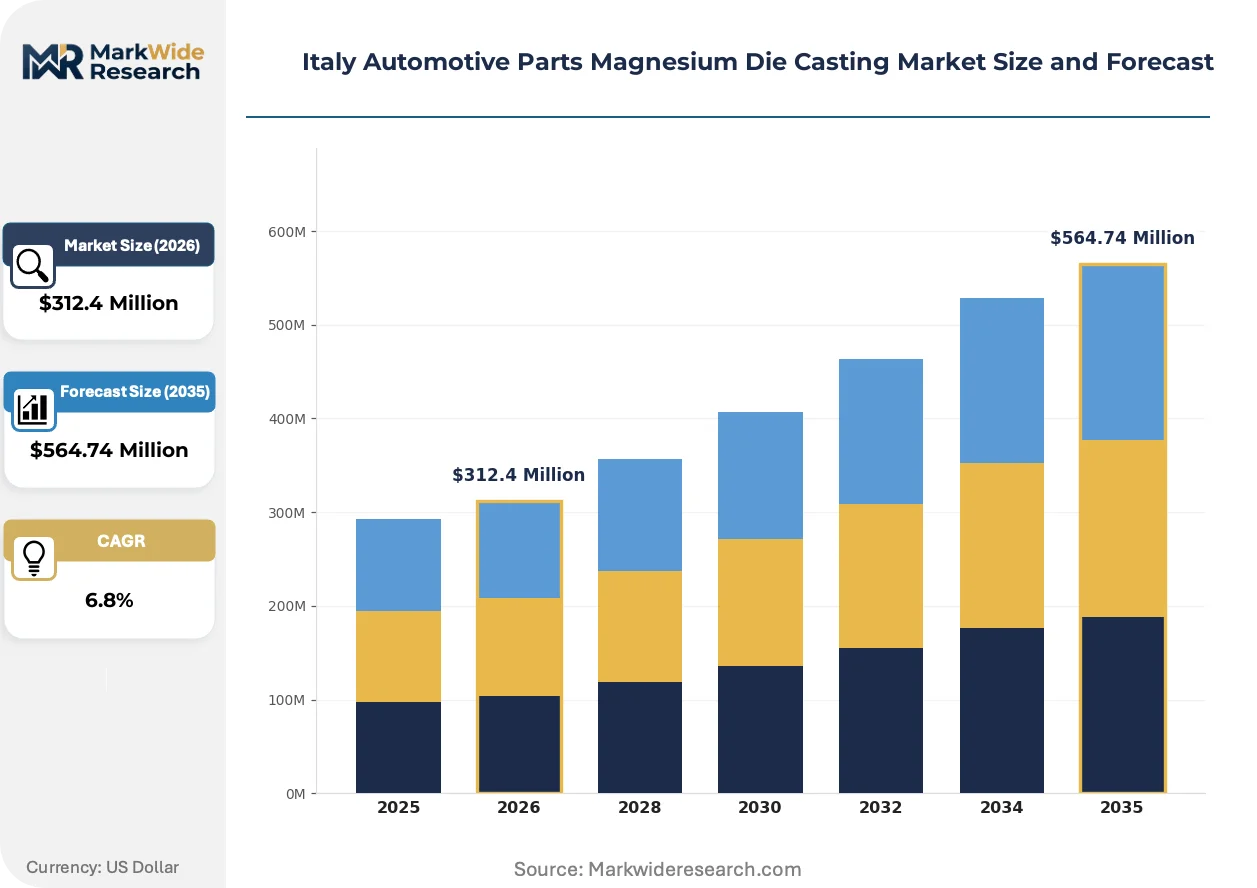
Market Dynamics
Electrification is compressing traditional engine component demand while simultaneously expanding structural magnesium applications for battery housings and crash-critical EV architectures across Italian manufacturing corridors.
Growth Catalysts
- PNRR Lightweighting Incentives:Italy's National Recovery and Resilience Plan directs capital subsidies toward die casting equipment modernization for Tier-1 suppliers serving electrified platforms.
- AZ91D Alloy Specification:AM60B and AZ91D magnesium alloys with 1.8 g/cm³ density enable 30-40% mass reduction versus aluminum equivalents in powertrain housings.
- Emilia-Romagna Cluster Density:Bologna-Modena manufacturing concentration reduces logistics friction between foundries and Stellantis/Ferrari/Lamborghini assembly plants.
Market Restraints
- Chinese Magnesium Feedstock Concentration:EU reliance on PRC-sourced primary magnesium exposes Italian foundries to carbon border adjustment penalties under EU Green Deal implementation.
- REACH Alloy Purity Compliance:ECHA-mandated exposure limits for molten metal handling increase foundry capex requirements for ventilation and worker protection systems.
- Steel Substitution in Crash Structures:Advanced high-strength steel grades retain cost advantages for certain battery enclosure applications where magnesium casting complexity exceeds value capture.
Strategic Opportunities
- Southern Italy Capacity Expansion:Underutilized industrial zones in Apulia and Sicily offer labor cost arbitrage for foundries serving export-oriented OEM supply chains.
- High-Pressure Die Casting Convergence:Integration of real-time thermal monitoring with robotic extraction systems reduces porosity defects in thin-walled EV structural components.
- EU Critical Raw Materials Act Reserves:Preferential European smelter allocation mechanisms under CRMA implementation could secure domestic magnesium feedstock for Italian recyclers.
Industry Challenges
- Tooling Engineer Scarcity:Retirement waves among Bologna-trained die designers outpace vocational pipeline output for complex multi-slide casting geometries.
- CE Marking Timeline Compression:Extended conformity assessment periods for novel alloy formulations delay qualification for safety-critical automotive applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Automotive Parts Magnesium Die Casting Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Cases, Structural Parts, Chassis Parts End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Manufacturing Stage: Design, Prototype, Production, Finishing Technology: High-Pressure Die Casting, Gravity Die Casting, Cold Chamber, Hot Chamber |
| Companies Covered | Gibbs Die Casting Group, Pace Industries, Shiloh Industries, Georg Fischer AG, Meridian Lightweight Technologies, Dynacast, Brabant Alucast, Chicago White Metal Casting, GF Automotive, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Automotive Parts Magnesium Die Casting Market Shifts & Advancements
Process digitization and alloy formulation advances are redefining competitive capability thresholds for Italian magnesium die casters supplying electrified vehicle architectures.
Thin-wall high-pressure die casting with wall thickness below 1.5mm is rendering obsolete conventional gravity casting for EV battery tray production. Stellantis and Ferrari procurement teams specify these geometries for 2026 platform launches. The technology is rendering obsolete older foundry equipment incapable of maintaining thermal uniformity across complex rib structures.
EU Green Deal carbon border adjustment mechanisms reshape magnesium feedstock economics for Italian foundries. Embedded emissions tracking now determines landed cost competitiveness between primary and secondary alloy sources. Northern European OEMs increasingly specify recycled-content thresholds in supplier qualification protocols.
Consolidated Tier-1 procurement is compressing supplier qualification cycles from 18 months to 9 months for magnesium structural components. Single-source agreements with integrated die casting-machining operations disperse fragmented multi-vendor arrangements. This concentration is most visible in Emilia-Romagna supply corridors serving premium EV platforms.
Italy Automotive Parts Magnesium Die Casting Market Segmentation
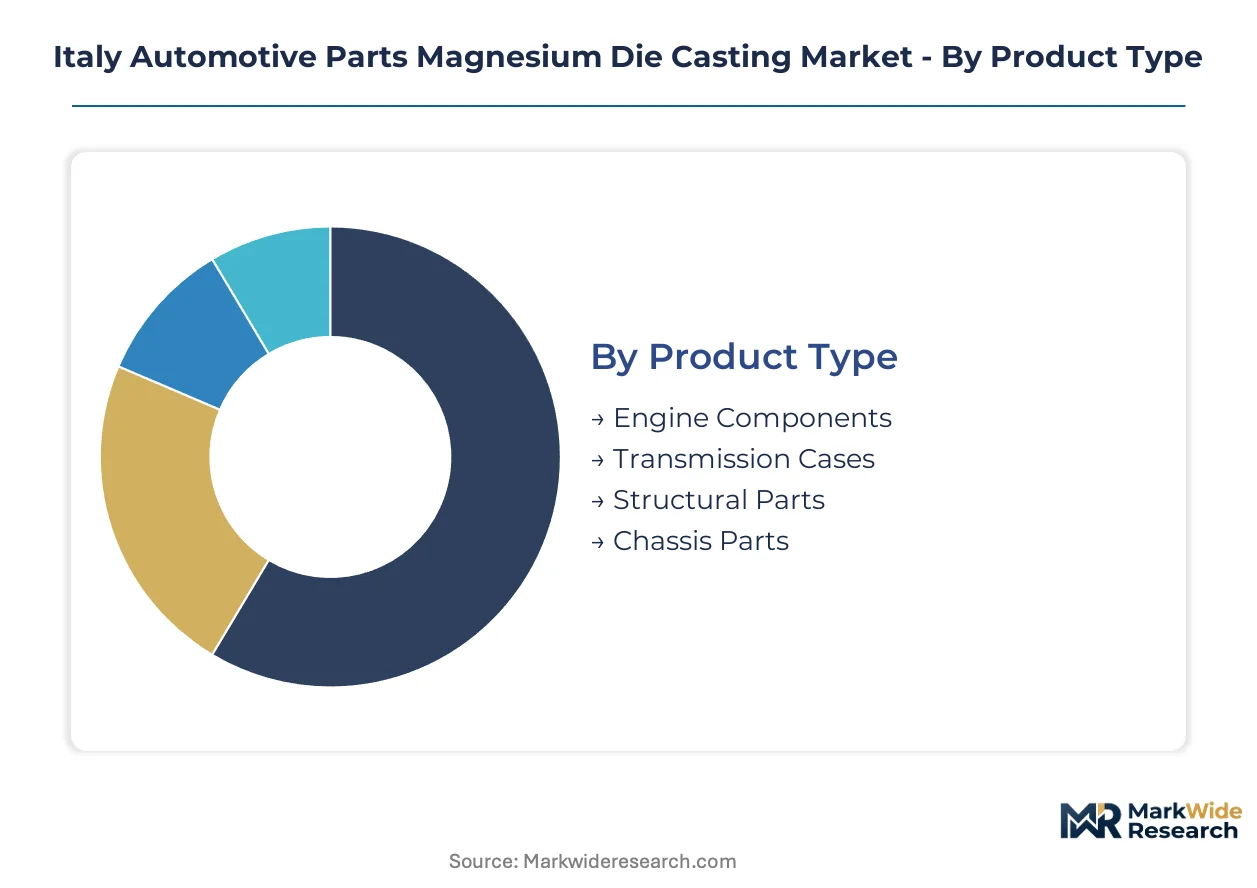
Magnesium die casting suppliers in Italy configure service intensity and technical support differently across segment boundaries. Product complexity and qualification timelines determine aftermarket attachment rates and customer retention economics for foundries serving the Emilia-Romagna automotive corridor.
Product Type:
After-sales service intensity varies sharply across product categories, with structural parts demanding sustained engineering support while engine components rely on standardized replacement programs.
- Structural Parts:Battery housings and crash-critical castings require AZ91D alloy with wall thickness below 1.5mm for EV platform compliance. Stellantis procurement teams in Turin specify these geometries for premium electrified architectures, driving qualification cycles that extend technical service obligations across multi-year supply agreements.
- Engine Components:Cylinder head covers and oil pans utilize AM60B magnesium alloy with established tooling libraries and predictable wear patterns. Bologna-area foundries supply Ferrari and Lamborghini powertrain divisions through legacy programs with compressed aftermarket response windows.
- Transmission Cases:Hybrid transmission housings integrate cooling channels and mounting bosses for electrified drivetrains.
- Chassis Parts:Steering column brackets and pedal assemblies serve volume OEM platforms with standardized durability specifications.
By volume, engine components lead. By growth pace, structural parts are ahead.
End User:
Customer concentration shapes margin architecture, with Tier-1 suppliers capturing integrated die casting-machining value while aftermarket providers fragment across low-volume replacement demand.
- Tier-1 Suppliers:Integrated manufacturing operations serving Stellantis and Ferrari consolidate procurement through single-source agreements with real-time quality monitoring. These relationships concentrate in Modena-Bologna supply corridors where logistics friction costs determine competitive positioning.
- OEMs:Direct foundry relationships with Lamborghini and Maserati prioritize prototype-to-production continuity for low-volume specialty platforms.
- Aftermarket Providers:Independent distributors serve aging vehicle fleets with reverse-engineered replacement castings.
- Vehicle Assemblers:Contract manufacturers for export-oriented EV startups source standardized structural components.
Tier-1 suppliers command the deepest supplier relationships. Aftermarket providers are expanding most quickly as EV fleet age accumulates.
Manufacturing Stage:
Process maturity determines capital recovery profiles, with production-stage operations amortizing equipment across high-volume cycles while prototype services capture premium pricing for unproven geometries.
- Production:High-pressure die casting cells with robotic extraction and thermal monitoring achieve cycle times under 90 seconds for thin-walled EV battery trays. Emilia-Romagna foundries deploy these systems for Stellantis platform launches with embedded quality verification.
- Prototype:Gravity die casting and soft-tooling approaches validate complex rib structures before hard-tooling commitment for safety-critical applications.
- Design:Collaborative engineering with OEM chassis teams optimizes casting geometry for manufacturability and mass reduction targets.
- Finishing:CNC machining, surface treatment, and leak testing complete dimensional compliance for powertrain sealing requirements.
Production dominates capital deployment. Design services are climbing the fastest as OEMs front-load engineering collaboration.
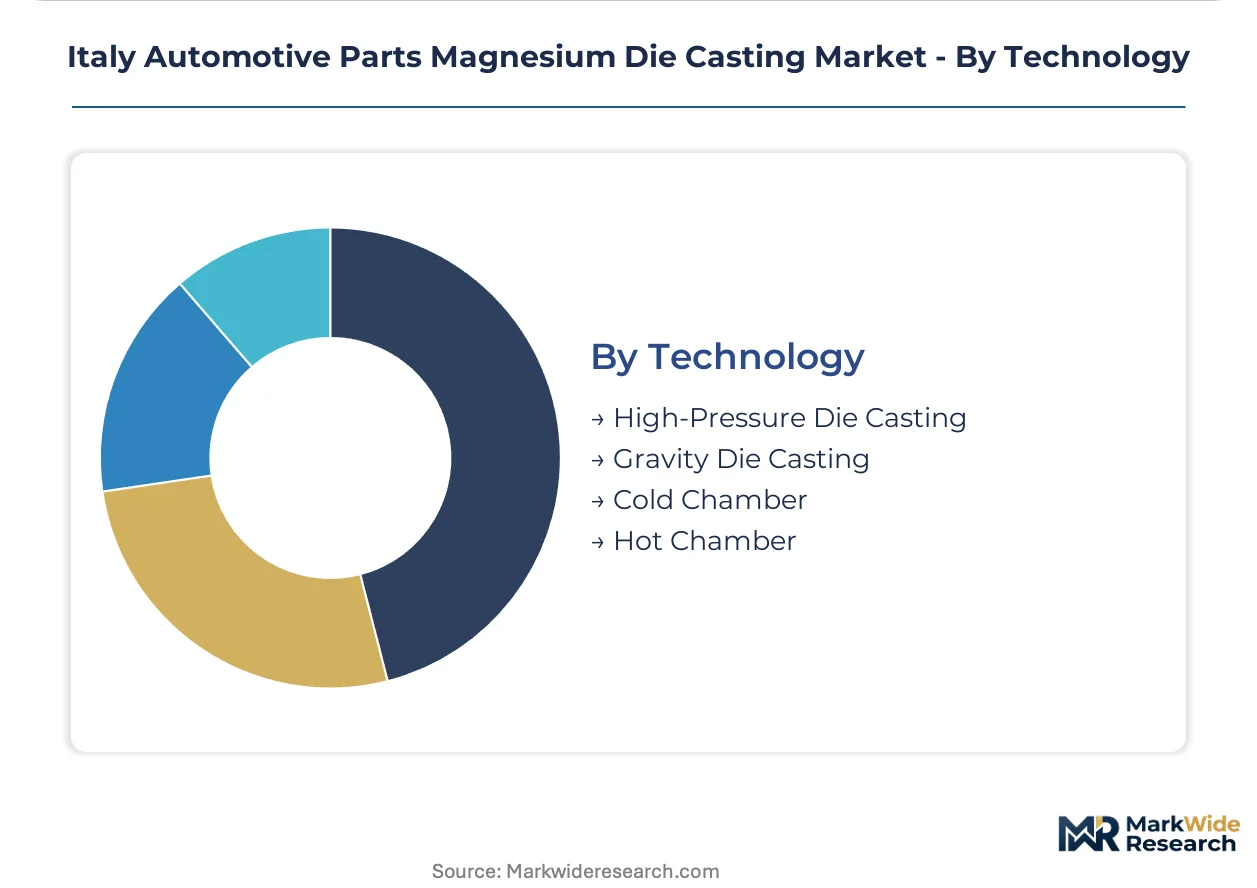
Technology:
Equipment vintage stratifies competitive capability, with hot chamber systems retaining cost advantages for small complex geometries while cold chamber dominance grows for large structural castings.
- High-Pressure Die Casting:Multi-slide tooling with real-time thermal management produces porosity-free castings for crash-critical battery enclosures. Bologna-area specialists deploy these systems for Ferrari EV architectures with wall thickness uniformity requirements.
- Hot Chamber:Magnesium-compatible gooseneck systems inject molten alloy without transfer operations, reducing oxide inclusion for small intricate components.
- Cold Chamber:Horizontal shot sleeve configurations handle larger shot weights for transmission cases and structural housings.
- Gravity Die Casting:Low-pressure permanent mold techniques serve prototype validation and low-volume finishing where surface integrity exceeds cycle speed priorities.
High-pressure die casting anchors production capacity. Cold chamber installations are gaining share fastest as structural part dimensions expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian magnesium die casting capacity clusters along three industrial axes, with electrification redrawing procurement maps across the peninsula. Foundry investment flows toward regions offering proximity to electrified vehicle assembly or labor cost advantages for export platforms.
Emilia-Romagna
Bologna and Modena anchor the densest concentration of Tier-1 magnesium suppliers serving Stellantis and Ferrari electrified architectures. MIMIT coordinates with EU REACH frameworks to enforce workplace exposure limits in this corridor's foundry operations. Real-time thermal monitoring systems are displacing legacy equipment for thin-walled battery tray production.
Piedmont
Turin-based OEM procurement teams specify magnesium structural components for upcoming EV platform launches, compressing supplier qualification timelines. The EU Green Deal's carbon border adjustments pressure local foundries to document embedded emissions in imported feedstock. Tooling engineering scarcity is acute as retirement waves outpace vocational training output.
Lombardy
Milan's financial and engineering services support die casting modernization across the industrial triangle. CE marking directives from Brussels extend conformity assessment periods for novel alloy formulations. Brescia-area foundries are deploying robotic extraction systems to reduce porosity defects in high-pressure cells.
Apulia
Underutilized industrial zones in Bari and Taranto offer labor cost arbitrage for export-oriented supply chains. PNRR capital subsidies are directing equipment modernization toward southern facilities serving pan-European OEM networks. Secondary alloy recovery operations are scaling to mitigate Chinese primary magnesium dependence.
Sicily
Catania's emerging foundry cluster targets North African and Middle Eastern automotive export markets. EU Critical Raw Materials Act implementation could secure preferential smelter allocations for island-based recyclers. Logistics infrastructure gaps currently limit just-in-time delivery to northern Italian assembly plants.
Italy Automotive Parts Magnesium Die Casting Market Competitive Landscape
Integrated multi-process specialists and regional single-site operators split the Italian magnesium die casting market between capital-intensive platform supply and flexible niche production. Market structure tilts toward consolidation as Tier-1 procurement teams compress vendor lists for electrified platforms. Swiss-Italian engineering conglomerates and North American lightweighting specialists represent the dominant strategic archetypes. Competitive moves center on single-source agreement capture and in-house machining capability expansion.
Among transnational engineering groups, Georg Fischer AG exemplifies the integrated process specialist archetype through its Swiss-Italian operational footprint. Meridian Lightweight Technologies occupies a position representing North American lightweighting expertise anchored into European OEM supply chains. Gibbs Die Casting Group sits within the scale-driven tier, exemplifying capacity concentration for high-volume structural component programs.
| Leading Market Players |
|---|
| Gibbs Die Casting Group |
| Pace Industries |
| Shiloh Industries |
| Georg Fischer AG |
| Meridian Lightweight Technologies |
| Dynacast |
| Brabant Alucast |
| Chicago White Metal Casting |
| GF Automotive |
| Others |
Supply & Pricing Matrix
Brenner Base Corridor freight economics amplify cost differentials between Emilia-Romagna foundries and southern Italian competitors, compressing margin pools for AZ91D alloy shipments while PNRR subsidy eligibility reshapes procurement geography. This logistics-cost overlay concentrates pricing power among Bologna-Modena suppliers with Stellantis direct-feed contracts.
Pricing Analysis
EU REACH compliance dictates the pricing tier structure across Italian magnesium die casting, separating CE-marked premium grades for Ferrari EV architectures from standard AM60B engine components. Three-tier pricing structure across premium, standard, and economy levels reflects alloy purity certification, wall-thickness tolerance, and embedded carbon documentation. Cost compression in standard-grade transmission cases is intensifying because Chinese primary magnesium feedstock faces carbon border adjustment penalties. Aftermarket providers exhibit highest price sensitivity, while OEM direct contracts tolerate premium positioning for prototype-to-production continuity.
Supply Chain Analysis
Tariff exposure between China and the European Union dominates supply chain risk architecture for Italian magnesium die casters. Primary magnesium concentrates in Chinese smelters, with secondary recovery scaling in Germany and Norway as alternative feedstock anchors. Tooling steel and hot-chamber injection systems draw from German and Swiss engineering suppliers. Single-source vulnerability persists in AZ91D alloy formulations qualified for crash-critical battery enclosures. Distribution runs through Tier-1 integrated die casting-machining operations with single-source agreements, displacing fragmented multi-vendor arrangements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italy's automotive magnesium die casting market sits at a platform-economics inflection where Stellantis EV architecture standardization rewires supplier interoperability requirements. Tier-1 procurement consolidation around embedded carbon tracking creates winner-take-most dynamics for qualified foundries.
For Market Incumbents: Pre-empt southern Italian competitor scaling by securing PNRR equipment modernization subsidies before Apulia and Sicily foundries achieve qualification timelines. Anchor defensive positioning through backward integration into secondary magnesium recovery, mitigating Chinese feedstock concentration risk. Capture in-house CNC machining capability expansion to defend single-source agreement retention against Meridian Lightweight Technologies and Georg Fischer AG platform supply consolidation. For New Entrants and Emerging Players: Apulia-based export-oriented supply chains for North African EV assemblers represent the most penetrable entry point, exploiting labor cost arbitrage and underutilized industrial zone availability. Secondary alloy recovery operations serving pan-European OEM networks offer white-space positioning ahead of EU Critical Raw Materials Act preferential allocation mechanisms. Pursue qualification partnerships with Brescia-area robotic extraction system integrators to compress technology deployment timelines. For Investors and Strategic Acquirers: Carve-out targets emerge from Swiss-Italian engineering conglomerates divesting non-core magnesium casting divisions amid portfolio rationalization. Long-term viability hinges on securing CRMA-aligned feedstock security and Stellantis platform qualification continuity. Monitor EU carbon border adjustment implementation pace as the critical inflection signal for secondary alloy recovery economics.| Strategic Initiative | Industry Significance |
|---|---|
| Secondary Alloy Recovery Scale-Up | EU Green Deal carbon border adjustments reward domestic recyclers with embedded emissions advantages over Chinese primary imports. |
| High-Pressure Die Casting Modernization | Real-time thermal monitoring integration qualifies Bologna-area foundries for Stellantis thin-walled battery tray specifications. |
| In-House Machining Capability Expansion | Vertical control over CNC finishing secures single-source agreements displacing fragmented multi-vendor Tier-2 arrangements. |
| Southern Italy Capacity Expansion | PNRR capital subsidies direct equipment investment toward Apulia and Sicily for export-oriented OEM supply chain integration. |
| REACH Compliance Certification Investment | ECHA-mandated workplace exposure limit adherence qualifies foundries for Ferrari and Lamborghini safety-critical component programs. |
Research Methodology
A spread of perspectives from Tier-1 supplier procurement directors, OEM platform engineers, foundry operations managers, and aftermarket distribution heads converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through SEC filings of listed automotive suppliers, IHS Markit vehicle production databases, and EU customs trade records for magnesium alloy imports. Bottom-up capacity assessments across Emilia-Romagna, Piedmont, and Lombardy foundries triangulated against top-down OEM procurement spend estimates.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation dimensions spanning product type, end-user tier, manufacturing stage maturity, and technology equipment vintage. CAGRs derived from weighted average of historical capacity utilization trends and announced platform launch schedules. Forecast inputs incorporated PNRR subsidy disbursement timelines and EU CRMA implementation progression for domestic smelter allocation mechanisms.
Practitioners should monitor Chinese magnesium export quota adjustments, Stellantis EV platform launch delays, and ECHA REACH exposure limit enforcement intensity for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Performance Parts Market
Automotive Parts
Mexico Automotive Parts Zinc Die Casting Market
Automotive Parts
Industrial Brakes Market
Automotive Parts
Global Automotive Plastics Market
Automotive Parts
Passenger Car Wiper Blade Market
Automotive Parts
South Africa Commercial Vehicles Lubricants Market
Automotive Parts
North America Automotive Airfilters Market
Automotive Parts
Industrial Gearbox and Gear Motors Market
Automotive Parts
Diesel Oxidation Catalyst Market
Automotive Parts
Automotive Pneumatic Actuators Market
Automotive Parts
Qatar Passenger Vehicles Lubricants Market
Automotive Parts
Qatar Commercial Vehicles Lubricants Market
Automotive Parts
Global Inductive Loop Vehicle Detector Market
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
Automotive Air Compressor Market
Automotive Parts
Drum Brake Market