
 Automotive Millimeter Wave Compatible Emblem Market | 2026-2036
Automotive Millimeter Wave Compatible Emblem Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Millimeter Wave Compatible Emblem Market Intelligence
Software-defined feature enablement via over-the-air updates is hardening the requirement for millimeter-wave transparent materials in vehicle emblems from the point of manufacture. Continental AG leverages its deep systems integration expertise in ADAS to supply complete sensor-emblem modules. Robert Bosch GmbH competes with a broad portfolio of radar sensors and compatible components for global OEMs. TOYODA GOSEI Co., Ltd specializes in the material science and molding processes essential for creating non-interfering exterior parts.
An automotive millimeter wave compatible emblem is a vehicle insignia engineered from materials with low dielectric loss and signal attenuation properties. These emblems, often made from specific grades of polycarbonate or other polymers, ensure the unimpeded transmission and reception of radar signals for ADAS functions. Applications such as Adaptive Cruise Control and Collision Avoidance represent the largest share of the market. Demand is primarily driven by OEMs and Tier-1 Suppliers who integrate these components directly into new vehicle platforms.
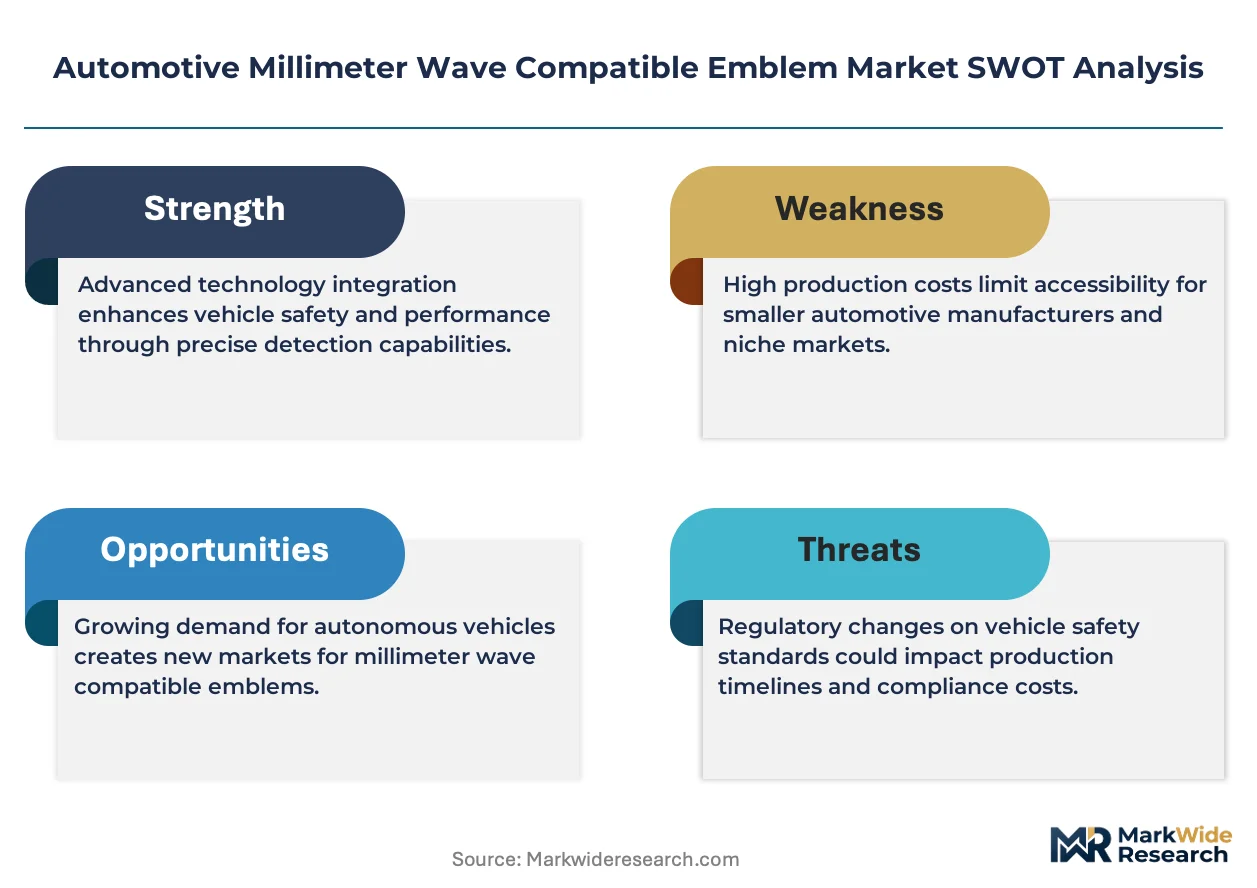
Vehicle safety mandates from regulators like the US NHTSA and compliance with UNECE WP.29 regulations on automated driving systems are critical demand drivers. Material performance must often align with standards such as those set by Japan's JIS for durability and signal transparency. Stakeholders must navigate the trade-off between advanced material properties required for higher frequency bands and the persistent cost pressures within automotive supply chains.
Market Dynamics
The fundamental market dynamic is the emblem's transformation from a passive branding element into an active, critical component of the vehicle's sensory system. This shift is driven by the architectural integration of 77 GHz radar for advanced driver-assistance systems, hardening requirements for material transparency and signal integrity.
Growth Catalysts
- Vehicle Safety Mandates:Regulations such as those from the US NHTSA and compliance with UNECE WP.29 for automated driving systems compel automotive OEMs to integrate ADAS, directly stimulating demand for compatible emblems.
- Advanced Radar Technology:The industry-wide migration to higher-frequency 77 GHz radar systems requires new material compositions in emblems to minimize signal loss and ensure the accuracy of functions like adaptive cruise control.
- OEM Platform Integration:Demand from automotive manufacturers to incorporate ADAS features as standard equipment on high-volume vehicle platforms serves as a primary catalyst for emblem and sensor module procurement.
Market Restraints
- Material Cost-Performance Trade-Off:The high cost of specialized polymers and composites with low dielectric properties creates a persistent tension against the intense cost-down pressures prevalent in the automotive supply chain.
- Signal Interference and Degradation:Aesthetic finishes, chrome plating, and certain paint pigments can significantly attenuate radar signals, constraining design freedom and requiring extensive validation testing to prevent performance degradation.
- Supply Chain Concentration:A significant portion of the specialized material science and high-precision molding expertise is concentrated in automotive hubs in Germany and Japan, creating potential bottlenecks and supply vulnerabilities.
Strategic Opportunities
- Integrated Sensor Modules:There is a significant opportunity for suppliers to offer pre-calibrated, integrated modules that combine the emblem, radar sensor, and heating elements, simplifying OEM assembly and improving system reliability.
- Expansion in Commercial Vehicles:The increasing adoption of ADAS in heavy-duty trucks and commercial fleets to improve safety and reduce operational costs presents an underpenetrated market for ruggedized, compatible emblems.
- Multi-Material Solutions:Developing hybrid emblems using a combination of polymers and specialized coatings offers a path to optimize radar transparency, aesthetic quality, and environmental durability, creating new value propositions.
Industry Challenges
- Complex Validation and Testing:Ensuring emblem performance across diverse weather conditions, temperatures, and cleaning-agent exposures requires complex and time-consuming validation cycles, delaying time-to-market for new vehicle models.
- Design and Styling Constraints:Reconciling the technical requirements of radar transparency with the aesthetic and branding demands of automotive designers poses a continuous challenge for material scientists and component engineers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Millimeter Wave Compatible Emblem Market |
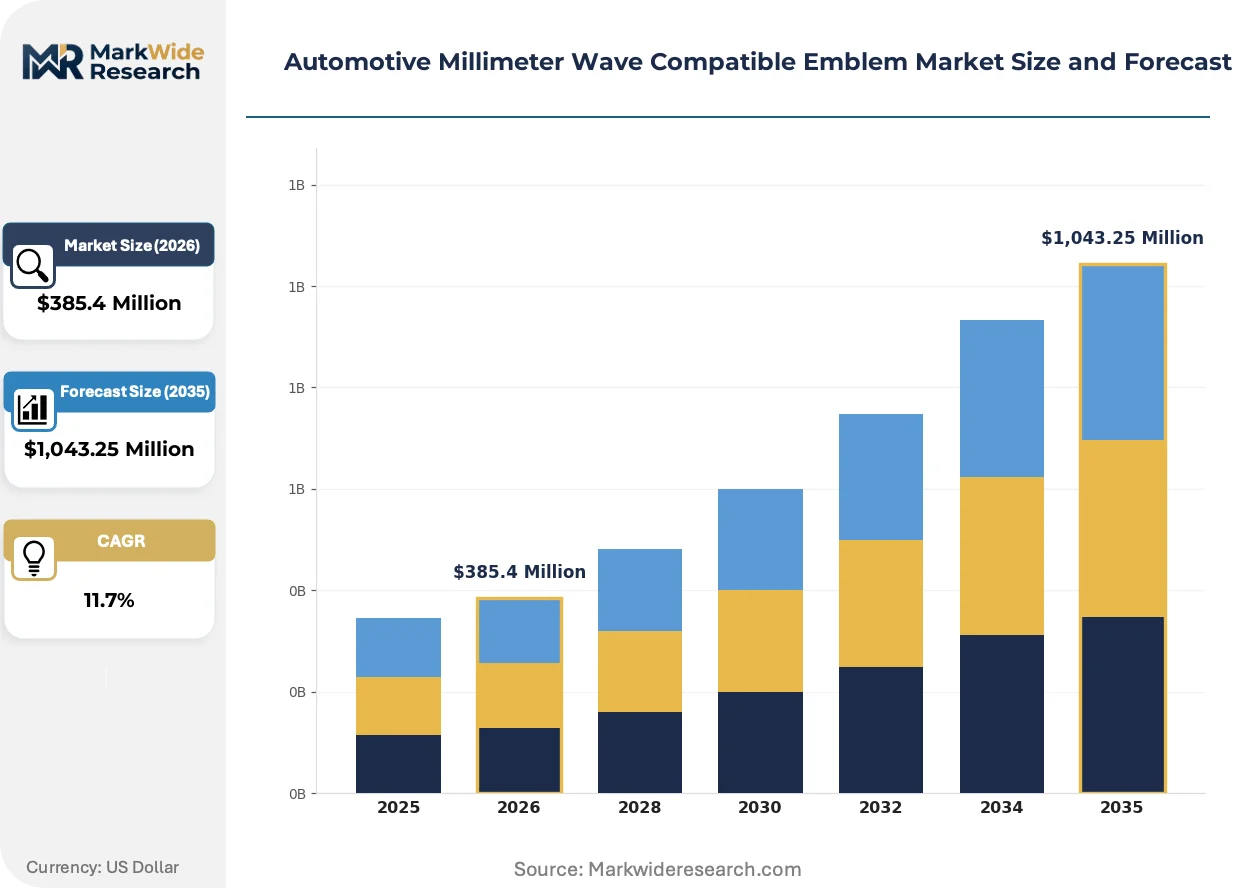
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,043.25 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Emblems, Passive Emblems, Hybrid Emblems, Smart Chips Technology: Frequency Modulation, Phase Modulation, Digital Beamforming, Analog Beamforming Application: Collision Avoidance, Adaptive Cruise Control, Parking Assistance, Blind Spot Detection, Lane Departure Warning End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers |
| Companies Covered | Toyota Motor Corporation, ROHDE & SCHWARZ GmbH & Co. KG, TOYODA GOSEI Co., Ltd, Continental AG, Robert Bosch GmbH, Shinko Nameplate Co., Ltd, Shimadzu Corporation, Denso Corporation, ZANINI AUTO GRUP, S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Millimeter Wave Compatible Emblem Market Strategic Shifts & Innovations
Material science advancements are enabling the functionalization of vehicle exteriors, turning previously decorative parts into integral elements of the perception stack. This evolution is driven by the convergence of sensor technology, regulatory pressures, and new OEM procurement models that prioritize system-level performance.
Advanced polymers and multi-material composites engineered for low signal attenuation are central to product evolution. Automotive OEMs are rapidly adopting these materials for next-generation ADAS platforms to ensure sensor fidelity. This innovation is electrifying the vehicle's surface, transforming static branding components into active enablers for automated driving functions.
Mandates for material performance, such as Japan's JIS standards for durability and signal transparency, are becoming globally influential. These standards force suppliers to invest in specific testing protocols and material qualifications to access key automotive markets. Consequently, global component manufacturers must align their quality control and R&D processes with these stringent Japanese requirements to supply major OEMs.
A procurement model shift is visible as OEMs move from sourcing discrete parts to acquiring integrated modules. This trend disrupts component specialists and favors Tier-1 suppliers capable of delivering a pre-validated sensor-emblem assembly. This preference for integrated systems is most pronounced within the German and Japanese automotive sectors, where deep systems engineering is a core competency.
Automotive Millimeter Wave Compatible Emblem Market Segmentation
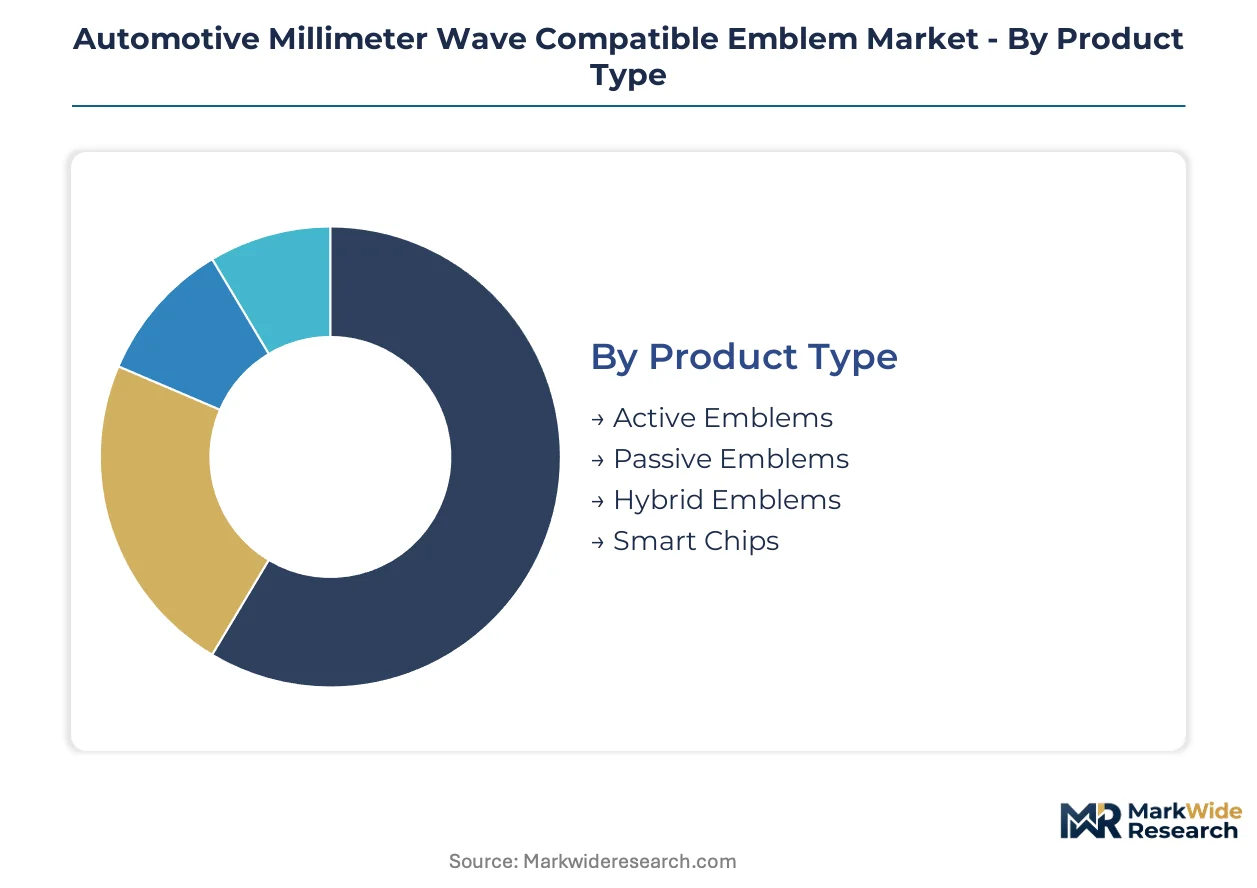
The Automotive Millimeter Wave Compatible Emblem Market is segmented to provide a granular understanding of the diverse product forms, underlying technologies, critical applications, and primary end-users driving its evolution. This segmentation highlights the various technical requirements and commercial pathways influencing market development.
Product Type:
The product type segmentation reflects the spectrum from highly customized, integrated solutions to more standardized, discrete components.
- Active Emblems:These emblems integrate radar sensors directly within their housing, providing a compact, pre-calibrated unit for vehicle integration. Demand for active emblems is concentrating among premium automotive brands seeking seamless aesthetic integration and high performance for advanced ADAS functions.
- Hybrid Emblems:Hybrid emblems combine radar-transparent materials with integrated heating elements or illumination features, balancing aesthetic design with functional requirements. OEMs prioritize hybrid emblems for their ability to maintain brand identity while ensuring sensor functionality in diverse environmental conditions.
- Passive Emblems:Passive emblems are engineered solely for radar transparency, allowing an independently mounted radar sensor to transmit and receive signals through the emblem material. These components offer a cost-effective solution for basic ADAS integration in high-volume vehicle platforms.
- Smart Chips:Smart chips represent embedded electronic components within the emblem structure, potentially enabling additional functionalities like data processing or communication. Their integration offers future potential for enhanced vehicle-to-everything (V2X) communication capabilities.
Most installed capacity flows through Passive Emblems. Expansion is steepest in Active Emblems.
Technology:
This technology segmentation illustrates the varying sophistication and adoption rates of radar signal processing techniques within the market.
- Digital Beamforming:Digital beamforming technology enables precise control over radar signal direction and shape by processing individual antenna element signals digitally, enhancing resolution and interference rejection. Its adoption is accelerating in high-performance ADAS systems for complex environmental perception.
- Frequency Modulation:Frequency modulation (FM) radar, often used in FMCW (Frequency Modulated Continuous Wave) systems, measures distance and velocity by analyzing frequency shifts in the reflected signal. This foundational technology underpins many current adaptive cruise control and collision avoidance applications.
- Phase Modulation:Phase modulation techniques involve altering the phase of the radar signal to encode information or improve target differentiation, offering advantages in specific radar sensing scenarios. The technique is finding niche applications in specialized sensor arrays requiring high angular accuracy.
- Analog Beamforming:Analog beamforming shapes the radar beam using phase shifters and attenuators at the radio frequency (RF) front-end, offering a less complex and often more cost-effective solution than digital methods. Many entry-level radar systems still utilize analog beamforming for basic ADAS functions.
The adoption of Frequency Modulation remains foundational. Digital Beamforming is gaining significant traction.
Application:
The application segment highlights the diverse ADAS functions that rely on millimeter wave compatible emblems, ranging from safety-critical systems to convenience features.
- Collision Avoidance:These systems utilize radar signals to detect potential frontal impacts, providing warnings or initiating automatic braking to mitigate or prevent accidents. Collision avoidance applications represent a significant volume driver due to stringent vehicle safety mandates from regulators like the US NHTSA.
- Adaptive Cruise Control:Adaptive cruise control (ACC) systems maintain a set speed and a safe following distance from the vehicle ahead by continuously monitoring traffic conditions via radar. OEMs are integrating ACC as standard equipment on a growing number of vehicle platforms, driving consistent demand.
- Parking Assistance:Parking assistance systems employ radar sensors to detect obstacles around the vehicle during parking maneuvers, often providing visual or audible alerts to the driver. These systems enhance driver convenience and reduce the likelihood of low-speed collisions.
- Blind Spot Detection:Blind spot detection (BSD) systems use radar to monitor areas alongside and behind the vehicle that are not visible in side mirrors, alerting the driver to vehicles in their blind spots. BSD is becoming a widely adopted safety feature across vehicle segments.
- Lane Departure Warning:While primarily camera-based, some advanced lane-keeping assist systems incorporate radar for enhanced accuracy, especially in adverse weather conditions, to detect unintended lane deviations. Radar integration in these systems adds robustness and reliability.
Collision avoidance systems drive significant volume. Parking assistance applications show consistent integration.
End User:
The end-user segmentation differentiates between the primary entities responsible for integrating these components into the automotive supply chain and delivering them to the final consumer.
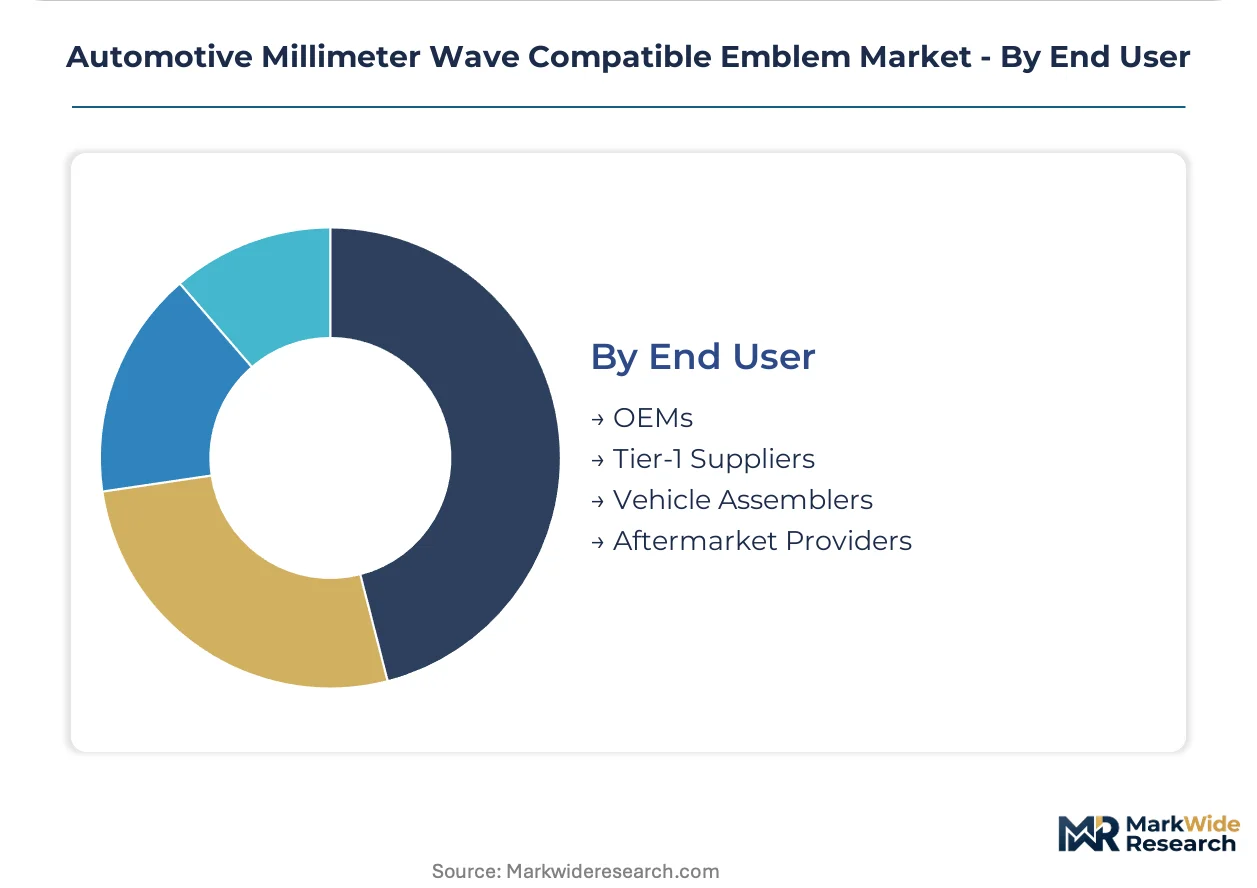
- OEMs:Original Equipment Manufacturers (OEMs) are the primary integrators of millimeter wave compatible emblems, incorporating them directly into new vehicle designs and platforms during the manufacturing process. OEMs dictate material specifications and performance requirements for these critical components.
- Tier-1 Suppliers:Tier-1 suppliers develop and provide complete sub-systems, such as radar sensor modules that include compatible emblems, directly to automotive OEMs. These suppliers leverage their engineering expertise to deliver pre-validated, integrated solutions.
- Vehicle Assemblers:Vehicle assemblers focus on the final assembly of vehicles, integrating components and sub-assemblies supplied by OEMs and Tier-1 suppliers. Their role involves the physical installation of these emblems and associated radar systems.
- Aftermarket Providers:Aftermarket providers supply replacement parts or upgrade kits for vehicles already in operation, including compatible emblems for repair or enhancement. This segment addresses maintenance needs and offers upgrade opportunities for older vehicle models.
OEMs dictate initial component specifications. Tier-1 suppliers increasingly manage integrated module delivery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan exhibit distinct yet influential roles in the millimeter wave compatible emblem market. While German automotive manufacturers prioritize advanced ADAS integration, Japanese suppliers excel in material science innovation. This dual focus drives different aspects of market development and technology adoption.
Germany
Demand for high-performance ADAS features in premium vehicles propels emblem market expansion in Germany. The KBA mandates for vehicle safety and automated driving systems compel manufacturers to integrate sophisticated radar technology. Automotive clusters in Bavaria, particularly around Munich and Stuttgart, focus on R&D for next-generation sensor-emblem modules.
Japan
Japanese OEMs require advanced material science for radar-transparent emblems, driven by stringent vehicle safety standards. JIS standards for durability and signal transparency are critical for component qualification in this market. The Chubu region, including Nagoya, serves as a hub for material development and precision molding for automotive exterior parts.
United States
The United States market experiences significant demand from OEM integration of ADAS features across diverse vehicle segments. NHTSA regulations for collision avoidance systems directly stimulate the need for compliant millimeter wave emblems. Manufacturing centers in Michigan, especially Detroit, concentrate on integrating these components into new vehicle platforms.
China
China's automotive market demands compatible emblems due to rapid ADAS adoption in both domestic and international brands. MIIT policies supporting intelligent connected vehicles accelerate the integration of radar-based safety features. Major automotive production bases in the Yangtze River Delta drive volume manufacturing and local supply chain development.
South Korea
South Korea sees sustained demand for compatible emblems, primarily from its major automotive manufacturers aiming for global ADAS leadership. The country's national vehicle safety standards emphasize advanced driver assistance functions. Industrial complexes around Seoul and Ulsan are centers for advanced component manufacturing and system integration.
Automotive Millimeter Wave Compatible Emblem Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the automotive millimeter wave compatible emblem market. The market exhibits a tiered structure, with established Tier-1 suppliers dominating integrated module delivery for complex ADAS applications. Component specialists focus on material science and precision manufacturing for passive emblem solutions, catering to cost-sensitive vehicle platforms. Strategic partnerships between material providers and system integrators, alongside capacity expansion in key automotive hubs, represent dominant competitive moves.
Within the integrated sensor-emblem module segment, Continental AG and Robert Bosch GmbH exemplify comprehensive system integration capabilities for advanced driver-assistance systems. TOYODA GOSEI Co., Ltd, a Japan-based automotive supplier, anchors material science and precision molding expertise for radar-transparent exterior parts. These entities occupy positions across the value chain, from specialized component manufacturing to delivering full system solutions, often leveraging their established relationships with global OEMs. Their offerings represent distinct approaches to meeting the evolving technical requirements of the market.
| Leading Market Players |
|---|
| Toyota Motor Corporation |
| ROHDE & SCHWARZ GmbH & Co. KG |
| TOYODA GOSEI Co., Ltd |
| Continental AG |
| Robert Bosch GmbH |
| Shinko Nameplate Co., Ltd |
| Shimadzu Corporation |
| Denso Corporation |
| ZANINI AUTO GRUP, S.A. |
| Others |
Cost & Logistics Intelligence
Specialized material science and precision molding expertise concentrated in German and Japanese automotive hubs contributes to distinct pricing tiers across millimeter wave compatible emblems. Labor-cost differentials between these regions and emerging production centers influence overall module costs.
Pricing Analysis
Capacity additions in China and Mexico are reshaping price floors for passive millimeter wave compatible emblems. The dominant pricing model is contract-based long-term offtake between suppliers and OEMs. Price differentiation stems from customization levels and adherence to stringent certification like Japan's JIS standards. OEM cost-down mandates drive persistent downward pricing pressure, making OEMs highly price-sensitive compared to aftermarket providers.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the downstream logistics for millimeter wave compatible emblems. Geographic supply concentration for advanced material science and precision molding resides in Germany, Japan, and increasingly China. The supply chain draws from specialized polymers and integrated radar sensors as key inputs. Single-source vulnerability for specific grades of low dielectric loss polymers presents a structural risk, with distribution running primarily direct to OEMs and Tier-1 suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive millimeter wave compatible emblem market functions as a stable compounder, driven by persistent vehicle safety mandates. This underlying regulatory pressure ensures consistent, predictable demand for ADAS-enabling components.
For Market Incumbents: Cement systems integration capabilities by offering complete sensor-emblem modules to automotive OEMs. Invest heavily in advanced material R&D to maintain a performance edge against emerging lower-cost component specialists. Expand capacity in key automotive hubs like Germany and Japan while securing critical material supply chains. Pursue further certification investments, aligning with stringent standards such as Japan's JIS, to reinforce quality leadership.
For New Entrants and Emerging Players: Tier-2 material suppliers should target the commercial vehicle segment with ruggedized, cost-effective passive emblems. Focus on developing multi-material solutions that balance radar transparency with aesthetic quality for high-volume platforms. Penetrate under-served regional markets such as emerging Asian economies by offering localized production and support. Emphasize competitive pricing and rapid prototyping as key go-to-market angles.
For Investors and Strategic Acquirers: Tier-1 automotive suppliers are the most active acquirers in this space, seeking to consolidate capabilities. The market exhibits strong long-term viability over the next five to ten years due to persistent ADAS growth. Target niche specialists in advanced material science or integrated module providers that offer proprietary technology. A key signal to watch is the continued OEM procurement model shift towards standardized, pre-validated sensor-emblem systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Deepen Systems Integration | Continental AG enhances its ADAS offering by delivering pre-calibrated sensor-emblem modules to OEMs. |
| Invest in Advanced Material R&D | TOYODA GOSEI Co., Ltd develops new polymers with low dielectric loss for next-generation radar systems. |
| Expand Commercial Vehicle Offerings | Suppliers can capture new demand from heavy-duty truck manufacturers integrating ADAS for fleet safety. |
| Forge Multi-Material Partnerships | Collaboration between material providers and aesthetic designers optimizes emblem performance and vehicle branding. |
| Localize Production in Emerging Markets | Companies reduce logistics costs and meet regional demand from Chinese automotive manufacturers. |
Research Approach
Bottom-up ADAS application modeling reconciled against top-down component supplier tracking forms the analytical core of this study. Primary interviews with OEM platform engineers, Tier-1 procurement leads, and material scientists provided critical insights. Secondary validation drew from vehicle production databases, ADAS regulatory filings from NHTSA and UNECE, and material science journals. This approach ensures robust triangulation of market data.
An input-output matrix framework integrates historical performance with projected ADAS adoption rates across the analysis window. The model segments market evolution by product type, technology, application, and end user. Compound Annual Growth Rates (CAGRs) derive from projected 77 GHz radar penetration rates and ADAS feature standardization. This framework ensures a granular view of market dynamics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory changes and rapid material science breakthroughs. Forecasts reflect assumptions concerning ADAS adoption rates and OEM platform shifts. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Stainless Steel Tubes Market
Automotive Components
Automotive Solar Control Glass Market
Automotive Components
Automotive Tailgate Market
Automotive Components
Europe Automotive Plastics Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
France Automotive Market
Automotive Components
Automotive Fender Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Automotive Retarders Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Automotive Headliners Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Asia-Pacific Automotive Parts and Components Market