
 Automotive Headliners Market | 2026-2036
Automotive Headliners Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Headliners Market Intelligence
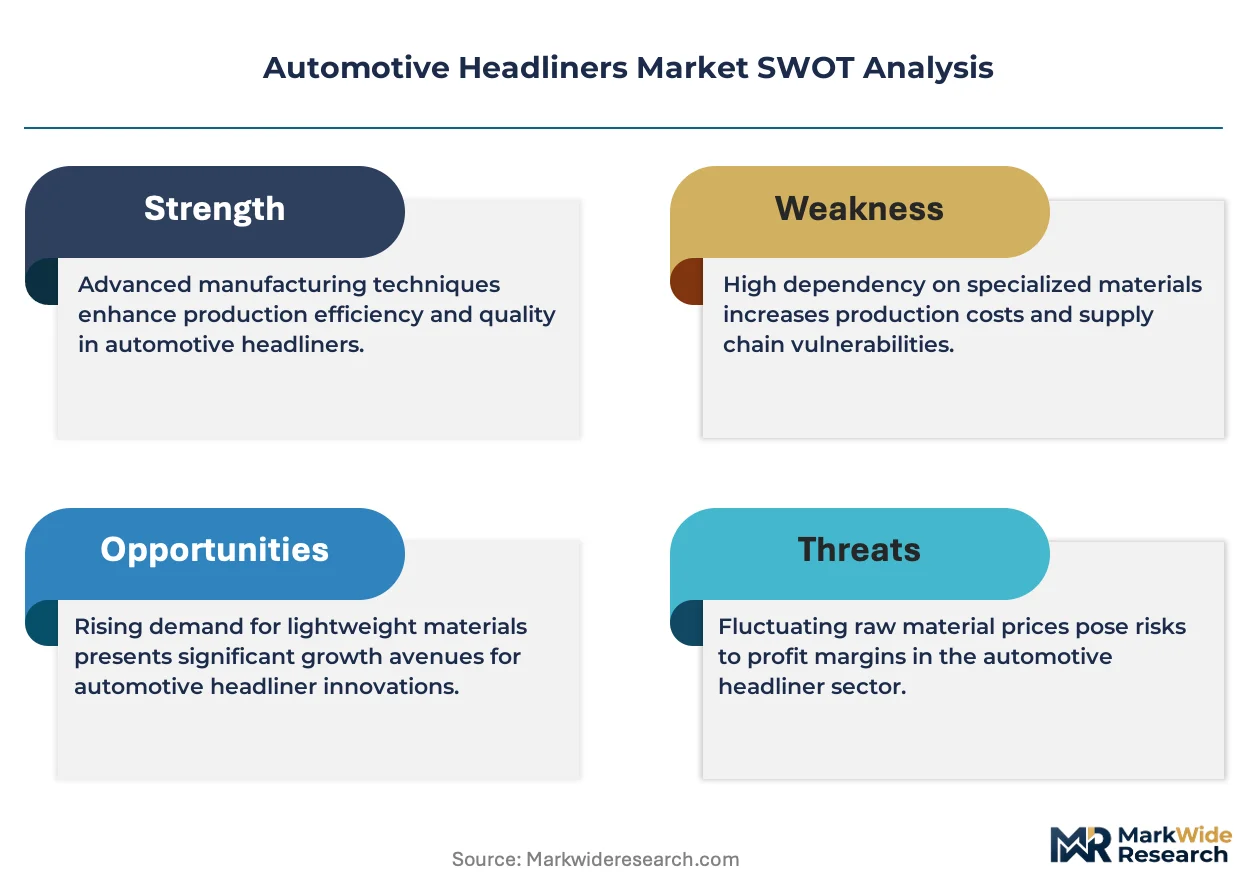
The gap between premium and commodity headliner tiers is shifting from surface aesthetics to integrated functional systems. Grupo Antolin leverages its vertical integration across textile backing and foam substrates to control cost structures in high-volume programs. Toyota Boshoku anchors its position through captive supply relationships with Toyota Motor Corporation's global assembly network. Lear Corporation differentiates via acoustic engineering capabilities that embed active noise cancellation modules directly into headliner assemblies.
Automotive headliners are interior roof modules typically comprising a substrate layer of polyurethane or fiberglass-reinforced composite, a foam core for thermal and acoustic insulation, and a decorative facing fabric bonded through hot-melt or water-based adhesive lamination, engineered to meet head impact criteria and cabin air quality standards. Thermoplastic headliners are gaining share in electric vehicle platforms where weight reduction directly extends driving range, while fabric headliners retain dominance in mainstream passenger car segments where cost-per-gram targets remain stringent. Injection molding technology leads in cycle-time efficiency for high-volume OEM programs, whereas vacuum forming occupies niche applications requiring deep-draw geometries in commercial vehicle cabs.
The US NHTSA enforces Federal Motor Vehicle Safety Standard 201 for head impact protection, compelling substrate thickness and energy-absorption specifications that influence material selection across all supply tiers. Europe's REACH regulation and ECHA restrictions on formaldehyde emissions in vehicle interiors are reshaping adhesive chemistry and textile finishing processes for suppliers accessing EU member state markets. Stakeholders must monitor evolving end-of-life vehicle directives from the EU and state-level extended producer responsibility frameworks in California, as recyclability mandates begin to penetrate interior component specifications.
Market Dynamics
Electric vehicle platform architecture is compressing headliner weight targets below 1.2 kg per unit, forcing substrate material transitions from fiberglass-reinforced composites toward thermoplastic olefin foams. This shift is redistributing supplier capability requirements across acoustic engineering, thermal management integration, and automated lamination throughput.
Growth Catalysts
- EU REACH VOC limits:Water-based adhesive systems are displacing solvent-based chemistries in lamination lines serving Stuttgart and Munich assembly plants.
- Active noise cancellation modules:Premium tier headliners now embed speaker arrays and microphone arrays as standard cabin comfort features.
- Germany's premium manufacturing corridor:Concentrated OEM demand around Baden-Württemberg and Bavaria sustains dedicated supplier tooling investments.
Market Restraints
- Polyurethane foam input volatility:Petrochemical feedstock price swings compress margin predictability for substrate suppliers operating on annual OEM price-down schedules.
- Alcantara supply concentration:Single-source dependency for premium suede-look facings creates vulnerability in luxury program launches.
- Head impact energy absorption floors:NHTSA FMVSS 201 thickness mandates prevent full lightweighting in US-market headliner designs.
Strategic Opportunities
- Recyclable mono-material headliners:EU end-of-life vehicle directives are mandating disassembly-friendly designs that eliminate mixed-fiber lamination.
- India passenger vehicle localization:Import substitution policies under PLI schemes attract thermoplastic headliner capacity for compact SUV platforms.
- Thermoplastic-EV convergence:Weight-per-kilogram targets in battery-electric architectures favor injection-molded substrates over fabric-wrapped alternatives.
Industry Challenges
- Acoustic simulation talent scarcity:OEMs now require headliner suppliers to deliver NVH predictive models prior to physical prototyping.
- Multi-material bonding certification:Water-based adhesives must pass simultaneous validation for peel strength, fogging, and formaldehyde emission under ECHA restrictions.
- Legacy press reconfiguration:Vacuum forming assets require capital-intensive retrofit for thermoplastic olefin processing temperatures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Headliners Market |
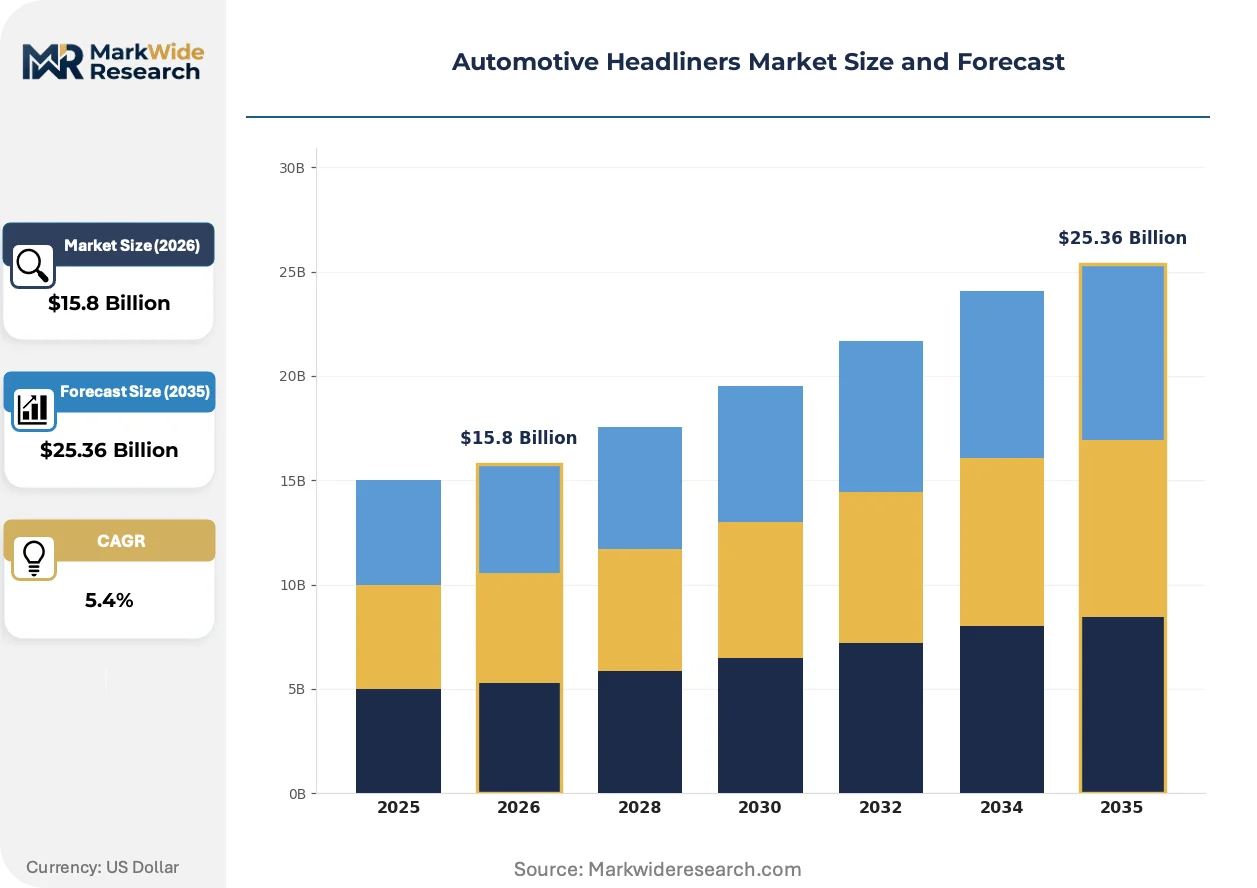
| Market Size in 2026 | $15.8 Billion |
| Market Size in 2035 | $25.36 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fabric Headliners, Composite Headliners, Fiber-Reinforced Headliners, Foam Headliners, Thermoplastic Headliners Technology: Injection Molding, Vacuum Forming, Lamination, Ultrasonic Welding, Adhesive Bonding Application: Passenger Cars, Commercial Vehicles, Electric Vehicles, Off-Road Vehicles, Autonomous Vehicles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Refurbishers, Auto Dealerships |
| Companies Covered | Grupo Antolin, Toyota Boshoku Corporation, Motus Integrated Technologies, Lear Corporation, IAC Group, Magna International, Freudenberg Performance Materials, Sage Automotive Interiors, Howa Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Headliners Market Strategic Shifts & Innovations
Headliner manufacturing is converging toward integrated functional modules that combine thermal-acoustic substrates with embedded electronics, compressing traditional tier boundaries between interior trim and electrical system suppliers.
Automated robotic lamination cells are automating adhesive application and fabric positioning with micron-level repeatability. Tier 1 suppliers in Germany and Japan are deploying these systems for high-mix, low-volume premium programs. This automation is automating quality variance reduction while enabling single-operator supervision of previously labor-intensive bonding stations.
REACH Annex XVII restrictions on formaldehyde-releasing substances are compelling textile finishers to migrate from traditional resin binders to bio-based crosslinking agents. Lamination houses serving EU-bound production must now maintain dual adhesive inventories. Passenger car segments with 7-year model cycles face compressed revalidation timelines compared to commercial vehicle platforms.
Fleet procurement departments are consolidating interior component sourcing under platform-level contracts rather than discrete commodity purchases. Direct OEM-headliner supplier relationships are displacing multi-tier distribution in electric vehicle programs. This concentration is most visible in California's zero-emission vehicle mandates, where single-source module awards span seat, headliner, and pillar trim categories.
Automotive Headliners Market Segmentation
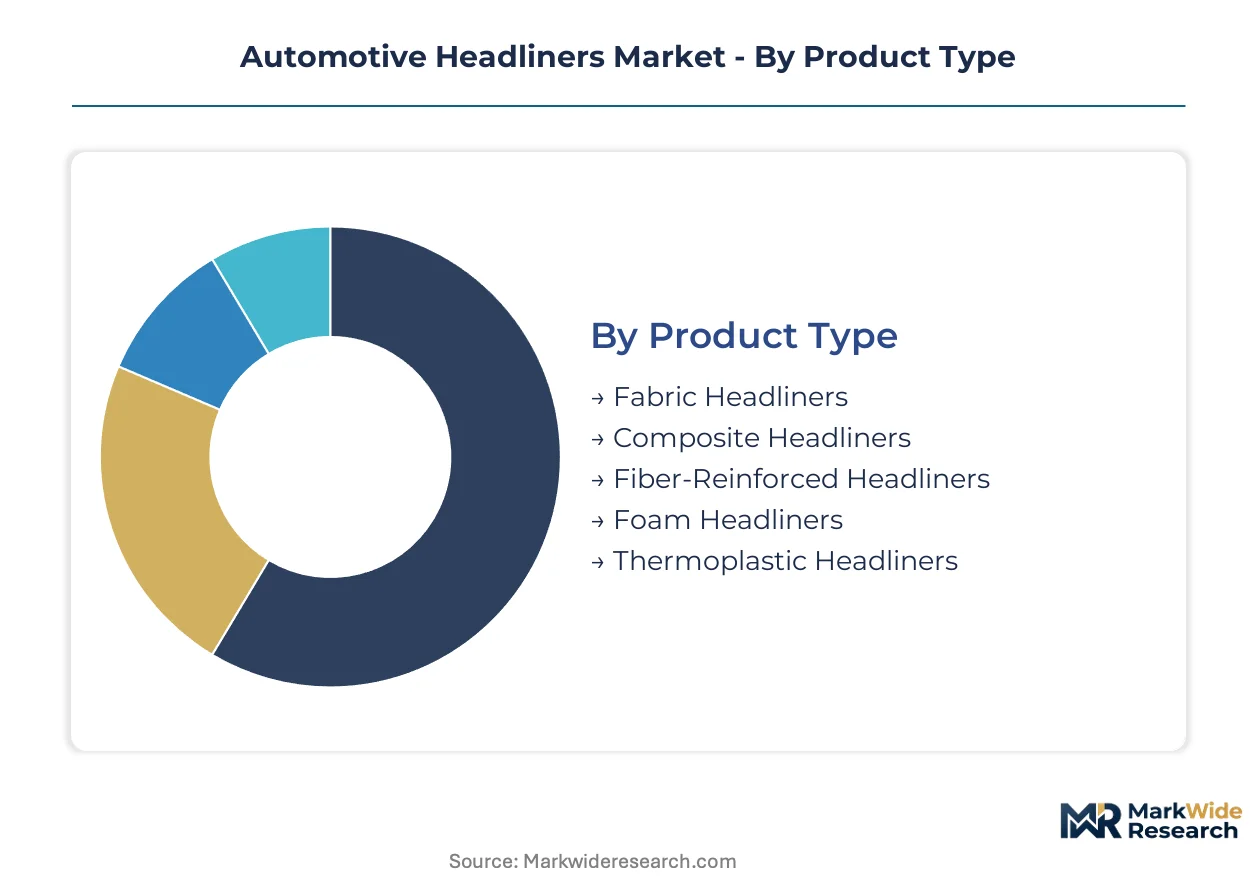
Headliner segmentation tracks diverging material science requirements between weight-driven electric platforms and cost-driven mainstream production. Buyers select technologies based on cycle-time targets, acoustic specifications, and regulatory compliance burdens in their primary assembly markets.
Product Type:
Cost tier separates premium interior programs from high-volume commodity supply.
- Thermoplastic Headliners:Injection-molded polypropylene substrates deliver sub-1.2 kg unit weights critical for battery-electric range extension. Demand concentrates in Germany's Stuttgart manufacturing corridor where OEMs specify mono-material designs for end-of-life recyclability under EU directives.
- Fabric Headliners:Woven textile facings over polyurethane foam cores dominate mainstream passenger car segments. Toyota Boshoku and Lear Corporation anchor volume production through captive supply relationships with Japanese and US assembly networks.
- Composite Headliners:Fiberglass-reinforced substrates meet NHTSA FMVSS 201 head impact criteria in US-market SUVs and trucks.
- Fiber-Reinforced Headliners:Natural fiber composites serve European OEMs targeting bio-based content thresholds in corporate sustainability reporting.
- Foam Headliners:Expanded polypropylene cores provide thermal-acoustic insulation in commercial vehicle cabs with deep-draw geometries.
Fabric headliners lead volumes today; thermoplastic variants are gaining share fastest.
Technology:
Volume throughput and geometric complexity dictate process selection across OEM program tiers.
- Injection Molding:High-pressure thermoplastic processing achieves sub-60-second cycle times for million-unit annual programs. Grupo Antolin deploys robotic lamination cells downstream of molding stations to automate fabric bonding with micron-level repeatability.
- Lamination:Water-based adhesive systems now dominate EU-bound production as REACH Annex XVII restrictions displace solvent chemistries. Stuttgart and Munich assembly plants require dual adhesive inventories to serve export markets with divergent VOC standards.
- Vacuum Forming:Deep-draw capability serves commercial vehicle headliners with integrated grab handles and overhead console mounting points.
- Ultrasonic Welding:Solvent-free bonding meets ECHA formaldehyde emission limits for textile-to-foam attachment in premium programs.
- Adhesive Bonding:Hot-melt systems retain cost advantage in high-volume Asian assembly plants outside EU regulatory scope.
Injection molding commands the largest installed base; lamination is expanding most quickly on regulatory pull.
Application:
Platform architecture and powertrain type reshape material specifications and supplier capability requirements.
- Electric Vehicles:Battery-electric platforms compress headliner weight targets below 1.2 kg per unit, forcing substrate transitions from fiberglass composites toward thermoplastic olefin foams. California's zero-emission vehicle mandates concentrate module sourcing under consolidated platform contracts.
- Passenger Cars:Mainstream sedan and SUV segments retain fabric-wrapped headliners where cost-per-gram targets remain stringent. India's PLI localization schemes attract thermoplastic capacity for compact SUV export programs.
- Commercial Vehicles:Heavy-duty cab designs specify vacuum-formed substrates with integrated structural ribs for overhead storage loads.
- Autonomous Vehicles:Sensor mounting provisions and cable routing channels embed directly into headliner substrates during molding.
- Off-Road Vehicles:Moisture-resistant closed-cell foams address agricultural and construction equipment exposure requirements.
Passenger cars anchor current volumes; electric vehicle applications show the steepest expansion trajectory.
End User:
Procurement consolidation and technical integration depth separate direct OEM relationships from tiered distribution channels.
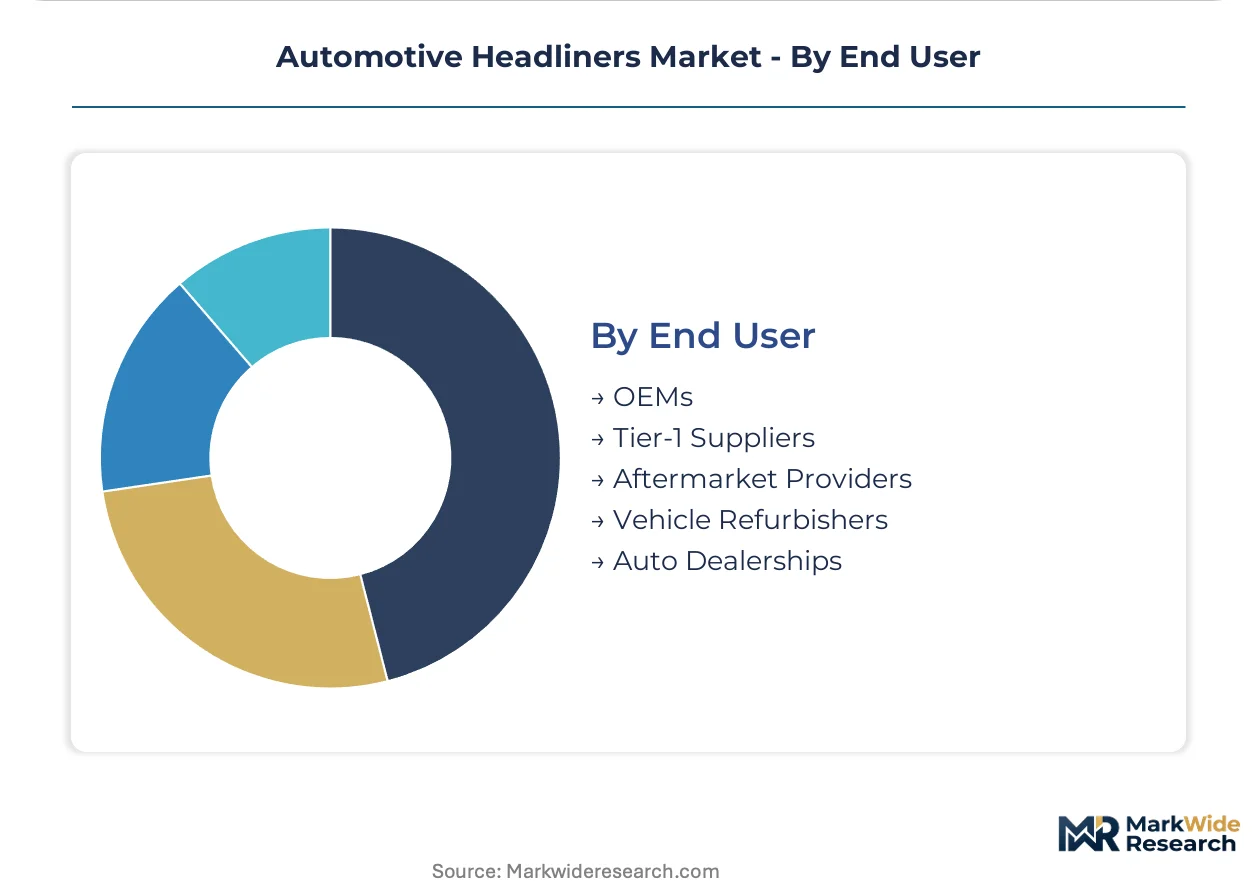
- OEMs:Direct module sourcing now spans seat, headliner, and pillar trim categories under single-source awards in electric vehicle programs. Fleet procurement departments in California and Germany have displaced multi-tier distribution for platform-level contracts.
- Tier-1 Suppliers:Grupo Antolin, Lear Corporation, and Toyota Boshoku anchor the supply base through acoustic engineering capabilities and captive resin compounding operations.
- Aftermarket Providers:Replacement headliners for vehicle refurbishment target 7-10 year model cycle segments with simplified adhesive bonding kits.
- Vehicle Refurbishers:Commercial fleet operators source foam-backed fabric assemblies for cab interior renewal programs.
- Auto Dealerships:Premium vehicle retailers offer Alcantara headliner upgrades as differentiation tools in luxury segments.
Tier-1 suppliers handle the majority of production volume; OEM direct sourcing is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Acoustic engineering talent clusters in Stuttgart and Munich anchor European supply capabilities, while injection molding specialists concentrate in Japan's Aichi prefecture. Water-based adhesive chemists and thermoplastic process engineers represent the scarcest human capital pools across major manufacturing regions.
United States
NHTSA FMVSS 201 head impact standards drive substrate thickness specifications for SUVs and trucks manufactured in Michigan and Ohio assembly corridors. EPA oversight of volatile organic compound emissions shapes lamination chemistry choices for suppliers serving Detroit-based OEMs. The Southeast manufacturing belt spanning Tennessee, Alabama, and South Carolina attracts thermoplastic headliner capacity for electric vehicle platforms.
Germany
REACH Annex XVII formaldehyde restrictions compel textile finishers serving Baden-Württemberg plants to migrate from resin binders toward bio-based crosslinking agents. Stuttgart's premium vehicle manufacturing corridor sustains dedicated supplier tooling investments for Alcantara-faced headliner programs. Munich-based OEM procurement departments now award consolidated platform contracts spanning seat, headliner, and pillar trim categories.
China
MIIT new energy vehicle mandates compress headliner weight targets below 1.2 kg for battery-electric platforms produced in Shanghai and Guangzhou. GB standards for cabin air quality accelerate water-based adhesive adoption among lamination houses serving Yangtze River Delta assembly plants. Injection molding capacity concentrates in Jiangsu province for compact SUV export programs targeting Southeast Asian markets.
Japan
METI carbon neutrality roadmaps favor thermoplastic olefin substrates over fiberglass composites in Nagoya-area production networks. JIS standards for interior material flammability influence foam core specifications across Toyota City supplier parks. Kanto region acoustic engineering capabilities support embedded active noise cancellation module integration for premium sedan programs.
India
PLI scheme localization incentives attract thermoplastic headliner manufacturing for compact SUV platforms assembled in Tamil Nadu and Maharashtra. BIS certification requirements for automotive interior components extend validation timelines for European suppliers entering the market. Haryana's Gurgaon-Manesar automotive corridor hosts tier-1 lamination capacity serving Maruti Suzuki and Hyundai export programs.
Automotive Headliners Market Key Industry Players
Top-tier vendors anchor premium acoustic module supply, while mid-scale fabricators compete on cycle-time efficiency for high-volume OEM programs. The supply base organizes around three strategic archetypes: vertically integrated interior module specialists, captive suppliers bound to single OEM networks, and independent acoustic engineering houses. Consolidation pressures intensify as platform-level procurement contracts displace discrete component sourcing. Geographic expansion and backward integration into resin compounding represent the dominant competitive moves reshaping tier relationships.
Among Japanese captive suppliers, Toyota Boshoku Corporation exemplifies the OEM-tied archetype through its embedded position within Toyota Motor Corporation's global assembly network. Grupo Antolin, a Spanish limited company, represents the vertically integrated model with upstream control across textile backing and foam substrate operations. Lear Corporation, a US-based corporation, anchors the independent engineering tier through its acoustic system integration capabilities. These three entities collectively illustrate how competitive positioning stratifies across supply relationship types rather than product differentiation alone.
| Leading Market Players |
|---|
| Grupo Antolin |
| Toyota Boshoku Corporation |
| Motus Integrated Technologies |
| Lear Corporation |
| IAC Group |
| Magna International |
| Freudenberg Performance Materials |
| Sage Automotive Interiors |
| Howa Co., Ltd. |
| Others |
Cost & Logistics Intelligence
OEM platform-level procurement consolidation under California zero-emission mandates is compressing supplier margins and forcing tier-1 headliner manufacturers to absorb annual price-down schedules while maintaining REACH-compliant adhesive inventories for EU-bound production.
Pricing Analysis
Bundled module awards spanning seat, headliner, and pillar trim categories now dominate electric vehicle procurement, displacing discrete component pricing. Three-tier pricing structure across premium Alcantara-faced, standard fabric-wrapped, and economy thermoplastic levels reflects acoustic engineering depth and certification burden. Cost compression in commodity fabric headliners is intensifying because polyurethane foam feedstock volatility outpaces OEM price-down negotiation cycles. Fleet procurement departments exhibit highest price sensitivity, while luxury OEMs in Stuttgart and Munich prioritize differentiation over unit cost.
Supply Chain Analysis
Alcantara supply rests on single-source Italian producers, creating vulnerability for premium program launches. Polyurethane foam feedstock draws from German petrochemical complexes and US Gulf Coast crackers, while thermoplastic olefin resin concentrates in South Korean and Japanese polymer plants. Single-source dependency for suede-look facings represents the dominant structural risk. Distribution runs through captive supply relationships for Japanese OEMs and direct OEM contracts for European premium manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: thermoplastic headliner capacity in India's PLI schemes captures cost advantages against REACH-compliant European production while serving export demand.
For Market Incumbents: Deepen backward integration into resin compounding to offset polyurethane foam margin volatility. Secure dedicated Alcantara allocation through long-term supply agreements before luxury program launches accelerate. Prioritize acoustic engineering talent retention as OEMs mandate NVH predictive models prior to physical prototyping. For New Entrants and Emerging Players: Tier-2 lamination houses in Haryana's Gurgaon-Manesar corridor offer the most penetrable entry point for compact SUV export programs. Target thermoplastic substrate supply for battery-electric platforms where weight-per-kilogram specifications favor injection-molded alternatives. Pursue joint development agreements with Indian OEMs under PLI localization requirements. For Investors and Strategic Acquirers: Asymmetric upside sits with independent acoustic engineering houses possessing active noise cancellation module integration capabilities. Long-term viability hinges on platform-level contract capture in electric vehicle architectures. Watch for EU end-of-life vehicle directive enforcement tightening as the signal for recyclable mono-material design premiumization.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive supply of thermoplastic olefin substrates insulates margin from petrochemical volatility. |
| Water-Based Adhesive Line Conversion | REACH Annex XVII compliance secures access to Stuttgart and Munich assembly plant awards. |
| Acoustic Engineering Talent Acquisition | NVH predictive modeling capability meets OEM requirements prior to prototype commitment. |
| Robotic Lamination Cell Deployment | Micron-level repeatability enables single-operator supervision of premium program bonding stations. |
| Mono-Material Headliner Development | EU recyclability mandates position suppliers for end-of-life vehicle directive compliance premiums. |
Research Approach
Coverage spans Germany, the United States, Japan, China, and India, with primary inputs from each market. The approach combines structured interviews with Tier 1 supplier procurement officers, OEM platform engineers, acoustic R&D directors, and aftermarket distributors with secondary validation from vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs/trade records. Bottom-up segment sizing and top-down market triangulation cross-verify value estimates.
Granularity-level modeling tracks thermoplastic, fabric, composite, fiber-reinforced, and foam headliner product types across injection molding, lamination, vacuum forming, ultrasonic welding, and adhesive bonding technologies. Vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions inform volume projections. CAGRs derive from regression analysis against battery-electric vehicle penetration curves and REACH regulatory phase-in schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to petrochemical feedstock volatility, Alcantara supply allocation constraints, and NHTSA FMVSS 201 standard revisions. Forecasts reflect documented assumptions about OEM platform consolidation timing and EU end-of-life vehicle directive enforcement trajectories. A small set of named triggers—polyurethane price spikes, REACH Annex XVII expansion, and single-source suede facing disruptions—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Water Valve Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automotive Exhaust Headers Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Automotive Resonator Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Automotive Glass Market
Automotive Components
Automobile AC Condensers Market
Automotive Components
Global Automotive Coupling Market
Automotive Components
Asia-Pacific Automotive Composites Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Actuators Market
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
Auto Fender Market
Automotive Components
Automotive Heater Core Market