
 France Automotive Market | 2026-2036
France Automotive Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive Market Intelligence
Advanced high-strength steel replacing conventional mild steel in vehicle body structures is repositioning cost-performance trade-offs for French automakers. Stellantis leverages its extensive brand lineup, including Peugeot and Citroën, to optimize platform development and component sourcing. Renault Group differentiates through its early and dedicated investment in the electric vehicle segment. Component manufacturer Valeo sustains its market position by supplying critical technologies like ADAS and thermal management systems to these OEMs.
The France automotive market comprises the production, distribution, and sale of passenger and commercial vehicles within the nation's borders. Vehicles are technically defined by their powertrain, with modern designs integrating complex electronics to meet safety and connectivity standards. The Electric Vehicles segment is expanding rapidly, challenging the long-standing dominance of Internal Combustion Engine models. Among end users, sales to Fleet Operators and Leasing Companies are growing as businesses prioritize total cost of ownership and emissions reduction goals.
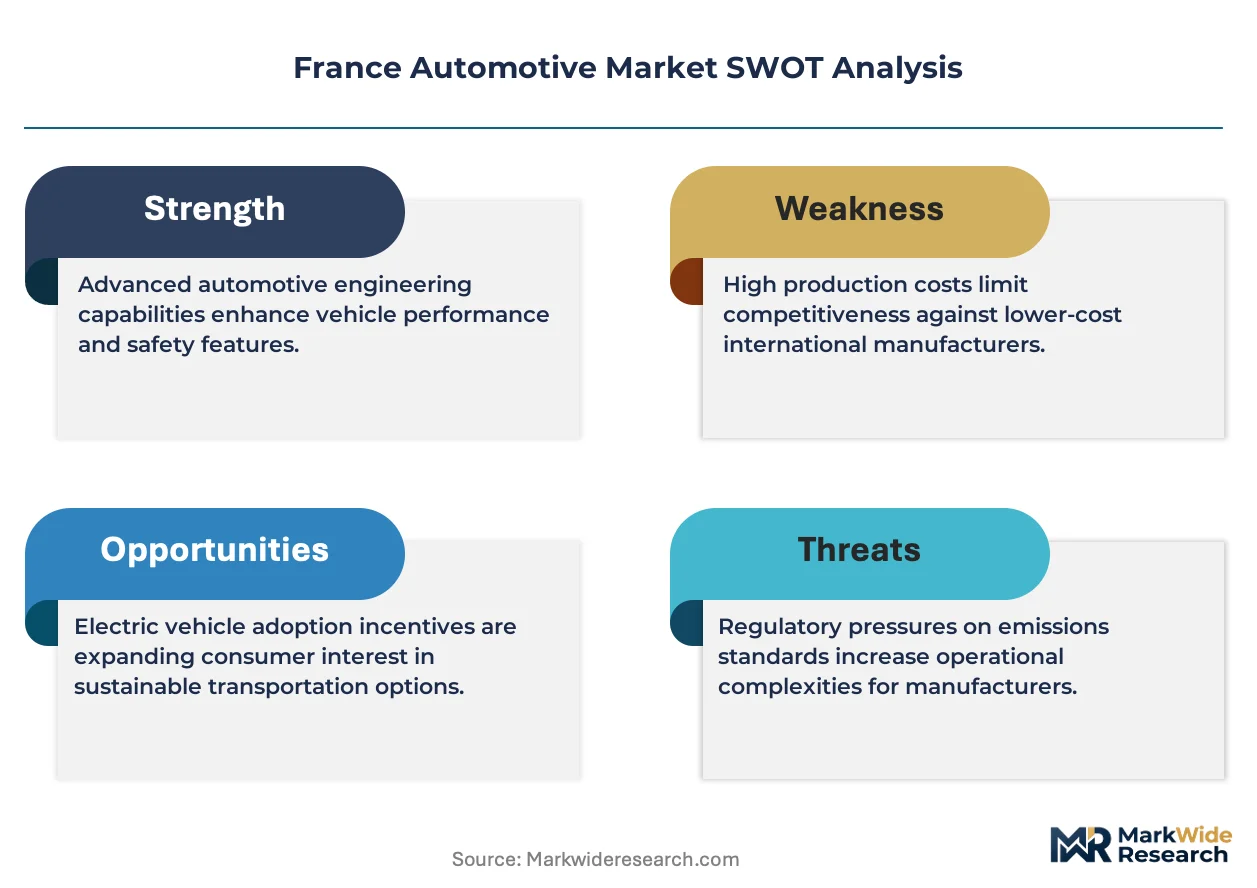
Regulatory frameworks like the EU Green Deal set stringent limits on vehicle emissions, heavily influencing design and engineering cycles. France's domestic bonus-malus écologique policy directly shapes consumer purchasing by taxing higher-emission vehicles and providing subsidies for cleaner alternatives. Success for original equipment manufacturers will depend on their ability to scale electric vehicle production profitably while managing the complex transition from legacy internal combustion platforms.
Market Dynamics
The powertrain transition, driven by the EU Green Deal and France's domestic bonus-malus écologique policy, is the central force shaping the French automotive market. This regulatory pressure accelerates the shift from internal combustion engines to electric vehicle platforms.
Growth Catalysts
- Consumer Incentives:France's bonus-malus écologique policy directly stimulates demand for low-emission vehicles by subsidizing electric models and penalizing higher-emission ones, influencing purchasing decisions at the consumer level.
- Fleet Electrification:Logistics and corporate fleet operators, particularly within the Île-de-France region, are rapidly adopting electric vehicles to meet emissions targets and lower total operational costs.
- Infrastructure Investment:The coordinated expansion of public and semi-public electric vehicle charging stations across the country reduces range anxiety and enables wider EV adoption beyond urban centers.
Market Restraints
- High Capital Cost:The elevated upfront purchase price of electric vehicles compared to their internal combustion engine counterparts remains a significant barrier for many private buyers, despite long-term savings.
- Battery Supply Chain:Heavy reliance on imported battery cells and raw materials from the Asia-Pacific region exposes French automakers to significant geopolitical risk and price volatility.
- Charging Infrastructure Gaps:The inconsistent availability of fast-charging infrastructure in rural and less-populated areas of France limits the practical appeal of electric vehicles for certain consumers.
Strategic Opportunities
- Battery Circular Economy:Developing domestic capabilities for battery recycling and second-life applications offers a path to reduce reliance on imported materials and create new value streams from end-of-life EV batteries.
- Mobility Services:The expansion of integrated Mobility-as-a-Service platforms in major cities presents an opportunity to capture value beyond vehicle sales through subscriptions and shared usage models.
- Electric LCVs:A growing market for specialized light commercial vehicles for last-mile delivery and municipal services provides a focused segment for targeted electric vehicle development.
Industry Challenges
- Workforce Transition:A significant skills gap exists in reskilling the labor force from mechanical engineering for ICEs to the software, electronics, and battery expertise required for electric vehicles.
- Legacy Asset Management:OEMs face the financial and operational challenge of managing the decline of ICE-related manufacturing assets while simultaneously funding the high capital expenditure for new EV plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive Market |
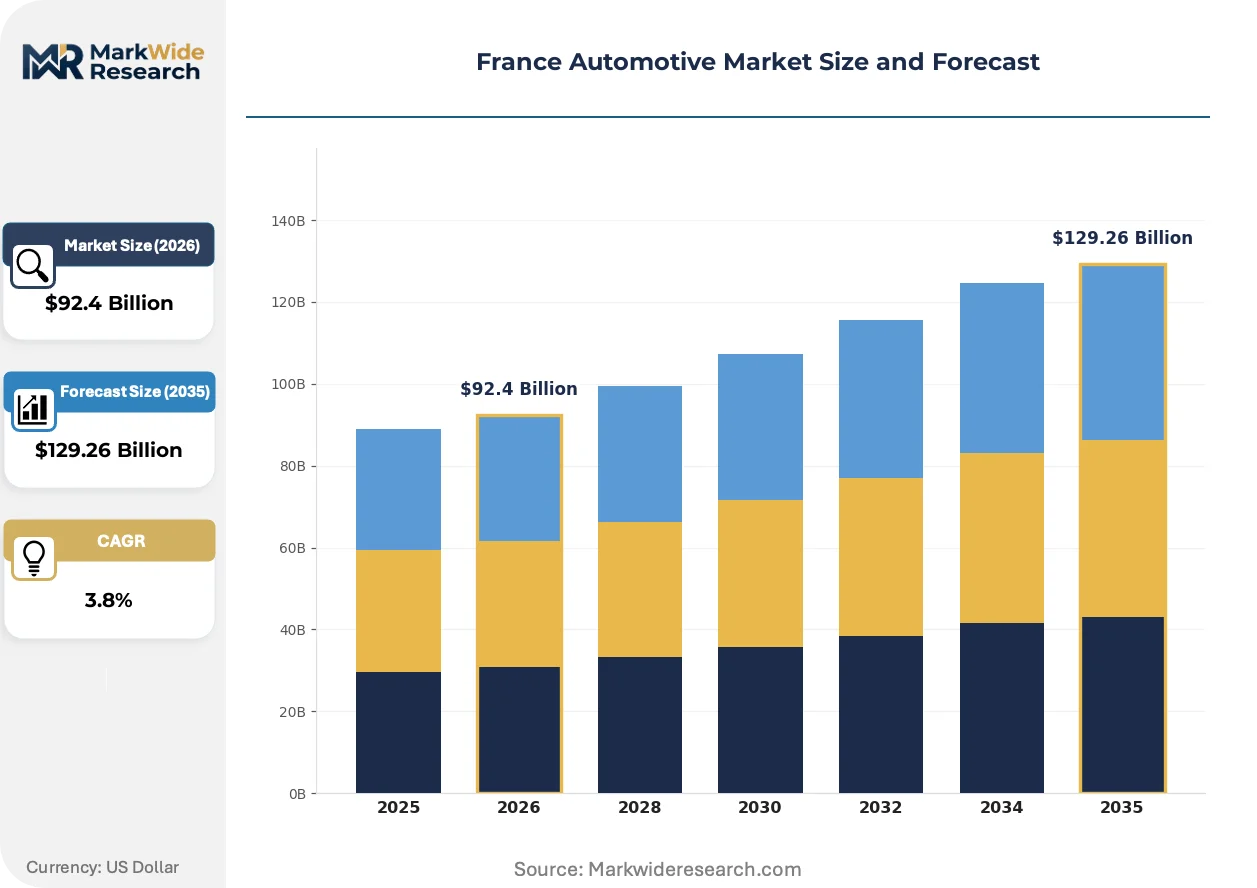
| Market Size in 2026 | $92.4 Billion |
| Market Size in 2035 | $129.26 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Light Commercial Vehicles, Heavy Trucks, Electric Vehicles, Hybrids Technology: Internal Combustion Engine, Electric Powertrain, Hybrid Drivetrain, Hydrogen Fuel Cell, Autonomous Driving Application: Private Transport, Ride Sharing, Logistics Transport, Public Transit, Emergency Services End User: Individual Consumers, Fleet Operators, Leasing Companies, Government Agencies, Transportation Companies |
| Companies Covered | Stellantis, Renault Group, Peugeot, Citroën, DS Automobiles, Alpine, Michelin, Valeo, French Electric Vehicle, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive Market Strategic Shifts & Innovations
The convergence of digitalization and electrification is fundamentally reconfiguring vehicle architecture within the French automotive sector. This dual shift alters not just the product itself but also the underlying value chains and competitive dynamics.
Advanced Driver-Assistance Systems (ADAS) utilize a sensor suite including cameras and radar to automate safety-critical functions and improve driver awareness. These systems see high adoption rates among premium vehicle buyers and commercial fleet operators seeking to reduce accidents. This technology is converging with vehicle-to-everything (V2X) connectivity, forming the technical foundation for future autonomous driving applications.
Implementation of the EU's Corporate Sustainability Reporting Directive (CSRD) imposes stringent new rules for environmental and social disclosures. This regulation compels French automakers to meticulously track and report on their entire carbon footprint, including emissions from their supply chain and vehicle usage. Component suppliers are most impacted, now required to provide verifiable data on the carbon intensity of their products.
A pronounced shift from traditional vehicle ownership to more flexible usership models is altering consumer behavior. This trend disrupts the legacy dealership channel, as OEM-led subscription services and comprehensive leasing packages gain traction. The change is most visible among younger, urban demographics and corporate clients within the Île-de-France and Auvergne-Rhône-Alpes regions.
France Automotive Market Segmentation
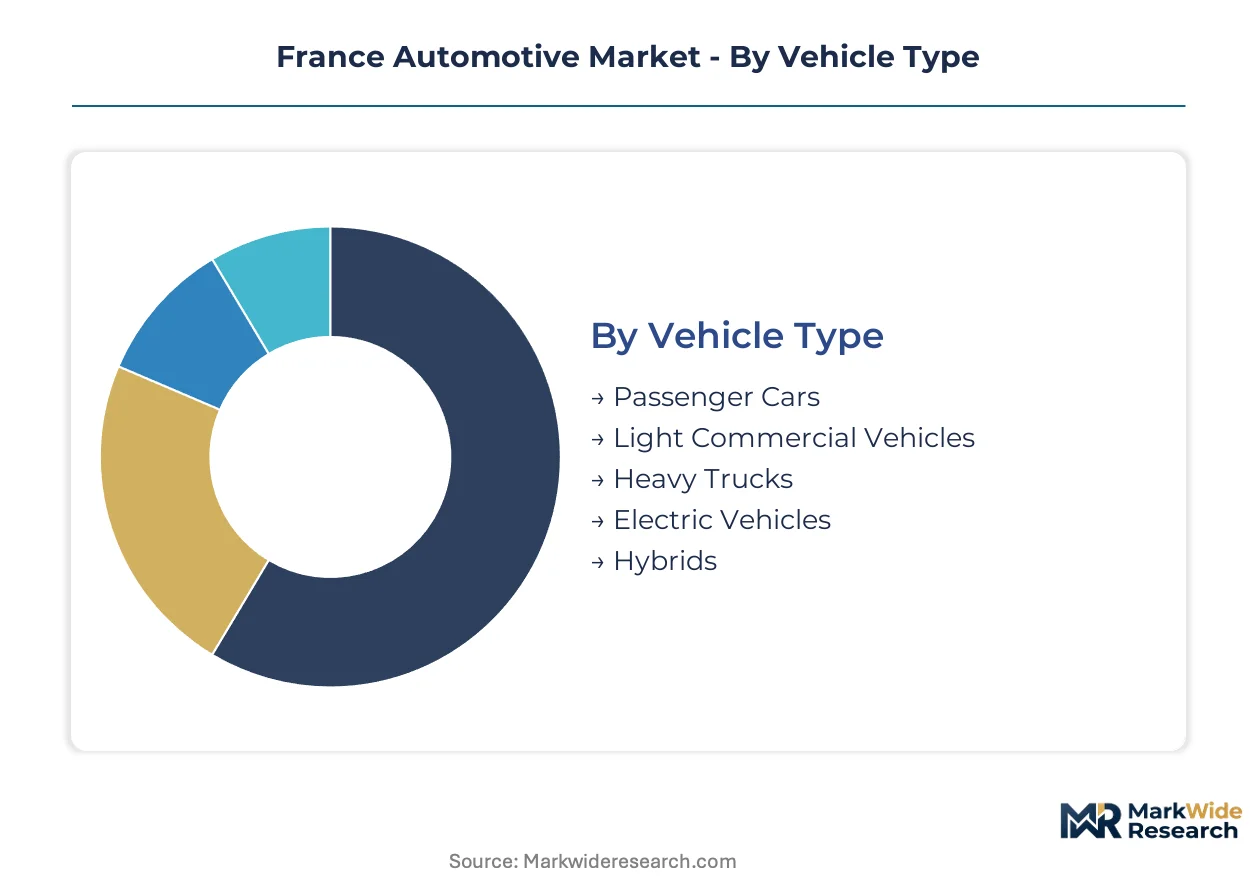
Segmentation provides a granular understanding of the France automotive market, highlighting distinct demand patterns and technological shifts. This detailed breakdown helps stakeholders identify key growth areas and adapt strategies to evolving consumer preferences and regulatory mandates, particularly amidst the ongoing powertrain transition.
Vehicle Type:
Different vehicle types in France face distinct regulatory hurdles, particularly concerning emissions standards set by the EU Green Deal and local bonus-malus écologique policy.
- Electric Vehicles:Electric Vehicles rely on battery-electric powertrains, producing zero tailpipe emissions. Demand concentrates among fleet operators in the Île-de-France region, driven by stringent corporate sustainability targets and operational cost savings.
- Light Commercial Vehicles:Light Commercial Vehicles (LCVs) are designed for goods transport and last-mile delivery, crucial for urban logistics. Fleet electrification initiatives accelerate LCV adoption, especially as businesses prioritize emissions reduction and total cost of ownership.
- Passenger Cars:Passenger Cars represent the largest volume segment, primarily serving individual consumer mobility needs across France.
- Heavy Trucks:Heavy Trucks facilitate long-haul and regional freight transport, facing increasing pressure to adopt lower-emission technologies.
- Hybrids:Hybrid vehicles combine internal combustion engines with electric motors, offering a transitional solution for reduced fuel consumption.
Leading the category by volume: Passenger Cars. Growing fastest: Electric Vehicles.
Technology:
Technology choices directly influence vehicle performance and suitability across various applications within the French automotive market.
- Electric Powertrain:Electric Powertrains integrate electric motors, battery packs, and power electronics to deliver propulsion with zero local emissions. New vehicle sales demonstrate a clear shift towards these systems, particularly in urban environments under regulatory impetus.
- Autonomous Driving:Autonomous Driving systems incorporate advanced sensors, artificial intelligence, and V2X connectivity to enable partial or full self-operation. Adoption is observed in premium vehicles and commercial fleets, enhancing safety and operational efficiency.
- Internal Combustion Engine:Internal Combustion Engines (ICEs) convert fuel into mechanical power, forming the historical backbone of the French automotive fleet.
- Hybrid Drivetrain:Hybrid Drivetrains combine ICEs with electric motors, providing improved fuel economy and reduced emissions compared to conventional ICEs.
- Hydrogen Fuel Cell:Hydrogen Fuel Cell technology generates electricity through a chemical reaction, offering zero-emission mobility with rapid refueling potential.
Innovation in Electric Powertrain technology drives significant investment, while Internal Combustion Engine platforms maintain a foundational presence.
Application:
The diverse applications of automotive products in France cater to varied user needs, reflecting distinct volume and value contributions.
- Logistics Transport:Logistics Transport encompasses vehicles used for goods delivery and supply chain operations, vital for e-commerce growth. Fleet electrification initiatives are rapidly transforming this segment, driven by urban emissions regulations and cost optimization.
- Private Transport:Private Transport involves vehicles for individual ownership and personal mobility, representing the largest segment by vehicle count. Consumer purchasing decisions are heavily influenced by the bonus-malus écologique policy and evolving lifestyle preferences.
- Ride Sharing:Ride Sharing platforms utilize vehicles for on-demand transport services, gaining traction in major French urban centers.
- Public Transit:Public Transit includes buses and trams, serving collective urban and regional mobility requirements across France.
- Emergency Services:Emergency Services deploy specialized vehicles for critical public safety and healthcare operations nationwide.
The Private Transport segment commands the largest share of operational vehicles, whereas Logistics Transport exhibits strong growth potential.
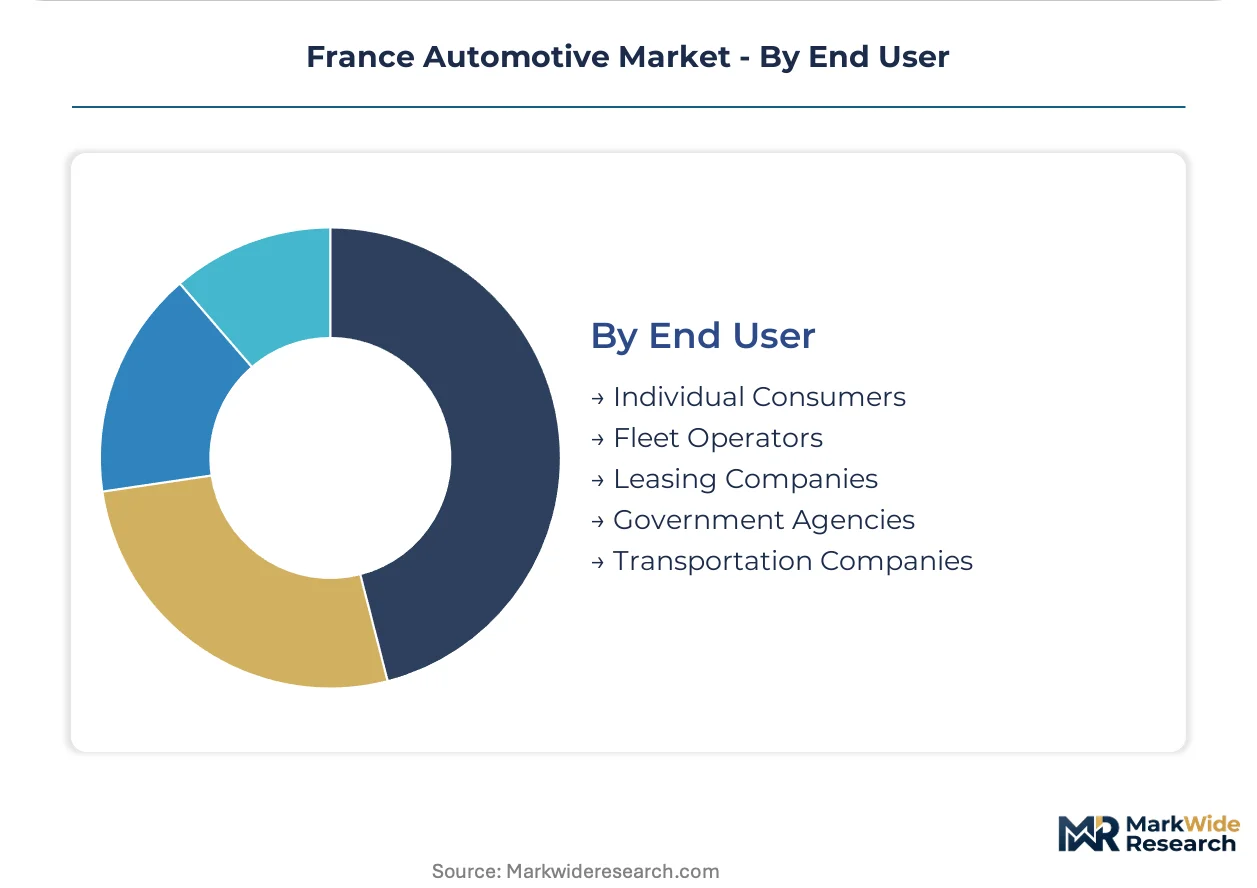
End User:
Different end-user segments exhibit varying purchasing power and total cost of ownership considerations, influencing manufacturer strategies and margin profiles.
- Fleet Operators:Fleet Operators include corporate, logistics, and rental companies managing vehicle pools for business purposes. Their purchasing decisions prioritize total cost of ownership and emissions compliance, particularly in regions like Île-de-France.
- Individual Consumers:Individual Consumers are private buyers acquiring vehicles for personal use, heavily influenced by government incentives and vehicle availability. The bonus-malus écologique policy directly shapes their purchasing behavior towards cleaner alternatives.
- Leasing Companies:Leasing Companies provide vehicle access through subscription or long-term rental models, catering to both corporate and individual clients.
- Government Agencies:Government Agencies procure vehicles for public service operations, often adhering to specific procurement guidelines and environmental mandates.
- Transportation Companies:Transportation Companies operate vehicles for passenger or freight services, focusing on operational efficiency and regulatory compliance.
Strategic engagement with Individual Consumers remains critical for volume, while Fleet Operators represent a high-growth customer base.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's bonus-malus écologique policy significantly influences automotive demand across its sub-regions, driving consumer preferences towards cleaner vehicle alternatives. This regulatory framework, coupled with localized economic conditions, shapes investment priorities for manufacturers and infrastructure developers. Regional dynamics reflect varied adoption rates for electric vehicles and mobility services.
Île-de-France
Demand for electric vehicles and associated charging infrastructure concentrates heavily within the Île-de-France region. Fleet operators in Paris and its surrounding areas prioritize EV adoption to meet stringent corporate sustainability targets. The region benefits from substantial public and private investment in charging networks, reducing range anxiety for both commercial and private users.
Auvergne-Rhône-Alpes
The Auvergne-Rhône-Alpes region exhibits a growing appetite for flexible usership models and shared mobility services. Consumer purchasing decisions here are increasingly influenced by total cost of ownership and environmental considerations. Cities like Lyon and Grenoble are becoming hubs for integrated mobility solutions, attracting investment in new transport technologies.
Hauts-de-France
Hauts-de-France remains a critical automotive manufacturing base, with a strong focus on industrial vehicle production and electric light commercial vehicles. Regulatory incentives from the EU Green Deal encourage the transition from traditional internal combustion engine production. Stellantis and Renault Group maintain significant production facilities in areas like Douai and Valenciennes, adapting their lines for EV components.
Nouvelle-Aquitaine
Nouvelle-Aquitaine is emerging as a center for battery technology and advanced materials research within the French automotive ecosystem. Strategic government initiatives support the development of gigafactories and associated R&D capabilities. Bordeaux and Limoges are fostering innovation in sustainable mobility solutions and high-performance battery components.
France Automotive Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the France automotive market, reflecting a tiered competitive structure. Original Equipment Manufacturers (OEMs) dominate vehicle production, while specialized component suppliers provide critical technologies. Strategic archetypes include diversified automotive groups, electric vehicle pioneers, and advanced technology providers. Companies frequently engage in platform optimization and strategic partnerships to navigate the powertrain transition.
At the OEM level, Stellantis and Renault Group exemplify the shift towards electric vehicle platforms, leveraging their extensive brand portfolios and established distribution networks. Stellantis optimizes platform development and component sourcing across brands like Peugeot and Citroën. Renault Group differentiates through early and dedicated investment in the electric vehicle segment. Valeo, as a component manufacturer, occupies a position as a critical technology supplier, anchoring the market for advanced driver-assistance systems and thermal management solutions. These entities represent different facets of the market, from vehicle assembly to specialized system integration, each adapting to the evolving regulatory and technological landscape.
| Leading Market Players |
|---|
| Stellantis |
| Renault Group |
| Peugeot |
| Citroën |
| DS Automobiles |
| Alpine |
| Michelin |
| Valeo |
| French Electric Vehicle |
| Others |
Cost & Logistics Intelligence
Lithium carbonate spot prices, alongside nickel and cobalt, cascade through the automotive supply chain, directly influencing battery cell costs and subsequently the final pricing tiers of electric vehicles in France. This commodity volatility forces French automakers to balance long-term supply agreements with short-term market adjustments for profitability.
Pricing Analysis
Pricing for French automotive products leverages lead-time differentiation, with premium vehicles often commanding higher prices for immediate availability or custom configurations. Pricing stratifies across premium, standard, and economy tiers, reflecting vehicle features like advanced ADAS capabilities and brand prestige. Pricing softness stems from intense competition among OEMs and the bonus-malus écologique policy, which pressures higher-emission vehicle prices. Individual Consumers exhibit the highest price sensitivity, particularly for entry-level models, while Fleet Operators prioritize total cost of ownership over upfront purchase price.
Supply Chain Analysis
Single-source vulnerability sits with the Asia-Pacific region for critical battery raw materials and finished cells, exposing French automakers to geopolitical risks. The supply chain for electric vehicles draws heavily from China for lithium and rare earth elements, alongside semiconductors from Taiwan. Commodity price volatility for inputs like steel and aluminum also presents a structural risk to manufacturing costs. Distribution runs through established OEM-dealer networks for new vehicle sales, increasingly supplemented by direct-to-consumer models for electric vehicles and subscription services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France automotive market is engaged in a vertical-integration race, with key players pursuing upstream control over battery cell production capabilities as a primary lever.
For Market Incumbents:Acquire battery technology startups or specialized software firms to internalize critical electric vehicle intellectual property. Invest heavily in retooling existing manufacturing facilities in Hauts-de-France for electric powertrain component production, mitigating the threat from emerging EV pure-plays. Focus R&D efforts on advanced battery chemistries that reduce reliance on volatile imported raw materials. This strategy helps manage the complex transition from legacy internal combustion platforms under stringent EU Green Deal regulations.
For New Entrants and Emerging Players:Software-defined vehicle platforms present a technology-first wedge for new entrants to differentiate in the French market, particularly within specialized segments. Target the burgeoning electric Light Commercial Vehicle (LCV) segment for last-mile delivery in urban centers like Île-de-France, which remains a relatively penetrable application. Implement flexible ownership models, such as subscription services and short-term leasing, as a go-to-market angle to attract younger, urban demographics and small businesses.
For Investors and Strategic Acquirers:Distressed-cycle entries favor acquirers with long-term capital in the French automotive component manufacturing sector. Invest in companies specializing in critical electric vehicle technologies, such as advanced thermal management systems or power electronics, which offer sustained relevance across the EV transition. The long-term viability of the market depends on successful electrification, spanning a multi-decade horizon. A critical signal to watch is the consistent expansion of public fast-charging infrastructure density across France, indicating broader consumer readiness for EV adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures long-term access to essential EV components, stabilizing production costs for French OEMs. |
| Software-Defined Vehicle Investment | Enhances vehicle functionality and over-the-air update capabilities, improving customer experience for users in France. |
| Charging Infrastructure Partnership | Expands public and semi-public charging networks, reducing range anxiety for French EV drivers. |
| EV Platform Standardization | Optimizes production efficiency and reduces development costs across diverse electric vehicle models. |
| Advanced ADAS Development | Improves vehicle safety and paves the way for future autonomous driving applications in France. |
Research Approach
EU Commission reports, national automotive association statistics, and financial filings of major French OEMs like Stellantis and Renault Group formed the secondary backbone for this analysis. This research combined extensive primary interviews with OEM platform engineers, Tier 1 procurement specialists, logistics fleet managers, and regulatory experts. Bottom-up analysis of vehicle registration data was triangulated with top-down market sizing for comprehensive validation.
The analytical framework applied a bottom-up approach, modeling demand drivers across vehicle type, technology, application, and end user segments, alongside regional adoption patterns in France. Forecasted compound annual growth rates were derived through a weighted average of segment-specific projections over the projection horizon. Key forecast inputs included electric vehicle adoption curves and planned charging infrastructure rollout plans within France.
Several conditions sit outside the modeled scope, including unforeseen geopolitical shifts affecting raw material supply and drastic changes in French or EU regulatory incentives. Forecasts reflect assumptions regarding technological progression and market dynamics. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Australia Automotive Composites Market
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
Automotive Retarders Market
Automotive Components
Global Cylinder Deactivation System Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Europe Torque Vectoring Market
Automotive Components
Automotive HVAC Ducts Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Automotive Mufflers Market
Automotive Components
Automotive Actuators Market
Automotive Components
China Automotive Composites Market
Automotive Components
Automotive Metal Market
Automotive Components
Automotive Carbon Fiber Market