
 Europe Automotive Glass Market | 2026-2036
Europe Automotive Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Glass Market Intelligence
The capital-intensity divergence between integrated float-glass producers and downstream fabricators is unwinding competitive stability across the value chain. Saint-Gobain Sekurit leverages captive soda-lime silica supply to sustain margin control across French and German OEM programs. AGC Inc. anchors its position through deep R&D spending on chemically strengthened thin-glass architectures for electric vehicle rooflines.
Europe automotive glass encompasses laminated and tempered transparent assemblies engineered from soda-lime silica formulations with interlayer PVB or ionoplast bonding, manufactured through gravity-fed float processes followed by thermal toughening or autoclave lamination to meet ECE R43 optical and fragmentation standards. Windscreens command the dominant value pool given mandatory laminated construction and integrated sensor apertures for ADAS camera clusters. Heated glass technology is capturing accelerated OEM specification as battery thermal management protocols extend to cabin glazing surfaces.
EMA material safety directives, EU Green Deal carbon-border adjustments, and ECE R43 homologation standards collectively mandate lighter, recyclable glazing substrates while restricting heavy-metal coatings. REACH compliance on interlayer chemistry shapes supplier qualification timelines and raw-material substitution pathways. Stakeholders must weigh backward integration into PVB resin production against technology licensing partnerships as electrification redefines glazing thermal and electromagnetic performance requirements.
Market Dynamics
The EU Green Deal's carbon-border adjustment mechanism is compressing margins for float-glass importers while rewarding captive soda-lime silica producers with integrated European furnaces. This regulatory pressure is redrawing competitive boundaries between integrated manufacturers and downstream fabricators.
Growth Catalysts
- EU Green Deal Emissions Targets:Tightening CO2 fleet standards are accelerating OEM procurement of lightweight laminated windscreens to reduce vehicle mass. German and French passenger EV assembly corridors are specifying thin-glass architectures at scale.
- Heated Glass Technology:Battery thermal management protocols are extending to cabin glazing surfaces, creating pull-through demand for conductive coatings and embedded heating elements in Nordic markets with cold-climate operation requirements.
- ECE R43 Homologation Standards:Mandatory optical and fragmentation requirements for windscreens are locking in laminated construction with integrated sensor apertures, securing value pools for ADAS-compatible glazing suppliers.
Market Restraints
- Natural Gas Price Volatility:Float-glass furnace operations depend on natural gas feedstock, and input cost spikes from European supply disruptions are eroding margin stability for non-integrated producers.
- PVB Interlayer Supply Concentration:Polyvinyl butyral resin production clusters with a limited set of chemical specialists, creating qualification bottlenecks for new automotive glass entrants seeking REACH-compliant interlayer chemistry.
- Heavy-Metal Coating Restrictions:EMA material safety directives are prohibiting traditional reflective coatings, forcing costly reformulation of solar-control glazing without performance degradation.
Strategic Opportunities
- Poland and Czech Republic EV Assembly:Underpenetrated relative to German capacity, these Central European production zones are attracting new glazing fabrication facilities to serve expanding battery-electric vehicle programs.
- Smart Glass Convergence:Electrochromic and suspended-particle device technologies are merging with antenna-integrated glazing, opening premium specification tiers for roofline and side-window applications.
- CSRD-Driven Supplier Disclosure:Corporate Sustainability Reporting Directive requirements are creating competitive advantage for glass producers with verified recycled-content certificates and Scope 3 emissions transparency.
Industry Challenges
- Chemically Strengthened Thin-Glass Expertise:The shift to sub-3mm windscreen architectures demands ion-exchange process engineers and thin-glass handling specialists that European labor markets currently undersupply.
- ADAS Sensor Aperture Certification:Camera-cluster integration requires optical distortion control within tight tolerances, extending homologation timelines and requiring co-development protocols with Tier 1 electronics suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Glass Market |
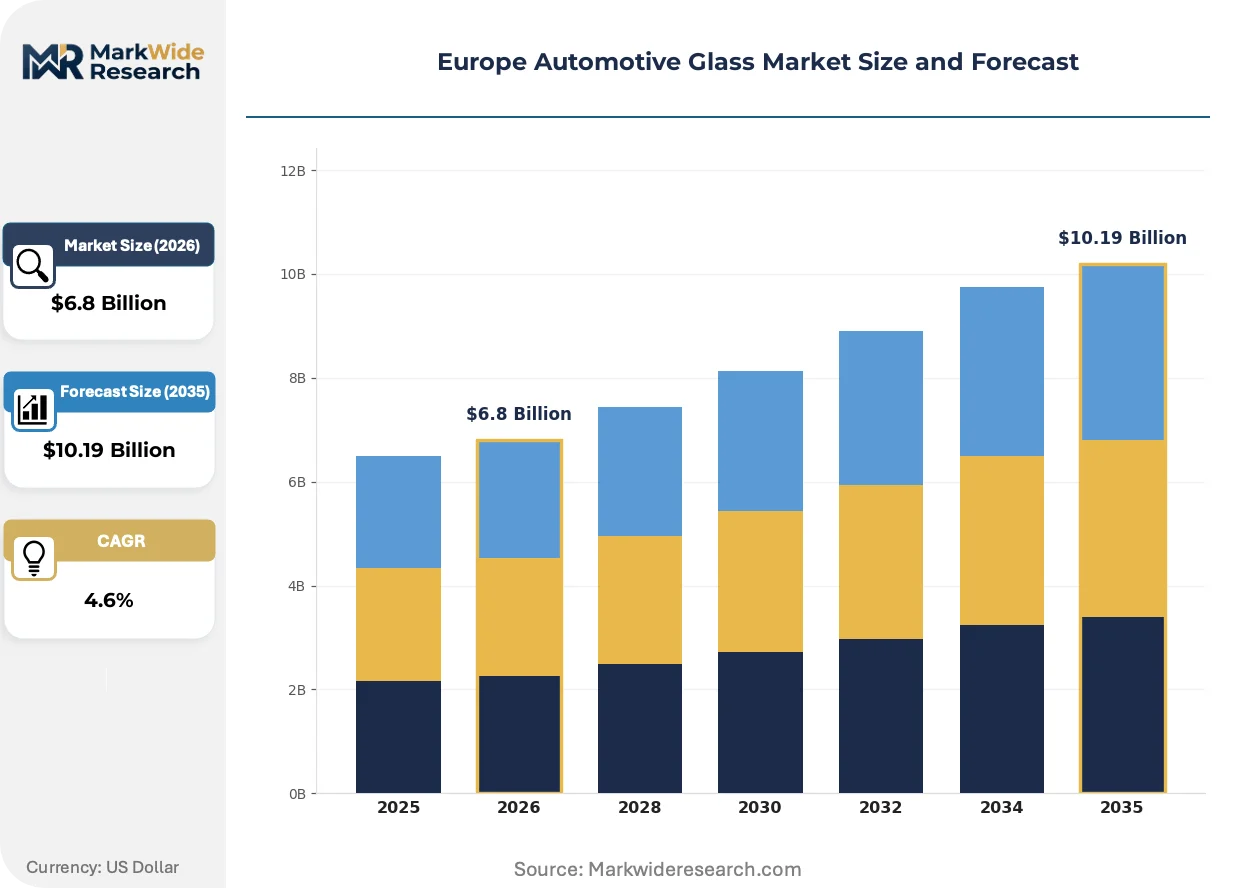
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Windscreens, Side Windows, Rear Windows, Sunroofs Technology: Laminated, Tempered, Heated, Tinted End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Distribution Channel: Direct Sales, Online Retail, Distributors, Service Outlets |
| Companies Covered | Fuyao Glass Industry Group, Xinyi Glass Holdings Limited, Saint-Gobain Sekurit, Magna International, Nippon Sheet Glass Co., Ltd., AGC Inc., Guardian Industries, Webasto Group, NSG Group, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Glass Market Strategic Shifts & Innovations
Electrification is rewriting thermal and electromagnetic performance specifications for automotive glazing, while regulatory disclosure mandates are forcing transparency through the value chain. These pressures are accelerating material substitution and process innovation simultaneously.
Chemically strengthened thin-glass architectures are displacing conventional laminated constructions in electric vehicle rooflines and panoramic applications. AGC Inc. and integrated European producers are scaling ion-exchange toughening lines to serve German and French OEM programs specifying weight reduction. The technology is displacing thicker soda-lime assemblies that previously dominated structural glazing roles.
REACH compliance on interlayer chemistry is reshaping supplier qualification timelines across the European value chain. ECHA substance restrictions are forcing PVB resin substitution pathways and raw-material traceability investments. Downstream fabricators in France and Germany are responding by locking in multi-year resin supply contracts with certified chemical producers.
Aftermarket procurement is fragmenting as independent repair networks gain access to pattern-part windscreens with ADAS recalibration capabilities. Traditional captive distribution through OEM dealer channels is yielding to specialized auto-glass service operators with mobile recalibration equipment. This shift is most visible in the UK and Netherlands where insurance-mediated repair networks dominate claims volume.
Europe Automotive Glass Market Segmentation
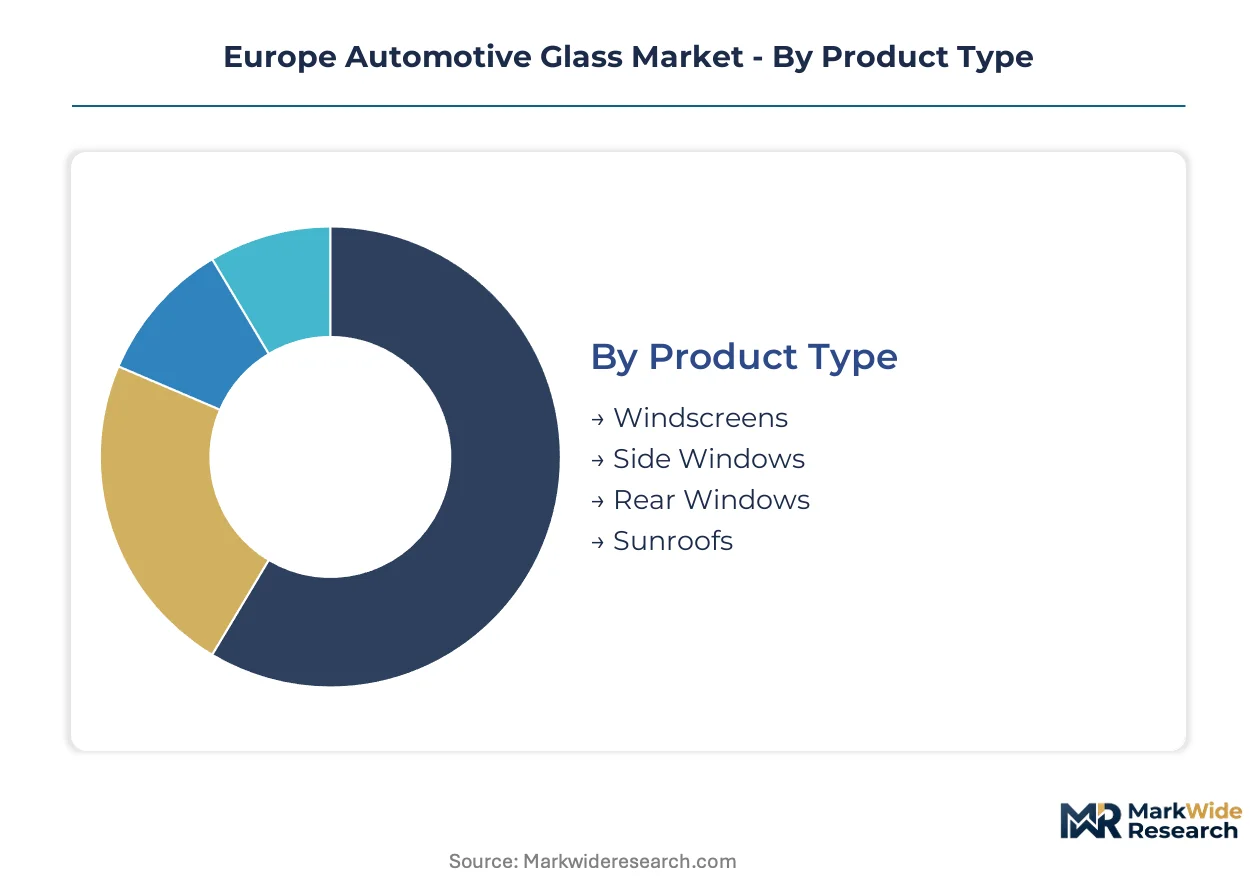
Segmentation in European automotive glass reflects divergent technical specifications across vehicle architectures and regulatory compliance tiers. Product type and technology choices determine furnace configuration, interlayer chemistry, and homologation pathways that shape supplier margins and qualification timelines.
Product Type:
Laminated windscreens face intensifying substitution pressure from chemically strengthened thin-glass roofline assemblies as OEMs pursue mass reduction targets under EU Green Deal fleet standards.
- Windscreens:Mandatory laminated construction under ECE R43 standards integrates PVB interlayers with sensor apertures for ADAS camera clusters. German and French passenger EV programs are specifying sub-4mm thin-glass architectures to reduce vehicle mass. Heated conductive coatings are penetrating Nordic markets for cold-climate battery thermal management.
- Sunroofs:Panoramic rooflines are displacing fixed metal panels in premium electric vehicle segments, driving demand for ionoplast interlayers and structural bonding systems. Czech and Polish EV assembly corridors are attracting dedicated fabrication capacity for oversized glazing modules.
- Side Windows:Tempered soda-lime constructions dominate passenger door applications with rapid fragmentation properties for emergency egress compliance.
- Rear Windows:Heated defogger grids and antenna integration define specification tiers across hatchback and SUV rear assemblies.
Windscreens anchor the volume base while sunroofs gain share at the steepest rate.
Technology:
Cost tier differentiation separates premium specification tiers from standard fleet-grade glazing, with heated and smart technologies commanding 40-60% price premiums over base laminated constructions.
- Laminated:PVB and ionoplast interlayer bonding delivers optical clarity and post-breakage retention for windscreen safety performance. REACH compliance on resin chemistry is extending supplier qualification timelines for new market entrants seeking ECHA-certified interlayer supply.
- Heated:Embedded conductive coatings and wire grids extend battery thermal management protocols to cabin surfaces, with strongest pull-through in Norway, Sweden, and Finland cold-climate operation profiles.
- Tempered:Rapid thermal toughening produces fragmentation patterns meeting ECE R43 side and rear window standards.
- Tinted:Solar-control additives and reflective coatings face heavy-metal restrictions under EMA material safety directives, forcing reformulation without performance degradation.
Laminated technology commands the installed value base while heated specifications expand most quickly across Nordic EV programs.
End User:
Customer type fragmentation is accelerating as aftermarket networks capture ADAS recalibration capabilities that previously locked replacement demand within OEM dealer channels.
- OEMs:Direct procurement relationships with integrated float-glass producers secure volume commitments and co-development protocols for platform-specific glazing modules. Saint-Gobain Sekurit and AGC Inc. anchor supply positions through captive soda-lime silica and thin-glass R&D investment.
- Aftermarket Providers:Independent repair networks with mobile recalibration equipment are displacing traditional captive distribution in UK and Netherlands insurance-mediated claims markets.
- Vehicle Assemblers:Central European production zones in Poland and Czech Republic are attracting glazing fabrication facilities to serve expanding battery-electric vehicle programs.
- Tier-1 Suppliers:Electronics integration specialists manage camera-cluster aperture certification and optical distortion control within ADAS homologation timelines.
OEMs retain the specification authority base while aftermarket providers are gaining share fastest in Northern European repair networks.
Distribution Channel:
Supply concentration in direct sales relationships is yielding to fragmented service outlet networks as independent operators invest in pattern-part inventory and mobile installation capabilities.
- Direct Sales:Long-term supply agreements between integrated producers and German, French, and Italian OEM programs lock in volume and margin stability through platform lifecycle commitments.
- Service Outlets:Specialized auto-glass operators with same-day replacement and recalibration capabilities are capturing insurance claims volume from traditional dealer channels.
- Distributors:Regional warehousing networks serve independent repair shops with pattern-part inventory for legacy vehicle parc maintenance.
- Online Retail:Digital procurement platforms are emerging for fleet maintenance operators and independent installers seeking transparent pricing and specification matching.
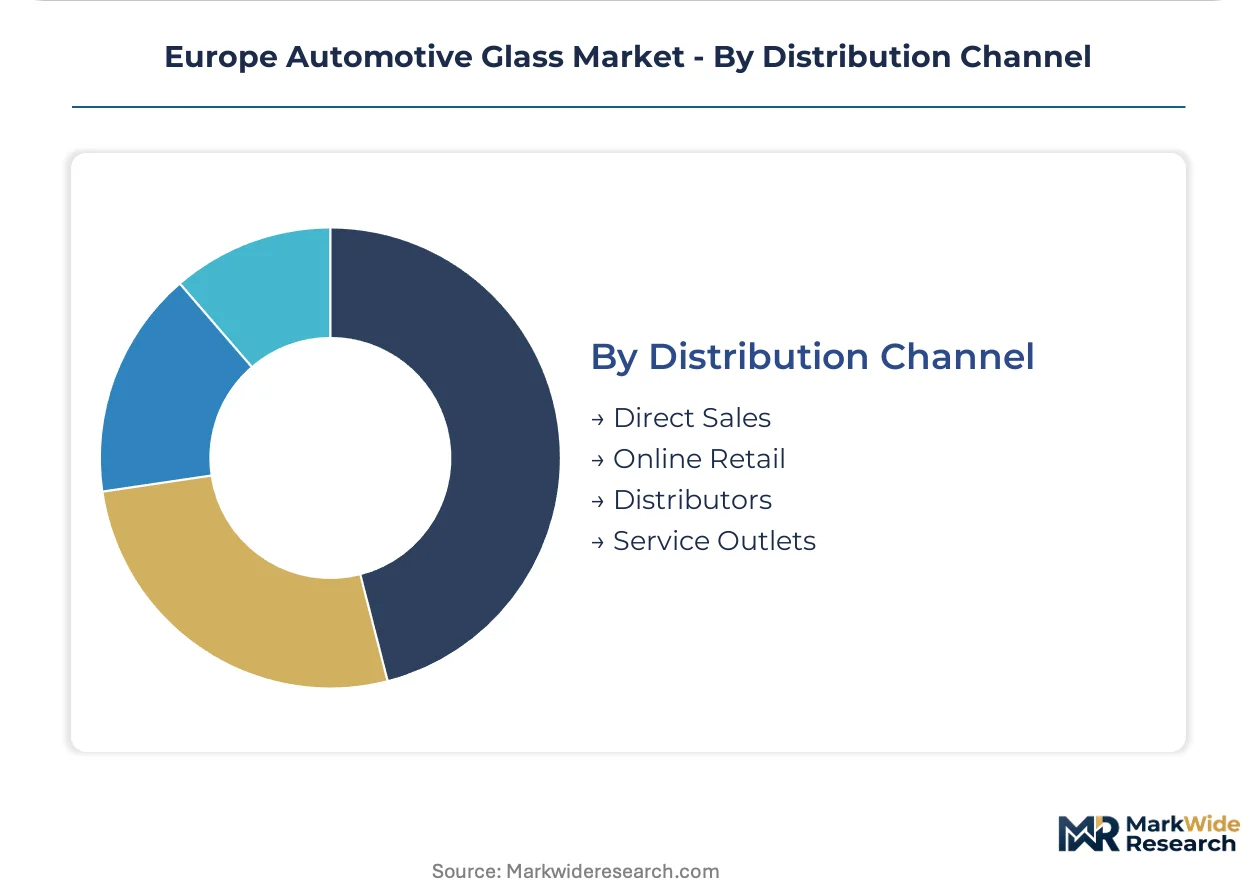
Direct sales channels anchor the revenue base while service outlets are climbing the fastest across UK, Netherlands, and Scandinavian markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across European automotive glass diverge sharply between Nordic cold-climate specifications demanding heated conductive coatings and Central European mass-market programs prioritizing lightweight thin-glass architectures for EV range optimization.
Germany
Passenger EV assembly corridors in Bavaria and Baden-Württemberg are specifying sub-4mm windscreen architectures at scale to meet EU Green Deal fleet emissions targets. KBA homologation protocols for ADAS sensor apertures extend qualification timelines for camera-cluster integration. Stuttgart and Munich anchor integrated supply relationships between OEMs and captive soda-lime silica producers.
France
Renault and Stellantis programs in Île-de-France and Hauts-de-France are driving procurement of laminated windscreens with embedded antenna systems for connected vehicle platforms. ANSM material safety directives on interlayer chemistry shape REACH-compliant resin qualification pathways. Douai and Maubeuge production zones attract dedicated glazing fabrication capacity for electric vehicle platforms.
Poland
Battery-electric vehicle assembly expansion in Lower Silesia and Masovian Voivodeship is pulling glazing suppliers eastward from German supply bases. EU Green Deal carbon-border adjustments favor local fabrication over imported float-glass modules. Gliwice and Warsaw industrial corridors are attracting dedicated sunroof and panoramic glazing facilities.
Sweden
Cold-climate operation requirements in Scandinavian markets are accelerating OEM specification of heated glass technology with conductive coatings for battery thermal management extension. ECHA substance restrictions on heavy-metal formulations are forcing reformulation of traditional solar-control glazing. Gothenburg and Trollhättan anchor Volvo program supply chains for Nordic specification tiers.
Czech Republic
Skoda Auto and emerging EV platform assembly in Central Bohemia are creating demand for oversized glazing modules and structural bonding systems. EU CSRD disclosure requirements are creating competitive advantage for producers with verified recycled-content certificates. Mladá Boleslav and Kvasiny production clusters are attracting Tier-1 glazing integration specialists.
Europe Automotive Glass Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with captive float-glass producers commanding margin control through backward integration into soda-lime silica supply while downstream fabricators face input cost volatility from natural gas price spikes. Three archetypes dominate: integrated European furnace operators with captive raw material supply, Asian-scale producers leveraging ion-exchange thin-glass expertise, and regional fabrication specialists serving aftermarket networks. Competitive moves concentrate on strategic partnerships for ADAS co-development and capacity expansion into Central European EV assembly corridors.
Within the integrated European tier, Saint-Gobain Sekurit and AGC Inc. occupy anchor positions exemplifying captive supply chain control and deep R&D investment in chemically strengthened architectures. Fuyao Glass Industry Group represents the Asian-scale archetype with manufacturing presence serving European OEM programs. These three companies illustrate the structural divergence between integrated margin stability and specialist flexibility across the value chain.
| Leading Market Players |
|---|
| Fuyao Glass Industry Group |
| Xinyi Glass Holdings Limited |
| Saint-Gobain Sekurit |
| Magna International |
| Nippon Sheet Glass Co., Ltd. |
| AGC Inc. |
| Guardian Industries |
| Webasto Group |
| NSG Group |
| Others |
Cost & Logistics Intelligence
Float-glass furnace scale economies in Germany and France anchor price floors across the European value chain, with integrated producers commanding margin stability through captive soda-lime silica supply while downstream fabricators absorb natural gas cost volatility. This concentration of melting capacity shapes procurement negotiations with OEMs and locks qualification timelines for new entrants.
Pricing Analysis
Aftermarket service revenue streams anchored by ADAS recalibration capabilities now drive lifetime value capture beyond initial glass sales. Three-tier pricing structure across premium, standard, and economy levels separates OEM-specified heated and smart glass from base laminated constructions and pattern-part alternatives. Pricing pressure stems from EU Green Deal carbon-border adjustments compressing margins for non-integrated importers. Fleet operators and insurance-mediated repair networks exhibit highest price sensitivity, while premium EV OEMs prioritize performance specifications over unit cost.
Supply Chain Analysis
Inventory lead times for PVB interlayer resin stretch qualification timelines as REACH-compliant chemistry concentrates with limited chemical specialists in Belgium and the Netherlands. Raw material flows draw from German soda-lime silica furnaces, Italian ionoplast interlayer production, and Nordic conductive coating specialists. Single-source vulnerability sits with PVB resin supply concentration. Distribution runs through direct OEM supply agreements for volume programs and fragmented service outlet networks for aftermarket replacement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
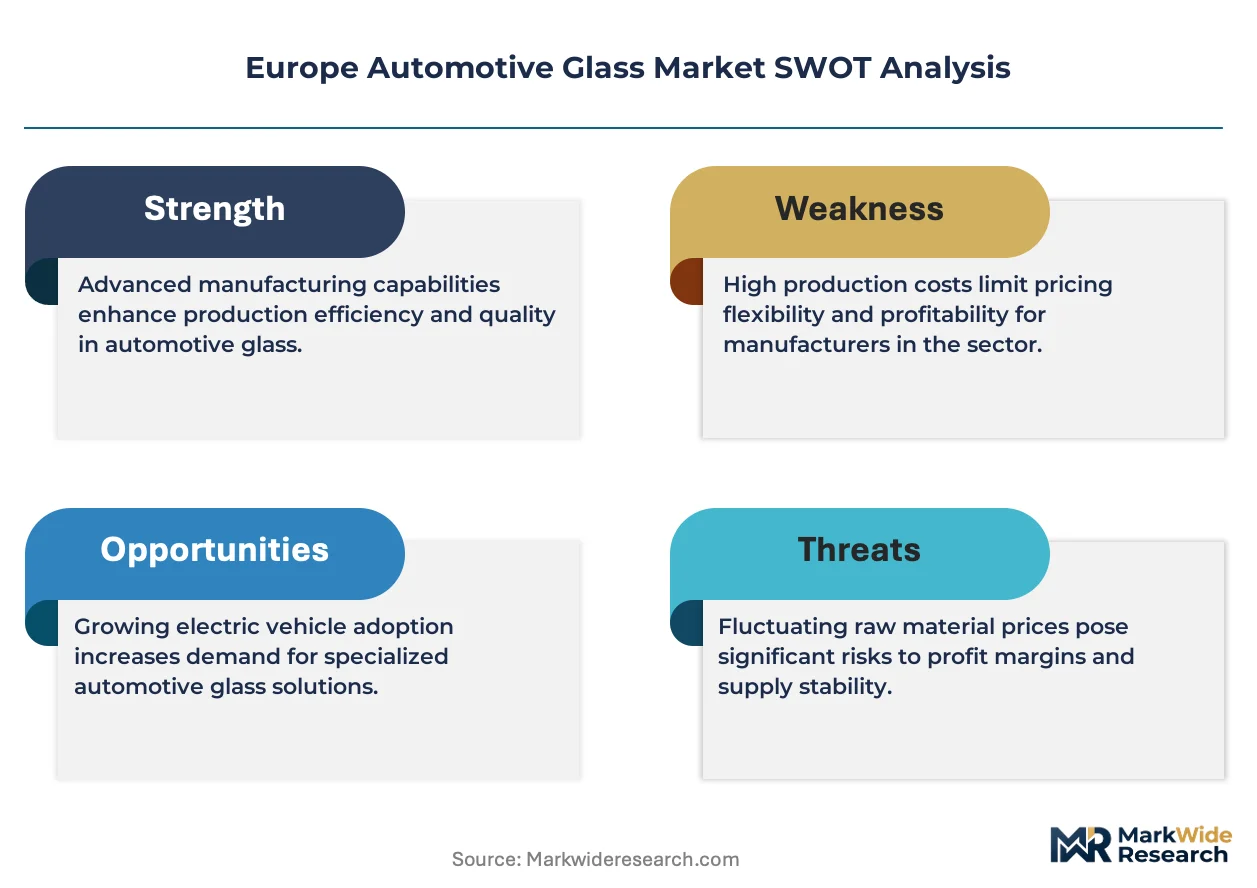
The Europe automotive glass market rewards producers with ion-exchange process engineers and thin-glass handling specialists that regional labor markets currently undersupply. Capability gaps in chemically strengthened architectures and ADAS optical certification create defendable positions for integrated incumbents while raising barriers for new entrants.
For Market Incumbents: Fortify backward integration into PVB resin supply or lock multi-year interlayer contracts with ECHA-certified producers to defend against REACH-driven qualification bottlenecks. Expand ion-exchange toughening capacity in Czech and Polish industrial corridors to capture Central European EV assembly growth. Prioritize co-development protocols with Tier 1 electronics suppliers for camera-cluster aperture certification.
For New Entrants and Emerging Players: Anchor in aftermarket service networks with mobile ADAS recalibration capabilities, where insurance-mediated claims volume in the UK and Netherlands offers lowest barriers to customer access. Target pattern-part windscreen supply for legacy vehicle parc maintenance. Pursue digital procurement platform partnerships with fleet maintenance operators to bypass captive OEM dealer channels.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated producers with verified recycled-content certificates and Scope 3 emissions transparency under CSRD disclosure requirements. Long-term viability hinges on thin-glass R&D depth and Central European manufacturing footprint expansion. Watch for inflection in OEM specification rates for sub-3mm windscreen architectures as EU Green Deal fleet standards tighten.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PVB Resin | Secures REACH-compliant interlayer supply against ECHA qualification bottlenecks for integrated producers. |
| Ion-Exchange Toughening Capacity Expansion | Captures German and French OEM demand for sub-4mm thin-glass architectures in EV roofline applications. |
| ADAS Co-Development Partnerships | Locks camera-cluster aperture certification timelines with Tier 1 electronics suppliers for platform-specific glazing. |
| Central European Manufacturing Footprint | Positions fabrication facilities to serve Polish and Czech battery-electric vehicle assembly corridors. |
| CSRD-Aligned Recycled Content Certification | Creates competitive advantage in OEM procurement decisions driven by Corporate Sustainability Reporting Directive mandates. |
Research Approach
Initial hypotheses were tested against primary input from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and ion-exchange process specialists and refined through secondary validation. Primary fieldwork combined structured interviews with furnace operators and glazing fabricators across German, French, and Central European production zones. Secondary sources encompassed ECE R43 homologation filings, EU Green Deal regulatory texts, vehicle production databases, and customs trade records for float-glass imports. Bottom-up segment sizing triangulated against top-down market value estimates.
Variance decomposition across product type, technology tier, end-user channel, and regional production cluster shaped the analytical framework. Modeled dimensions included windscreen versus sunroof versus side-window specifications, laminated versus heated versus tempered technology tiers, OEM versus aftermarket versus vehicle assembler end-user categories, and German versus French versus Central European regional clusters. CAGRs were derived from installed base growth and content-per-vehicle trajectories. Forecast inputs incorporated EU fleet emissions target stringency and EV penetration rates by assembly corridor.
Material uncertainties — natural gas price volatility, PVB resin supply disruptions, and ECHA substance restriction amendments — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory stability and OEM platform commitment timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Off-Highway Actuators Market
Automotive Components
Intelligent Torque Controlled Coupling (ITCC) Market
Automotive Components
Automotive Connecting Rod Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Automotive Rear End Module Market
Automotive Components
Automotive Metal Stamping Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Drive System Market
Automotive Components
Auto Fender Market
Automotive Components
Automotive Key Market
Automotive Components
Aftermarket Automotive Parts & Components Market
Automotive Components
India Automotive Stamping Market
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Automotive Plastic Components Market
Automotive Components
Italy Automotive Actuators Market
Automotive Components
Global Automotive Collapsible Steering Column Market