
 Automotive Emblem Market | 2026-2036
Automotive Emblem Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Emblem Market Analysis
Mexico is narrowing its supplier base around Monterrey-to-Detroit logistics corridors as North American OEMs reshore emblem procurement. Tokai Rika Co. Ltd. leverages its vertical integration in chrome plating to sustain cost advantages across Japanese and North American contracts. Lacks Enterprises anchors substantial capacity in decorative trim clusters around Detroit, competing on proximity to final assembly. SRG Global differentiates through advanced coating technologies that extend weathering performance beyond standard OEM specifications.
Automotive emblems are identification and brand markers affixed to vehicle exteriors, typically manufactured through injection molding, die-casting, or stamping followed by electroplating, painting, or physical vapor deposition finishing. These components must withstand thermal cycling, UV exposure, and chemical attack while maintaining precise dimensional tolerances for flush mounting on body panels. Metal emblems retain premium positioning in luxury segments where weight and tactile quality justify higher unit costs, while LED emblems represent the fastest-expanding category as electrified vehicles adopt illuminated branding for nighttime recognition. Plastic emblems dominate volume production due to lower per-unit material costs and compatibility with complex three-dimensional geometries.
EPA regulations on hexavalent chromium emissions shape plating process investments across U.S.-based suppliers, while REACH restrictions in Europe limit certain substrate and coating chemistries. Japan's METI encourages domestic production of high-durability decorative components through JIS standard compliance benchmarks. Stakeholders must monitor evolving material compliance timelines and electrification-driven design shifts as illuminated and sensor-integrated emblems redefine functional requirements.
Market Dynamics
Electrification is compressing emblem design cycles as OEMs integrate illumination, sensors, and thermal management into previously passive brand markers, forcing suppliers to retool from decorative metalwork to electromechanical subsystems.
Growth Catalysts
- REACH material restrictions:European chemical limits on hexavalent chromium and heavy-metal finishes are accelerating supplier investment in PVD and eco-plating alternatives that command premium positioning.
- EV exterior lighting integration:Electrified vehicle platforms are embedding emblems within active illumination systems, expanding addressable component value per vehicle.
- Monterrey-to-Detroit corridor concentration:North American logistics optimization around this specific route is shortening lead times for just-in-sequence emblem delivery to assembly plants.
Market Restraints
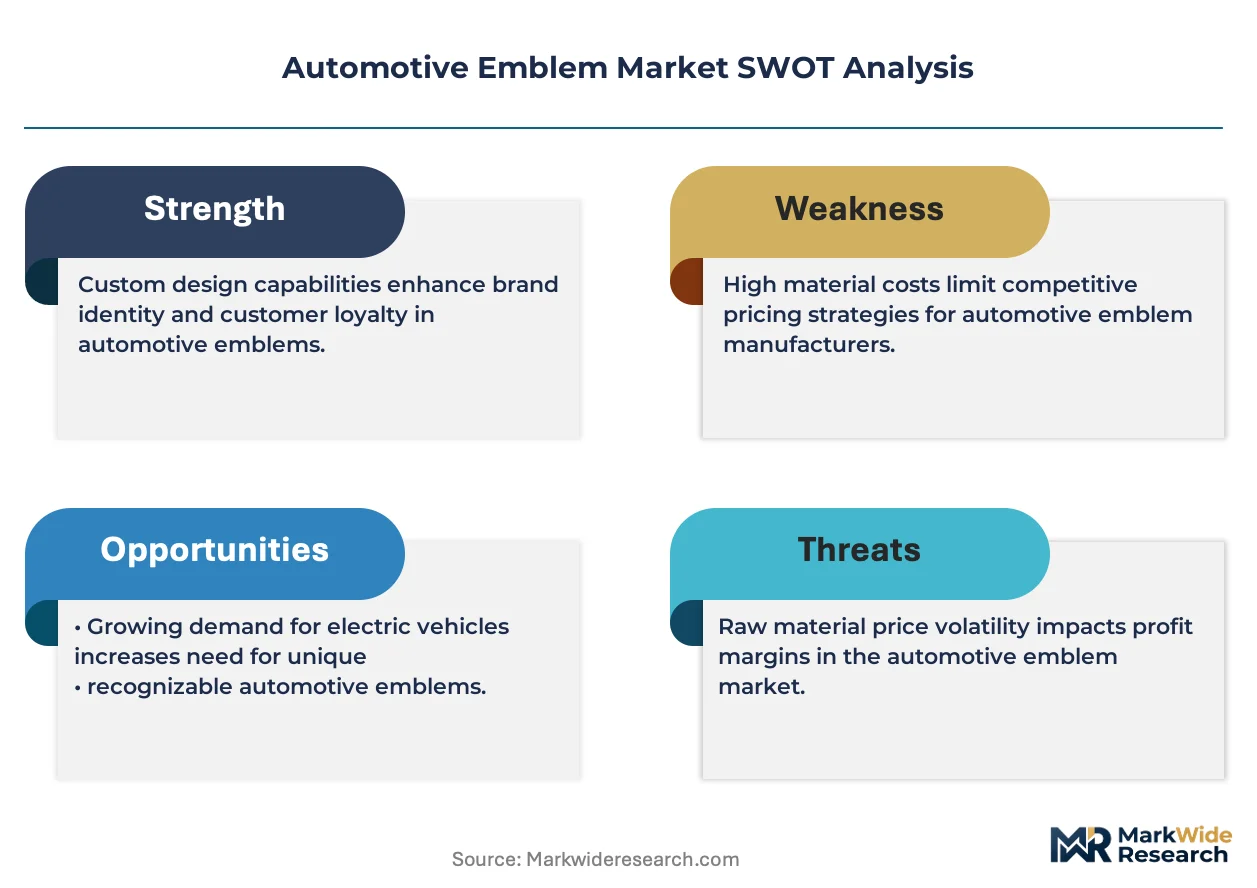
- Chrome plating input volatility:Nickel and chromium price swings compress margin predictability for suppliers dependent on conventional electroplating.
- German-Japanese supplier concentration:Flagship assembly plants in these countries source predominantly from entrenched domestic supplier parks, creating barriers for new entrants.
- Plastic tactile quality ceiling:Metal emblems retain irreplaceable weight and haptic differentiation in luxury segments where polymer alternatives fail to satisfy buyer expectations.
Strategic Opportunities
- China NMPA labeling compliance services:Foreign suppliers can capture value by offering regulatory navigation for domestic OEMs exporting to markets with divergent material standards.
- Sensor-integrated smart emblems:Convergence of radar-transparent substrates and LED illumination enables new product categories for ADS-equipped vehicles.
- Aftermarket personalization channels:Direct-to-consumer replacement emblems bypass traditional Tier-1/Tier-2 supply hierarchies in enthusiast vehicle segments.
Industry Challenges
- Electroplating-to-PVD workforce reskilling:Physical vapor deposition requires fundamentally different technician competencies than legacy wet chemistry processes.
- Dual certification timeline compression:Simultaneous EPA hexavalent chromium compliance and REACH substance registration demands parallel capital deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Emblem Market |
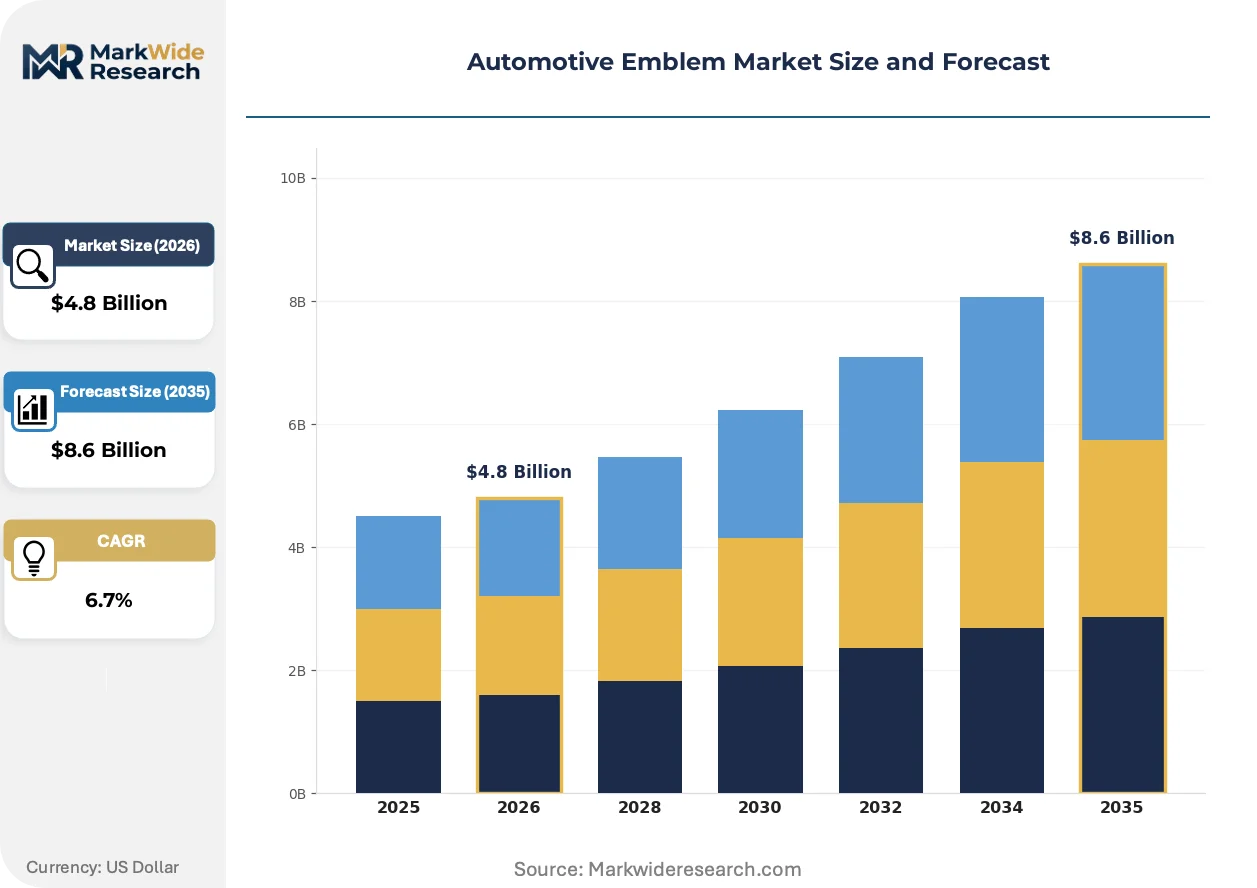
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Emblems, Plastic Emblems, LED Emblems, 3D Emblems End User: OEMs, Aftermarket Providers, Dealerships, Auto Manufacturers Design Type: Custom Designs, Standard Designs, Vintage Designs, Modern Designs Material: Aluminum, Stainless Steel, Carbon Fiber, Acrylic |
| Companies Covered | Tokai Rika Co. Ltd., Lacks Enterprises, Toyoda Gosei Co. Ltd., SRG Global, Leonhard KURZ, Zanini Auto Group, Shinko Nameplate, CIE Automotive, LaFrance Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Emblem Market Emerging Trajectories
Functional integration is overtaking pure aesthetics as the primary value driver, with emblems evolving from passive brand identifiers into active vehicle subsystems that must manage heat, transmit signals, and withstand electrified powertrain environments.
LED illumination is migrating from decorative accent to functional exterior lighting. Premium EV platforms embed emblems within signature lighting signatures for nighttime brand recognition. This technology is migrating from high-end electric flagships toward mass-market crossover segments, compressing the traditional metal-emblem supply base into specialized luxury niches.
EPA regulations on hexavalent chromium emissions are forcing plating process reinvestment across U.S.-based suppliers. Wet chemistry lines face retrofit or replacement costs that favor consolidated operations with capital reserves. Chrome-dependent product categories are most affected, with suppliers accelerating physical vapor deposition and spray-coated metallic finishes as compliant alternatives.
Fleet procurement of standardized emblem specifications is displacing model-year customization. Rental and commercial vehicle operators negotiate multi-year supply agreements with minimal design variation, compressing supplier design resources toward consumer retail channels. This pattern is most visible in North American full-size pickup and commercial van segments where fleet penetration exceeds retail in certain configurations.
Automotive Emblem Market Segmentation
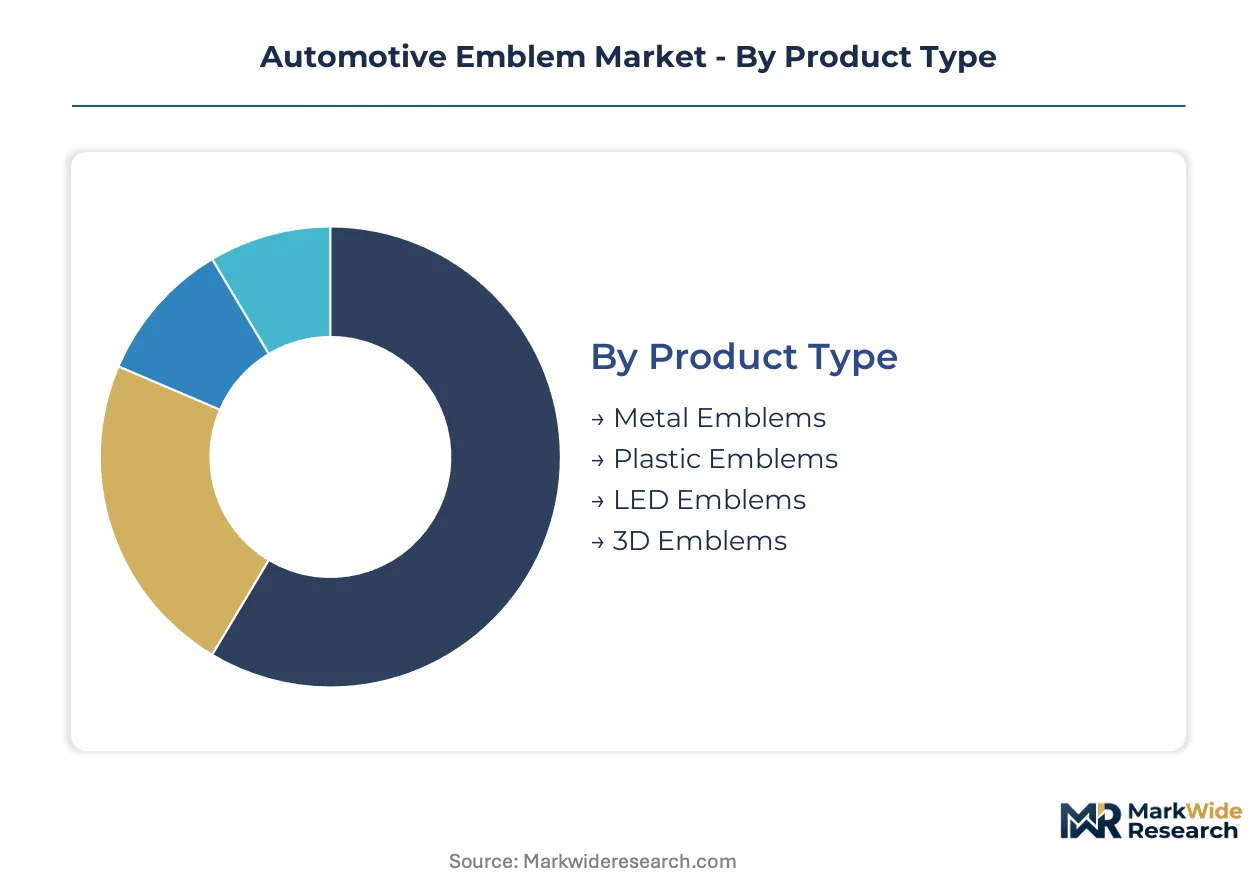
Segmentation in the automotive emblem market reveals divergent margin profiles and technology refresh cycles across material and functional categories. Suppliers must align capacity investments with the electrification-driven acceleration of LED and smart emblem adoption while maintaining legacy metal and plastic production for volume segments.
Product Type:
LED emblems compress design cycles to 18-24 months as electrified platforms demand continuous functional upgrades, while metal emblems operate on 5-7 year refresh timelines tied to traditional model cycles.
- Metal Emblems:Die-cast aluminum and zinc alloy substrates finished through electroplating or PVD retain premium positioning in luxury vehicle segments. German and Japanese flagship assembly plants source these components domestically, with weight and tactile quality justifying higher unit costs despite REACH restrictions on hexavalent chromium processes.
- LED Emblems:Electromechanical subsystems integrating illumination, thermal management, and sensor transparency represent the steepest expansion trajectory as EV platforms embed active exterior lighting for nighttime brand recognition. OEM specifications now demand IP67 sealing and radar-transparent substrates that exceed conventional emblem engineering.
- Plastic Emblems:Injection-molded ABS and polycarbonate variants dominate high-volume production through lower material costs and complex geometry compatibility.
- 3D Emblems:Sculpted forms achieved through multi-axis machining or advanced molding create depth effects for premium trim differentiation.
Plastic emblems anchor the volume base while LED emblems gain share at the steepest rate.
End User:
Procurement patterns split between long-term supply agreements with concentrated OEM supplier parks and fragmented aftermarket channels with shorter lead-time requirements.
- OEMs:Original equipment manufacturers negotiate multi-year contracts with just-in-sequence delivery requirements, concentrating procurement around Detroit, Stuttgart, and Toyota City supplier parks. NMPA labeling compliance and REACH material registration demands favor established Tier-1 suppliers with parallel certification capabilities.
- Auto Manufacturers:Captive brand operations at Volkswagen, Toyota, and General Motors maintain direct supplier relationships for flagship emblems, with design control residing in-house.
- Aftermarket Providers:Direct-to-consumer channels bypass traditional supply hierarchies for enthusiast personalization segments.
- Dealerships:Franchise networks source replacement emblems through authorized distributor networks with brand-controlled pricing.
OEMs dominate absolute procurement value while aftermarket providers expand most quickly through personalization demand.
Design Type:
Cost structures range from amortized tooling for standardized designs to per-unit premiums for custom engineering with unique substrate specifications.
- Custom Designs:Bespoke emblem engineering for limited-production vehicles or special editions commands 3-5x standard pricing. These programs require dedicated tooling investments and carry higher technical risk due to unproven thermal cycling performance.
- Modern Designs:Minimalist flat graphics and illuminated elements align with contemporary EV exterior aesthetics, with design resources concentrating in California, Munich, and Shanghai studios.
- Standard Designs:Carryover specifications across model years minimize engineering overhead for high-volume nameplates.
- Vintage Designs:Heritage reproduction emblems serve restoration and collector vehicle segments with specialized material matching.
Standard designs carry the production volume while custom designs capture the highest margin per unit.
Material:
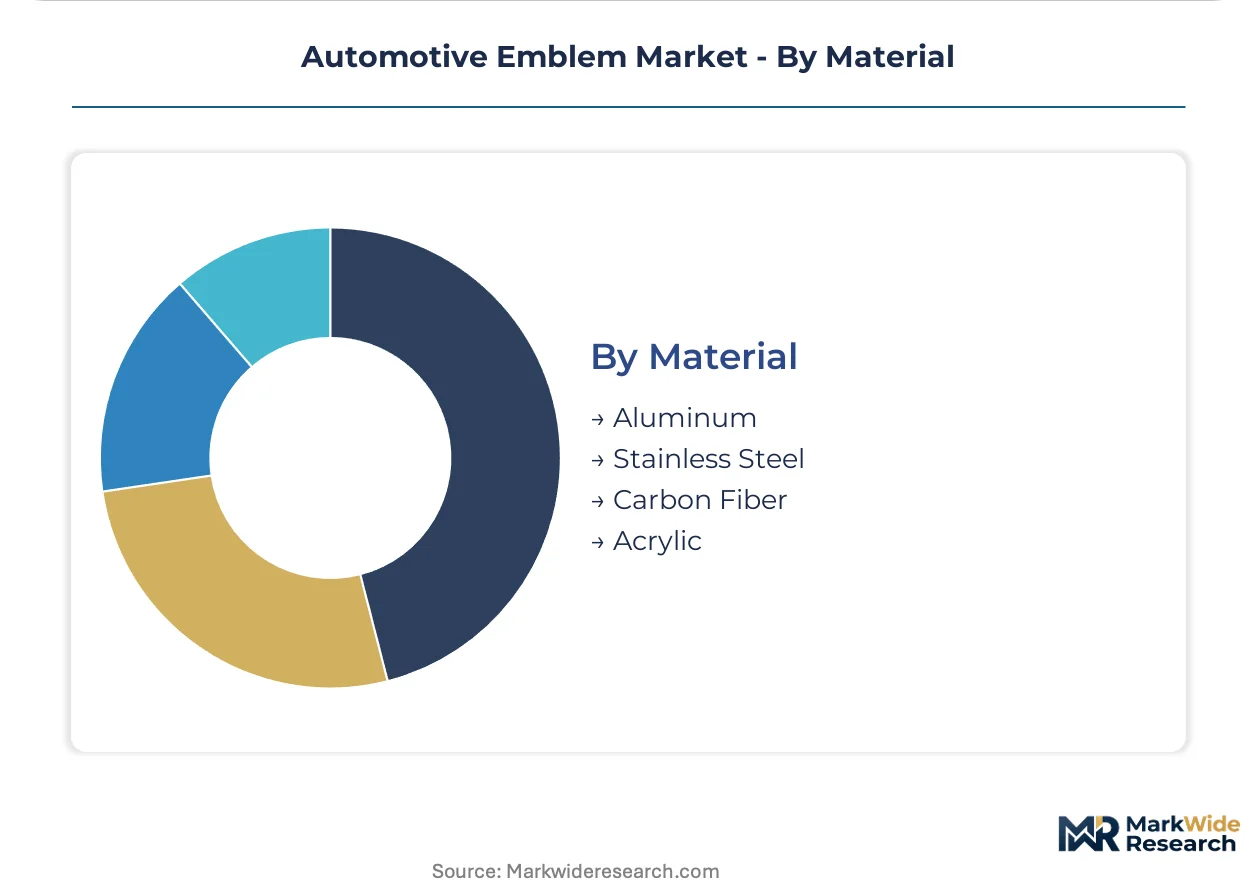
Substrate selection determines regulatory compliance pathways, with aluminum and stainless steel facing REACH restrictions while carbon fiber navigates EPA emissions during processing.
- Aluminum:Lightweight die-cast and stamped aluminum substrates balance formability with corrosion resistance, dominating premium volume applications. EPA hexavalent chromium regulations are forcing plating process reinvestment for U.S.-based aluminum finishers.
- Acrylic:Thermoplastic substrates enable complex optical designs for illuminated emblems with integrated light guides, with optical-grade specifications demanding tight dimensional tolerances for consistent light diffusion.
- Stainless Steel:Cold-rolled grades offer superior weathering performance without protective coatings, though higher material costs limit deployment to luxury segments.
- Carbon Fiber:Composite substrates deliver weight reduction and technical aesthetics for performance vehicle applications.
Aluminum underpins the broadest application base while acrylic climbs fastest through LED emblem adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA hexavalent chromium regulations anchor North American supplier reinvestment while ECHA REACH restrictions reshape European finishing chemistries. OEM assembly clusters in Germany, Japan, and the United States concentrate procurement through domestic supplier parks with just-in-sequence delivery requirements.
United States
Detroit-area supplier parks anchor domestic emblem procurement for the Big Three automakers. EPA regulations on hexavalent chromium emissions force plating process reinvestment across Michigan and Ohio finishing operations. The Monterrey-to-Detroit logistics corridor compresses lead times for just-in-sequence delivery to assembly plants in Michigan and Tennessee.
Germany
Stuttgart and Munich flagship plants source premium metal emblems through entrenched domestic supplier networks. ECHA REACH restrictions on heavy-metal finishes accelerate physical vapor deposition adoption among Baden-Württemberg coating specialists. The supplier park concentration around Wolfsburg and Ingolstadt creates barriers for non-European entrants.
China
NMPA vehicle labeling rules tighten compliance requirements for chrome and heavy-metal finishes on vehicles sold domestically. MIIT encourages domestic production of high-durability decorative components through GB standard alignment. Yangtze River Delta and Pearl River Delta clusters concentrate injection-molded plastic emblem capacity for volume EV platforms.
Japan
METI promotes domestic production of high-durability decorative components through JIS standard compliance benchmarks. Toyota City and Nagoya supplier parks maintain captive relationships with emblem specialists for flagship vehicle programs. Japanese OEMs source predominantly from domestic Tier-1 networks, limiting foreign supplier penetration.
Mexico
Nuevo León assembly plants serve North American OEMs with shortened logistics corridors to Texas and Michigan. The country's automotive manufacturing incentives attract emblem suppliers co-locating with final assembly. Monterrey industrial parks concentrate decorative trim operations targeting Detroit just-in-sequence requirements.
Automotive Emblem Market Vendor Landscape
Integrated plating specialists and regional proximity players split the market through divergent capability investments. The supplier base concentrates around three strategic archetypes: vertical chrome platers with captive finishing assets, regional logistics-optimized fabricators, and coating technology licensors. Competitive moves center on EPA-compliant process retrofit and LED emblem module partnerships with electrified vehicle platforms.
Among Japanese fabricators, Tokai Rika Co. Ltd. and Toyoda Gosei Co. Ltd. exemplify the integrated plating archetype with domestic JIS-certified operations. Detroit-proximate Lacks Enterprises occupies a position within the regional logistics tier serving North American OEM just-in-sequence requirements. SRG Global represents the coating technology vector through advanced weathering performance capabilities.
| Leading Market Players |
|---|
| Tokai Rika Co. Ltd. |
| Lacks Enterprises |
| Toyoda Gosei Co. Ltd. |
| SRG Global |
| Leonhard KURZ |
| Zanini Auto Group |
| Shinko Nameplate |
| CIE Automotive |
| LaFrance Corp. |
| Others |
Supply Flow & Price Mechanics
The Monterrey-to-Detroit logistics corridor compresses freight costs for just-in-sequence emblem delivery while concentrating supplier pricing power among chrome-plating specialists with captive finishing assets. REACH restrictions on hexavalent chromium and EPA emissions rules are bifurcating the supply base into premium PVD-capable suppliers and cost-pressured conventional platers, with price differentiation widening between compliant and legacy finish categories.
Pricing Analysis
Geographic price spreads between German domestic supplier parks and Mexican export-oriented operations reflect divergent labor and compliance cost structures. Contract-based long-term offtake agreements dominate OEM procurement, with price differentiation driven by certification tier (REACH-registered vs. transitional) and volume scale commitments. Cost compression in conventional chrome-plating tiers is intensifying because nickel and chromium input volatility erodes margin predictability. Fleet procurement managers exhibit the highest price sensitivity, while luxury OEMs purchasing metal emblems for flagship programs demonstrate minimal elasticity.
Supply Chain Analysis
Export-control scrutiny on physical vapor deposition equipment and advanced coating technologies limits technology transfer to certain jurisdictions, constraining supplier capability expansion. Manufacturing concentrates in Germany, Japan, and Mexico, with raw material dependencies on nickel cathodes, chromium trioxide, and optical-grade acrylic resins. Single-source vulnerability persists for EPA-compliant PVD coating lines, where qualified equipment suppliers number fewer than five globally. Distribution runs through Tier-1 supplier parks co-located with final assembly plants in Detroit, Stuttgart, and Toyota City.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive emblem market is approaching a platform-economics inflection as illuminated and sensor-integrated emblems become interoperable subsystems within standardized EV exterior lighting architectures. Suppliers must align with OEM software-defined vehicle roadmaps or risk displacement by electronics-integrated module specialists.
For Market Incumbents: Entrench plating-process compliance advantages by accelerating EPA-compliant PVD retrofit investments ahead of hexavalent chromium phase-out deadlines. Deepen captive finishing capacity in Monterrey industrial parks to defend proximity-based contracts against reshoring competitors. Lock in multi-year supply agreements with electrified vehicle platforms before LED emblem specifications standardize.
For New Entrants and Emerging Players: Establish a beachhead in aftermarket personalization channels where direct-to-consumer sales bypass entrenched Tier-1 hierarchies. Target sensor-integrated smart emblem development for ADS-equipped vehicles, where radar-transparent substrate expertise remains scarce. Pursue white-label manufacturing partnerships with Chinese EV exporters navigating NMPA labeling compliance for European markets.
For Investors and Strategic Acquirers: Regional logistics-optimized fabricators with Monterrey-to-Detroit corridor positioning represent the most defensible acquisition archetype as North American OEMs consolidate supplier bases. Long-term viability hinges on electromechanical integration capabilities rather than decorative metalwork heritage. Monitor EPA enforcement timelines for hexavalent chromium emissions as the inflection signal for plating asset stranded-cost risk.
| Strategic Initiative | Industry Significance |
|---|---|
| PVD Process Retrofit Investment | EPA-compliant coating lines secure continued access to U.S. OEM procurement programs. |
| LED Emblem Module Partnership | Electrified vehicle platforms embed illuminated branding within signature lighting architectures. |
| Monterrey Supplier Park Co-location | Proximity to Detroit assembly plants compresses just-in-sequence delivery lead times. |
| REACH Certification Acceleration | ECHA-registered coating chemistries unlock premium positioning in European luxury segments. |
| Aftermarket Direct Channel Launch | Enthusiast personalization demand bypasses traditional Tier-1/Tier-2 supply hierarchies. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, Tier-1 supplier procurement directors, aftermarket distributors, and decorative trim plant managers. Secondary validation drew from EPA enforcement databases, ECHA substance registration filings, vehicle production registries, and customs trade records. Bottom-up capacity assessments across plating and coating operations were triangulated against top-down OEM procurement value chain estimates.
Calibration against historical production volumes and announced platform launches anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include material substrate, functional category (passive vs. illuminated vs. sensor-integrated), vehicle class, and regional production cluster. CAGRs were derived from fitted growth curves incorporating electrification penetration rates and regulatory compliance timelines. Industry-specific forecast inputs encompassed NMPA labeling rule implementation schedules and EPA hexavalent chromium emissions phase-out trajectories.
Sensitivities concentrate around EPA enforcement intensity, REACH substance restriction expansions, and EV platform launch delays. Forecasts reflect documented assumptions regarding regulatory timelines and OEM electrification commitments. Material shifts in hexavalent chromium exemption durations or illuminated emblem standardization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Hardware Market
Automotive Components
Auto Fender Market
Automotive Components
Automotive Light Bars Market
Automotive Components
Global Automotive Brake Components Market
Automotive Components
Automotive Brake System and Components Market
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Asia Pacific Automotive AHSS Market
Automotive Components
Automotive Clutch Disc Market
Automotive Components
Automotive Filters Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
Europe Automotive Plastics Market
Automotive Components
Latin America Automotive Electric Actuators Market