
 Brake Cooling Duct and Hose Market | 2026-2036
Brake Cooling Duct and Hose Market Size, Share, and Industry Trends Forecast 2026-2036
Brake Cooling Duct and Hose Market Analytics
German automotive suppliers is consolidating capacity around precision thermal management for high-performance braking systems. Brembo leverages its motorsport heritage to anchor premium duct and hose specifications for racing applications. Continental AG sustains broad OEM relationships across European and North American passenger vehicle platforms. Gates Corporation specializes in elastomeric hose formulations that withstand repeated thermal cycling under extreme brake temperatures.
Brake cooling ducts and hoses are engineered conduits that channel ambient or forced air toward brake rotors, calipers, and pads to dissipate thermal energy exceeding 500°C during sustained deceleration events. These components typically incorporate aluminum ducting for structural rigidity, silicone or fluorocarbon rubber hoses for flexible routing, and stainless steel fittings for secure attachment under vibration and thermal expansion. The motorsports application segment commands premium pricing due to bespoke aerodynamic integration and FIA-mandated safety compliance, while automotive OEM demand scales through platform-standardized aluminum duct architectures that reduce per-unit tooling burden across vehicle lines.
NHTSA, EPA, and ECE R90 standards collectively govern brake system thermal performance, material emissions, and replacement part equivalence across the United States and European markets. These frameworks compel manufacturers to validate hose compounds for ozone resistance and duct geometries for minimum airflow coefficients before market authorization. Stakeholders must monitor evolving thermal efficiency mandates from regulators and track composite material substitutions that could displace conventional aluminum and rubber architectures in next-generation electric vehicle platforms.
Market Dynamics
Brake cooling duct and hose procurement is concentrating around high-performance electric vehicle platforms where regenerative braking coexistence demands redesigned thermal architectures. Tier-1 suppliers are consolidating aluminum forging and silicone compounding capabilities to serve dual OEM and motorsport demand streams from shared production footprints.
Growth Catalysts
- NHTSA thermal performance mandates:Updated brake system testing protocols in the United States require validated airflow coefficients for sustained high-speed deceleration scenarios, forcing OEMs to specify duct geometries with documented thermal dissipation rates.
- Motorsport platform standardization:FIA GT3 and Formula E homologation rules now mandate redundant cooling pathways, creating pull-through demand for braided stainless steel hose assemblies and CFD-optimized duct profiles.
- Silicone rubber formulation advances:Fluorosilicone compounds withstand 300°C continuous exposure with 40% lower compression set than conventional HNBR, enabling thinner wall sections and reduced packaging envelopes in wheel well architectures.
Market Restraints
- Aluminum alloy supply concentration:Primary 6061-T6 and 3003-H14 sheet capacity clusters in Chinese smelting corridors, exposing European and North American duct fabricators to tariff volatility and extended lead times for aerospace-grade material.
- REACH substance restrictions:ECHA candidate list expansion targeting short-chain chlorinated paraffins and certain phthalate plasticizers forces reformulation of hose inner liners, with validation timelines extending 18-24 months for new compound qualification.
- Composite substitution threat:Carbon fiber reinforced polymer air guides achieve comparable thermal conductivity at 60% lower mass for fixed-geometry applications, displacing aluminum in upper-mid vehicle segments where cost sensitivity permits material premiums.
Strategic Opportunities
- Indian passenger vehicle thermal upgrade:Domestic OEMs serving the sub-4-meter SUV segment lack indigenous duct engineering capabilities, creating white space for technical partnerships that transfer aluminum hydroforming and silicone extrusion know-how.
- EPA commercial vehicle idle reduction credits:Extended service brake cooling enables shorter cool-down intervals between heavy descents, qualifying fleet operators for fuel efficiency incentives under Phase 2 greenhouse gas regulations.
- Additive manufacturing convergence:Laser powder bed fusion of aluminum-silicon-magnesium alloys permits topology-optimized internal rib structures impossible with conventional stamping, integrating conformal cooling passages directly into duct walls.
Industry Challenges
- Multi-physics simulation talent scarcity:Coupled CFD-thermal-structural modeling for brake cooling duct design requires expertise spanning turbulence modeling, elastomer hyperelasticity, and aluminum creep-fatigue interaction, with fewer than 200 qualified engineers available across Tier-1 supplier networks.
- ECE R90 replacement part certification:Aftermarket duct and hose assemblies must demonstrate equivalence to original thermal performance through dynamometer testing protocols that cost €45,000-€80,000 per SKU variant, compressing margin for low-volume specialty applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brake Cooling Duct and Hose Market |
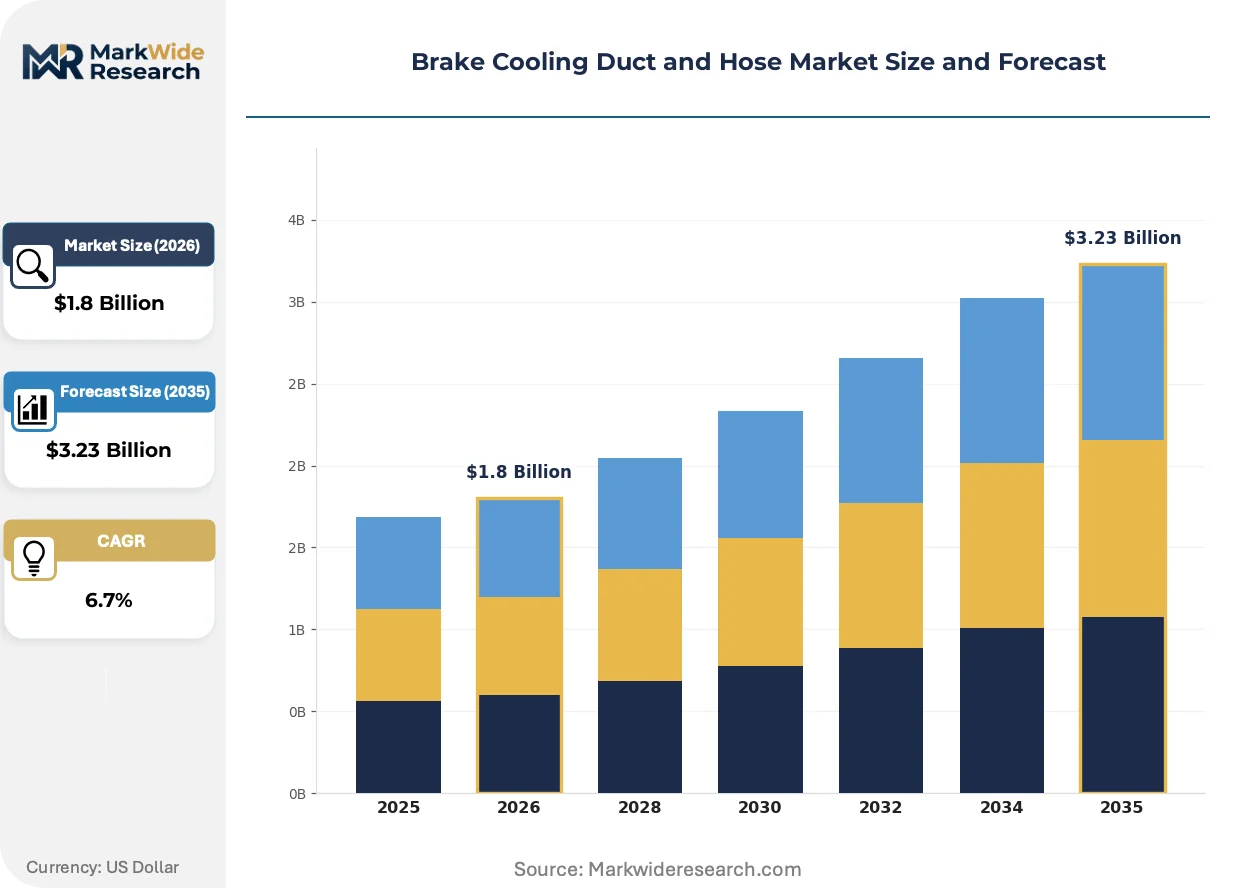
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ducts, Hoses, Fittings, Accessories Material: Aluminum, Rubber, Composite, Steel Application: Aerospace, Automotive, Industrial, Motorsports End User: Original Equipment Manufacturers, Aftermarket Suppliers, Distributors, Repair Shops |
| Companies Covered | Brembo, Valeo, Continental AG, Gates Corporation, ZF Friedrichshafen AG, Pegasus Auto Racing Supplies, APR Performance, Bernie Gillon Motorsport Ltd., All Star Performance, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brake Cooling Duct and Hose Market Evolving Landscape
Thermal management architectures are bifurcating between legacy internal combustion platforms and electric vehicle designs where brake duty cycles shift dramatically. Material scientists and vehicle integration engineers are co-developing solutions that reconcile packaging constraints with escalating performance validation requirements.
Continuous fiber thermoplastic composites are integrating into brake cooling duct prototypes for high-volume electric vehicle programs. BMW and Porsche engineering teams specify unidirectional carbon-PEEK tapes for wheel-mounted duct sections where impact resistance and mass reduction outweigh cost premiums. This material transition is integrating functional grading capabilities that vary fiber orientation between attachment points and airflow surfaces, compressing the traditional metal-to-polymer hybrid assemblies into single-component solutions.
REACH Annex XVII restrictions on per- and polyfluoroalkyl substances are compelling fluorocarbon rubber suppliers to accelerate PFAS-free elastomer development for hose inner liners. The industrial consequence extends beyond material substitution to full system requalification, as ozone resistance and permeation specifications must be revalidated without legacy fluoroelastomer chemistry. Motorsport applications face the most acute timeline pressure, with FIA environmental compliance deadlines preceding broader automotive phase-outs by 24 months.
Fleet procurement departments are consolidating brake cooling component sourcing through long-term thermal performance agreements rather than unit-price contracts. Commercial vehicle operators in Germany and the United States now specify guaranteed maximum brake temperature thresholds over 150,000-kilometer service intervals, transferring technical risk to duct and hose suppliers. This behavioral shift is most visible in long-haul trucking corridors serving Alpine and Rocky Mountain routes, where sustained grade descent events dominate brake thermal loading profiles and service contract structures.
Brake Cooling Duct and Hose Market Segmentation
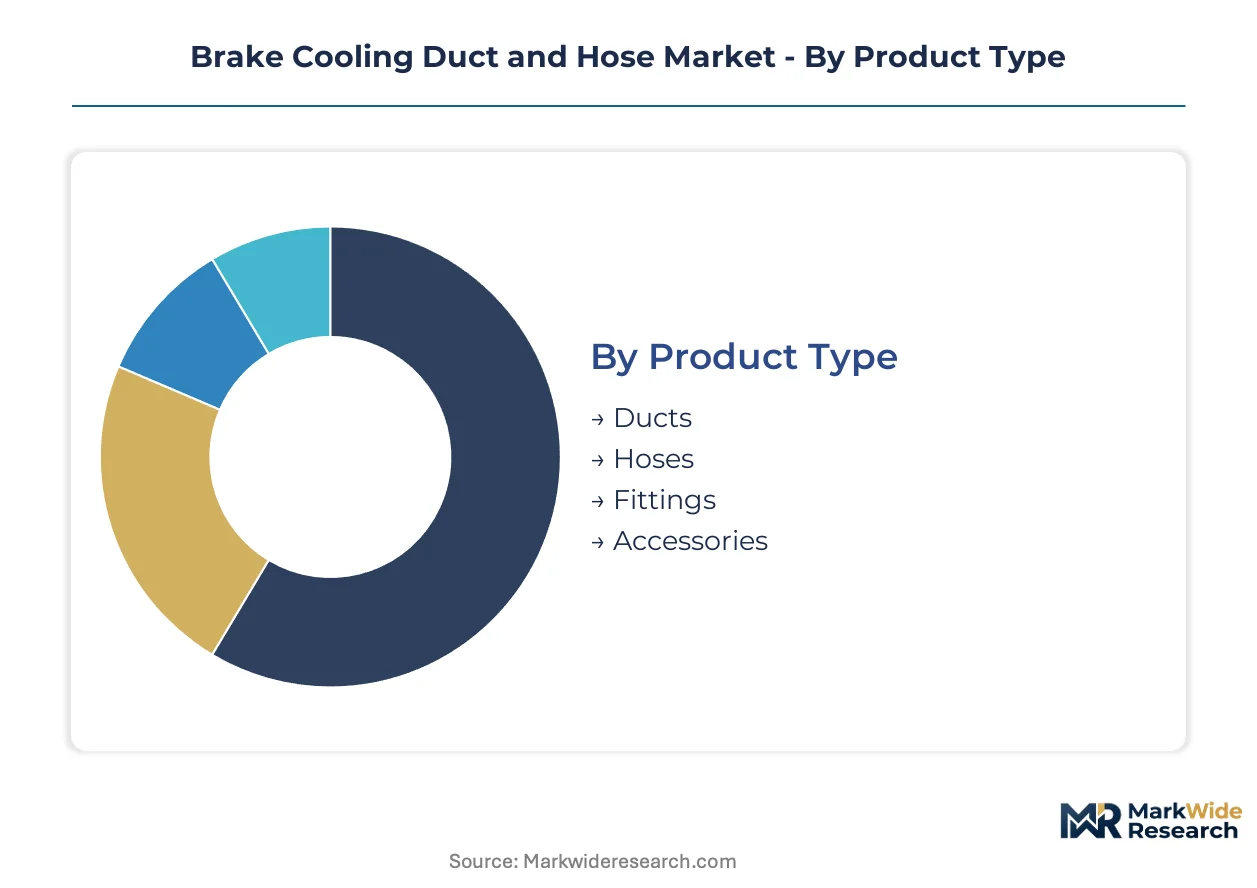
Brake cooling component procurement splits sharply between mass-market automotive platforms demanding standardized aluminum architectures and motorsport applications requiring bespoke thermal engineering. Material selection and regulatory compliance requirements vary dramatically across these divergent demand streams.
Product Type:
Volume production concentrates on stamped aluminum ducts, while premium engineering focuses on hose assemblies with validated thermal cycling performance.
- Ducts:Aluminum hydroformed channels route ambient air toward brake rotors with CFD-optimized geometries that NHTSA mandates for documented airflow coefficients. German OEMs around Stuttgart specify 6061-T6 architectures with integrated mounting flanges for platform standardization across vehicle lines.
- Hoses:Silicone and fluorocarbon rubber conduits provide flexible routing between fixed duct sections and suspension-mounted calipers, with fluorosilicone compounds now displacing HNBR for 300°C continuous exposure in wheel well packaging constraints. Motorsport teams specify braided stainless steel reinforcement for FIA-mandated redundant cooling pathways.
- Fittings:Stainless steel and anodized aluminum connectors secure assemblies under vibration and thermal expansion cycles.
- Accessories:Mounting brackets, heat shields, and airflow deflectors complete thermal management installations.
Today's leader: Ducts. Tomorrow's challenger: Hoses.
Material:
Cost tier stratification separates commodity aluminum from emerging composite architectures commanding material premiums.
- Aluminum:6061-T6 and 3003-H14 alloys dominate automotive OEM specifications for structural rigidity and thermal conductivity, though Chinese smelting concentration exposes European fabricators to tariff volatility. Primary sheet capacity clustering in specific corridors forces inventory positioning strategies at Tier-1 suppliers.
- Rubber:Silicone, fluorosilicone, and HNBR compounds form flexible hose inner liners, with REACH Annex XVII PFAS restrictions compelling full system requalification timelines extending 18-24 months for ozone resistance validation without legacy fluoroelastomer chemistry.
- Composite:Unidirectional carbon-PEEK tapes from BMW and Porsche engineering programs integrate into wheel-mounted duct sections where impact resistance and mass reduction outweigh cost premiums, achieving comparable thermal conductivity at 60% lower mass than aluminum in upper-mid vehicle segments.
- Steel:Stainless steel braid and fitting materials provide corrosion resistance and secure attachment under mechanical loading.
Aluminum captures current volume. Composites climb the fastest.
Application:
Customer type dictates engineering intensity, from fleet procurement standardization to FIA homologation compliance.
- Automotive:Passenger and commercial vehicle OEMs specify platform-standardized duct architectures that reduce per-unit tooling burden, with regenerative braking coexistence in electric vehicle platforms demanding redesigned thermal architectures. German manufacturing corridors concentrate procurement for high-performance braking systems.
- Motorsports:FIA GT3 and Formula E homologation rules mandate redundant cooling pathways and bespoke aerodynamic integration, commanding premium pricing for CFD-optimized profiles and braided hose assemblies with documented thermal dissipation rates.
- Aerospace:Aircraft braking systems require lightweight thermal management for landing gear applications.
- Industrial:Heavy machinery and off-highway equipment utilize brake cooling for sustained duty cycles.
Automotive dominates present procurement. Motorsports defines performance benchmarks.
End User:
Supply channel configuration determines margin structure and technical risk allocation.
- Original Equipment Manufacturers:Direct relationships with Tier-1 suppliers consolidate aluminum forging and silicone compounding capabilities from shared production footprints, with long-term thermal performance agreements transferring technical risk to component vendors over 150,000-kilometer service intervals.
- Aftermarket Suppliers:ECE R90 replacement part certification requires dynamometer testing protocols costing €45,000-€80,000 per SKU variant, compressing margin for low-volume specialty applications.
- Distributors:Inventory positioning strategies bridge OEM and repair channel demand fluctuations.
- Repair Shops:Service bay installation of replacement duct and hose assemblies.
OEMs anchor current revenue. Aftermarket certification costs reshape competitive entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as manufacturers relocate aluminum forging and silicone compounding capacity to jurisdictions with streamlined REACH-equivalent compliance pathways. Cost-of-compliance gaps between European and Asian regulatory regimes are accelerating facility migration decisions.
United States
NHTSA thermal performance mandates and EPA Phase 2 greenhouse gas regulations drive OEM procurement of validated brake cooling architectures. Fleet operators in Rocky Mountain corridors specify guaranteed maximum temperature thresholds over extended service intervals. Detroit-area Tier-1 suppliers consolidate aluminum hydroforming capacity to serve domestic OEM and commercial vehicle demand streams.
Germany
Automotive manufacturing corridors around Stuttgart and Munich concentrate precision thermal management procurement for high-performance braking systems. KBA enforcement of ECE R90 replacement part certification compels aftermarket suppliers to maintain costly dynamometer testing protocols. Baden-Württemberg-based fabricators anchor European motorsport specification development for FIA-homologated cooling pathways.
China
Primary 6061-T6 and 3003-H14 aluminum sheet capacity clustering exposes European and North American duct fabricators to tariff volatility and extended lead times. Domestic OEMs serving the sub-4-meter SUV segment lack indigenous duct engineering capabilities. Yangtze River Delta smelting corridors dominate aerospace-grade material supply for global automotive programs.
India
Domestic passenger vehicle thermal upgrade demand creates white space for technical partnerships transferring aluminum hydroforming and silicone extrusion know-how. BIS material standards for automotive rubber compounds are converging toward European ozone resistance specifications. Tamil Nadu and Maharashtra manufacturing clusters attract joint venture proposals from European Tier-1 suppliers seeking localized production.
Japan
METI industrial standards for automotive thermal management components influence regional procurement specifications across Asia-Pacific OEM networks. Precision rubber compounding expertise in Kanto and Kansai industrial zones supports fluorosilicone formulation development for 300°C continuous exposure applications. Japanese automotive OEMs specify platform-standardized duct architectures that reduce per-unit tooling burden across vehicle lines.
Brake Cooling Duct and Hose Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue additive manufacturing and composite material substitution for premium positioning. The vendor base stratifies between consolidated aluminum forging specialists and fragmented silicone hose compounders serving niche motorsport applications. Three archetypes dominate: integrated brake system suppliers with captive thermal management divisions; dedicated duct and hose fabricators with platform-standardization expertise; and motorsport specialists commanding premium pricing for bespoke aerodynamic integration. Competitive moves center on capacity consolidation through shared production footprints and strategic partnerships for composite material co-development.
Among European integrated suppliers, Continental AG and ZF Friedrichshafen AG exemplify the brake-system-tier archetype with broad OEM relationship networks spanning passenger and commercial vehicle platforms. Brembo occupies a distinctive position leveraging motorsport heritage to anchor premium specification development for racing applications. Gates Corporation represents the specialized hose formulation segment with elastomeric expertise addressing repeated thermal cycling requirements. These three companies collectively illustrate the competitive spectrum from mass-market platform standardization to premium bespoke engineering.
| Leading Market Players |
|---|
| Brembo |
| Valeo |
| Continental AG |
| Gates Corporation |
| ZF Friedrichshafen AG |
| Pegasus Auto Racing Supplies |
| APR Performance |
| Bernie Gillon Motorsport Ltd. |
| All Star Performance |
| Others |
Value Network & Pricing Analysis
FIA homologation certification bifurcates procurement into premium motorsport assemblies and commodity automotive OEM specifications, with this tier divergence manifesting in both margin structures and supplier network configurations. Motorsport teams absorb 40-60% distributor markups for braided stainless steel hose assemblies with documented thermal cycling validation, while mass-market OEMs negotiate direct-to-factory aluminum duct pricing anchored to Yangtze River Delta 6061-T6 sheet benchmarks.
Pricing Analysis
Distributor margin layers separate aftermarket channels from direct OEM supply, with three-tier pricing structure across premium, standard, and economy levels reflecting certification grade and volume scale differentiation. Price compression runs through commodity aluminum duct tiers as Chinese smelting concentration intensifies buyer leverage, while fluorosilicone hose compounds command stability due to REACH-driven reformulation scarcity. Fleet procurement departments exhibit lowest price sensitivity through long-term thermal performance agreements, whereas independent repair shops face acute cost pressure from ECE R90 certification overhead.
Supply Chain Analysis
Trans-Pacific freight cost volatility shapes inventory positioning strategies for European and North American fabricators sourcing from Yangtze River Delta primary smelting corridors. Aluminum sheet supply concentrates in China, with secondary dependence on German rolling mills for aerospace-grade 6061-T6 specifications; silicone rubber compounding feeds from Japanese Kanto industrial zones and German chemical corridors. Tariff exposure constitutes the dominant structural risk, with distribution running through Tier-1 supplier consolidation into shared production footprints serving dual OEM and motorsport demand streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The brake cooling duct and hose market compounds steadily as electric vehicle platform proliferation sustains thermal architecture redesign cycles across multiple vehicle generations.
For Market Incumbents: To counter carbon fiber reinforced polymer substitution in upper-mid vehicle segments, Brembo and Continental AG should deepen captive aluminum forging capacity in Baden-Württemberg while accelerating PFAS-free fluorosilicone compound qualification ahead of FIA environmental compliance deadlines. Certification investment in additive manufacturing capabilities for topology-optimized duct geometries offers defensive positioning against emerging topology-optimized competitors. For New Entrants and Emerging Players: Enter via technical partnership structures with Indian domestic OEMs serving the sub-4-meter SUV segment, where indigenous aluminum hydroforming and silicone extrusion capabilities remain underdeveloped. Joint venture proposals targeting Tamil Nadu and Maharashtra manufacturing clusters offer the most penetrable geographic entry point, with localized production circumventing tariff exposure on Chinese primary aluminum while transferring European thermal management engineering know-how. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized silicone hose compounders possessing validated 300°C continuous exposure formulations and established FIA homologation relationships. Long-term viability over the coming decade hinges on electric vehicle platform standardization cycles and regenerative braking coexistence thermal architectures; acquisition targets should demonstrate active PFAS-free elastomer development pipelines. The signal to monitor is ECHA candidate list expansion velocity affecting hose inner liner reformulation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Forging | Captive 6061-T6 capacity insulates Brembo from Yangtze River Delta tariff volatility and lead time extension. |
| PFAS-Free Elastomer Development | Fluorosilicone compounders meeting REACH Annex XVII deadlines capture FIA motorsport procurement ahead of broader automotive phase-outs. |
| Additive Manufacturing Adoption | Laser powder bed fusion of Al-Si-Mg alloys enables topology-optimized internal rib structures impossible with conventional stamping methods. |
| Indian Joint Venture Formation | Technical partnerships with Maharashtra-based OEMs transfer aluminum hydroforming expertise into sub-4-meter SUV thermal upgrade demand. |
| Long-Term Thermal Performance Agreements | Fleet procurement consolidation transfers technical risk to component vendors over extended service intervals in Alpine and Rocky Mountain corridors. |
Research Methodology
Coverage spans United States, Germany, China, India, and Japan, with primary inputs from each market combining structured interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and motorsport team technical directors alongside secondary validation. Trade data from customs authorities, NHTSA brake safety filings, ECHA REACH registrations, and vehicle production databases anchored bottom-up volume estimates against top-down thermal content-per-vehicle analysis.
Rate-of-change decomposition separated volume growth from value expansion across vehicle class, propulsion architecture, and regional production cluster segmentation. CAGRs were derived through iterative reconciliation of OEM platform rollout schedules, motorsport homologation cycles, and regulatory compliance timeline impacts; electric vehicle brake duty cycle shifts and regenerative braking coexistence thermal architectures constituted critical forecast inputs throughout the projection horizon.
Inputs from primary stakeholder interviews and regulatory filing databases were available through the study window; gaps in real-time Chinese smelting capacity utilization data introduce uncertainty bands around aluminum cost trajectory assumptions. Stakeholders should weight forecast assumptions against their own operating context and monitor ECHA substance restriction announcements for timeline revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Europe Automotive Plastics Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
GCC Automotive Lubrication Services Market
Automotive Components
Automotive Door Module Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Automotive Headlight Bulb Market
Automotive Components
Europe Automotive Bearing Market
Automotive Components
Automotive Stabilizer Bar Link Market
Automotive Components
Global Automotive Damper Control Unit Market
Automotive Components
Automotive Headliners Market
Automotive Components
Automotive Radiator Fan Market
Automotive Components
Automotive Brake System and Components Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Automotive Skid Plate Market