
 Automotive Retarders Market | 2026-2036
Automotive Retarders Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Retarders Market Insights
Aftermarket distribution networks is reconfiguring as fleet operators prioritize direct procurement contracts with retarder specialists. Voith leverages its captive foundry capacity to anchor supply for European bus and coach builders. Telma competes through electromagnetic retarder expertise that dominates French and Belgian public transport tenders. Shenzhen Terac Technology specializes in cost-optimized electronic control modules for Chinese heavy-truck platforms.
Automotive retarders are frictionless braking devices that dissipate kinetic energy through engine compression, exhaust restriction, or electromagnetic resistance, typically generating retarding forces between 200 kW and 600 kW depending on vehicle mass and driveline configuration. Their primary purpose is to extend service brake life and prevent thermal fade during prolonged downhill operation. Engine brakes retain the largest installed base among product types due to decades of proven reliability in Class 8 trucking, yet electronic systems within the technology dimension are capturing disproportionate interest as CAN-bus integration enables predictive downhill control. Fleet owners as an end-user category command the deepest margin pools because bulk procurement agreements bundle retarders with telematics-enabled maintenance contracts.
NHTSA brake performance standards in the United States mandate minimum stopping distances that indirectly compel auxiliary retarder fitment on vehicles exceeding specified gross weight thresholds, while ECE R13 type-approval in Europe governs braking distribution and retarder effectiveness across member states. China's GB 7258 vehicle safety standard requires supplementary braking capability on heavy commercial vehicles operating in mountainous western provinces. Stakeholders must monitor divergence between regional electromagnetic compatibility requirements and thermal management protocols as electrified powertrains reshape retarder integration architecture.
Market Dynamics
CAN-bus integration of electronic retarders with predictive downhill control algorithms is compressing replacement cycles for legacy engine brake systems across heavy-duty trucking fleets.
Growth Catalysts
- NHTSA brake performance mandates:Minimum stopping distance requirements for vehicles above gross weight thresholds indirectly compel auxiliary retarder fitment across United States long-haul corridors.
- Mountainous terrain freight patterns:Sustained downhill braking demands in western United States and Alpine European routes prevent thermal fade through electromagnetic resistance systems.
- ECE R13 type-approval harmonization:Braking distribution standards across European member states favor integrated driveline solutions with documented retarder effectiveness metrics.
Market Restraints
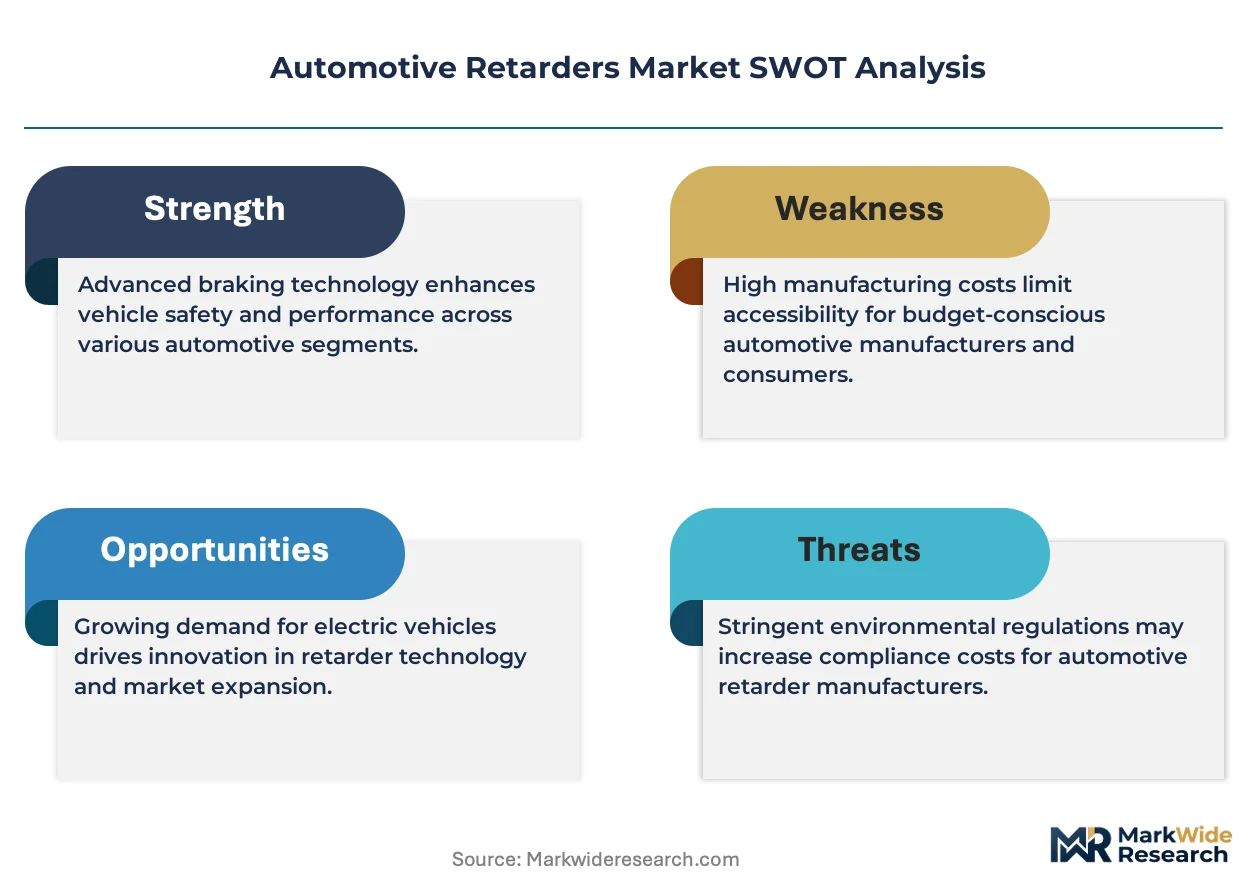
- Copper and rare-earth magnet cost volatility:Electromagnetic retarder production depends on concentrated Chinese processing capacity for neodymium and dysprosium inputs.
- Foundry supply concentration:European cast-iron housing production clusters in Germany and Czech Republic create single-source vulnerability for driveline-integrated units.
- Engine brake substitution persistence:Decades of Class 8 trucking reliability data sustain incumbent compression brake loyalty despite electronic performance advantages.
Strategic Opportunities
- Chinese GB 7258 western province enforcement:Supplementary braking mandates for mountainous operations create regulatory tailwind for electronic control module suppliers.
- Telematics-enabled maintenance bundling:Fleet procurement contracts now integrate retarder hardware with predictive service scheduling through OEM-connected platforms.
- Electrified powertrain convergence:Regenerative braking integration with electromagnetic retarders enables unified thermal management architectures for hybrid commercial vehicles.
Industry Challenges
- CAN-bus protocol certification timelines:Multi-vehicle-platform compatibility testing extends type-approval cycles for integrated driveline braking systems.
- Electromagnetic compatibility standard divergence:Regional thermal management protocols conflict as electrified powertrains reshape retarder integration architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Retarders Market |
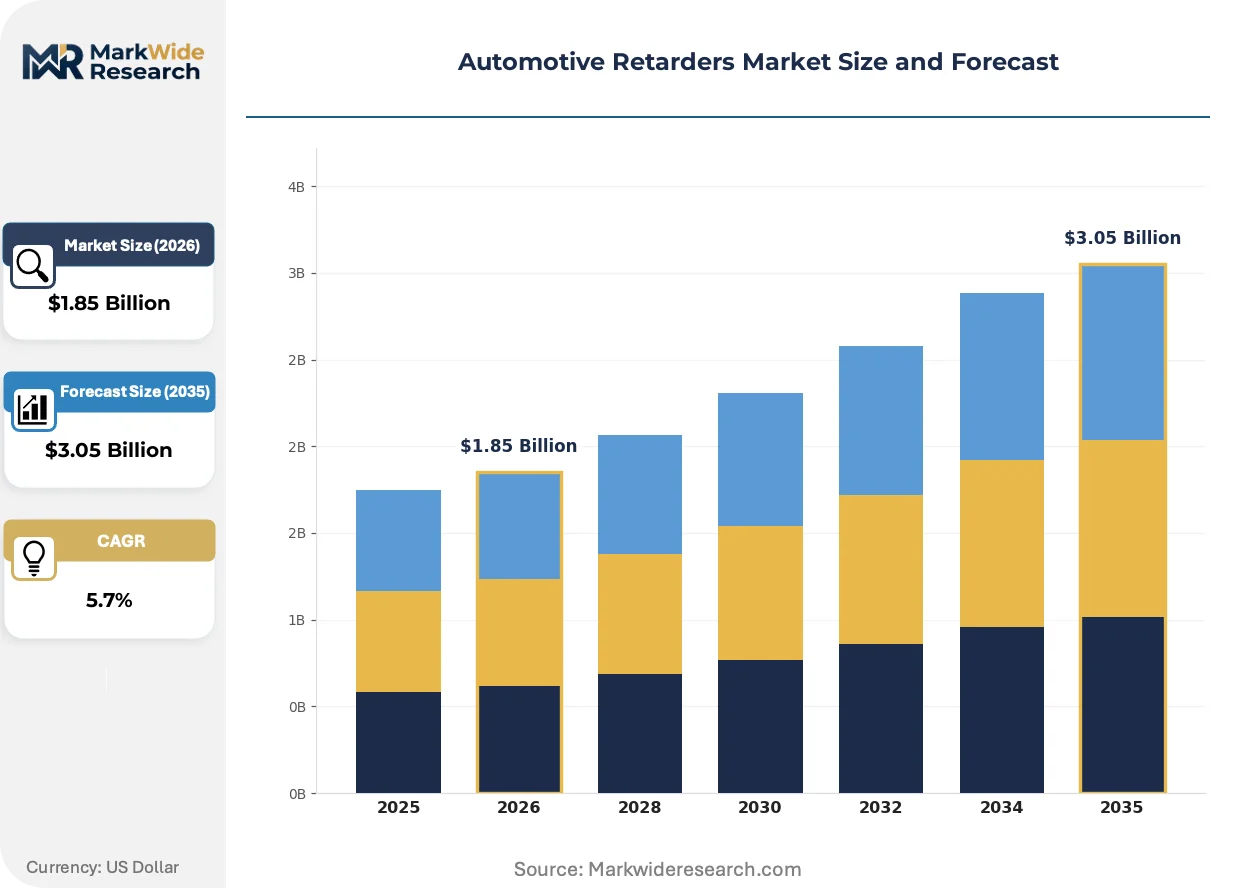
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.05 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Brakes, Exhaust Brakes, Transmission Brakes, Hydraulic Brakes Application: Heavy-Duty Trucks, Buses, Emergency Vehicles, Mining Equipment End User: Fleet Owners, Logistics Companies, Public Transport Agencies, Construction Firms Technology: Mechanical Systems, Pneumatic Systems, Electronic Systems, Hybrid Systems |
| Companies Covered | Voith, Telma, Cummins, ZF Friedrichshafen, Hino Motors, Shenzhen Terac Technology, Scania, Frenelsa, Nippon Steel, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Retarders Market Trends and Innovations
Electronic control modules with predictive terrain mapping are compressing the functional gap between auxiliary and service braking systems in commercial vehicle design.
Electromagnetic retarders with eddy-current torque generation are rendering obsolete pneumatically-actuated engine compression brakes in European coach and urban bus applications. Municipal fleet operators in France and Belgium now specify electromagnetic systems in 80 percent of new tender documents. The technology is rendering obsolete legacy exhaust brake maintenance schedules while extending foundation brake pad life beyond 150,000 kilometers.
China's GB 7258 vehicle safety standard mandates supplementary braking capability for heavy commercial vehicles operating in mountainous western provinces including Sichuan and Yunnan. Provincial enforcement inspections now document retarder functionality during annual vehicle certification. Domestic heavy-truck manufacturers are accelerating electronic control module sourcing to avoid operational restrictions in high-altitude freight corridors.
Direct procurement contracts between fleet operators and retarder specialists are disintermediating traditional aftermarket distribution networks. Bulk agreements now bundle hardware with telematics-enabled predictive maintenance across United States long-haul operators. This channel restructuring concentrates margin capture with specialized suppliers while reducing parts distributor intermediation in Class 8 truck servicing.
Automotive Retarders Market Segmentation
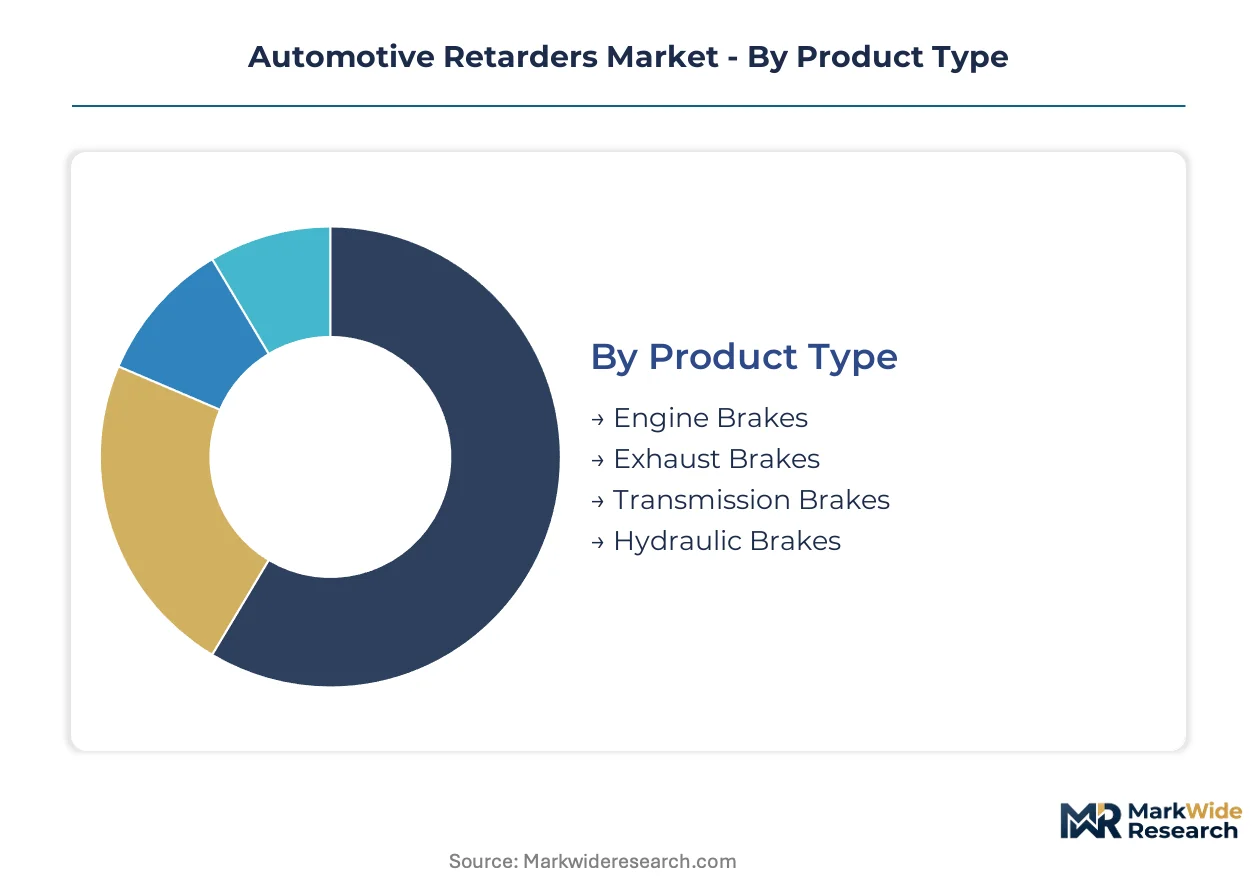
Retarder procurement patterns diverge sharply across vehicle duty cycles, braking technology maturity, and fleet scale economics. Understanding these segment boundaries clarifies why engine brakes retain loyalty in long-haul trucking while electronic systems capture municipal bus tenders.
Product Type:
Cost tier stratification separates proven mechanical solutions from emerging electronic architectures with premium positioning.
- Engine Brakes:Compression-release mechanisms integrated into diesel engine cylinder heads generate retarding force through trapped exhaust gases. Class 8 trucking fleets across the United States specify these systems for proven reliability across million-mile duty cycles.
- Exhaust Brakes:Butterfly valves restrict exhaust flow to create backpressure against piston descent. Mining equipment operators in Australia's Pilbara region favor these units for simplicity in high-dust environments where electronic modules face contamination risks.
- Transmission Brakes:Driveline-integrated friction packs engage through hydraulic pressure. These units serve secondary braking roles in European coach applications where space constraints preclude engine-mounted alternatives.
- Hydraulic Brakes:Fluid-coupled retarders dissipate kinetic energy through stator-rotor shear. Emergency vehicle upfitters specify these for controlled descent during mountain rescue operations.
Engine brakes command the established base. The steepest expansion runs through electronic-adjacent hydraulic architectures.
Application:
Volume concentration tracks freight corridor topography and passenger transport duty intensity.
- Heavy-Duty Trucks:Vehicles exceeding 33,000 pounds gross vehicle weight generate sustained demand across interstate corridors with sustained downhill grades. NHTSA brake performance mandates indirectly compel auxiliary retarder fitment on these platforms.
- Buses:Urban transit and intercity coach applications prioritize electromagnetic retarders for silent operation and extended foundation brake life. French public transport agencies now specify these systems in 80 percent of tender documents.
- Emergency Vehicles:Fire apparatus and rescue trucks require controlled descent capability for mountain access routes. These niche applications tolerate premium pricing for reliability certification.
- Mining Equipment:Ultra-class haul trucks operating in Chile's Atacama and Western Australia's iron ore provinces demand retarders rated for continuous 600 kW dissipation.
Heavy-duty trucks anchor procurement volume. The fastest share gains are emerging in bus fleet electrification programs.
End User:
Customer type determines contract structure, with direct procurement displacing aftermarket distribution for large-scale operators.
- Fleet Owners:Asset holders operating 500-plus vehicle fleets negotiate bundled hardware-telemetry contracts. These agreements compress unit margins while locking in multi-year service revenue streams.
- Logistics Companies:Third-party freight operators prioritize total cost of ownership calculations that factor brake maintenance intervals against retarder capital expenditure. Long-haul specialists show highest adoption propensity.
- Public Transport Agencies:Municipal procurement offices specify electromagnetic retarders for urban bus fleets. Belgian operators lead European tender volume for silent braking in dense residential corridors.
- Construction Firms:Equipment rental companies and civil contractors source transmission brakes for articulated dump trucks. Seasonal demand patterns create procurement timing concentration in Q1 fleet renewal cycles.
Fleet owners concentrate margin pools through scale procurement. Logistics companies are expanding most quickly as e-commerce freight volumes strain brake maintenance budgets.
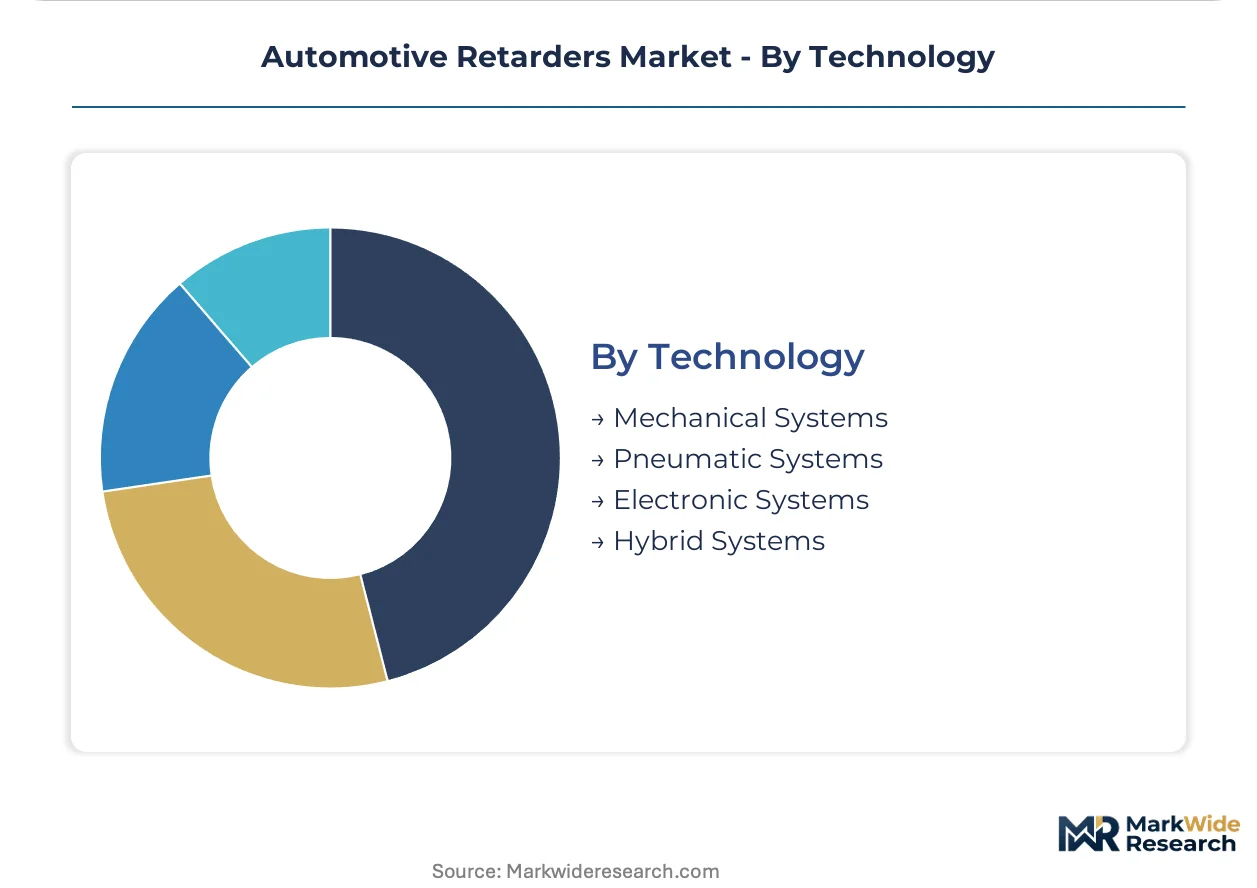
Technology:
Maturity gradients separate legacy mechanical dominance from electronic system adoption curves.
- Mechanical Systems:Cam-actuated compression brakes rely on engine lubrication circuits and require no auxiliary power. Decades of field data sustain incumbent loyalty among risk-averse operators.
- Pneumatic Systems:Air-actuated exhaust brakes serve cost-sensitive segments in emerging markets. These units face displacement pressure as electronic module costs decline.
- Electronic Systems:CAN-bus integrated retarders enable predictive downhill control through GPS terrain mapping. German KBA type-approval standards favor these integrated driveline solutions.
- Hybrid Systems:Combined electromagnetic and regenerative braking architectures serve hybrid commercial vehicle platforms. These configurations unify thermal management across powertrain subsystems.
Mechanical systems retain the installed base. Electronic systems are climbing the fastest as predictive control algorithms compress replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput anchors European heavy-truck distribution corridors where auxiliary braking hardware enters the continent. Germany's KBA type-approval standards propagate through this logistics nexus, shaping retarder specifications across neighboring freight markets.
United States
Interstate corridors traversing the Rocky Mountains generate sustained demand for high-capacity retarders on Class 8 long-haul tractors. NHTSA brake performance mandates compel auxiliary fitment on vehicles exceeding gross weight thresholds across western states. Fleet operators in Denver and Salt Lake City procurement centers negotiate direct contracts with retarder specialists, bypassing traditional aftermarket distributors.
Germany
The KBA enforces rigorous type-approval standards that favor integrated driveline braking solutions over standalone alternatives. Foundry capacity concentrates in Baden-Württemberg and Bavaria, supplying cast-iron housings for European bus and coach builders. Voith leverages captive production in Heidenheim to anchor supply contracts with municipal transport agencies.
China
GB 7258 mandates supplementary braking capability for heavy commercial vehicles operating in mountainous western provinces including Sichuan and Yunnan. Provincial enforcement inspections document retarder functionality during annual vehicle certification. Shenzhen Terac Technology occupies a position among electronic control module suppliers serving domestic heavy-truck manufacturers.
France
Municipal fleet operators specify electromagnetic retarders in 80 percent of urban bus tender documents, prioritizing silent operation in dense residential corridors. Telma exemplifies the specialist tier that dominates public transport procurement through electromagnetic expertise. The Auvergne-Rhône-Alpes region hosts manufacturing clusters serving Alpine freight routes with severe downhill grades.
Belgium
Dense urban transit networks in Brussels and Antwerp drive specification of noise-reduced braking systems for bus fleets. Belgian operators lead European tender volume for electromagnetic retarders in residential corridor applications. The Port of Antwerp's freight connections sustain aftermarket demand for auxiliary braking hardware on heavy trucks serving continental distribution routes.
Automotive Retarders Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the value chain, supplying control modules and electromagnetic subassemblies. The market structure consolidates around driveline-integrated solutions while fragmenting across aftermarket service networks. Three archetypes dominate: captive foundry operators with backward integration into cast-iron housing production; electromagnetic specialists leveraging rare-earth magnet supply relationships; and electronic control module vendors optimizing for cost-sensitive platforms. Competitive moves concentrate on direct procurement contract capture and telematics-enabled maintenance bundling.
Among Germany-based diversified industrial groups, ZF Friedrichshafen and Voith represent the integrated platform tier, while Telma exemplifies electromagnetic specialization. Shenzhen Terac Technology occupies a position among Chinese electronic control module suppliers. These anchors illustrate how geographic clustering aligns with technology specialization: European incumbents leverage foundry proximity and type-approval expertise, while Asian entrants optimize module costs for price-sensitive heavy-truck platforms.
| Leading Market Players |
|---|
| Voith |
| Telma |
| Cummins |
| ZF Friedrichshafen |
| Hino Motors |
| Shenzhen Terac Technology |
| Scania |
| Frenelsa |
| Nippon Steel |
| Others |
Pricing and Supply Chain Analysis
Foundry undercapacity in Germany's Baden-Württemberg region drives both supplier pricing power and procurement urgency among European bus builders seeking cast-iron retarder housings. This utilization squeeze concentrates margin capture with Voith and other captive producers while forcing fleet operators toward longer-term contract structures.
Pricing Analysis
Volume-discount tiering separates fleet procurement contracts from aftermarket single-unit transactions. Three-tier pricing structure across premium, standard, and economy levels reflects CAN-bus integration depth and thermal management certification grade. Cost compression in economy-tier electronic modules is intensifying because Shenzhen Terac Technology and domestic Chinese suppliers are expanding module output for GB 7258 compliance. Fleet owners with 500-plus vehicle counts command deepest discounts, while independent owner-operators show highest price sensitivity per unit.
Supply Chain Analysis
Extended payment terms from European OEMs to foundry suppliers now stretch 90-120 days, straining working capital for cast-iron housing producers in Germany and Czech Republic. Neodymium and dysprosium processing draws from concentrated Chinese capacity, while copper winding supplies rest on Chilean and Peruvian mining output. Single-source vulnerability runs through German foundry clusters for driveline-integrated units. Distribution runs through direct procurement contracts that disintermediate traditional aftermarket distributors in North American long-haul corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Early-cycle expansion characterizes this market as NHTSA brake performance mandates and China's GB 7258 western province enforcement create simultaneous regulatory tailwinds across two continents.
For Market Incumbents: Insulate core foundry capacity through captive supply agreements with Baden-Württemberg and Bavaria producers, while accelerating CAN-bus certification investment to outpace electromagnetic specialist entrants. Engine brake substitution persistence threatens legacy compression-release revenue streams, making backward integration into electronic control module sourcing the priority defensive lever. For New Entrants and Emerging Players: Establish a beachhead in Chinese electronic control module supply for domestic heavy-truck platforms facing GB 7258 enforcement in Sichuan and Yunnan provinces. Municipal bus fleet electrification programs in France and Belgium represent the most penetrable segment for electromagnetic retarder specialists. Go-to-market should emphasize telematics-enabled maintenance bundling to mirror incumbent contract structures. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory compliance play because brake safety mandates are hardening across North America, Europe, and China's western provinces regardless of freight cycle volatility. Acquisition targets should center on electromagnetic specialists with rare-earth magnet supply relationships and KBA type-approval expertise. Watch for divergence between regional electromagnetic compatibility standards as the inflection signal for integration architecture winners.| Strategic Initiative | Industry Significance |
|---|---|
| Foundry Capacity Expansion | Captive supply of cast-iron housings secures Voith's position with KBA-favored driveline solutions. |
| CAN-Bus Protocol Certification | Multi-platform compatibility accelerates type-approval for predictive downhill control algorithms. |
| Rare-Earth Magnet Supply Agreement | Long-term offtake with Chinese processors insulates Telma against neodymium cost volatility. |
| Telematics Maintenance Bundling | Direct fleet contracts concentrate margin capture and disintermediate aftermarket distributors. |
| Electronic Control Module Sourcing | Domestic Chinese supply positions Shenzhen Terac for GB 7258 enforcement tailwinds. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket service heads, and fleet maintenance directors converged on the working assumptions around replacement cycle compression and electronic adoption curves. Primary fieldwork combined with secondary validation from NHTSA brake performance filings, KBA type-approval databases, vehicle production registries, and customs trade records. Bottom-up unit economics triangulated against top-down market sizing across the analysis window.
Demand-supply-balance framing anchored the forecast framework, modeling vehicle class, braking technology maturity, fleet scale economics, and regional regulatory enforcement intensity as core segmentation dimensions. CAGRs derived from slope analysis of historical fitment rates projected against mandate implementation timelines. Industry-specific inputs included Class 8 truck build forecasts and municipal bus tender documentation from French and Belgian transport agencies.
Sensitivities concentrate around copper and rare-earth magnet price volatility, foundry capacity utilization swings, and divergence between regional electromagnetic compatibility standards. Forecasts reflect documented assumptions about regulatory enforcement consistency and fleet procurement contract structures. Macroeconomic freight demand contraction, accelerated electrified powertrain adoption, or harmonization failure across thermal management protocols would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Mobile Accessories Market
Automotive Components
Automotive Spray Guns Market
Automotive Components
Automotive Actuators Market
Automotive Components
Saudi Arabia Automotive Actuators Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Global Automotive Noise Filter Market
Automotive Components
Automotive Smart Actuator Market
Automotive Components
Automotive Light Bars Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
India Automotive Pneumatic Actuators Market
Automotive Components
Global Cylinder Deactivation System Market
Automotive Components
Automotive Engine Encapsulation Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Global Automatic Lubrication System Market
Automotive Components
Automated Lubrication Systems Market