
 Automotive Fender Market | 2026-2036
Automotive Fender Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Fender Market Analysis
High-strength steel-to-aluminum substitution in body-in-white architectures is narrowing the cost gap between traditional stamped fenders and lightweight alternatives. Plastic Omnium leverages its thermoplastic composite expertise to supply integrated fender modules for modular EV platforms. Magna International anchors North American production through captive stamping and aluminum forming operations near Detroit and Ontario assembly plants. Thyssenkrupp competes via its tailored blanking and hot-forming capabilities that sustain OEM relationships across German and Chinese passenger car programs.
An automotive fender is a body panel mounted over the wheel arch, typically stamped from cold-rolled steel (0.6–0.8 mm thickness), aluminum sheet (5000/6000 series), or injection-molded thermoplastic composites, serving to shield the vehicle underbody from road debris and define exterior aerodynamic profile. Steel retains dominant share in mass-market sedans and trucks where cost-per-kilogram and repair network familiarity preserve its position, while aluminum and composite formulations are capturing structural margin pools in premium SUVs and battery-electric architectures where range efficiency demands mass reduction. Front fender assemblies command higher value content due to integration with headlamp housings, crash structures, and sensor mounting points for advanced driver-assistance systems.
EPA Corporate Average Fuel Economy standards and NHTSA crashworthiness protocols in the United States, alongside ECHA REACH substance restrictions and EU End-of-Life Vehicle directives in Europe, collectively mandate lighter yet structurally validated exterior panels with documented recyclability. China's MIIT new energy vehicle credit system and GB standards for passenger car energy consumption further bias fender material selection toward aluminum and fiber-reinforced polymers. Stakeholders must monitor evolving OEM platform consolidation strategies and regional scrap-recycling infrastructure readiness as determinants of long-term material cost trajectories and supplier qualification barriers.
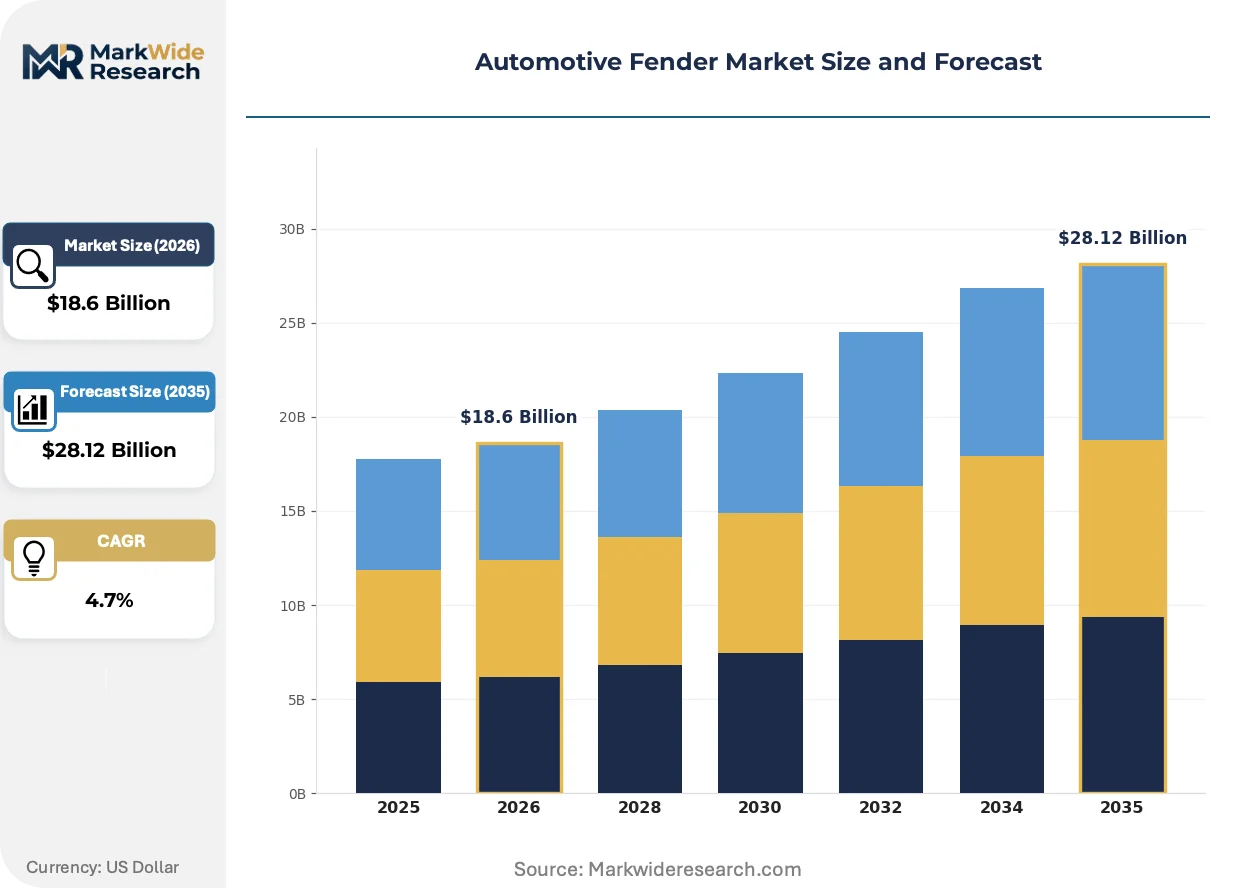
Market Dynamics
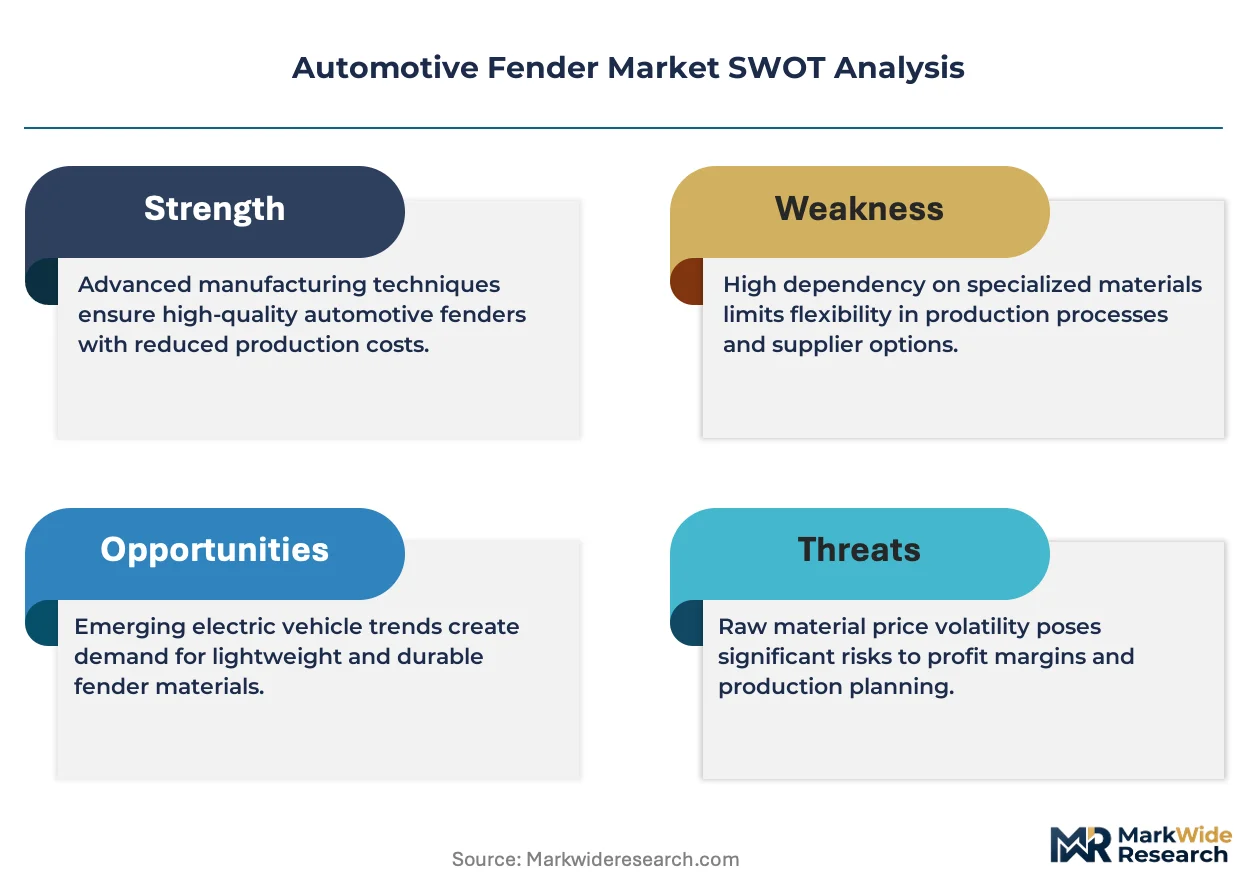
The automotive fender market is experiencing structural compression as OEM platform consolidation forces suppliers to align with modular EV architectures that demand multi-material competence across aluminum, steel, and thermoplastic composites.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:These mandates force mass reduction in body-in-white structures, accelerating aluminum fender adoption in North American passenger car programs.
- Battery-electric vehicle platforms:Range efficiency requirements in premium SUVs and sedans are creating dedicated demand for lightweight fender modules that preserve aerodynamic integrity.
- China MIIT new energy vehicle credit system:Domestic OEMs are scaling proprietary stamping capacity to capture vertical margin pools in aluminum forming and assembly.
Market Restraints
- Aluminum sheet price volatility:LME aluminum fluctuations compress supplier margins on fixed-price OEM contracts, particularly for 5000/6000 series alloys used in fender stamping.
- German and Chinese supplier concentration:Tailored blanking and hot-forming capabilities cluster around Thyssenkrupp and captive Chinese state-owned enterprises, limiting second-source options.
- Steel recycling infrastructure maturity:Closed-loop aluminum and composite recycling networks remain underdeveloped versus established steel scrap recovery, raising end-of-life compliance costs under EU directives.
Strategic Opportunities
- Integrated fender modules:Thermoplastic composite expertise enables suppliers to capture sensor-mounting and headlamp-housing integration value in ADAS-equipped vehicles.
- European REACH compliance tailwinds:Material recyclability documentation requirements redirect qualification criteria toward suppliers with documented closed-loop aluminum formulations.
- North American nearshoring:Captive stamping and aluminum forming operations near Detroit and Ontario assembly plants reduce logistics exposure and tariff risk.
Industry Challenges
- Multi-material joining competence:OEMs demand suppliers proficient in aluminum-to-steel welding, adhesive bonding, and composite-metal hybrid assembly—skills concentrated among German and Japanese tooling specialists.
- Crash-structure validation timelines:NHTSA protocols and Euro NCAP testing extend product development cycles for fenders integrated with pedestrian protection and sensor calibration requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Fender Market |
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $28.12 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Front Fender, Rear Fender, Custom Fender, Wide Fender Material: Steel, Aluminum, Plastic, Composite Vehicle Type: SUV, Sedan, Hatchback, Truck End User: Manufacturers, Aftermarket Providers, Repairs Shops, DIY Enthusiasts |
| Companies Covered | Plastic Omnium, Magna International, Thyssenkrupp, Sungwoo Hitech, Futaba Industrial, Faurecia, Tata AutoComp Systems, Hyundai Mobis, Benteler Deutschland, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Fender Market Emerging Trajectories
Material substitution and regulatory compliance are compressing traditional supply relationships while creating openings for suppliers with cross-material process expertise and documented sustainability credentials.
Hot-forming of ultra-high-strength aluminum alloys is collapsing the performance gap between stamped steel and lightweight alternatives in structural fender applications. Premium EV manufacturers are adopting these grades for crash-critical front fender assemblies. The technology is collapsing legacy tiering between steel-dominant mass-market suppliers and aluminum-focused premium specialists.
ECHA REACH substance restrictions and the EU End-of-Life Vehicle directive are mandating documented recyclability for exterior panels. Suppliers must now maintain material passports and closed-loop recovery agreements. European OEMs are qualifying only those stamping operations with certified aluminum scrap return programs.
Buyer concentration among consolidated EV platform architects is compressing supplier negotiation leverage. Volkswagen Group, Tesla, and BYD are unbundling fender procurement from full body-in-white contracts, creating direct relationships with specialized stampers. This pattern is most visible in China, where domestic OEMs are absorbing assembly capacity previously held by global Tier 1 integrators.
Automotive Fender Market Segmentation
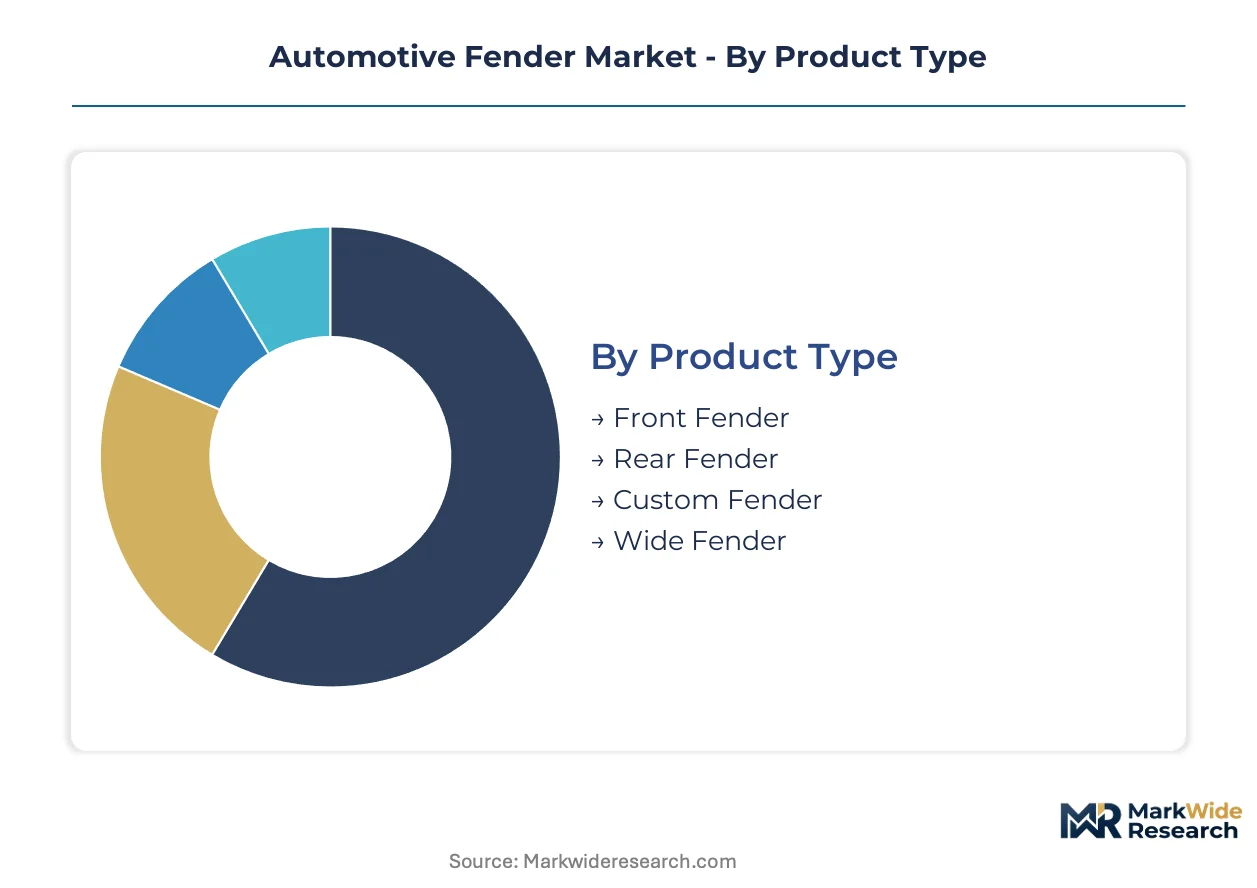
Automotive fender procurement patterns diverge sharply across material grades and vehicle architectures. OEM platform consolidation is compressing supplier margins in some segments while opening premium value pools in others.
Product Type:
Application geometry determines integration complexity and sensor-mounting value capture across fender positions.
- Front Fender:These assemblies incorporate headlamp housings, crash structures, and ADAS sensor mounting points. Demand concentrates in premium SUVs and battery-electric sedans where pedestrian protection protocols mandate reinforced aluminum forming.
- Rear Fender:Stamped panels with lower structural loading but higher styling differentiation requirements. OEMs in China are scaling proprietary capacity for rear quarter panels to reduce import dependency.
- Custom Fender:Aftermarket styling modifications for performance vehicles and restoration projects.
- Wide Fender:Extended profiles for off-road trucks and modified SUVs requiring specialized tooling.
Front fender holds installed capacity. Rear fender is rotating up the share rankings.
Material:
Cost tier and mass-reduction targets drive material selection divergence between mass-market and premium vehicle programs.
- Steel:Cold-rolled grades (0.6–0.8 mm thickness) dominate mass-market sedans and trucks where repair network familiarity and scrap recovery infrastructure preserve economics. EPA CAFE standards are narrowing but not eliminating this position.
- Aluminum:5000/6000 series sheet and hot-formed ultra-high-strength grades capture structural margin pools in premium EV architectures. European REACH compliance is redirecting qualification toward suppliers with closed-loop scrap return programs.
- Plastic:Injection-molded thermoplastics for non-structural wheel arch liners and lower-cost vehicle programs.
- Composite:Fiber-reinforced polymers enabling integrated module designs with sensor housing consolidation.
Steel retains volume leadership. Aluminum is climbing the fastest on value-per-vehicle metrics.
Vehicle Type:
Platform architecture and aerodynamic requirements shape fender specification intensity across body styles.
- SUV:Higher fender surface area and structural loading drive aluminum adoption for mass reduction. Chinese domestic OEMs are absorbing stamping capacity for SUV programs previously held by global Tier 1 suppliers.
- Sedan:Aerodynamic optimization and pedestrian protection standards favor multi-material front fender designs. German and Japanese tooling specialists concentrate joining competence for these applications.
- Hatchback:Compact dimensions limit material substitution economics; steel retains dominant share.
- Truck:Durability requirements and established repair networks preserve steel dominance in commercial and heavy-duty segments.
SUV commands specification premiums. Sedan is expanding most quickly in aluminum content per vehicle.
End User:
Customer type determines channel structure, certification requirements, and margin capture mechanisms.
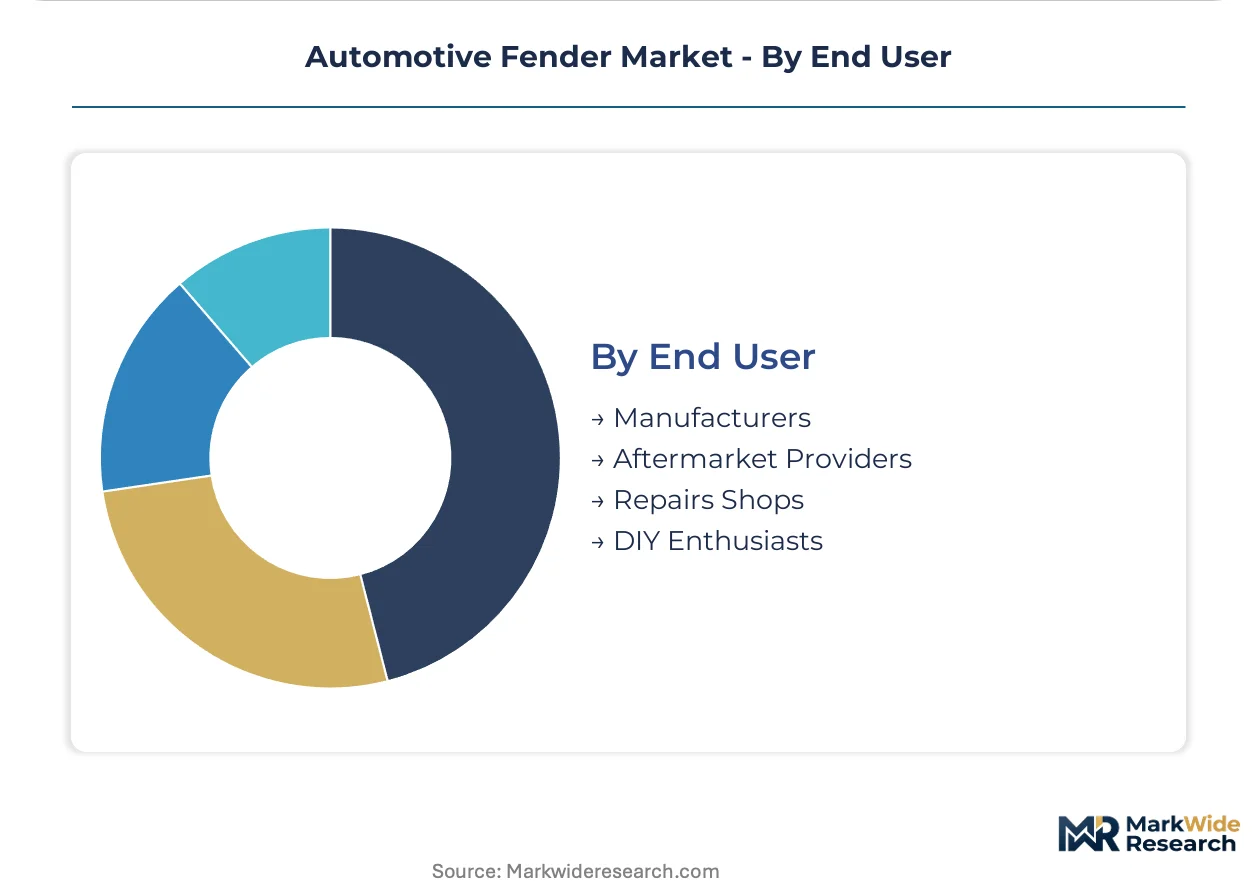
- Manufacturers:OEM direct procurement with platform-integrated specifications and multi-year supply agreements. Qualification barriers center on crash-structure validation timelines under NHTSA and Euro NCAP protocols.
- Aftermarket Providers:Independent distributors serving collision repair and vehicle modification demand. Price volatility in aluminum sheet compresses inventory holding strategies.
- Repair Shops:Insurance-driven replacement demand with network certification requirements.
- DIY Enthusiasts:Online retail channels for restoration and customization projects with minimal regulatory oversight.
Manufacturers hold installed capacity. Aftermarket providers are gaining share fastest on aluminum price normalization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Platform architects in China, Germany, and the United States command the majority of fender procurement decisions, with each market imposing distinct material and compliance requirements that reshape supplier qualification criteria.
China
Domestic EV manufacturers BYD and NIO are absorbing aluminum stamping capacity previously held by global Tier 1 integrators. MIIT new energy vehicle credit thresholds force material substitution toward lightweight alloys. The Yangtze River Delta cluster around Shanghai concentrates proprietary forming operations for premium SUV programs.
Germany
Premium OEM platform consolidation at Volkswagen Group and BMW is unbundling fender procurement from full body-in-white contracts. ECHA REACH substance restrictions mandate documented recyclability for exterior panels. The Ruhr industrial corridor hosts tailored blanking operations serving both domestic and export passenger car programs.
United States
EPA Corporate Average Fuel Economy standards are narrowing the cost gap between steel and aluminum fenders in Detroit's passenger car programs. NHTSA crashworthiness protocols extend validation timelines for pedestrian protection integration. Magna International anchors captive stamping operations near Ontario assembly plants to reduce cross-border logistics exposure.
Japan
Hybrid and battery-electric architectures from Toyota and Honda are creating dedicated demand for multi-material joining competence. METI carbon neutrality roadmaps bias supplier selection toward documented closed-loop aluminum recovery. The Nagoya industrial zone concentrates hot-forming specialists serving both domestic OEMs and Southeast Asian export platforms.
South Korea
Hyundai Motor Group's EV platform scaling is redirecting procurement toward integrated fender modules with ADAS sensor mounting points. KBA-equivalent domestic certification requirements mirror Euro NCAP pedestrian protection standards. The Busan-Ulsan manufacturing belt hosts composite forming operations for aerodynamic-optimized exterior panels.
Automotive Fender Market Vendor Landscape
Channel-controlling players compete with product-specialist players across three distinct tiers. Tier 1 integrators with captive stamping and aluminum forming operations anchor OEM relationships through multi-year platform agreements. Mid-scale specialists with thermoplastic composite expertise capture value in sensor-integrated module designs. Regional fabricators with tailored blanking capabilities serve as second-source options for volume programs. Dominant competitive moves include strategic partnerships for multi-material joining competence and geographic expansion near consolidated EV assembly clusters.
Within the channel-controlling tier, Plastic Omnium and Magna International exemplify suppliers with cross-material process portfolios spanning steel stamping, aluminum forming, and thermoplastic composite injection molding. Thyssenkrupp occupies a position among European fabricators with hot-forming and tailored blanking capabilities that sustain relationships across German and Chinese OEM programs. These three entities represent distinct strategic archetypes: the composite-integrated module supplier, the vertically integrated North American stamper, and the European precision forming specialist.
| Leading Market Players |
|---|
| Plastic Omnium |
| Magna International |
| Thyssenkrupp |
| Sungwoo Hitech |
| Futaba Industrial |
| Faurecia |
| Tata AutoComp Systems |
| Hyundai Mobis |
| Benteler Deutschland |
| Others |
Supply Flow & Price Mechanics
Overcapacity in European aluminum stamping operations is compressing supplier margins while simultaneously accelerating fixed-price contract renegotiations with German OEMs. This utilization gap drives tier-2 fabricators toward spot-market aluminum sourcing and away from long-term offtake commitments, fragmenting pricing discipline across the supplier base.
Pricing Analysis
Cost-plus contracts with LME aluminum indexation dominate procurement between OEMs and stampers, insulating buyers from alloy price spikes while squeezing supplier margins during volatility. Price differentiation hinges on crash-structure certification tier and geographic proximity to assembly plants, with Detroit-adjacent suppliers commanding premiums over distant competitors. Cost compression in mass-market steel fenders is intensifying because Chinese state-owned enterprises are absorbing legacy capacity previously held by global Tier 1s. Aftermarket providers exhibit highest price sensitivity due to inventory holding exposure, while premium EV manufacturers prioritize qualification speed over unit cost.
Supply Chain Analysis
Upstream feedstock flows from bauxite refining in Guinea, Australia, and China through smelting operations concentrated in the Yangtze River Delta and Gulf Coast corridors. Cold-rolled steel coil draws from integrated mills in Japan, South Korea, and the US Midwest, while thermoplastic resin supplies rest on petrochemical complexes along the US Gulf Coast and Rotterdam Antwerp. Single-source vulnerability concentrates in tailored blanking tooling, where German and Japanese specialists control hot-forming die production. Distribution runs through captive OEM logistics networks for direct procurement, with aftermarket channels fragmenting across independent distributors and online retail platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Collision repair and certified recycling services are expanding faster than hardware sales as aluminum fender penetration drives demand for specialized tooling and closed-loop scrap recovery programs.
For Market Incumbents: Build switching-cost moats through captive closed-loop aluminum recovery agreements that lock OEMs into multi-year scrap return programs. Secure hot-forming die capacity expansion in the Yangtze River Delta to defend against Chinese state-owned enterprise absorption of global Tier 1 share. Threat substitution from thermoplastic composite modules demands accelerated R&D investment in aluminum-to-composite hybrid joining competence. For New Entrants and Emerging Players: Build out aftermarket certification networks for aluminum fender repair, the most penetrable segment as insurance-driven collision demand outpaces OEM production growth. Target South Korean EV platform suppliers with modular fender module designs integrating ADAS sensor housings. Go-to-market leverage rests on METI-aligned sustainability documentation that satisfies Hyundai Motor Group procurement criteria. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among stampers with documented REACH compliance and closed-loop material passports, as European OEMs mandate multi-year service agreements for recyclability documentation. Long-term viability favors suppliers with cross-material process portfolios spanning steel, aluminum, and thermoplastic composites. Watch for MIIT credit threshold adjustments as the inflection signal for Chinese domestic absorption acceleration versus global supplier retention.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Material Joining Competence Acquisition | Captures sensor-integrated module contracts from Volkswagen Group and Tesla platform architects. |
| Closed-Loop Aluminum Recovery Certification | Qualifies suppliers under ECHA REACH mandates for European OEM procurement eligibility. |
| Geographic Manufacturing Footprint Expansion | Reduces logistics exposure near Detroit and Ontario assembly plants under EPA CAFE compliance pressure. |
| Hot-Forming Capacity Buildout | Collapses performance gap between stamped steel and ultra-high-strength aluminum in crash-critical applications. |
| Aftermarket Repair Network Certification | Captures insurance-driven replacement demand as aluminum fender penetration raises specialized tooling requirements. |
Methodological Framework
The analysis maps aluminum forming, steel stamping, thermoplastic composite injection, and aftermarket repair sub-sectors, each validated through OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations managers, and collision repair network administrators. Primary interview intelligence triangulates against vehicle production databases, IHS Markit registration data, SEC supplier filings, and ECHA substance restriction documentation. Bottom-up segment sizing reconciles with top-down market value estimates across material-grade and vehicle-architecture dimensions.
Assumptions held fixed include current EPA CAFE trajectory, ECHA REACH substance restriction scope, and MIIT credit system thresholds, while aluminum price volatility and OEM platform consolidation pace were varied across sensitivity scenarios. Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, material grade tier, and regional production cluster. CAGRs derive from installed capacity utilization trends and substitution elasticity estimates between steel and aluminum formulations, with battery-electric platform scaling and pedestrian protection protocol stringency as key forecast inputs.
Sensitivities concentrate around LME aluminum price corridor shifts, Chinese state-owned enterprise capacity absorption rates, and Euro NCAP pedestrian protection timeline accelerations. Forecasts embed these structural assumptions without claiming predictive certainty. Cross-checking against IHS Markit vehicle production forecasts and supplier order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Asia-Pacific Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Connecting Rod Bearing Market
Automotive Components
Automotive Metal Casting Market
Automotive Components
Brake Cooling Duct and Hose Market
Automotive Components
Automotive Brake Tube Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
Global Automotive Cigarette Lighters Market
Automotive Components
Automotive Glass Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Asia-Pacific Automotive Plastics Market
Automotive Components
Asia Pacific Automotive AHSS Market
Automotive Components
Global Automotive Acoustic Materials Market
Automotive Components
Automotive Spray Guns Market
Automotive Components
Automotive Exhaust Silencer Market
Automotive Components
MEMS Automobile Sensors Market