
 Automotive Carbon Fiber Composites Parts Market | 2026-2036
Automotive Carbon Fiber Composites Parts Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Carbon Fiber Composites Parts Market Outlook
Premium vehicle architectures and mass-market platforms is rebalancing as high-pressure resin transfer molding costs drop below thermoset pre-preg thresholds for series production above fifty thousand units annually. Toray Industries sustains dominant feedstock positions across PAN precursor supply chains into both Japanese and European tier-1 converters. SGL Carbon specializes in automotive-specific carbon fiber grades through its joint development pipelines with BMW, anchoring its position in structural battery housing applications.
Automotive carbon fiber composites parts are fiber-reinforced polymer structures typically comprising 60-70% carbon fiber by weight in a thermoset epoxy or thermoplastic matrix, manufactured through pre-preg layup, resin transfer molding, or compression molding to achieve strength-to-weight ratios exceeding aluminum by factor of four. These components serve primarily to reduce vehicle curb weight for emission compliance and electric vehicle range extension. Body panels and chassis segments lead current volume absorption due to mature design libraries and crash-test validation databases accumulated over two decades of motorsport transfer. Interior components and wheels represent faster-growing margin pools where aesthetic differentiation commands pricing premiums from luxury OEMs.
The EPA, EU Green Deal framework, and China's MIIT dual carbon goals collectively mandate fleet-weight reductions that make carbon fiber substitution economically viable against penalty structures for non-compliance. NHTSA crashworthiness protocols and ECE R94/R95 standards shape laminate architecture decisions, particularly in frontal crash management systems where energy absorption must match metallic benchmarks. Stakeholders must monitor thermoplastic recycling infrastructure maturation and second-generation precursor cost curves to time capacity commitments ahead of platform lock-ins by major OEMs.
Market Dynamics
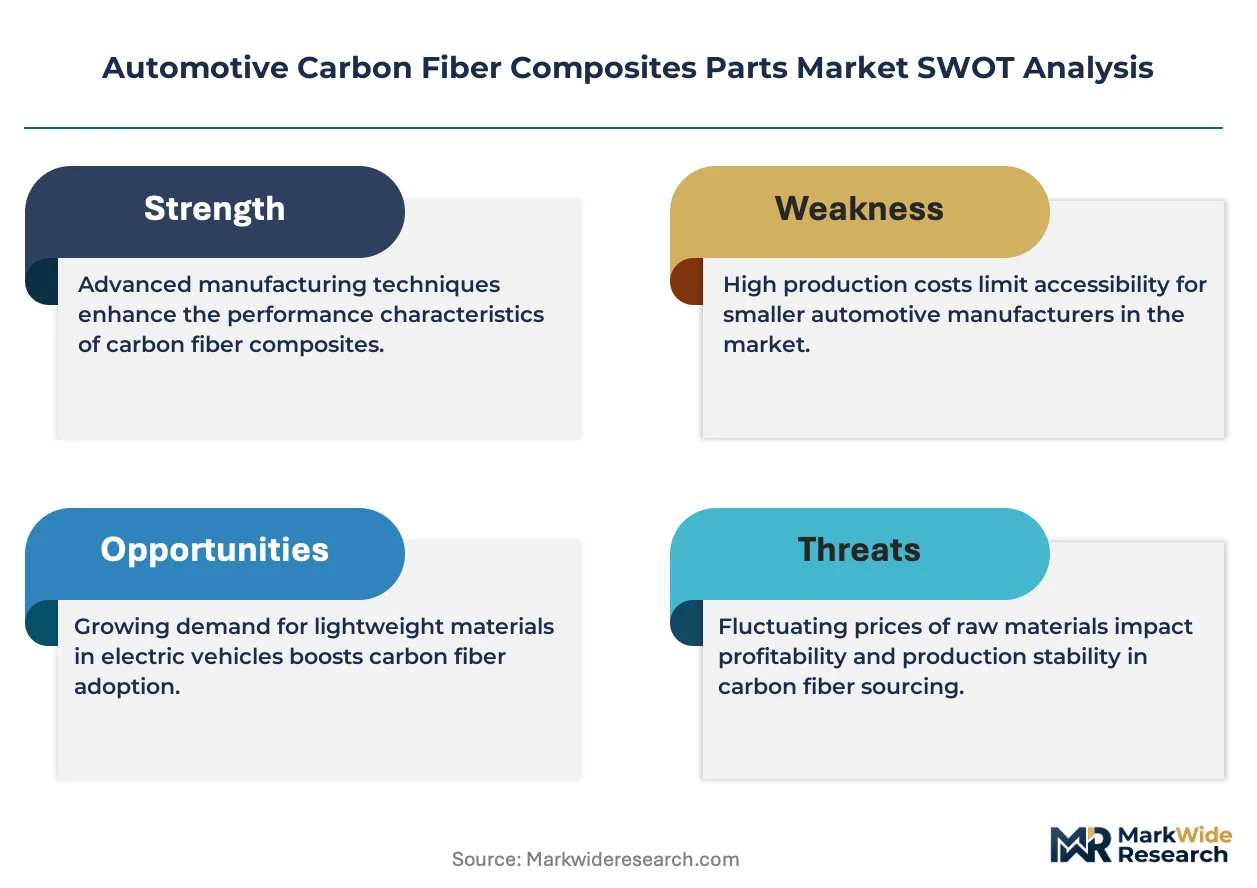
High-pressure resin transfer molding cost curves are crossing thermoset pre-preg thresholds, unlocking series production economics for carbon fiber structural components above fifty thousand units annually and compressing the traditional premium-mass market boundary.
Growth Catalysts
- EU Green Deal fleet emission targets:Stringent CO2 reduction mandates force automakers to substitute steel and aluminum with lighter composite architectures to avoid penalty structures.
- Electric vehicle platform expansion:Battery enclosure and range optimization requirements from BMW and Porsche accelerate adoption of carbon fiber hoods, roof panels, and structural housings.
- German premium automotive cluster concentration:Dedicated composites engineering centers in Stuttgart and Munich anchor R&D spillover into scalable manufacturing processes.
Market Restraints
- PAN precursor supply concentration:Feedstock dependency on Toray Industries and limited alternative precursor suppliers creates input cost volatility and allocation risk.
- Thermoset recycling infrastructure immaturity:Landfill disposal restrictions under REACH and lack of industrial-scale pyrolysis capacity constrain end-of-life economics for epoxy-matrix components.
- Crash-test validation database gaps:NHTSA frontal impact protocols and ECE R94/R95 energy absorption benchmarks require expensive laminate architecture redevelopment for each new platform.
Strategic Opportunities
- Thermoplastic matrix conversion:Polyamide and PEEK-based recyclable composites enable closed-loop manufacturing and align with EU circular economy action plan incentives.
- Second-generation precursor cost curves:Lignin-based and textile-grade PAN alternatives from SGL Carbon joint development pipelines promise 30-40% feedstock cost reduction.
- Interior component and wheel margin pools:Aesthetic differentiation commands pricing premiums from luxury OEMs where design flexibility outweighs structural load requirements.
Industry Challenges
- Composite design engineer scarcity:Laminate simulation, draping simulation, and crash-appropriate failure modeling expertise concentrates in motorsport-derived talent pools.
- Multi-material joining certification timelines:Adhesive bonding, riveting, and hybrid connection validation for carbon fiber-to-aluminum interfaces extends platform development cycles.
- Quality assurance protocol standardization:Automated fiber placement inspection, void detection, and porosity thresholds lack harmonized ISO benchmarks across tier-1 suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Carbon Fiber Composites Parts Market |
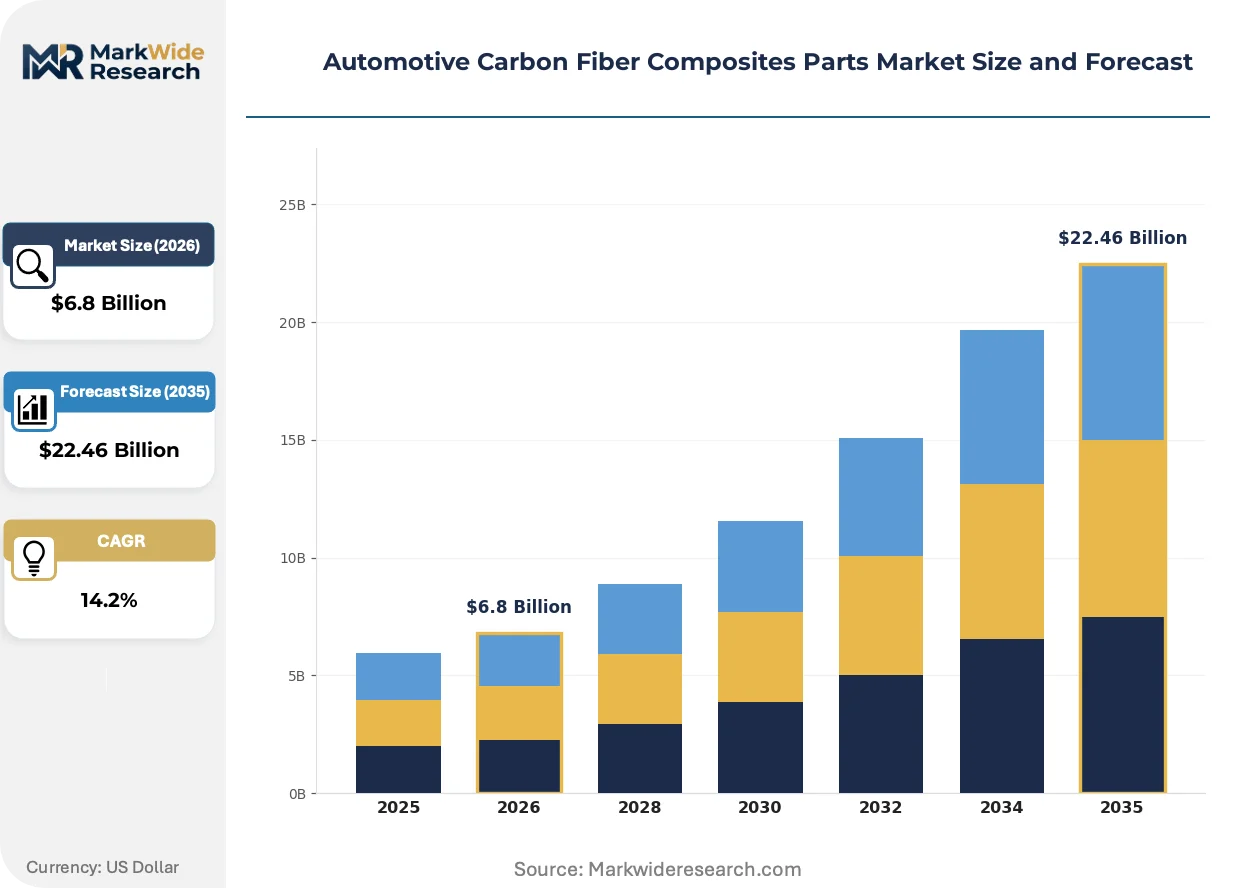
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Body Panels, Interior Components, Chassis, Wheels End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Application: Lightweighting, Structural Reinforcement, Aesthetic Enhancement, Crash Management Manufacturing Stage: Pre-Preg, Resin Transfer Molding, Compression Molding, Thermoplastics |
| Companies Covered | Teijin Limited, Owens Corning, Toray Industries Inc., BASF SE, Solvay, Hexcel Corporation, Cytec Industries, Mitsubishi Chemical Holdings Corporation, SGL Carbon SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Carbon Fiber Composites Parts Market Strategic Shifts
Process automation and material system convergence are compressing the cost-performance frontier for carbon fiber structural components, shifting competitive advantage from feedstock access to manufacturing yield optimization.
High-pressure resin transfer molding is consolidating as the dominant series-production technology for automotive structural components. European premium OEMs now specify HP-RTM for battery enclosures and floor pans at volumes exceeding thirty thousand units annually. This process compression is eliminating the historical premium-mass market boundary that thermoset pre-preg autoclave curing enforced.
The EU Green Deal's tightened fleet emission targets are forcing laminate architecture redesigns across body-in-white programs. Automakers must demonstrate gram-per-kilometer CO2 reductions through documented mass savings to avoid penalty structures. Germany's KBA type-approval processes now require explicit carbon fiber recycling pathway documentation for new vehicle certifications.
Buyer concentration among platform-sharing OEM consortia is compressing supplier negotiation leverage. Volkswagen Group, BMW, and Mercedes-Benz now coordinate carbon fiber procurement through shared tier-1 converters to standardize laminate specifications. This procurement consolidation is most visible in Stuttgart and Munich engineering centers where joint specification committees set PAN grade and resin system requirements.
Automotive Carbon Fiber Composites Parts Market Segmentation
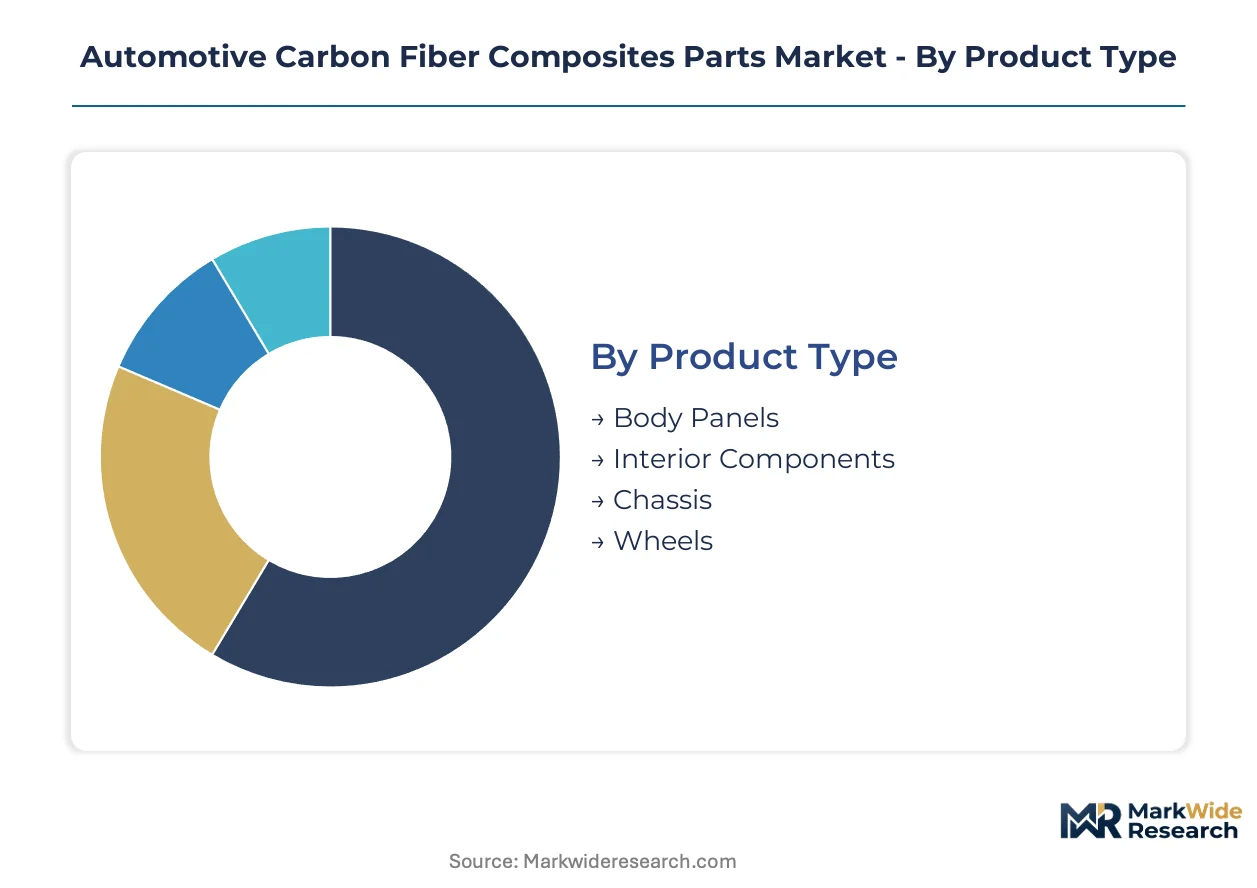
Automotive carbon fiber composites parts segmentation reveals how certification burdens, cost thresholds, and manufacturing scalability divide commercial opportunity. Each dimension exposes where laminate architecture investments align with regulatory validation requirements and series-production economics.
Product Type:
EU Green Deal fleet emission documentation and NHTSA crashworthiness certification create divergent approval timelines across structural versus cosmetic applications.
- Body Panels:Hoods, roof panels, and trunk lids comprise 60-70% carbon fiber by weight in epoxy matrices, achieving 40-50% mass reduction versus aluminum equivalents. German premium OEMs in Stuttgart and Munich concentrate procurement for EV platform range optimization, with KBA type-approval requiring explicit recycling pathway documentation.
- Chassis:Floor pans, battery enclosures, and structural cross-members demand ECE R94/R95 frontal impact validation and NHTSA FMVSS 208 compliance for energy absorption matching metallic benchmarks. BMW and Porsche specifications anchor demand through dedicated composites engineering centers.
- Interior Components:Dashboard carriers, seat shells, and trim panels prioritize aesthetic surface quality and design flexibility over structural load-bearing, commanding pricing premiums from luxury OEMs where differentiation outweighs crash-test investment.
- Wheels:One-piece and multi-piece rim constructions face SAE J2530 radial fatigue and impact testing protocols, with supply concentrating in motorsport-derived tier-1 converters serving low-volume, high-margin applications.
Body Panels sits at the top of the volume ranking, with Chassis climbing the fastest as EV platform expansion accelerates structural battery housing demand.
End User:
Procurement consolidation among platform-sharing consortia compresses supplier negotiation leverage and standardizes laminate specifications across the value chain.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz coordinate carbon fiber procurement through shared tier-1 converters, with joint specification committees in Germany setting PAN grade and resin system requirements for body-in-white programs.
- Tier-1 Suppliers:Specialized converters like SGL Carbon maintain automotive-specific carbon fiber grades through joint development pipelines, anchoring positions in structural battery housing applications with dedicated capacity allocations.
- Vehicle Assemblers:Contract manufacturers and niche EV startups source through tolling arrangements, lacking direct feedstock access and dependent on converter-managed laminate architecture development.
- Aftermarket Providers:Aerodynamic kits and cosmetic upgrades operate outside OEM crash-test validation frameworks, serving enthusiast segments with reduced regulatory burden but limited volume scalability.
Tier-1 Suppliers command the steepest margin expansion trajectory, with Aftermarket Providers facing the most constrained growth due to certification exclusion from platform development cycles.
Application:
Functional purpose determines whether laminate design prioritizes mass reduction metrics, mechanical performance, or surface aesthetics.
- Lightweighting:Gram-per-kilometer CO2 reduction documentation for EU Green Deal compliance drives laminate architecture redesigns across body-in-white programs, with automakers substituting steel and aluminum to avoid penalty structures.
- Crash Management:Frontal impact energy absorption systems require expensive laminate redevelopment for each new platform, with NHTSA protocols and ECE R94/R95 standards shaping architecture decisions where composite performance must match metallic benchmarks.
- Structural Reinforcement:Torsional rigidity enhancement for EV battery protection concentrates in HP-RTM manufactured floor pans, where high-pressure resin transfer molding cost curves now enable series production above fifty thousand units annually.
- Aesthetic Enhancement:Visible weave patterns and surface finish quality command design flexibility premiums from luxury OEMs, with interior and exterior cosmetic applications outpacing structural segments in margin contribution.
Lightweighting dominates current volume absorption, with Aesthetic Enhancement gaining share fastest as luxury differentiation strategies expand carbon fiber interior penetration.
Manufacturing Stage:
Process technology selection dictates cost-positioning against aluminum and steel substitution thresholds, with automation levels determining yield optimization potential.
- Resin Transfer Molding:High-pressure RTM consolidates as the dominant series-production technology for structural components, with European premium OEMs specifying HP-RTM for battery enclosures at volumes exceeding thirty thousand units annually.
- Thermoplastics:Polyamide and PEEK-based recyclable composites enable closed-loop manufacturing and align with EU circular economy action plan incentives, though industrial-scale recycling infrastructure remains immature under REACH landfill restrictions.
- Pre-Preg:Autoclave-cured thermoset layup retains dominance in low-volume, high-performance applications and motorsport transfer programs, with cost structures now exceeded by HP-RTM for series production.
- Compression Molding:Sheet molding compound derivatives serve intermediate volume tiers where cycle time requirements exceed RTM capabilities but pre-preg economics prove prohibitive.
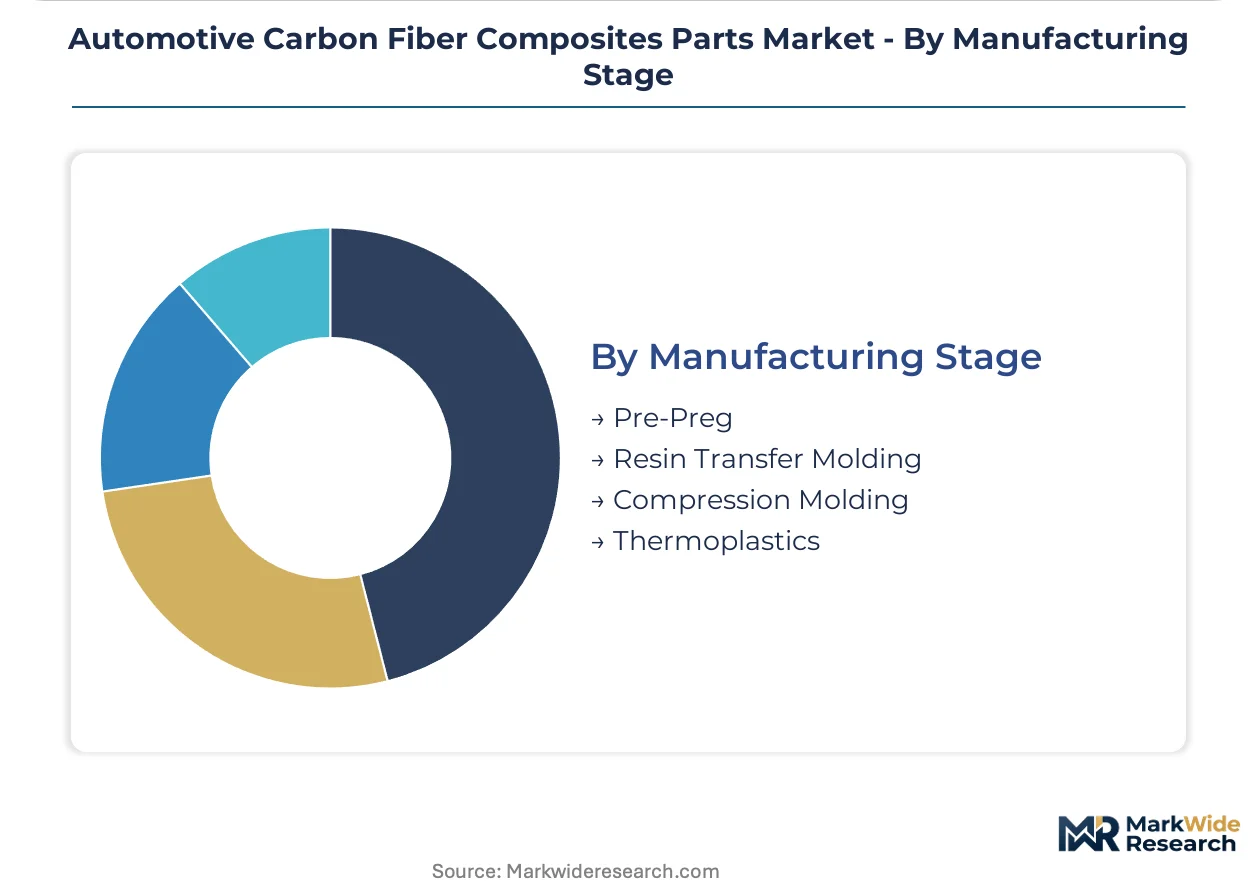
Resin Transfer Molding leads installed capacity, with Thermoplastics expanding most quickly as recyclability mandates and second-generation precursor cost curves mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Composite design engineers cluster in Stuttgart and Munich, anchoring Europe's automotive carbon fiber talent base. Japanese precursor specialists concentrate around Tokyo and Osaka. Chinese converters scale HP-RTM capacity in Shanghai and Shenzhen.
United States
EV platform expansion from Detroit and California-based startups drives structural battery housing demand. The EPA's tightened CAFE standards mandate fleet-weight reductions that justify carbon fiber substitution against aluminum. Michigan's automotive corridor hosts tier-1 converter engineering centers serving Ford and General Motors lightweighting programs.
Germany
BMW, Mercedes-Benz, and Porsche specifications anchor European demand for HP-RTM manufactured components. The EU Green Deal's fleet emission targets require documented gram-per-kilometer CO2 reductions through mass savings. Stuttgart and Munich engineering centers coordinate joint procurement committees that standardize PAN grade and resin system requirements.
China
Domestic EV manufacturers accelerate adoption of carbon fiber roof panels and battery enclosures for range optimization. MIIT dual carbon goals pressure automakers to demonstrate lightweighting compliance in type-approval submissions. Shanghai and Shenzhen manufacturing clusters scale high-pressure resin transfer molding capacity for series production above fifty thousand units annually.
Japan
Toray Industries maintains dominant feedstock positions across PAN precursor supply chains into automotive tier-1 converters. METI industrial policy supports second-generation precursor development for cost curve compression. Tokyo and Osaka metropolitan areas concentrate composite materials R&D spillover from aerospace into automotive applications.
South Korea
Hyundai and Kia EV platforms specification drives demand for structural reinforcement components. MFDS environmental regulations shape end-of-life recycling pathway requirements for epoxy-matrix components. Seoul Capital Area engineering centers specialize in thermoplastic matrix conversion for closed-loop manufacturing alignment.
Automotive Carbon Fiber Composites Parts Market Competitive Environment
Top-tier vendors anchor feedstock supply, while mid-tier fabricators compete on manufacturing yield optimization. The market structure concentrates around precursor specialists, composite converters, and resin system formulators. Three archetypes dominate: PAN precursor suppliers with backward integration into carbon fiber production, tier-1 automotive converters with OEM joint development pipelines, and diversified chemical conglomerates with matrix formulation capabilities. Competitive moves center on capacity expansion in HP-RTM manufacturing and strategic partnerships for thermoplastic recycling infrastructure.
Within the precursor-specialist tier, Toray Industries and Mitsubishi Chemical Holdings Corporation exemplify feedstock dominance through PAN supply chain control. SGL Carbon occupies a position as the automotive-focused converter archetype, representing tier-1 suppliers with dedicated OEM engineering relationships. Among diversified chemical conglomerates, BASF SE and Solvay sit within the resin system and thermoplastic matrix formulation segment, anchoring positions in recyclable composite development aligned with EU circular economy mandates.
| Leading Market Players |
|---|
| Teijin Limited |
| Owens Corning |
| Toray Industries Inc. |
| BASF SE |
| Solvay |
| Hexcel Corporation |
| Cytec Industries |
| Mitsubishi Chemical Holdings Corporation |
| SGL Carbon SE |
| Others |
Value Chain & Pricing Dynamics
High-pressure resin transfer molding adoption simultaneously compresses manufacturing cost curves and concentrates supply leverage among European tier-1 converters with dedicated OEM engineering relationships. This process transition eliminates the historical premium-mass market boundary that thermoset pre-preg autoclave curing enforced, redistributing pricing power toward buyers with platform-scale volume commitments.
Pricing Analysis
Carbon fiber components split between bundled laminate architecture development and unbundled feedstock supply contracts. Three-tier pricing structure across premium, standard, and economy levels separates HP-RTM structural components from pre-preg autoclave parts and compression-molded derivatives. Price differentiation stems from certification grade requirements and volume scale thresholds. Cost compression in standard-tier HP-RTM components is intensifying because procurement consolidation among platform-sharing OEMs compresses converter margins. Aftermarket providers exhibit highest price sensitivity due to exclusion from platform development cycles, while luxury OEMs demonstrate lowest sensitivity where aesthetic differentiation commands premiums.
Supply Chain Analysis
PAN precursor supply rests on Japanese specialty chemical producers, with Toray Industries anchoring feedstock positions into both Japanese and European tier-1 converters. Raw material dependencies include acrylonitrile monomer, carbon fiber tow grades, and epoxy resin systems. Geographic supply concentration centers on Japan, Germany, and China, with Chinese converters scaling HP-RTM capacity in Shanghai and Shenzhen manufacturing clusters. Single-source vulnerability from Toray's dominant precursor position creates allocation risk during demand surges. Distribution runs through joint specification committees in Stuttgart and Munich that standardize laminate requirements across Volkswagen Group, BMW, and Mercedes-Benz procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive carbon fiber composites parts market functions as a regulatory compounder where EU Green Deal fleet emission targets mandate documented mass savings for CO2 compliance, structurally embedding demand for lightweight composite architectures regardless of cyclical automotive production fluctuations.
For Market Incumbents: Extend HP-RTM capacity allocations ahead of platform lock-ins by major OEMs, securing dedicated engineering relationships with BMW and Porsche battery enclosure programs. Backward integration into second-generation precursor development with lignin-based alternatives defends margin position against feedstock cost volatility from Toray supply concentration. Joint development pipelines with German premium OEMs anchor structural battery housing positions against emerging thermoplastic competitors.
For New Entrants and Emerging Players: Capture interior component and wheel margin pools where aesthetic differentiation commands pricing premiums and crash-test validation burdens remain lighter than structural applications. The aftermarket aerodynamic kit segment offers most penetrable entry path, serving enthusiast demand outside OEM certification frameworks with reduced regulatory burden. Partner with motorsport-derived tier-1 converters for laminate architecture development capabilities absent in-house.
For Investors and Strategic Acquirers: Valuations sit cheapest among diversified chemical conglomerates with thermoplastic matrix formulation capabilities positioned for EU circular economy mandate alignment. Long-term viability framing centers on recyclability infrastructure maturation and second-generation precursor cost curve realization as inflection indicators. Acquisition target archetype: tier-1 converters with dedicated OEM engineering relationships and HP-RTM manufacturing yield optimization expertise.
| Strategic Initiative | Industry Significance |
|---|---|
| HP-RTM Capacity Expansion | Enables series production economics above fifty thousand units annually for BMW and Porsche EV platforms. |
| Second-Generation Precursor Development | Lignin-based alternatives from SGL Carbon joint pipelines promise thirty to forty percent feedstock cost reduction. |
| Thermoplastic Matrix Conversion | Polyamide and PEEK-based recyclable composites align with EU circular economy action plan incentives. |
| OEM Joint Development Pipeline | Dedicated engineering relationships with German premium OEMs anchor structural battery housing market positions. |
| Recycling Infrastructure Partnership | Industrial-scale pyrolysis capacity addresses REACH landfill restrictions and closes end-of-life economics gaps. |
Study Parameters
Multiple input streams — primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, IHS Markit registration data, and SEC filings from composite converters; plus customs and trade flow records — were reconciled through bottom-up and top-down triangulation. Primary fieldwork concentrated on Stuttgart and Munich engineering centers, Tokyo and Osaka precursor specialist headquarters, and Shanghai manufacturing clusters. Secondary sources included KBA type-approval documentation, EPA CAFE standard filings, and EU Green Deal regulatory impact assessments.
Data-stream reconciliation across product type, end user, application, and manufacturing stage dimensions generated volume and value outputs across the projection horizon. Segmentation modeling incorporated vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster variables. CAGRs were derived from platform-scale adoption curves for HP-RTM manufacturing and precursor cost compression trajectories. Industry-specific forecast inputs included battery enclosure demand from BMW and Porsche EV platforms and EU fleet emission penalty structure thresholds.
Regulatory enforcement delays, thermoplastic recycling infrastructure buildout timelines, and PAN precursor supply allocation disruptions are the dominant revision risks to modeled outcomes. Forecasts reflect assumptions around HP-RTM cost curve trajectories and OEM platform standardization decisions. A small set of named triggers — KBA certification pathway changes, REACH landfill restriction enforcement, and Toray capacity expansion announcements — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive License Plate Light Market
Automotive Components
France Automotive Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
Automotive Gear Shifter Market
Automotive Components
Japan Automotive Composites Market
Automotive Components
United States Automotive Pneumatic Actuators Market
Automotive Components
Europe Heat Shrink Tubing for Automotive Market
Automotive Components
Automotive Differential Market
Automotive Components
Iran Automotive Lubricants Market
Automotive Components
Automotive Metal Market
Automotive Components
Automotive Radiator Fan Market
Automotive Components
Automotive Comfort Actuators Market
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
Automotive Distributor O Ring Market
Automotive Components
Global Automotive Brake Components Market