
 South Africa Automotive Adaptive Lighting System Market | 2026-2036
South Africa Automotive Adaptive Lighting System Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Automotive Adaptive Lighting System Market Analytics
Asset-light leasing structures for automotive electronics subsystems is reconfiguring how tier-one suppliers and aftermarket distributors enter the South Africa adaptive lighting value chain. Valeo Group leverages its control systems expertise to anchor premium OEM contracts in Gauteng assembly corridors. HELLA KGaA Hueck & Co competes through specialized sensor-based module production that sustains local content requirements. Koito Manufacturing Co Ltd dominates technical partnerships with Japanese-brand vehicle plants in Durban.
Automotive adaptive lighting systems integrate electronically controlled headlamp units that modulate beam pattern, intensity, and direction through motor-driven projectors, LED matrices, or xenon arc sources in response to vehicle speed, steering angle, and ambient conditions. These systems reduce glare exposure to oncoming traffic while maximizing driver visibility during cornering, elevation changes, and adverse weather. Matrix LED product types lead installed value across passenger vehicle applications where OEM specification intensity runs highest. Automated technology segments command expanding share as sensor fusion with camera and radar inputs displaces manual adjustment modes. Electric vehicle application demand concentrates among premium battery platforms where energy-efficient lighting supports range optimization targets.
South Africa's National Regulator for Compulsory Specifications mandates headlamp performance and alignment compliance under compulsory specification VC 8024, while the South African Bureau of Standards maintains vehicle lighting test protocols aligned with UN ECE regulations. The National Energy Regulator of South Africa indirectly shapes demand through efficiency benchmarking that favors LED and laser lighting architectures over conventional halogen systems. Stakeholders must monitor alignment between local specification updates and evolving UN harmonized technical standards to preserve market access and avoid retesting burdens.
Market Dynamics
Matrix LED architectures are collapsing the cost-performance trade-off that previously constrained premium lighting to flagship nameplates, forcing recalibration of supplier tiering across Gauteng assembly corridors.
Growth Catalysts
- UN ECE harmonization:South Africa's alignment with UN ECE R48 and R123 lighting standards under the National Regulator for Compulsory Specifications reduces retesting burdens for OEMs importing complete vehicle platforms.
- Durban-Japanese technical partnerships:Japanese-brand vehicle plants in KwaZulu-Natal generate concentrated demand for sensor-integrated adaptive modules with localized calibration capabilities.
- LED energy efficiency mandates:The National Energy Regulator of South Africa benchmarks vehicle subsystem efficiency, indirectly accelerating displacement of halogen architectures in fleet procurement specifications.
Market Restraints
- Import dependency for semiconductor components:Control chips and LED drivers concentrate in East Asian foundries, exposing South African integrators to currency volatility and extended lead times.
- VC 8024 alignment complexity:The National Regulator for Compulsory Specifications enforces compulsory headlamp performance standards that diverge from UN ECE test protocols in beam pattern verification, creating dual certification burdens for suppliers serving export and domestic markets simultaneously.
- Substitution by static LED systems:Lower-tier vehicle platforms specify fixed-beam LED headlamps with manual leveling, limiting adaptive system penetration to premium segments.
Strategic Opportunities
- Eastern Cape vehicle assembly expansion:Volkswagen Group's Kariega plant and Isuzu Motors South Africa in Gqeberha represent underpenetrated production nodes for adaptive lighting integration beyond Gauteng concentration.
- Camera-radar sensor fusion:Convergence of forward-facing camera arrays with radar inputs enables predictive beam adjustment, creating upgrade pathways for existing vehicle platforms without full electrical architecture redesign.
- Aftermarket retrofit channel development:Independent service networks in Cape Town and Johannesburg metropolitan areas present distribution innovation potential for certified adaptive module upgrades outside OEM captive supply chains.
Industry Challenges
- Optical calibration technician scarcity:Precision headlamp alignment requires specialized expertise in photometric measurement equipment that outpaces vocational training program output.
- Legacy vehicle electrical architecture integration:Adaptive systems demand controller area network bandwidth and power distribution capacity that pre-2020 vehicle platforms lack, complicating retrofit and model-year carryover strategies.
- Homologation timeline compression:Accelerated product cycles from European and Japanese OEMs compress the window for local compliance testing and regulatory submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Automotive Adaptive Lighting System Market |
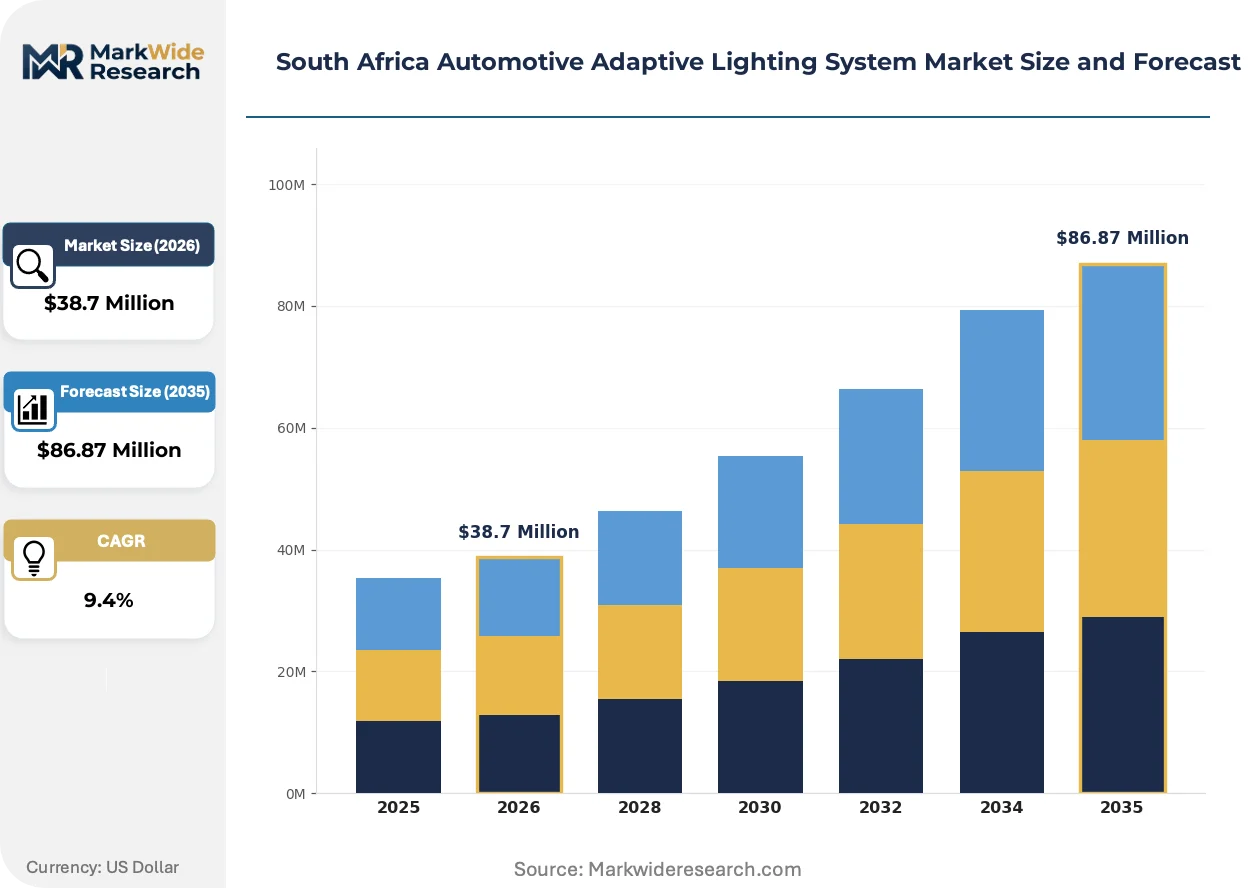
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $86.87 Million |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Matrix LED, Adaptive Xenon, Dynamic Bending, Laser Lighting End User: OEMs, Aftermarket Providers, Automotive Suppliers, Dealerships Technology: Control Systems, Sensor-Based, Manual Adjustment, Automated Systems Application: Passenger Vehicles, Commercial Vehicles, Luxury Vehicles, Electric Vehicles |
| Companies Covered | Magneti Marelli SpA, Texas Instruments, Hyundai Mobis, Koito Manufacturing Co Ltd, Koninklijke Philips N.V., Osram, HELLA KGaA Hueck & Co, Stanley Electric Co Ltd, Valeo Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Automotive Adaptive Lighting System Market Evolving Landscape
Digital light processing is reshaping how beam patterns are computed and projected, shifting competitive advantage from mechanical precision to software-defined optical performance.
Matrix LED technology is collapsing the distinction between high-beam and low-beam hardware through individually addressable diode arrays that extinguish specific segments to avoid oncoming glare. Premium OEMs in Gauteng assembly corridors specify these systems at escalating rates for mid-tier nameplates previously limited to static xenon. The technology is collapsing supplier margin structures by commoditizing the mechanical actuators that previously differentiated tier-one from tier-two lighting integrators.
VC 8024 under the National Regulator for Compulsory Specifications is tightening photometric performance thresholds for adaptive headlamp certification, with 2024 amendments introducing dynamic leveling verification under loaded vehicle conditions. This regulatory shift forces recalibration of supplier test protocols and documentation systems. Component manufacturers serving the South African market must now maintain parallel compliance documentation for UN ECE alignment and local compulsory specification divergence.
Fleet procurement specifications are fragmenting across buyer categories, with rental and corporate fleet operators prioritizing total cost of ownership metrics that favor standardized LED modules over adaptive complexity. Mining and logistics fleets in the Northern Cape and Limpopo provinces specify ruggedized lighting with manual override capabilities, resisting sensor-dependent automation. This demand-side segmentation is compressing the addressable market for premium adaptive systems outside passenger vehicle applications.
South Africa Automotive Adaptive Lighting System Market Segmentation
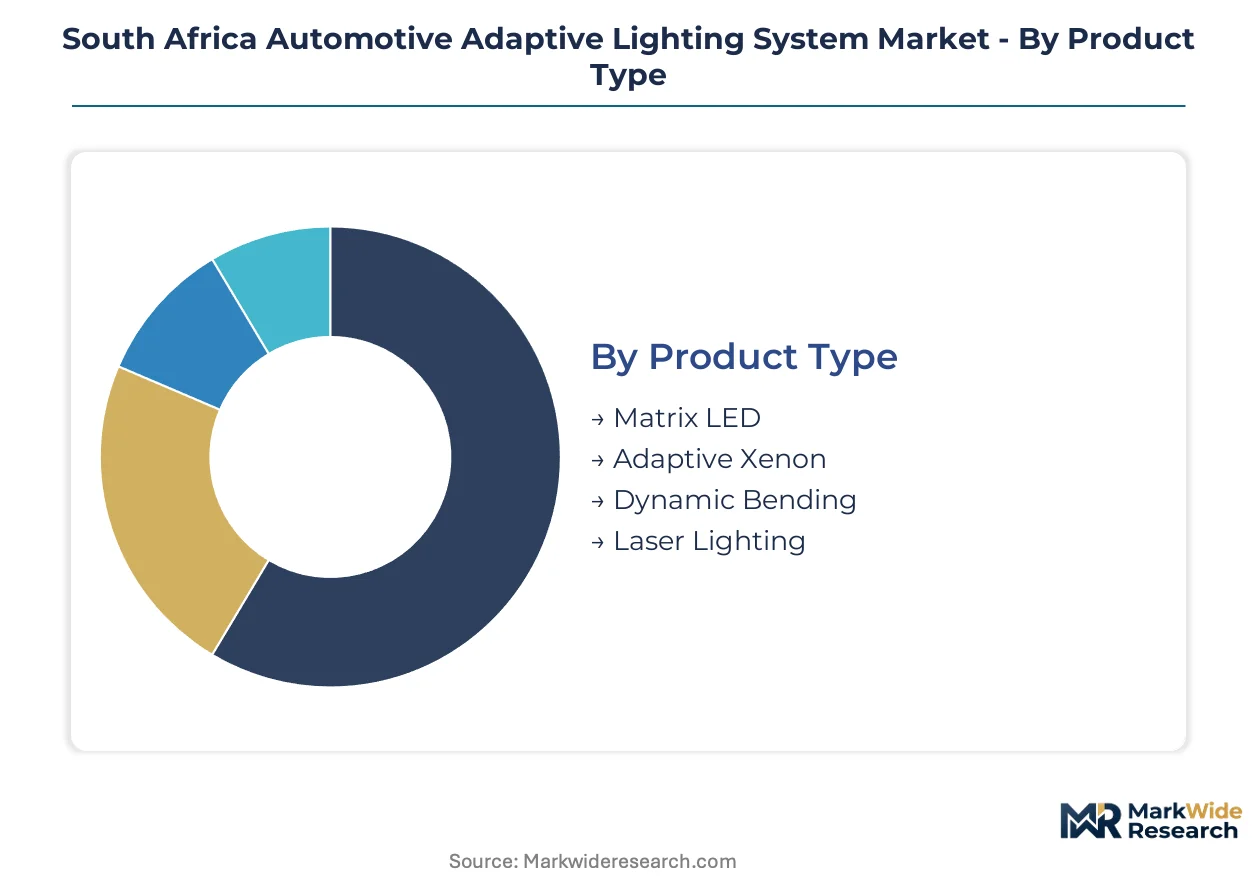
Adaptive lighting system segmentation in South Africa reflects divergent technical requirements across OEM captive supply and independent aftermarket channels. Gauteng assembly corridors concentrate specification intensity for matrix LED architectures, while aftermarket retrofit demand fragments across price-performance tiers in metropolitan service networks.
Product Type:
After-sales-service intensity varies sharply across lighting architectures, with semiconductor-dependent matrix systems requiring specialized diagnostic equipment versus mechanically simpler xenon platforms.
- Matrix LED:Individually addressable diode arrays extinguish specific segments to avoid oncoming glare without mechanical beam switching. Gauteng-based premium OEM assembly lines specify these systems for mid-tier nameplates previously limited to static xenon, compressing supplier margin structures through actuator commoditization.
- Adaptive Xenon:Motor-driven projector units modulate beam direction through electromechanical actuation in response to vehicle dynamics. Durban-Japanese technical partnerships sustain concentrated demand for these systems where localized calibration capabilities support just-in-time assembly sequences.
- Dynamic Bending:Cornering-focused beam pivot systems rotate headlamp units in phase with steering angle inputs.
- Laser Lighting:High-intensity coherent light sources extend beam throw distance for highway cruising applications.
Matrix LED holds the largest share; momentum sits with laser lighting architectures as energy efficiency mandates from the National Energy Regulator of South Africa intensify.
End User:
Cost tier stratification separates specification authority from installation execution across the value chain.
- OEMs:Vehicle manufacturers in Gauteng and the Eastern Cape exercise direct control over lighting system specification, sourcing complete adaptive modules from tier-one integrators. Volkswagen Group's Kariega plant and Isuzu Motors South Africa in Gqeberha represent expanding procurement nodes beyond traditional Gauteng concentration.
- Aftermarket Providers:Independent service networks in Cape Town and Johannesburg metropolitan areas develop certified adaptive module upgrade channels outside OEM captive supply chains, targeting legacy vehicle platforms with controller area network bandwidth constraints.
- Automotive Suppliers:Tier-one and tier-two integrators manage subsystem assembly and regulatory compliance documentation.
- Dealerships:Authorized retail channels handle warranty-integrated replacement and software calibration services.
OEMs command specification authority; aftermarket providers are climbing the fastest as retrofit channel development accelerates in metropolitan clusters.
Technology:
Application context determines automation depth, with sensor fusion architectures displacing manual modes in premium battery platforms.
- Control Systems:Electronic control units process vehicle speed, steering angle, and ambient condition inputs to coordinate motor-driven actuators or LED matrix switching. These systems anchor Valeo Group's premium OEM contract positioning in Gauteng assembly corridors through proprietary algorithm portfolios.
- Sensor-Based:Forward-facing camera arrays combined with radar inputs enable predictive beam adjustment before steering input registration. HELLA KGaA Hueck & Co competes through specialized module production that sustains local content requirements under South Africa's automotive incentive frameworks.
- Manual Adjustment:Driver-initiated beam leveling through dashboard controls persists in lower-tier fleet specifications.
- Automated Systems:Fully autonomous beam modulation without driver intervention requires highest controller area network bandwidth.
Control systems anchor current revenue; automated systems gain share fastest as electric vehicle application demand concentrates among premium battery platforms.
Application:
Customer type fragmentation splits procurement priorities between total cost of ownership metrics and performance differentiation.
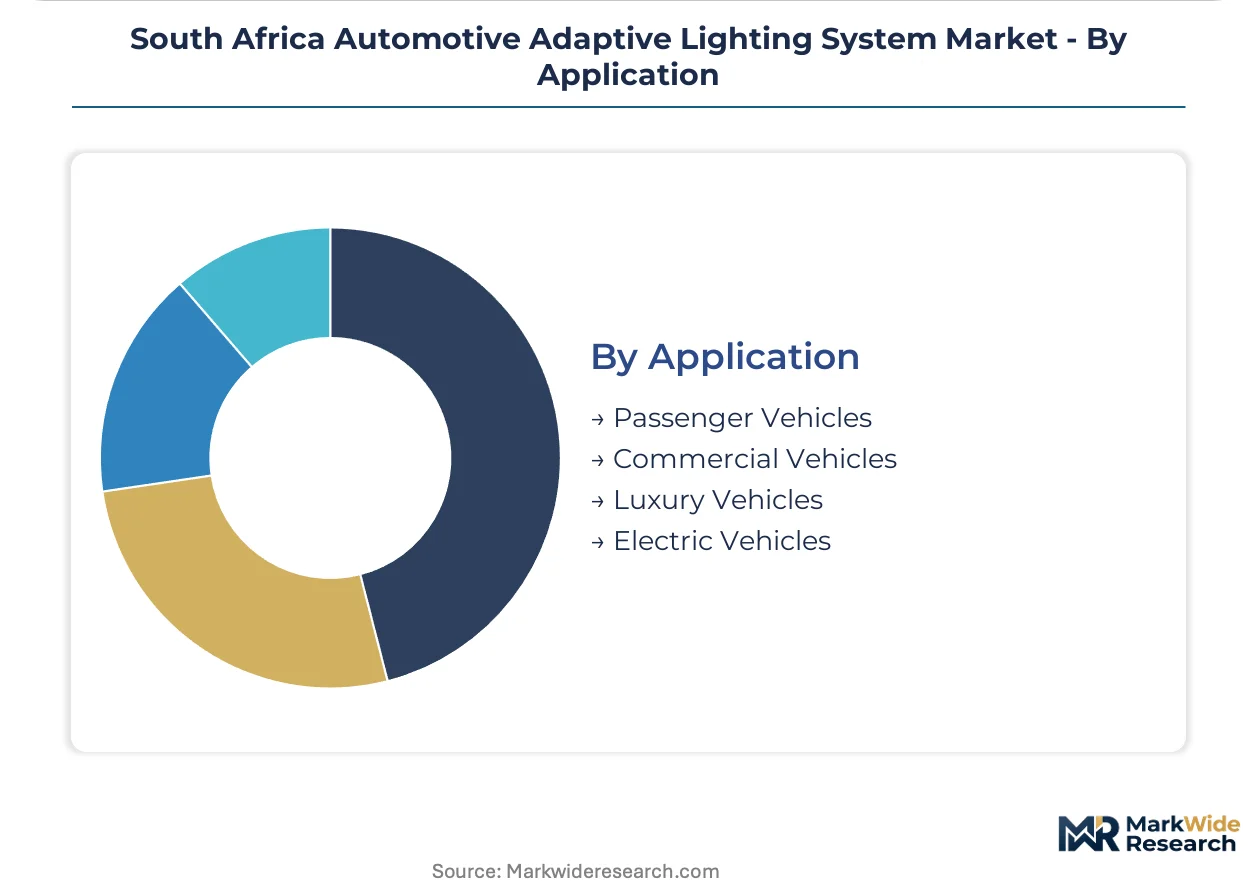
- Passenger Vehicles:Private ownership segments drive specification intensity for glare-reduction and cornering visibility features. Matrix LED installed value concentrates here where OEM specification intensity runs highest across Gauteng premium assembly lines.
- Luxury Vehicles:Flagship nameplates specify full sensor fusion architectures with predictive beam adjustment. Koito Manufacturing Co Ltd dominates technical partnerships with Japanese-brand vehicle plants in Durban for these applications.
- Commercial Vehicles:Mining and logistics fleets in the Northern Cape and Limpopo provinces specify ruggedized lighting with manual override capabilities.
- Electric Vehicles:Battery platform range optimization targets favor energy-efficient LED and laser architectures over conventional halogen systems.
Passenger vehicles dominate volume; electric vehicles show steepest expansion trajectory as efficiency benchmarking from the National Energy Regulator of South Africa reshapes fleet procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Africa's adaptive lighting system trade flows reflect import dependency for semiconductor components alongside concentrated domestic assembly capacity in Gauteng and the Eastern Cape. The National Regulator for Compulsory Specifications shapes cross-border procurement through VC 8024 alignment requirements that diverge from UN ECE protocols.
Gauteng Province
Premium passenger vehicle assembly lines in Rosslyn and Pretoria generate the highest specification intensity for matrix LED architectures. The National Regulator for Compulsory Specifications enforces headlamp alignment standards that OEMs must satisfy before platform deployment. Tier-one integrators cluster around Tshwane and Johannesburg metropolitan nodes to service just-in-time supply sequences for BMW, Nissan, and Ford manufacturing facilities.
KwaZulu-Natal
Durban-Japanese technical partnerships concentrate demand for sensor-integrated adaptive modules with localized calibration capabilities. Toyota South Africa Motors and other Japanese-brand plants specify adaptive xenon systems where electromechanical actuation supports established assembly workflows. The provincial automotive supplier park in Prospecton anchors subsystem integration activity for export-oriented production.
Eastern Cape
Volkswagen Group's Kariega plant and Isuzu Motors South Africa in Gqeberha represent underpenetrated production nodes for adaptive lighting integration beyond traditional Gauteng concentration. The Department of Trade, Industry and Competition's Automotive Production and Development Programme incentivizes local content thresholds that tier-one suppliers must satisfy. Supplier park development in the Coega Industrial Development Zone is attracting component manufacturers seeking proximity to expanding OEM capacity.
Western Cape
Independent aftermarket service networks in Cape Town metropolitan areas develop certified adaptive module upgrade channels outside OEM captive supply chains. The provincial government's GreenCape initiative promotes energy-efficient vehicle subsystem procurement that favors LED architectures over conventional halogen. Precision headlamp alignment facilities cluster around Stikland and Epping industrial zones to support fleet maintenance contracts.
South Africa Automotive Adaptive Lighting System Market Competitive Landscape
On the supply side, the industry is tiered between global lighting system integrators, semiconductor component suppliers, and regional assembly specialists. Three strategic archetypes dominate: European-headquartered tier-one integrators with full-system capabilities, East Asian component manufacturers leveraging technical partnerships, and diversified electronics conglomerates supplying control chips and LED drivers. Competitive moves concentrate on strategic partnerships with OEM assembly corridors and technology licensing arrangements that preserve market access under local content requirements.
Among the established tier-one integrators, Valeo Group, HELLA KGaA Hueck & Co, and Koito Manufacturing Co Ltd occupy positions that exemplify distinct competitive vectors. Valeo Group represents the European full-system integrator archetype with control systems expertise anchoring premium OEM contracts. HELLA KGaA Hueck & Co exemplifies the specialized sensor-based module producer competing through local content compliance. Koito Manufacturing Co Ltd sits within the Japanese technical partnership archetype that dominates supply relationships with Durban-based vehicle plants.
| Leading Market Players |
|---|
| Magneti Marelli SpA |
| Texas Instruments |
| Hyundai Mobis |
| Koito Manufacturing Co Ltd |
| Koninklijke Philips N.V. |
| Osram |
| HELLA KGaA Hueck & Co |
| Stanley Electric Co Ltd |
| Valeo Group |
| Others |
Value Network & Pricing Analysis
Semiconductor import dependency from East Asian foundries compresses pricing tier spreads between matrix LED and static xenon systems while forcing tier-one integrators toward long-term offtake contracts with Gauteng OEM assembly corridors. This single-source vulnerability simultaneously elevates premium tier pricing power for localized calibration capabilities and squeezes mid-tier margins through currency volatility pass-through.
Pricing Analysis
Industrial OEM buyers anchor a contract-based long-term offtake structure that stratifies across premium, standard, and economy tiers based on certification grade under VC 8024 and volume scale commitments. Price differentiation hinges on UN ECE alignment documentation completeness and after-sales diagnostic equipment bundling. Pricing pressure stems from static LED substitution in fleet procurement specifications, compressing adaptive system premiums. Rental and corporate fleet operators exhibit highest price sensitivity; luxury vehicle platforms show lowest sensitivity due to performance differentiation requirements.
Supply Chain Analysis
Tariff exposure between South Africa and East Asian semiconductor manufacturing centers dominates supply chain risk calculations for LED drivers and control chips. Component sourcing draws from Taiwan, South Korea, and China, with raw material dependencies concentrated in gallium nitride substrates, silicon carbide wafers, and rare-earth phosphors. Single-source vulnerability in automotive-grade microcontroller supply creates inventory buffering requirements. Distribution runs through tier-one integrator hubs in Tshwane and Prospecton supplier parks serving just-in-time OEM assembly sequences.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
OEM procurement consolidation around Gauteng and Eastern Cape assembly corridors is shifting specification authority toward fewer buyers with expanding technical compliance requirements. This buyer-power concentration demands differentiated defensive postures across incumbent, entrant, and investor archetypes.
For Market Incumbents: Entrench control systems expertise through backward integration into LED driver semiconductor sourcing, countering East Asian foundry dependency. Deepen calibration service capabilities at Tshwane technical centers to defend against aftermarket retrofit channel encroachment. Prioritize VC 8024 compliance documentation investments as regulatory divergence from UN ECE protocols intensifies certification burdens. For New Entrants and Emerging Players: Pursue aftermarket retrofit channel development in Cape Town and Johannesburg metropolitan clusters where legacy vehicle electrical architecture constraints create white-space opportunity. Target commercial vehicle applications in Northern Cape and Limpopo mining corridors with ruggedized adaptive modules featuring manual override capabilities. Deploy certified upgrade programs through independent service networks as the primary go-to-market angle. For Investors and Strategic Acquirers: VC 8024 amendment implementation reshapes the acquisition landscape by elevating regulatory compliance capabilities above pure technology differentiation. Long-term viability centers on tier-one integrators with parallel UN ECE and local compulsory specification documentation systems. Acquire specialized sensor-based module producers with established local content credentials. Monitor National Energy Regulator efficiency benchmarking announcements as the signal to watch for LED architecture demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Matrix LED Platform Standardization | Reduces actuator cost differentials across BMW and Nissan Gauteng assembly lines. |
| Semiconductor Supply Agreement | Secures LED driver allocation from Taiwan foundries for Durban-Japanese technical partnerships. |
| Software-Defined Lighting Investment | Shifts competitive advantage from mechanical precision to algorithm-based beam computation. |
| Eastern Cape Manufacturing Footprint | Positions tier-one integrators near Volkswagen Kariega and Isuzu Gqeberha expansion capacity. |
| Calibration Infrastructure Partnership | Addresses optical technician scarcity through vocational training alignment with Stikland industrial zones. |
Research Methodology
Cross-validation between OEM platform engineering disclosures and tier-one supplier procurement documentation anchors the qualitative findings. Primary interviews with automotive lighting system integrators, OEM procurement leads, aftermarket distributors, and National Regulator for Compulsory Specifications compliance officers combined with secondary validation from vehicle production databases, UN ECE regulatory filings, and South African Bureau of Standards test protocol documentation. Bottom-up installed base analysis and top-down OEM specification tracking triangulate market sizing across the projection horizon.
Calibration against historical penetration rates of xenon and LED architectures informs the analytical framework across vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derive from segment-level growth rate reconciliation with aggregate market expansion. Forecast inputs incorporate National Energy Regulator efficiency benchmarking trajectory and VC 8024 amendment implementation timing.
Sensitivities concentrate around semiconductor supply disruption duration, currency volatility magnitude, and regulatory harmonization pace between local and UN ECE standards. Forecasts reflect documented assumptions regarding OEM platform launch schedules and fleet procurement specification evolution. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Door Guards Market
Automotive Safety and Security Systems
Global Electronic Brake Force Distribution System Market
Automotive Safety and Security Systems
Air Brake System Market
Automotive Safety and Security Systems
Two Wheeler Crash Guard Market
Automotive Safety and Security Systems
Automotive Airbag Silicone Market
Automotive Safety and Security Systems
Asia Pacific Airbag Systems Market
Automotive Safety and Security Systems
Automotive Driver Drowsiness Detection System Market
Automotive Safety and Security Systems
Brazil Airbag Systems Market
Automotive Safety and Security Systems
Europe Automotive Anti-Lock Braking System Market
Automotive Safety and Security Systems
Automatic Brake Pad Inspection System Market
Automotive Safety and Security Systems
Automotive Intelligent Headlight System Market
Automotive Safety and Security Systems
Motorcycle E-Call Market
Automotive Safety and Security Systems
Global Airbag Systems Market
Automotive Safety and Security Systems
Automotive Blind Spot Detection (BSD) System Market
Automotive Safety and Security Systems
Vehicle Speed Monitoring System Market
Automotive Safety and Security Systems
Vehicle Occupancy Detection System Market