
 Asia-Pacific Automotive Parts and Components Market | 2026-2036
Asia-Pacific Automotive Parts and Components Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Automotive Parts and Components Market Outlook
Modular powertrain packaging is rebalancing buyer choice across the Asia-Pacific Automotive Parts and Components Market. DENSO Corporation leverages its thermal management integration to anchor hybrid-electric contracts with Japanese OEMs. Robert Bosch GmbH sustains broad sensor and actuator portfolios that compete across multiple vehicle platforms. Bharat Forge Limited specializes in lightweight metal powertrain components that occupy critical positions in commercial vehicle supply chains.
Automotive parts and components encompass engineered subsystems—braking systems, suspension components, electrical parts, and powertrain components—manufactured to OEM and aftermarket specifications through processes including forging, precision machining, injection molding, and electronics assembly. These products transmit power, ensure vehicle control, manage energy distribution, and maintain occupant safety across passenger and commercial vehicles. Powertrain components command the largest value pool as electrification intensifies motor and inverter content per vehicle. Electrical parts represent the fastest-expanding segment due to rising semiconductor and wiring harness density in connected and electric architectures. Braking systems remain structurally mature but face margin pressure as electromechanical brake-by-wire platforms replace conventional hydraulic assemblies.
China's MIIT enforces NEV production quotas and GB standards that dictate supplier certification thresholds for battery and motor components. India's BIS and Automotive Research Association of India implement CMVR safety and emissions rules that condition market access for braking and lighting suppliers. Japan's METI coordinates JIS standards and carbon-neutrality roadmaps that steer R&D investment toward hydrogen-compatible powertrain materials. Stakeholders must monitor how divergent electrification timelines across Beijing, Tokyo, and New Delhi reshape component standardization and regional sourcing decisions.
Market Dynamics
Electrification mandates across China, Japan, and India are compressing supplier development cycles while fragmenting component specifications, forcing tier-1 manufacturers to maintain parallel powertrain portfolios.
Growth Catalysts
- China's NEV mandate:MIIT production quotas accelerate motor and inverter procurement volumes, pulling suppliers toward high-voltage component certification.
- Lightweighting materials:Aluminum-intensive chassis and battery enclosures reduce vehicle mass, extending electric range without cell chemistry breakthroughs.
- Yangtze River Delta clustering:Co-location of assemblers and tier-1 suppliers in Shanghai-Jiangsu-Zhejiang corridor compresses logistics costs and prototype iteration timelines.
Market Restraints
- Rare earth supply concentration:Permanent magnet motor production depends on Chinese-processed neodymium, creating single-source vulnerability for Japanese and Korean motor suppliers.
- Silicon carbide substrate shortage:Wafer capacity constraints limit inverter power module scaling, capping 800V architecture rollout for premium EV platforms.
- Divergent GB-JIS-BIS standards:Incompatible battery safety testing protocols force suppliers to maintain three certification tracks, inflating R&D overhead.
Strategic Opportunities
- Southeast Asian EV assembly:Thailand and Indonesia offer tariff-advantaged export platforms for suppliers serving Australian and Middle Eastern markets.
- Hydrogen-compatible powertrains:Japan's METI carbon-neutrality roadmap funds fuel cell stack and high-pressure tank component development.
- Remanufactured aftermarket:India's extended vehicle parc creates demand for refurbished powertrain modules as OEMs withdraw from internal combustion service parts.
Industry Challenges
- High-voltage technician scarcity:Battery pack assembly and service require certified electricians, creating recruitment bottlenecks across Chinese and Indian plants.
- Functional safety certification lag:ISO 26262 ASIL-D compliance for autonomous braking systems extends development timelines by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Automotive Parts and Components Market |
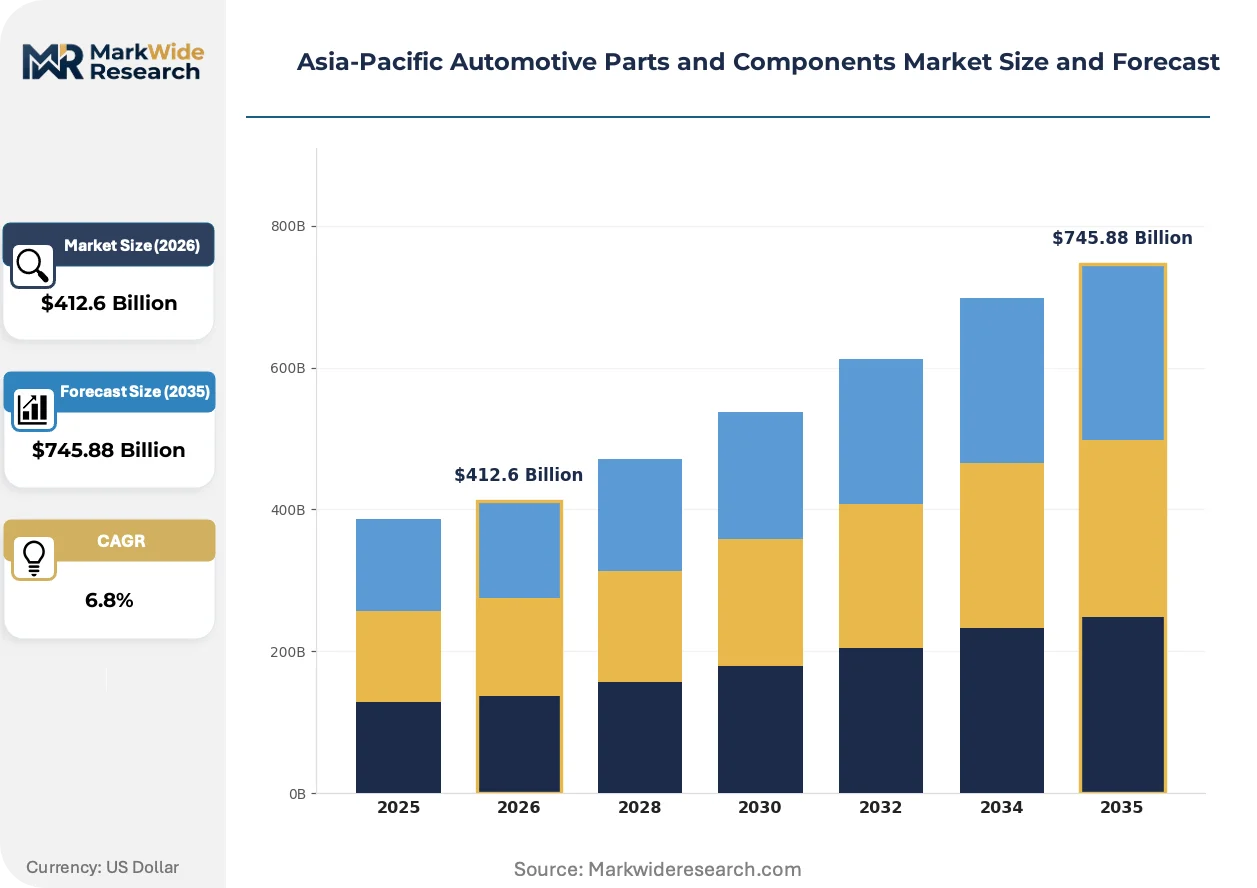
| Market Size in 2026 | $412.6 Billion |
| Market Size in 2035 | $745.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braking Systems, Suspension Components, Electrical Parts, Powertrain Components End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Material: Metals, Plastics, Composites, Rubber Distribution Channel: Online Retailers, Wholesale Distributors, Direct Sales, Brick-and-Mortar Stores |
| Companies Covered | Aisin Corporation, Continental AG, DENSO Corporation, Mando, Sumitomo Electric Industries, Ltd., Robert Bosch GmbH, Hyundai Mobis Co., Ltd., Bharat Forge Limited, ZF Friedrichshafen AG, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Automotive Parts and Components Market Strategic Shifts
Digital manufacturing and connected component architectures are redefining how automotive parts are designed, validated, and monetized across the Asia-Pacific supply base.
Generative design algorithms paired with additive manufacturing are automating topology optimization for suspension knuckles and motor housings. Tier-1 suppliers in Japan and South Korea deploy these tools to reduce prototype iteration cycles from weeks to days. The technology is automating material distribution decisions that previously required senior engineer judgment.
India's BIS has mandated AIS-156 battery safety standards for all NEV platforms sold domestically, imposing thermal runaway propagation tests and crash-triggered disconnect requirements. Suppliers must redesign pack architectures and cooling circuits to achieve certification. The regulation most affects two-wheeler and three-wheeler segments where cost pressures previously limited passive safety investment.
Fleet operators and mobility platforms now specify component-level telematics integration as a procurement prerequisite, unbundling hardware from predictive maintenance contracts. Traditional distributors lose margin to direct supplier-fleet data arrangements. This pattern concentrates in China's ride-hailing and logistics sectors where vehicle utilization rates justify real-time component monitoring.
Asia-Pacific Automotive Parts and Components Market Segmentation
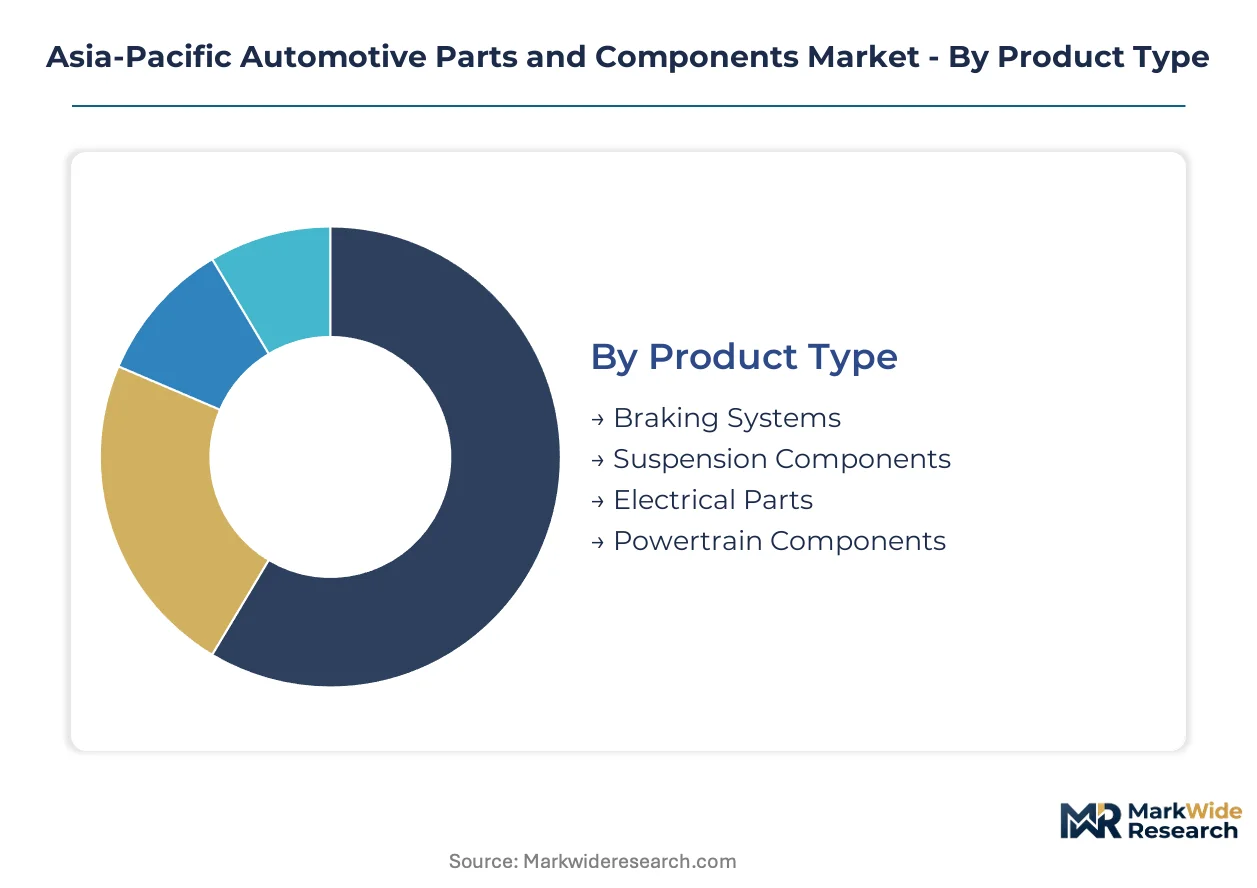
Segmentation reveals how electrification and supply chain restructuring are redistributing value across component categories in the Asia-Pacific Automotive Parts and Components Market. Each dimension exposes different pressure points—from material substitution in powertrain housings to channel conflict between traditional distributors and direct fleet sales.
Product Type:
Volume concentrates in mature mechanical systems while premium capture shifts toward electrified subsystems with semiconductor content.
- Powertrain Components:Motors, inverters, and transmissions engineered for internal combustion, hybrid, and battery-electric architectures. China's Yangtze River Delta manufacturing cluster absorbs the bulk of motor and inverter procurement as domestic OEMs expand NEV output.
- Electrical Parts:Wiring harnesses, sensors, control modules, and semiconductors managing energy distribution and vehicle connectivity. India's AIS-156 battery safety mandates are forcing redesigns of pack monitoring electronics and disconnect circuits for two-wheeler and three-wheeler platforms.
- Braking Systems:Hydraulic and electromechanical assemblies ensuring vehicle deceleration and stability control.
- Suspension Components:Springs, dampers, and linkages maintaining ride quality and handling precision.
Today's leader: Powertrain Components. Tomorrow's challenger: Electrical Parts.
End User:
Procurement authority is consolidating at the vehicle assembler level while tier-1 suppliers fight to retain design ownership.
- OEMs:Original equipment manufacturers specifying component performance, certification, and integration requirements. Japanese OEMs are consolidating inverter and thermal management sourcing through single-source contracts with DENSO Corporation and affiliated keiretsu suppliers.
- Tier-1 Suppliers:System integrators managing subsystem design, testing, and tier-2 component procurement. These suppliers face margin compression as assemblers bring battery pack assembly in-house to capture cell-to-pack integration value.
- Vehicle Assemblers:Final manufacturers integrating complete vehicles from component and subsystem inputs.
- Aftermarket Providers:Distributors and service networks supplying replacement parts for vehicle maintenance and repair.
Design authority flows toward OEMs. Margin capture concentrates with tier-1 system integrators.
Material:
Cost tier stratification separates commodity inputs from performance-critical alloys and fiber-reinforced polymers.
- Metals:Steel, aluminum, and specialty alloys forged and machined for structural and thermal applications. Bharat Forge Limited anchors commercial vehicle crankshaft and axle sourcing through closed-die forging capabilities in Pune and Chennai.
- Composites:Carbon fiber and glass-reinforced polymers enabling mass reduction in battery enclosures and body panels. Japanese suppliers under METI carbon-neutrality roadmaps are qualifying recycled carbon fiber for hydrogen tank pressure vessels.
- Plastics:Injection-molded polymers for interior trim, underhood components, and electrical housings.
- Rubber:Elastomer compounds for seals, hoses, vibration isolation, and tire components.
Metals dominate tonnage. Composites gain fastest on weight-critical electrified platforms.
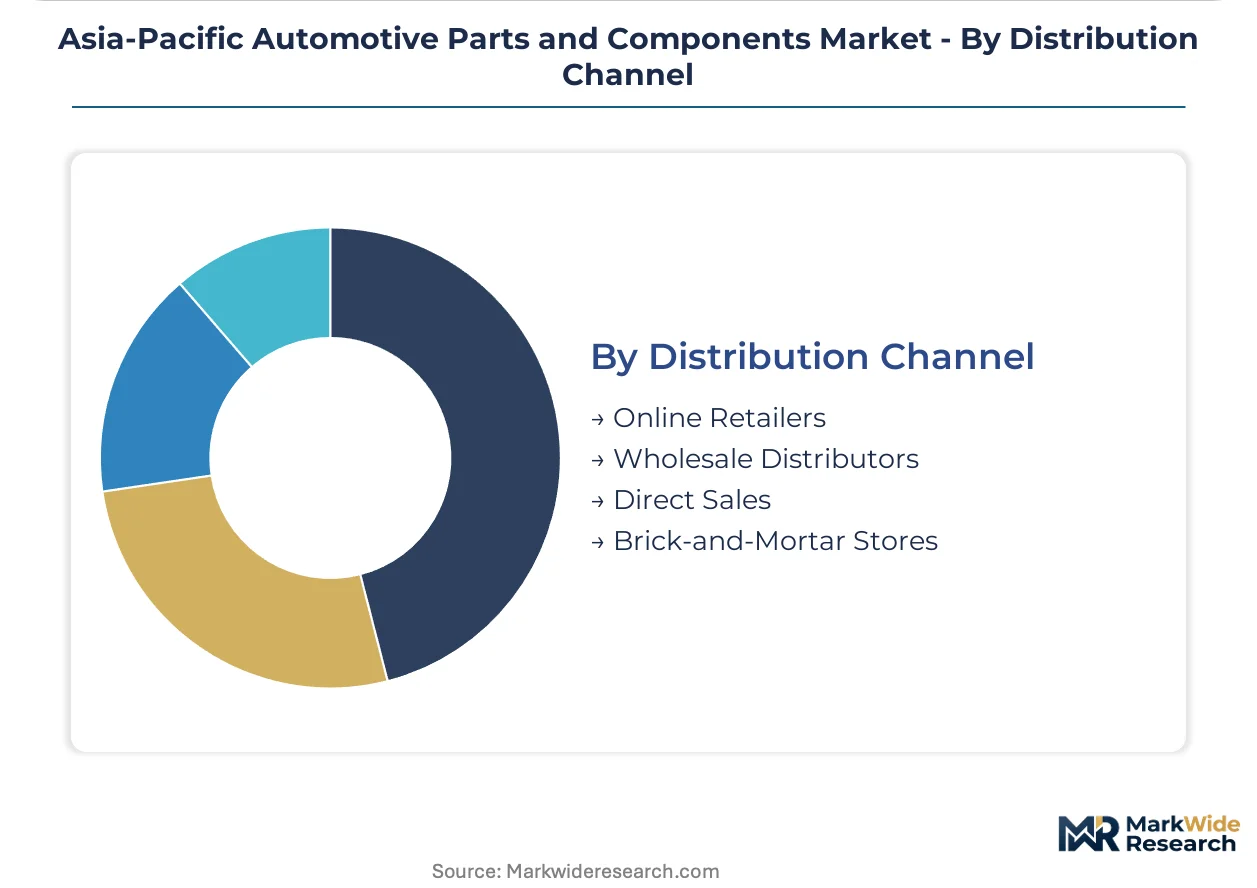
Distribution Channel:
Channel structure fragments between asset-heavy wholesale networks and data-enabled direct relationships.
- Direct Sales:Supplier-to-assembler contracts negotiated on multi-year platforms with embedded telematics and predictive maintenance terms. China's ride-hailing and logistics fleets now mandate component-level data integration as a procurement condition, bypassing traditional distributors.
- Wholesale Distributors:Regional inventory aggregators serving independent repair shops and smaller assemblers with consolidated SKU availability.
- Online Retailers:E-commerce platforms enabling price-transparent parts sourcing for aftermarket and small-volume OEM procurement.
- Brick-and-Mortar Stores:Physical retail and service locations providing immediate availability and installation support.
Direct Sales commands platform economics. Online Retailers erode legacy distributor margins fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's post-war keiretsu system established the template for Asia-Pacific automotive component manufacturing, embedding tier-1 suppliers within OEM supply hierarchies that later spread to South Korea and China. This organizational lineage continues to shape procurement patterns across the region.
China
NEV production quotas from MIIT pull motor and inverter procurement toward domestic suppliers certified under GB standards. The Yangtze River Delta manufacturing cluster concentrates tier-1 facilities in Shanghai, Jiangsu, and Zhejiang provinces where prototype iteration timelines compress through co-location with vehicle assemblers.
Japan
METI carbon-neutrality roadmaps steer R&D investment toward hydrogen-compatible powertrain materials and fuel cell stack components. The Chubu region around Nagoya anchors thermal management and hybrid-electric subsystem production through keiretsu-affiliated suppliers integrated with Toyota and Honda assembly networks.
India
BIS and ARAI implement CMVR safety and emissions rules that condition market access for braking and lighting suppliers. The Pune-Chennai industrial corridor hosts Bharat Forge and affiliated metal-forming operations serving commercial vehicle crankshaft and axle demand from domestic OEMs.
South Korea
Hyundai-Kia's integrated supply chain model concentrates motor and battery component procurement through captive tier-1 relationships. The Busan-Ulsan manufacturing belt houses powertrain and electrical parts facilities aligned with export-oriented vehicle assembly plants.
Thailand
Board of Investment incentives for EV assembly create tariff-advantaged export platforms serving Australian and Middle Eastern markets. The Eastern Economic Corridor attracts powertrain and electrical component suppliers seeking regional hub status outside China's direct supply chain gravity.
Asia-Pacific Automotive Parts and Components Market Competitive Environment
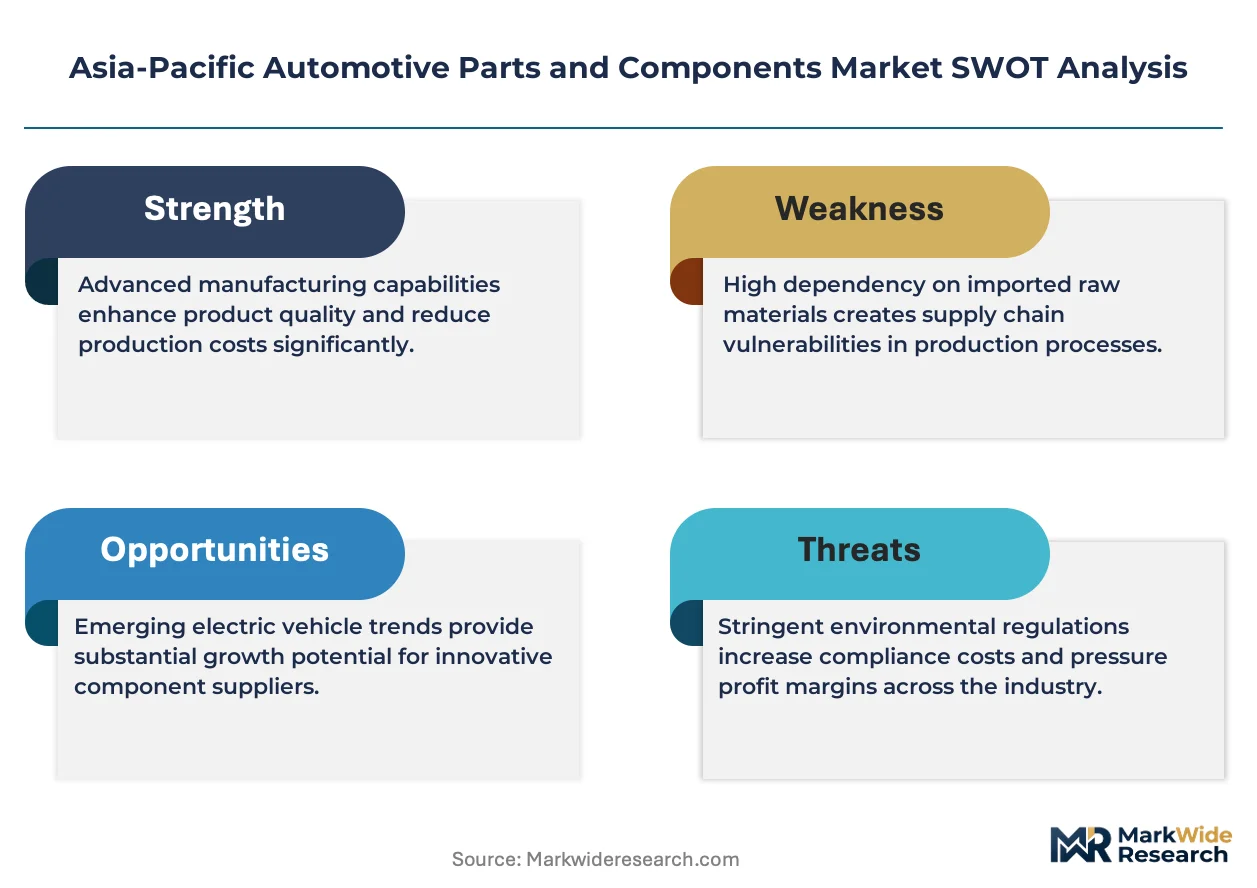
Premium-margin players sit above commodity-margin players across certification intensity and thermal management integration depth. The market structure stratifies into three tiers: keiretsu-affiliated Japanese suppliers with embedded OEM relationships, German and Korean system integrators competing on platform scale, and Indian metal-forming specialists capturing commercial vehicle volume. Consolidation pressure intensifies as assemblers bring battery pack assembly in-house and tier-1 suppliers respond through thermal management portfolio expansion and Southeast Asian capacity placement.
Among keiretsu-integrated specialists, DENSO Corporation and Aisin Corporation exemplify the premium-tier archetype through thermal and powertrain subsystem integration with Japanese OEMs. Robert Bosch GmbH occupies a position spanning sensor and actuator portfolios across multiple vehicle platforms and regional markets. Bharat Forge Limited anchors the metal-forming tier through closed-die forging capabilities concentrated in Indian industrial corridors serving commercial vehicle demand.
| Leading Market Players |
|---|
| Aisin Corporation |
| Continental AG |
| DENSO Corporation |
| Mando |
| Sumitomo Electric Industries, Ltd. |
| Robert Bosch GmbH |
| Hyundai Mobis Co., Ltd. |
| Bharat Forge Limited |
| ZF Friedrichshafen AG |
| Others |
Value Chain & Pricing Dynamics
Rare earth magnet costs cascade from Chinese-processed neodymium through motor supplier pricing tiers, compressing margins for Japanese and Korean tier-1 manufacturers locked into long-term OEM contracts. This input-cost concentration forces premium-mid-economy pricing differentiation across powertrain component portfolios, with high-voltage certification investments separating certified suppliers from commodity competitors.
Pricing Analysis
Platform-based contract pricing with embedded telematics and predictive maintenance terms dominates procurement between tier-1 suppliers and vehicle assemblers. Price differentiation hinges on ISO 26262 functional safety certification grade and volume scale commitments, with ASIL-D compliant braking systems commanding substantial premiums over baseline hydraulic assemblies. Pricing pressure stems from OEM in-sourcing of battery pack assembly, eroding tier-1 subsystem margins. Fleet operators and ride-hailing platforms exhibit lowest price sensitivity due to utilization-rate economics, while independent aftermarket distributors face acute margin compression from direct supplier-fleet data arrangements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from China's Yangtze River Delta assemblers, while wholesale distributors serve fragmented independent repair networks. Geographic supply concentration centers on China, Japan, and South Korea for motor and inverter production, with India anchoring commercial vehicle metal-forming operations. Raw material dependencies draw from Chinese-processed rare earth elements, Korean silicon carbide substrates, and Japanese thermal management alloys. Single-source vulnerability in neodymium processing creates structural risk for permanent magnet motor suppliers. Distribution runs through keiretsu-affiliated networks in Japan, integrated chaebol channels in South Korea, and state-coordinated procurement clusters in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific Automotive Parts and Components Market functions as a geographic-arbitrage play where Southeast Asian EV assembly incentives in Thailand and Indonesia offset China's supply chain gravity through tariff-advantaged export access to Australian and Middle Eastern buyers.
For Market Incumbents: Hedge against OEM in-sourcing threats by expanding thermal management integration depth and securing hydrogen-compatible powertrain material qualifications under Japan's METI carbon-neutrality roadmap. Prioritize Southeast Asian capacity placement to capture regional hub status outside direct Chinese supply chain dominance. Reinforce keiretsu relationships through embedded software-defined vehicle component development.
For New Entrants and Emerging Players: The premium-economy tier price-point gap in India's two-wheeler and three-wheeler electrification creates white-space opportunity for AIS-156 certified battery pack suppliers. Target Thailand's Eastern Economic Corridor for tariff-advantaged export platform positioning. Pursue direct fleet sales channels with telematics integration as the primary go-to-market angle.
For Investors and Strategic Acquirers: Roll-up economics work for thermal management specialists because OEM consolidation of inverter sourcing through single-source contracts is concentrating design authority with subsystem integrators. Five-to-ten year viability favors suppliers with GB-JIS-BIS triple certification capability. Monitor silicon carbide substrate capacity expansion as the critical inflection signal for 800V architecture rollout timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Secures cell-to-pack integration value as OEMs bring assembly in-house. |
| Platform Standardization | Reduces R&D overhead from divergent GB-JIS-BIS certification tracks. |
| Geographic Manufacturing Footprint | Thailand and Indonesia offer tariff-advantaged export platforms. |
| Software-Defined Vehicle Investment | Fleet operators now mandate component-level telematics integration. |
| Charging Infrastructure Partnership | Links powertrain suppliers to downstream energy ecosystem monetization. |
Study Parameters
Bottom-up vehicle production modeling reconciled against top-down supplier shipment tracking forms the analytical core. Primary interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations heads combined with secondary validation from vehicle production databases, IHS Markit registration data, MIIT NEV quota filings, and METI technology roadmap disclosures. Top-down trade flow analysis and bottom-up content-per-vehicle estimates triangulate market sizing.
Historical trendline analysis of motor and inverter procurement volumes against NEV production trajectories established baseline growth patterns. Segmentation modeling spans vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions across the projection horizon. CAGRs derive from regression-adjusted production forecasts incorporating electrification mandate compliance timelines and supplier certification capacity constraints.
Caveats apply where rare earth supply disruptions, silicon carbide substrate shortages, or divergent standardization timelines could materially shift the outlook. Forecasts reflect assumptions regarding MIIT quota enforcement consistency and METI hydrogen roadmap funding continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Dynamic Spotlight Market
Automotive Components
Automotive Distributor Market
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Global Flexible Shaft Couplings Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
Drive System Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Automotive Carbon Fiber Market
Automotive Components
Automotive Catalytic Converter Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Global Automotive Window Regulator Market
Automotive Components
Automotive Resonator Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
Automotive Straps Market