
 Europe Automotive Plastics Market | 2026-2036
Europe Automotive Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Plastics Market Foresight
Polypropylene is rebalancing interior component economics as it displaces heavier ABS and metal substrates in dashboard carriers and door panels. BASF SE leverages its Ludwigshafen polymer complex to sustain captive supply of glass-reinforced grades for structural applications. LANXESS anchors its position through high-heat polyamide formulations tailored for under-the-hood thermal management. Covestro AG differentiates via polycarbonate glazing solutions that compete with conventional glass in panoramic roof modules.
Europe automotive plastics comprise engineered polymers and polymer composites formulated to meet automotive specifications for impact resistance, thermal stability, and surface finish, typically processed through injection molding or extrusion into components that reduce vehicle mass and enable design integration. Polypropylene dominates volume demand across interior and exterior applications due to its cost-performance ratio and recyclability alignment with EU circular economy mandates. Injection molding leads technology adoption for complex geometries with tight tolerances, while blow molding retains share in fluid reservoir and ducting applications where hollow forms are required.
The EU Green Deal's carbon border adjustments and REACH chemical registration requirements are reshaping material selection criteria, compelling suppliers to document lifecycle emissions and substance safety across the value chain. ECHA's restrictions on persistent organic pollutants and the F-Gas Regulation phase-down are eliminating certain foam blowing agents and flame retardants from approved formulations. Stakeholders must monitor the interplay between EMA polymer safety assessments and OEM sustainability scorecards to anticipate which resin grades retain market access.
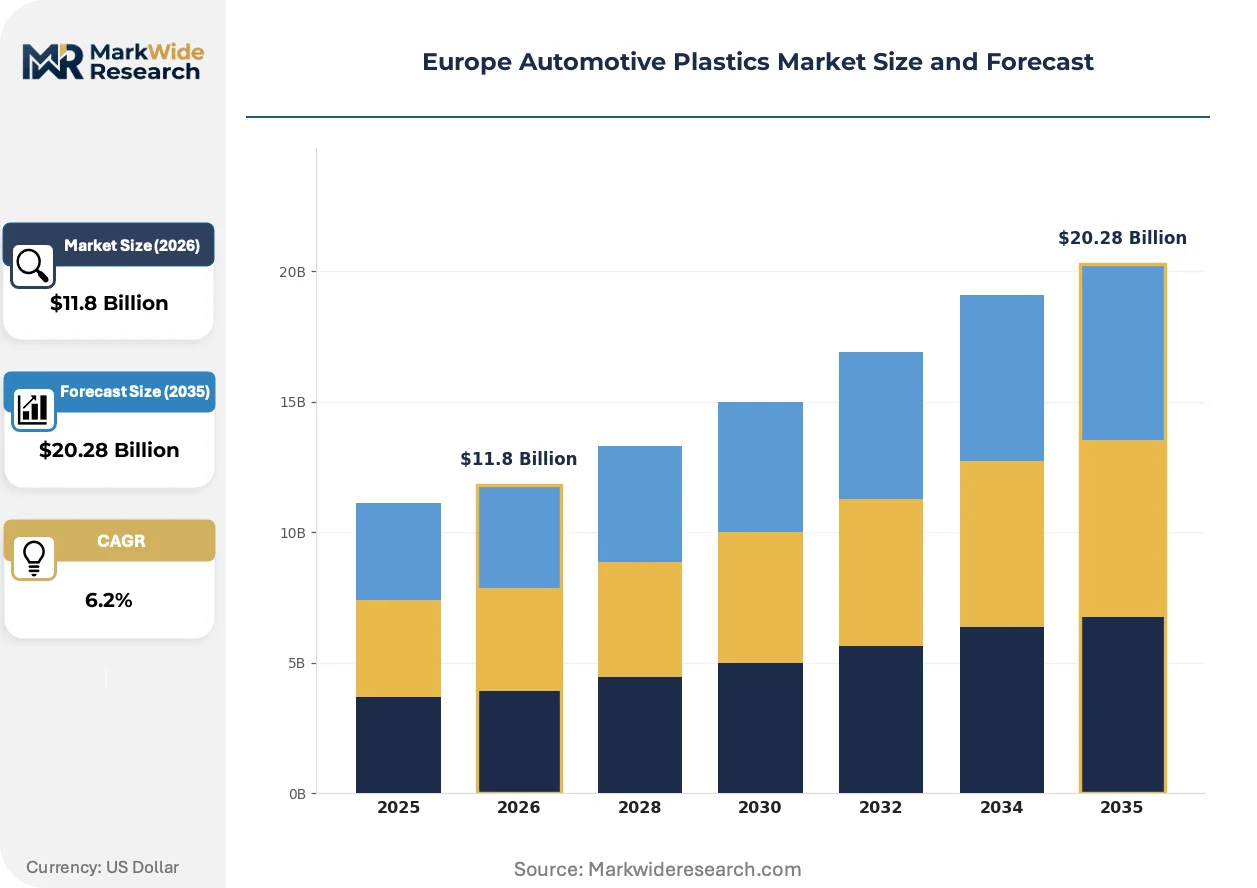
Market Dynamics
The EU Green Deal's binding CO2 fleet targets and carbon border adjustment mechanisms are forcing OEMs to eliminate metal mass from vehicle architectures, redirecting engineering resources toward polymer substitution programs.
Growth Catalysts
- REACH chemical registration:The regulation's substance authorization process favors established polymer grades with documented safety profiles, accelerating qualified material adoption.
- Electric vehicle platforms:Battery enclosure designs demand flame-retardant thermoplastic composites that reduce thermal propagation risk while cutting assembly weight.
- German automotive corridor:Stuttgart-to-Wolfsburg production density creates localized demand pull for just-in-time polymer compound deliveries.
Market Restraints
- Crude oil derivatives volatility:Naphtha and propylene feedstock costs swing with Brent crude movements, compressing compounder margins unpredictably.
- Antwerp-Rotterdam supply concentration:European polymer distribution hinges on Benelux port infrastructure, creating single-point vulnerability.
- Mechanical property ceilings:Glass-reinforced polyamides hit stiffness limits in structural load paths above 150°C continuous service temperature.
Strategic Opportunities
- Eastern European manufacturing:Slovakia and Czech Republic assembly plants remain underpenetrated by local compounding capacity.
- Circular economy mandates:EU End-of-Life Vehicle Directive revisions reward post-consumer recycled content integration in interior panels.
- Bio-based feedstock convergence:Mass balance certification chains linking renewable naphtha to automotive grades unlock premium positioning.
Industry Challenges
- Polymer characterization expertise:OEM sustainability scorecards require lifecycle assessment competency that mid-tier molders lack.
- Multi-material bonding certification:Adhesive selection for metal-to-plastic hybrid joints faces EMA safety review delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Plastics Market |
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.28 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ABS, Polycarbonate, Polypropylene, Nylon End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Application: Interior Components, Exterior Parts, Under-the-Hood, Structural Technology: Injection Molding, Blow Molding, Thermoforming, Extrusion |
| Companies Covered | DSM N.V., LANXESS, BASF SE, Exxon Mobil Corporation, Solvay, Borealis AG, Celanese Corporation, LyondellBasell Industries N.V., Covestro AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Plastics Market Shifts & Advancements
Material science advances and regulatory compliance automation are converging to reshape how automotive plastics are formulated, validated, and integrated into vehicle platforms across European supply chains.
Long-fiber thermoplastic injection molding is consolidating structural component manufacturing by enabling direct metal replacement in front-end modules and seat structures. German and French OEMs are qualifying these grades for crash-critical applications at accelerated timelines. The technology is consolidating multiple stamped metal parts into single molded assemblies, reducing supplier count and logistics complexity.
ECHA's restrictions on persistent organic pollutants are eliminating legacy brominated flame retardants from interior formulations, forcing compounders to validate phosphorus-based alternatives through full-scale burn testing. The F-Gas Regulation phase-down compounds this pressure by restricting hydrofluorocarbon blowing agents in foam insulation. Under-the-hood applications in thermal management modules face the steepest reformulation costs and longest requalification cycles.
Automotive procurement departments are consolidating resin suppliers to reduce audit burden under extended producer responsibility frameworks. Tier-1 molders in France and Italy are responding by pre-qualifying compounders with integrated recycling capabilities and mass balance certification. This concentration is most visible in dashboard carrier programs where sustainability documentation requirements now outweigh unit cost in source selection criteria.
Europe Automotive Plastics Market Segmentation
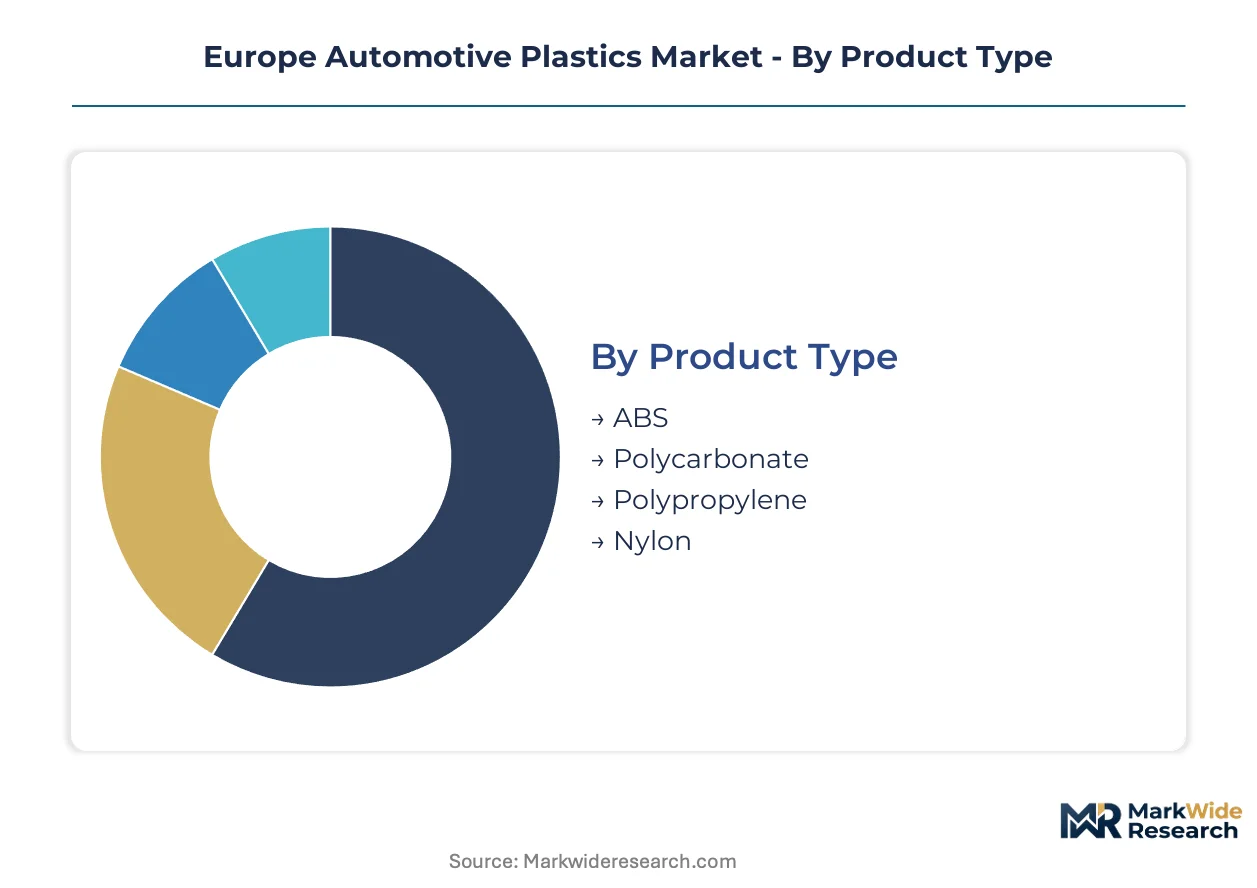
Segmentation in Europe automotive plastics reveals how capital allocation and regulatory pressure concentrate value creation across distinct material grades and processing technologies. German and French OEM procurement patterns favor suppliers with qualified capacity across multiple polymer categories simultaneously.
Product Type:
Capital intensity varies sharply across polymer platforms, with polyamide compounding requiring the heaviest upstream investment in glass-fiber handling and drying infrastructure.
- Polypropylene:Formulated with talc or glass fiber reinforcement for dashboard carriers and bumper beams. Demand concentrates in Stuttgart-to-Wolfsburg manufacturing corridors where just-in-time delivery contracts favor compounders with captive resin supply. REACH registration burdens favor incumbent suppliers with decade-long substance documentation.
- Polycarbonate:Optical-grade formulations serve panoramic roof modules and headlamp lenses. French OEMs specify Covestro's Makrolon grades for weight reduction against laminated glass. Thermal stability requirements above 130°C continuous service drive specification toward high-viscosity extrusion grades.
- ABS:Acrylonitrile-butadiene-styrene retains share in decorative interior trim where surface aesthetics outweigh density concerns. Compounding requires emulsion polymerization capacity concentrated in Benelux chemical clusters.
- Nylon:Polyamide 6 and 6.6 formulations dominate under-the-hood thermal management. LANXESS Durethan grades qualify for charge air cooler housings and oil pan modules. Moisture absorption management adds processing complexity absent in olefinic alternatives.
Most installed capacity flows through polypropylene. Expansion is steepest in polycarbonate glazing applications.
End User:
Customer type determines contract structure, with OEM direct relationships demanding the longest qualification timelines but yielding the highest margin stability.
- Tier-1 Suppliers:Faurecia and Plastic Omnium mold interior and exterior assemblies under program-specific supply agreements. These firms consolidate resin purchasing across multiple OEM customers to achieve volume pricing leverage.
- OEMs:Volkswagen Group and Stellantis maintain direct compounding relationships for strategic grades where intellectual property protection matters. Captive polymer development centers in Wolfsburg and Turin formulate proprietary glass-reinforced specifications.
- Aftermarket Providers:Collision repair parts distributors source commodity ABS and polypropylene grades through regional compounders. Price sensitivity limits specification to non-reinforced injection molding resins.
- Dealerships:Service channel procurement of interior trim components represents minimal volume but requires rapid color-matching capabilities from local molders.
Tier-1 suppliers command the largest aggregate volume. OEM direct relationships are climbing the fastest as platform consolidation reduces supplier count.
Application:
Functional requirements separate segments by thermal and mechanical load, with structural applications imposing the most severe qualification protocols.
- Interior Components:Dashboard carriers, door panels, and pillar trim specify low-emission polypropylene to meet VDA 270 odor testing. ECHA restrictions on brominated flame retardants force reformulation toward phosphorus-based alternatives.
- Under-the-Hood:Charge air coolers, oil pans, and thermal management modules demand heat-stabilized polyamide. Continuous service temperatures above 150°C eliminate all but glass-reinforced 6.6 grades from consideration.
- Exterior Parts:Bumpers and fenders balance impact resistance with paint adhesion. TPO formulations with controlled rubber phase morphology dominate this specification space.
- Structural:Front-end modules and seat structures adopt long-fiber thermoplastic injection molding for metal replacement. Crash performance validation requires multi-year testing programs.
Interior applications absorb the greatest compound volume. Structural adoption is expanding most quickly as electric vehicle platforms prioritize mass reduction.
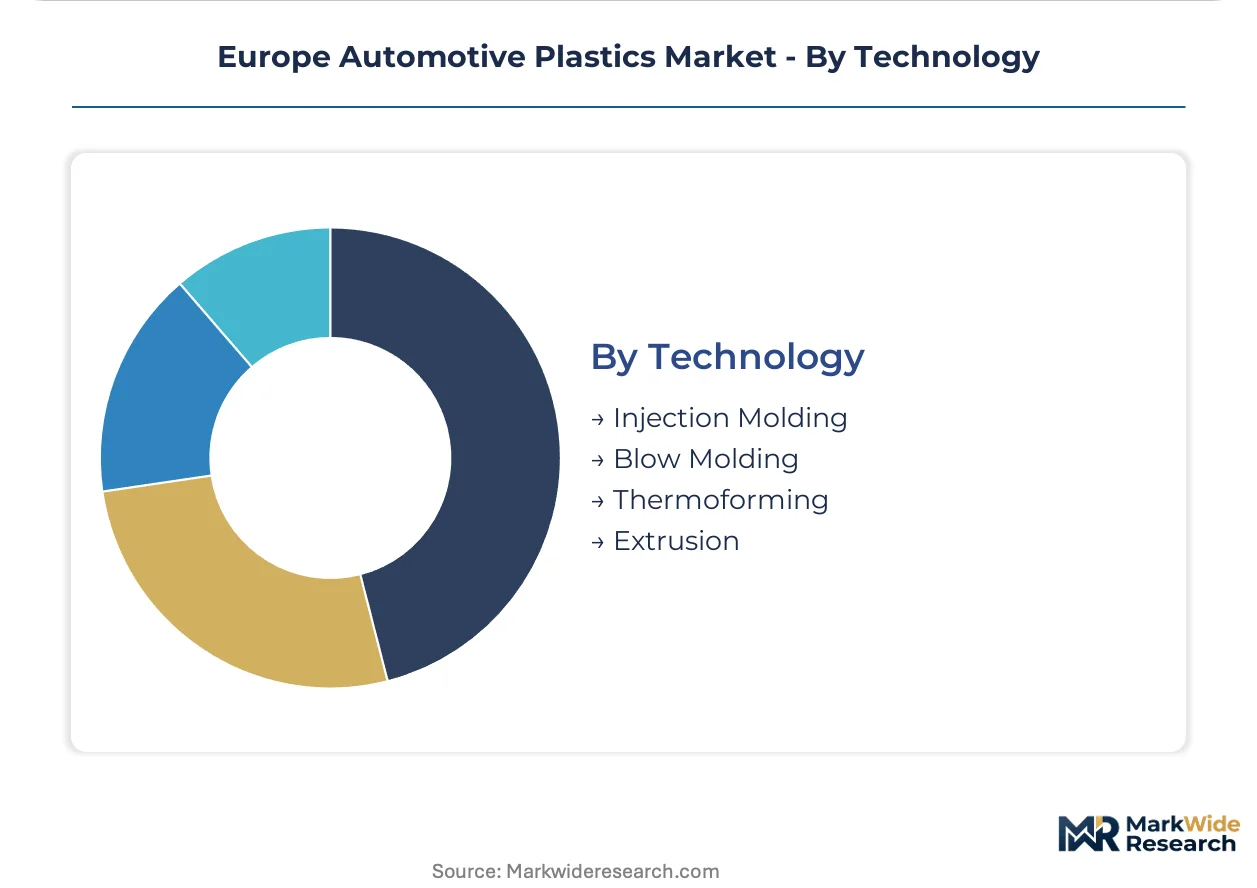
Technology:
Process selection locks in capital equipment decisions for decades, with injection molding demanding the highest upfront tooling investment per production cell.
- Injection Molding:Complex geometries with tight tolerances dominate interior and structural applications. All-electric machines from Engel and KraussMaffei enable precision control for thin-wall dashboard carriers.
- Blow Molding:Fluid reservoirs, air ducts, and fuel filler pipes require hollow forms impossible through solid-shot processes. Accumulator head technology handles high-melt-strength polyolefins.
- Thermoforming:Skylight glazing and interior trim panels leverage vacuum and pressure forming for large-area parts. Tooling costs run substantially below injection alternatives.
- Extrusion:Profile and sheet production feeds downstream thermoforming or serves direct applications in sealing systems. Twin-screw compounding lines integrate filler dispersion with profile shaping.
Injection molding commands the dominant installed base. Long-fiber thermoplastic variants within injection processes are gaining share fastest for structural metal replacement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Stuttgart-to-Wolfsburg corridor concentrates Europe's highest automotive plastics consumption density, with German OEMs driving specification standards that cascade through French and Italian supply chains. REACH registration requirements and EU Green Deal carbon border adjustments are reshaping material sourcing patterns across the continent.
Germany
Volkswagen Group and Mercedes-Benz AG consume flame-retardant polyamide grades for electric vehicle battery enclosures, while BMW specifies long-fiber thermoplastics for seat structures. The KBA enforces type-approval standards that extend to polymer crash performance. BASF's Ludwigshafen complex anchors captive compounding capacity serving Wolfsburg and Munich assembly plants.
France
Stellantis operations in Sochaux and Mulhouse source polycarbonate glazing solutions for panoramic roof modules to cut vehicle mass. ANSM chemical safety reviews delay new adhesive formulations for metal-to-plastic hybrid joints. The Auvergne-Rhône-Alpes cluster around Lyon hosts compounding facilities supplying thermal management grades to Renault's powertrain operations.
Italy
Stellantis Turin and Ferrari Maranello specify aesthetic ABS grades for interior trim where surface finish outweighs density concerns. ECHA restrictions on brominated flame retardants force reformulation of dashboard carriers toward phosphorus-based alternatives. The Emilia-Romagna automotive belt concentrates injection molding capacity for just-in-time delivery to premium vehicle assembly.
Spain
SEAT Martorell and Ford Valencia source TPO formulations for bumper beams and exterior panels requiring paint adhesion compatibility. The EU End-of-Life Vehicle Directive revisions reward post-consumer recycled content integration in interior components. Catalonia's chemical parks near Tarragona distribute polypropylene compounds through Mediterranean port infrastructure.
Poland
Volkswagen Poznań and Stellantis Tychy assembly plants pull commodity polypropylene grades for interior panels from regional compounders. CSRD reporting requirements extend sustainability documentation obligations to Tier-2 molders. The Silesian manufacturing zone offers lower-cost production bases for dashboard carrier programs serving German OEMs.
Europe Automotive Plastics Market Competitive Landscape
Global majors compete with regional champions across polymer technology platforms, with integrated petrochemical groups holding feedstock cost advantages over standalone compounders. The vendor base stratifies into three tiers: captive resin producers with downstream compounding, independent specialists in high-heat engineering grades, and regional distributors of commodity formulations. Consolidation is accelerating through backward integration by resin producers into compounding assets, while technology licensing agreements spread long-fiber thermoplastic processing expertise.
Among Benelux-integrated resin producers, DSM N.V. and Solvay occupy positions exemplifying the engineering-grade specialization archetype, while BASF SE anchors the fully integrated model spanning naphtha through finished compounds. LANXESS represents the mid-tier independent compounder competing through application-specific formulation expertise rather than feedstock scale.
| Leading Market Players |
|---|
| DSM N.V. |
| LANXESS |
| BASF SE |
| Exxon Mobil Corporation |
| Solvay |
| Borealis AG |
| Celanese Corporation |
| LyondellBasell Industries N.V. |
| Covestro AG |
| Others |
Supply & Pricing Matrix
Engineered-grade certification divergence separates polyamide compounders commanding premium positioning from commodity polypropylene suppliers competing on volume scale, with this tier split manifesting in divergent supply chain footprints and contract structures across German and French OEM procurement desks.
Pricing Analysis
Naphtha and propylene feedstock costs transmit directly to compounder quotations through quarterly contract adjustments with Stuttgart-to-Wolfsburg OEMs. Price differentiation rests on REACH registration completeness and glass-fiber loading percentages, with fully-certified grades capturing margin premiums. Cost compression in commodity polypropylene is intensifying because regional compounders in Poland and Czech Republic are expanding capacity. Aftermarket distributors exhibit highest price sensitivity, while OEM direct relationships prioritize qualification stability over unit cost.
Supply Chain Analysis
Polymer engineering talent shortages in Slovakia and Czech Republic constrain compounding capacity expansion despite assembly plant demand growth. Raw material flows draw from Benelux naphtha crackers, Saudi propylene imports, and Ludwigshafen captive resin production. Single-source vulnerability concentrates at Antwerp-Rotterdam port infrastructure handling bulk polymer distribution. Distribution runs through just-in-time hub arrangements serving Stuttgart-to-Wolfsburg manufacturing corridors with 48-hour delivery windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
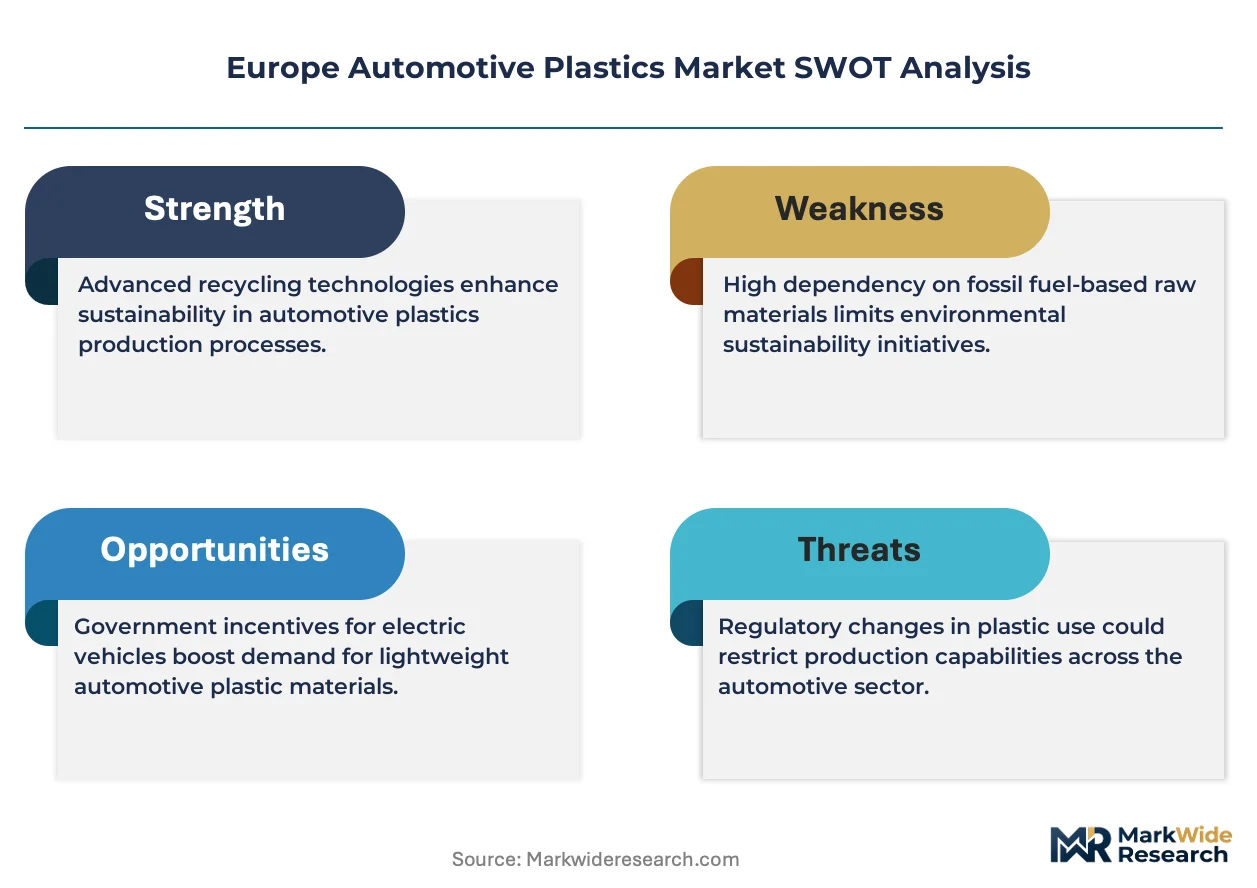
The Europe automotive plastics market functions as a stable compounder anchored by EU Green Deal CO2 mandates that lock in material substitution programs across German OEM platforms.
For Market Incumbents: Deploy captive resin integration to defend margin position against feedstock volatility. BASF's Ludwigshafen model demonstrates how backward integration into naphtha cracking insulates compounders from Brent crude swings. Incumbents should simultaneously pre-qualify phosphorus-based flame retardant formulations ahead of ECHA's persistent organic pollutant phase-outs.
For New Entrants and Emerging Players: Enter via Slovakia and Czech Republic assembly corridors where local compounding capacity remains underdeveloped relative to Volkswagen Poznań and Stellantis Tychy production volumes. New entrants should target post-consumer recycled content certification for dashboard carrier programs, leveraging EU End-of-Life Vehicle Directive incentives as the go-to-market wedge.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier compounders lack lifecycle assessment competency for OEM sustainability scorecards. The acquisition target archetype combines mass balance certification chains with Eastern European manufacturing presence. Watch for EMA polymer safety assessment delays as the signal indicating which resin grades retain market access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Naphtha Cracking | BASF's Ludwigshafen complex demonstrates feedstock cost control for Wolfsburg supply. |
| Phosphorus-Based Flame Retardant Qualification | ECHA restrictions on brominated alternatives force reformulation investment cycles. |
| Eastern European Compounding Capacity | Slovakia and Czech Republic assembly plants lack local glass-reinforced supply. |
| Post-Consumer Recycled Content Certification | EU End-of-Life Vehicle Directive revisions reward circular economy integration. |
| Long-Fiber Thermoplastic Process Licensing | German OEMs accelerate crash-critical metal replacement qualification timelines. |
Research Methodology
Multiple input streams — primary interviews with Tier 1 supplier procurement directors, OEM platform engineers, and aftermarket distributors; secondary validation through vehicle production databases, customs trade flows, and SEC filings from listed compounders; and technical literature from ECHA substance registrations — were reconciled through bottom-up volume modeling and top-down value triangulation.
Data-stream reconciliation across the projection horizon applied segmentation dimensions spanning polymer grade tier, end-use application thermal load, vehicle propulsion architecture, and regional production cluster concentration. CAGRs were derived from fitted growth curves incorporating EU fleet CO2 target compliance deadlines and electric vehicle platform rollout schedules as structural demand drivers.
Inputs from OEM sustainability scorecard disclosures and EMA polymer safety assessments were available through the study window; gaps in real-time compounding capacity utilization data introduce uncertainty bands around Eastern European expansion forecasts. Material deviation in REACH substance authorization timelines or Brent crude volatility spikes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Sheet Molding Compound (SMC) for Automotive Market
Automotive Components
Automotive Hubcaps Market
Automotive Components
Global Automotive Condenser Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Automotive Sunroof Glass Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
Canada Automotive Glass Fiber Composites Market
Automotive Components
Automotive Active Bonnet Market
Automotive Components
Europe Automotive Heat Exchanger Market
Automotive Components
Automotive Camshaft Phase Variator Market
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
Automotive Evaporative Emission Control (EVAP) System Market
Automotive Components
India Automotive Heat Exchanger Market
Automotive Components
Saudi Arabia Automotive Actuators Market