
 Automotive Active Bonnet Market | 2026-2036
Automotive Active Bonnet Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Active Bonnet Market Analysis
Electromechanical engineering talent scarcity is collapsing development timelines for next-generation pedestrian protection systems. Bosch leverages its integrated sensor-to-actuator architecture to sustain technology leadership in mechatronic bonnet deployment. Continental competes through software algorithm refinement that differentiates its collision detection response latency. ZF Friedrichshafen anchors European supply relationships with Tier-1 vehicle assemblers seeking hydraulic system reliability.
An automotive active bonnet is a deployable hood structure incorporating pyrotechnic or spring-loaded actuators, multi-axis accelerometers, and predictive control modules that elevate the bonnet surface within milliseconds of pedestrian contact detection to reduce head impact severity. The system operates through real-time sensor fusion processing at sub-100-millisecond thresholds to create critical deformation space between rigid engine bay components and the outer panel. Active Systems command the dominant value share due to their complex actuator assemblies and control unit integration requirements, while Sensors represent the fastest-expanding margin pool as OEMs demand higher-resolution pedestrian detection capabilities. OEMs constitute the primary demand channel, though Aftermarket Providers are gaining structural relevance as retrofit regulations extend to commercial vehicle segments in select jurisdictions.
Euro NCAP testing protocols, the EU General Safety Regulation, and the UN ECE R127 pedestrian safety standard collectively mandate measurable head impact criteria that OEMs address through active bonnet deployment. The EPA and NHTSA in the United States maintain parallel regulatory pressure through Federal Motor Vehicle Safety Standard pedestrian protection guidelines and corporate average fuel economy considerations that influence bonnet weight and actuator design. Stakeholders must monitor algorithm validation requirements and cross-border homologation timelines as regulatory divergence between European and North American testing methodologies intensifies compliance complexity.
Market Dynamics
Electromechanical engineering talent scarcity is compressing development timelines for pedestrian protection systems, forcing OEMs to consolidate supplier relationships around vertically integrated mechatronic specialists capable of delivering sensor-to-actuator architectures under unified program management.
Growth Catalysts
- Euro NCAP pedestrian protection protocols:Germany's KBA and the United Kingdom's Vehicle Certification Agency mandate measurable head impact criteria that OEMs address through active bonnet deployment in luxury passenger segments.
- Spring-loaded actuator advancement:Pyrotechnic alternatives face regulatory scrutiny for deployment reliability, accelerating OEM preference for mechanical systems with predictive control modules.
- Western European regulatory concentration:The EU General Safety Regulation and UN ECE R127 standard create synchronized compliance requirements across Germany, France, and Italy that standardize procurement specifications.
Market Restraints
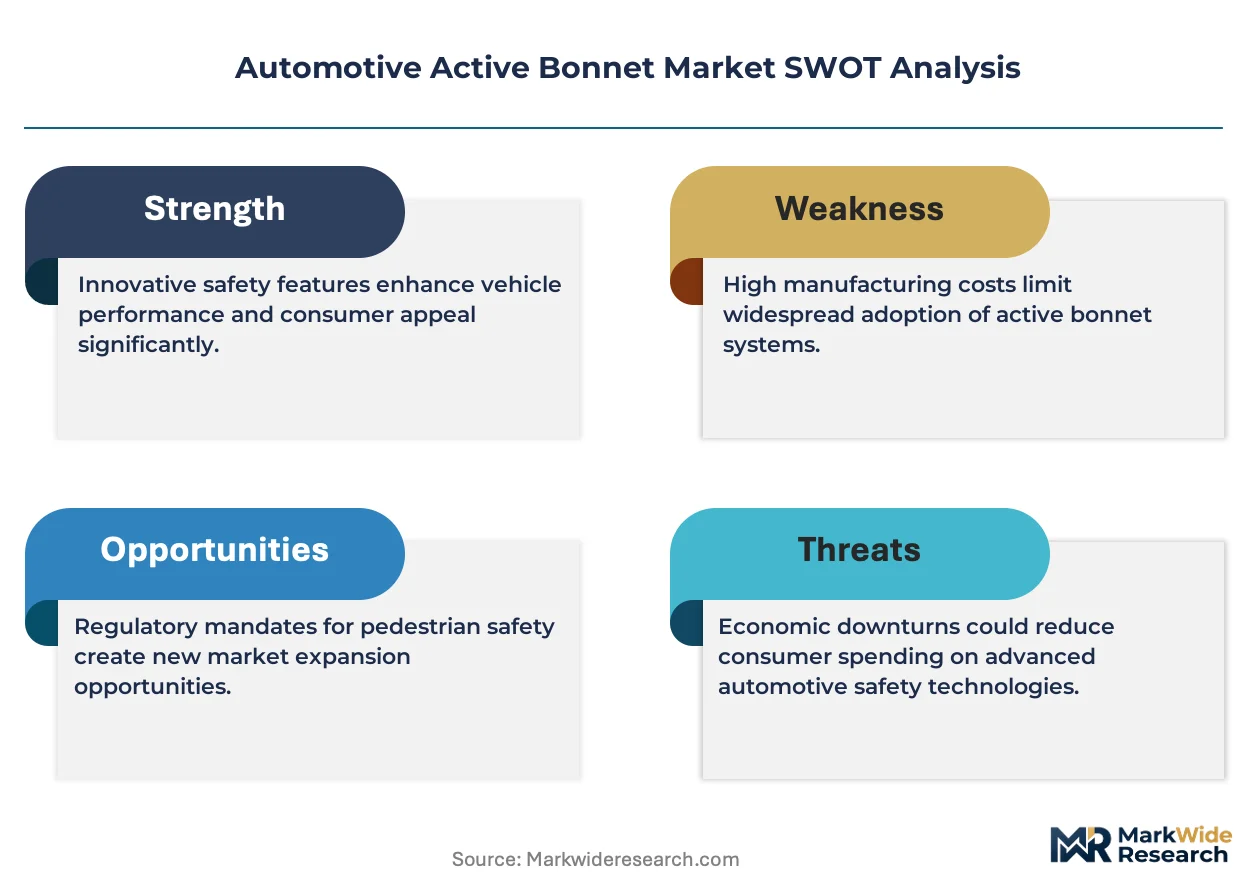
- Electromechanical talent scarcity:Sub-100-millisecond sensor fusion engineering expertise concentrates in Stuttgart, Munich, and Wolfsburg, limiting supplier scalability.
- Hydraulic system input cost volatility:Precision-machined actuator housings and high-pressure sealing components face commodity price pressure from specialized steel alloys.
- Cross-border homologation friction:Divergence between Euro NCAP testing methodologies and NHTSA Federal Motor Vehicle Safety Standard guidelines forces dual validation programs.
Strategic Opportunities
- Commercial vehicle retrofit mandates:Select European jurisdictions are extending pedestrian protection requirements to urban delivery fleets, opening aftermarket channels previously confined to passenger OEMs.
- Sensor-to-cloud convergence:Integration of multi-axis accelerometers with vehicle-to-infrastructure communication modules enables predictive deployment before pedestrian contact.
- Eastern European manufacturing expansion:Czech Republic and Poland assembly plants seek localized active bonnet supply to avoid intra-EU logistics penalties under CSRD scope 3 reporting.
Industry Challenges
- Algorithm validation timeline compression:UN ECE R127 certification requires extensive real-world pedestrian contact simulation that strains computational validation resources.
- Legacy powertrain integration complexity:Internal combustion engine bay packaging constraints limit deformation space architecture compared to electric vehicle platforms with front-trunk configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Active Bonnet Market |
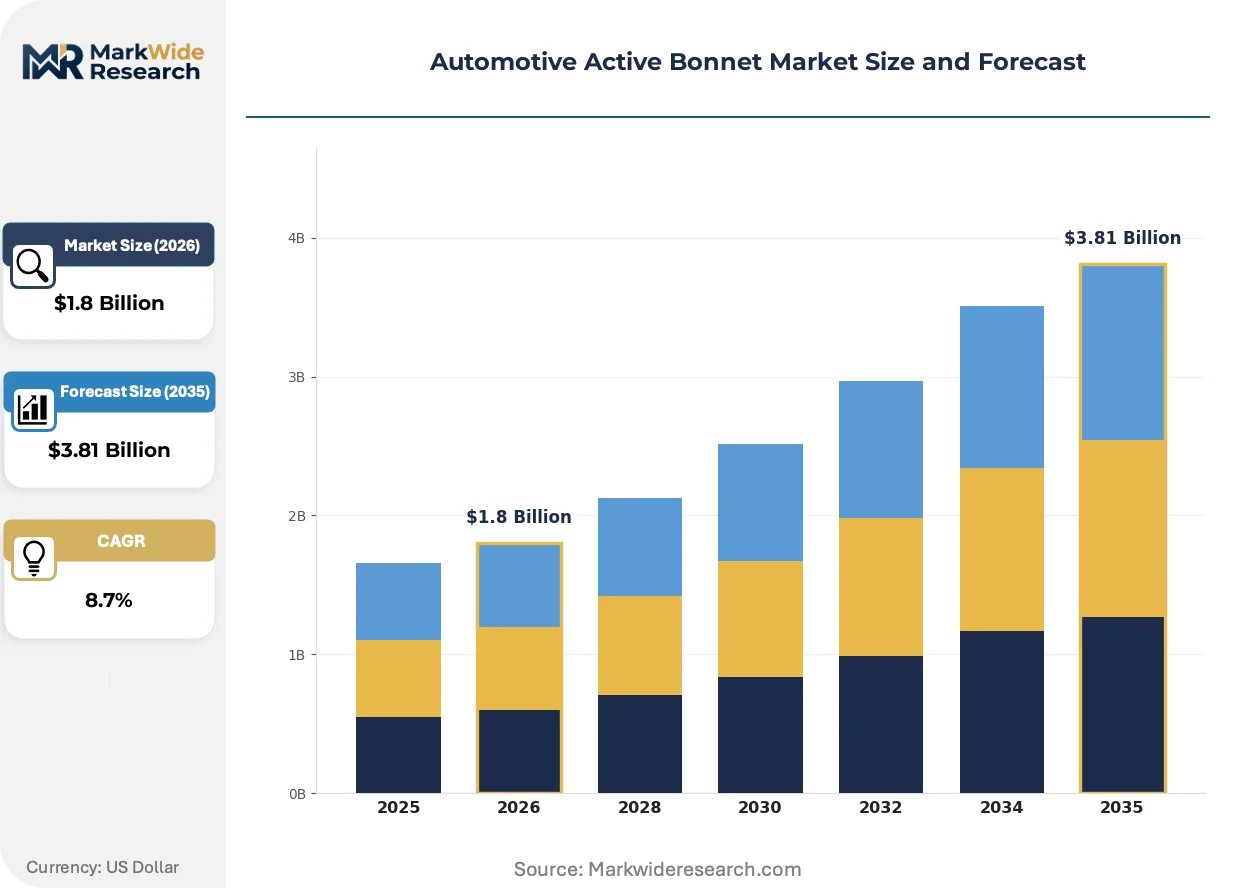
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Systems, Active Systems, Sensors, Control Units End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Application: Pedestrian Safety, Collision Avoidance, Impact Mitigation, Emergency Response Technology: Mechatronics, Electronics, Software Algorithms, Hydraulic Systems |
| Companies Covered | Bosch, Delphi Technologies, Autoliv, Aisin Seiki, Magna International, ZF Friedrichshafen, TRW Automotive, Denso, Continental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Active Bonnet Market Emerging Trajectories
Predictive collision detection architectures are redefining competitive positioning in pedestrian protection, compressing response latency thresholds while expanding the addressable incident envelope beyond direct contact scenarios.
Capacitive proximity sensing arrays integrated with thermal imaging overlays are supplanting pure inertial measurement unit dependency for pedestrian classification. Luxury German OEMs have accelerated fitment of fused-sensor configurations across their executive sedan portfolios. This convergence is supplanting single-modality systems in premium segments and compressing price differentiation between active bonnet tiers.
The EU General Safety Regulation's phased implementation through 2026 mandates automatic emergency braking and vulnerable road user detection as standard equipment. This regulatory architecture forces powertrain-agnostic platform engineering that accommodates active bonnet deployment across internal combustion and battery-electric variants. Western European OEMs are responding by consolidating pedestrian protection program ownership under centralized safety system divisions rather than body engineering silos.
Fleet procurement departments are unbundling active bonnet specification from bundled safety packages, creating direct supplier engagement channels previously intermediated by Tier-1 integrators. Large German commercial fleet operators now issue standalone requests for quotation on pedestrian protection subsystems. This pattern is most visible in urban logistics segments operating under municipal low-emission zone access requirements that prioritize safety certification for operating permits.
Automotive Active Bonnet Market Segmentation
Active bonnet procurement patterns diverge sharply between integrated OEM platforms and fragmented aftermarket channels, with technology choices dictating supplier consolidation strategies across European vehicle assembly networks.
Product Type:
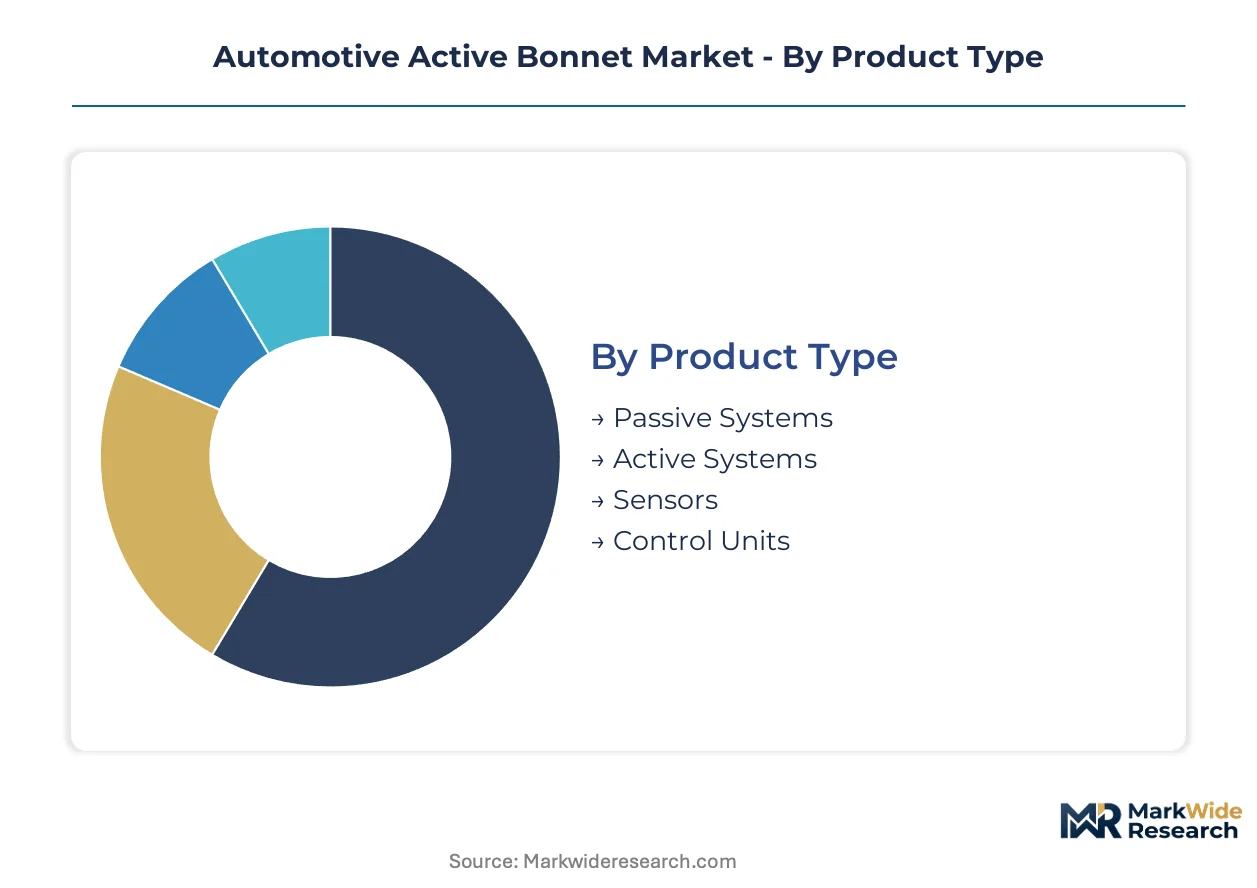
German luxury OEMs dominate demand for Active Systems and Sensors, while Passive Systems concentrate in cost-optimized Southern European vehicle programs.
- Active Systems:Deployable hood structures incorporate pyrotechnic or spring-loaded actuators with real-time sensor fusion processing. Stuttgart-based vehicle manufacturers specify these for executive sedans facing Euro NCAP pedestrian protection protocols. Actuator assembly complexity sustains premium pricing tiers.
- Sensors:Multi-axis accelerometers and capacitive proximity arrays enable sub-100-millisecond detection thresholds. Czech Republic and Poland assembly plants source these for localized supply chain compliance under CSRD scope 3 reporting requirements. Resolution demands are climbing fastest in this category.
- Passive Systems:Fixed deformation structures without active deployment mechanisms serve budget vehicle segments in Italy and Spain.
- Control Units:Predictive algorithm modules process collision detection inputs for unified mechatronic architectures.
Active Systems holds the largest share; momentum sits with Sensors.
End User:
Procurement authority is shifting from bundled Tier-1 packages toward direct OEM safety system divisions and standalone fleet operator specifications.
- OEMs:Centralized safety engineering divisions now own pedestrian protection program ownership across powertrain platforms. BMW and Mercedes-Benz integrate active bonnet specification at the vehicle architecture stage rather than body engineering silos. Regulatory convergence across EU General Safety Regulation timelines standardizes their procurement.
- Aftermarket Providers:Urban logistics fleet operators in Germany and the Netherlands issue standalone RFQs for retrofit pedestrian protection. Municipal low-emission zone access permits increasingly mandate safety certification independent of OEM channels. Commercial vehicle retrofit regulations are unlocking this segment.
- Vehicle Assemblers:Eastern European manufacturing plants seek localized supply to avoid intra-EU logistics penalties.
- Tier-1 Suppliers:Bosch, Continental, and ZF Friedrichshafen intermediate system integration for legacy OEM relationships.
OEMs command dominant procurement volume; aftermarket channels are expanding most quickly.
Application:
Regulatory mandates concentrate investment in Pedestrian Safety while algorithm advancement extends addressable incident envelopes.
- Pedestrian Safety:UN ECE R127 certification requirements drive measurable head impact criteria engineering. KBA and the United Kingdom's Vehicle Certification Agency enforce deployment reliability standards that shape system architecture choices. This application absorbs the majority of active bonnet program budgets.
- Collision Avoidance:Vehicle-to-infrastructure communication modules enable predictive deployment before physical contact. German OEMs pilot these fused-sensor configurations in urban autonomous driving test fleets. Response latency compression defines competitive positioning here.
- Impact Mitigation:Deformation space creation between engine bay components and outer panels addresses secondary collision consequences.
- Emergency Response:Post-collision bonnet positioning assists first responder access to battery-electric vehicle front compartments.
Pedestrian Safety represents the largest application segment; Collision Avoidance shows the steepest expansion trajectory.
Technology:
Mechatronics and Software Algorithms concentrate engineering talent scarcity, while Hydraulic Systems anchor established European supply relationships.
- Mechatronics:Integrated sensor-to-actuator architectures unify electromechanical deployment under single program management. Bosch leverages this vertical integration to sustain technology leadership against algorithm-focused competitors. Stuttgart and Munich engineering clusters dominate capability concentration.
- Software Algorithms:Collision detection response latency differentiation drives Continental's competitive positioning. Real-time pedestrian classification through thermal imaging overlays supplants pure inertial measurement dependency. Computational validation resources strain under UN ECE R127 certification timelines.
- Electronics:Control module miniaturization accommodates powertrain-agnostic platform engineering requirements.
- Hydraulic Systems:Precision-machined actuator housings face input cost volatility from specialized steel alloy commodity markets.
Mechatronics captures the dominant technology share; Software Algorithms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
KBA enforces Euro NCAP pedestrian protection protocols that concentrate active bonnet demand in Germany's luxury vehicle manufacturing corridor. United Kingdom regulators mirror these standards through the Vehicle Certification Agency. France, Italy, and Czech Republic assembly networks complete the European regulatory perimeter that shapes procurement geography.
Germany
Stuttgart-based OEMs specify active bonnet systems for executive sedans facing KBA certification timelines. The EU General Safety Regulation mandates automatic vulnerable road user detection through 2026 implementation phases. Munich and Wolfsburg engineering clusters concentrate electromechanical talent for sensor-to-actuator architecture development.
United Kingdom
The Vehicle Certification Agency enforces measurable head impact criteria that drive fitment across British luxury passenger segments. UN ECE R127 certification requirements standardize deployment reliability testing for domestic vehicle programs. London-based fleet operators now issue standalone RFQs for pedestrian protection retrofitting in urban logistics vehicles.
France
French OEMs integrate active bonnet specification at the vehicle architecture stage under centralized safety engineering divisions. REACH compliance frameworks influence material selection for precision-machined actuator housings. Lyon and Paris manufacturing corridors source localized sensor assemblies to minimize intra-EU logistics exposure under CSRD scope 3 reporting.
Italy
Italian vehicle programs concentrate passive system demand in cost-optimized segments while active bonnet penetration climbs in premium Turin and Milan manufacturing networks. ECHA substance restriction protocols shape pyrotechnic actuator material compliance. Southern European procurement patterns favor mechanical spring-loaded alternatives facing regulatory reliability scrutiny.
Czech Republic
Czech assembly plants seek localized active bonnet supply to avoid logistics penalties under tightening EU carbon accounting frameworks. Skoda Auto and regional OEM partnerships drive sensor procurement for powertrain-agnostic platform engineering. Brno and Prague industrial zones anchor Eastern European manufacturing expansion for Western European vehicle certification compliance.
Automotive Active Bonnet Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in active bonnet system supply. Vertically integrated mechatronic specialists capture dominant value share through unified sensor-to-actuator program management. Algorithm-focused competitors differentiate through collision detection response latency refinement. Hydraulic system specialists anchor established European supply relationships with legacy OEM networks. Consolidation pressures intensify as talent scarcity forces supplier relationship rationalization around unified architectures.
Among Germany-based integrated specialists, Bosch and ZF Friedrichshafen exemplify the vertically consolidated archetype that dominates European OEM relationships. Continental occupies a position within the algorithm-focused tier competing through software differentiation rather than electromechanical integration. These three anchors represent the structural concentration that defines competitive positioning in pedestrian protection system supply.
| Leading Market Players |
|---|
| Bosch |
| Delphi Technologies |
| Autoliv |
| Aisin Seiki |
| Magna International |
| ZF Friedrichshafen |
| TRW Automotive |
| Denso |
| Continental |
| Others |
Supply Flow & Price Mechanics
Spring-loaded actuator replacement of pyrotechnic alternatives is redrawing supplier geography across the Czech Republic and Poland while compressing margin structures for precision-machined housing producers in Germany. This substitution dynamic simultaneously elevates mechanical system procurement in Eastern European assembly networks and intensifies price competition among Stuttgart and Munich engineering clusters defending legacy actuator contracts.
Pricing Analysis
Western European markets command 40-60% premiums over Eastern European procurement for identical sensor-to-actuator configurations. Three-tier pricing structure across premium, standard, and economy levels separates KBA-certified systems from UN ECE R127 baseline configurations and non-certified retrofit alternatives. Cost compression in economy tiers is intensifying because Czech and Polish plants exploit localized supply chain compliance under CSRD scope 3 reporting. Aftermarket fleet operators exhibit highest price sensitivity; luxury OEM platform engineers demonstrate lowest sensitivity due to bundled safety system procurement authority.
Supply Chain Analysis
Germany and the Czech Republic anchor precision-machined actuator housing production for European OEM networks. Supply chains draw from specialized steel alloy feedstock, high-pressure sealing component foundries, and multi-axis accelerometer fabrication facilities in South Korea and Japan. Single-source vulnerability concentrates in electromechanical engineering talent pools across Stuttgart, Munich, and Wolfsburg. Distribution runs through Tier-1 integrator channels for legacy OEM relationships and direct supplier engagement for unbundled fleet procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent suppliers must navigate software-defined vehicle architectures that threaten to displace discrete active bonnet control units with centralized computing platforms. This substitution defense requires preemptive positioning in predictive collision detection algorithms and sensor-to-cloud convergence pathways.
For Market Incumbents: Shield algorithm validation capabilities against emerging software-focused competitors by deepening in-house production of predictive control modules. Consolidate backward integration into capacitive proximity sensing arrays to reduce dependency on external semiconductor suppliers. Prioritize certification investment in UN ECE R127 real-world pedestrian contact simulation resources to compress competitor timeline advantages.
For New Entrants and Emerging Players: Lead with aftermarket retrofit channels in German and Dutch urban logistics fleets where municipal low-emission zone access permits mandate standalone safety certification. Target commercial vehicle segments previously intermediated by Tier-1 integrators with direct RFQ engagement models. Exploit algorithm-focused positioning in collision avoidance applications where response latency differentiation commands premium positioning.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mechatronic specialists holding captive Stuttgart engineering talent pools. Long-term viability hinges on sensor-to-actuator architecture consolidation rather than discrete component supply. Watch for inflection signals in vehicle-to-infrastructure communication module integration rates that indicate predictive deployment technology maturation.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-to-Actuator Architecture Consolidation | Unifies electromechanical deployment under Bosch and ZF Friedrichshafen program management against algorithm-focused competitors. |
| Predictive Collision Detection Investment | Compresses response latency thresholds below Continental's current software differentiation in German autonomous test fleets. |
| Eastern European Manufacturing Footprint | Localizes supply for Czech and Polish assembly plants avoiding CSRD scope 3 logistics penalties under tightening EU carbon accounting. |
| Aftermarket Channel Direct Engagement | Bypasses Tier-1 integrators for German fleet operator RFQs in urban logistics segments requiring safety certification. |
| Algorithm Validation Resource Expansion | Accelerates UN ECE R127 certification timelines that strain computational resources across Stuttgart engineering clusters. |
Methodological Framework
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, aftermarket fleet operators, and KBA certification specialists and refined through secondary validation. Primary fieldwork combined structured interviews with vehicle safety system directors at Stuttgart and Munich manufacturers with channel partner discussions across German and Czech distribution networks. Secondary sources encompassed vehicle production databases, Euro NCAP testing protocol documentation, UN ECE R127 regulatory filings, and IHS Markit registration data. Bottom-up segment sizing triangulated against top-down market consolidation estimates.
Variance decomposition across the projection horizon isolates volume drivers from pricing dynamics and technology substitution effects. Segmentation dimensions encompassed product type, end-user procurement channel, application priority, and technology architecture across powertrain-agnostic platform engineering requirements. CAGRs were derived from segment-level growth trajectory analysis calibrated to regulatory implementation timelines. Industry-specific inputs included KBA certification schedule adherence and CSRD scope 3 reporting compliance thresholds.
The analysis sits within stated boundaries; outcomes outside sustained Euro NCAP pedestrian protection protocol enforcement or accelerated software-defined vehicle platform adoption would require recalibration. Forecasts reflect assumptions regarding electromechanical engineering talent availability and specialized steel alloy input cost stability. Recalibration cycles align with material shifts in EU General Safety Regulation implementation phases and cross-border homologation methodology convergence.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Automated Lubrication Systems Market
Automotive Components
Automotive Towbar Market
Automotive Components
Automotive Exhaust Components Aftermarket Market
Automotive Components
Automobile Fluid Pipe Products Market
Automotive Components
Automotive Solenoid Valve Market
Automotive Components
Automotive Chromium Market
Automotive Components
Asia Pacific Automotive Bearing Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
North America Automotive Hydraulic Actuators Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Germany Automotive Composites Market
Automotive Components
South Korea Automotive Pneumatic Actuators Market
Automotive Components
Automotive Straps Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Automotive Wiper Blades Market