
 Automotive Solar Control Glass Market | 2026-2036
Automotive Solar Control Glass Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Solar Control Glass Market Analysis
A capital-intensity divergence between float-glass furnace operators and thin-film coating specialists is reorganizing competitive tiers in automotive glazing. Saint-Gobain leverages integrated float and magnetron-sputtering capacity across European plants. Guardian Glass anchors North American supply through large-scale tempering lines serving Detroit-area OEMs. Xinyi Glass Holdings competes on cost-optimized laminated output for Asia-based vehicle assemblers.
Automotive solar control glass incorporates metallic oxide or dielectric interference layers deposited onto flat glass substrates, typically achieving solar heat gain coefficients below 0.40 while maintaining visible light transmission above 70 percent for driver visibility compliance. Laminated glass with interlayer-absorbing technology leads volume shipments due to mature supply chains and crash-safety integration, while electrochromic variants represent the fastest-growing technology segment as OEMs seek dynamic tinting for panoramic EV roofs. Conventional coated glass still occupies the largest margin pool in aftermarket channels where retrofit demand sustains premium pricing.
The EPA enforces fuel-economy standards that indirectly mandate solar-load reduction through glazing performance, while Europe's F-Gas Regulation restricts high-global-warming-potential blowing agents in glass spacer systems. Japan's METI promotes next-generation vehicle energy-efficiency targets that encompass cabin thermal management. Stakeholders must monitor evolving OEM specifications for electrochromic integration and assess backward integration into sputtering-target supply as coating complexity intensifies.
Market Dynamics
Electrochromic integration into panoramic EV roof systems is compressing development cycles and forcing coating specialists to recalibrate sputtering-target supply chains for dynamic-tint architectures.
Growth Catalysts
- EPA fuel-economy mandates:Solar-load reduction requirements embedded in Corporate Average Fuel Economy standards compel Detroit-area OEMs to specify low-SHGC glazing for cabin thermal management.
- Japan METI next-generation vehicle targets:Energy-efficiency frameworks encompassing cabin climate control accelerate laminated glass with infrared-absorbing interlayers in domestic EV production.
- Panoramic roof proliferation:Glass surface area per vehicle is expanding as premium EV architectures prioritize cabin openness, multiplying coated surface requirements per unit.
Market Restraints
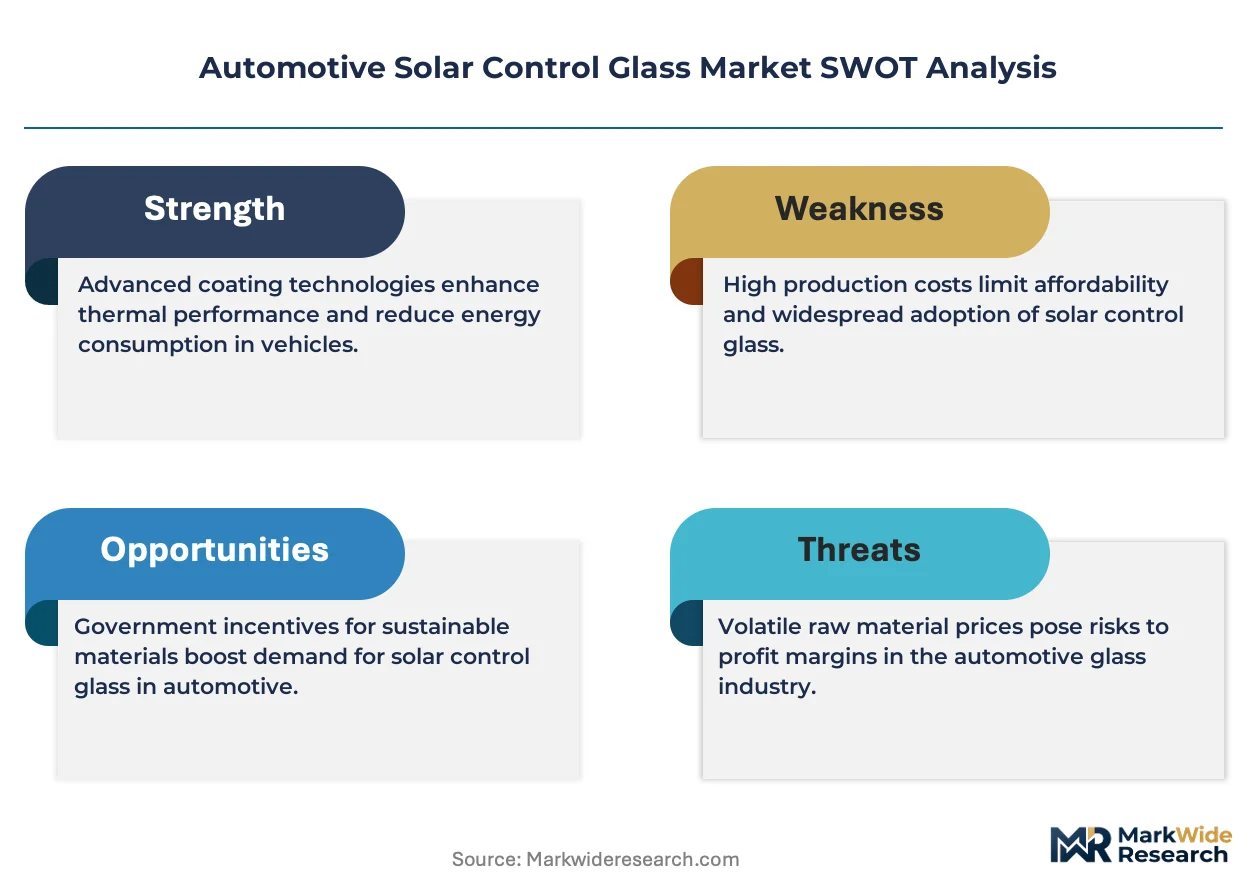
- Silver price volatility:Magnetron-sputtering processes rely on silver-based metallic oxide layers, exposing coating specialists to precious metal input cost swings.
- Float-glass furnace concentration:Primary flat glass supply clusters in China and Southeast Asia, creating geographic single-source vulnerability for European and North American coaters.
- Electrochromic durability thresholds:Switching cycle longevity in extreme temperature cycling remains below automotive-grade reliability standards, delaying mass deployment.
Strategic Opportunities
- India PLI scheme for advanced automotive components:Domestic manufacturing incentives for EV ecosystems create localized glazing demand as Tata Motors and Mahindra expand electric portfolios.
- Aftermarket retrofit channels:Independent installers in Sun Belt US states represent underserved demand for solar-control windscreen replacements as vehicle age extends.
- Building-integrated photovoltaics convergence:Automotive coating expertise in dielectric interference layers transfers to architectural BIPV applications, opening adjacent revenue streams.
Industry Challenges
- Sputtering-target metallurgist scarcity:Rare earth and noble metal alloy formulation expertise concentrates in German and Japanese supplier bases, constraining coating line expansion.
- Dual certification timelines:Simultaneous ECE R43 and FMVSS 205 compliance for laminated variants extends product validation cycles by eight to fourteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Solar Control Glass Market |
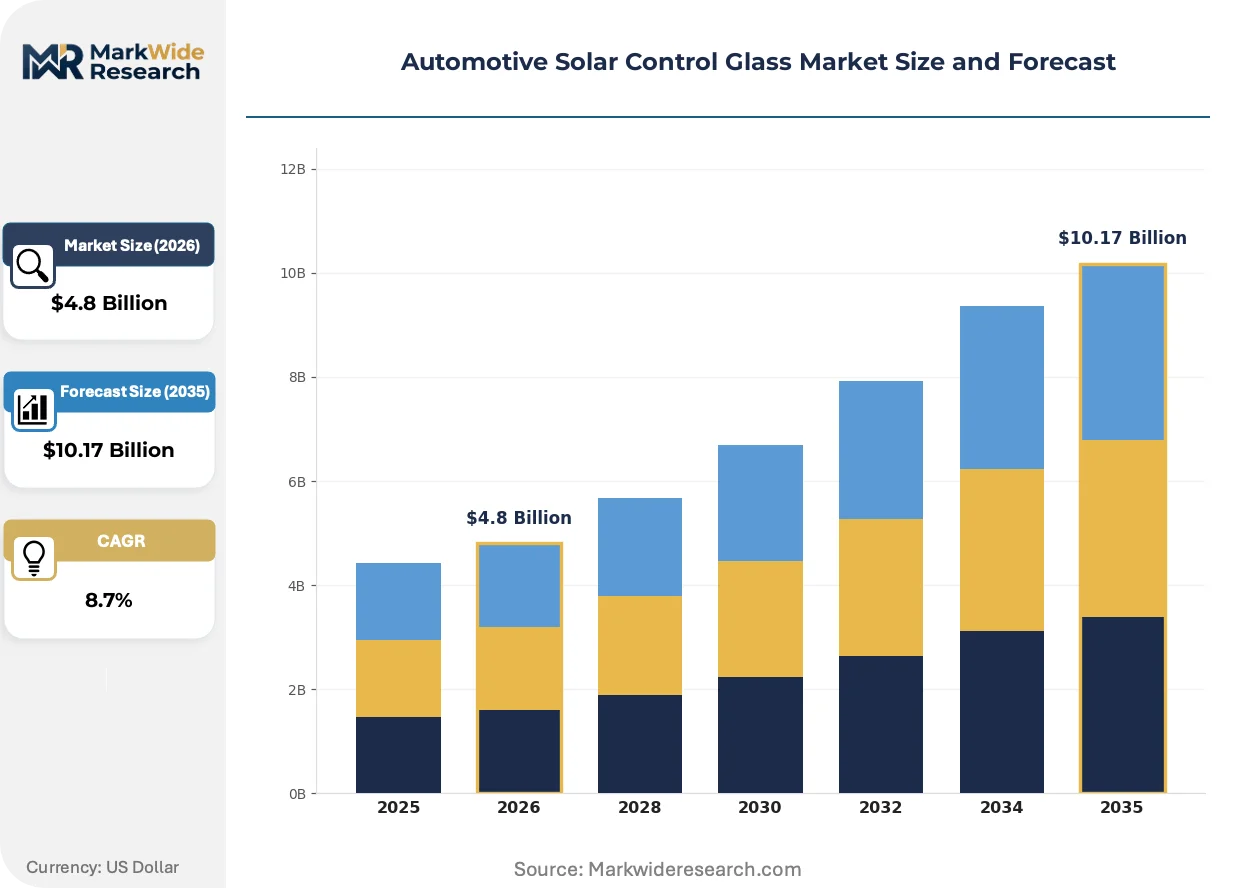
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Temperable Glass, Laminated Glass, Coated Glass, Polycarbonate Application: Passenger Vehicles, Commercial Vehicles, Luxury Vehicles, Electric Vehicles Technology: Electrochromic, Thermochromic, Photochromic, Conventional End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Guardian Glass, Nippon Sheet Glass, Saint-Gobain, Xinyi Glass Holdings, Schott AG, AGC Automotive, PPG Industries, Asahi Glass, NSG Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Solar Control Glass Market Emerging Trajectories
Coating complexity is bifurcating the supply base between integrated float-coat operators and specialized thin-film technology licensors, with electrochromic functionality emerging as the primary axis of differentiation.
Magnetron-sputtered multilayer stacks incorporating silver and dielectric oxides are fragmenting the competitive landscape between incumbent coated-glass producers and electrochromic specialists. European premium OEMs are adopting dynamic-tint skylights at prototype scale. This technology is fragmenting procurement patterns as buyers split contracts between static-coated base volumes and electrochromic premium tiers.
Europe's F-Gas Regulation restrictions on high-GWP blowing agents in insulating glass spacer systems are reshaping laminated glass interlayer specifications. Manufacturers must reformulate polyvinyl butyral curing processes to comply with fluorinated gas phase-down schedules. German KBA type-approval procedures now incorporate spacer system carbon footprint documentation, affecting supplier qualification timelines.
Fleet procurement of solar-control glazing is consolidating through direct OEM supply agreements, displacing traditional aftermarket distributor networks for crash-replacement volumes. Large US rental and commercial fleet operators are negotiating multi-year windscreen supply contracts with tier-one laminators. This concentration is most visible in Texas and Florida markets where solar-load reduction delivers measurable fuel economy returns.
Automotive Solar Control Glass Market Segmentation
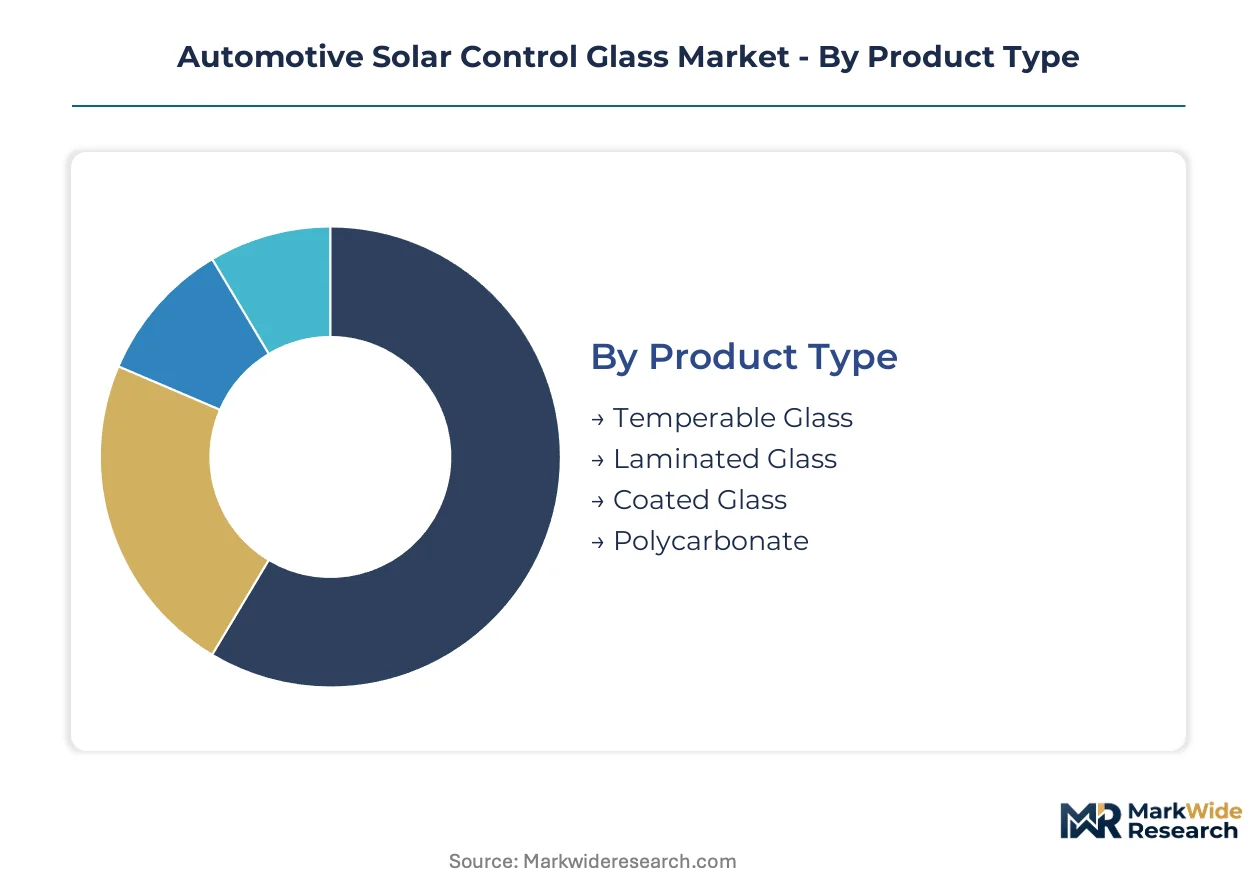
Automotive solar control glass segments distribute unevenly across procurement channels. OEM direct contracts dominate high-performance coated and electrochromic volumes, while aftermarket channels sustain replacement demand for conventional laminated products.
Product Type:
Laminated glass ships primarily through tier-1 supplier networks serving Detroit-area and Stuttgart-based OEM assembly plants. Temperable and coated variants flow through both captive OEM supply agreements and independent distributor channels.
- Laminated Glass:Polyvinyl butyral interlayers with infrared-absorbing additives block solar transmission while maintaining structural integrity for windscreen applications. Demand concentrates in premium passenger vehicle programs across Germany and Japan where OEMs prioritize crash safety alongside thermal management.
- Coated Glass:Magnetron-sputtered silver and dielectric oxide layers achieve sub-0.40 solar heat gain coefficients on float glass substrates. European coaters serving domestic EV manufacturers capture the margin-intensive volume as F-Gas Regulation compliance tightens interlayer specifications.
- Temperable Glass:Heat-strengthened substrates for side and rear glazing applications.
- Polycarbonate:Lightweight polymer alternatives for non-structural cabin glazing.
By volume, laminated glass leads. By growth pace, coated glass is ahead.
Application:
Segment economics diverge sharply by vehicle class procurement patterns. Luxury and electric vehicle programs command premium pricing for dynamic-tint technologies, while commercial fleet operators negotiate standardized static-coated specifications.
- Electric Vehicles:Panoramic roof architectures multiply coated surface area per unit as cabin openness becomes a competitive differentiator. Tesla, BYD, and Volkswagen Group programs across California, Shenzhen, and Lower Saxony drive specification intensity for electrochromic integration.
- Luxury Vehicles:Mercedes-Benz S-Class and BMW 7-Series programs incorporate switchable tint skylights at prototype scale. German KBA type-approval timelines for these dynamic systems extend validation cycles, compressing supplier development schedules.
- Passenger Vehicles:Mass-market internal combustion programs specify cost-optimized static coatings.
- Commercial Vehicles:Fleet operators in Texas and Florida prioritize solar-load reduction for fuel economy compliance.
Passenger vehicles anchor absolute volume. Electric vehicles are climbing the fastest.
Technology:
Technology tiers separate by manufacturing complexity and intellectual property concentration. Conventional sputtered coatings flow through established float-coat integrated plants, while electrochromic systems require specialized thin-film deposition expertise.
- Electrochromic:Tungsten oxide and nickel oxide thin-film stacks enable voltage-driven tint modulation across panoramic roof surfaces. Japanese and German coating specialists face durability threshold gaps as switching cycle longevity in extreme temperature cycling remains below automotive-grade reliability standards.
- Conventional:Static multilayer interference coatings dominate current production volumes through mature magnetron-sputtering infrastructure.
- Thermochromic:Temperature-responsive vanadium dioxide coatings for passive solar modulation.
- Photochromic:UV-triggered darkening technologies limited to aftermarket retrofit applications.
Conventional technology holds installed base dominance. Electrochromic systems show the steepest expansion trajectory.
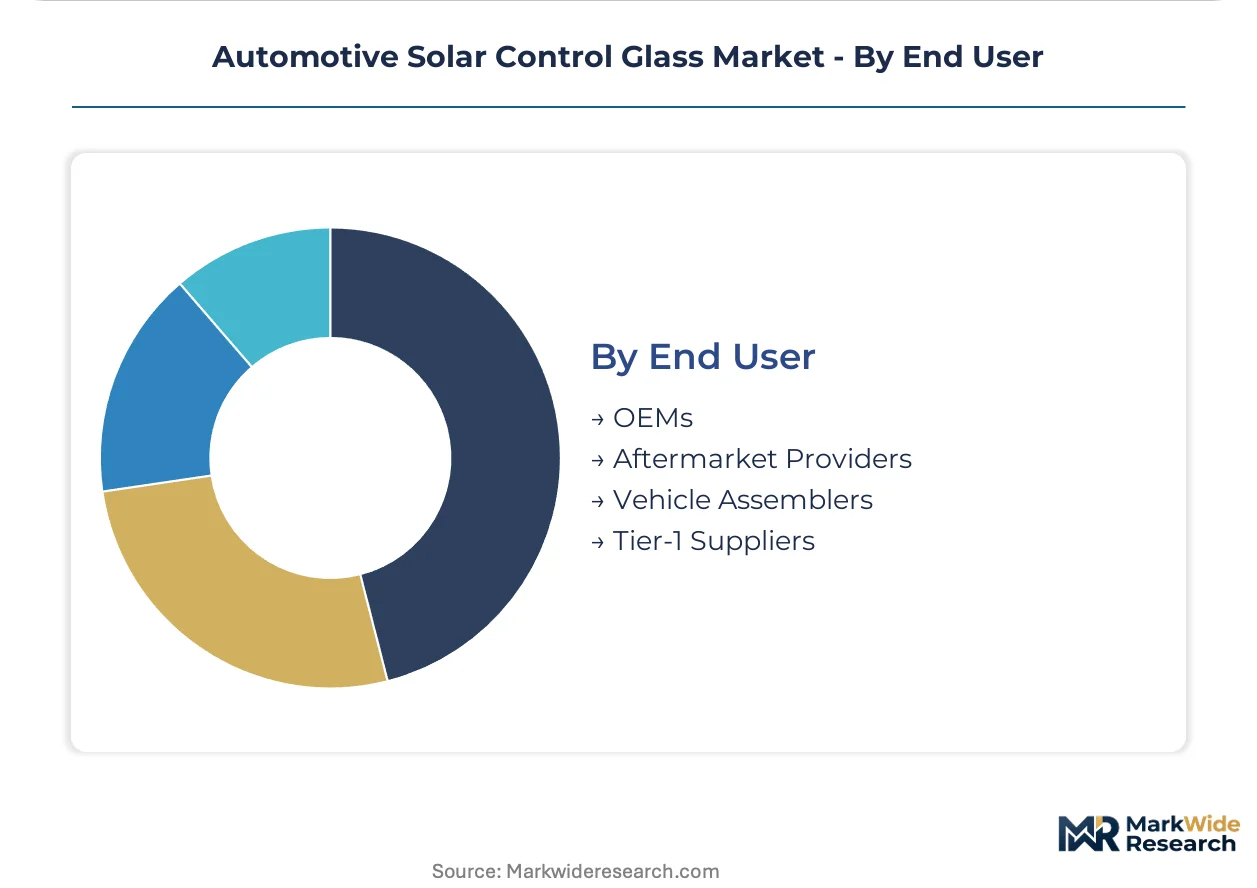
End User:
Procurement concentration is shifting toward direct OEM engagement as fleet operators consolidate windscreen replacement contracts. Tier-1 laminators and vehicle assemblers face margin compression from these volume aggregators.
- OEMs:Volkswagen Group, Toyota, and General Motors specify laminated and coated glass through multi-year supply agreements with integrated float-coat operators. EPA fuel-economy mandates and Japan METI energy-efficiency targets embed solar-load requirements directly into vehicle platform specifications.
- Aftermarket Providers:Independent installers in Sun Belt US states represent fragmented demand for crash-replacement and retrofit solar-control windscreens.
- Tier-1 Suppliers:Saint-Gobain Sekurit and Guardian Automotive intermediate between coaters and vehicle assembly plants.
- Vehicle Assemblers:Contract manufacturers in emerging EV production clusters.
OEMs command pricing power through volume consolidation. Aftermarket providers are gaining share fastest as vehicle age extends replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
European coaters command premium pricing through F-Gas Regulation compliance, while Chinese float-glass operators undercut on laminated output for Asia-based assemblers. This asymmetry is widening as energy-efficiency mandates tighten in Stuttgart and Wolfsburg while capacity expands in Shenzhen and Foshan.
United States
Detroit-area OEMs specify low-SHGC glazing under EPA Corporate Average Fuel Economy mandates. Texas and Florida fleet operators consolidate multi-year windscreen contracts for solar-load reduction. Guardian Glass anchors North American supply through large-scale tempering lines serving Michigan assembly plants.
Germany
Mercedes-Benz and BMW programs drive specification intensity for dynamic-tint skylights. KBA type-approval procedures now incorporate spacer system carbon footprint documentation under F-Gas Regulation phase-down schedules. Lower Saxony hosts Volkswagen Group EV platforms multiplying coated surface area per panoramic roof unit.
Japan
METI next-generation vehicle energy-efficiency targets accelerate laminated glass with infrared-absorbing interlayers. Toyota and domestic EV producers prioritize cabin thermal management in platform specifications. Kansai and Nagoya industrial corridors concentrate magnetron-sputtering expertise for dielectric oxide deposition.
China
BYD and Shenzhen-based EV assemblers expand glass surface area per vehicle through panoramic roof architectures. Dual carbon goals and provincial manufacturing incentives reshape coating line investment patterns. Yangtze River Delta float-glass furnace clusters create geographic concentration for cost-optimized laminated output.
India
PLI scheme incentives for advanced automotive components create localized glazing demand as Tata Motors and Mahindra expand electric portfolios. Domestic manufacturing mandates accelerate tier-1 laminator qualification timelines. Maharashtra and Gujarat vehicle assembly clusters absorb imported coating technology through joint venture structures.
Automotive Solar Control Glass Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Integrated float-coat operators leverage furnace scale and magnetron-sputtering capacity across European plants. Specialized thin-film coating specialists concentrate electrochromic intellectual property. Strategic moves center on backward integration into sputtering-target supply and geographic expansion into emerging EV production clusters.
Among European integrated operators, Saint-Gobain exemplifies the float-coat archetype through captive furnace and coating infrastructure. Guardian Glass occupies a position as the North American scale anchor serving Detroit-area OEM direct contracts. Xinyi Glass Holdings represents the cost-optimized laminated output model for Asia-based vehicle assemblers.
| Leading Market Players |
|---|
| Guardian Glass |
| Nippon Sheet Glass |
| Saint-Gobain |
| Xinyi Glass Holdings |
| Schott AG |
| AGC Automotive |
| PPG Industries |
| Asahi Glass |
| NSG Group |
| Others |
Supply Flow & Price Mechanics
Eight-to-fourteen-month dual certification timelines for ECE R43 and FMVSS 205 compliance compress supplier pricing power while concentrating procurement leverage among Detroit-area and Stuttgart-based OEMs with volume consolidation. This lead-time band forces coating specialists to absorb qualification costs upfront, eroding margins on initial contract wins while captive float-coat operators defend position through integrated furnace and sputtering capacity.
Pricing Analysis
Configured-to-order electrochromic glazing commands substantial premiums over static-coated base specifications as OEMs split procurement between premium dynamic-tint tiers and standardized laminated volumes. Price differentiation rests on certification grade and customization level, with KBA type-approval documentation and F-Gas Regulation compliance separating premium European coaters from cost-optimized Asian laminators. Cost compression in conventional coated segments is intensifying because silver price volatility in magnetron-sputtering processes squeezes coating specialist margins. Fleet operators in Texas and Florida exhibit highest price sensitivity through consolidated multi-year windscreen contracts, while German luxury EV programs show lowest sensitivity for electrochromic panoramic roof integration.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes elevates inbound logistics costs for European and North American coaters dependent on Chinese and Southeast Asian float-glass furnace output. Primary flat glass supply draws from China, Germany, and Japan, with magnetron-sputtering target formulation resting on rare earth and noble metal alloy expertise concentrated in German and Japanese supplier bases. Single-source vulnerability in float-glass furnace concentration creates geographic exposure for coating line expansion. Distribution runs through tier-1 laminator networks serving OEM direct contracts, with aftermarket channels fragmenting through independent installers in Sun Belt US states.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive solar control glass faces substitution pressure from advanced polycarbonate cabin glazing and aerodynamic active-shutter systems that reduce solar-load without coated surface area expansion. Incumbents must navigate this threat while defending margin position against integrated float-coat operators and electrochromic specialists.
For Market Incumbents: Fortify backward integration into sputtering-target supply chains to offset silver price volatility and rare earth alloy scarcity constraining coating line expansion. Secure captive furnace capacity in emerging EV production clusters through joint venture structures, particularly in India where PLI scheme incentives accelerate domestic manufacturing mandates. Defend against electrochromic substitution by embedding static-coated specifications into mass-market ICE platform designs before dynamic-tint durability thresholds achieve automotive-grade reliability standards. For New Entrants and Emerging Players: Certification fast-track through streamlined ECE R43 compliance offers entry path into European aftermarket retrofit channels underserved by incumbent distributor concentration. White-space targets include Sun Belt US states where vehicle age extension drives crash-replacement demand, and India where Tata Motors and Mahindra electric portfolio expansion outpaces qualified tier-1 laminator capacity. Penetrate through direct fleet procurement relationships bypassing traditional aftermarket distributor networks, emphasizing fuel economy documentation for Texas and Florida commercial operators. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because coating complexity bifurcation between integrated float-coat operators and specialized thin-film technology licensors creates acquisition targets with stranded electrochromic intellectual property. Target coating specialists with proven tungsten oxide and nickel oxide thin-film stack durability approaching automotive-grade switching cycle thresholds. Watch for electrochromic reliability standard achievement as inflection indicator triggering premium-tier procurement acceleration and margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sputtering-Target Supply | Captive rare earth alloy formulation reduces exposure to German and Japanese supplier concentration. |
| Electrochromic Durability Certification Investment | KBA type-approval for switching cycle longevity unlocks Mercedes-Benz and BMW panoramic roof programs. |
| Joint Venture Manufacturing in India | PLI scheme incentives and Maharashtra assembly clusters localize supply for Tata Motors electric expansion. |
| Fleet Direct Procurement Channel Development | Texas and Florida commercial operators consolidate multi-year contracts bypassing aftermarket distributors. |
| F-Gas Regulation Compliance Documentation | Spacer system carbon footprint records satisfy German KBA phase-down schedules for European OEM qualification. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, customs and trade flow records, and EPA fuel-economy compliance filings. Interviews with Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributor operations heads, and coating line metallurgists informed demand segmentation and technology adoption timelines. Bottom-up volume builds across laminated, coated, and electrochromic product tiers triangulate against top-down market value estimates derived from disclosed supply contract structures.
Segmentation dimensions modeled encompass vehicle propulsion architecture, glass content per vehicle, OEM tier positioning, and regional production cluster regulatory frameworks. CAGRs were derived from trend extrapolation of EPA Corporate Average Fuel Economy mandate stringency, METI next-generation vehicle target evolution, and panoramic roof penetration rates across premium EV platforms. Forecast inputs incorporate silver price volatility bands, float-glass furnace capacity expansion announcements, and electrochromic switching cycle durability improvement trajectories across the projection horizon.
Decision-makers should treat outputs as directional under base assumptions of sustained EPA fuel-economy mandate enforcement, F-Gas Regulation phase-down adherence, and electrochromic reliability threshold achievement within the modeling period; material deviation would warrant model refresh. Specific risk factors include tariff escalation on Chinese float-glass imports, precious metal supply disruption, and premature polycarbonate cabin glazing substitution. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Advanced Automotive Materials Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Europe Automotive Airfilters Market
Automotive Components
Automotive Active Suspension System Market
Automotive Components
Automotive Part Cleaners and Degreasers Market
Automotive Components
Automotive Wiper Blades Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Automotive Front-End Module (FEM) Market
Automotive Components
India Automotive Sunroof Market
Automotive Components
Global Automotive Pneumatic Valve Market
Automotive Components
Automotive Metal Stamping Market
Automotive Components
Morocco Automotive Lubricants Market
Automotive Components
Asia-Pacific Heat Shrink Tubing for Automotive Market
Automotive Components
Electric Vehicle Fluid Lubricants Market