
 Automotive Tailgate Market | 2026-2036
Automotive Tailgate Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Tailgate Market Intelligence
A shift from single-source component supply to multi-source procurement for tailgate systems is realigning OEM strategies. Magna International leverages its full-system assembly capabilities to secure large contracts with global automakers. Faurecia specializes in interior and seating integration alongside its tailgate mechanisms, offering a bundled solution. Gestamp Automoción competes on the basis of its advanced metal stamping and hot forming expertise for structural components.
An automotive tailgate is a hinged rear door providing access to a vehicle's cargo compartment. These components are typically constructed from steel, aluminum, or composite materials and can feature complex latching and power-actuation systems. Power tailgates represent the fastest-growing product type, driven by consumer convenience features in new passenger vehicles. While passenger vehicles constitute the largest application segment, pickups offer significant margin opportunities for ruggedized, high-load-capacity tailgate designs.
Regulatory compliance shapes product design, with mandates from bodies like the US NHTSA influencing latch strength and safety standards. In Europe, CE marking and related directives govern electronic components within power tailgates, while China's GB standards dictate material and performance requirements for market entry. A key decision for suppliers involves balancing investment in advanced composite materials against the cost-sensitivity of high-volume vehicle platforms.
Market Dynamics
The imperative to reduce vehicle weight to meet stringent global fuel economy and emissions standards is the central force shaping the automotive tailgate market. This pressure compels a move away from traditional steel constructions toward lighter, more advanced materials like aluminum and composites.
Growth Catalysts
- SUV and Crossover Proliferation:The sustained consumer shift toward SUVs and crossovers, which frequently feature larger and more complex tailgates, directly stimulates volume demand, particularly for value-added power liftgate systems.
- Lightweighting Mandates:Regulatory frameworks, including fuel economy standards in the United States and CO2 emissions targets in Europe, incentivize the adoption of lightweight materials, creating a strong pull for aluminum and composite tailgate structures.
- Chinese Market Scale:The immense scale of vehicle production in China provides a massive demand base for tailgate systems, with both domestic and global automakers localizing production to serve this critical market.
Market Restraints
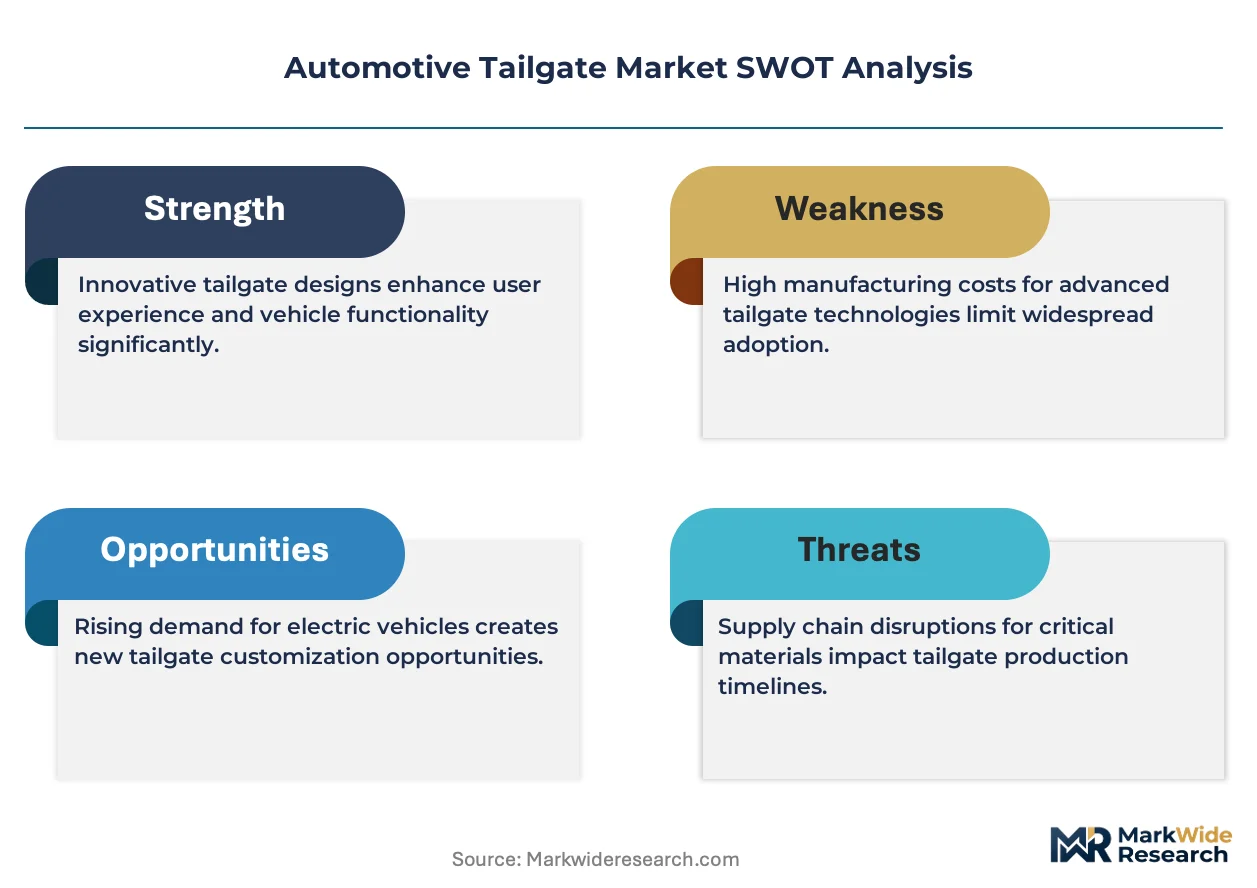
- Material Cost Premium:The higher per-kilogram cost of automotive-grade aluminum and carbon fiber composites compared to conventional steel presents a significant barrier to their widespread adoption in high-volume, cost-sensitive vehicle segments.
- Electronic Integration Complexity:Integrating sensors, actuators, and control modules for power tailgate systems introduces potential failure points and increases warranty risks for OEMs, complicating design and validation processes.
- Tooling and Forming Challenges:Advanced materials like hot-stamped boron steel and large composite panels require specialized, high-cost tooling and manufacturing processes, limiting supplier capacity and increasing capital expenditure hurdles.
Strategic Opportunities
- Light Commercial Vehicle Applications:Developing ruggedized, high-capacity, and multi-functional tailgates for the global pickup truck and light commercial vehicle segments offers a high-margin growth avenue beyond passenger cars.
- Smart System Integration:The convergence of gesture control, anti-pinch sensors, and vehicle-to-everything (V2X) connectivity creates opportunities for intelligent tailgate systems that enhance user safety and convenience.
- Hybrid Material Structures:Engineering multi-material tailgates that strategically combine steel, aluminum, and composites offers a pathway to achieve significant weight reduction at a more manageable cost point than all-composite solutions.
Industry Challenges
- Global Standards Harmonization:Suppliers face the operational challenge of designing and validating tailgate systems that simultaneously comply with divergent safety and electronic regulations, such as NHTSA standards in the US, CE marking in Europe, and GB standards in China.
- Capital-Intensive Manufacturing:The shift to new materials necessitates substantial capital investment in specialized production equipment, including large-tonnage stamping presses for aluminum and automated lines for composite molding, straining supplier finances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Tailgate Market |
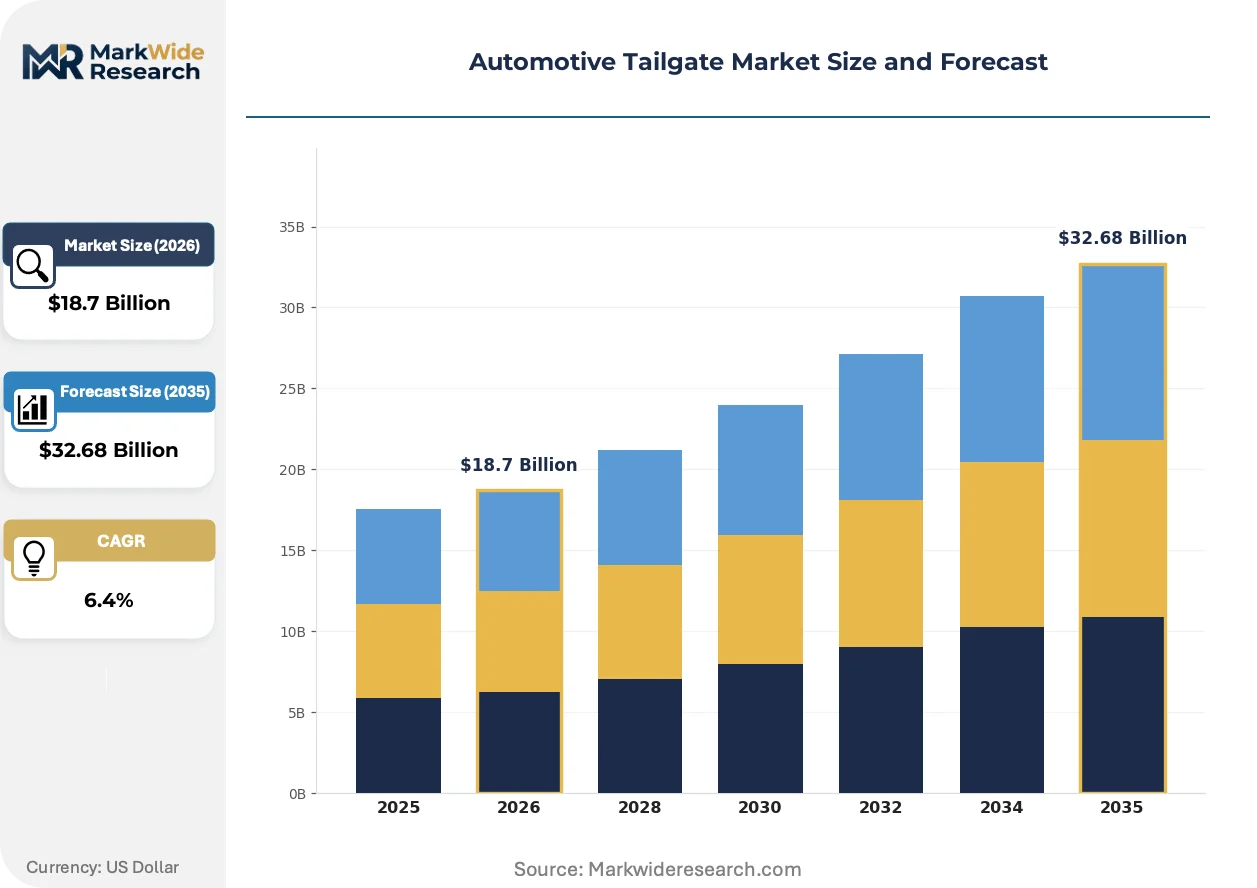
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Tailgate, Power Tailgate, Assisted Tailgate, Sport Tailgate Technology: Hydraulic Lift, Electric Motor, Pneumatic System, Mechanical Lever Application: Passenger Vehicles, Commercial Vans, Pickups, Utility Vehicles End User: OEMs, Aftermarket Retailers, Vehicle Assemblers, Tier-1 Suppliers |
| Companies Covered | Faurecia, ZF Friedrichshafen, Magna International, Hella, Gestamp Automoción, Plastic Omnium, Robert Bosch, Valeo, Aisin Seiki, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Tailgate Market Strategic Shifts & Innovations
The evolution of the tailgate from a simple hinged door into a sophisticated mechatronic module defines the market's current trajectory. This transformation integrates advanced materials, complex electronics, and software to deliver enhanced functionality and convenience demanded by modern vehicle buyers.
Hands-free power liftgates with integrated kick-to-open sensors are a key product evolution. These systems use capacitive or motion sensors to detect a user's gesture, providing automated access to the cargo area. Adoption is widespread and accelerating in new SUV and crossover models across all price points. This technology is automating cargo access, turning a manual chore into a sought-after convenience feature that reshapes consumer expectations.
European Union regulations governing vehicle functional safety, such as the principles within ISO 26262, directly impact power tailgate design. These directives mandate stringent fail-safe mechanisms for all electronic components to prevent hazards like uncontrolled closing or pinching. The passenger vehicle segment is most affected, forcing suppliers to invest heavily in robust validation and documentation for actuators, control units, and sensors to achieve market certification.
OEM purchasing models are moving toward the acquisition of complete, pre-validated tailgate modules instead of individual components. This disrupts the traditional supply chain, favoring larger Tier 1 suppliers capable of delivering a fully integrated system combining the structure, latches, and electronic actuation. This demand-side shift is most prominent in North American and European vehicle programs, where automakers seek to minimize assembly complexity and shorten development cycles.
Automotive Tailgate Market Segmentation
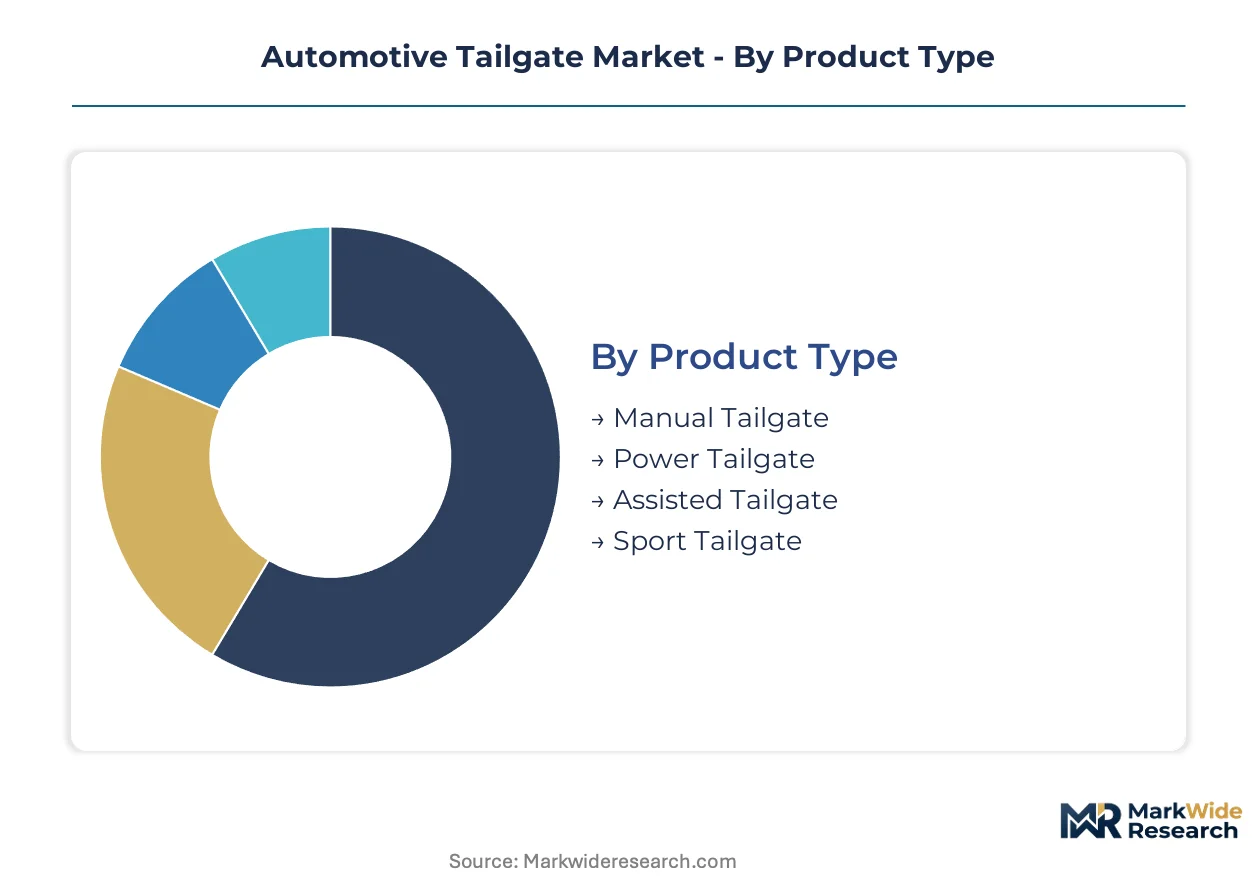
The automotive tailgate market segments across diverse product types, underlying technologies, vehicle applications, and end-user structures. Understanding these distinctions helps suppliers and manufacturers allocate resources effectively and tailor product development to specific market demands. Each segment presents unique engineering challenges and commercial opportunities within the broader automotive industry.
Product Type:
Capital investment in specialized tooling and complex electronic integration significantly differentiates tailgate product types. High-volume production for power systems requires substantial upfront capital.
- Power Tailgate:These systems incorporate electric motors or hydraulic actuators for automated opening and closing, often featuring hands-free operation. Demand is concentrating in the passenger vehicle segment, particularly SUVs and crossovers, driven by consumer convenience features.
- Manual Tailgate:Traditional hinged designs rely solely on human effort for operation, representing the most basic and cost-effective solution. This product type retains significant volume in cost-sensitive vehicle platforms and certain commercial applications.
- Assisted Tailgate:These tailgates integrate gas struts or torsion bars to reduce the physical effort required for lifting and lowering. They offer a balance between manual operation and full power systems.
- Sport Tailgate:Designed for performance vehicles, these often feature lightweight materials and aerodynamic profiles, sometimes incorporating active spoilers. They cater to niche segments prioritizing vehicle dynamics and aesthetics.
Manual Tailgate absorbs the bulk of installed capacity; Power Tailgate is expanding most quickly.
Technology:
The functional range of tailgate systems is directly influenced by the underlying actuation technology employed. Each technology offers distinct advantages for specific vehicle requirements and performance characteristics.
- Electric Motor:Widely adopted in modern power tailgates, electric motors provide precise control and enable advanced features like anti-pinch protection and programmable height settings. This technology dominates new passenger vehicle installations, especially in Europe and North America.
- Hydraulic Lift:These systems use fluid pressure to actuate heavy tailgate structures, offering high lifting capacity and robust operation. Hydraulic lifts are often found in larger commercial vehicles and heavy-duty pickups where load-bearing strength is critical.
- Pneumatic System:Utilizing compressed air, pneumatic systems offer smooth and relatively quiet operation for automated tailgate functions. Their application is more specialized, often seen in specific luxury or commercial vehicle designs.
- Mechanical Lever:The simplest technology, mechanical levers provide basic latching and unlatching functions for manual tailgates. This foundational technology remains prevalent in entry-level vehicles and rugged commercial applications.
Demand for Electric Motor is climbing fastest, while Mechanical Lever retains a substantial base.
Application:
The profitability and design complexity of tailgate systems vary significantly across different vehicle applications. Each segment demands specific performance attributes and integration capabilities.
- Passenger Vehicles:This segment includes sedans, hatchbacks, SUVs, and crossovers, which represent the largest volume market for tailgates. Consumer demand for convenience features drives the adoption of power and hands-free systems in this category.
- Pickups:Tailgates for pickup trucks require extreme durability, high load capacity, and often multi-functional designs for cargo management. This application offers significant margin opportunities due to the ruggedized requirements and specialized features.
- Commercial Vans:Tailgates for commercial vans prioritize robust construction, security, and ease of access for frequent loading and unloading operations. Durability and low maintenance are key considerations for fleet operators.
- Utility Vehicles:This category encompasses a diverse range of vehicles, including off-road vehicles and specialized work trucks, where tailgates must withstand harsh environments and heavy use. Customization for specific tasks is common.
Passenger Vehicles generates the highest volume, but Pickups offer superior unit profitability.
End User:
The distribution and procurement models for automotive tailgates are shaped by the end-user landscape. Different end-users have distinct purchasing power and influence over product specifications.
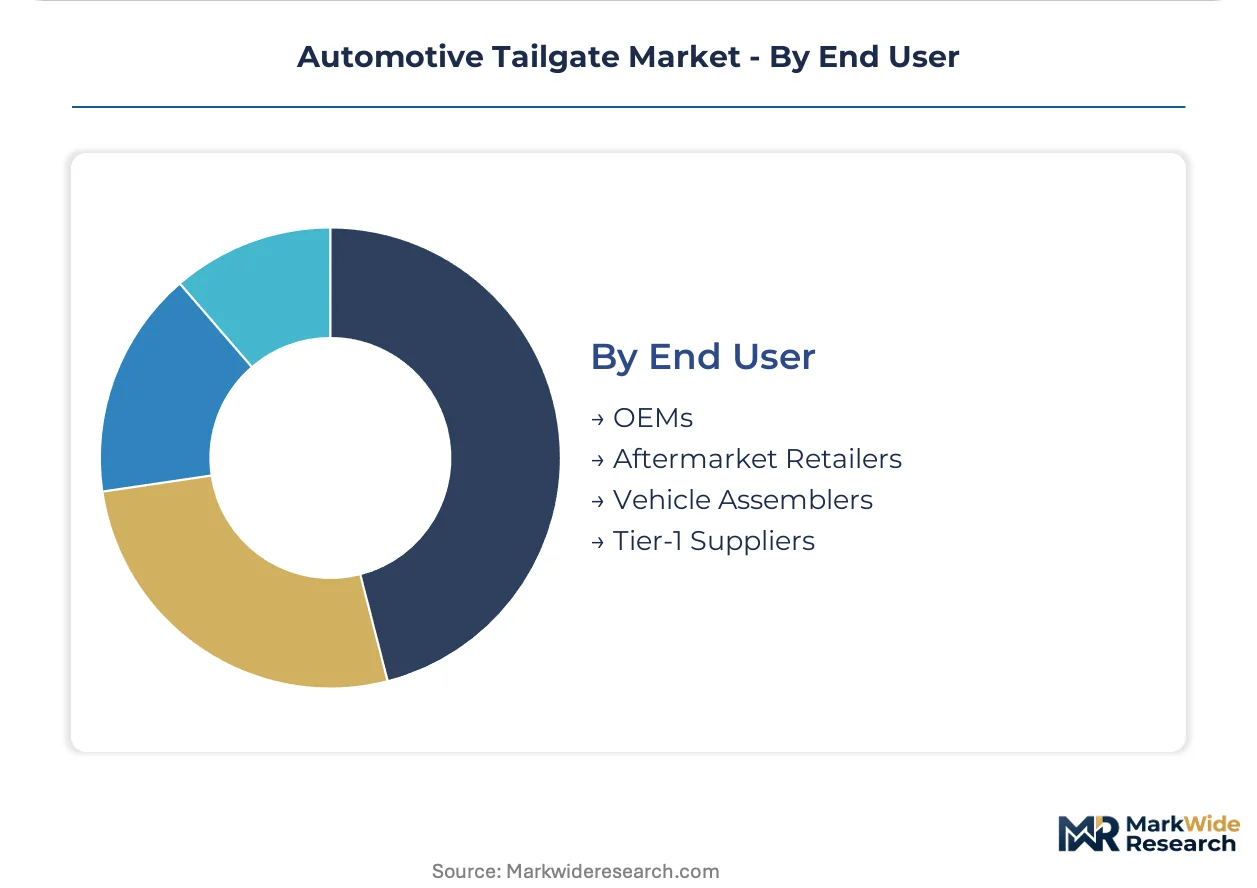
- OEMs:Original Equipment Manufacturers are the primary purchasers of complete tailgate systems for integration into new vehicle production lines. Their procurement models favor multi-source strategies and full-system assembly capabilities from large Tier 1 suppliers.
- Tier-1 Suppliers:These companies design, manufacture, and integrate complex tailgate modules, supplying them directly to OEMs. They often manage sub-suppliers for components like latches, actuators, and composite panels.
- Aftermarket Retailers:These channels provide replacement tailgates and components for vehicle repairs or upgrades after initial sale. Demand in this segment is driven by vehicle age, accident rates, and consumer customization trends.
- Vehicle Assemblers:These entities focus on the final assembly of vehicles, sometimes procuring specific tailgate components or modules for integration. Their role often involves coordinating with various suppliers to ensure seamless assembly.
Direct engagement with OEMs shapes product development, while Aftermarket Retailers facilitate market reach.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global automotive industry, anchored by vast steel and aluminum production capacities, drives demand for tailgate systems across key manufacturing regions. Vehicle production volumes in these areas directly influence market dynamics and technological adoption. Regulatory pressures for lightweighting further shape material choices and design innovation across these critical markets.
China
Massive domestic vehicle production in China fuels substantial demand for tailgate systems, particularly for the expanding SUV and crossover segments. The nation's GB standards dictate material and performance requirements for market entry, influencing local and international suppliers. Automotive manufacturing hubs in cities like Shanghai and Guangzhou continue to attract significant investment in advanced production capabilities.
United States
The United States market sees sustained consumer shift toward SUVs and crossovers, directly stimulating volume demand for power liftgate systems. US NHTSA regulations heavily influence latch strength and safety standards for all vehicle components, including tailgates. Major automotive manufacturing corridors, including the Southern auto belt and Detroit, remain critical for vehicle assembly and component integration.
Germany
German automotive manufacturers prioritize technological innovation and premium features, driving demand for sophisticated power and smart tailgate systems. CE marking and related EU directives govern electronic components within power tailgates, ensuring stringent functional safety standards. Stuttgart and Munich serve as central hubs for advanced automotive R&D and high-volume production of complex vehicle modules.
Japan
Japanese automakers emphasize precision engineering and integrated manufacturing, contributing to a stable demand for high-quality tailgate components. JIS standards ensure stringent quality and performance criteria for automotive parts supplied within the domestic market. Major automotive clusters around Toyota City and Nagoya support extensive supply chains for vehicle body systems.
India
Expanding passenger vehicle sales in India, particularly in the compact SUV segment, are creating new opportunities for tailgate system suppliers. The Bureau of Indian Standards (BIS) sets national requirements for automotive component quality and safety. Automotive production centers in Chennai and Pune are becoming increasingly important for localized manufacturing and supply to the subcontinent's growing market.
Automotive Tailgate Market Key Industry Players
Strategic partnerships dominate the current landscape, as OEMs seek comprehensive solutions from a streamlined supplier base. The market exhibits a tiered structure, where large Tier 1 suppliers offer full-system integration, while specialized manufacturers focus on advanced materials or specific electronic components. Key competitive moves include portfolio diversification to offer complete modules and capacity expansion for lightweight material processing.
On the full-system integration vector, Magna International and Faurecia exemplify the trend of providing complete, pre-validated tailgate modules directly to OEMs. Magna International, a global automotive supplier, leverages its extensive assembly capabilities to secure large contracts. Faurecia, a French automotive equipment supplier, occupies a position integrating interior systems alongside tailgate mechanisms, offering a bundled solution. Gestamp Automoción, a Spanish multinational company, sits within the archetype of structural component specialists, anchoring its competitive advantage in advanced metal stamping and hot forming expertise.
| Leading Market Players |
|---|
| Faurecia |
| ZF Friedrichshafen |
| Magna International |
| Hella |
| Gestamp Automoción |
| Plastic Omnium |
| Robert Bosch |
| Valeo |
| Aisin Seiki |
| Others |
Cost & Logistics Intelligence
Multi-source procurement strategies anchor the supply position for automotive tailgates, influencing pricing power through competitive bidding among Tier 1 suppliers.
Pricing Analysis
Warranty and service bundling often differentiates pricing for complex power tailgate systems, contrasting with the per-unit transactional model for manual versions. Value-based pricing emerges for advanced features like gesture control, reflecting enhanced user convenience. Pricing softness stems from intense competition in the high-volume manual and assisted tailgate segments, particularly for cost-sensitive vehicle platforms. OEMs purchasing for premium passenger vehicles exhibit lower price sensitivity, prioritizing integrated functionality and reliability over upfront cost.
Supply Chain Analysis
Single-source vulnerability sits with specialized manufacturers of advanced composite materials, creating potential supply bottlenecks and cost fluctuations. Geographic supply for critical components draws from China for electronics, Germany for premium system engineering, and the United States for large-scale vehicle integration. Raw material dependencies include automotive-grade steel, aluminum, and various composite resins. Commodity price volatility for these inputs represents a significant structural risk. Distribution runs through a direct model from Tier 1 suppliers to OEMs for new vehicle production.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive tailgate market is a vertical-integration race, with players pursuing upstream control over advanced material processing to secure competitive advantage.
For Market Incumbents: Hedge against material cost premiums by investing in multi-material engineering capabilities and securing long-term supply agreements for composites. Consolidate market position by offering complete, pre-validated tailgate modules, leveraging functional safety certifications like ISO 26262. Focus R&D on robust electronic integration to minimize warranty risks, a key threat from complex power systems.
For New Entrants and Emerging Players: Capture white-space opportunities in light commercial vehicle applications by developing ruggedized, multi-functional tailgates. Target the pickup truck segment, which offers superior unit profitability due to specialized requirements. A viable go-to-market angle involves offering modular, easily integratable smart components like advanced sensors and actuators to smaller OEMs or Tier 2 suppliers.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized technology providers offering integrated electronic modules or advanced material solutions. Long-term viability remains strong for companies capable of delivering comprehensive, lightweight, and smart tailgate systems. Identify acquisition targets with strong intellectual property in gesture control or advanced composite molding. The signal to watch is the increasing OEM shift from component-level purchasing to full-system module acquisition.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Composite Manufacturing Capacity | Reduces weight for fuel economy compliance, offering a competitive edge in material innovation. |
| Expand Power Liftgate Electronics R&D | Enhances user convenience and safety features, aligning with consumer demand for smart vehicles. |
| Secure Long-Term Aluminum Supply Contracts | Mitigates commodity price volatility for a key lightweighting material, stabilizing production costs. |
| Develop Ruggedized Tailgates for Pickups | Addresses a high-margin segment with specialized durability and load-capacity requirements. |
| Pursue ISO 26262 Certification for Control Units | Ensures functional safety compliance for electronic power tailgates, crucial for European market entry. |
Research Approach
Multi-period observation of vehicle production volumes and material adoption rates anchored the trend analysis, supplemented by interviews with OEM platform engineers and Tier 1 procurement leads. This approach integrated insights from composite material suppliers and automotive electronics specialists. Secondary validation drew from vehicle production databases, regulatory filings (NHTSA, CE marking), material science journals, and patent databases, employing both bottom-up and top-down triangulation.
An input-output matrix structured the quantitative model, segmenting the market by product type, technology, application, end-user, and regional production cluster. CAGRs were derived from historical data extrapolation and forward-looking market drivers identified through primary and secondary research. Key forecast inputs included vehicle production forecasts, material cost trends, and anticipated regulatory changes, such as new fuel economy standards across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical shifts and material cost volatility. Forecasts reflect assumptions regarding technological advancements and market adoption rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Carbon Thermoplastic Market
Automotive Components
Japan Automotive Electric Actuators Market
Automotive Components
Automotive Straps Market
Automotive Components
Africa Automotive Lubricants Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Automotive Bushing Technologies Market
Automotive Components
Global Automotive Chrome Accessories Market
Automotive Components
Automotive Emblem Market
Automotive Components
Asia-Pacific Automotive Parts and Components Market
Automotive Components
Automotive Hubcaps Market
Automotive Components
Automotive Polymer Composites Market
Automotive Components
Russia Automotive Pneumatic Actuators Market
Automotive Components
Automotive Defroster Market
Automotive Components
Automotive Millimeter Wave Compatible Emblem Market
Automotive Components
France Automotive Electric Actuators Market
Automotive Components
Australia Automotive Pneumatic Actuators Market