
 Automotive Injector Nozzle Market | 2026-2036
Automotive Injector Nozzle Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Injector Nozzle Market Analysis
Precision machining talent scarcity is reorganizing supplier geography across the automotive injector nozzle value chain. Robert Bosch GmbH leverages captive tooling operations in Germany to sustain high-pressure common rail nozzle output. Denso Corporation anchors Asian supply through integrated ceramic processing in Japan. Continental AG competes via electromechanical actuator specialization for gasoline direct injection platforms.
An automotive injector nozzle is a precision-machined component typically fabricated from hardened steel or advanced ceramic composites, featuring orifice diameters measured in microns to atomize fuel at pressures exceeding 2,000 bar in diesel systems and 350 bar in emerging gasoline direct injection designs. Its primary purpose is to deliver metered, atomized fuel charges into combustion chambers to optimize thermal efficiency and minimize particulate emissions. Gasoline direct injectors command premium positioning as downsized turbocharged engines proliferate, while piezoelectric technology segments capture the fastest growth trajectory due to sub-millisecond response requirements. Diesel injector demand remains structurally mature in Europe but retains margin density through aftermarket rebuild programs.
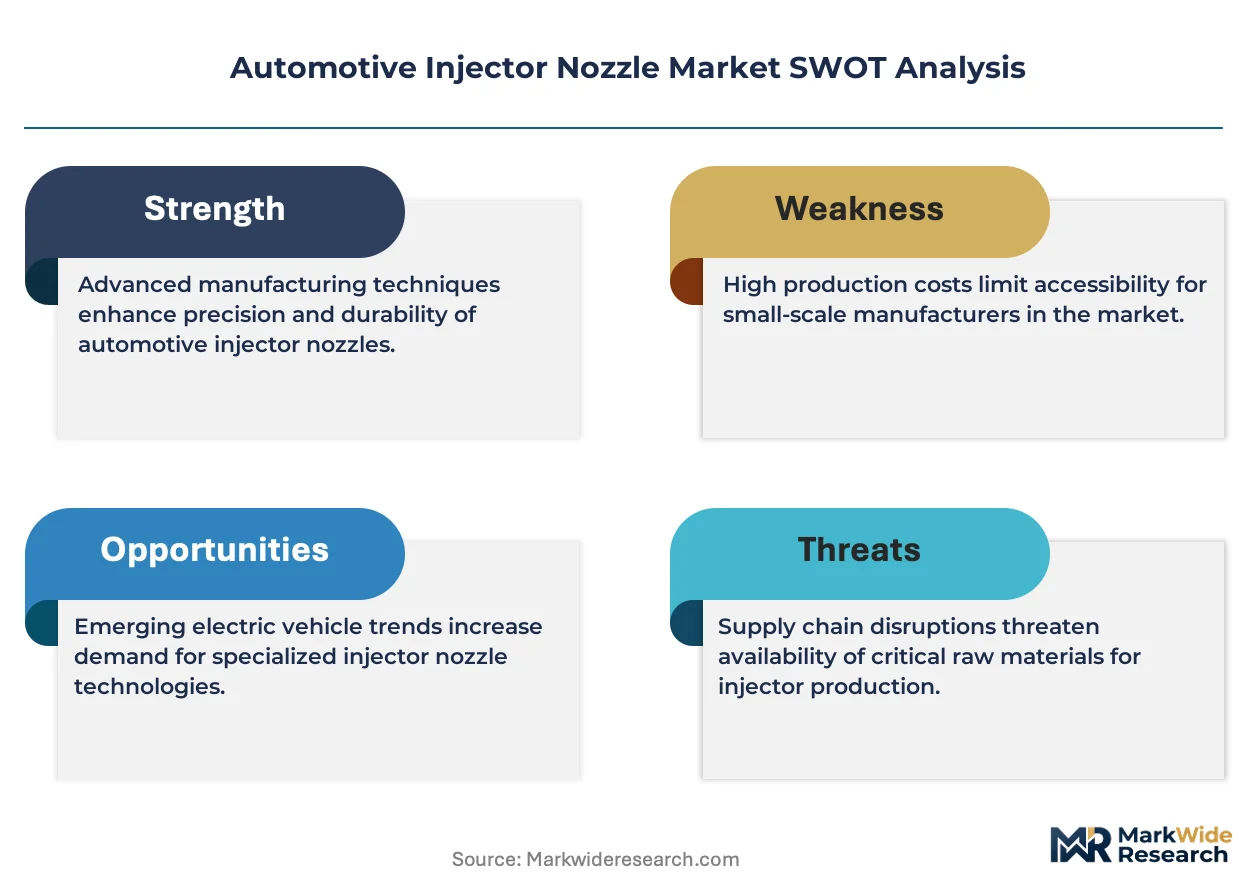
EPA tailpipe regulations and the EU Green Deal's fleet CO2 mandates are forcing simultaneous reductions in particulate matter and nitrogen oxide outputs, which directly tightens nozzle orifice tolerance specifications and accelerates piezoelectric actuator replacement cycles. China's MIIT fuel consumption standards and NMPA emission enforcement are reshaping import qualification protocols for foreign nozzle suppliers serving domestic vehicle assemblers. Stakeholders must monitor regulatory divergence between Euro 7 preparation and China's Stage VI-b implementation to calibrate R&D allocation across electromechanical and piezoelectric technology platforms.
Market Dynamics
EPA tailpipe standards and EU Green Deal fleet mandates are compressing nozzle orifice tolerances while piezoelectric actuator replacement cycles accelerate, forcing simultaneous investment in precision machining capacity and electromechanical R&D across supplier networks.
Growth Catalysts
- Gasoline Direct Injection Proliferation:Downsized turbocharged engines in passenger vehicles require higher-pressure nozzles with micron-level precision, expanding addressable component value per vehicle platform.
- Euro 7 Preparation:Draft particulate matter and nitrogen oxide limits tighten orifice specifications and validate piezoelectric technology investments for sub-millisecond fuel delivery control.
- Ceramic Composite Adoption:Advanced ceramic processing enables higher thermal tolerance and extended service intervals in high-pressure common rail architectures, differentiating supplier technical capabilities.
Market Restraints
- Hardened Steel Input Volatility:Specialty alloy pricing fluctuations compress margin predictability for precision-machined steel nozzle producers serving volume OEM contracts.
- German Supplier Concentration:Captive tooling operations in Stuttgart and Dresden regions create geographic supply risk if trade friction or energy cost spikes disrupt component flows.
- Solenoid Valve Substitution:Lower-cost electromagnetic actuators retain share in cost-sensitive commercial vehicle segments, limiting piezoelectric penetration in price-elastic applications.
Strategic Opportunities
- India PLI Scheme Alignment:Component manufacturing incentives for advanced automotive systems create localized production pathways for foreign nozzle suppliers qualifying under domestic value-add thresholds.
- Aftermarket Rebuild Programs:Diesel injector remanufacturing in Europe retains margin density through authorized service networks, extending revenue capture beyond initial equipment sales.
- Electromechanical-Piezoelectric Convergence:Hybrid actuator architectures blending response speed with cost efficiency open mid-market gasoline direct injection platforms previously reserved for single-technology solutions.
Industry Challenges
- Precision Machining Talent Scarcity:Micron-tolerance grinding and EDM specialists command premium wages in supplier clusters, constraining capacity expansion timelines.
- Dual Certification Burden:Simultaneous Euro 7 and China Stage VI-b qualification protocols duplicate testing expenditure and compress product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Injector Nozzle Market |
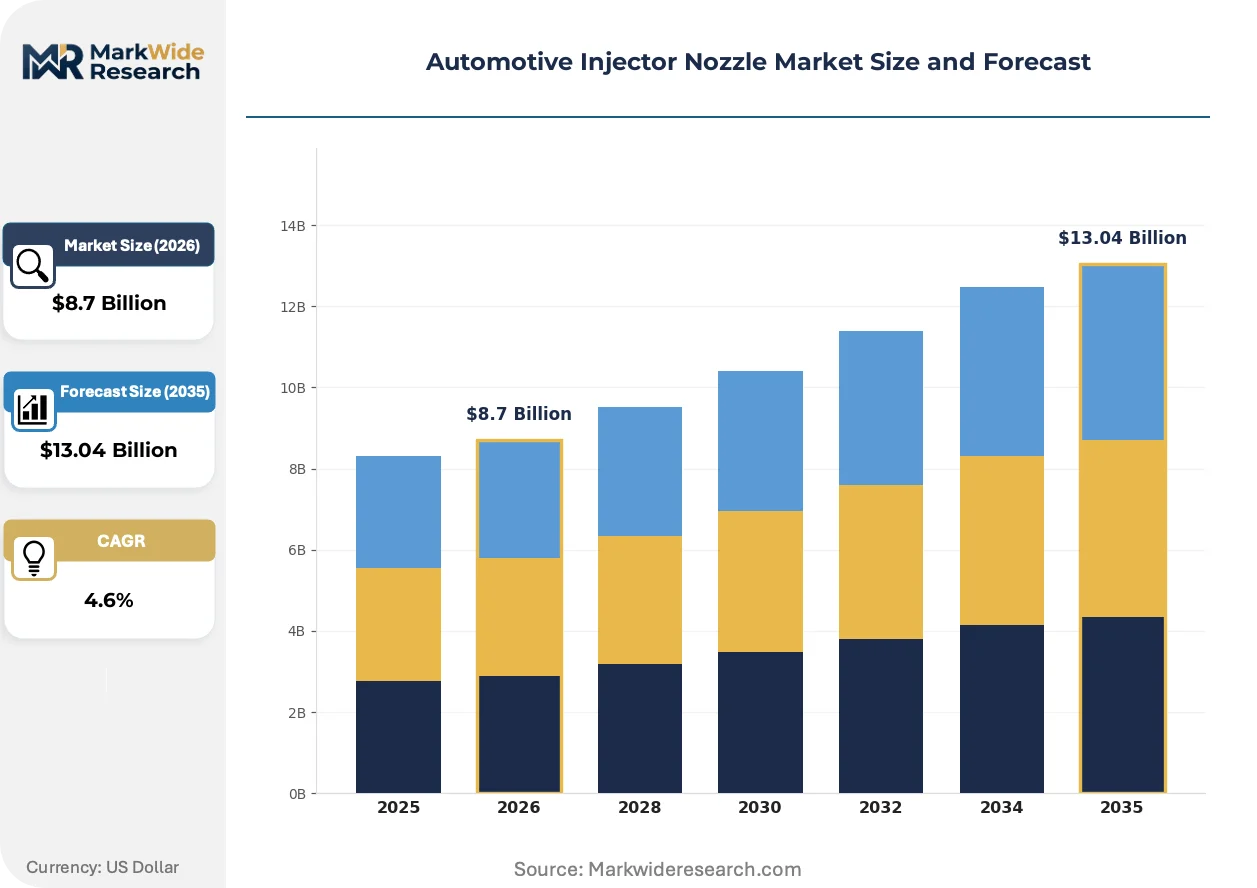
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gasoline Injectors, Diesel Injectors, Direct Injectors, Multi-Point Fuel Injectors Technology: Electromechanical, Piezoelectric, Hydraulic, Solenoid Operated End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Fuel Type: Petrol, Diesel, Alternative Fuels, Biofuels |
| Companies Covered | Robert Bosch GmbH, Denso Corporation, Continental AG, Delphi Automotive PLC, Keihin Corporation, Magneti Marelli S.p.A., Infineon Technologies AG, BorgWarner Inc., Eaton Corporation PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Injector Nozzle Market Emerging Trajectories
Active nozzle architectures are displacing passive designs as combustion efficiency targets tighten, with electromechanical actuation and intelligent fuel mapping converging to enable cycle-by-cycle injection control.
Piezoelectric stack actuators is decomposing traditional solenoid-based fuel delivery in high-performance gasoline direct injection applications. European and Japanese OEMs specify piezoelectric platforms for downsized turbocharged engines requiring multiple injection events per combustion cycle. This displacement is compressing the addressable market for conventional electromagnetic nozzle architectures while elevating supplier technical barriers.
EPA's updated tailgate particulate standards and the EU Green Deal's interim CO2 benchmarks are mandating simultaneous reductions in nitrogen oxide and particulate matter outputs. These dual constraints tighten allowable orifice diameter variance and accelerate validation timelines for new nozzle geometries. Diesel aftermarket rebuild specialists in Germany and France are responding by certifying remanufactured piezoelectric units to original tolerance specifications.
Buyer consolidation among tier-one fuel system integrators is compressing supplier negotiation leverage and elongating qualification cycles. Single-source contracts for high-pressure common rail platforms now span entire vehicle generations, displacing multi-vendor sourcing strategies prevalent in prior engine architectures. This concentration is most visible in German and Chinese passenger vehicle supply chains where Bosch, Denso, and Continental anchor procurement decisions.
Automotive Injector Nozzle Market Segmentation
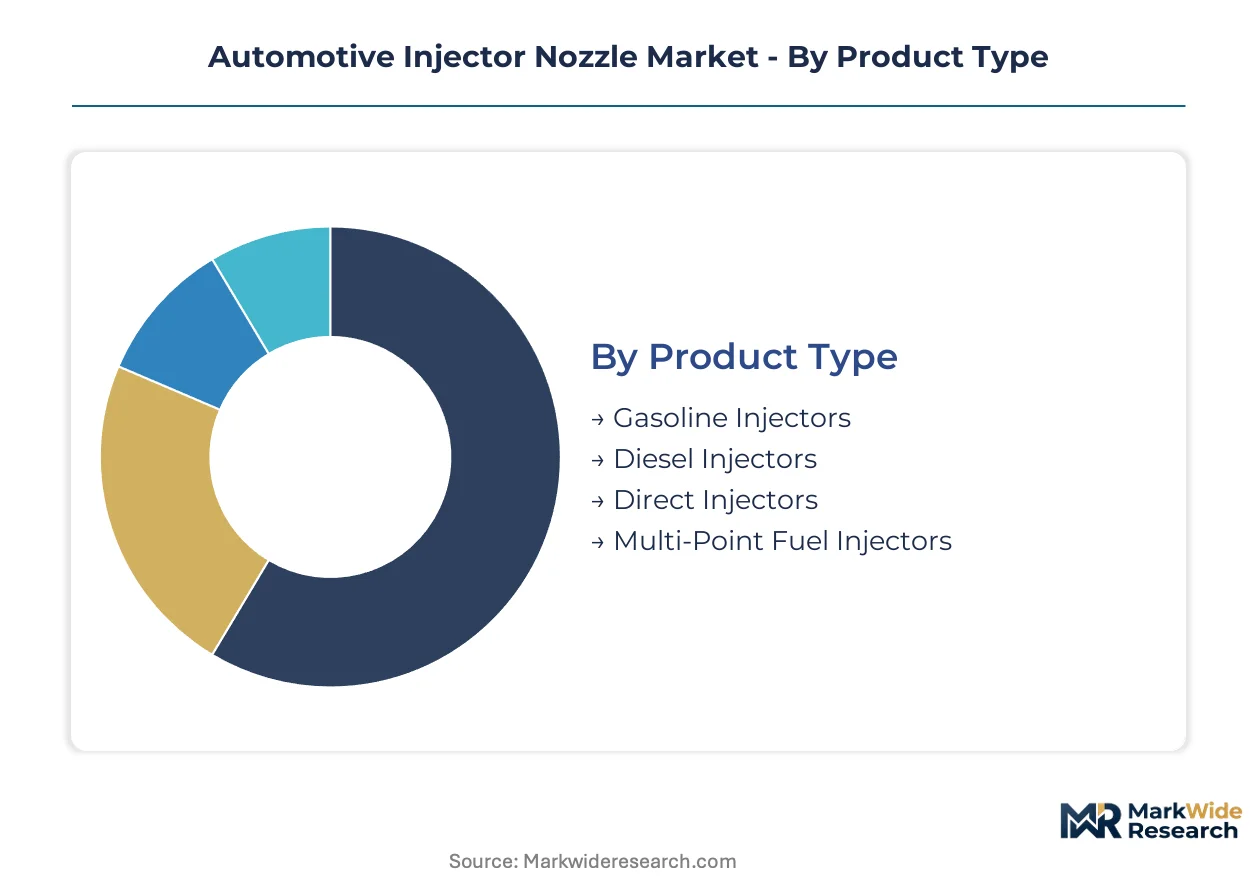
Injector nozzle segmentation reveals how regulatory pressure and combustion architecture choices split demand across incompatible technical specifications. Each dimension—product type, technology, end user, and fuel type—carries distinct certification burdens and margin structures that reshape supplier positioning.
Product Type:
EPA tailpipe standards and Euro 7 drafts are forcing divergent investment patterns across nozzle architectures, with gasoline direct injection absorbing disproportionate R&D allocation.
- Gasoline Injectors:Port fuel injection nozzles operate at lower pressures with simpler solenoid actuation, retaining share in cost-sensitive vehicle segments where EPA Tier 3 compliance suffices without direct injection complexity. Demand concentrates in North American light-truck platforms where thermal efficiency targets remain less stringent than passenger car mandates.
- Direct Injectors:High-pressure gasoline direct injection nozzles feature 200+ bar operating pressures with micron-tolerance orifice machining to satisfy EU Green Deal interim CO2 benchmarks. German and Chinese OEM procurement specifications now require piezoelectric actuation for multiple injection events per cycle.
- Diesel Injectors:Common rail architectures with 2,000+ bar pressures dominate commercial vehicle applications.
- Multi-Point Fuel Injectors:Legacy port injection designs persist in emerging-market vehicle platforms.
Direct injectors handle the majority of throughput; gasoline injectors are the fastest mover on share.
Technology:
Cost tier differentiation separates premium piezoelectric platforms from volume electromechanical solutions, with procurement patterns tracking vehicle segment price elasticity.
- Piezoelectric:Ceramic stack actuators deliver sub-millisecond response times enabling five or more injection events per combustion cycle, satisfying Euro 7 particulate matter limits for downsized turbocharged gasoline engines. Japanese and German OEMs specify this technology exclusively for premium passenger vehicle platforms.
- Electromechanical:Solenoid-driven nozzles balance cost and precision for mid-market applications, with Continental AG and Robert Bosch GmbH optimizing electromagnetic response curves to approach piezoelectric performance at 40% lower unit cost.
- Hydraulic:Pressure-amplified designs serve heavy-duty diesel common rail systems.
- Solenoid Operated:Conventional electromagnetic actuation retains commercial vehicle share.
Electromechanical platforms capture the volume base; piezoelectric systems are climbing the fastest on revenue contribution.
End User:
Customer type determines qualification timeline and contract structure, with OEM direct procurement compressing supplier margins while extending commitment duration.
- OEMs:Volkswagen Group, Toyota Motor Corporation, and Stellantis NV specify nozzle architectures at platform conception, locking suppliers into generation-long contracts with zero-defect quality protocols. Direct OEM relationships require simultaneous EPA, EU Green Deal, and China MIIT certification.
- Tier-1 Suppliers:Bosch, Denso, and Continental integrate nozzle production into complete fuel system modules, capturing value through electromechanical actuator specialization and captive ceramic processing capabilities.
- Aftermarket Providers:Authorized remanufacturing networks in Germany and France rebuild piezoelectric diesel injectors to original tolerance specifications.
- Vehicle Assemblers:Contract manufacturers and regional brands source through tier-1 intermediaries.
OEMs dominate absolute procurement value; aftermarket providers are expanding most quickly as diesel fleet ages.
Fuel Type:
Application chemistry constrains material selection and thermal tolerance specifications, with alternative fuel compatibility emerging as a technical differentiator.
- Petrol:Gasoline direct injection nozzles face unique deposit formation challenges from fuel impingement on cylinder walls, driving specialized coating requirements and accelerated validation protocols under EPA updated particulate standards.
- Diesel:High-pressure common rail nozzles require hardened steel or advanced ceramic composites to withstand 2,000+ bar pressures and corrosive sulfur compounds, with European aftermarket rebuild programs extending service revenue capture.
- Alternative Fuels:Hydrogen and synthetic fuel compatibility demands modified sealing materials and revised spray pattern geometries.
- Biofuels:Ethanol and biodiesel blends accelerate elastomer degradation, requiring fluorocarbon seal specifications.
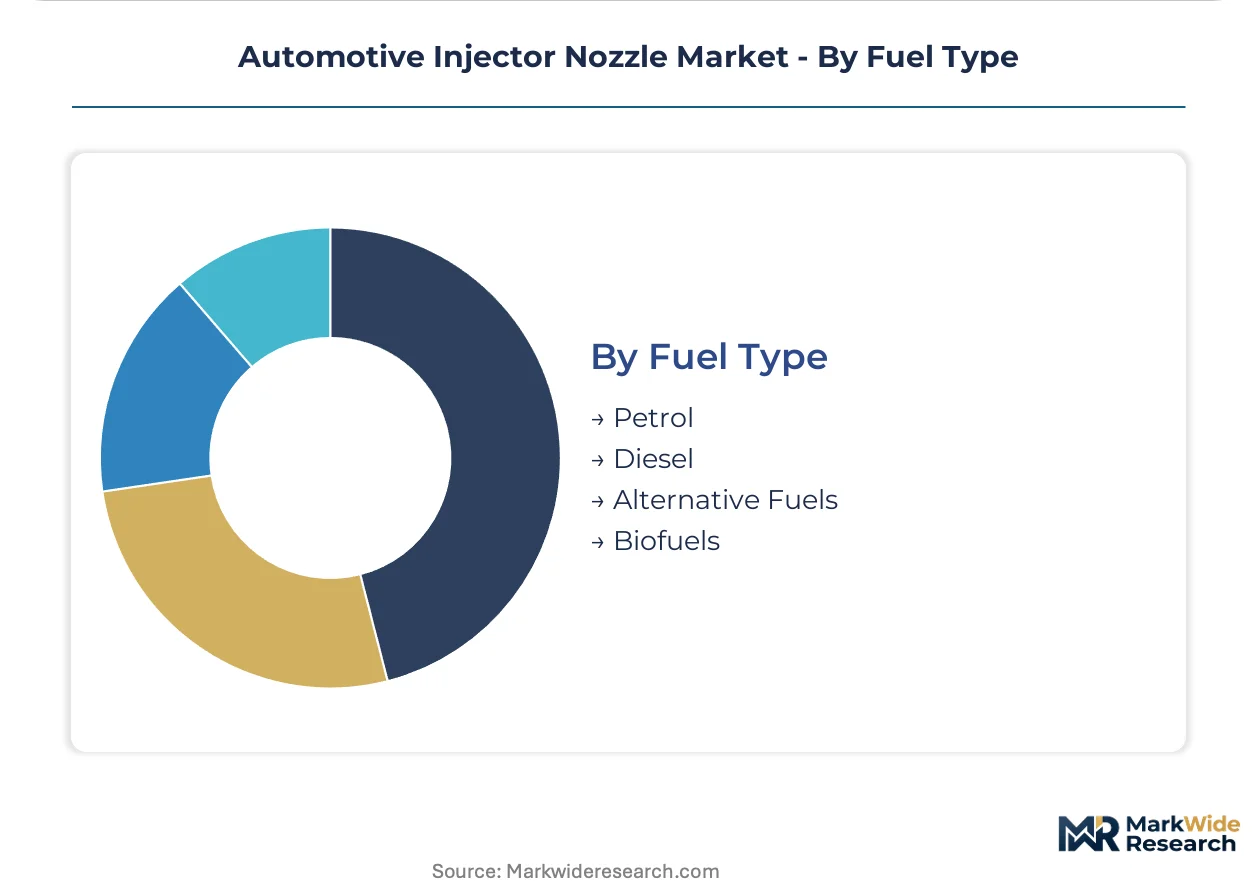
Petrol nozzles absorb the largest development expenditure; alternative fuel compatibility is gaining specification priority fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in German supplier clusters while Chinese domestic qualification protocols compress margins for foreign entrants. Stuttgart and Dresden anchor captive tooling operations that command premium positioning. Shenzhen and Shanghai assembly plants drive volume absorption through localized tier-1 sourcing mandates.
United States
Light-truck platforms sustain port fuel injection demand where EPA Tier 3 compliance suffices without direct injection complexity. Michigan and Ohio supplier corridors face talent scarcity for micron-tolerance grinding specialists. Detroit-based OEM procurement offices now require simultaneous EPA certification and zero-defect quality protocols for generation-long contracts.
Germany
Volkswagen Group and BMW AG specifications lock suppliers into piezoelectric platforms for downsized turbocharged engines. EU Green Deal interim CO2 benchmarks tighten allowable orifice diameter variance beyond current machining capabilities. Stuttgart-Dresden tooling clusters defend margin density through captive ceramic processing and electromechanical actuator specialization.
China
MIIT fuel consumption standards and NMPA emission enforcement reshape import qualification protocols for foreign nozzle suppliers. Yangtze River Delta vehicle assemblers source through tier-1 intermediaries to satisfy domestic value-add thresholds. Shanghai procurement offices now demand dual certification for Euro 7 preparation and Stage VI-b implementation.
Japan
Toyota Motor Corporation and Honda Motor Co. anchor Asian demand through integrated ceramic processing specifications. METI technology roadmaps validate piezoelectric investments for sub-millisecond fuel delivery control. Nagoya-Osaka supplier corridors concentrate precision machining talent for high-pressure common rail architectures.
India
PLI scheme component manufacturing incentives create localized production pathways for foreign suppliers qualifying under domestic value-add thresholds. Tamil Nadu and Gujarat vehicle assemblers expand gasoline direct injection adoption as BIS emission standards tighten. Chennai supplier parks face elongated qualification cycles under tier-one fuel system integrator consolidation.
Automotive Injector Nozzle Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where premium positioning separates from volume positioning. The market consolidates around three strategic archetypes: integrated system specialists with captive ceramic processing, precision machining houses with electromechanical actuator specialization, and scale-driven component fabricators serving aftermarket rebuild networks. Dominant competitive moves include backward integration into specialty alloy supply and geographic expansion through India PLI scheme alignment.
Within the integrated system tier, Robert Bosch GmbH and Denso Corporation exemplify archetypes combining captive tooling with generation-long OEM contracts. Continental AG occupies a position bridging electromechanical cost efficiency and piezoelectric response speed. These three anchors represent the premium-mid-economy stratification visible across German and Asian procurement decisions.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Denso Corporation |
| Continental AG |
| Delphi Automotive PLC |
| Keihin Corporation |
| Magneti Marelli S.p.A. |
| Infineon Technologies AG |
| BorgWarner Inc. |
| Eaton Corporation PLC |
| Others |
Supply Flow & Price Mechanics
Captive ceramic processing capacity in Stuttgart and Dresden anchors supplier pricing power through generation-long OEM contracts. Scale economies in piezoelectric stack production compress unit costs for Bosch and Denso while elevating entry barriers for precision machining specialists lacking in-house tooling operations.
Pricing Analysis
The customization-premium spread separates configured-to-order piezoelectric platforms from standard electromechanical solenoid units. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with Euro 7-compliant piezoelectric actuators commanding 40% premiums over baseline electromagnetic architectures. Pricing pressure stems from hardened steel input volatility and tier-one fuel system integrator consolidation. Commercial vehicle segments exhibit highest price sensitivity, while German passenger vehicle OEMs demonstrate lowest elasticity due to zero-defect quality protocols.
Supply Chain Analysis
Just-in-time inventory strategies dominate German and Japanese supplier corridors where micron-tolerance grinding specialists command premium wages. Geographic supply concentrates in Germany, China, and Japan, with Yangtze River Delta assembly plants driving volume absorption through localized tier-1 sourcing mandates. Raw material dependencies center on specialty hardened steel alloys, advanced ceramic composites, and piezoelectric ceramic stacks. Single-source vulnerability risks concentrate in Stuttgart-Dresden tooling clusters dependent on captive electromechanical actuator production. Distribution runs through tier-one fuel system integrators anchoring procurement decisions for entire vehicle generations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as gasoline direct injection penetration accelerates across downsized turbocharged engine platforms. EPA tailpipe standards and EU Green Deal mandates create sustained adoption tailwinds for high-pressure nozzle architectures.
For Market Incumbents: Consolidate backward integration into specialty alloy supply and captive ceramic processing to defend margin density against solenoid valve substitution threats. Lock generation-long contracts with Volkswagen Group and Toyota Motor Corporation through simultaneous Euro 7 and China Stage VI-b certification investment. Prioritize precision machining talent acquisition in Nagoya-Osaka and Stuttgart corridors to constrain competitor capacity expansion timelines. For New Entrants and Emerging Players: Aftermarket rebuild service gaps in European diesel fleets present white-space opportunities where authorized remanufacturing networks under-serve aging piezoelectric injector demand. Target India PLI scheme alignment for localized production pathways qualifying under domestic value-add thresholds. Pursue electromechanical-piezoelectric hybrid actuator development for mid-market gasoline direct injection platforms previously reserved for single-technology solutions. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among aftermarket rebuild specialists with authorized service network contracts extending beyond initial equipment sales. Long-term viability favors precision machining houses with electromechanical actuator specialization bridging cost efficiency and response speed. Watch for inflection when China Stage VI-b enforcement accelerates import qualification protocol divergence from Euro 7 preparation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloys | Captive hardened steel supply defends margin predictability against commodity volatility for Bosch. |
| India PLI Scheme Manufacturing Localization | Tamil Nadu and Gujarat production qualification satisfies MIIT domestic value-add thresholds for foreign entrants. |
| Dual Certification Investment (Euro 7 + Stage VI-b) | Simultaneous EPA and NMPA qualification compresses product launch windows but locks generation-long OEM contracts. |
| Aftermarket Rebuild Network Expansion | Authorized remanufacturing in Germany and France captures margin density from aging diesel fleet service intervals. |
| Hybrid Actuator Architecture Development | Electromechanical-piezoelectric convergence opens mid-market gasoline direct injection platforms for Continental AG. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with OEM platform engineers, tier-1 fuel system procurement leads, aftermarket distributor operations heads, and precision machining specialists. Secondary validation drew from vehicle production databases, IHS Markit registration data, EPA certification filings, and EU Green Deal regulatory drafts. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Across the modeling period, volume and value outputs reflected analytical frameworks segmenting by propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from regression analysis of historical penetration curves and regulatory mandate timelines. Forecast inputs incorporated EPA tailpipe standard phase-in schedules, MIIT fuel consumption trajectory enforcement, and piezoelectric actuator replacement cycle acceleration patterns.
Underlying assumptions cover sustained gasoline direct injection adoption, hardened steel pricing mean-reversion, and precision machining talent availability, with deviation risk concentrated in regulatory divergence between Euro 7 and China Stage VI-b implementation timelines. Revision becomes warranted when dual certification burden costs exceed 15% of new product development budgets or when solenoid valve substitution rates in commercial vehicles accelerate beyond baseline displacement curves.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
India Automotive Pneumatic Actuators Market
Automotive Components
Automotive Brake Pads Market
Automotive Components
Global Automotive Interior Plastic Components Market
Automotive Components
North America Automotive Intercooler Market
Automotive Components
Automotive Metal Stamping Market
Automotive Components
Automotive Actuators Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Global Automotive Mats Market
Automotive Components
Beryllium Copper for Automobile Market
Automotive Components
Automotive Carbon Fiber Composites Parts Market
Automotive Components
Automotive Defroster Market
Automotive Components
Automotive Engine Bearings Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Automotive Bushing Market
Automotive Components
Global Automotive Plastic Compounding Market