
 GCC Automotive Lubrication Services Market | 2026-2036
GCC Automotive Lubrication Services Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Automotive Lubrication Services Market Foresight
Synthetic lubricant formulations are consolidating share against mineral-based alternatives across GCC service bays, tightening margin structures for traditional operators. Valvoline leverages its blending facility network to secure bulk supply agreements with fleet maintenance companies. Gulf Oil Middle East anchors its position through backward integration into base oil trading across Jebel Ali and Dammam ports. Q8 Oils competes via specialized high-temperature formulations engineered for desert operating conditions.
Automotive lubrication services encompass the scheduled replacement and replenishment of friction-reducing fluids within vehicle powertrains, drivelines, and thermal management systems, typically involving SAE viscosity-grade oils and OEM-specified service intervals measured in kilometers or engine hours. Engine oil change generates the highest transaction frequency and customer touchpoint density among service types, while differential oil replacement commands premium labor rates due to specialized equipment requirements. Quick service centers now dominate volume throughput for passenger cars, though fleet maintenance companies capture superior contract value through multi-vehicle lubrication schedules negotiated with logistics firms and rental companies.
GSO technical regulations and UAE-specific Emirates Authority for Standardization and Metrology (ESMA) specifications mandate lubricant performance certifications that filter market access for uncertified service providers. Saudi Standards, Metrology and Quality Organization (SASO) enforcement of API SP and ILSAC GF-6 standards is accelerating equipment upgrades at independent workshops. Stakeholders must monitor how carbon intensity disclosures under evolving Gulf environmental frameworks reshape procurement criteria for state-linked fleet operators.
Market Dynamics
Fleet operators across Saudi Arabia and the UAE are compressing lubrication service intervals as GSO sulfur emission caps tighten, forcing service providers to upgrade diagnostic equipment and retrain technicians for synthetic formulation handling.
Growth Catalysts
- Emission enforcement tightening:GSO regulations now mandate API SP and ILSAC GF-6 lubricant standards, compelling fleet maintenance companies to renew service contracts with certified providers equipped for high-performance synthetic oils.
- Logistics corridor density:The Dubai-Abu Dhabi freight corridor generates concentrated demand from high-utilization commercial truck pools requiring scheduled preventive maintenance at shortened intervals.
- Base oil infrastructure expansion:Jebel Ali and Dammam port facilities are deepening storage and blending capacity, reducing lead times for bulk lubricant procurement by independent service centers.
Market Restraints
- Group II/III base oil price volatility:Feedstock costs for synthetic lubricant production fluctuate with regional refinery output, squeezing margin structures for service operators locked into fixed-price fleet contracts.
- Certification concentration risk:ESMA and SASO approval processes filter market access, leaving uncertified independent workshops in secondary GCC cities unable to service state-linked fleet operators.
- Extended-drain technology substitution:Advanced synthetic formulations with 15,000+ kilometer service intervals are reducing transaction frequency at quick-lube centers dependent on volume throughput.
Strategic Opportunities
- Oman and Kuwait fleet penetration:Underdeveloped preventive maintenance cultures in these markets present first-mover advantages for service chains offering bundled lubrication and inspection packages to emerging logistics operators.
- Electric vehicle thermal fluid services:Battery electric commercial vehicles entering GCC fleets require specialized dielectric coolant and grease formulations, creating new high-margin service categories distinct from traditional engine oil changes.
- Carbon disclosure procurement criteria:Evolving environmental frameworks are reshaping tender requirements for state-linked operators, favoring service providers with verified supply chain carbon intensity documentation.
Industry Challenges
- Synthetic handling technician certification:The shift from mineral to synthetic formulations demands retraining programs for service bay staff, with SASO-mandated competency assessments creating bottlenecks in workforce scaling.
- Multi-brand diagnostic equipment integration:Fleet operators running mixed European, Asian, and domestic commercial vehicle brands require service centers to maintain OEM-specific fluid specification databases and dispensing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Automotive Lubrication Services Market |
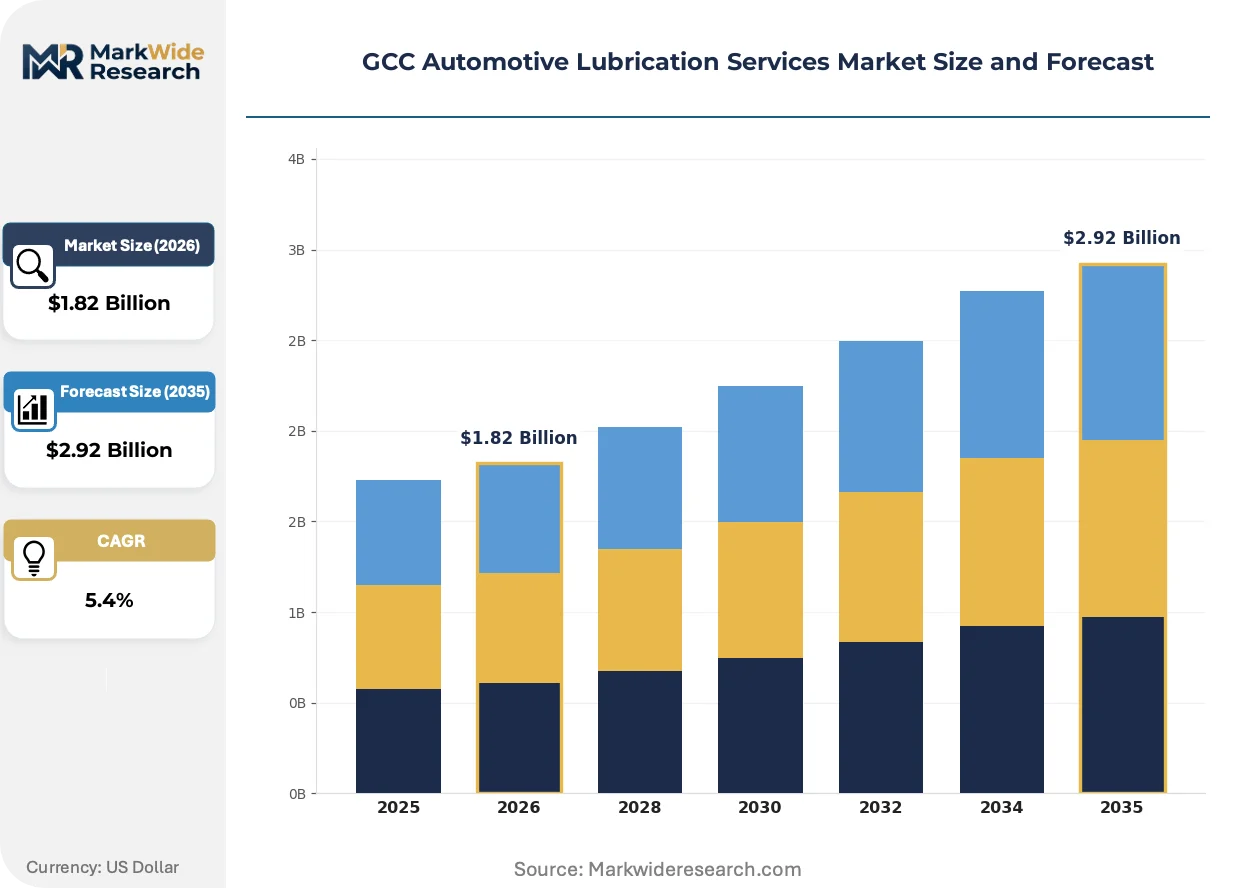
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Engine Oil Change, Transmission Fluid Replacement, Brake Fluid Service, Coolant Flush, Differential Oil Replacement Vehicle Type: Passenger Cars, Commercial Trucks, Motorcycles, Heavy Equipment, Specialty Vehicles Sales Channel: Authorized Dealers, Independent Workshops, Quick Service Centers, Mobile Service Providers, Fleet Maintenance Companies Client Type: Fleet Operators, Individual Owners, Rental Companies, Logistics Firms, Government Agencies |
| Companies Covered | Quick PitStop, Q8 Oils, Al-Futtaim Auto & Machinery Co. (FAMCO), ServiceMyCar, Xpress Lube, Valvoline, Lube Express, Gulf Oil Middle East, ZDEGREE, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Automotive Lubrication Services Market Shifts & Advancements
Synthetic lubricant technology is compressing traditional service models while regulatory certification requirements fragment competitive access. These shifts are reshaping how fleet operators select providers and how service centers configure their technical capabilities.
Low-viscosity synthetic formulations (0W-16, 0W-20 grades) are absorbing market share from conventional mineral oils in passenger car segments. Quick service centers in Dubai and Riyadh are adopting these fluids to meet manufacturer warranty requirements for newer engine architectures. The technology is absorbing service bay capacity as technicians require additional training for proper handling and disposal protocols.
SASO enforcement of API SP standards is accelerating equipment upgrades at independent workshops across Saudi Arabia. The regulation mandates specific additive package certifications that legacy dispensing systems cannot verify, forcing capital expenditure on automated fluid management systems. Secondary cities in the Eastern Province are most affected, with workshop consolidation accelerating as smaller operators defer compliance investments.
Fleet procurement teams are unbundling lubrication services from comprehensive maintenance contracts. Large logistics operators in the UAE now negotiate direct bulk supply agreements with lubricant blenders while outsourcing labor-only service execution to third-party bays. This pattern is most visible among e-commerce fulfillment fleets operating 24-hour utilization schedules in the Dubai South logistics cluster.
GCC Automotive Lubrication Services Market Segmentation
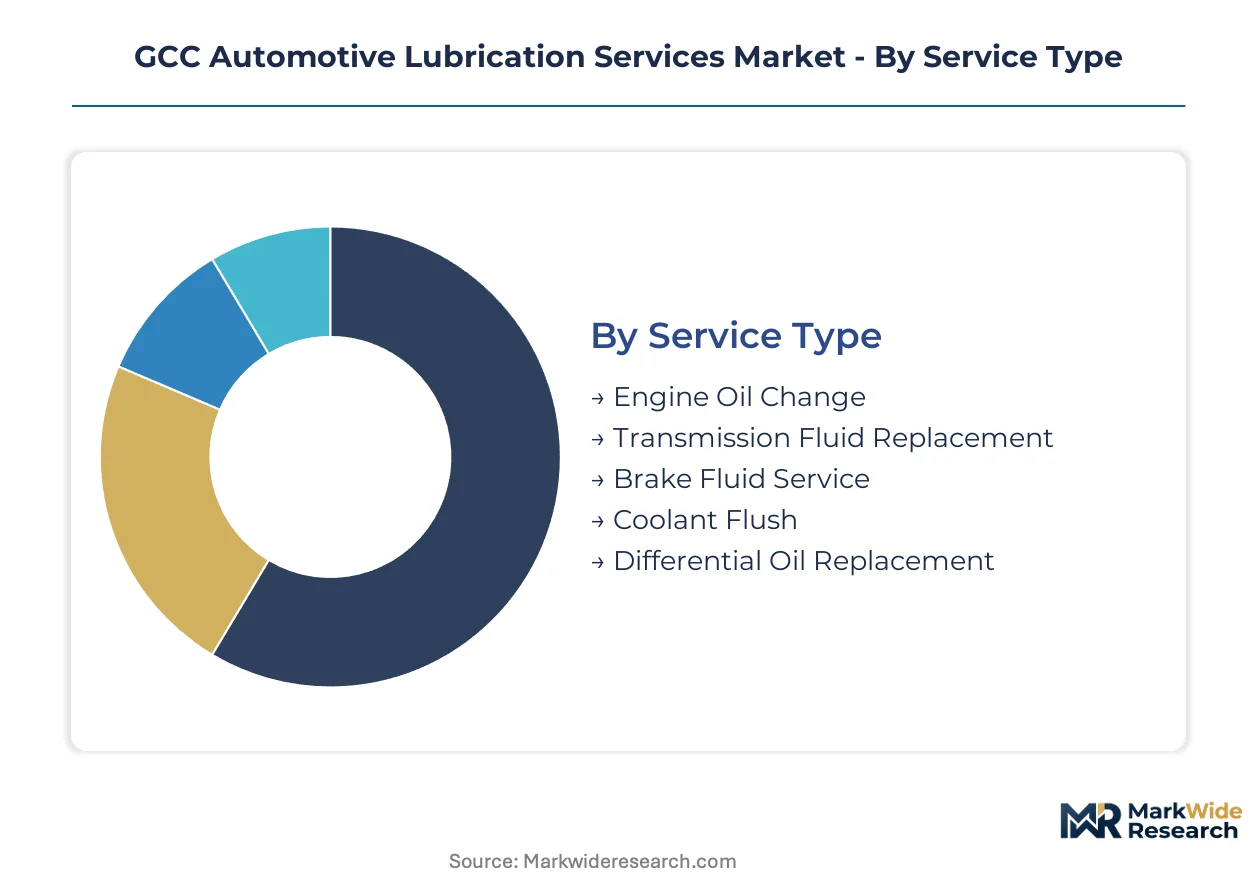
Segmentation in GCC automotive lubrication services reveals how procurement patterns diverge between high-frequency transactional work and long-term contractual relationships. Understanding these splits helps identify where margin compression hits hardest and where certification barriers create defensive moats.
Service Type:
Standardization dominates high-volume engine work while specialized differential and transmission services command customization premiums.
- Engine Oil Change:SAE viscosity-grade oil replacement at manufacturer-specified intervals generates the highest transaction frequency across GCC service bays. Dubai-Abu Dhabi corridor logistics fleets compress these intervals under GSO emission enforcement, driving synthetic formulation demand.
- Transmission Fluid Replacement:Automatic and manual gearbox fluid exchange requires OEM-specific specification databases and temperature-controlled dispensing equipment. Fleet operators in Saudi Arabia's Eastern Province increasingly bundle this with engine services under preventive maintenance contracts.
- Brake Fluid Service:DOT specification fluid replacement addresses moisture absorption in desert operating conditions.
- Coolant Flush:Thermal management system replenishment with ethylene glycol or propylene glycol formulations.
- Differential Oil Replacement:Hypoid gear lubricant service commands premium labor rates due to specialized extraction equipment and limited service bay availability.
Leading the category by volume: Engine Oil Change. Growing fastest: Transmission Fluid Replacement.
Vehicle Type:
Cost tiers separate passenger car commodity services from commercial vehicle premium contracts.
- Commercial Trucks:High-utilization freight vehicles operating 24-hour schedules in UAE logistics clusters require shortened service intervals and bulk synthetic procurement. GSO sulfur caps force these operators toward certified providers with API SP dispensing verification.
- Passenger Cars:Private vehicle lubrication concentrates in quick service centers across Riyadh and Dubai, where low-viscosity synthetic grades (0W-16, 0W-20) now dominate newer engine architectures.
- Motorcycles:Smaller displacement engines with distinct wet clutch lubrication requirements.
- Heavy Equipment:Construction and mining machinery operating in extreme thermal conditions.
- Specialty Vehicles:Ambulance, fire apparatus, and agricultural equipment with OEM-mandated service protocols.
Commercial Trucks generate highest contract value per vehicle. Passenger Cars deliver greatest transaction volume.
Sales Channel:
Geographic concentration of fleet operators favors channel models with corridor-proximate infrastructure.
- Fleet Maintenance Companies:Multi-vehicle lubrication schedules negotiated directly with logistics firms capture superior contract value through bundled inspection and fluid management services. These operators dominate Dubai South and Jebel Ali port hinterlands.
- Quick Service Centers:High-throughput bays in Saudi urban centers specialize in passenger car volume work with standardized 30-minute service guarantees.
- Authorized Dealers:OEM-tied facilities with warranty-compliant fluid specifications and diagnostic integration.
- Independent Workshops:Secondary city operators facing ESMA and SASO certification barriers.
- Mobile Service Providers:On-site lubrication for mining and construction fleets in remote locations.
Fleet Maintenance Companies lead in revenue per transaction. Quick Service Centers expand most quickly in passenger segments.
Client Type:
Procurement sophistication separates institutional buyers from individual consumers.
- Fleet Operators:State-linked and private logistics companies now unbundle lubrication from comprehensive maintenance, negotiating direct bulk supply agreements with blenders while outsourcing labor-only execution. Carbon intensity documentation increasingly shapes tender criteria.
- Logistics Firms:E-commerce fulfillment operators with 24-hour vehicle utilization demand scheduled preventive maintenance at compressed intervals.
- Individual Owners:Price-sensitive retail customers driving quick-lube center volume.
- Rental Companies:Turnover-focused vehicle pools with standardized service protocols.
- Government Agencies:Municipal and state fleet procurement with emerging environmental compliance requirements.
Fleet Operators dominate contract value. Logistics Firms show steepest expansion trajectory in service frequency requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet maintenance contracts concentrate in Saudi Arabia and the UAE, where logistics corridors generate the densest service demand. Qatar, Kuwait, and Oman present expansion frontiers with underdeveloped preventive maintenance cultures. Bahrain's compact geography supports mobile service models.
Saudi Arabia
Commercial truck fleets operating between Riyadh and Dammam compress lubrication intervals under tightening emission protocols. SASO enforcement of API SP standards forces independent workshops in the Eastern Province to upgrade dispensing equipment or exit state-linked procurement. Jeddah's logistics hub attracts quick-service chains targeting e-commerce delivery vehicles with 24-hour utilization schedules.
United Arab Emirates
The Dubai-Abu Dhabi freight corridor generates concentrated demand from high-utilization commercial pools requiring synthetic formulations. ESMA certification requirements filter market access for uncertified operators in secondary emirates. Dubai South's e-commerce fulfillment cluster drives unbundled procurement models where fleet operators negotiate direct bulk supply agreements.
Qatar
Construction-linked heavy equipment fleets dominate lubrication demand around Doha and Lusail development zones. The country's national standardization body mandates lubricant performance certifications aligned with Gulf Standardization Organization frameworks. Ras Laffan's industrial port complex hosts captive maintenance facilities for petrochemical logistics vehicles.
Kuwait
Underdeveloped fleet maintenance cultures create first-mover opportunities for service chains offering bundled inspection packages. The national quality authority implements GSO technical regulations with phased compliance timelines. Al Ahmadi's oil sector logistics operations present contract value concentration for providers with API SP dispensing verification.
Oman
Emerging logistics operators in Muscat and Sohar require education on preventive maintenance economics versus reactive repair models. The national standards and metrology organization adopts SASO-aligned certification requirements with enforcement lag. Sohar Port's free zone attracts regional blender facilities reducing procurement lead times for service centers.
GCC Automotive Lubrication Services Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with quick-service chains dominating passenger car volume while fleet maintenance companies capture superior contract value. The market structure tilts toward consolidation in certified synthetic formulation handling, leaving uncertified independents in secondary cities unable to service state-linked operators. Three archetypes define positioning: multinational lubricant blenders with backward integration into base oil trading, regional quick-service chains with corridor-proximate infrastructure, and fleet-focused maintenance companies with multi-vehicle scheduling capabilities. Competitive moves concentrate on certification compliance investments and bulk supply agreement negotiations with logistics operators.
Among multinational lubricant specialists, Valvoline leverages its blending facility network to secure fleet maintenance contracts, while Q8 Oils occupies a position serving high-temperature desert operating conditions through specialized formulations. Gulf Oil Middle East anchors the regional tier through upstream control over base oil trading across Jebel Ali and Dammam port facilities. These three exemplify how backward integration and certification readiness separate defendable market positions from commodity service execution.
| Leading Market Players |
|---|
| Quick PitStop |
| Q8 Oils |
| Al-Futtaim Auto & Machinery Co. (FAMCO) |
| ServiceMyCar |
| Xpress Lube |
| Valvoline |
| Lube Express |
| Gulf Oil Middle East |
| ZDEGREE |
| Others |
Supply & Pricing Matrix
Synthetic formulation adoption across GCC service bays is compressing mineral oil margins while concentrating procurement power with certified blenders. Fleet operators now negotiate direct bulk agreements, bypassing traditional distributors and forcing independent workshops into price-taking positions.
Pricing Analysis
Volume throughput at quick service centers diverges sharply from contract value at fleet maintenance companies. Three-tier pricing structure across premium synthetic, mid-grade semi-synthetic, and economy mineral levels separates ESMA-certified providers from uncertified independents. Price differentiation hinges on API SP dispensing verification and bulk procurement scale. Pricing pressure stems from fixed-price fleet contracts confronting Group II/III base oil feedstock volatility. Individual owners at quick-lube centers exhibit highest price sensitivity; state-linked fleet operators prioritize certification compliance over unit cost.
Supply Chain Analysis
Regional distribution centers at Jebel Ali and Dammam ports anchor hub-and-spoke patterns feeding service centers across Saudi Arabia and the UAE. Base oil supply concentrates in Kuwait, the UAE, and Saudi Arabia with blending capacity expansion at Sohar Port. Raw material dependencies include Group II/III base oils, additive packages, and specialized high-temperature formulations. Single-source vulnerability around certified additive suppliers creates bottlenecks for SASO compliance. Distribution runs through authorized dealer networks, fleet maintenance companies with captive logistics, and independent workshop channels in secondary cities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified synthetic blending capacity constraints prop pricing power for compliant operators while filtering market access for uncertified independents. This supply-constrained dynamic favors early movers with backward integration into base oil procurement.
For Market Incumbents: Anchor defensible positioning through API SP certification investments at Eastern Province and secondary emirate facilities. Secure multi-year bulk supply agreements with Dubai South e-commerce fleets before base oil price volatility escalates. Deepen backward integration into Jebel Ali port storage capacity to control feedstock costs against Group II/III price swings. For New Entrants and Emerging Players: Launch via mobile service models targeting Omani and Kuwaiti construction fleets with bundled inspection and lubrication packages. Penetrate Muscat and Sohar's underdeveloped preventive maintenance culture before SASO-aligned certification enforcement tightens. Lead with dielectric coolant services for battery electric commercial vehicles entering GCC logistics pools. For Investors and Strategic Acquirers: Re-rating potential sits with fleet maintenance companies possessing ESMA certification and Dubai-Abu Dhabi corridor infrastructure given unbundling trends in procurement. Long-term viability favors operators with verified carbon intensity documentation for state-linked tender access. Monitor GSO sulfur cap enforcement intensity as the inflection signal for certification-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| API SP Certification Investment | SASO enforcement at Saudi independent workshops accelerates equipment upgrade cycles and filters competitive access. |
| Backward Integration into Base Oil Trading | Jebel Ali and Dammam port storage control reduces procurement lead times and buffers feedstock price volatility exposure. |
| Electric Vehicle Thermal Fluid Service Launch | Dielectric coolant and grease formulations for battery electric trucks create high-margin categories distinct from engine oil changes. |
| Fleet Maintenance Contract Unbundling | Direct blender agreements by Dubai South logistics operators separate fluid supply from labor-only service execution. |
| Carbon Intensity Documentation Verification | State-linked procurement tenders increasingly require verified supply chain emissions data for lubricant service providers. |
Research Methodology
Trade publications, customs records, and Gulf Standardization Organization technical filings formed the secondary backbone for market sizing and regulatory mapping. Fleet procurement managers at Saudi and UAE logistics operators, blending facility technical directors, and independent workshop owners in the Eastern Province provided primary perspective on interval compression and certification requirements. Bottom-up service center capacity modeling and top-down lubricant consumption estimates were triangulated against base oil import data.
Historical trendline analysis of service interval compression and synthetic formulation penetration informed projection frameworks across the analysis window. Segmentation dimensions modeled include service type, vehicle class, sales channel concentration, and client procurement sophistication. CAGRs were derived from fitted growth curves applied to fleet expansion patterns and emission regulation phase-in schedules. Forecast inputs incorporated GSO sulfur cap enforcement timelines and base oil infrastructure capacity additions at Sohar and Jebel Ali.
Regulatory enforcement delays, base oil price volatility spikes, and accelerated electric vehicle adoption are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions regarding certification compliance rates and fleet contract renewal patterns. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
India Passenger Vehicles Lubricants Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Automotive Sheet Metal Components Market
Automotive Components
Automotive Grade Modules Market
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
United States Aftermarket Automotive Parts and Components Market
Automotive Components
Automotive Radiator Grille Market
Automotive Components
Automotive Differential Market
Automotive Components
Automotive Sensor Cleaning System Market
Automotive Components
Automotive Spark Plugs and Glow Plugs Market
Automotive Components
Automotive Filters Market
Automotive Components
Asia-Pacific Automotive Parts and Components Market
Automotive Components
Automotive Brake Tube Market
Automotive Components
Global Automotive Plastic Bumper Market
Automotive Components
Canada Automotive Glass Fiber Composites Market
Automotive Components
Global Automotive Brake Components Market