
 Automotive Front-End Module (FEM) Market | 2026-2036
Automotive Front-End Module (FEM) Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Front-End Module (FEM) Market Outlook
ISO 9001 and IATF 16949 qualification cycles is rotating supplier eligibility, locking out uncertified molders and assembly houses from OEM direct contracts. HBPO GmbH leverages its captive bumper-radiator integration lines to dominate European passenger car programs. Valeo sustains technology leadership in active grille shutter systems, while Plastic Omnium anchors global volume through composite material innovations in lightweight front-end carriers.
An automotive front-end module is an integrated assembly comprising the bumper beam, radiator support, grille, headlamp housings, and crash management structures, typically manufactured through injection-molded long-fiber thermoplastics or hybrid steel-composite processes, serving to consolidate multiple exterior and thermal functions into a single subassembly delivered to vehicle assembly lines. Modular bumpers and lighting components carry the deepest margin pools due to styling differentiation and sensor integration complexity, whereas smart grilles and active aerodynamics represent the fastest-expanding technology segment as electrified powertrains demand optimized airflow management. Composite materials compete with advanced high-strength steel in cost-sensitive commercial vehicle applications.
NHTSA's Federal Motor Vehicle Safety Standard 581 shapes bumper impact requirements in the United States, while ECE R94 and the EU General Safety Regulation mandate pedestrian head-impact compliance for grille and hood leading edges, directly influencing FEM architecture and material selection. EPA corporate average fuel economy standards and the EU Green Deal's fleet CO2 targets push OEMs toward lighter, more aerodynamic front-end designs that integrate active airflow control. Stakeholders must monitor how impending Euro 7 emission standards and evolving battery electric vehicle thermal management needs reshape module specification sheets and supplier qualification timelines.
Market Dynamics
Platform consolidation in battery electric vehicles is compressing front-end module architectures toward multi-functional thermal-aerodynamic units, forcing suppliers to merge crash structures with active airflow management in single injection-molded carriers.
Growth Catalysts
- EU General Safety Regulation pedestrian mandates:Head-impact compliance requirements for hood leading edges and grille surfaces are accelerating engineered polymer adoption in bumper-beam assemblies.
- Injection-molded long-fiber thermoplastics:These materials enable 30-40% mass reduction versus stamped steel radiator supports while consolidating 15-20 discrete components into single carriers.
- Stuttgart-Wolfsburg engineering corridor:Dense clustering of OEM technical centers and Tier-1 development facilities compresses prototype-to-production cycles for integrated front-end programs.
Market Restraints
- Steel price volatility:Advanced high-strength steel remains cost-competitive for commercial vehicle bumper beams, limiting composite penetration in price-sensitive fleet segments.
- IATF 16949 certification scarcity:Mold qualification timelines of 18-24 months lock uncertified suppliers out of direct OEM contracts, concentrating supply among incumbent Tier-1s.
- Thermal management complexity:Battery electric vehicle cooling demands exceed legacy radiator support load cases, requiring expensive structural redesigns of carrier architectures.
Strategic Opportunities
- Active grille shutter convergence:Integration of motorized louver systems with radar-transparent grille surfaces opens sensor fusion opportunities in premium electric vehicle segments.
- EU Green Deal fleet CO2 targets:Aerodynamic optimization mandates create pull-through demand for smart airflow modules that reduce drag coefficients at highway speeds.
- Aftermarket modular replacement:Crash repair channels favor bolt-on FEM subassemblies over component-level replacement, expanding addressable service revenue pools.
Industry Challenges
- CAE simulation talent scarcity:Shortage of engineers proficient in long-fiber thermoplastic anisotropic modeling extends validation cycles for new carrier designs.
- Tooling amortization pressure:Multi-cavity injection molds for hybrid steel-composite carriers require 200,000+ unit volumes to break even, constraining program flexibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Front-End Module (FEM) Market |
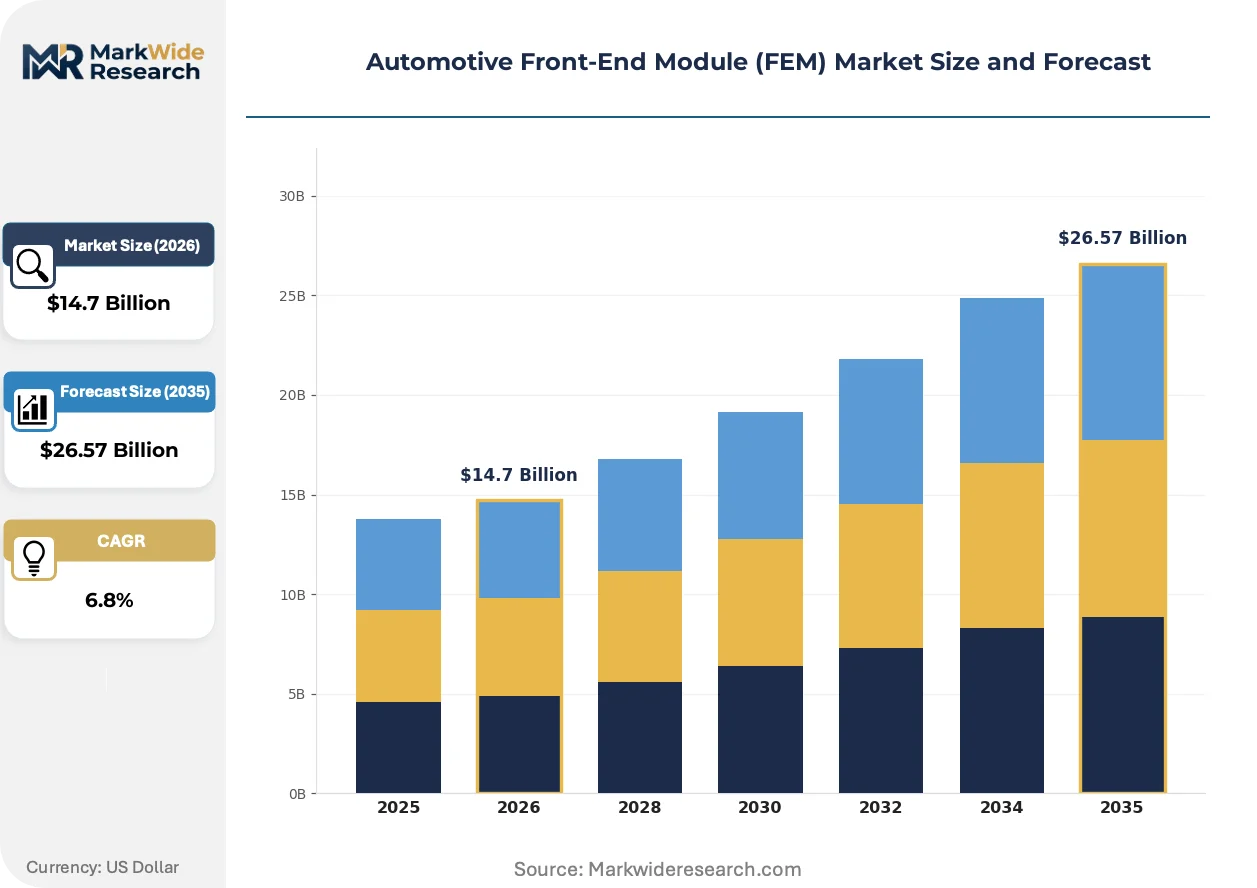
| Market Size in 2026 | $14.7 Billion |
| Market Size in 2035 | $26.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Bumpers, Radiators, Grilles, Lighting Components Technology: Active Aerodynamics, Composite Materials, Advanced Driver Assistance Systems, Smart Grilles End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Market Application: Passenger Vehicles, Commercial Vehicles, Electric Vehicles, Sports Cars |
| Companies Covered | MAHLE GmbH, Plastic Omnium, Hyundai Mobis, Valeo, HBPO GmbH, Faurecia, Magna International, SL Corporation, Denso Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Front-End Module (FEM) Market Strategic Shifts
Material substitution and regulatory compression are redefining front-end module value chains, with functional integration outpacing component-level optimization as the dominant design paradigm.
Continuous fiber-reinforced thermoplastic (CFRTP) tapes are supplanting short-glass compounds in bumper beams for electric vehicle platforms. Premium OEMs in Germany and California are specifying these materials for 2026-2028 model year architectures. CFRTP integration enables load-bearing crash structures to simultaneously house thermal management ducting, collapsing three legacy subsystems into one molded carrier.
REACH restrictions on hexavalent chromium plating are eliminating decorative metal finishes from grille surfaces. ECHA substance-of-very-high-concern listings now cover traditional coating chemistries used in chrome-appearance trim. OEM specification sheets are pivoting toward physical vapor deposition alternatives and painted composite finishes, with German luxury marques leading the transition.
Buyer concentration among electric vehicle pure-plays is compressing supplier negotiation leverage. New OEM entrants with vertically integrated engineering teams are bypassing traditional Tier-1 relationships to source direct from composite molders. This pattern is most pronounced in California and Shanghai, where startup OEMs maintain captive design studios and release module specifications as build-to-print contracts rather than black-box development programs.
Automotive Front-End Module (FEM) Market Segmentation
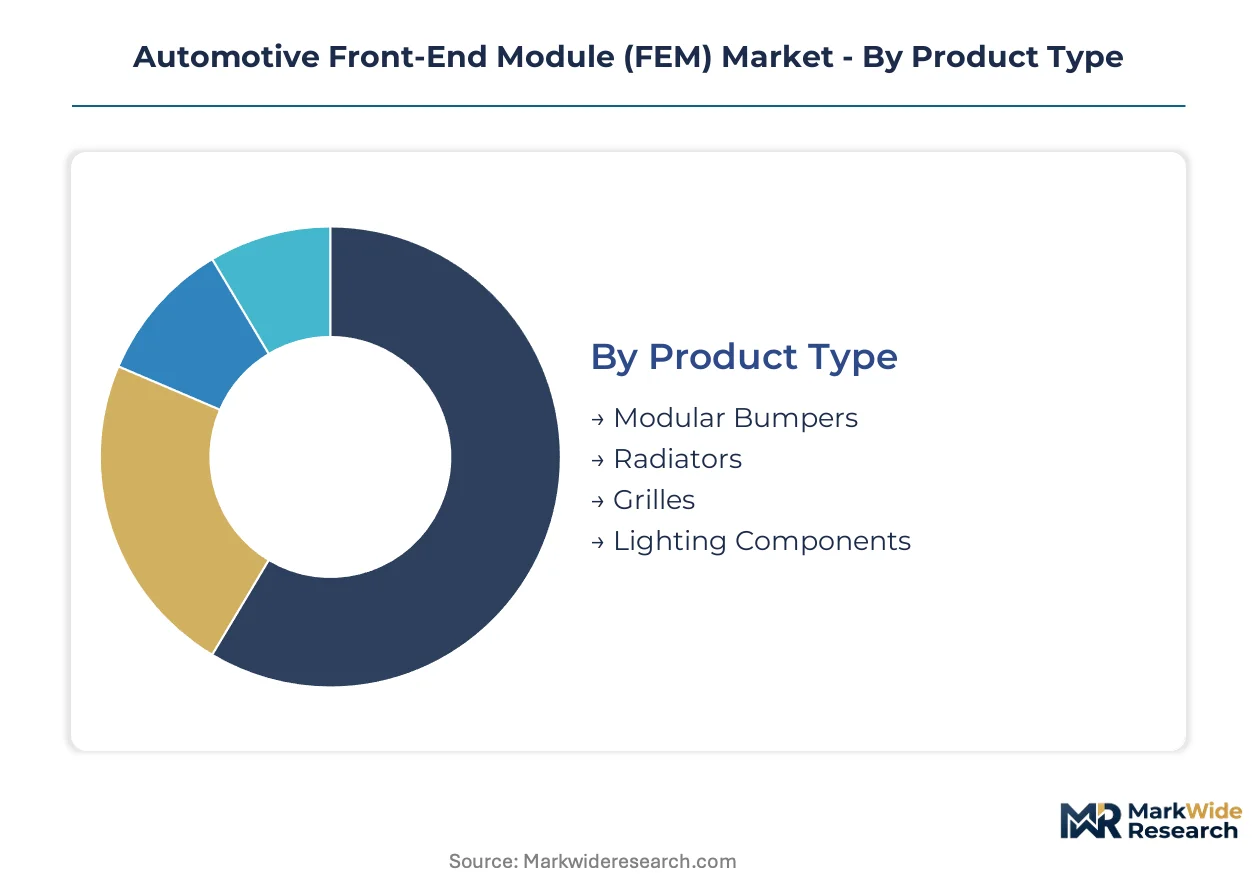
Front-end module segmentation reveals how material substitution and functional integration are fragmenting traditional supply categories. Suppliers must align capability investments with where specification power is shifting across product, technology, and customer dimensions.
Product Type:
Composite-intensive segments face acute substitution pressure from advanced high-strength steel in cost-sensitive commercial applications, while styling-driven modules defend polymer architectures through differentiation value.
- Modular Bumpers:Injection-molded long-fiber thermoplastic carriers consolidate crash management beams with pedestrian energy absorption structures. German luxury OEMs specify these assemblies for integrated sensor mounting and active grille shutter housing, compressing supplier tier structures.
- Radiators:Aluminum core-and-tank assemblies integrated into polymer support carriers serve thermal management functions for internal combustion and hybrid powertrains. Stuttgart engineering corridors concentrate development programs as platform consolidation accelerates.
- Grilles:Radar-transparent composite surfaces with motorized louver systems enable active airflow control for electric vehicle thermal regulation.
- Lighting Components:Headlamp housings and daytime running light carriers merge styling surfaces with sensor integration mounting points.
Modular bumpers anchor the volume base while smart grille integration gains share at the steepest rate.
Technology:
Technology segmentation tracks where specification power is migrating from passive structural performance toward active functional control, reshaping supplier qualification requirements.
- Active Aerodynamics:Motorized grille shutters and deployable spoiler systems modulate airflow to optimize battery thermal management and highway efficiency. California electric vehicle pure-plays specify these systems as standard equipment, pulling development resources from passive grille suppliers.
- Composite Materials:Continuous fiber-reinforced thermoplastic tapes replace short-glass compounds in load-bearing crash structures, enabling component consolidation and mass reduction targets under EPA and EU Green Deal fleet standards.
- Advanced Driver Assistance Systems:Radar and lidar sensor integration requirements dictate grille surface material specifications and mounting precision.
- Smart Grilles:Active louver systems with integrated thermal management ducting collapse legacy subsystems into single molded carriers.
Composite materials command the largest installed base though active aerodynamics climbs the fastest as electrification penetrates premium segments.
End User:
Customer segmentation exposes how buyer concentration and vertical integration are compressing traditional Tier-1 margins and redirecting contract flows.
- OEMs:Volkswagen Group, BMW, and Mercedes-Benz maintain captive engineering centers in Wolfsburg and Stuttgart corridors, releasing build-to-print specifications that bypass traditional supplier development roles. IATF 16949 certification requirements lock direct contracts to qualified molders.
- Tier-1 Suppliers:HBPO GmbH and Valeo anchor European passenger car programs through integrated bumper-radiator assembly lines and active grille shutter technology leadership.
- Aftermarket Providers:Crash repair channels favor bolt-on FEM subassemblies over component-level replacement, expanding service revenue pools.
- Vehicle Assemblers:Contract manufacturers and startup OEMs with vertically integrated engineering teams source direct from composite molders.
Tier-1 suppliers retain the deepest program penetration while OEM direct sourcing expands most quickly among electric vehicle pure-plays.
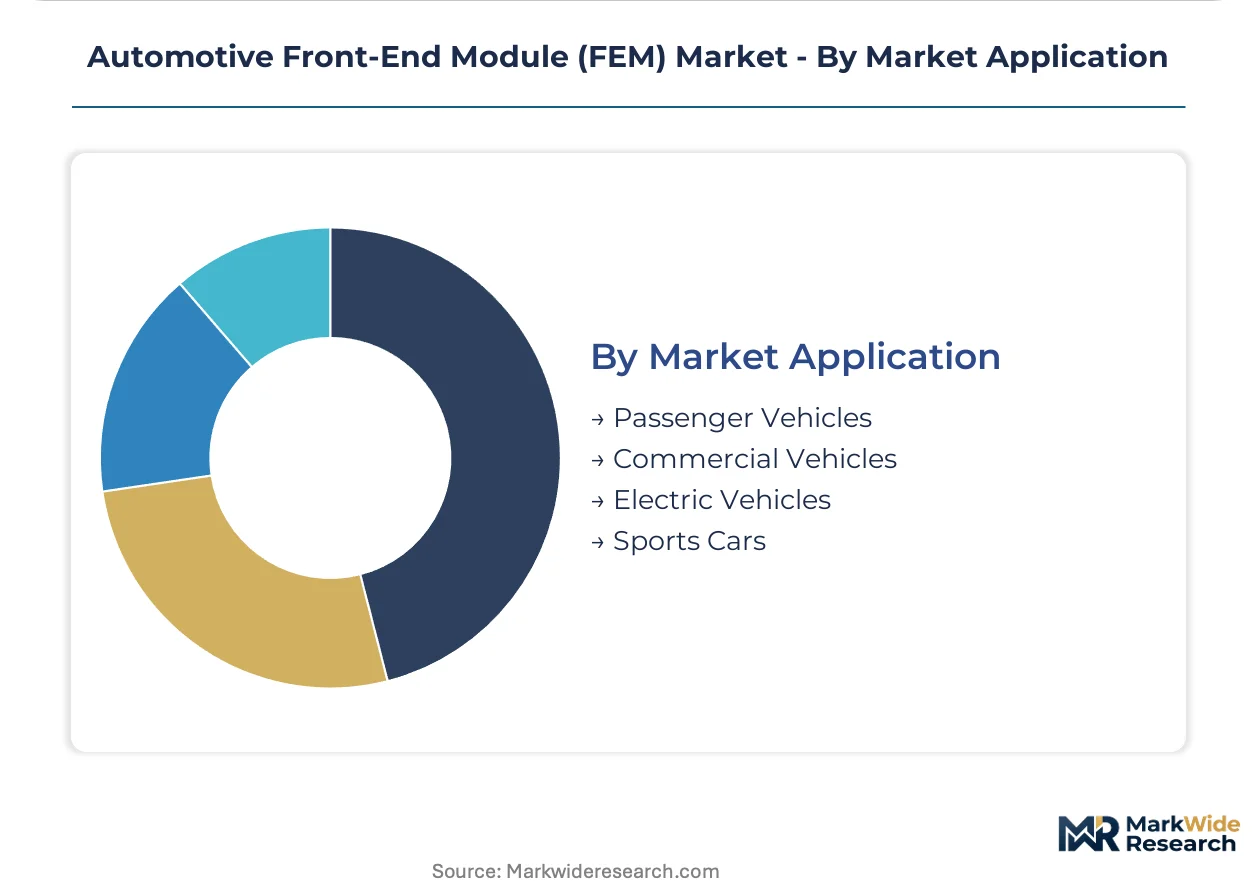
Market Application:
Application segmentation maps how powertrain electrification is rewriting thermal load cases and crash structure requirements across vehicle categories.
- Passenger Vehicles:European C-segment and D-segment platforms drive integrated front-end adoption as ECE R94 pedestrian protection mandates and EU General Safety Regulation compliance tighten material specifications. German automakers lead specification development.
- Electric Vehicles:Battery thermal management demands exceed legacy radiator support architectures, requiring structural redesigns that merge crash structures with active airflow control in single injection-molded carriers.
- Commercial Vehicles:Fleet price sensitivity sustains advanced high-strength steel bumper beams, limiting composite penetration in heavy-duty applications.
- Sports Cars:Low-volume programs prioritize styling differentiation and aerodynamic performance over cost optimization.
Passenger vehicles anchor the volume base while electric vehicle applications expand at the steepest trajectory as platform consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electric vehicle pure-plays and established German luxury OEMs concentrate specification power, compressing supplier negotiation leverage across three continents. Platform consolidation demands are reshaping regional supplier access patterns.
Germany
Stuttgart and Wolfsburg engineering corridors anchor European FEM development as Volkswagen Group, BMW, and Mercedes-Benz release build-to-print specifications. ECE R94 pedestrian protection mandates under EU General Safety Regulation tighten material specifications for bumper-beam assemblies. Baden-Württemberg's supplier density compresses prototype-to-production cycles for integrated front-end programs serving premium passenger car platforms.
United States
NHTSA Federal Motor Vehicle Safety Standard 581 shapes bumper impact requirements while California electric vehicle pure-plays specify active aerodynamics as standard equipment. EPA corporate average fuel economy standards push OEMs toward lighter front-end designs with integrated airflow control. Detroit's technical centers and Silicon Valley engineering studios source direct from composite molders, bypassing traditional Tier-1 development roles.
China
Domestic EV brands with vertically integrated engineering teams release module specifications as build-to-print contracts rather than black-box programs. MIIT fuel consumption and new energy vehicle mandates accelerate composite adoption for mass reduction targets. Shanghai and Yangtze River Delta manufacturing clusters concentrate molding capacity for both domestic OEMs and export programs serving European premium marques.
South Korea
Hyundai Motor Group and battery electric vehicle subsidiaries specify integrated thermal-aerodynamic modules merging crash structures with active grille systems. Korea's national automotive testing and research institute validates pedestrian protection compliance for export-bound assemblies. Seoul Capital Area engineering centers coordinate with Busan-Ulsan manufacturing bases on CFRTP tape integration for 2026-2028 model year architectures.
Japan
Toyota, Honda, and Nissan maintain captive FEM engineering for hybrid and battery electric platforms under METI carbon neutrality roadmaps. JIS standards and type approval processes extend validation cycles for new carrier designs using long-fiber thermoplastics. Nagoya-based technical centers concentrate development resources for composite-intensive front-end architectures serving domestic and North American export markets.
Automotive Front-End Module (FEM) Market Competitive Environment
Player mix skews toward integrated system suppliers with captive bumper-radiator assembly lines and composite material specialists with IATF 16949 certification lock-in. Market structure concentrates among German and French Tier-1s holding direct OEM contracts, while Asian conglomerates defend position through scale and vertical control over molding operations. Two strategic archetypes dominate: full-service module integrators managing black-box development programs, and build-to-print composite molders serving startup OEMs with specification release authority. Competitive moves center on M&A for thermal management capability and capacity expansion for CFRTP tape processing.
Within the European integrated-system tier, HBPO GmbH and Valeo exemplify divergent specialization paths—one through captive assembly line dominance, the other through active airflow technology leadership. Among diversified automotive conglomerates, MAHLE GmbH and Plastic Omnium occupy positions spanning thermal management and exterior systems. Hyundai Mobis anchors the Asian supplier archetype with scale-driven module production tied to captive OEM relationships.
| Leading Market Players |
|---|
| MAHLE GmbH |
| Plastic Omnium |
| Hyundai Mobis |
| Valeo |
| HBPO GmbH |
| Faurecia |
| Magna International |
| SL Corporation |
| Denso Corporation |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month mold qualification timelines concentrate supply among IATF 16949-certified Tier-1s, compressing pricing power for uncertified molders while amplifying margin capture for incumbent integrators with captive bumper-radiator assembly lines in Germany and South Korea.
Pricing Analysis
Cost-plus contracts with steel and polymer indexation dominate OEM-Tier-1 agreements, transferring commodity volatility risk to buyers while preserving supplier margins. Three-tier pricing structure across premium, standard, and economy levels separates active aerodynamics-integrated modules from passive crash structures and commercial vehicle steel beams. Pricing pressure stems from EV pure-plays releasing build-to-print specifications that bypass traditional black-box development premiums. Commercial vehicle fleet buyers exhibit highest price sensitivity due to total-cost-of-ownership procurement models, while German luxury OEMs prioritize styling differentiation over unit cost.
Supply Chain Analysis
Just-in-time sequencing from Stuttgart-Wolfsburg corridor molders to final assembly lines leaves minimal buffer inventory, exposing programs to polymer feedstock disruption. Supply concentrates in Germany, China, and South Korea, with CFRTP tape processing capacity anchoring in Baden-Württemberg and Busan-Ulsan manufacturing bases. Raw material dependencies span long-fiber thermoplastic compounds, aluminum radiator cores, and radar-transparent composite substrates. Single-source vulnerability around specialized injection molding tools for hybrid steel-composite carriers constrains program flexibility. Distribution runs through OEM sequencing centers and Tier-1 module integration facilities rather than aftermarket wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform consolidation in battery electric vehicles is compressing front-end architectures toward multi-functional thermal-aerodynamic units, with EU Green Deal fleet CO2 mandates and Euro 7 emission standards creating regulatory pull-through for integrated module suppliers.
For Market Incumbents: Shield program margins by deepening backward integration into CFRTP tape processing and active grille shutter motorization capabilities, countering EV pure-plays that release build-to-print specifications to bypass traditional Tier-1 development roles. Prioritize capacity expansion in Stuttgart-Wolfsburg corridor to compress prototype-to-production cycles for German OEM captive engineering centers.
For New Entrants and Emerging Players: Aftermarket modular replacement services represent an under-served white-space where crash repair channels favor bolt-on FEM subassemblies over component-level replacement, bypassing incumbent Tier-1 lock-in on new vehicle programs. Target California and Shanghai startup OEMs with vertically integrated engineering teams sourcing direct from qualified composite molders. Lead with build-to-print execution speed rather than black-box development capabilities.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compression play because pedestrian protection mandates and aerodynamic optimization requirements under EU General Safety Regulation and EPA standards continuously reshape module specifications and supplier qualification barriers. Acquisition focus centers on IATF 16949-certified molders with active aerodynamics integration capabilities. Watch for EV platform standardization announcements as inflection signals for module consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| CFRTP Tape Processing Capacity Expansion | Enables load-bearing crash structures to merge thermal ducting in single molded carriers for 2026-2028 EV architectures. |
| Active Grille Shutter Technology Integration | Captures sensor fusion opportunities in premium electric vehicle segments requiring radar-transparent surfaces. |
| Backward Integration into Polymer Compounding | Insulates margin exposure to long-fiber thermoplastic feedstock volatility and REACH compliance costs. |
| Sequencing Center Proximity to Stuttgart Corridor | Compresses logistics costs and prototype iteration cycles for Volkswagen Group and Mercedes-Benz programs. |
| Aftermarket Modular Replacement Channel Development | Expands addressable revenue pools as crash repair regulations favor bolt-on subassembly replacement. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across OEM platform engineering, Tier-1 procurement, and aftermarket distribution functions. Primary fieldwork encompassed composite molder operations directors, IATF 16949 certification auditors, and thermal management system architects. Secondary validation drew from vehicle production databases, ECE R94 pedestrian protection test protocols, EU General Safety Regulation implementation guidance, and customs records tracking polymer compound imports. Bottom-up unit economics triangulated against top-down OEM platform volume allocations.
Across the analysis window, forecasts model vehicle class, propulsion architecture, content per vehicle, and regional production cluster dimensions. CAGRs derive from segment-level demand elasticity assessments against regulatory mandate timelines and platform consolidation roadmaps. EV thermal load case requirements and active aerodynamics penetration curves serve as primary forecast sensitivity inputs.
Forecasts assume regulatory continuity in EU Green Deal implementation and NHTSA bumper standards; material policy shifts would require re-modeling. Revision becomes warranted when EV platform standardization announcements or REACH substance restrictions cross implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Air Deflector Market
Automotive Components
Automotive Pressure Plate Market
Automotive Components
Europe Automotive Electric Actuators Market
Automotive Components
Global Automotive Interior Component Market
Automotive Components
Automotive Engine Connecting Rods Market
Automotive Components
Automotive Connecting Rod Market
Automotive Components
North America Automotive Bearing Market
Automotive Components
Global Automotive Carbon Ceramic Brake Rotors Market
Automotive Components
France Automotive Market
Automotive Components
Europe Automotive Glass Market
Automotive Components
Europe Automotive Plastics Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
Automotive Towbar Market
Automotive Components
Alloys for Automotive Market
Automotive Components
Automotive Catalytic Converter Market
Automotive Components
Automotive Metal Stamping Market