
 Global Automotive Active Body Panel Market | 2026-2036
Global Automotive Active Body Panel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Active Body Panel Market Intelligence
Software-defined aerodynamic profiles, activated through subscription services, is shifting the value proposition from a one-time hardware sale to recurring revenue streams. Mercedes-Benz Group AG integrates these systems deeply into its premium EV models for performance differentiation. Porsche AG leverages active panels to optimize track performance and road efficiency in its sports cars. Hyundai Mobis operates as a key Tier-1 supplier, providing advanced electromechanical actuation technologies to multiple original equipment manufacturers.
Automotive active body panels are mechatronic components that dynamically alter a vehicle's exterior shape to optimize performance. These systems use electromechanical actuators or shape memory alloys to adjust elements like grilles and spoilers, reacting in milliseconds to changing driving conditions. Active spoilers represent the fastest-growing product type, driven by their dual benefit in high-speed stability and visual appeal. Fuel efficiency enhancement remains the dominant application, as automakers use these panels to meet stringent emissions targets.
Regulations like the US EPA's fuel economy standards and the EU Green Deal's CO2 targets create direct incentives for aerodynamic efficiency technologies. In China, GB standards for vehicle safety and performance also influence the adoption of features like impact-adaptive panels. The key decision for OEMs now revolves around standardizing these features for mass-market vehicles versus reserving them for premium performance tiers.
Market Dynamics
The imperative for automakers to meet stringent CO2 emissions targets, particularly the EU Green Deal, serves as the central force shaping the market. This regulatory pressure compels the adoption of aerodynamic efficiency technologies, moving them from niche performance features to mainstream components.
Growth Catalysts
- Regulatory Mandates:The EU Green Deal and US EPA fuel economy standards create direct financial and compliance incentives for automakers to deploy technologies like active grille shutters and spoilers that reduce aerodynamic drag and improve efficiency.
- EV Performance Optimization:Within the luxury electric vehicle segment, active body panels are used to extend battery range by minimizing drag and to enhance driving dynamics, providing a key point of performance differentiation.
- Material and Actuator Advances:The development of lightweight shape memory alloys and compact, powerful electromechanical actuators lowers the weight penalty and packaging complexity of these systems, making them viable for a wider range of vehicle platforms.
Market Restraints
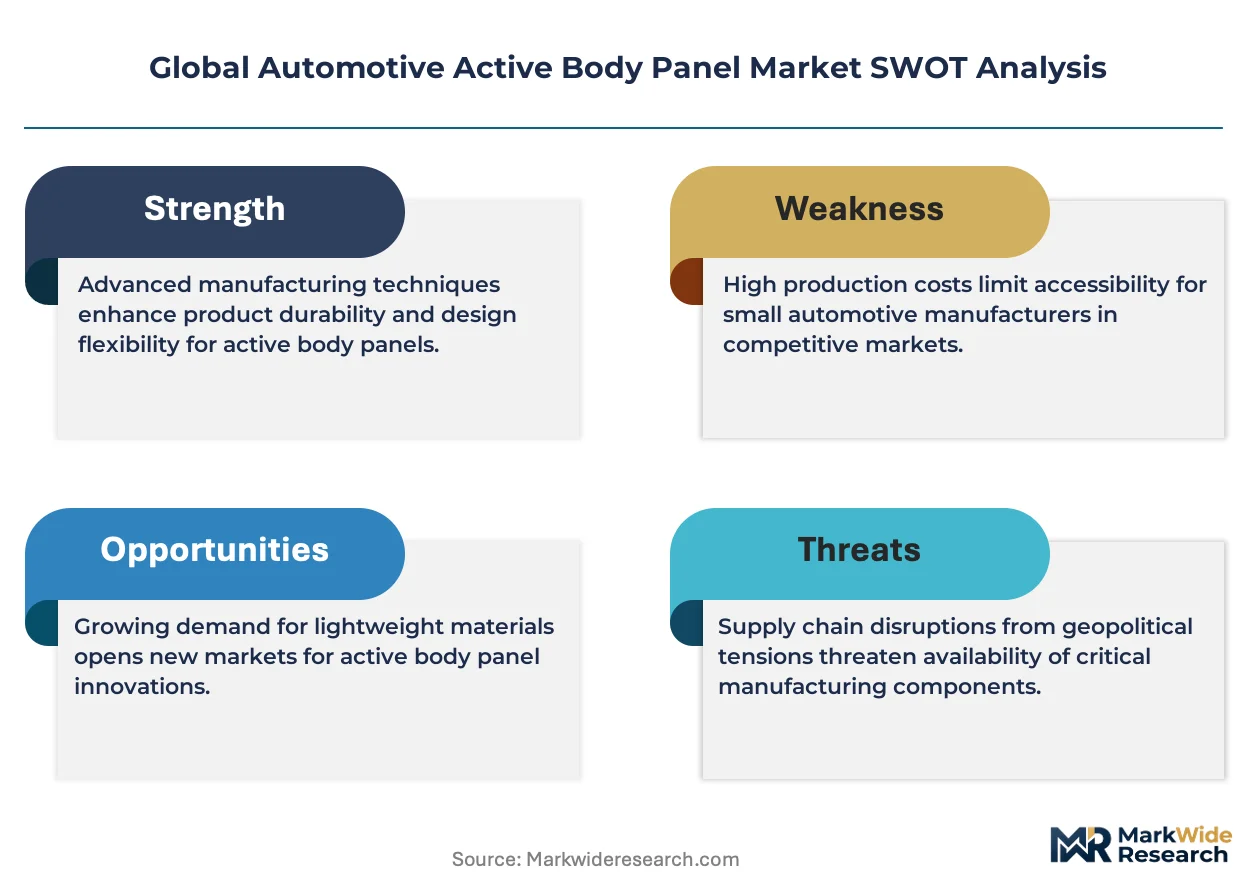
- High System Cost:The significant upfront cost of mechatronic components, including sensors, actuators, and controllers, limits the adoption of active body panels to premium vehicle segments, creating a barrier for mass-market deployment.
- Supply Chain Concentration:A limited number of Tier-1 suppliers possess the specialized expertise in advanced electromechanical actuation and control software, creating potential bottlenecks and pricing power concentration within the supply chain.
- Durability and Reliability Concerns:The long-term reliability of movable exterior parts exposed to harsh environmental conditions like ice, debris, and extreme temperatures remains a significant engineering and warranty-related concern for original equipment manufacturers.
Strategic Opportunities
- Commercial Vehicle Aerodynamics:Applying active aerodynamic systems to long-haul trucks and commercial fleets presents a substantial opportunity to generate significant fuel savings, offering a clear and rapid return on investment for fleet operators.
- Integration with ADAS:Linking active body panels with advanced driver-assistance systems allows for predictive aerodynamic adjustments based on navigation data, traffic conditions, and vehicle speed, creating a smarter and more efficient performance envelope.
- Aftermarket and Customization:A developing opportunity exists in the automotive aftermarket for modular active aerodynamic kits, allowing owners of performance and modified vehicles to add or upgrade these features for track use or aesthetic purposes.
Industry Challenges
- Software Integration Complexity:Integrating the control logic for active panels with a vehicle's core electronic control unit (ECU) architecture is a major challenge, requiring complex software validation to ensure seamless and safe operation across all driving modes.
- Lack of Standardization:The absence of industry-wide standards for communication protocols and physical interfaces between panel modules and vehicle systems increases development time and cost for both OEMs and suppliers.
- Mechatronics Talent Scarcity:A shortage of engineers with combined expertise in mechanical engineering, electronics, and software development specific to the automotive domain constrains the design and validation capacity of many organizations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Active Body Panel Market |
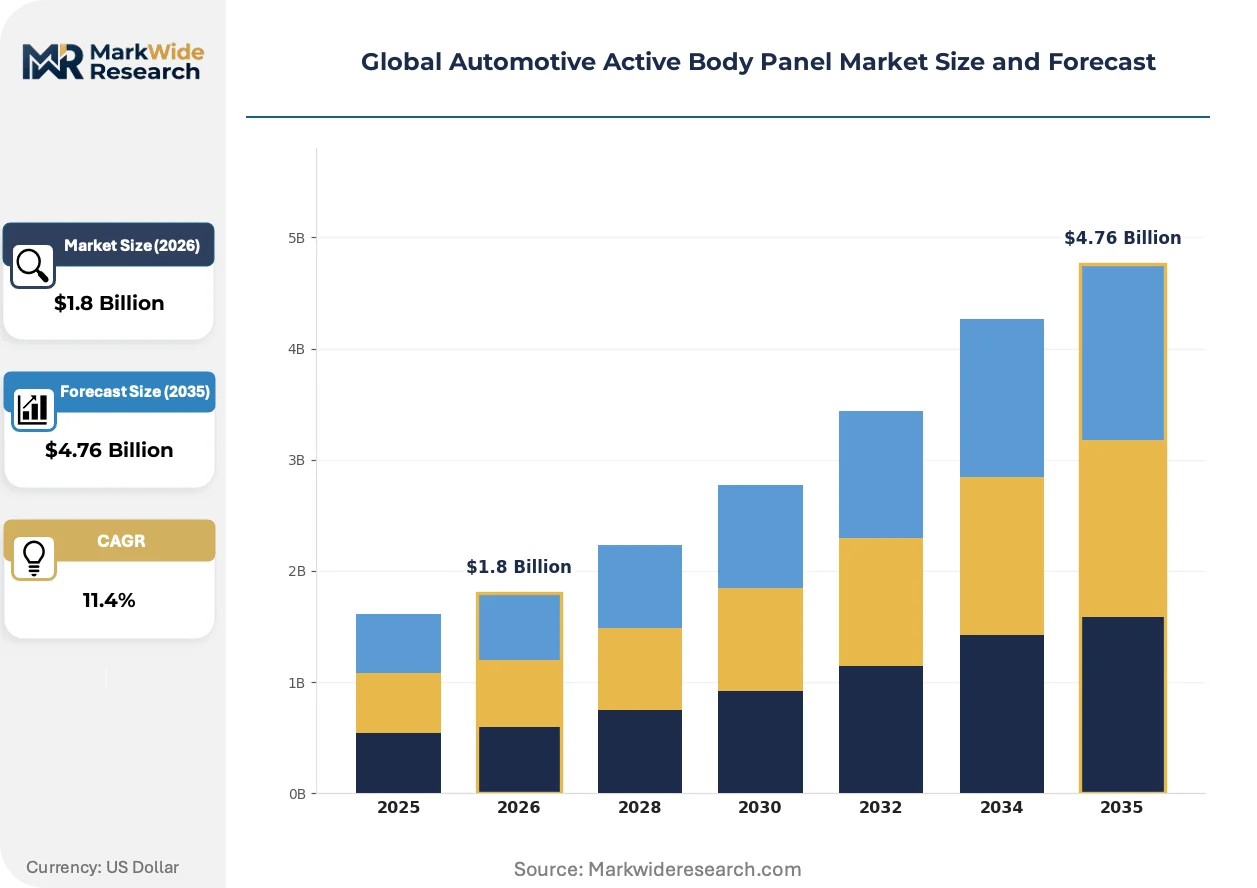
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Active Grilles, Active Spoilers, Adaptive Fender Flares, Dynamic Wheel Arch Covers Technology: Electromechanical Actuation, Pneumatic Systems, Hydraulic Systems, Shape Memory Alloys Application: Fuel Efficiency Enhancement, Vehicle Aerodynamics, Impact Protection, Thermal Management End User: OEM Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | BMW AG, Audi AG, Mercedes-Benz Group AG, Porsche AG, Ford Motor Company, General Motors, Volkswagen AG, Toyota Motor Corporation, Hyundai Mobis, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Active Body Panel Market Strategic Shifts & Innovations
The evolution from static, fixed bodywork to dynamic, software-defined surfaces is reshaping vehicle design and performance capabilities. This transition enables vehicles to physically adapt to their environment and driver inputs in real time, unlocking new levels of efficiency and dynamic control.
Shape memory alloys (SMAs) provide a lightweight, silent, and compact alternative to traditional electromechanical actuators. Premium automakers are adopting SMAs for applications like active grille shutters where space and noise are critical design constraints. This technology is modularizing the construction of active aerodynamic systems, allowing for more integrated and less complex component designs that can be easily adapted across different vehicle platforms.
In the United States, the EPA's fuel economy standards directly incentivize the use of technologies that reduce aerodynamic drag. This regulatory pressure forces automakers to incorporate active aerodynamic features to meet fleet-wide efficiency targets. The mass-market SUV and sedan segments are most affected, prompting a strategic shift to standardize components like active grille shutters previously reserved for luxury or performance models.
A notable behavioral shift is the consumer acceptance of software-enabled features activated via subscription or over-the-air updates. This trend is disrupting the traditional one-time hardware purchase model, as automakers explore recurring revenue by offering enhanced aerodynamic modes or performance settings as a digital service. This model is most prominent in the premium EV sector in Europe and North America, where software defines much of the user experience.
Global Automotive Active Body Panel Market Segmentation
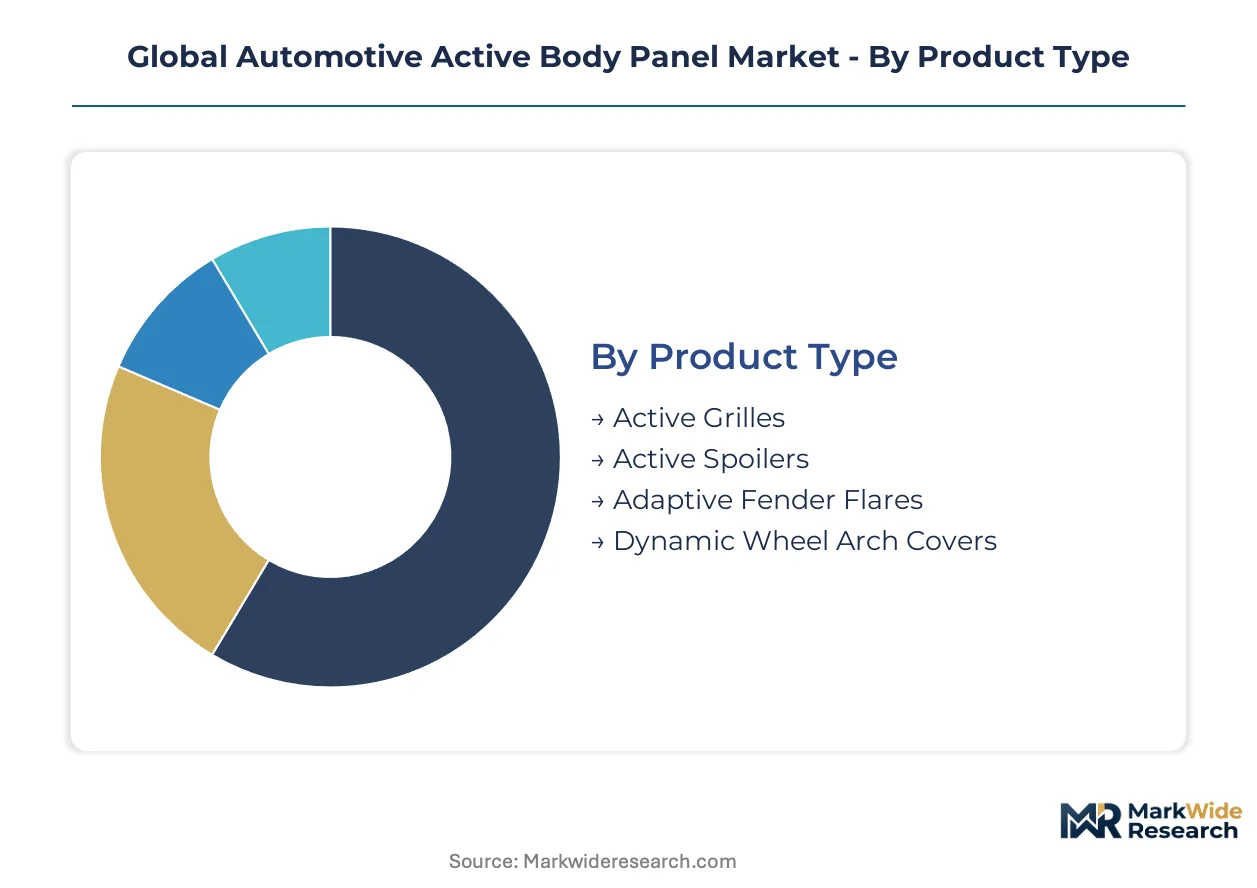
The Global Automotive Active Body Panel Market is defined by diverse product types, technologies, applications, and end-users. Understanding these segments reveals where innovation is concentrated and where value is created across the automotive supply chain. This segmentation highlights the various ways active body panels contribute to vehicle performance.
Product Type:
Automakers prioritize specific product types based on their impact on vehicle performance and design integration.
- Active Grilles:These components dynamically open and close to manage airflow to the engine bay or battery, reducing aerodynamic drag at high speeds and improving cooling when needed. Demand concentrates in mass-market SUV and sedan segments to meet stringent fuel economy standards.
- Active Spoilers:Positioned at the rear of a vehicle, these deploy to increase downforce for enhanced high-speed stability and braking performance, while retracting for reduced drag. Their visual appeal and performance benefits drive significant adoption within premium electric vehicles.
- Adaptive Fender Flares:These panels adjust their position to optimize airflow around the wheel wells, particularly for vehicles with variable ride heights or specialized performance requirements.
- Dynamic Wheel Arch Covers:Designed to minimize air turbulence around the wheels, these covers contribute to overall vehicle efficiency and are increasingly seen in concept and premium EV models.
Volume sits with Active Grilles; growth tilts toward Active Spoilers.
Technology:
The choice of actuation technology dictates the responsiveness, packaging, and cost of active body panel systems.
- Electromechanical Actuation:This technology uses electric motors, gears, and linkages to provide precise and robust control over movable body panels, offering wide applicability across various vehicle types. It represents the most common method for deploying active aerodynamic elements due to its reliability and proven performance.
- Shape Memory Alloys:These advanced materials can return to a pre-defined shape when heated, offering a lightweight, compact, and silent alternative to traditional actuators for applications like active grille shutters. Premium automakers are exploring SMAs for their integration benefits in space-constrained designs.
- Pneumatic Systems:Utilizing compressed air to move components, pneumatic systems offer rapid response times suitable for certain specialized active aerodynamic applications.
- Hydraulic Systems:Employing pressurized fluid, hydraulic systems provide high force output, making them suitable for heavier or more robust active body panel movements in select vehicle platforms.
Electromechanical actuation remains the dominant technology, while shape memory alloys are gaining share fastest for compact designs.
Application:
Manufacturers deploy active body panels to address critical functional requirements and differentiate vehicle capabilities.
- Fuel Efficiency Enhancement:This primary application involves reducing aerodynamic drag to lower fuel consumption in internal combustion engine vehicles and extend battery range in electric vehicles. Regulations like the EU Green Deal directly incentivize this application across all vehicle segments.
- Vehicle Aerodynamics:Beyond basic efficiency, active panels optimize overall vehicle aerodynamics for improved handling, stability, and high-speed performance. Luxury sports cars and high-performance electric vehicles leverage these systems for dynamic driving differentiation.
- Impact Protection:Some active panels are designed to deploy pre-emptively or reactively to mitigate pedestrian impact or enhance occupant safety in certain collision scenarios.
- Thermal Management:Active panels contribute to managing engine or battery temperatures by controlling airflow, ensuring optimal operating conditions and system longevity.
Fuel efficiency enhancement drives the largest demand, with vehicle aerodynamics expanding most quickly in performance segments.
End User:
Value chain participants focus on distinct customer types, each with unique requirements for integration and scale.
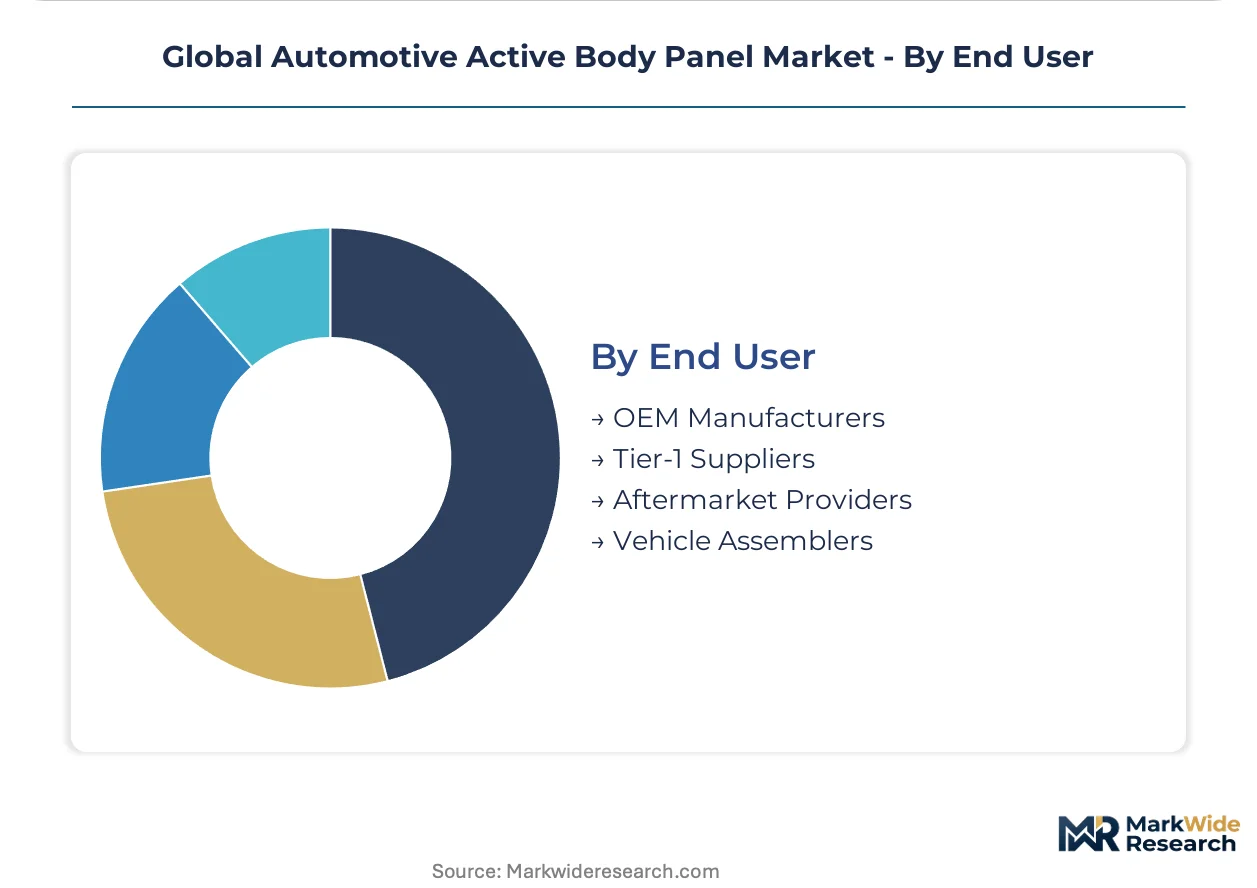
- OEM Manufacturers:These are the primary customers, integrating active body panel systems directly into their vehicle production lines to meet design, performance, and regulatory objectives. They demand high reliability and seamless integration with vehicle electronics.
- Tier-1 Suppliers:Companies like Hyundai Mobis develop and supply complete active body panel modules and actuation systems to OEM manufacturers, playing a crucial role in technology development and mass production. Their expertise is critical for component standardization.
- Aftermarket Providers:This segment caters to vehicle owners seeking to upgrade or customize their vehicles with active aerodynamic components for aesthetic or performance enhancements.
- Vehicle Assemblers:These entities are responsible for the final integration and testing of active body panel systems within the broader vehicle assembly process, ensuring functional integrity.
OEM manufacturers represent the largest customer base, with Tier-1 suppliers experiencing significant growth in component demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The production-vs-consumption dynamic shapes the global automotive active body panel market. Automakers in major manufacturing regions drive demand for advanced aerodynamic solutions. This market sees a concentration of both technology development and vehicle integration in key automotive hubs.
Germany
Germany's automotive manufacturing hubs concentrate significant demand for active body panels. The EU Green Deal's stringent CO2 emission standards compel German automakers to integrate these efficiency technologies. Stuttgart and Munich, centers for premium automotive brands, are particularly active in developing and applying these systems.
United States
United States automakers prioritize active body panels for meeting fuel economy standards. The US EPA's regulations directly incentivize the adoption of drag-reducing technologies across vehicle fleets. Detroit, Michigan, remains a critical hub for automotive R&D and production, driving integration into mass-market vehicles.
China
China's automotive market sees increasing adoption of active body panels, driven by performance and efficiency demands. GB standards for vehicle safety and performance influence the integration of features like impact-adaptive panels. The Yangtze River Delta region, a major automotive production base, is a key area for domestic and international OEM uptake.
South Korea
South Korea's advanced component supply chains are central to active body panel development and production. The country's strong focus on EV technology and export markets encourages the integration of performance-enhancing aerodynamics. Seoul and Ulsan, home to major automotive manufacturers and suppliers, are at the forefront of electromechanical actuation advancements.
Japan
Japanese automotive manufacturers are integrating active body panels to enhance vehicle efficiency and dynamics. METI's initiatives supporting advanced automotive technologies contribute to R&D in this sector. The Nagoya region, a core of Japan's automotive industry, sees significant investment in innovative aerodynamic solutions.
Global Automotive Active Body Panel Market Key Industry Players
Capital-heavy producers compete with asset-light designers in the automotive active body panel market. The market exhibits a tiered structure, with established OEMs driving demand and specialized Tier-1 suppliers providing advanced modules. Strategic archetypes include integrated automotive groups, dedicated mechatronics suppliers, and emerging software-defined vehicle specialists. Dominant competitive moves involve strategic partnerships for technology co-development and capacity expansion in advanced manufacturing.
Within the integrated automotive group archetype, Mercedes-Benz Group AG and Porsche AG exemplify premium vehicle manufacturers leveraging active body panels for performance differentiation and brand appeal. These German automotive giants integrate advanced aerodynamic systems into their high-end models, optimizing both efficiency and dynamic control capabilities. Hyundai Mobis, a prominent South Korean firm, occupies a critical position as a key Tier-1 supplier, providing specialized electromechanical actuation technologies to multiple original equipment manufacturers across the globe, thereby anchoring the supply chain for these complex systems.
| Leading Market Players |
|---|
| BMW AG |
| Audi AG |
| Mercedes-Benz Group AG |
| Porsche AG |
| Ford Motor Company |
| General Motors |
| Volkswagen AG |
| Toyota Motor Corporation |
| Hyundai Mobis |
| Others |
Cost & Logistics Intelligence
OEM manufacturers' concentrated demand for active body panels directly influences the dominant transactional pricing model. This model incorporates value-based elements for advanced features and software-defined functionalities in premium segments.
Pricing Analysis
Margin tightening in the mass-market segment reflects the high upfront cost of mechatronic components. The market primarily uses a per-unit transactional pricing model for hardware, complemented by subscription services for software-defined features. Price differentiation stems from performance differentiation and customization levels for premium vehicles. Mass-market OEMs exhibit higher price sensitivity compared to luxury vehicle manufacturers.
Supply Chain Analysis
Logistics and freight costs represent a significant component of the overall delivered price for active body panel systems. Geographic supply concentration centers on South Korea for advanced component manufacturing and Germany for integrated system development. The supply chain draws from specialized inputs like electromechanical actuators and shape memory alloys. Single-source vulnerability with key Tier-1 suppliers creates a structural risk. Distribution runs through a direct model from Tier-1 suppliers to OEM manufacturing plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a technology-transition phase, with software-defined surfaces progressively replacing traditional static bodywork. This shift redefines vehicle performance and revenue models.
For Market Incumbents:
Cement strategic partnerships with software developers to deepen integration of active panel control logic into vehicle ECUs. Standardizing component interfaces across vehicle platforms can mitigate the high system cost threat. Mercedes-Benz Group AG and Porsche AG should invest in R&D for advanced materials like shape memory alloys, expanding their application beyond niche uses. Expanding production capacity for these advanced systems in key automotive manufacturing hubs would reinforce market position.
For New Entrants and Emerging Players:
Aftermarket specialists represent a penetrable segment for modular active aerodynamic kits. Targeting commercial vehicle aerodynamics offers a white-space opportunity for significant fuel savings. A go-to-market angle focusing on performance enhancement and customization via subscription-based upgrades can attract performance vehicle owners. Independent software vendors can develop platform-agnostic control algorithms, offering a differentiated solution.
For Investors and Strategic Acquirers:
The window for entry favors specialized mechatronics suppliers and software integration firms with proven automotive expertise. Long-term viability extends beyond a 5-10 year horizon as active panels move into mass-market vehicles. Acquisition targets should possess strong intellectual property in electromechanical actuation or software validation. The signal to watch is the standardization of active grille shutters in high-volume SUV and sedan segments.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Aerodynamics Investment | Deepens integration of dynamic profiles, enabling recurring revenue streams for automakers. |
| Advanced Actuator Technology Development | Reduces system weight and packaging complexity, expanding application to diverse vehicle types. |
| Commercial Fleet Integration Partnerships | Unlocks significant fuel savings for long-haul trucks, offering clear return on investment. |
| Aftermarket Modular Kit Launch | Captures customization demand from performance vehicle enthusiasts, diversifying revenue. |
| Standardization of Communication Protocols | Lowers development costs and accelerates adoption across multiple OEM platforms. |
Research Approach
EU Green Deal reports, US EPA publications, and GB standards documents formed the secondary backbone for this analysis. This was combined with primary interviews with OEM platform engineers, Tier-1 supplier R&D leads, automotive design specialists, and regulatory compliance officers. The study employed both bottom-up and top-down triangulation to ensure data accuracy and consistency across market segments.
Historical trendline analysis provided the foundation for projecting market expansion across the analysis window. The forecast framework modeled segmentation dimensions including product type, technology, application, end-user, and regional production clusters. Compound annual growth rates were derived from historical data and projected market drivers, incorporating inputs like EV adoption rates and CO2 emission targets.
Caveats apply where raw material price volatility, geopolitical trade policies, or rapid technological obsolescence could materially shift the outlook. Forecasts reflect assumptions documented through extensive research and expert consultations. Stakeholders should weigh assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Global Automotive Collapsible Steering Column Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
Global Automotive Plastic Compounding Market
Automotive Components
Automotive Ignition Box Market
Automotive Components
Automotive Stamped Component Market
Automotive Components
Automotive Rear End Module Market
Automotive Components
Automotive Braking Component Market
Automotive Components
Brazil Automotive Composites Market
Automotive Components
Argentina Automotive Composites Market
Automotive Components
North America Automotive Hydraulic Actuators Market
Automotive Components
India Automotive Heat Exchanger Market
Automotive Components
Global Automotive Selector Lever Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
Platinum Automotive Catalyst Market
Automotive Components
Aftermarket Automotive Parts & Components Market