
 Automotive Stainless Steel Tubes Market | 2026-2036
Automotive Stainless Steel Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Stainless Steel Tubes Market Analysis
The direct mill-to-OEM supply channel is narrowing as Tier-1 suppliers consolidate procurement power. ArcelorMittal leverages its integrated European steelmaking network to control alloy feedstock costs. JFE Steel Corporation anchors its position through specialized ferritic grades for exhaust applications. Thyssenkrupp AG competes on precision cold-drawing capabilities for fuel and brake line tolerances.
Automotive stainless steel tubes are corrosion-resistant hollow sections, typically manufactured from austenitic 300-series or ferritic 400-series alloys via seamless extrusion or electric resistance welding, engineered to withstand thermal cycling and chemical exposure in underhood and underbody environments. Seamless tubes command premium positioning in high-pressure fuel line applications where wall uniformity eliminates leak paths. Welded products dominate exhaust system volumes where cost efficiency outweighs the performance margin of seamless alternatives. Grade 409 leads structural exhaust demand for its oxidation resistance at elevated temperatures, while Grade 316 gains share in flex-fuel and corrosive fuel line configurations.
EPA tailpipe standards, Euro 7 emissions frameworks, and Japan's METI fuel efficiency regulations collectively mandate lighter, more durable exhaust architectures that favor advanced stainless grades. NHTSA structural safety requirements for fuel system integrity further tighten material specifications for line applications. Stakeholders must monitor alloy surcharge volatility and regulatory phase-in timelines to time capacity investments and grade portfolio shifts.
Market Dynamics
Exhaust system architecture is undergoing forced redesign as Euro 7 and EPA tailpipe standards mandate higher thermal efficiency and reduced NOx output, compelling OEMs to specify thicker-walled, higher-alloy tubes that withstand extended thermal cycling and corrosive condensate exposure.
Growth Catalysts
- Euro 7 Implementation:The framework's stricter particulate and NOx limits are accelerating replacement of aluminized mild steel with Grade 409 and 441 stainless in exhaust manifolds and after-treatment housings across European OEM platforms.
- Hybrid Powertrain Thermal Loads:Start-stop cycling and intermittent engine operation in PHEVs generate more corrosive condensate, expanding specification of stabilized ferritic grades for muffler and resonator assemblies.
- Japan METI Efficiency Mandates:Vehicle weight reduction targets are driving hollow-section stainless substitution for solid bar stock in chassis and structural tubing applications.
Market Restraints
- Nickel Price Volatility:Austenitic 300-series grades remain exposed to London Metal Exchange nickel surge events, compressing margin visibility for tube mills serving fuel line and sensor housing segments.
- Chinese Capacity Concentration:Over half of global welded tube output originates from Zhejiang and Jiangsu province mill clusters, creating single-source vulnerability for European Tier-1 exhaust module suppliers.
- Aluminum Substitution in EV Thermal Management:Battery cooling circuits increasingly specify aluminum extrusions over stainless tubing for weight savings, displacing legacy Grade 304 specifications in non-exhaust fluid lines.
Strategic Opportunities
- India PLI Scheme for Auto Components:Production-linked incentives for advanced materials manufacturing are attracting greenfield stainless tube capacity to serve Maruti Suzuki and Tata Motors domestic supply chains.
- Hydrogen Fuel Cell Stack Manifolds:Proton exchange membrane systems require 316L-grade tubing with sub-ppm sulfur content for hydrogen compatibility, opening premium specification tiers absent in conventional ICE applications.
- Direct Mill-to-OEM Digital Procurement:Blockchain-verified alloy certification platforms are enabling bypass of traditional distributor markup for high-volume exhaust system contracts.
Industry Challenges
- Dual-Certification Timeline Compression:Simultaneous IATF 16949 and ISO 14001 audits for new mill qualifications are extending supplier onboarding to 18-24 months, delaying program launches.
- Seamless Cold-Drawing Skill Scarcity:Retirement of European tool-and-die specialists proficient in multi-pass pilger reduction is constraining capacity expansion for high-pressure fuel injection tubing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Stainless Steel Tubes Market |
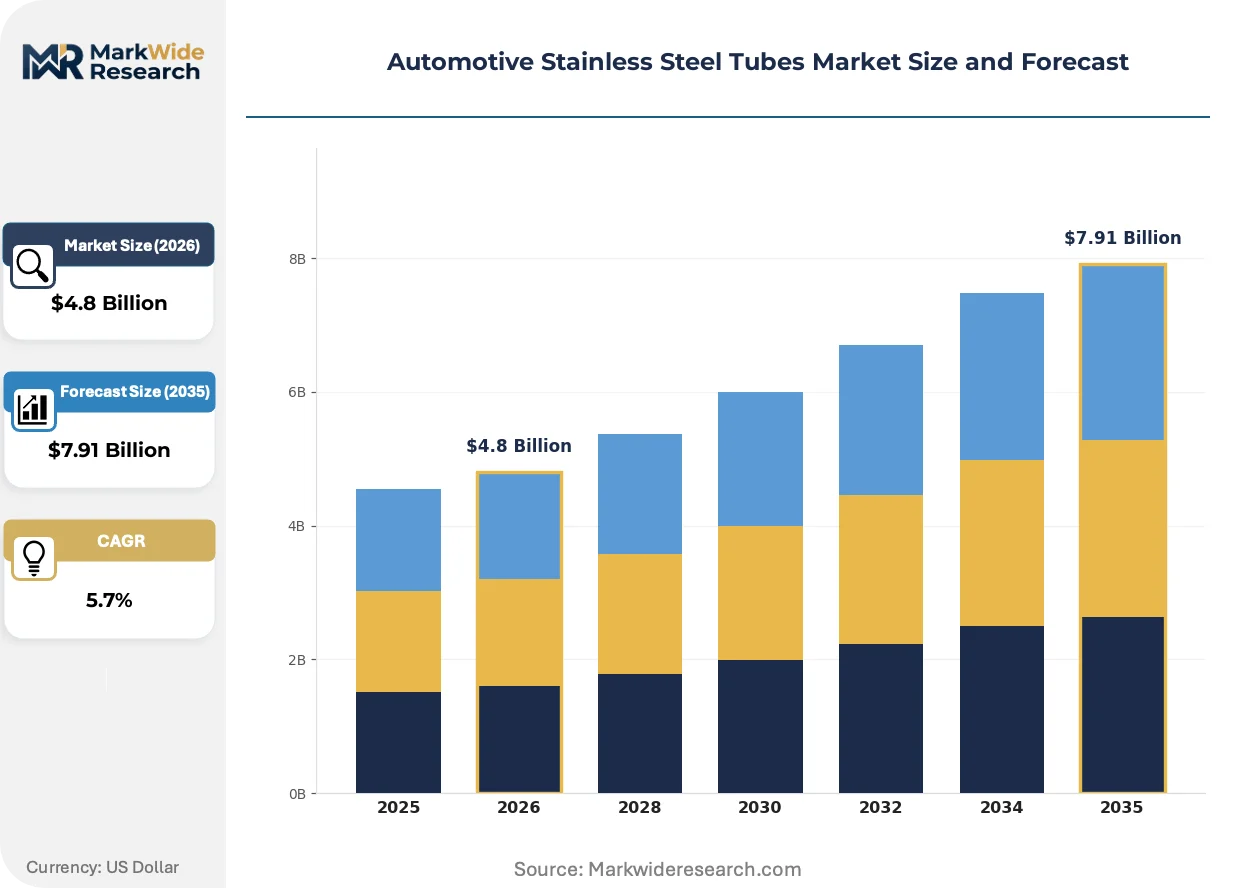
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Seamless, Welded, Round, Square End User: OEMs, Tier-1 Suppliers, Vehicle Assemblers, Aftermarket Providers Application: Exhaust Systems, Fuel Lines, Brake Lines, Structural Components Grade: 304, 316, 409, 430 |
| Companies Covered | Nippon Steel Corporation, ArcelorMittal, JFE Steel Corporation, Thyssenkrupp AG, Sandvik AB, Tubacex S.A., Centravis, Outokumpu, Fischer Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Stainless Steel Tubes Market Emerging Trajectories
Material specification protocols are fragmenting as powertrain electrification splits demand into thermal-management-optimized alloys for hybrids and corrosion-resistant grades for hydrogen infrastructure. Tube producers must now maintain parallel grade portfolios with diverging certification requirements.
Continuous laser welding with inline seam annealing is migrating from exhaust system commodity tubing into fuel line and brake line applications. Tier-1 brake system suppliers in Germany and Japan are adopting this process for wall-thickness consistency below 0.5mm. The technology is enabling cost parity with seamless alternatives in pressure-critical applications while preserving the productivity advantages of welded production.
REACH Annex XVII restrictions on hexavalent chromium conversion coatings are forcing conversion to trivalent passivation and organic coating systems for stainless tube surface finishing. Surface treatment houses in the EU are retooling electrolytic lines to comply with sunset dates for legacy processes. Exhaust component manufacturers serving Volkswagen Group and Stellantis platforms are qualifying alternative corrosion protection to maintain supply continuity.
Consolidated procurement desks at major exhaust system integrators are unbundling tube supply from module assembly contracts. Buyers at Tenneco, Faurecia, and Eberspächer are negotiating direct alloy surcharge pass-through mechanisms rather than fixed-price annual agreements. This behavioral shift is most pronounced in Germany and the US Midwest, where OEM cost-down pressures are transferring price volatility risk downstream to mill suppliers.
Automotive Stainless Steel Tubes Market Segmentation
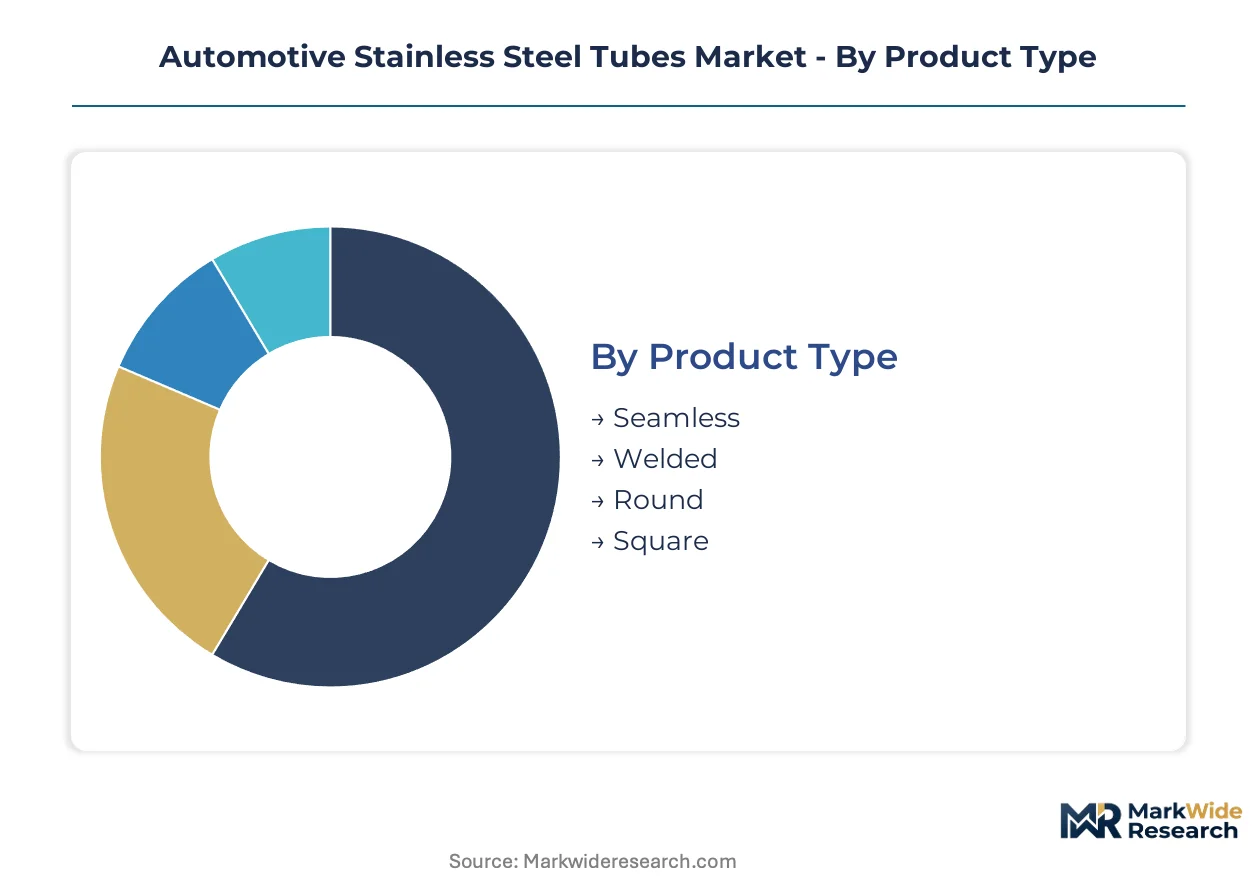
Segmentation in automotive stainless steel tubes reflects divergent technical requirements across powertrain architectures. Specification protocols split between thermal endurance for exhaust systems and precision tolerances for fluid handling, with grade selection determining alloy surcharge exposure and procurement strategy.
Product Type:
Mature welded tube formats dominate exhaust system volumes, while seamless alternatives retain premium positioning in pressure-critical applications where wall uniformity governs leak resistance.
- Seamless:Manufactured via rotary piercing and multi-pass pilger reduction, seamless tubes achieve wall thickness uniformity within ±0.05mm. Demand concentrates in Germany and Japan for high-pressure direct fuel injection lines where NHTSA integrity requirements eliminate welded alternatives.
- Welded:Produced through electric resistance welding with inline seam annealing, welded tubes balance cost efficiency with adequate performance for exhaust manifolds and muffler assemblies. Procurement volumes cluster with Tenneco and Faurecia module integrators serving European OEM platforms.
- Round:Standard cross-section for fluid transport and exhaust gas routing, round tubes constitute the baseline geometry across fuel, brake, and HVAC line applications.
- Square:Structural hollow sections specified for chassis reinforcement and battery tray framing in hybrid architectures where METI weight reduction mandates drive substitution from solid bar stock.
Welded tubes retain volume leadership; seamless holds the steepest expansion curve as fuel injection pressures climb.
End User:
Procurement authority is shifting downstream as Tier-1 suppliers consolidate specification control and negotiate direct alloy surcharge pass-through mechanisms.
- OEMs:Direct mill relationships persist for exhaust system architecture programs at Volkswagen Group and Stellantis, though contract structures increasingly unbundle tube supply from module assembly.
- Tier-1 Suppliers:Faurecia, Tenneco, and Eberspächer procurement desks now dominate grade selection and volume commitment, leveraging consolidated demand to compress distributor margins.
- Vehicle Assemblers:Contract manufacturers in emerging production jurisdictions qualify local tube mills for non-critical structural applications under PLI scheme incentives.
- Aftermarket Providers:Independent distributors serve replacement exhaust components and corrosion-related fuel line repairs, with demand tied to vehicle age profiles in the US Midwest and German aftermarket channels.
Tier-1 suppliers retain volume leadership; vehicle assemblers hold the steepest expansion curve as localization mandates proliferate.
Application:
Application mix tracks powertrain electrification trajectories, with exhaust system demand facing long-term displacement while brake and structural applications expand.
- Exhaust Systems:Manifolds, catalytic converter housings, and after-treatment assemblies specify Grade 409 and 441 for oxidation resistance above 650°C. Euro 7 thermal efficiency mandates are accelerating substitution of aluminized mild steel across European OEM platforms.
- Fuel Lines:High-pressure gasoline direct injection and flex-fuel compatibility require Grade 316 austenitic tubing with molybdenum enhancement for ethanol corrosion resistance. Specification intensity is climbing in US and Brazilian flex-fuel vehicle production.
- Brake Lines:Precision cold-drawn tubing with sub-0.5mm wall thickness serves hydraulic brake circuits, with continuous laser welding migrating from exhaust into this segment for cost parity with seamless alternatives.
- Structural Components:Hollow-section tubing for chassis rails, subframes, and battery enclosures substitutes for solid steel where METI and EPA weight reduction targets apply.
Exhaust systems retain volume leadership; structural components hold the steepest expansion curve as electrification reconfigures vehicle architecture.
Grade:
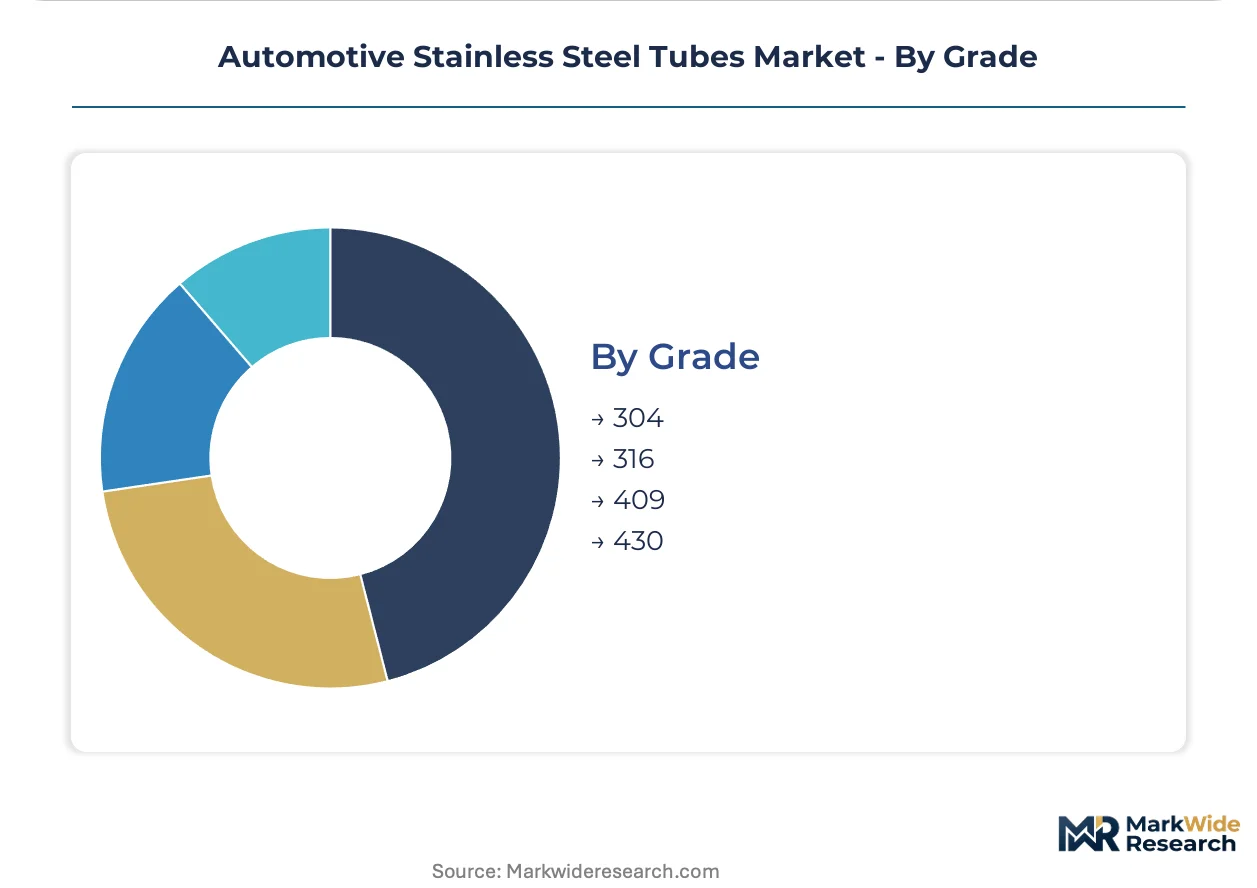
Grade portfolio requirements are fragmenting as hydrogen infrastructure and hybrid thermal loads impose divergent corrosion and oxidation specifications.
- 304:General-purpose austenitic grade with 18% chromium and 8% nickel content, specified for brake lines and moderate-temperature fluid handling where cost sensitivity limits alloy surcharge exposure.
- 316:Molybdenum-bearing austenitic grade delivering superior chloride and ethanol corrosion resistance. Demand is climbing for flex-fuel fuel lines and hydrogen fuel cell stack manifolds where sub-ppm sulfur content is mandatory.
- 409:Stabilized ferritic grade with 11% chromium, dominating exhaust system commodity volumes for oxidation resistance at elevated temperatures with minimal nickel content to hedge price volatility.
- 430:Lower-alloy ferritic grade for decorative trim and non-critical structural applications where corrosion exposure is limited and cost compression is prioritized.
Grade 409 retains volume leadership; Grade 316 holds the steepest expansion curve as hydrogen compatibility specifications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tube mills in Germany command alloy surcharge premiums that Chinese exporters cannot match, while Japanese producers leverage JIS certification barriers to defend domestic market share. This pricing-power asymmetry is reshaping procurement geography across exhaust system supply chains.
United States
Domestic OEM platforms at Ford and General Motors specify Grade 409 for exhaust manifolds under EPA tailpipe standards tightening through 2027. NHTSA fuel system integrity rules mandate seamless tubing for high-pressure direct injection lines. Detroit-area mill clusters in Michigan and Ohio concentrate cold-drawing capacity for brake line precision tolerances.
Germany
Volkswagen Group and BMW exhaust architecture programs absorb the majority of European Grade 441 volumes as Euro 7 thermal efficiency mandates accelerate. KBA type-approval requirements enforce sub-50ppm sulfur content for hydrogen fuel cell compatibility. Mill concentrations in North Rhine-Westphalia and Lower Saxony supply Faurecia and Eberspächer module integrators.
Japan
METI vehicle weight reduction targets drive hollow-section stainless substitution for solid bar stock in chassis applications at Toyota and Honda. JIS G 3446 standards govern automotive mechanical tubing specifications with stricter dimensional tolerances than ASTM equivalents. Nagoya-area steelworks anchor ferritic grade production for hybrid thermal management systems.
China
Zhejiang and Jiangsu province mill clusters produce over half of global welded tube output for export exhaust module assembly. GB/T 12770 standards govern welded stainless steel tubes for mechanical structures with evolving alignment to Euro 7 corrosion requirements. Shanghai-port logistics hubs consolidate outbound shipment to European Tier-1 suppliers.
India
PLI scheme incentives for advanced materials manufacturing attract greenfield stainless tube capacity to serve Maruti Suzuki and Tata Motors domestic supply chains. BIS IS 6913 certification governs automotive steel tubes with phased alignment to global OEM audit protocols. Gujarat and Maharashtra industrial corridors concentrate new mill investment for localization mandates.
Automotive Stainless Steel Tubes Market Vendor Landscape
Integrated steelmakers and specialized tube mills split the market between captive alloy feedstock control and precision cold-drawing capabilities. European producers leverage backward integration into ferrochrome and nickel sourcing to hedge London Metal Exchange volatility. Japanese and South Korean mills compete on JIS-certified dimensional consistency for fuel line applications. Dominant competitive moves include unbundling tube supply from module assembly contracts and negotiating direct alloy surcharge pass-through mechanisms.
Among integrated European steelmakers, ArcelorMittal and Thyssenkrupp AG exemplify the alloy-feedstock-control archetype, while JFE Steel Corporation anchors the specialized-ferritic-grade tier for exhaust thermal management. Nippon Steel Corporation occupies a position bridging seamless precision capabilities with integrated mill scale. These three structures represent the strategic positioning spectrum: upstream resource control, application-specific metallurgy, and dimensional precision at volume.
| Leading Market Players |
|---|
| Nippon Steel Corporation |
| ArcelorMittal |
| JFE Steel Corporation |
| Thyssenkrupp AG |
| Sandvik AB |
| Tubacex S.A. |
| Centravis |
| Outokumpu |
| Fischer Group |
| Others |
Supply Flow & Price Mechanics
Shanghai-port logistics corridors anchor cost dynamics for welded tube exports from Zhejiang and Jiangsu mill clusters, compressing margins for European Tier-1 suppliers while enabling alloy surcharge pass-through mechanisms that differentiate mill-direct pricing from distributor-mediated transactions.
Pricing Analysis
Configured-to-order seamless tubing for high-pressure fuel injection lines commands substantial premiums over standard-welded exhaust commodity grades. Three-tier pricing structure across premium seamless, standard welded, and economy ferritic grades reflects certification intensity and wall-thickness precision. Cost compression in welded exhaust segments intensifies as Chinese mill capacity floods export markets. Aftermarket distributors serving corrosion-related replacement demand exhibit highest price sensitivity; OEM platform engineering teams prioritize performance specifications over unit cost.
Supply Chain Analysis
Extended payment terms from European exhaust module integrators are forcing working capital strain on specialized cold-drawing mills. Supply concentrates in China, Germany, and Japan, with raw material feeds drawing from Indonesian nickel laterite and South African ferrochrome. Single-source vulnerability pervades welded tube procurement from Jiangsu province clusters. Distribution runs through Tier-1 module assembly contracts at Tenneco, Faurecia, and Eberspächer.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive stainless steel tubes face sustained substitution pressure from aluminum extrusions in battery thermal management circuits, compelling incumbents to defend specification control in hydrogen fuel cell and high-pressure fuel line applications where material integrity requirements exclude lightweight alternatives.
For Market Incumbents: Harden grade portfolio differentiation by securing captive ferrochrome supply through backward integration into European ferroalloy networks. Accelerate IATF 16949 certification timelines for hydrogen-compatible 316L production to preempt emerging specialty mills. Lock in direct mill-to-OEM digital procurement platforms before blockchain-verified alloy traceability becomes table stakes.
For New Entrants and Emerging Players: Hydrogen fuel cell stack manifold supply chains in Germany and Japan represent the most penetrable entry point for sub-ppm sulfur 316L grades absent established incumbent relationships. India's PLI scheme subsidized greenfield capacity for Maruti Suzuki and Tata Motors localization mandates offers second-mover advantage without legacy distributor encumbrance. Lead with seamless cold-drawing precision capabilities rather than commodity welded volume.
For Investors and Strategic Acquirers: European tool-and-die specialists with multi-pass pilger reduction expertise and retiring workforce succession plans present consolidation targets for seamless fuel line capacity scarcity. Long-term viability hinges on hydrogen infrastructure buildout trajectories and Euro 7 enforcement rigor. Watch for alloy surcharge volatility spikes as inflection signals for margin compression versus pricing power restoration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ferrochrome | ArcelorMittal's captive alloy feedstock hedges London Metal Exchange nickel surge exposure. |
| Hydrogen-Grade 316L Certification | Sub-ppm sulfur content qualification opens premium specification tiers for fuel cell stack manifolds. |
| Digital Procurement Platform Deployment | Blockchain-verified alloy certification enables bypass of traditional distributor markup structures. |
| Continuous Laser Welding Migration | Inline seam annealing technology achieves wall-thickness consistency below 0.5mm for brake line cost parity. |
| India PLI Scheme Capacity Buildout | Greenfield stainless tube investment serves Maruti Suzuki domestic supply chain localization mandates. |
Methodological Framework
Operator-level perspectives from Tier-1 supplier procurement directors, OEM platform engineers, cold-drawing mill operations managers, and aftermarket distribution channel heads anchored the qualitative base. Secondary validation drew from vehicle production databases, IHS Markit registration data, SEC filings from integrated steelmakers, and customs trade records for stainless steel tube flows. Bottom-up volume modeling triangulated against top-down alloy consumption estimates across the analysis window.
Scenario-bracketing framed projections across regulatory phase-in timelines, nickel price volatility bands, and powertrain electrification penetration curves. Segmentation dimensions spanned product type, end-user procurement authority, application thermal requirements, and grade corrosion specifications. CAGRs derived from regression against historical content-per-vehicle trends and OEM platform launch schedules. Forecast inputs incorporated Euro 7 enforcement assumptions and METI weight reduction mandate compliance trajectories.
Stress conditions across London Metal Exchange nickel surge events, Chinese export duty policy shifts, and hydrogen infrastructure deployment delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory adherence and alloy substitution elasticity. Macroeconomic contraction, accelerated aluminum substitution in EV thermal systems, or unilateral trade barrier imposition would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Automotive Injector Nozzle Market
Automotive Components
Automotive Headliners Market
Automotive Components
Automotive Seat Frame Market
Automotive Components
Automotive Spark Plugs and Glow Plugs Market
Automotive Components
Automotive Exhaust Headers Market
Automotive Components
Beryllium Copper for Automobile Market
Automotive Components
Africa and Middle East Automotive Pneumatic Actuators Market
Automotive Components
Automotive Fender Market
Automotive Components
Australia Automotive Pneumatic Actuators Market
Automotive Components
Automotive License Plate Light Market
Automotive Components
Automotive V-Belts Market
Automotive Components
Latin America Automotive Electric Actuators Market
Automotive Components
Asia-Pacific Automotive Upholstery Market
Automotive Components
Turkey Automotive Plastic Compounding Market
Automotive Components
India Automotive Glass Fiber Composites Market
Automotive Components
Automotive Rear End Module Market