
 Middle East and Africa Passenger Information System Market | 2026-2036
Middle East and Africa Passenger Information System Market Size, Share, and Industry Trends Forecast 2026-2036
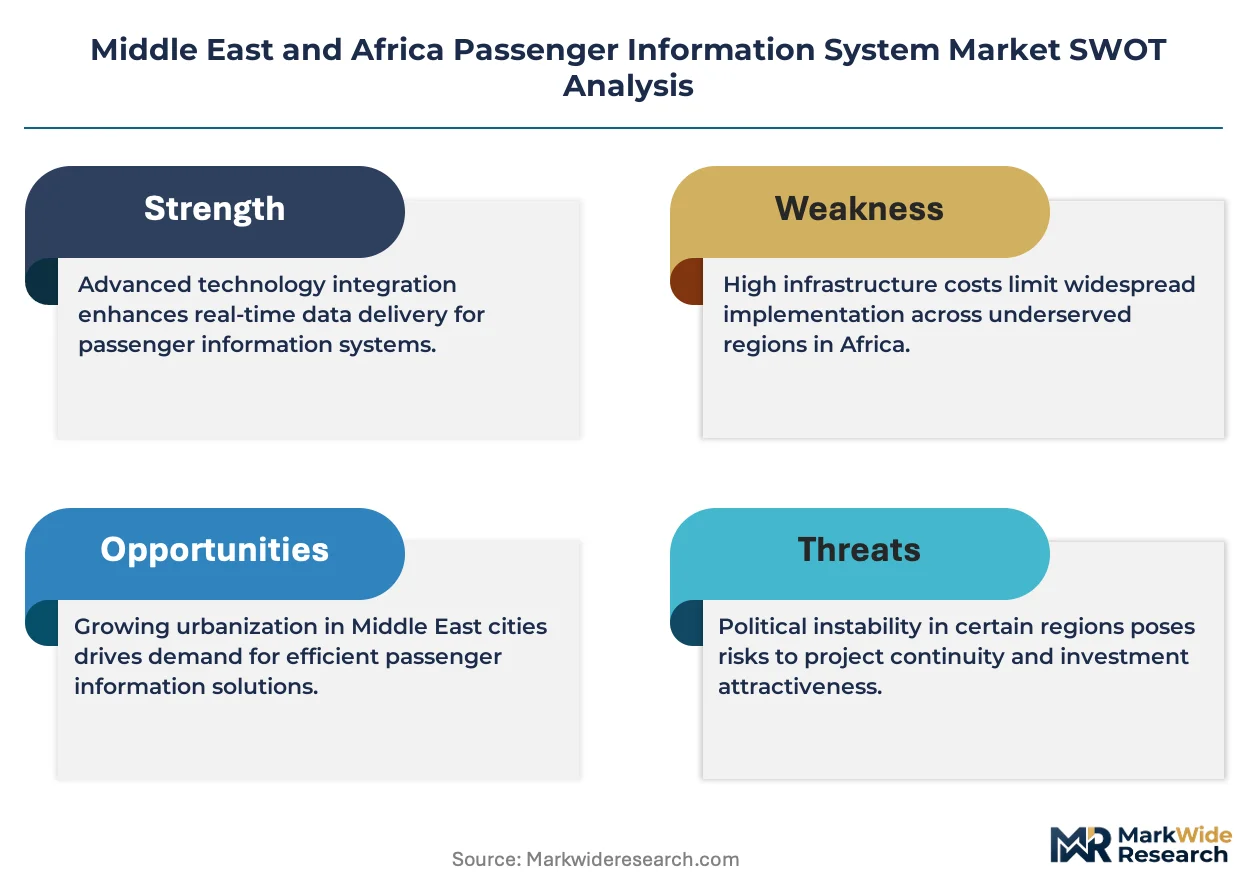
Middle East and Africa Passenger Information System Market Foresight
CE marking requirements under the EU Medical Device Regulation framework is consolidating compliance burdens for European-origin suppliers serving North African transit projects. Siemens Mobility leverages its Cairo Metro automation legacy to sustain project pipelines across Egypt. Thales Group anchors its regional footprint through Dubai's driverless metro signaling and passenger information integration. Alstom competes on African rail corridors with display and communication system bundling.
A passenger information system comprises integrated hardware and software platforms that deliver real-time travel data through visual displays, audio announcements, and mobile connectivity interfaces, typically operating on IP-based networks with sub-second latency requirements for schedule updates and emergency alerts. These systems serve transit operators by reducing passenger uncertainty, improving crowd distribution, and enabling dynamic service adjustments during disruptions. Display Systems dominate procurement volumes across Middle Eastern airports and metro networks, while Communication Systems capture expanding share as operators integrate Wi-Fi and cellular-based passenger alerts. LED technology leads technology segment adoption due to luminosity performance in high-ambient-light environments, whereas Digital Signage represents the fastest-expanding category as advertising revenue models subsidize infrastructure deployment.
Saudi Arabia's Communications and Information Technology Commission enforces cybersecurity standards for connected transit infrastructure, while South Africa's National Regulator for Compulsory Specifications mandates electromagnetic compatibility certification for railway electronics. The UAE's Telecommunications and Digital Government Regulatory Authority shapes 5G-enabled passenger connectivity requirements for Dubai's expanding metro and tram networks. Stakeholders must monitor evolving data localization mandates and interoperability standards that will determine system architecture choices across the region's fragmented procurement landscape.
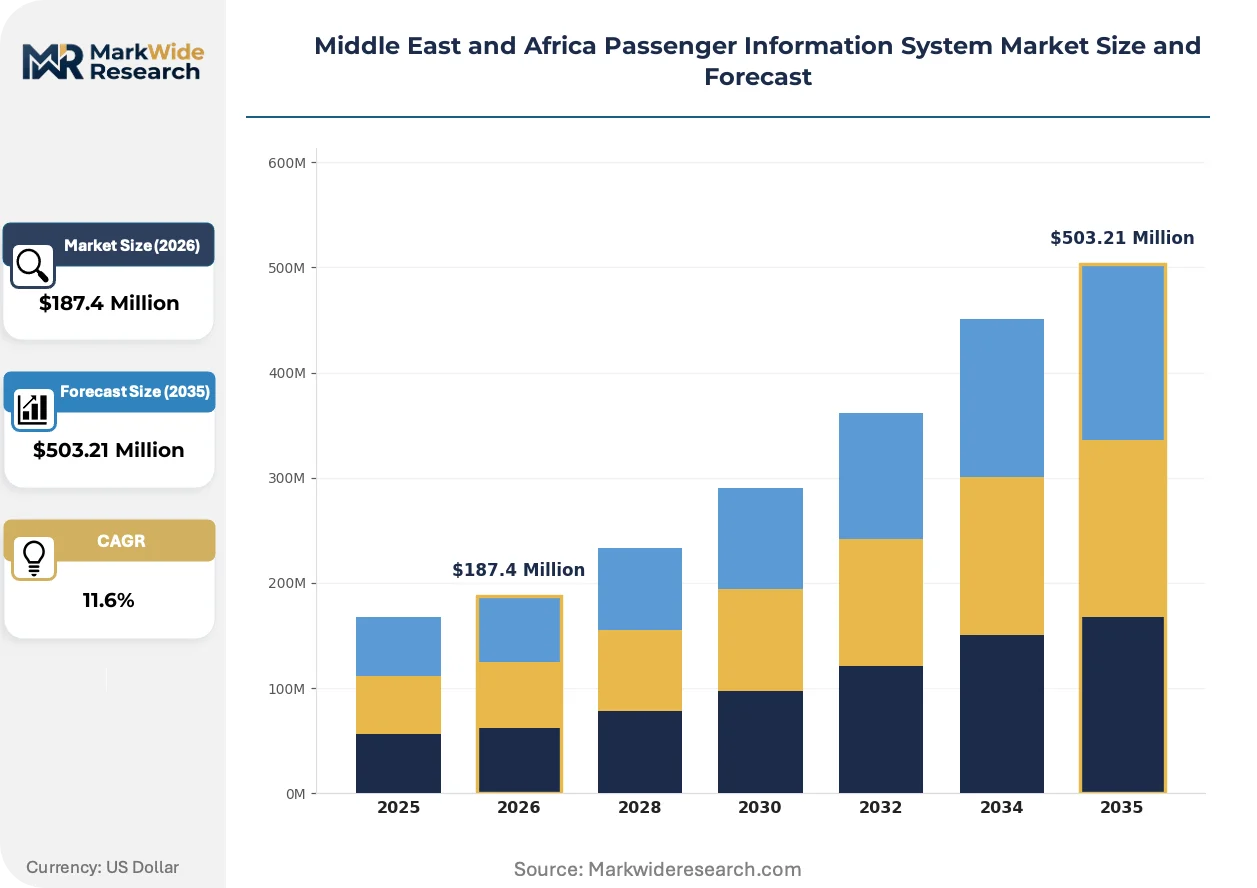
Market Dynamics
Saudi Arabia's Vision 2030 transit investments and the UAE's smart city mandates are compressing procurement cycles across Gulf Cooperation Council rail and airport projects. These state-led infrastructure programs are overriding traditional budget constraints and accelerating digital platform deployment timelines.
Growth Catalysts
- Vision 2030 Transit Mandates:Saudi Arabia's sovereign investment framework is underwriting metro expansion in Riyadh and Jeddah, creating guaranteed demand for integrated passenger communication networks.
- 5G-Enabled Connectivity:The UAE's Telecommunications and Digital Government Regulatory Authority is mandating next-generation passenger Wi-Fi standards across Dubai's expanding metro and tram infrastructure.
- Airport Modernization:Cairo International Airport and Johannesburg OR Tambo are prioritizing real-time display system overhauls to manage rising passenger volumes.
Market Restraints
- Electronics Import Dependence:LED display modules and IP-based network components rely heavily on East Asian manufacturing, exposing projects to shipping cost volatility and currency fluctuation.
- Cybersecurity Compliance Burden:Saudi Arabia's Communications and Information Technology Commission imposes stringent connected infrastructure standards that extend system certification timelines.
- Technical Skills Scarcity:Sub-Saharan rail operators face acute shortages of technicians trained in IP network maintenance and digital signage calibration.
Strategic Opportunities
- Advertising Revenue Subsidies:Digital signage platforms with programmatic advertising integration are attracting private capital to underwrite hardware deployment costs.
- East African Rail Corridors:Kenya's Standard Gauge Railway and Ethiopia-Djibouti line expansions represent underpenetrated demand for basic passenger information infrastructure.
- Mobile-First Alert Systems:Convergence of cellular-based passenger alerts with existing display networks is opening retrofit contracts for mid-tier African operators.
Industry Challenges
- Legacy System Integration:Cairo Metro's aging analog announcement infrastructure requires complex middleware development to interface with modern IP-based platforms.
- Certification Timeline Compression:South Africa's National Regulator for Compulsory Specifications mandates electromagnetic compatibility testing that conflicts with accelerated construction schedules.
- Localization Mandate Navigation:Evolving data residency requirements across Gulf states force suppliers to re-architect cloud-based content management systems mid-deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Passenger Information System Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Display Systems, Communication Systems, Control Systems, Announcement Systems Technology: LCD, LED, OLED, Digital Signage Application: Airports, Train Stations, Bus Terminals, Subways End User: Transit Authorities, Airport Operators, Transport Operators, Government Agencies |
| Companies Covered | Siemens Mobility, Thales Group, Cubic Corporation, Alstom, Advantech Co., Ltd., Mitsubishi Electric Corporation, Teleste Corporation, ST Engineering, Medha Servo Drives Private Limited, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Passenger Information System Market Shifts & Advancements
LED-based display technology is consolidating its position as the default specification for high-ambient-light transit environments. Three parallel developments are compressing upgrade cycles and reshaping supplier relationships across the region.
Edge-computing display controllers with localized content caching are consolidating system architecture by eliminating dependency on continuous cloud connectivity. Dubai's driverless metro and Riyadh's new lines are specifying these controllers to maintain sub-second latency for emergency alerts during network outages. This consolidation is compressing the addressable market for traditional centralized server-based solutions.
South Africa's National Regulator for Compulsory Specifications is tightening electromagnetic compatibility certification for railway electronics, forcing European and Asian suppliers to establish local testing partnerships. The industrial consequence is extended pre-qualification timelines for new market entrants. Airport and heavy rail projects in Johannesburg and Cape Town are responding by bundling certification costs into multi-year framework agreements with incumbent vendors.
Operator purchasing patterns are rotating toward performance-based service contracts that unbundle hardware procurement from maintenance obligations. Gulf Cooperation Council transit authorities are leading this shift, replacing capital expenditure models with operational expenditure frameworks tied to system uptime metrics. This reconfiguration is most visible in Dubai's metro and tram network expansions, where maintenance risk has transferred to system integrators.
Middle East and Africa Passenger Information System Market Segmentation
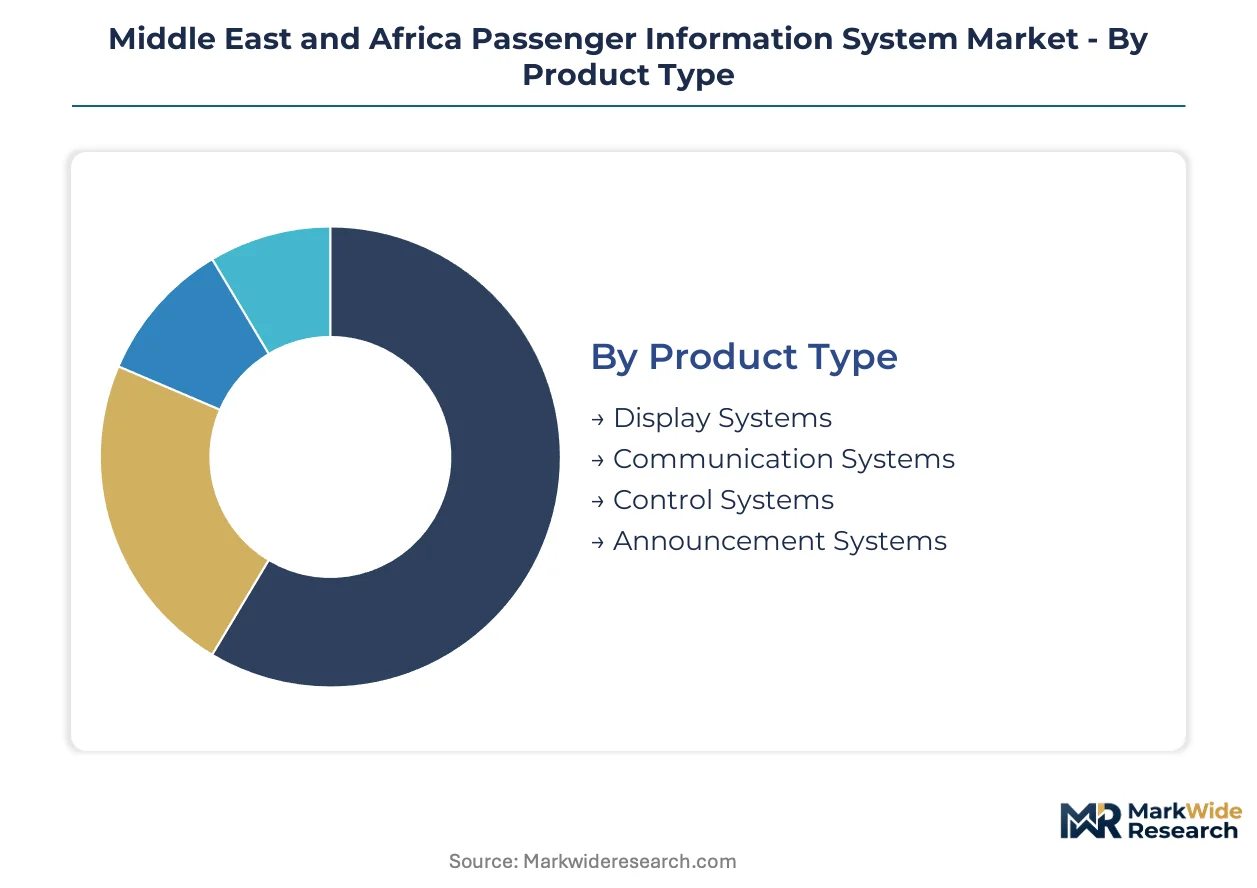
Passenger information system procurement across the Middle East and Africa fragments across four distinct category hierarchies. Certification requirements, ambient environmental conditions, and operator procurement maturity vary sharply by segment, shaping supplier positioning and margin structures.
Product Type:
South Africa's National Regulator for Compulsory Specifications mandates electromagnetic compatibility testing for display and communication hardware, while Saudi Arabia's Communications and Information Technology Commission imposes cybersecurity certification on control systems. These divergent approval pathways segment supplier capabilities and project timelines.
- Display Systems:LED and LCD panels delivering real-time schedule data, wayfinding graphics, and emergency alerts across high-ambient-light transit environments. Cairo International Airport and Dubai Metro expansion programs are concentrating procurement volumes here, driven by sovereign infrastructure mandates and advertising revenue integration.
- Communication Systems:IP-based audio networks, cellular alert platforms, and Wi-Fi passenger connectivity infrastructure. Demand clusters in the UAE's 5G-enabled transit corridors, where the Telecommunications and Digital Government Regulatory Authority mandates next-generation connectivity standards.
- Control Systems:Centralized content management and edge-computing controllers with localized caching capabilities. Riyadh Metro and Johannesburg Gautrain specify these for sub-second emergency alert latency.
- Announcement Systems:Automated audio broadcast infrastructure with multilingual support. Kenya's Standard Gauge Railway and Ethiopia-Djibouti line deployments represent emerging demand centers.
Leading the category by volume: Display Systems. Growing fastest: Communication Systems.
Technology:
Technology selection in this market tracks directly against installation environment luminosity, operational temperature ranges, and total cost of ownership over 10-year depreciation cycles. Premium specifications concentrate in Gulf Cooperation Council airport and metro greenfield projects.
- LED:High-brightness diode arrays dominating outdoor platform and terminal concourse deployments across Saudi Arabia and the UAE. Riyadh Metro's driverless lines specify LED for direct sunlight readability.
- LCD:Liquid crystal displays with localized backlighting, preferred for indoor climate-controlled environments. Cairo Metro modernization and Johannesburg OR Tambo retrofits favor LCD for cost-efficient refresh cycles.
- OLED:Organic light-emitting diode panels offering superior contrast ratios and thinner form factors. Premium lounge and first-class zone installations at Dubai International Airport represent primary demand.
- Digital Signage:Networked programmable displays enabling dynamic advertising content insertion. This segment is expanding most quickly as programmatic revenue models subsidize hardware deployment across Gulf transit authorities.
LED commands the largest installed base. Digital Signage climbs the fastest as private capital participation rises.
Application:
Application-specific procurement patterns reflect divergent passenger throughput densities, dwell time economics, and disruption frequency. Airport operators prioritize multilingual flexibility; rail operators emphasize real-time schedule accuracy.
- Airports:Integrated flight information, baggage claim, and gate management display networks. Cairo International Airport and Johannesburg OR Tambo are prioritizing real-time system overhauls to manage rising passenger volumes.
- Train Stations:Platform-edge displays and concourse wayfinding for intercity and commuter rail. Kenya's Standard Gauge Railway stations represent underpenetrated demand.
- Bus Terminals:Simpler departure board configurations with limited connectivity requirements. Sub-Saharan African operators favor these for lower total cost of ownership.
- Subways:High-density passenger information with emergency override capabilities. Dubai Metro and Riyadh Metro expansions are driving specification advancement.
Airports generate the highest revenue per installation. Subways show the steepest expansion trajectory from Vision 2030 and smart city mandates.
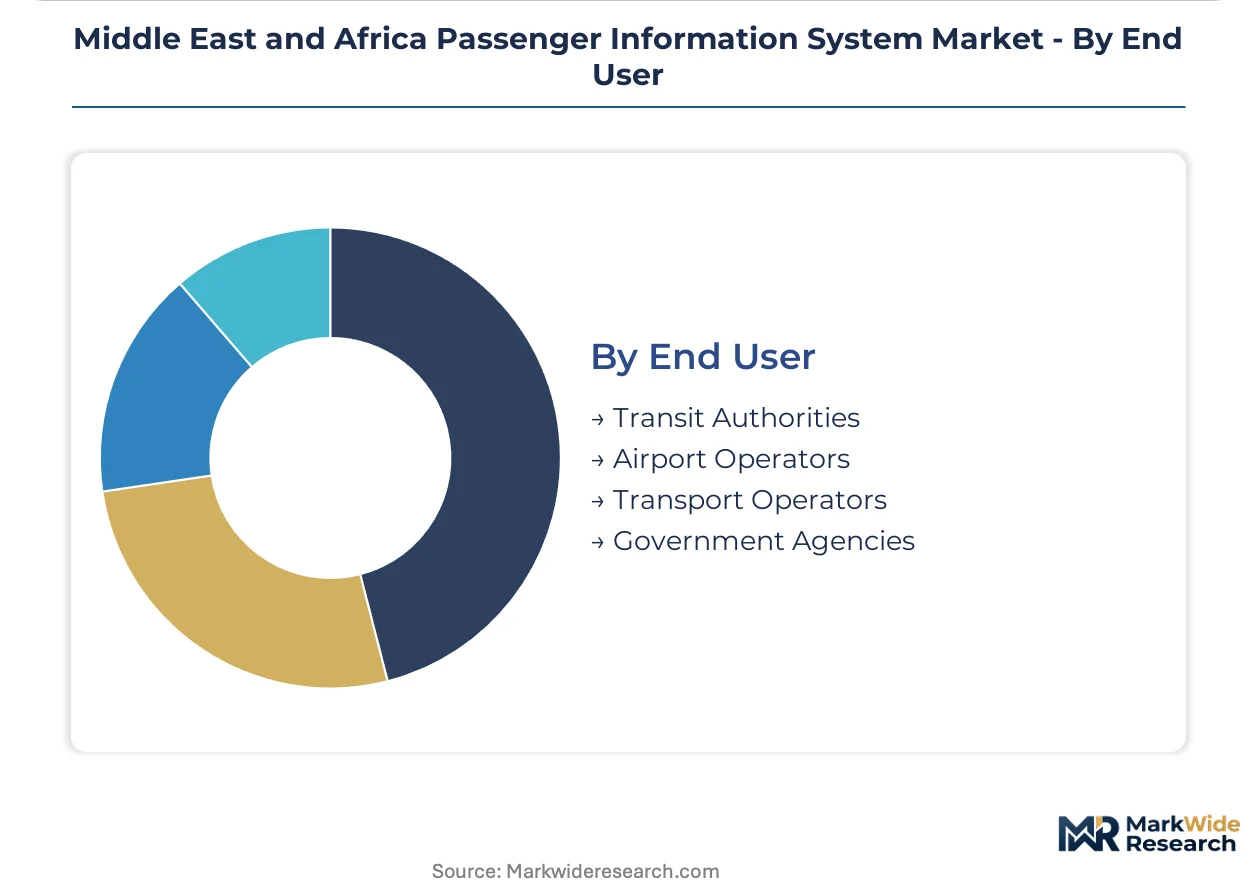
End User:
End-user procurement sophistication spans from centralized federal ministries with multi-year framework agreements to municipal operators with annual capital budgets. Contract structure preferences—capital expenditure versus performance-based service agreements—segment sharply here.
- Transit Authorities:Metropolitan and regional rail operators with integrated multi-modal mandates. Dubai's Roads and Transport Authority exemplifies advanced procurement with operational expenditure frameworks tied to uptime metrics.
- Airport Operators:State-owned or concession-managed aviation infrastructure companies. Cairo Airport Authority and Airports Company South Africa prioritize display system modernization for passenger experience differentiation.
- Transport Operators:Private concessionaires and state rail companies operating specific corridors. Saudi Arabia Railways and Etihad Rail are expanding real-time communication networks.
- Government Agencies:Federal and municipal ministries directing sovereign infrastructure investment. Saudi Arabia's Ministry of Transport and Logistics and the UAE's Federal Transport Authority shape long-term demand through master planning.
Transit Authorities dominate current procurement volumes. Government Agencies control the fastest-growing pipeline through sovereign wealth-backed rail expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
King Abdullah Economic City's logistics corridor is concentrating transit technology procurement as Saudi Arabia's sovereign development zones accelerate infrastructure buildout. This special-economic-zone model is replicating across Gulf states, compressing vendor qualification timelines and bundling display system contracts with adjacent rail electrification packages.
Saudi Arabia
Riyadh Metro's six-line automated network and Jeddah's airport rail link are generating concentrated demand for LED platform displays and edge-computing controllers. The Communications and Information Technology Commission enforces cybersecurity certification for connected transit infrastructure, extending system validation periods. NEOM's linear city project in the northwest is specifying passenger information integration with autonomous mobility pods.
United Arab Emirates
Dubai's Roads and Transport Authority is expanding driverless metro lines and tram networks with mandated 5G passenger connectivity. The Telecommunications and Digital Government Regulatory Authority shapes Wi-Fi performance standards for transit environments. Abu Dhabi's mid-region rail corridor is procuring integrated display and announcement systems for intercity service launch.
Egypt
Cairo Metro's Line 3 extension and Heliopolis light rail are modernizing analog announcement infrastructure with IP-based platforms. The National Telecom Regulatory Authority oversees electromagnetic compatibility for railway electronics imports. Cairo International Airport's Terminal 2 renovation is prioritizing multilingual digital signage for passenger experience differentiation.
South Africa
Gautrain's network expansion and Johannesburg OR Tambo's terminal upgrades are driving display system procurement. The National Regulator for Compulsory Specifications mandates EMC certification that conflicts with accelerated construction schedules. Cape Town's MyCiTi bus rapid transit corridors represent emerging demand for simpler departure board configurations.
Kenya
The Standard Gauge Railway's Nairobi-Mombasa corridor and planned branch lines to Naivasha are creating foundational demand for basic passenger information infrastructure. The Communications Authority of Kenya regulates spectrum allocation for railway communication systems. Mombasa Port's rail connectivity upgrades are bundling announcement systems with freight automation packages.
Middle East and Africa Passenger Information System Market Competitive Landscape
European producers anchor one tier; East Asian specialists hold contract manufacturing relationships with regional integrators. The vendor base clusters around three strategic archetypes: diversified industrial conglomerates with rail automation legacies, transit-focused system integrators with regional certification expertise, and display hardware specialists pursuing advertising revenue partnerships. Competitive positioning hinges on pre-qualification speed for sovereign framework agreements and backward integration into LED module sourcing.
Within the diversified conglomerate tier, Siemens Mobility and Thales Group exemplify vendors leveraging Cairo and Dubai project legacies to sustain pipeline visibility. Alstom occupies a position bundling display systems with rolling stock procurement across African rail corridors. These three European-originated entities represent the incumbent tier defending against Asian competitors on total cost of ownership metrics.
| Leading Market Players |
|---|
| Siemens Mobility |
| Thales Group |
| Cubic Corporation |
| Alstom |
| Advantech Co., Ltd. |
| Mitsubishi Electric Corporation |
| Teleste Corporation |
| ST Engineering |
| Medha Servo Drives Private Limited |
| Others |
Supply & Pricing Matrix
Backward integration into LED module sourcing anchors supply positions for display system vendors bidding on Gulf rail projects, while simultaneously constraining pricing power for integrators dependent on East Asian component markets. This captive production dynamic compresses margins for mid-tier suppliers serving African operators with limited procurement scale.
Pricing Analysis
Lead-time premiums compress pricing bands across Egyptian and Saudi procurement cycles, with spot inventory from Chinese LED manufacturers commanding discounts against certified European-origin hardware. Three-tier pricing structure across premium, standard, and economy levels separates Siemens and Thales framework agreements from regional integrators and basic display assemblers. Cost compression in economy-tier LED modules intensifies because shipping rate volatility and currency fluctuation erode landed cost advantages. Sub-Saharan municipal operators exhibit acute price sensitivity, whereas UAE sovereign wealth-backed transit authorities prioritize certification speed over unit economics.
Supply Chain Analysis
Dual-sourcing requirements from Dubai's Roads and Transport Authority and Saudi Arabia Railways mandate multi-supplier qualification for edge-computing controllers and IP network components. Manufacturing concentrates in China, South Korea, and Taiwan for LED diode arrays, display driver ICs, and embedded computing modules. Raw material dependencies span gallium nitride substrates, copper-clad laminates, and rare-earth phosphors. Single-source vulnerability persists for automotive-grade microcontroller units qualified under Saudi Communications and Information Technology Commission cybersecurity standards. Distribution runs through regional system integrators with local certification expertise, bypassing direct vendor relationships for mid-sized African operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Middle East and Africa passenger information system market functions as a vertical-integration race where control over LED module supply and edge-computing firmware development determines bid competitiveness on sovereign rail frameworks.
For Market Incumbents: Lock in long-term framework agreements with Cairo Metro and Dubai's Roads and Transport Authority before Asian competitors achieve EMC certification under South Africa's National Regulator for Compulsory Specifications. Prioritize backward integration into LED assembly to defend margin position against Korean display specialists. Certification investment in Saudi cybersecurity standards represents the critical defensive lever against emerging Chinese system integrators. For New Entrants and Emerging Players: The premium-economy price-point gap in East African rail corridors creates entry space for mobile-first alert platforms bypassing capital-intensive display infrastructure. Target Kenya's Standard Gauge Railway expansion and Ethiopia-Djibouti branch lines with cellular-based passenger information retrofits. A channel partnership with freight-rail operators bundling announcement systems with automation packages offers the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to industrial conglomerates seeking transit automation capabilities, with IPO viability constrained by project concentration risk. Acquisition targets display regional certification expertise coupled with advertising revenue platform development. Watch for inflection when Saudi Vision 2030 metro procurement shifts from hardware-centric to performance-based service contracting.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Investment | Early EMC and cybersecurity qualification under South Africa's NRCS and Saudi CITC compresses bid timelines for framework agreements. |
| Edge-Computing Controller Development | Localized caching capabilities meeting Dubai Metro's sub-second emergency alert latency specifications displace centralized server architectures. |
| Advertising Revenue Platform Integration | Programmatic digital signage insertion attracts private capital to underwrite hardware deployment across Gulf transit authorities. |
| Regional Testing Partnership Establishment | Local EMC certification facilities in Johannesburg and Riyadh accelerate pre-qualification for European and Asian suppliers. |
| Mobile-First Alert System Convergence | Cellular-based passenger notification retrofit contracts open mid-tier African operators previously inaccessible to full display system vendors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across transit authority procurement directors, rail operator engineering heads, system integrator project managers, and LED display manufacturer sales leads. Specific secondary sources included UN Comtrade statistics for display module imports, Saudi Communications and Information Technology Commission certification databases, South African National Regulator for Compulsory Specifications approval registries, and Dubai Roads and Transport Authority tender announcements. Bottom-up project pipeline aggregation and top-down infrastructure spending analysis were triangulated to validate market sizing.
Data-stream reconciliation across procurement volume tracking, certification timeline analysis, and technology adoption curve modeling informed the analytical framework. Segmentation dimensions spanned product type, display technology, application environment, and end-user procurement maturity across the projection horizon. CAGRs were derived from infrastructure investment trajectories, sovereign wealth deployment schedules, and technology refresh cycle compression. Industry-specific forecast inputs incorporated Saudi Vision 2030 project acceleration rates and 5G regulatory mandate implementation timelines from the UAE Telecommunications and Digital Government Regulatory Authority.
Inputs from transit authority tender databases and certification agency filings were available through the study window; gaps in proprietary project cost breakdowns and supplier margin structures introduce uncertainty bands around hardware-versus-service revenue splits. Forecasts reflect assumptions regarding sovereign infrastructure commitment continuity and East Asian component supply stability. A model refresh is warranted upon material change in Saudi Arabia's Communications and Information Technology Commission cybersecurity enforcement intensity or UAE 5G transit connectivity mandate expansion.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Transportation Solutions
Traffic Management System Market
Smart Transportation Solutions
Fleet Health Monitoring and Diagnostic Analytics Systems Market
Smart Transportation Solutions
Global Smart Parking Solutions Market
Smart Transportation Solutions
Ride-Hailing Market
Smart Transportation Solutions
France Ridesharing Market
Smart Transportation Solutions
Transportation for Smart Cities Market
Smart Transportation Solutions
Electric Kick Scooters Market
Smart Transportation Solutions
Physical Internet (PI) Market
Smart Transportation Solutions
Global Intelligent Road System Market
Smart Transportation Solutions
Global V2X Market
Smart Transportation Solutions
Smart Chassis Market
Smart Transportation Solutions
Automatic Identification Systems (AIS) Market
Smart Transportation Solutions
Intelligent Traffic Management Market
Smart Transportation Solutions
Real-Time Parking System Market
Smart Transportation Solutions
Alternate Transportation Market
Smart Transportation Solutions
Nordic Bike Sharing Market