
 Automotive Center Console Market | 2026-2036
Automotive Center Console Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Center Console Market Analysis
A capital-intensity divergence between full-system integrators and component specialists is reorganizing supplier hierarchies in the automotive center console value chain. Continental AG leverages its electronics and interior systems portfolio to sustain integrated cockpit contracts with major OEM platforms. Yanfeng Automotive Trim Systems Co., Ltd. anchors high-volume production capacity across Asia-Pacific assembly corridors. Faurecia S.A. differentiates through design-to-cost capabilities that compete for modular architecture programs with European and North American automakers.
The automotive center console constitutes the central control and storage interface mounted between vehicle front seats, typically integrating structural substrates of polypropylene or acrylonitrile butadiene styrene with surface finishes in leather, aluminum, or wood veneer for tactile and aesthetic performance. Its primary industrial purpose is to house transmission controls, infotainment interfaces, climate systems, and storage compartments while meeting head impact and flammability standards. Integrated consoles command premium positioning as OEMs consolidate HVAC, wireless charging, and display controls into unified modules. Modular consoles represent the fastest-expanding category as platform-sharing strategies across vehicle segments reduce tooling duplication. Plastic materials dominate volume production for cost-sensitive segments, while aluminum and leather finishes concentrate margin pools in luxury vehicle lines.
The US NHTSA enforces Federal Motor Vehicle Safety Standard 201 for interior impact protection, directly influencing console geometry and padding specifications. Europe's REACH regulation and ECHA substance restrictions govern chemical content in plastics, coatings, and adhesives used in console manufacturing. China's MIIT and GB standards mandate electromagnetic compatibility for embedded wireless charging and infotainment modules. Stakeholders must monitor evolving material compliance thresholds and platform electrification timelines to align console development cycles with OEM product roadmaps.
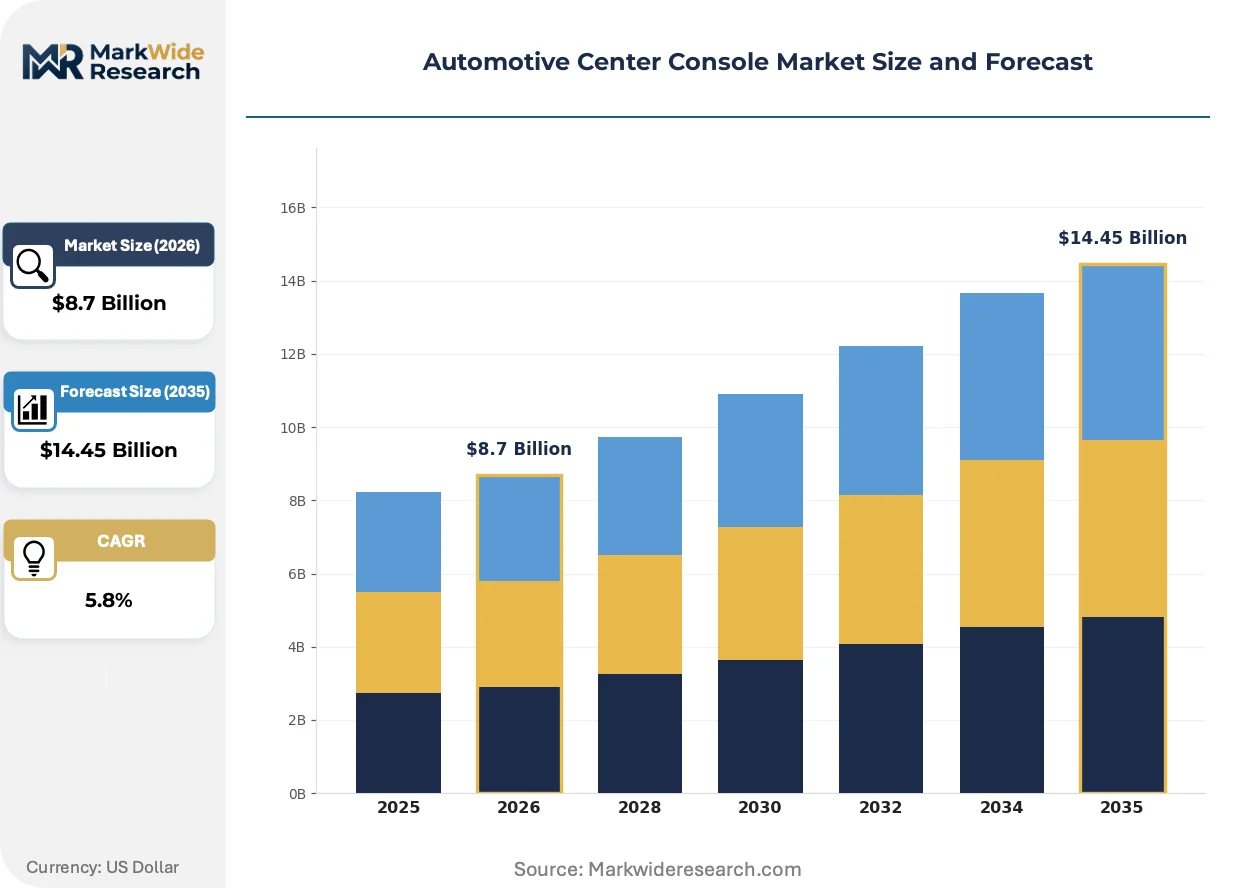
Market Dynamics
Platform electrification timelines and modular architecture mandates from luxury and electric vehicle OEMs are compressing console development cycles while forcing suppliers to consolidate HVAC, wireless charging, and infotainment controls into unified modules.
Growth Catalysts
- REACH chemical compliance:Europe's substance restrictions are accelerating material substitution toward bio-based polymers and low-VOC coatings that qualify suppliers for premium OEM contracts.
- Wireless charging integration:Consumer electronics convergence is pulling embedded inductive charging modules into center console specifications across mid-luxury vehicle segments.
- China's dual carbon goals:Domestic OEM procurement policies now prioritize lightweight recycled-content consoles, creating captive demand for compliant tier-one suppliers.
Market Restraints
- ABS and polypropylene price volatility:Petrochemical feedstock fluctuations compress margins for high-volume plastic console producers serving economy vehicle lines.
- Tooling cost concentration:Large-scale injection mold fabrication requires capital commitments that exclude mid-tier suppliers from integrated cockpit programs.
- Head impact geometry constraints:NHTSA Federal Motor Vehicle Safety Standard 201 limits design freedom for slim-profile console architectures in compact vehicle segments.
Strategic Opportunities
- India passenger vehicle expansion:Domestic OEM platform localization creates entry points for modular console suppliers with design-to-cost capabilities.
- Vehicle-to-everything interface convergence:Center consoles are becoming the physical anchor for V2X control modules, opening new specification categories.
- EU Green Deal procurement incentives:OEM sustainability scorecards now weight circular material content, advantaging suppliers with closed-loop recycling partnerships.
Industry Challenges
- Mechatronics integration complexity:Converging thermal, electronic, and mechanical systems in unified modules demands cross-functional engineering teams that remain scarce.
- Homologation timeline compression:Accelerated OEM product roadmaps force simultaneous compliance with evolving GB standards, REACH annex updates, and NHTSA interpretations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Center Console Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Consoles, Modular Consoles, Custom Consoles, Integrated Consoles Material: Plastic, Leather, Aluminum, Wood Feature: Wireless Charging, Storage Compartments, Control Panels, Infotainment Systems End User: OEMs, Aftermarket Providers, Custom Builders, Fleet Operators |
| Companies Covered | Continental AG, Faurecia S.A., Yanfeng Automotive Trim Systems Co., Ltd., Lear Corporation, AGM Automotive, LLC, Novares Group S.A., Novem Car Interior Design GmbH, DRÄXLMAIER Group, Magna International Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Center Console Market Emerging Trajectories
Active grille shutters and thermal management integration are pulling climate control hardware deeper into console architectures, while surface material specifications pivot toward haptic feedback compatibility and antimicrobial finishes.
Magnetorheological fluid dampers are fragmenting traditional mechanical hinge and latch mechanisms in adjustable console compartments. Tier-one suppliers serving German luxury OEMs have adopted these systems for premium storage modules since 2022. The technology is fragmenting established supplier relationships as electronics specialists capture mechanical component value pools previously held by injection molders.
China's GB standards for electromagnetic compatibility are tightening test protocols for embedded wireless charging coils and NFC payment modules in center console assemblies. Domestic MIIT enforcement has accelerated shielding material adoption among Asia-Pacific component suppliers. European exporters face retesting costs that compress their competitiveness in Chinese OEM supply chains.
Fleet procurement departments now specify modular console architectures that enable post-purchase feature activation through software unlocks. Rental and corporate fleet channels are displacing traditional retail-driven specification processes in volume vehicle segments. This pattern concentrates most visibly in United States commercial fleet contracts where total cost of ownership calculations now include upgrade pathway flexibility.
Automotive Center Console Market Segmentation
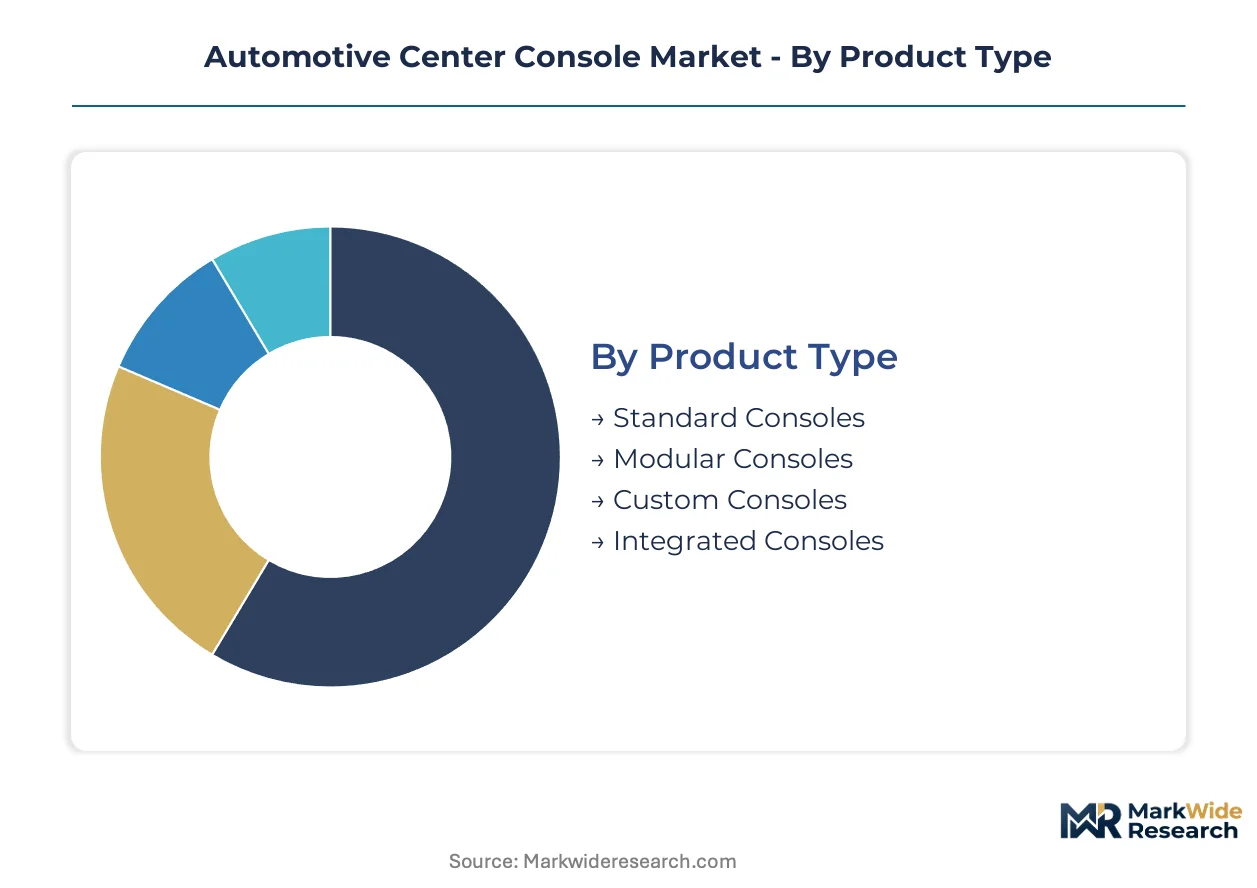
Console segmentation reveals how regulatory pressure and electrification timelines fragment supplier capabilities across material grades and integration depths. OEM procurement teams now weight electromagnetic compatibility and chemical compliance as heavily as cost-per-unit in sourcing decisions.
Product Type:
REACH substance restrictions and NHTSA Federal Motor Vehicle Safety Standard 201 create divergent certification burdens across architecture categories.
- Modular Consoles:Standardized sub-assemblies enable platform-sharing across vehicle segments while reducing tooling duplication. European luxury OEMs and Chinese electric vehicle manufacturers are expanding purchase orders for these architectures to compress development cycles. Established volume favors Modular Consoles; emerging adoption favors Integrated Consoles.
- Integrated Consoles:Unified modules consolidate HVAC, wireless charging, and infotainment controls into single structural units. Premium German and American OEMs specify these for flagship electric vehicle platforms where cabin space optimization drives design priorities.
- Standard Consoles:Fixed-configuration units serve economy vehicle lines with minimal electronic integration.
- Custom Consoles:Bespoke designs for limited-production luxury and performance vehicles carry extended development timelines.
Modular architectures capture the steepest expansion trajectory as platform electrification accelerates.
Material:
Cost tier stratification separates injection-molded commodity supply from finished surface treatments.
- Plastic:Polypropylene and acrylonitrile butadiene styrene substrates dominate high-volume production for cost-sensitive segments. China's dual carbon goals and domestic OEM procurement policies now prioritize lightweight recycled-content formulations, creating captive demand for compliant tier-one suppliers.
- Leather:Full-grain and synthetic hides concentrate in luxury vehicle lines where tactile performance justifies material premiums. European REACH chemical compliance requirements for tanning agents and adhesives have accelerated supplier consolidation toward vertically integrated tanneries.
- Aluminum:Brushed and anodized finishes serve premium thermal management and aesthetic specifications.
- Wood:Veneer applications remain restricted to flagship sedan and SUV programs with extended model cycles.
Plastic retains volume leadership; leather and aluminum together command disproportionate margin pools.
Feature:
Application criticality determines which embedded functions resist cost-down pressure during platform revisions.
- Wireless Charging:Inductive coil assemblies embedded in console surfaces have become standard specification across mid-luxury vehicle segments. China's GB standards for electromagnetic compatibility have tightened test protocols, accelerating shielding material adoption among Asia-Pacific component suppliers.
- Infotainment Systems:Display mounting structures and cable management channels integrate directly into console substrates. German and American OEMs are consolidating these with digital instrument clusters under single supplier contracts.
- Storage Compartments:Adjustable and fixed bins retain specification across all vehicle tiers as fundamental utility elements.
- Control Panels:Physical switchgear faces displacement by capacitive touch surfaces in next-generation architectures.
Storage maintains universal presence; wireless charging gains specification fastest.
End User:
Customer type dictates contract structure, with fleet procurement now displacing traditional retail-driven processes in volume segments.
- OEMs:Original equipment manufacturers specify console architectures during platform definition phases, locking suppliers into multi-year contracts. Platform-sharing strategies across vehicle segments have concentrated sourcing decisions among German, Chinese, and American automotive groups.
- Fleet Operators:Rental and corporate procurement departments now specify modular console architectures enabling post-purchase feature activation through software unlocks. United States commercial fleet contracts increasingly include total cost of ownership calculations that weight upgrade pathway flexibility.
- Aftermarket Providers:Replacement and upgrade channels serve vehicle aging populations with standardized fitment kits.
- Custom Builders:Low-volume specialty manufacturers commission bespoke console designs with extended lead times.
OEM contracts anchor production planning; fleet procurement is expanding fastest as a specification channel.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese OEMs demonstrate the lowest price elasticity for premium integrated consoles, while Indian and Brazilian buyers enforce strict design-to-cost thresholds that compress supplier margins. German luxury manufacturers occupy the middle ground, accepting material premiums for REACH-compliant finishes. United States fleet procurement operates on total cost of ownership metrics that favor modular upgrade pathways.
China
Domestic electric vehicle platforms from BYD, NIO, and Xpeng are standardizing wireless charging and NFC payment modules in center console specifications. MIIT enforcement of GB electromagnetic compatibility standards has accelerated shielding material adoption among Asia-Pacific component suppliers. The Yangtze River Delta cluster around Shanghai anchors high-volume production capacity for compliant tier-one suppliers serving both domestic OEMs and European exporters facing retesting costs.
Germany
BMW, Mercedes-Benz, and Volkswagen Group are consolidating HVAC, infotainment, and wireless charging controls into unified integrated console modules for flagship electric architectures. REACH chemical compliance requirements for tanning agents and adhesives have accelerated supplier consolidation toward vertically integrated tanneries. Bavaria's automotive engineering corridor maintains concentration of design-to-cost capabilities competing for modular architecture programs.
United States
Commercial fleet contracts from rental and corporate procurement departments now specify modular console architectures enabling post-purchase feature activation through software unlocks. NHTSA Federal Motor Vehicle Safety Standard 201 enforcement directly influences console geometry and padding specifications for domestic production. The Detroit-Windsor automotive corridor concentrates full-system integrators leveraging electronics and interior systems portfolios for integrated cockpit contracts.
India
Maruti Suzuki, Hyundai Motor India, and Tata Motors are localizing passenger vehicle platforms that create entry points for modular console suppliers with proven design-to-cost capabilities. BIS certification requirements for automotive interior components are tightening quality thresholds for imported sub-assemblies. The Chennai-Bangalore industrial corridor is emerging as a production hub for plastic injection-molded substrates serving cost-sensitive economy vehicle lines.
Japan
Toyota, Honda, and Nissan are platform-sharing modular console architectures across hybrid and battery-electric vehicle segments to reduce tooling duplication. METI guidance on circular economy principles is weighting recycled-content specifications in domestic OEM procurement scorecards. The Nagoya-Toyota industrial zone maintains concentration of mechatronics integration expertise for converging thermal, electronic, and mechanical systems.
Automotive Center Console Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered supplier hierarchy that reorganizes around integration depth and material compliance capabilities. The market structure consolidates around full-system integrators with captive electronics portfolios, high-volume component specialists with regional production density, and niche finish providers serving luxury tactile specifications. Three archetypes dominate: integrated cockpit contractors, modular architecture fabricators, and surface treatment specialists. M&A activity concentrates on electronics integration capabilities, while capacity expansion targets Asia-Pacific assembly corridors.
Among Germany-based integrated cockpit contractors, Continental AG and DRÄXLMAIER Group exemplify the full-system integrator archetype, anchoring multi-year platform contracts through combined electronics and interior systems portfolios. Faurecia S.A. occupies a position within the European modular architecture tier, competing for standardized sub-assembly programs through design-to-cost capabilities. Yanfeng Automotive Trim Systems Co., Ltd. represents the Asia-Pacific volume specialist archetype, with production concentration across Chinese OEM supply chains and captive positioning for domestic electrification timelines.
| Leading Market Players |
|---|
| Continental AG |
| Faurecia S.A. |
| Yanfeng Automotive Trim Systems Co., Ltd. |
| Lear Corporation |
| AGM Automotive, LLC |
| Novares Group S.A. |
| Novem Car Interior Design GmbH |
| DRÄXLMAIER Group |
| Magna International Inc. |
| Others |
Supply Flow & Price Mechanics
Multi-year platform contracts between OEMs and tier-one suppliers lock in both polypropylene and leather supply access while providing visibility into pricing trajectories across vehicle lifecycle commitments. These arrangements concentrate negotiation leverage among full-system integrators serving German and Chinese automotive groups, compressing margin flexibility for component specialists locked into fixed-volume agreements.
Pricing Analysis
After-sales parts and service revenue tiers drive lifetime value capture for console suppliers with embedded electronics portfolios. Three-tier pricing structure across premium, standard, and economy levels separates integrated cockpit modules from modular sub-assemblies and fixed-configuration units. Cost compression in plastic substrate tiers is intensifying because ABS and polypropylene feedstock volatility feeds directly into contract renegotiations. Fleet procurement departments demonstrate lowest price sensitivity due to total cost of ownership calculations, while Indian economy vehicle OEMs enforce strict design-to-cost thresholds.
Supply Chain Analysis
Port congestion on Asia-Europe trade lanes and container availability constraints in Shanghai anchor inbound logistics costs for European exporters serving Chinese OEM supply chains. Manufacturing concentration in China, Germany, and Mexico feeds from polypropylene resin, leather tanning chemicals, and aluminum extrusion inputs. Single-source vulnerability in magnetorheological fluid damper electronics creates exposure for premium storage module programs. Distribution runs through tier-one direct OEM contracts with limited aftermarket channel penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform electrification timelines fragment supplier capabilities across material compliance and integration depth, creating entry points for specialists in wireless charging shielding and bio-based polymer formulations.
For Market Incumbents: Secure REACH-compliant tanning agent supply through backward integration into vertically integrated tanneries before European chemical restrictions tighten further. Lock in multi-year platform contracts with Chinese electric vehicle OEMs to defend against emerging Asia-Pacific volume specialists with captive domestic positioning. For New Entrants and Emerging Players: Lead with electromagnetic compatibility testing capabilities for wireless charging modules, targeting retesting cost exposure among European exporters serving MIIT-enforced Chinese OEM supply chains. White-space exists in closed-loop recycling partnerships for lightweight recycled-content consoles aligned with EU Green Deal procurement incentives. For Investors and Strategic Acquirers: Electronics integration specialists with mechatronics cross-functional teams represent the highest-conviction acquisition archetype as converging thermal, electronic, and mechanical systems displace traditional injection molders. Watch for MIIT announcements on GB standard electromagnetic compatibility protocol updates as inflection indicators for shielding material demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces tooling duplication across vehicle segments for German and Chinese OEMs. |
| Battery Supply Agreement | Secures lightweight material access for electric vehicle console architectures. |
| Software-Defined Vehicle Investment | Enables post-purchase feature activation for fleet procurement contracts. |
| Geographic Manufacturing Footprint | Positions suppliers within Yangtze River Delta and Chennai-Bangalore corridors. |
| Charging Infrastructure Partnership | Integrates NFC payment modules into center console specifications for Chinese OEMs. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SEC 10-K filings, and customs trade records across tier-one supplier procurement, OEM platform engineers, aftermarket distributors, and dealership operations. Bottom-up volume modeling triangulates against top-down market sizing derived from OEM platform electrification roadmaps and regional production cluster analysis.
Segmentation dimensions modeled span vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster across the analysis window. CAGRs derive from regression analysis against historical platform-sharing adoption curves and electrification timeline acceleration. Industry-specific forecast inputs include REACH annex update schedules and MIIT GB standard enforcement patterns.
Forecasts assume regulatory continuity in REACH, NHTSA, and MIIT regimes; material policy shifts would require re-modeling. Supply chain disruptions from petrochemical feedstock volatility or single-source electronics concentration present specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Sound Proofing Material Market
Automotive Interior & Exterior
Asia Pacific Automotive Interiors Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Automotive Seat Recliners Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market
Automotive Interior & Exterior
Automotive Soft Trim Interior Materials Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Auto Ventilated Seat Fan Market
Automotive Interior & Exterior
Automotive Chromium Finishing Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
Smart Automotive Headlight Market
Automotive Interior & Exterior
Car Oxygen Bar Market
Automotive Interior & Exterior
Japan Automotive Flooring Market
Automotive Interior & Exterior
United States Car Bumper Guard Market