
 North America Automotive Interiors Market | 2026-2036
North America Automotive Interiors Market Size, Share, and Industry Trends Forecast 2026-2036
North America Automotive Interiors Market Analytics
Software-defined vehicle architecture is fragmenting traditional interior supply chains into hardware-agnostic module ecosystems. Magna International leverages its seating and electronics integration capabilities to compete across multiple cabin domains. Lear Corporation anchors North American wire harness and seat system production through capital-intensive regional manufacturing footprints. Adient PLC specializes in premium seating architectures that differentiate on ergonomic adjustability and thermal comfort performance.
North America automotive interiors encompass the complete cabin environment including instrument panels, seating systems, door trim, headliners, and center consoles, typically manufactured through injection molding, compression forming, foam-in-place polyurethane processes, and textile lamination to achieve specified haptic, acoustic, and aesthetic performance targets. The primary commercial purpose centers on occupant safety containment, thermal and acoustic isolation, brand differentiation through tactile quality, and integration of human-machine interface mounting structures. Dashboard and console assemblies concentrate margin pools due to their electronics integration complexity and higher engineering change frequency. Sustainable feature classifications are expanding fastest as OEM procurement mandates tighten post-consumer recycled content thresholds and volatile organic compound emission limits.
NHTSA Federal Motor Vehicle Safety Standards govern occupant protection and interior component flammability, while EPA regulations under the Toxic Substances Control Act restrict certain plasticizers and flame retardants in cabin materials, collectively elevating compliance costs for imported substrate formulations. California Air Resources Board zero-emission vehicle requirements indirectly reshape interior material selection through weight reduction imperatives that extend electric driving range. Stakeholders must monitor how evolving NHTSA automated driving system guidance redefines seating orientation and restraint system requirements before committing long-tooling capital to next-generation interior platforms.
Market Dynamics
Software-defined vehicle architecture is fragmenting traditional interior supply chains into hardware-agnostic module ecosystems, forcing tier-one suppliers to restructure engineering organizations around domain controllers rather than discrete component categories.
Growth Catalysts
- EPA Material Standards:Volatile organic compound emission limits are accelerating supplier investment in water-based adhesives and low-emission polyurethane foam formulations across Michigan's manufacturing corridor.
- Electric Vehicle Platforms:Battery-electric vehicle architectures are eliminating transmission tunnels and expanding flat-floor cabin designs that enable reconfigurable seating modules.
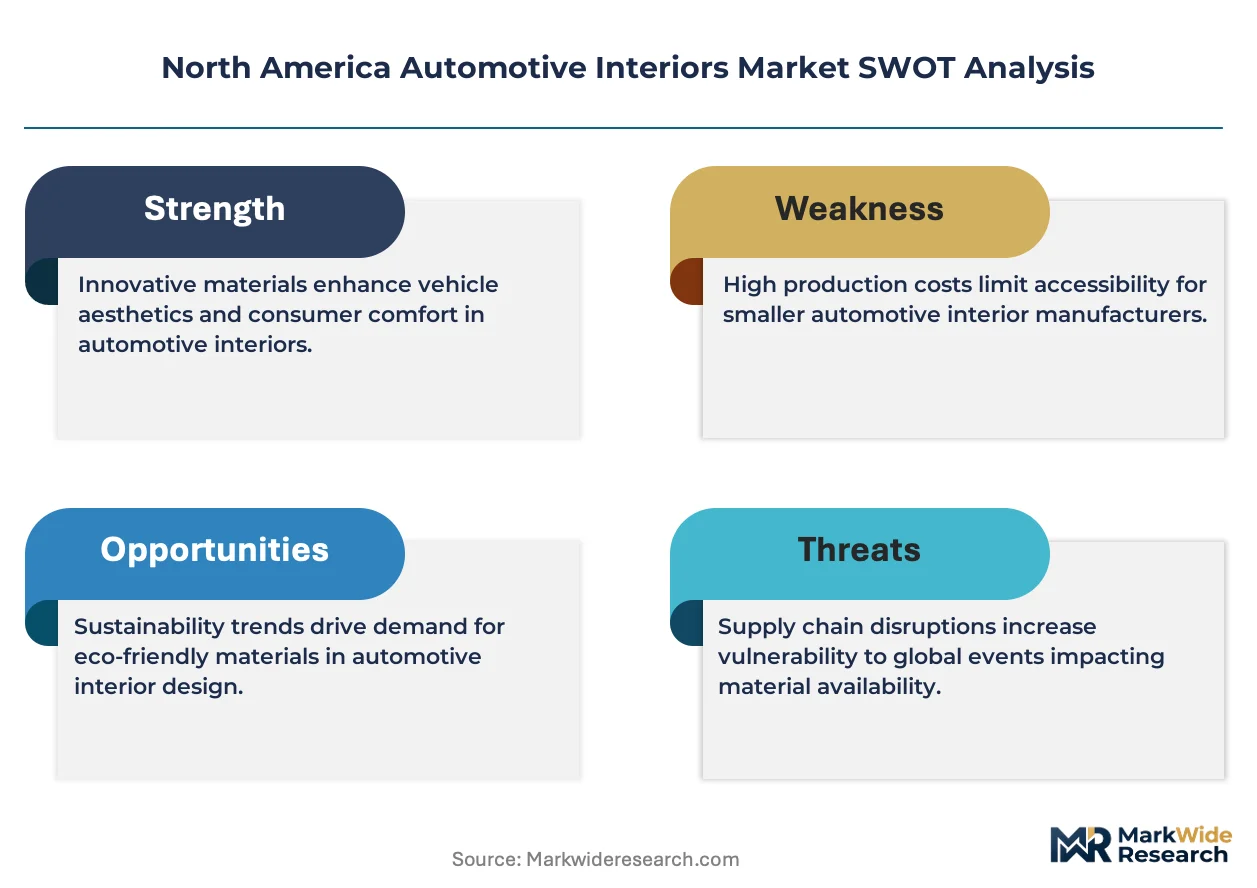
- NHTSA Automated Driving Guidance:Evolving occupant protection standards for partially automated vehicles are creating demand for adaptive restraint systems and non-traditional seating orientations.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene and polyurethane precursor costs fluctuate with crude oil indices, compressing margin visibility for injection-molded dashboard suppliers.
- Single-Source Tooling Concentration:Large-scale compression molds for instrument panels concentrate with three dominant toolmakers in Ontario and Michigan, creating supply bottleneck risk.
- Flammability Testing Burden:NHTSA Federal Motor Vehicle Safety Standard 302 requires extensive third-party burn-rate certification, extending new material qualification timelines by eight to fourteen months.
Strategic Opportunities
- Mexico Manufacturing Belt Expansion:Querétaro and Guanajuato production zones offer tariff-advantaged export positioning for seat assembly and wire harness integration serving US OEMs.
- Post-Consumer Recycled Content Mandates:California Air Resources Board procurement thresholds are creating premium pricing for recycled PET textile suppliers and bio-based foam alternatives.
- HMI-Ergonomics Convergence:Touchscreen mounting structures and adjustable seating architectures are merging design disciplines, enabling system-level contracts that span previously separate supplier tiers.
Industry Challenges
- Mechatronics Talent Scarcity:Seating suppliers struggle to hire firmware engineers capable of integrating sensor networks with pneumatic adjustment systems.
- Long-Tooling Capital Requirements:Dashboard injection molds require eighteen-to-twenty-four-month lead times, locking design commitments before final vehicle specifications stabilize.
- Legacy Platform Integration:New modular architectures must maintain backward compatibility with existing wire harness connector standards, constraining electrical system redesign freedom.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Automotive Interiors Market |
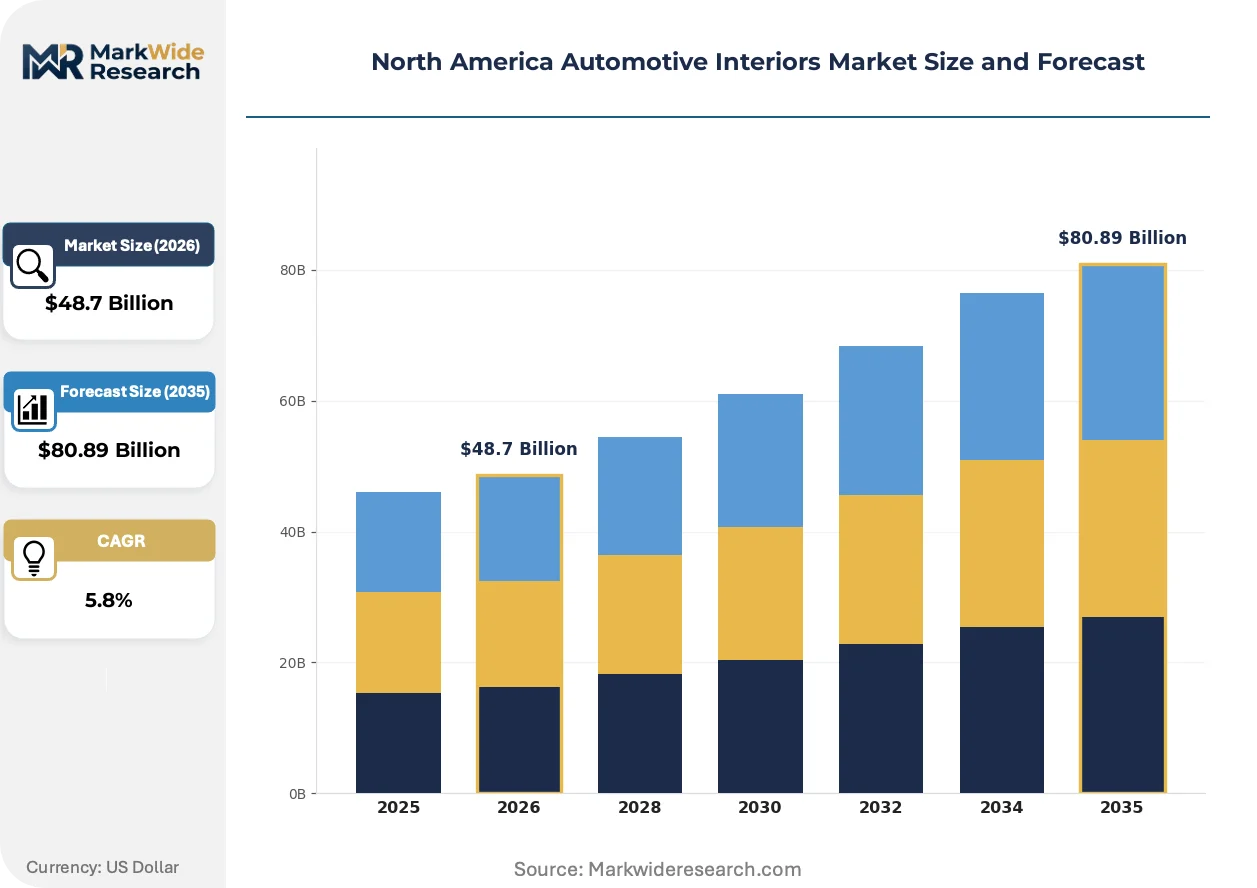
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $80.89 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dashboard, Upholstery, Console, Door Panels Material: Leather, Fabric, Plastic, Wood End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Tier-1 Suppliers Feature: Luxury, Ergonomic, Customizable, Sustainable |
| Companies Covered | Magna International, Johnson Controls International plc, Adient PLC, Grammer AG, Visteon Corporation, Lear Corporation, Grupo Antolin, Panasonic Corporation, Faurecia, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Automotive Interiors Market Evolving Landscape
Active grille shutters and thermal management systems are reshaping how cabin climate loads get calculated, forcing HVAC-integrated seat suppliers to coordinate development cycles with powertrain thermal engineers rather than operating as isolated comfort module vendors.
Biometric sensor integration is migrating from research prototypes into production seat frames, enabling real-time occupant health monitoring and adaptive climate control. Luxury OEMs in the Detroit Three are piloting electrocardiogram-embedded cushions for 2027 model year launches. This sensor migration is compressing the traditional boundary between seating suppliers and telematics system vendors, creating new intellectual property contention around data ownership.
NHTSA Federal Motor Vehicle Safety Standard updates for automated driving system occupant protection are mandating revised head restraint geometries and alternative seating orientations. The rulemaking process has extended compliance timelines, forcing suppliers to maintain dual tooling inventories for conventional and automated vehicle platforms. Seat system manufacturers serving the premium segment are most affected, as their customers pursue Level 3 automation certifications requiring non-forward-facing configurations.
Fleet procurement departments at rental car operators and corporate vehicle lessors are consolidating interior specification decisions at the national level, displacing individual dealership option selection. This buyer concentration is compressing trim-level diversity and rewarding suppliers with scale-efficient modular architectures. The consolidation pattern is most visible in Texas and Florida fleet registration clusters, where volume purchasing agreements now cover eighty percent of non-retail light vehicle acquisitions.
North America Automotive Interiors Market Segmentation
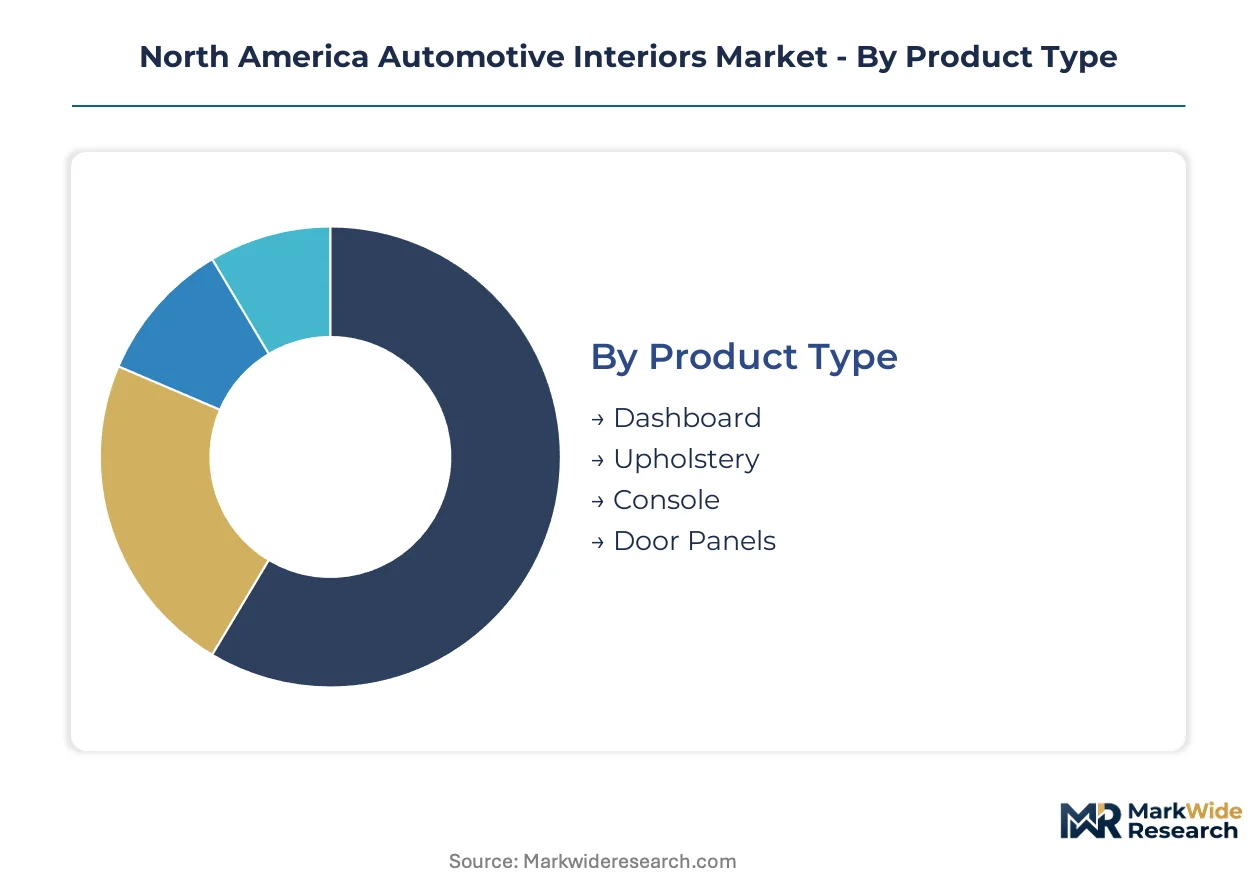
Interior segmentation in North America tracks how capital allocation splits across material chemistry, assembly complexity, and regulatory compliance tiers. Suppliers configure production lines differently for each dimension, creating distinct margin profiles and tooling requirements.
Product Type:
Cost tier differentiation separates high-investment cockpit modules from commodity trim pieces with shorter engineering cycles.
- Dashboard:Injection-molded instrument panel assemblies integrate structural foam substrates with soft-touch skins and electronics mounting bosses. Michigan-based OEM engineering centers concentrate procurement for these assemblies due to their crash safety certification burden and HVAC duct integration complexity.
- Upholstery:Seating surfaces and headliner textiles span cut-and-sew leather to compression-molded synthetic wraps. Mexican assembly plants in Querétaro are absorbing expanding upholstery volume as USMCA tariff advantages reshape sourcing geography for US-bound vehicles.
- Console:Center stack modules house gear selectors, cupholders, and wireless charging pads with lower structural requirements than dashboards.
- Door Panels:Map pocket assemblies and armrest substrates complete the cabin enclosure with localized injection molding near final assembly plants.
Dashboard holds installed capacity. Console is rotating up the share rankings.
Material:
Application requirements dictate material selection across touchpoint sensitivity, durability specifications, and emissions compliance thresholds.
- Leather:Full-grain and corrected-grain hides undergo chromium or vegetable tanning before automotive-grade finishing for steering wheels and seat bolsters. Premium truck platforms in Texas and Wyoming registration clusters sustain demand despite vegan alternative pressure from California fleet buyers.
- Fabric:Woven and knitted polyester textiles with foam lamination dominate mid-market seating inserts and door inserts. EPA volatile organic compound limits are forcing water-based adhesive transitions at Georgia and South Carolina textile finishing plants.
- Plastic:Polypropylene and ABS formulations serve structural components through injection molding and thermoforming processes.
- Wood:Veneer and hydrographic film applications concentrate in luxury brand differentiation strategies.
Plastic holds installed capacity. Sustainable alternatives are climbing the fastest.
End User:
Customer type determines specification authority, with vehicle assemblers and their tier-one delegates controlling design intent and tooling investment.
- OEMs:Detroit Three headquarters engineering groups in Michigan retain direct procurement relationships for dashboard and seating platform architectures. Their specification documents cascade material standards and test protocols through the supply base.
- Aftermarket Providers:Seat cover specialists and trim replacement vendors serve collision repair and vehicle customization demand through distribution networks concentrated in Florida and California retail clusters.
- Vehicle Assemblers:Final assembly plant material handling teams coordinate just-in-sequence interior module delivery from nearby supplier parks.
- Tier-1 Suppliers:Seating and cockpit system integrators manage sub-tier procurement for foam, textiles, and hardware components.
OEMs hold installed capacity. Aftermarket Providers are rotating up the share rankings.
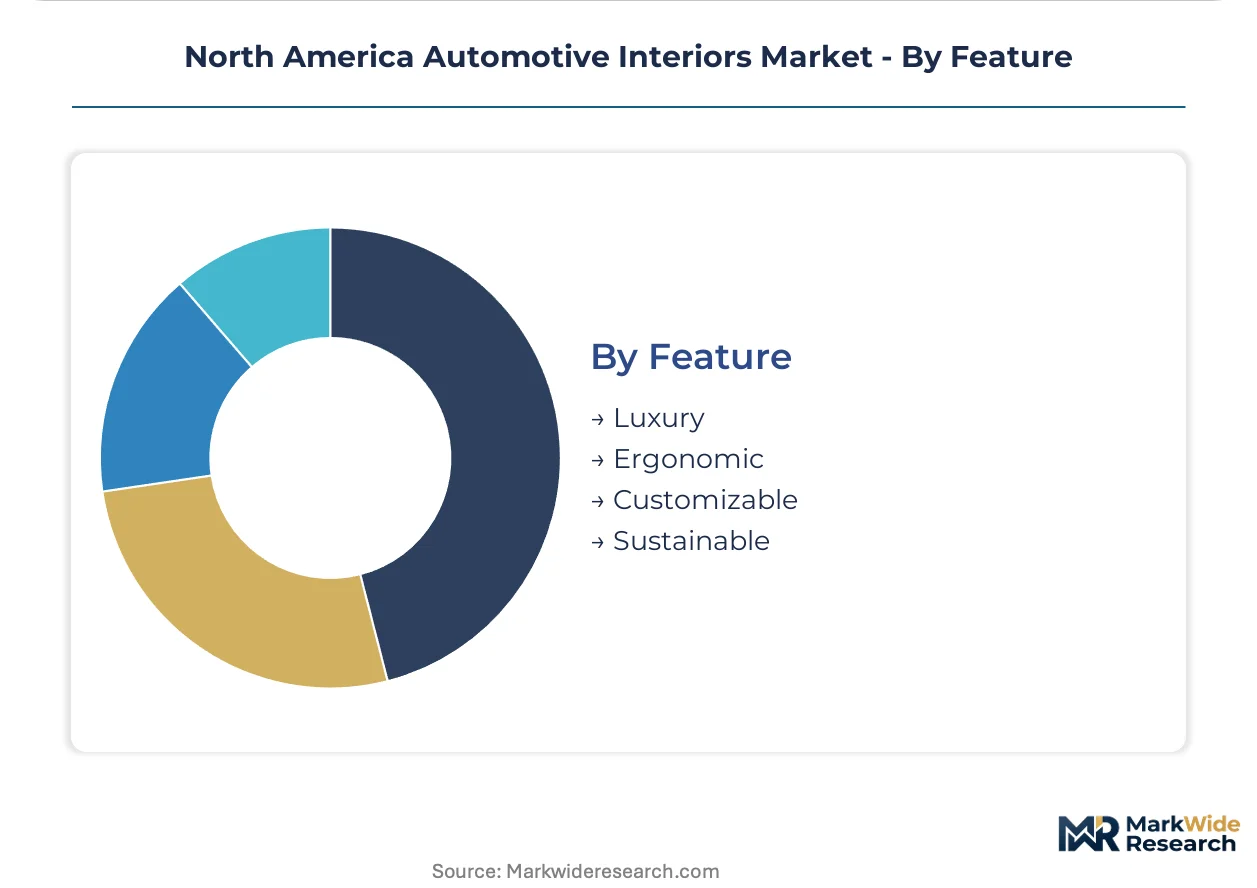
Feature:
Volume splits across price-positioning strategies, with ergonomic and sustainable classifications commanding engineering resource priority.
- Luxury:Nappa leather, genuine wood veneer, and ambient lighting systems differentiate premium vehicle trims. California Air Resources Board procurement mandates are complicating material selection as OEMs balance tactile quality with recycled content thresholds.
- Ergonomic:Adjustable lumbar support, heating and ventilation elements, and pressure-distributing foam constructions address occupant health and comfort performance. NHTSA automated driving guidance is expanding permissible seating orientations for Level 3 platforms, requiring redesigned ergonomic validation protocols.
- Customizable:Modular trim packages and color-configurable components support build-to-order manufacturing strategies.
- Sustainable:Bio-based foams, recycled PET textiles, and low-emission adhesive systems respond to tightening procurement mandates.
Luxury holds installed capacity. Sustainable is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico exports interior assemblies to US-based OEM final assembly plants across the Midwest and Southeast. Cross-border logistics corridors concentrate just-in-sequence delivery networks along I-35 and I-10 highway spines.
United States
Detroit Three engineering centers in Michigan specify dashboard and seating architectures for North American vehicle programs. NHTSA Federal Motor Vehicle Safety Standard 302 governs interior flammability testing requirements. The Michigan-Ohio supplier corridor houses concentrated injection molding capacity for instrument panel substrates.
Mexico
Querétaro and Guanajuato production zones absorb expanding seat assembly and wire harness integration volume. USMCA tariff advantages position Mexican plants for US-bound vehicle content. The Bajío region hosts tier-one supplier parks serving Volkswagen and BMW assembly operations.
Canada
Ontario-based toolmakers in Windsor and Toronto supply large-scale compression molds for instrument panel production. EPA volatile organic compound limits affect adhesive selection at cross-border finishing operations. The Ontario-Michigan manufacturing belt maintains integrated supply chain coordination across the Detroit River corridor.
North America Automotive Interiors Market Competitive Landscape
Channel-controlling players compete with product-specialist players across cockpit module and seating system categories. The supplier base organizes around tier-one integrators capable of domain-level contracting and sub-tier component specialists focused on material chemistry or hardware fabrication. Two strategic archetypes dominate: full-system integrators managing multi-domain interior platforms, and process-specialist suppliers concentrated in foam formulation or textile finishing. Competitive moves center on geographic expansion into tariff-advantaged production zones and portfolio diversification into software-integrated mechatronic systems.
Among North American headquartered integrators, Magna International, Lear Corporation, and Adient PLC exemplify the full-system archetype. Magna International occupies a position spanning seating and electronics integration domains. Lear Corporation anchors wire harness and seat system production through regional manufacturing footprints. Adient PLC represents premium seating specialization with ergonomic adjustability capabilities.
| Leading Market Players |
|---|
| Magna International |
| Johnson Controls International plc |
| Adient PLC |
| Grammer AG |
| Visteon Corporation |
| Lear Corporation |
| Grupo Antolin |
| Panasonic Corporation |
| Faurecia |
| Others |
Value Network & Pricing Analysis
Single-source tooling concentration in Ontario and Michigan determines both tiered pricing spreads and supply chain configuration, as instrument panel mold dependence forces buyers into premium contracting for capacity security while compressing margin visibility for commodity trim suppliers.
Pricing Analysis
Current-generation reconfigurable seating modules command premium positioning against prior-generation fixed architectures, while next-generation biometric-integrated systems are accelerating price stratification. Three-tier pricing structure across premium, standard, and economy levels separates Level 3 automation-ready seating from conventional forward-facing configurations from fleet-grade minimal adjustability. Cost compression in mid-market upholstery is intensifying because Mexican assembly plants absorb volume previously sourced from higher-cost US facilities. Fleet procurement departments exhibit highest price sensitivity, while luxury OEM engineering groups remain least responsive to incremental cost increases.
Supply Chain Analysis
Polypropylene and polyurethane precursor supply draws from petrochemical complexes in the US Gulf Coast, Canadian Alberta, and Mexican petrochemical corridors near Veracruz. Dashboard substrate production hinges on injection molding capacity clustered in Michigan and Ontario, while textile finishing for seating surfaces sources from Georgia, South Carolina, and expanding Mexican operations. Single-source vulnerability concentrates in large-scale compression molds held by three dominant toolmakers. Distribution runs through just-in-sequence supplier parks adjacent to final assembly plants across the Midwest and Southeast.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-enabled cabin reconfiguration is expanding service-attach revenue faster than hardware sales, as subscription-based seating position memory and climate preference synchronization create recurring revenue layers beyond initial module procurement.
For Market Incumbents: Insulate core cockpit module margins by securing backward integration into foam formulation chemistry and electronics integration firmware. Prioritize certification investment for NHTSA automated driving system occupant protection standards before design commitments lock. Channel control through exclusive supplier park positioning near Detroit Three assembly operations limits emerging competitor access.
For New Entrants and Emerging Players: Build out specialized capability in bio-based foam alternatives and recycled PET textile finishing to capture California Air Resources Board procurement premium. The aftermarket seat cover and trim replacement segment offers lowest entry barriers, with distribution networks in Florida and California retail clusters showing penetrable fragmentation. Target collision repair channel partnerships as initial go-to-market anchor.
For Investors and Strategic Acquirers: The market sits at a platform transition phase that favors mechatronics-integrated seating specialists over pure-play textile or foam component vendors. Long-term viability centers on intellectual property ownership in sensor-embedded seat architectures and domain controller software stacks. Monitor NHTSA rulemaking finalization timelines as inflection signal for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces tooling duplication across conventional and automated vehicle seating configurations for Detroit Three programs. |
| Software-Defined Vehicle Investment | Enables firmware-upgradable seat control modules that extend revenue capture through over-the-air feature activation. |
| Geographic Manufacturing Footprint | Querétaro and Guanajuato expansion secures USMCA tariff advantages for US-bound seat assembly volume. |
| Battery Supply Agreement | Electric vehicle platform volume commitments anchor long-term interior module procurement contracts. |
| Charging Infrastructure Partnership | Fleet operator relationships streamline national-level interior specification consolidation for rental and corporate lessors. |
Research Methodology
A spread of perspectives from Tier 1 supplier procurement officers, OEM platform engineers, aftermarket distributors, and dealership operations managers converged on the working assumptions underlying demand projections. Primary fieldwork combined structured interviews with secondary validation against vehicle production databases, IHS Markit registration data, SEC supplier filings, and EPA compliance disclosure records. Bottom-up segmentation modeling triangulated against top-down macroeconomic demand indicators.
Demand-supply balance framing anchored the analytical approach across the projection horizon, with segmentation dimensions spanning vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster. CAGRs were derived from iterative convergence of historical production trajectory analysis and forward-looking procurement intent signals. Industry-specific forecast inputs incorporated NHTSA regulatory timeline scenarios and electric vehicle platform rollout schedules.
Stress conditions across petrochemical feedstock volatility, tariff regime shifts, and automated driving system certification delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory compliance timelines and OEM platform consolidation patterns. Quarterly review of NHTSA rulemaking progress, USMCA dispute resolution filings, and Tier 1 supplier earnings guidance is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Energy Absorption (EA) Pads Market
Automotive Interior & Exterior
Automotive Center Stack Display Market
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Car Organizer Market
Automotive Interior & Exterior
All Plastic Front End Module Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Automotive OEM Interior Coatings Market
Automotive Interior & Exterior
Bonnet Lock Plate and Latch Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Asia-Pacific Automotive Flooring Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Automotive in-Vehicle Air Purifier Market
Automotive Interior & Exterior
Power Sunroof Market
Automotive Interior & Exterior
Russia Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Door Panel Market
Automotive Interior & Exterior
Auto Internal Connector Market