
 Yaw Damper Market | 2026-2036
Yaw Damper Market Size, Share, and Industry Trends Forecast 2026-2036
Yaw Damper Market Insights
The yaw damper market is recalibrating around a widening performance gap between premium electronic systems and legacy mechanical units. KYB Corporation leverages its hydraulic actuator heritage to anchor supply relationships with Asian rotorcraft manufacturers. ZF competes through integrated chassis-electronics capabilities that extend from automotive into aerospace damping architectures. KONI differentiates via specialized servo-valve engineering for business jet applications where weight reduction commands priority.
A yaw damper is a flight control augmentation device that suppresses Dutch roll oscillations through rudder deflection commands generated by rate gyro sensors and processed via analog or digital control laws, typically operating within bandwidths of 0.2 to 2.0 Hz. Its primary purpose is to reduce pilot workload and enhance passenger comfort by maintaining directional stability without continuous manual rudder input. Electronic product types now capture the dominant margin pool as fly-by-wire architectures displace electrohydraulic units in new commercial aircraft programs. MEMS sensor technology leads volume growth due to solid-state reliability and reduced calibration drift compared to legacy gyroscopic mechanisms, though inertial navigation platforms still occupy the military aircraft segment where jamming resilience matters.
FAA Part 25 airworthiness standards and EASA CS-25 certification requirements mandate yaw damper functionality for all transport-category aircraft, creating non-negotiable demand tied to type certificate validation timelines. The EU AI Act and emerging machine-learning verification protocols are forcing suppliers to document algorithmic transparency in adaptive damping control systems. Stakeholders must monitor how dual-certification strategies between FAA and China's CAAC reshape supplier qualification burdens for platforms targeting both markets.
Market Dynamics
The yaw damper market is undergoing a structural recalibration as fly-by-wire architectures systematically displace electrohydraulic control systems across new commercial aircraft programs, compressing supplier margins on legacy mechanical units while elevating electronic system value capture.
Growth Catalysts
- FAA Part 25 mandates:Airworthiness standards requiring yaw damper functionality for all transport-category aircraft create non-negotiable demand tied to type certificate validation timelines.
- MEMS sensor diffusion:Solid-state rate gyro technology delivers reduced calibration drift and improved reliability compared to legacy mechanical gyroscopic mechanisms.
- Commercial fleet renewal:Accelerating replacement cycles for aging narrow-body and wide-body aircraft drive specification of integrated electronic stability augmentation systems.
Market Restraints
- Dual-certification burdens:Simultaneous FAA and CAAC qualification requirements for platforms targeting both US and Chinese markets extend development timelines and duplicate testing costs.
- Specialized servo-valve supply concentration:Precision hydraulic component manufacturing clusters in Germany and Japan, creating geographic vulnerability for tier-two damper assemblers.
- Algorithmic transparency requirements:EU AI Act verification protocols force extensive documentation burdens on adaptive damping control development.
Strategic Opportunities
- Urban air mobility integration:Electric vertical takeoff and lift aircraft programs require lightweight stability augmentation for multirotor configurations.
- Aftermarket retrofit demand:Business jet operators seek electronic yaw damper upgrades to replace aging mechanical units in legacy airframes.
- India defense procurement:Indigenous rotorcraft development programs under the country's PLI scheme create qualified supplier pathways for damping system integrators.
Industry Challenges
- Control law verification timelines:Software certification under DO-178C standards for digital yaw damper implementations extends qualification periods.
- Legacy system integration friction:Hybrid architectures combining electronic command generation with existing hydraulic actuation require extensive interface validation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yaw Damper Market |
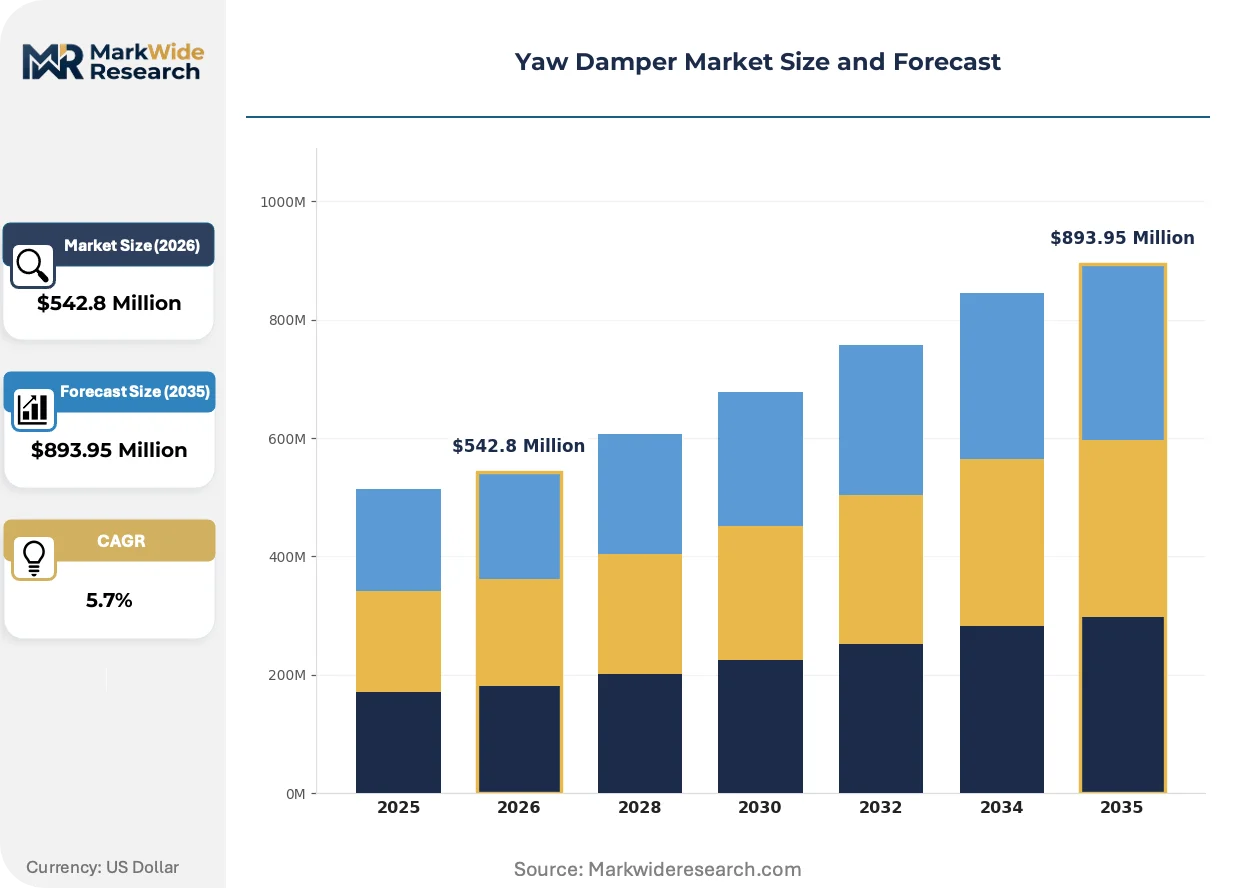
| Market Size in 2026 | $542.8 Million |
| Market Size in 2035 | $893.95 Million |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mechanical, Electrohydraulic, Electronic, Hybrid Technology: Gyroscopic, Inertial Navigation, Optical Sensor, MEMS Sensor Application: Commercial Aircraft, Business Jets, Military Aircraft, Rotorcraft End User: Airlines, Defense Contractors, Flight Schools, Aircraft Manufacturers |
| Companies Covered | KYB Corporation, KONI, ZF, Escorts Limited, Liebherr Group, Hitachi Astemo, MSA Damper, Schrey & Veit, Knorr-Bremse, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yaw Damper Market Trends and Innovations
Active reshaping of the yaw damper landscape centers on sensor fusion architectures, algorithmic governance frameworks, and compressed procurement cycles that favor integrated system suppliers over component vendors.
Digital twin-based hardware-in-the-loop testing is unifying validation workflows for yaw damper control law verification. Tier-one avionics suppliers deploy these platforms to compress certification timelines for fly-by-wire programs. The approach is unifying previously separate structural, thermal, and control loop analyses into continuous integration pipelines that accelerate design iteration.
EASA CS-25 certification amendments tighten performance bandwidth requirements for Dutch roll suppression across transport aircraft categories. Manufacturers must demonstrate enhanced stability margins under degraded sensor conditions. Business jet OEMs in Switzerland and France are responding with redundant MEMS triplex configurations that exceed baseline mandates.
Airline technical procurement teams now bundle yaw damper modules within comprehensive flight control system contracts rather than sourcing damping hardware separately. This consolidation favors suppliers offering integrated actuator-sensor-controller packages. The pattern is most pronounced among US-based low-cost carriers optimizing fleet standardization across A320neo and 737 MAX platforms.
Yaw Damper Market Segmentation
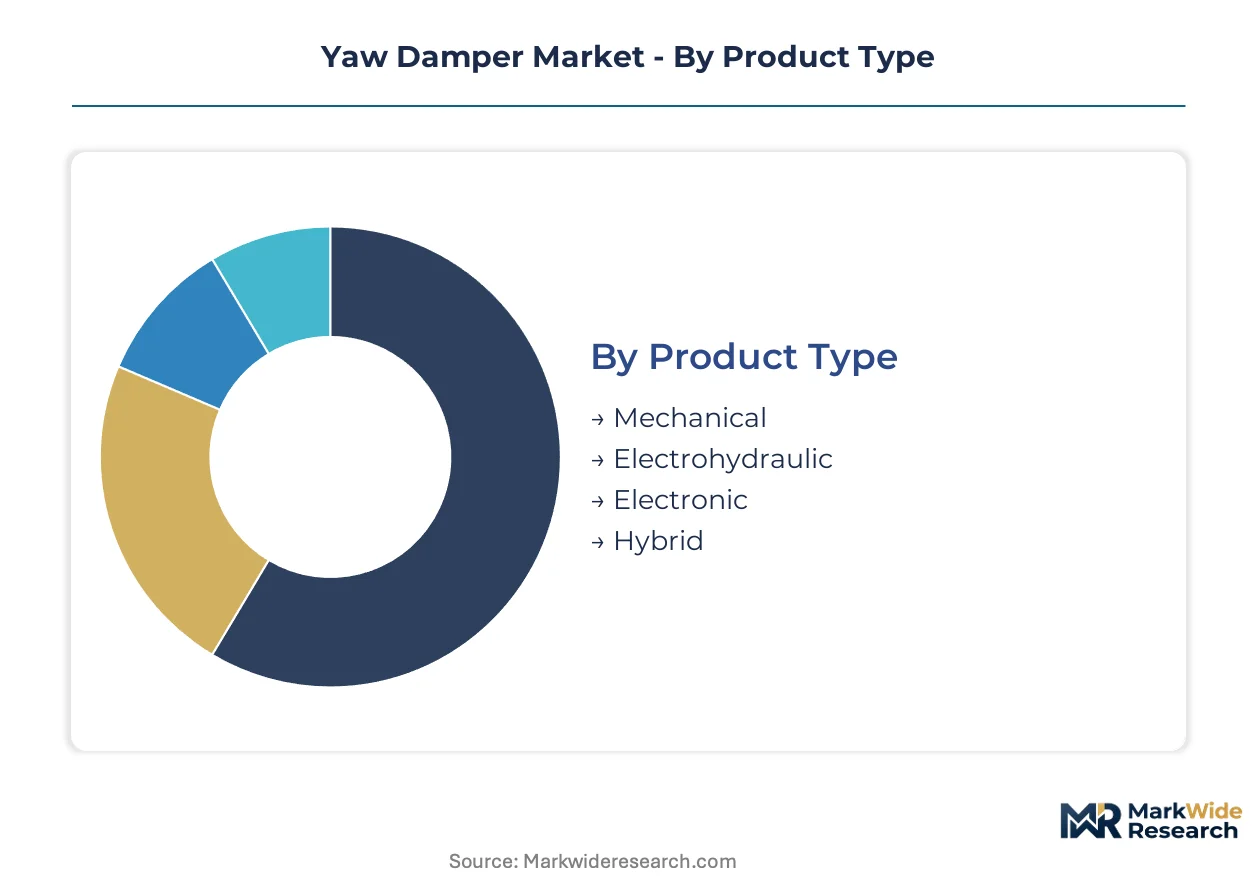
Yaw damper procurement patterns diverge sharply across aircraft categories and certification tiers, with fly-by-wire platforms demanding integrated electronic packages while legacy fleets sustain mechanical aftermarket demand. Segment boundaries are hardening as FAA Part 25 mandates force technology upgrades in transport-category applications while military programs preserve specialized inertial navigation requirements.
Product Type:
Supply concentration for precision servo-valves and solid-state controllers tilts procurement leverage toward integrated system suppliers in Germany and Japan.
- Electronic:Digital control laws process rate gyro signals through flight computers to command electromechanical actuators with bandwidth precision exceeding analog predecessors. Airlines operating A320neo and 737 MAX fleets in the United States specify these units exclusively for new deliveries under fleet standardization mandates.
- Electrohydraulic:Hybrid architectures combine electronic command generation with hydraulic power amplification, bridging certification-validated actuator designs with modern sensor inputs. Business jet retrofit programs in Switzerland and France favor these units for minimal airframe modification requirements.
- Mechanical:Purely gyroscopic-mechanical damping units persist in aging regional turboprop fleets where certification grandfathering limits upgrade economics.
- Hybrid:Emerging configurations blend electronic sensing with preserved hydraulic actuation for rotorcraft applications requiring jamming resilience.
Electronic systems absorb the bulk of installed capacity; hybrid architectures are expanding most quickly in military rotorcraft programs.
Technology:
Cost tiers separate aviation-grade MEMS sensors from military-purposed inertial platforms, with calibration drift specifications defining procurement boundaries.
- MEMS Sensor:Solid-state micromachined rate gyroscopes deliver reduced calibration drift and improved shock tolerance compared to mechanical alternatives. Commercial narrow-body production lines in the United States and France have standardized on MEMS-based damping for weight reduction and reliability gains.
- Inertial Navigation:Ring laser gyro and fiber-optic gyro platforms provide navigation-grade precision for GPS-denied environments. Military aircraft programs requiring jamming resilience specify these units despite cost premiums.
- Gyroscopic:Mechanical spinning-mass gyros persist in legacy airframes where airworthiness directives permit continued operation.
- Optical Sensor:Fiber-optic rate sensors serve specialized high-altitude platforms where electromagnetic interference immunity commands priority.
MEMS sensors command the dominant procurement volume; inertial navigation maintains the steepest margin structure.
Application:
Volume concentration tracks OEM delivery schedules, with commercial aircraft programs generating multi-unit orders per airframe against single-unit military procurements.
- Commercial Aircraft:Transport-category platforms require redundant yaw damper channels under FAA Part 25 and EASA CS-25 mandates. Fleet renewal programs at US low-cost carriers drive specification of integrated electronic stability augmentation across A320neo and 737 MAX deliveries.
- Business Jets:Weight reduction priorities favor compact MEMS-based units with triplex redundancy configurations. Swiss and French OEMs lead adoption of redundant sensor architectures exceeding baseline certification requirements.
- Military Aircraft:Survivability specifications demand hardened inertial platforms with backup mechanical modes.
- Rotorcraft:Multirotor urban air mobility prototypes require lightweight damping for directional stability in hover-to-transition flight regimes.
Commercial aircraft absorbs the bulk of installed capacity; urban air mobility rotorcraft applications are climbing the fastest.
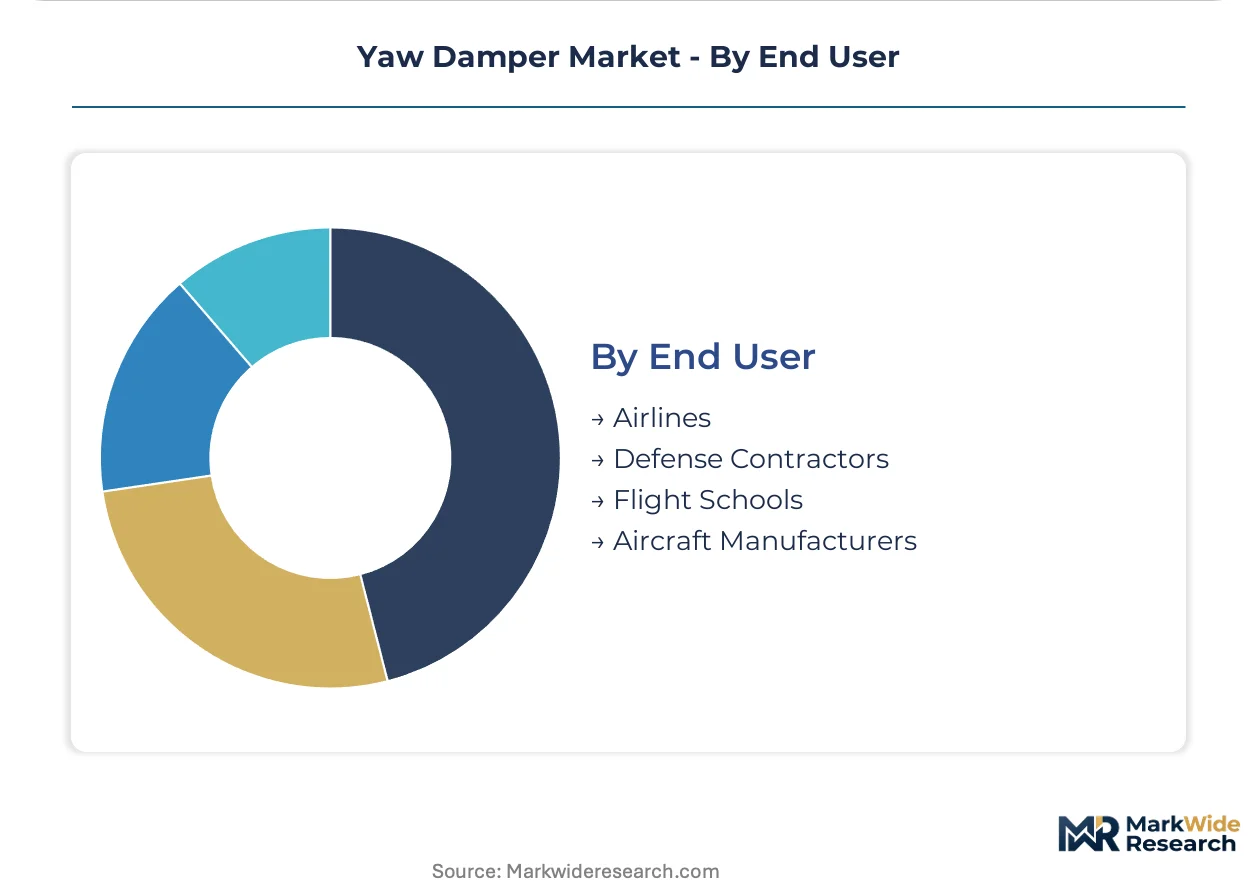
End User:
Procurement authority patterns split between OEM line-fit specifications and airline direct purchases for retrofit programs.
- Aircraft Manufacturers:Boeing and Airbus integrate yaw damper modules within comprehensive flight control system contracts rather than sourcing damping hardware separately. This bundling favors tier-one suppliers offering actuator-sensor-controller packages.
- Airlines:Technical procurement teams at US low-cost carriers optimize fleet standardization across platforms, creating volume leverage for multi-airframe contracts.
- Defense Contractors:Lockheed Martin and Boeing Defense specify military-hardened units with specialized environmental qualification requirements.
- Flight Schools:Training fleet operators prioritize cost-minimized mechanical units for piston-powered aircraft with limited stability augmentation needs.
Aircraft manufacturers absorb the bulk of installed capacity; defense contractors are gaining share fastest through classified platform development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wichita anchors aerospace manufacturing density for flight control systems, with Seattle and Toulouse forming complementary design-to-production corridors for integrated yaw damper specifications.
United States
FAA Part 25 mandates drive non-negotiable demand for electronic stability augmentation across Boeing 737 MAX and Airbus A320neo fleets operated by low-cost carriers. The FAA's airworthiness directive timeline compresses supplier qualification windows for new entrants. Wichita's aviation cluster concentrates tier-one actuator manufacturing, while Seattle hosts integrated flight control system design centers.
Germany
EASA CS-25 certification amendments tighten Dutch roll suppression bandwidth requirements, forcing specification upgrades for export-bound platforms. The EU AI Act imposes algorithmic transparency documentation burdens on adaptive damping control development. Precision servo-valve manufacturing clusters in Baden-Württemberg supply tier-two damper assemblers across European rotorcraft programs.
China
CAAC dual-certification requirements for platforms targeting domestic and export markets extend development timelines and duplicate testing expenditures. The country's civil aviation regulator tightens performance validation protocols for imported flight control subsystems. COMAC's Shanghai assembly lines specify localized yaw damper sourcing for C919 narrow-body production ramps.
Japan
METI industrial policy supports precision component manufacturing for aerospace hydraulic systems through targeted supply chain resilience programs. Domestic content requirements for defense rotorcraft sustain demand for specialized damping architectures. Nagoya's aerospace corridor integrates yaw damper modules within regional turboprop and helicopter OEM supply contracts.
India
PLI scheme incentives for indigenous rotorcraft development create qualified supplier pathways for damping system integrators. The country's national aviation regulator aligns certification protocols with FAA and EASA standards to accelerate export market access. Bengaluru's defense aerospace cluster hosts flight control system integration facilities for HAL's light utility helicopter programs.
Yaw Damper Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across a tiered supplier structure where integrated system vendors capture margin premiums over component specialists. The market consolidates around three strategic archetypes: hydraulic heritage manufacturers pivoting toward electromechanical architectures, diversified automotive-electronics suppliers leveraging chassis control expertise, and specialized servo-valve engineering houses serving weight-critical applications. Dominant competitive moves include strategic partnerships between sensor developers and actuator manufacturers, plus selective backward integration into MEMS fabrication capacity.
Within the hydraulic heritage tier, KYB Corporation and ZF exemplify manufacturers leveraging automotive and industrial damping expertise into aerospace qualification pathways. KONI occupies a position among specialized engineering houses where servo-valve precision commands premium positioning. These three anchors represent distinct competitive vectors: scale-driven platform integration, cross-industry technology transfer, and niche performance optimization.
| Leading Market Players |
|---|
| KYB Corporation |
| KONI |
| ZF |
| Escorts Limited |
| Liebherr Group |
| Hitachi Astemo |
| MSA Damper |
| Schrey & Veit |
| Knorr-Bremse |
| Others |
Pricing and Supply Chain Analysis
Electronic-mechanical capability divergence between fly-by-wire platforms and legacy hydraulic units manifests in parallel pricing stratification and supply chain tiering. FAA Part 25 certification tiers anchor value-based premiums for integrated electronic packages, while commodity mechanical damper sourcing concentrates in cost-driven aftermarket channels serving aging regional fleets.
Pricing Analysis
Certification-validated uptime performance anchors value-based pricing for electronic yaw damper systems. Three-tier pricing structure across premium, standard, and economy levels separates DO-178C compliant digital units from electrohydraulic hybrids and grandfathered mechanical replacements. Price differentiation hinges on FAA/EASA dual-certification completion and MEMS sensor redundancy grades. Cost compression in mechanical aftermarket tiers is intensifying because airlines extend retrofit cycles on aging turboprops. Defense contractors exhibit lowest price sensitivity due to jamming-resilience specifications; flight schools demonstrate highest sensitivity with piston-aircraft cost constraints.
Supply Chain Analysis
Direct-to-OEM channels handle integrated flight control system demand from Boeing and Airbus line-fit programs. Precision servo-valve manufacturing clusters in Germany and Japan; MEMS sensor fabrication concentrates in the United States and Taiwan. Supply chains draw from aerospace-grade aluminum forgings, specialized hydraulic fluids, and flight-certified microelectronics. Single-source vulnerability in precision valve machining creates geographic risk for tier-two damper assemblers. Distribution runs through tier-one avionics integrators bundling actuator-sensor-controller packages under multi-airframe contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
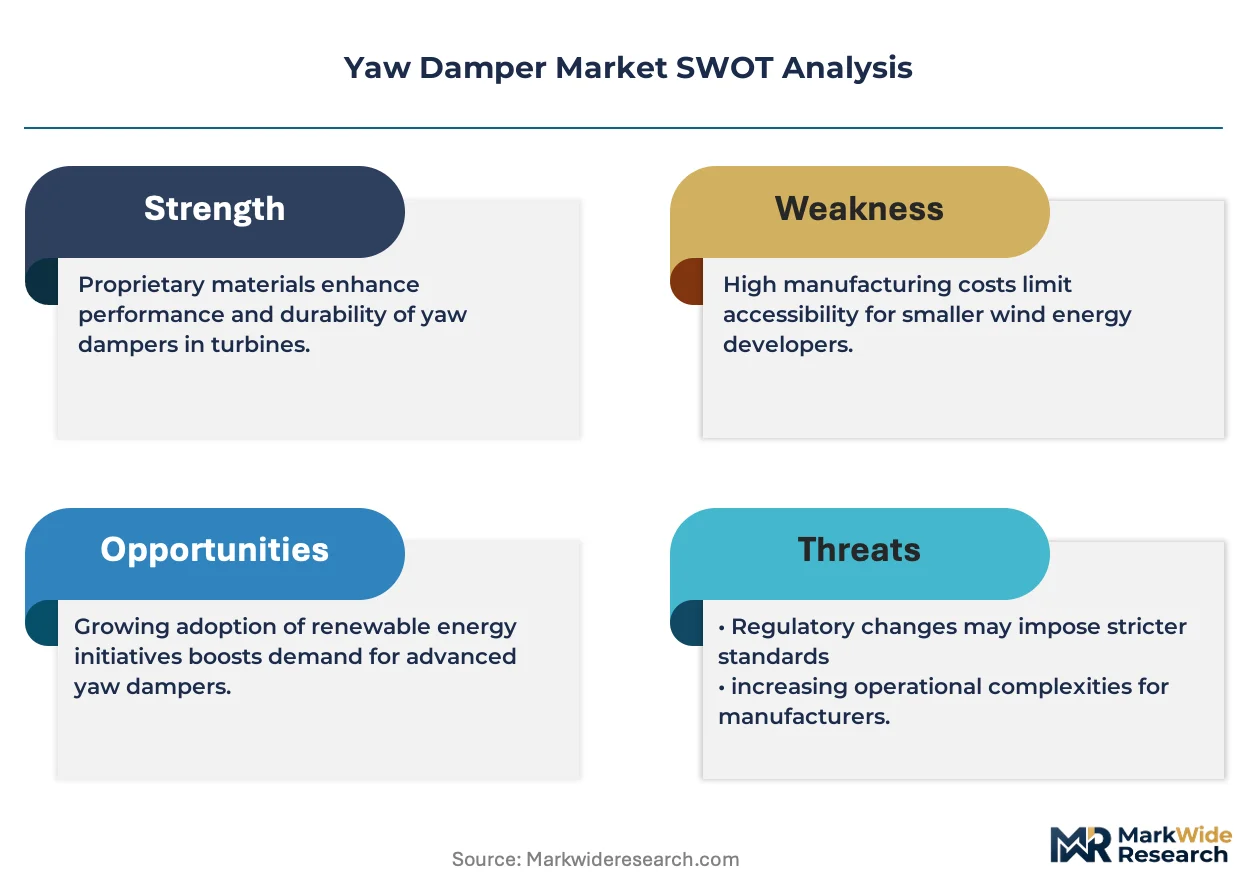
FAA Part 25 airworthiness mandates erect a cost-of-compliance barrier that protects qualified incumbents while forcing new entrants to absorb extended DO-178C software certification timelines before revenue capture.
For Market Incumbents: Acquire MEMS fabrication capacity to secure sensor supply autonomy against foundry allocation constraints. Defensive consolidation should prioritize backward integration into flight computer processing architectures as fly-by-wire platforms displace electrohydraulic hybrids. KYB Corporation and ZF demonstrate viable pathways leveraging automotive-electronics scale into aerospace qualification pipelines. Channel control through exclusive tier-one supplier agreements with Airbus and Boeing insulates against price erosion in commercial narrow-body segments. For New Entrants and Emerging Players: The premium-economy price gap in business jet retrofits creates entry leverage for electrohydraulic units minimizing airframe modification costs. White-space targets cluster in India's PLI-scheme rotorcraft programs and urban air mobility multirotor prototypes requiring lightweight stability augmentation. Swiss and French business jet OEMs represent the most penetrable customer archetype given triplex redundancy demand exceeding baseline EASA mandates. Go-to-market execution should emphasize DO-160G environmental qualification completion ahead of sales engagement. For Investors and Strategic Acquirers: Exit pathways concentrate in tier-one avionics consolidators seeking flight control system integration capabilities. Long-term viability favors suppliers with captive MEMS sensor technology and established FAA/EASA dual-certification track records. Acquisition target archetype: specialized servo-valve engineering houses with weight-critical business jet positioning. Watch COMAC C919 production ramp rates as inflection signal for China domestic supply chain localization pressure on Western incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Fabrication Backward Integration | Captive sensor supply reduces foundry allocation risk for tier-one damper integrators. |
| Dual-Certification Investment | Simultaneous FAA and EASA qualification opens Boeing and Airbus supply contracts. |
| Urban Air Mobility Partnership | Multirotor damping specifications from Joby Aviation and Archer Aviation establish new volume segments. |
| Aftermarket Retrofit Channel | Business jet operator direct sales bypass OEM bundling and capture higher margin capture. |
| India PLI Scheme Localization | HAL light utility helicopter programs create qualified supplier pathways for damping system integrators. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with flight control system engineers, airline technical procurement managers, FAA certification specialists, and tier-one supplier program directors combined with bottom-up and top-down triangulation. Secondary sources included FAA airworthiness directive databases, EASA CS-25 certification amendment records, COMAC supplier disclosure filings, and aerospace customs import-export statistics.
Segment-level modeling addressed product type granularity across electronic, electrohydraulic, mechanical, and hybrid architectures; technology tiers separating MEMS sensor, inertial navigation, gyroscopic, and optical sensor implementations; application splits across commercial aircraft, business jets, military aircraft, and rotorcraft; and end-user categories spanning aircraft manufacturers, airlines, defense contractors, and flight schools. CAGRs were derived from installed base renewal cycles, OEM delivery schedules, and retrofit penetration assumptions across the projection horizon. Industry-specific forecast inputs incorporated FAA Part 25 mandate compliance deadlines and EASA algorithmic transparency documentation burdens.
Inputs from FAA certification databases and EASA amendment records were available through the study window; gaps in CAAC validation protocol specifics introduce uncertainty bands for China market projections. Forecasts reflect assumptions regarding fleet renewal acceleration, MEMS sensor reliability improvements, and dual-certification burden evolution. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
Automotive Torque Vectoring System Market
Powertrain
High Speed Engine Market
Powertrain
Global Automotive GD Injector Market
Powertrain
Global Driveline Market
Powertrain
Crankshaft Oil Market
Powertrain
Automotive Camshaft Market
Powertrain
Axle Shaft Market
Powertrain
Carburetor Market
Powertrain
United Kingdom Automotive Engine Oils Market
Powertrain
Diesel Engine Catalyst Market
Powertrain
Transmission Oil Filters Market
Powertrain
Natural Gas Engines Market
Powertrain
Global Automotive Damper Pulley Market
Powertrain
Italy Electro Hydraulic Power Steering Market
Powertrain
Electric Two-Wheeler Powertrain and Range Validation Test Systems Market
Powertrain
Transmission Repair Market