
 Boat Console Market | 2026-2036
Boat Console Market Size, Share, and Industry Trends Forecast 2026-2036
Boat Console Market Outlook
Recreational boaters is bifurcating from commercial vessel buyers as the primary growth archetype in console procurement. Yamaha Motor Corporation leverages its outboard-to-console ecosystem to control integrated helm supply chains across multiple boatbuilder accounts. Sportsman Boats specializes in family-friendly center-console layouts that anchor its position in the coastal Southeast retail channel. Maverick Boat Group dominates shallow-draft technical poling skiffs, a niche where console weight and sight-line precision determine competitive outcomes.
A boat console serves as the centralized command station housing navigation displays, engine instrumentation, steering mechanisms, and electrical switching for marine vessels, typically fabricated from fiberglass, aluminum, or UV-stabilized polymer composites to withstand salt corrosion and continuous vibration. Digital Displays command the highest attachment rates as OEMs standardize multifunction touchscreen helm architectures, while Switch Panels retain steady aftermarket replacement demand due to simpler retrofit economics. Fiber Glass leads material selection among saltwater-oriented builders for its strength-to-weight ratio and moldability into complex integrated designs, though Aluminum gains share in commercial and freshwater applications where impact durability outweighs cosmetic refinement.
The US Coast Guard enforces navigation equipment and structural fire-safety standards that directly dictate console layout clearances and electrical harness routing, while ISO 12217 small-craft stability criteria influence console placement and mass distribution during hull design certification. The EPA's evaporative emission regulations under the Clean Air Act constrain fuel tank and vent integration within console cavities, adding engineering complexity for gasoline-powered configurations. Stakeholders must monitor how emerging battery-electric propulsion architectures will redefine console thermal management, wire gauge requirements, and helm interface protocols before committing to next-generation platform investments.
Market Dynamics
Integrated digital helm architectures are compressing traditional switch-panel supply chains as recreational boaters demand touchscreen consolidation. The US Coast Guard's updated ergonomics standards are forcing simultaneous redesigns across multiple OEM programs.
Growth Catalysts
- Center-console sportfishing expansion:Coastal Florida boatbuilders are scaling premium integrated helm orders to capture high-margin retail demand. Saltwater tournament fishing circuits drive specification upgrades.
- EPA evaporative emission compliance:The Clean Air Act's fuel tank venting mandates require engineered console cavities, creating captive demand for certified integrated designs.
- Fiberglass moldability advances:Complex UV-stabilized polymer composite forming enables seamless multifunction display housing, reducing assembly steps for saltwater-oriented OEMs.
Market Restraints
- Aluminum price volatility:Commercial and freshwater builders face margin compression from fluctuating aluminum sheet costs, constraining mid-tier console pricing flexibility.
- Single-source display dependency:Multifunction touchscreen suppliers concentrate in East Asian manufacturing clusters, exposing OEMs to concentrated supply disruption risk.
- ISO 12217 certification friction:Small-craft stability criteria demand iterative console placement testing, extending hull-design timelines and freezing platform commitments.
Strategic Opportunities
- Battery-electric thermal management:Electric propulsion architectures require redesigned console wire gauge and cooling integration, opening white space for first-mover engineering services.
- Aftermarket switch-panel retrofit channels:Simpler replacement economics favor independent marine service networks, bypassing OEM captive distribution in coastal maintenance corridors.
- Family-friendly layout specialization:Coastal Southeast retail channels show underpenetrated demand for ergonomics-optimized console configurations targeting recreational day-boaters.
Industry Challenges
- Marine electrical harness integration:Complex routing of high-amperage cables within compact console cavities demands specialized technician training that outpaces vocational program output.
- Multifunction display protocol fragmentation:Competing helm interface standards from marine electronics suppliers force costly dual-certification engineering for platform compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boat Console Market |
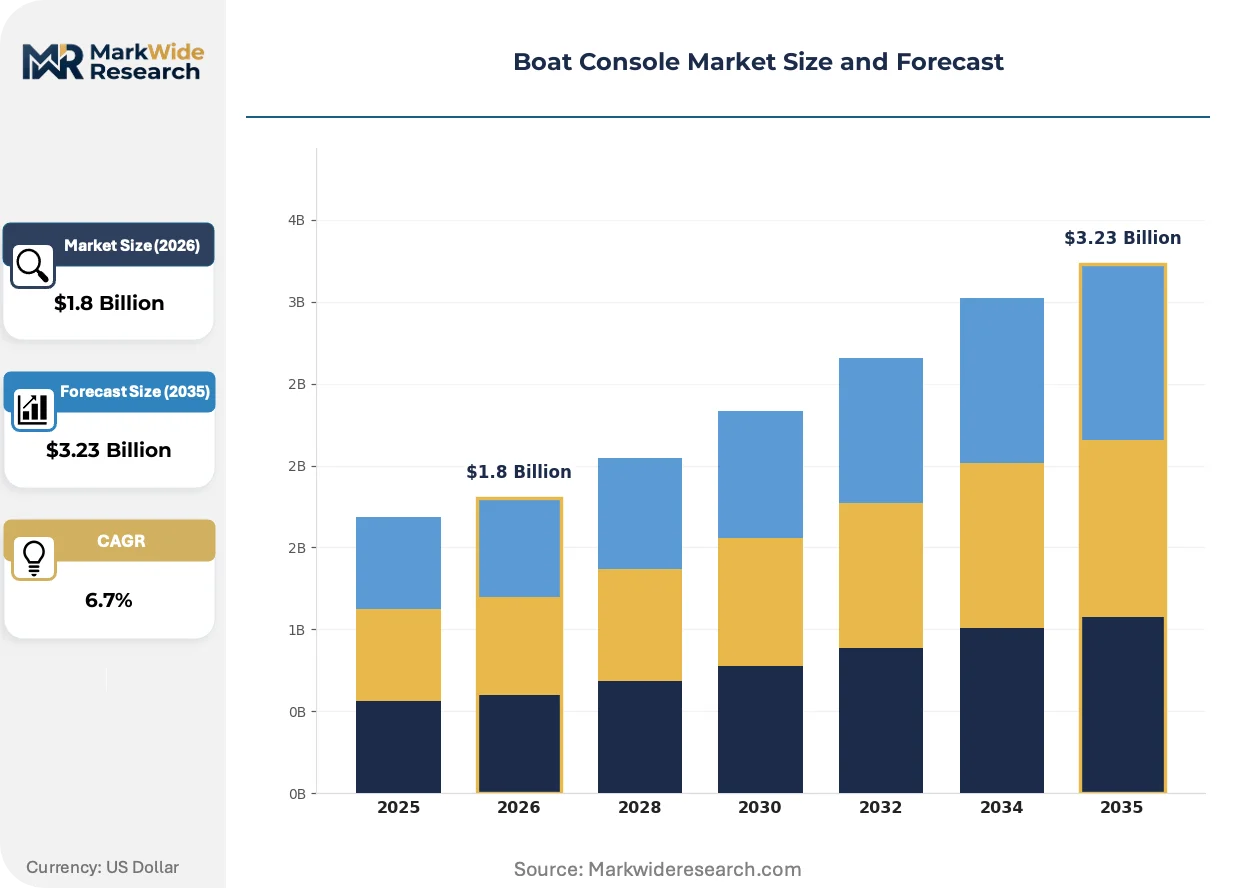
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
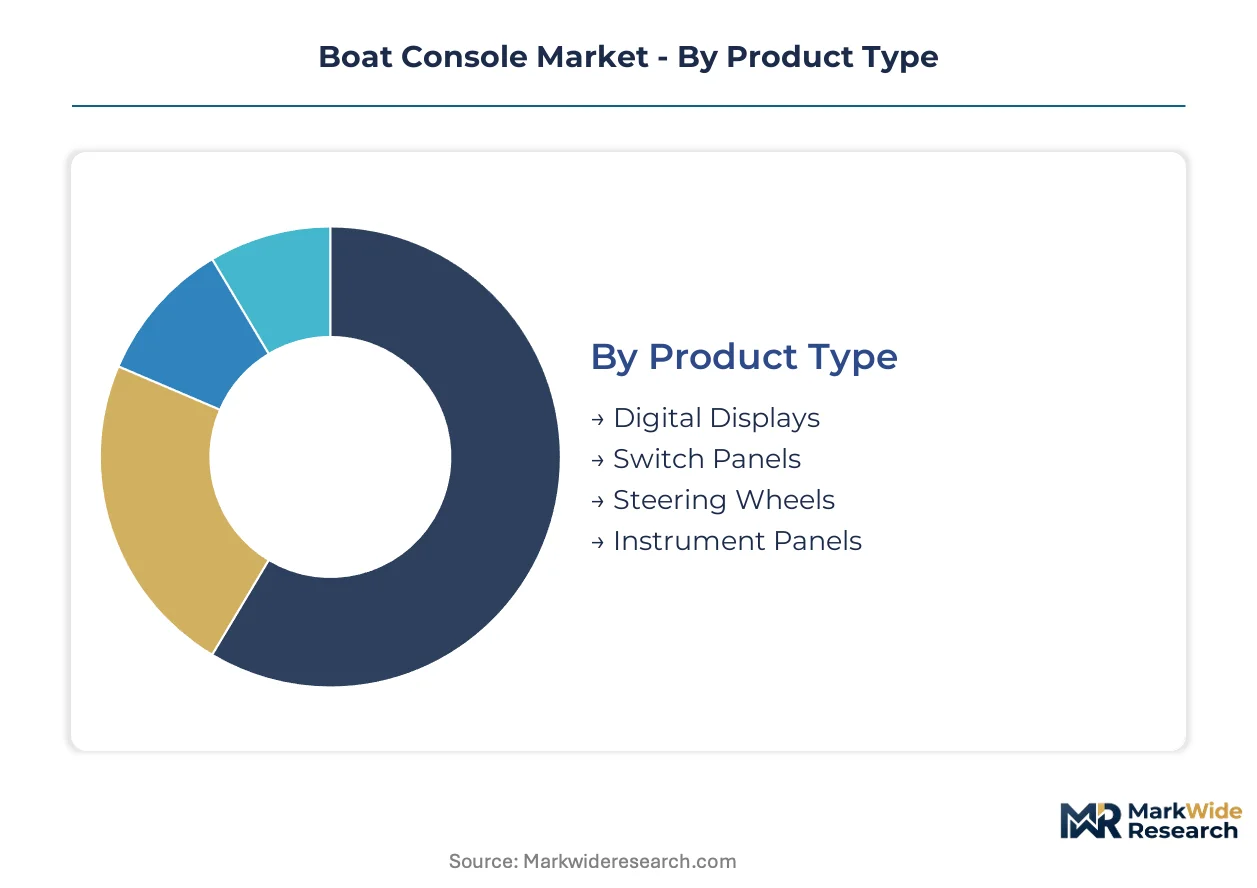
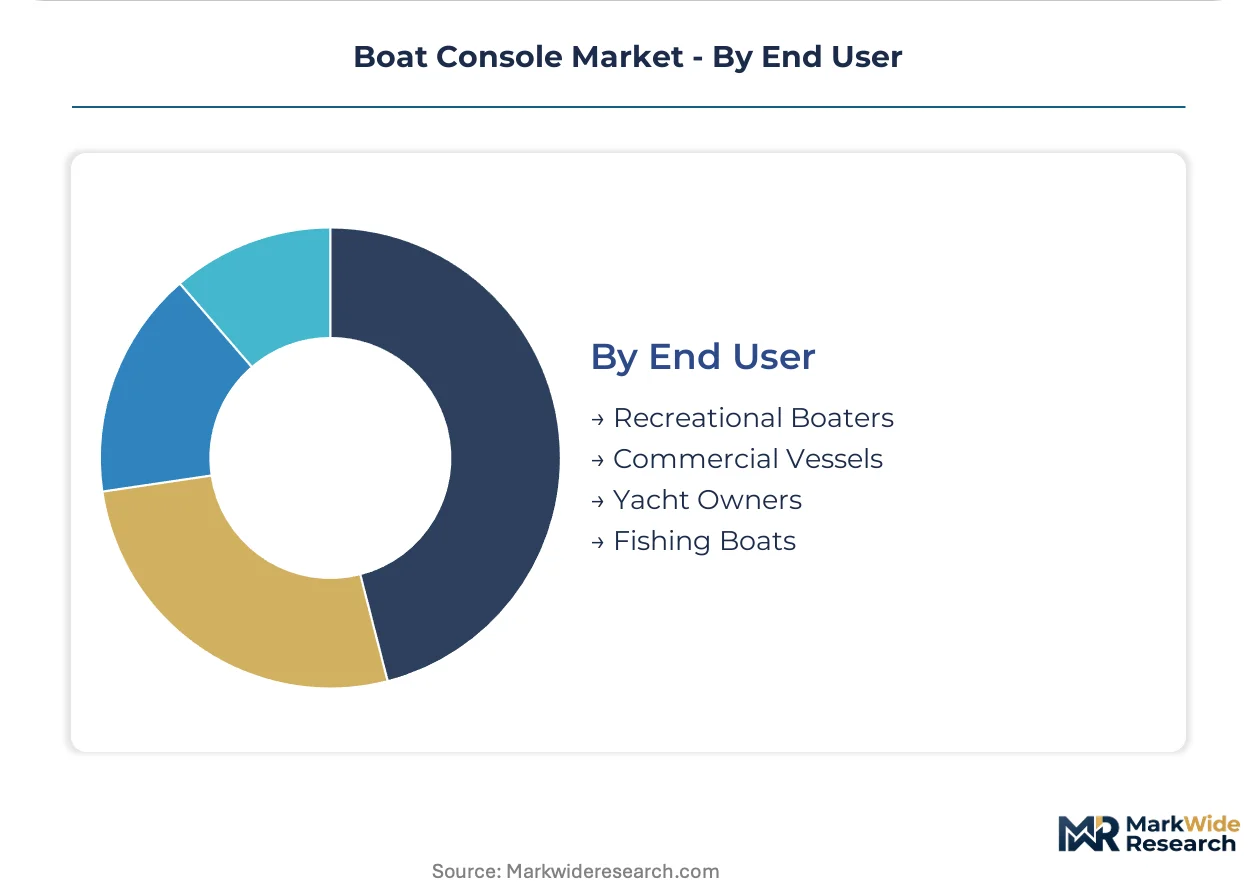
| Segmentation | Product Type: Digital Displays, Switch Panels, Steering Wheels, Instrument Panels Material: Plastic, Aluminum, Fiber Glass, Stainless Steel Size: Small, Medium, Large, Custom End User: Recreational Boaters, Commercial Vessels, Yacht Owners, Fishing Boats |
| Companies Covered | BAHAMA BOAT WORKS, Concept Boats, Invincible Boat Company, Maverick Boat Group, NauticStar Boats, Regulator Marine, Sportsman Boats, White River Marine Group, Yamaha Motor Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boat Console Market Strategic Shifts
Console architecture is pivoting from mechanical switch banks to software-defined helm surfaces, compressing hardware supplier tiers and elevating firmware integration capabilities.
Solid-state switching circuitry is miniaturizing traditional electromechanical relay assemblies into sealed semiconductor packages. Saltwater sportfishing OEMs are adopting these modules at accelerated procurement cycles. Component footprint reduction is miniaturizing console depth profiles, freeing hull interior volume for storage or seating reconfiguration.
The US Coast Guard's updated navigation lighting and ergonomics standards are mandating uniform display sight-line angles and emergency cutoff accessibility. Console fabricators must retool mold patterns to achieve compliance clearance zones. Center-console builders in Florida and Gulf Coast clusters are absorbing the largest certification adaptation costs.
Direct-to-builder specification consulting is displacing distributor-mediated console configuration. Sportfishing and family-cruiser OEMs now engage helm integrators in early hull-design phases, collapsing traditional tiered sales channels. This pattern concentrates most visibly in coastal Southeast boatbuilding corridors where builder concentration enables embedded technical sales presence.
Boat Console Market Segmentation
Console procurement patterns diverge sharply between saltwater sportfishing OEMs and freshwater recreational builders, with material selection and display architecture driving incompatible supplier ecosystems. Segmentation clarity enables targeted platform investments as integrated digital helms displace legacy switch-panel configurations.
Product Type:
Switch Panels face the most acute substitution pressure as touchscreen consolidation eliminates discrete electromechanical components from premium helm designs.
- Digital Displays:Multifunction touchscreen units integrate chartplotting, engine monitoring, and sonar visualization within single glass-panel architectures. Saltwater tournament fishing circuits in Florida and the Gulf Coast drive specification upgrades toward larger format displays with sunlight-readable brightness ratings.
- Switch Panels:Electromechanical breaker and toggle assemblies persist in aftermarket retrofit channels where simpler replacement economics favor independent marine service networks over OEM captive distribution.
- Steering Wheels:Hydraulic and electronic power-assist rim designs incorporate integrated control pods for throttle and trim functions.
- Instrument Panels:Analog gauge clusters retain presence in commercial and price-sensitive freshwater segments where digital migration lags.
Digital Displays retain volume leadership; Switch Panels hold the steepest contraction curve as consolidation accelerates.
Material:
Cost tier differentiation separates saltwater premium builders from commercial freshwater operators, with raw material volatility compressing margins at the mid-market junction.
- Fiber Glass:UV-stabilized polymer composite formulations deliver superior strength-to-weight ratios and moldability into complex integrated console geometries. Coastal Florida OEMs specify fiberglass for center-console sportfishing platforms where salt corrosion resistance and seamless display housing integration justify premium procurement.
- Aluminum:Marine-grade sheet and extrusion fabrications dominate commercial fishing and freshwater utility applications where impact durability outweighs cosmetic refinement. Price volatility in aluminum commodity markets constrains mid-tier console pricing flexibility for Great Lakes and inland river builders.
- Plastic:Injection-molded polymer housings serve entry-level runabout and pontoon segments with standardized console footprints.
- Stainless Steel:Corrosion-resistant hardware and structural reinforcement components anchor high-wear interface points.
Fiber Glass commands the premium tier; Aluminum spans the broadest volume base across commercial applications.
Size:
Application scale determines dimensional requirements, with hull beam width and helm station configuration dictating console footprint limits.
- Large:Integrated helm stations spanning 48-plus inches accommodate triple multifunction displays and companion seating for offshore sportfishing platforms. Tournament-specification center-console builders in coastal Florida and the Gulf Coast concentrate procurement of these architectures.
- Custom:Bespoke mold fabrication enables exact hull integration for limited-production technical poling skiffs and luxury yacht flybridge configurations. Sight-line precision and console weight distribution drive specification in shallow-draft applications where poling platform visibility determines competitive outcomes.
- Small:Compact single-display consoles serve runabout and personal watercraft segments.
- Medium:Standardized footprints dominate production center-console and dual-console families.
Custom configurations capture the highest margin per unit; Large formats drive aggregate revenue concentration.
End User:
Customer type bifurcation is accelerating as recreational boaters displace commercial operators as the primary growth archetype in console procurement.
- Recreational Boaters:Family-oriented day-cruising and watersports enthusiasts demand ergonomics-optimized console layouts with integrated seating and storage. Coastal Southeast retail channels show underpenetrated demand for these configurations as builders shift from fishing-centric to lifestyle-focused helm designs.
- Fishing Boats:Saltwater tournament and recreational angling platforms require rod holder integration, livewell controls, and sonar display mounting at optimized sight-line angles. The US Coast Guard's updated ergonomics standards mandate uniform display accessibility for this segment.
- Commercial Vessels:Workboat and transport operators prioritize durability and standardized replacement part availability over aesthetic integration.
- Yacht Owners:Superyacht and megayacht segments specify bespoke flybridge and lower helm stations with redundant system architectures.
Recreational Boaters are expanding share fastest; Fishing Boats anchor the deepest aftermarket parts demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Recreational boaters in coastal Florida drive the highest premium console attachment rates globally, while commercial operators in freshwater basins prioritize durability over integrated digital architectures. Regional procurement patterns diverge sharply between saltwater sportfishing clusters and inland utility builders.
United States
Coastal Florida boatbuilders scale integrated helm orders to capture high-margin retail demand from tournament fishing circuits. The US Coast Guard enforces updated navigation lighting and ergonomics standards that dictate console layout clearances. Miami-Dade and Fort Lauderdale clusters dominate OEM procurement of large-format multifunction display architectures.
Canada
Great Lakes recreational builders specify aluminum consoles for freshwater durability amid volatile commodity pricing. Transport Canada aligns with ISO 12217 small-craft stability criteria influencing console placement during hull certification. Ontario manufacturing corridors concentrate mid-tier production for price-sensitive runabout segments.
Italy
Luxury yacht flybridge specifications drive demand for bespoke custom console configurations in Mediterranean charter markets. The country's national maritime regulator enforces CE marking compliance for electrical harness routing within console cavities. Lombardy and Veneto industrial districts anchor specialized mold fabrication for limited-production technical platforms.
Australia
Recreational day-boating expansion in Queensland and New South Wales generates demand for family-friendly ergonomics-optimized layouts. The country's national maritime safety authority mandates navigation equipment standards affecting display sight-line requirements. Sydney and Gold Coast boatbuilding clusters concentrate procurement of UV-stabilized polymer composite housings.
Brazil
Coastal sportfishing growth in Rio de Janeiro and São Paulo states stimulates center-console platform development. ANVISA and environmental agencies enforce evaporative emission constraints on fuel tank integration within console designs. São Paulo industrial zones supply standardized console footprints for entry-level runabout segments.
Boat Console Market Competitive Environment
Player mix skews toward vertically integrated boatbuilders with captive console fabrication capabilities, compressing independent supplier margins. The vendor base stratifies across three tiers: premium integrated-helm specialists, mid-market standardized producers, and entry-level polymer molders. Competitive moves concentrate on early-stage hull-design consulting engagements and fiberglass mold retooling for regulatory compliance.
Among US-based fabricators, Maverick Boat Group and Sportsman Boats exemplify contrasting specialization archetypes within the coastal Southeast cluster. Yamaha Motor Corporation anchors the outboard-to-console ecosystem control position across multiple builder accounts. BAHAMA BOAT WORKS and Regulator Marine occupy positions in the premium sportfishing tier where console weight and sight-line precision determine competitive outcomes.
| Leading Market Players |
|---|
| BAHAMA BOAT WORKS |
| Concept Boats |
| Invincible Boat Company |
| Maverick Boat Group |
| NauticStar Boats |
| Regulator Marine |
| Sportsman Boats |
| White River Marine Group |
| Yamaha Motor Corporation |
| Others |
Value Chain & Pricing Dynamics
US Coast Guard updated ergonomics standards gate both supplier qualification and price differentiation simultaneously, as console fabricators must retool mold patterns for compliance clearance zones before accessing premium integrated-helm procurement channels. Saltwater sportfishing OEMs in coastal Florida absorb the largest certification adaptation costs, compressing margins for non-compliant suppliers while elevating pricing power for certified integrated-helm specialists.
Pricing Analysis
Prior-generation electromechanical switch panels trade at steep discounts to current-generation multifunction touchscreen architectures, while next-generation software-defined helm surfaces command project-based engineering premiums. Three-tier pricing structure across premium, standard, and economy levels separates fiberglass integrated designs from aluminum commercial fabrications and injection-molded polymer entry units. Cost compression in mid-tier aluminum consoles is intensifying because commodity sheet volatility constrains pricing flexibility for Great Lakes builders. Freshwater recreational operators exhibit highest price sensitivity; saltwater tournament fishing circuits demonstrate lowest sensitivity due to specification-driven procurement.
Supply Chain Analysis
China and South Korea anchor multifunction display manufacturing, while coastal Florida and Gulf Coast clusters concentrate fiberglass mold fabrication and final console assembly. Raw material flows draw from UV-stabilized polymer composite suppliers, marine-grade aluminum sheet producers, and semiconductor packaging foundries. Single-source vulnerability in East Asian display manufacturing exposes OEMs to concentrated supply disruption risk. Distribution runs through direct-to-builder specification consulting that collapses traditional tiered sales channels in coastal Southeast corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Battery-electric propulsion architectures are disrupting console thermal management and wire gauge requirements, creating first-mover engineering service opportunities across the forecast window.
For Market Incumbents: Fortify integrated-helm ecosystem control through backward integration into multifunction display firmware development and captive mold fabrication capacity in coastal Florida clusters. ISO 12217 certification investment serves as the priority defensive lever against iterative hull-design timeline extensions that freeze platform commitments. Aluminum price volatility threatens mid-tier margin structures; channel control through embedded technical sales presence reduces substitution risk. For New Entrants and Emerging Players: Anchor in aftermarket switch-panel retrofit channels where simpler replacement economics favor independent marine service networks over OEM captive distribution in coastal maintenance corridors. Family-friendly ergonomics-optimized layouts for recreational day-boaters represent the most penetrable white space in coastal Southeast retail channels. Direct specification consulting with early-stage hull designers enables bypass of established tiered distribution. For Investors and Strategic Acquirers: EPA Clean Air Act evaporative emission compliance milestones reshape the acquisition landscape toward certified integrated-design engineering services with fuel tank venting expertise. Long-term viability across the analysis window favors targets with demonstrated console cavity thermal management capabilities for electric propulsion transitions. Monitor battery-electric platform commitments from major outboard manufacturers as the critical inflection signal for console wire gauge and cooling integration demand.| Strategic Initiative | Industry Significance |
|---|---|
| Fiberglass Mold Retooling for Compliance | US Coast Guard ergonomics standards mandate clearance zone adaptations that determine premium tier access. |
| Integrated Display Firmware Development | Software-defined helm surfaces compress hardware supplier tiers and elevate ecosystem control for OEMs. |
| Electric Propulsion Thermal Engineering | Battery architectures require redesigned wire gauge and cooling integration, opening white space for specialists. |
| Direct-to-Builder Technical Sales Embedding | Early hull-design phase engagement collapses traditional distributor-mediated configuration channels. |
| Aftermarket Switch-Panel Channel Development | Independent marine service networks in coastal corridors bypass OEM captive distribution for retrofits. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with boatbuilder procurement directors, console fabrication plant managers, marine electronics integration specialists, and coastal dealership service heads. Secondary validation drew from US Coast Guard regulatory filings, EPA Clean Air Act enforcement databases, ISO 12217 certification records, and customs trade data for fiberglass composite and aluminum sheet imports. Bottom-up console procurement modeling and top-down recreational marine equipment market sizing were triangulated to reconcile volume estimates.
Across the analysis window, forecasts segment by product type, material grade, hull size category, and end-user archetype to capture divergent procurement patterns between saltwater sportfishing and freshwater recreational builders. CAGRs were derived from fitted growth curves anchored to OEM platform commitment timelines and regulatory compliance phase-in schedules. Electric propulsion architecture adoption curves and multifunction display consolidation rates served as key industry-specific forecast inputs.
Underlying assumptions cover stable aluminum commodity pricing, uninterrupted East Asian display supply, and gradual EPA enforcement intensity, with deviation risk concentrated in tariff exposure and semiconductor logistics chokepoints. Recalibration cycles align with material shifts in battery-electric platform announcements and US Coast Guard regulatory update schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Marine
Ballast Water Management Market
Marine
Hydraulic Marine Cranes Market
Marine
Marine Fasteners Market
Marine
Autonomous Underwater Vehicle (AUV) Market
Marine
Marine Lighting Market
Marine
Marine Turbocharger Market
Marine
Yacht Painting and Maintenance Market
Marine
Sailboat Propellers Market
Marine
Boat Hook Market
Marine
Marine Chartplotter Market
Marine
Asia-Pacific Electric Boat Market
Marine
Electric Boat and Ship Market
Marine
Marine Glass Market
Marine
Fishing Vessel Market
Marine
Marine Interiors Market
Marine
Marine Filter Market