
 Automotive Sound Proofing Material Market | 2026-2036
Automotive Sound Proofing Material Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Sound Proofing Material Market Outlook
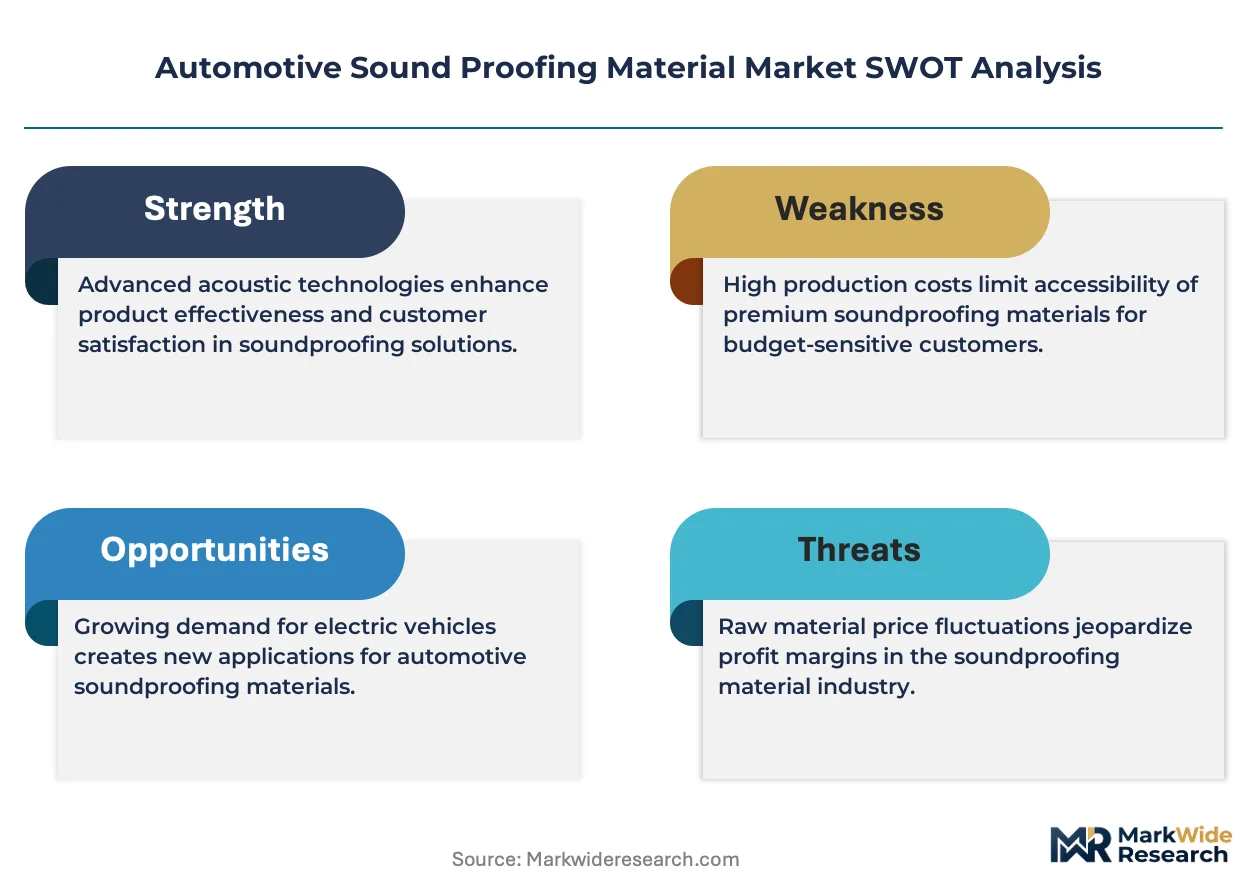
Project finance tied to dedicated EV platform programs is reshaping which suppliers can secure long-term contracts. Autoneum Holding AG leverages its integrated acoustic and thermal management portfolio to anchor major European OEM programs. Freudenberg Performance Materials sustains R&D intensity in lightweight nonwoven technologies that reduce mass while maintaining sound absorption coefficients. 3M differentiates through adhesive-backed damping sheets that simplify assembly-line installation for vehicle assemblers.
Automotive sound proofing materials encompass engineered substrates—typically foams, rubber compounds, or fiber-reinforced composites with densities between 80 and 200 kg/m³—designed to attenuate airborne and structure-borne noise within vehicle cabins. These materials function through porous absorption, mass-damping, or barrier-layer mechanisms to meet OEM targets of 35-40 dB interior sound pressure levels at highway speeds. Foam dominates material type volumes due to its versatility across door panels and roof liners, though mass loaded vinyl commands margin premiums in luxury segments where maximum low-frequency attenuation is specified. Engine compartment applications represent the fastest-growing installation site as thermal-acoustic combination shields replace discrete components under tightening hood-line packaging constraints.
The U.S. NHTSA's pedestrian safety alerts and the EU's F-Gas Regulation on blowing agents are pushing suppliers toward water-blown foam chemistries and bio-based feedstocks. China's MIIT fuel consumption standards indirectly drive demand by rewarding every kilogram of weight reduction that acoustic materials can deliver without performance sacrifice. Stakeholders must monitor how REACH's expanding substance restrictions and state-level U.S. VOC rules will redefine material qualification timelines and supplier certification costs.
Market Dynamics
Electric vehicle platform architectures are fundamentally recalibrating acoustic engineering priorities as propulsion noise signatures shift from combustion frequencies to aerodynamic and tire-generated frequencies.
Growth Catalysts
- China MIIT fuel consumption standards:Weight reduction mandates incentivize OEMs to specify lightweight foam composites that maintain absorption coefficients below 150 kg/m³ density thresholds.
- Wind and road noise prominence:EV drivetrain silence elevates cabin acoustic targets to 35 dB at highway speeds, expanding material surface area per vehicle by 15-20% versus internal combustion equivalents.
- Bio-based feedstock development:Polyol suppliers are commercializing castor oil and soybean-derived foam chemistries that satisfy REACH substance restrictions while preserving acoustic performance metrics.
Market Restraints
- Petrochemical input volatility:Polyurethane foam production depends on isocyanate and polyol pricing tied to crude oil derivatives, compressing supplier margins during energy price spikes.
- REACH authorization timelines:ECHA's expanding SVHC candidate list extends material qualification cycles to 18-24 months, freezing formulation changes mid-program.
- Mass-loaded vinyl substitution ceiling:Luxury segment demand for maximum low-frequency damping sustains PVC-based barriers despite sustainability pressures, limiting bio-alternative penetration.
Strategic Opportunities
- India PLI scheme for automotive:Domestic EV manufacturing incentives create localized acoustic material demand as Tata Motors and Mahindra expand premium electric portfolios.
- Thermal-acoustic convergence:Engine compartment shields integrating heat reflection with noise attenuation displace discrete components, doubling material value per installation site.
- Water-blown foam chemistry:F-Gas Regulation phase-down of HFC blowing agents positions CO₂ and water-based processes as compliance-compliant alternatives for European supply contracts.
Industry Challenges
- Acoustic-thermal simulation talent scarcity:OEM engineering teams lack sufficient CAE specialists capable of modeling multi-physics material behavior during pre-development phases.
- Cross-functional certification complexity:Suppliers must simultaneously satisfy NHTSA flammability, EPA VOC, and OEM-specific odor tests, extending validation timelines.
- Legacy platform retrofit friction:ICE-derived vehicle architectures impose packaging constraints that prevent optimal acoustic material placement without structural redesign.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Sound Proofing Material Market |
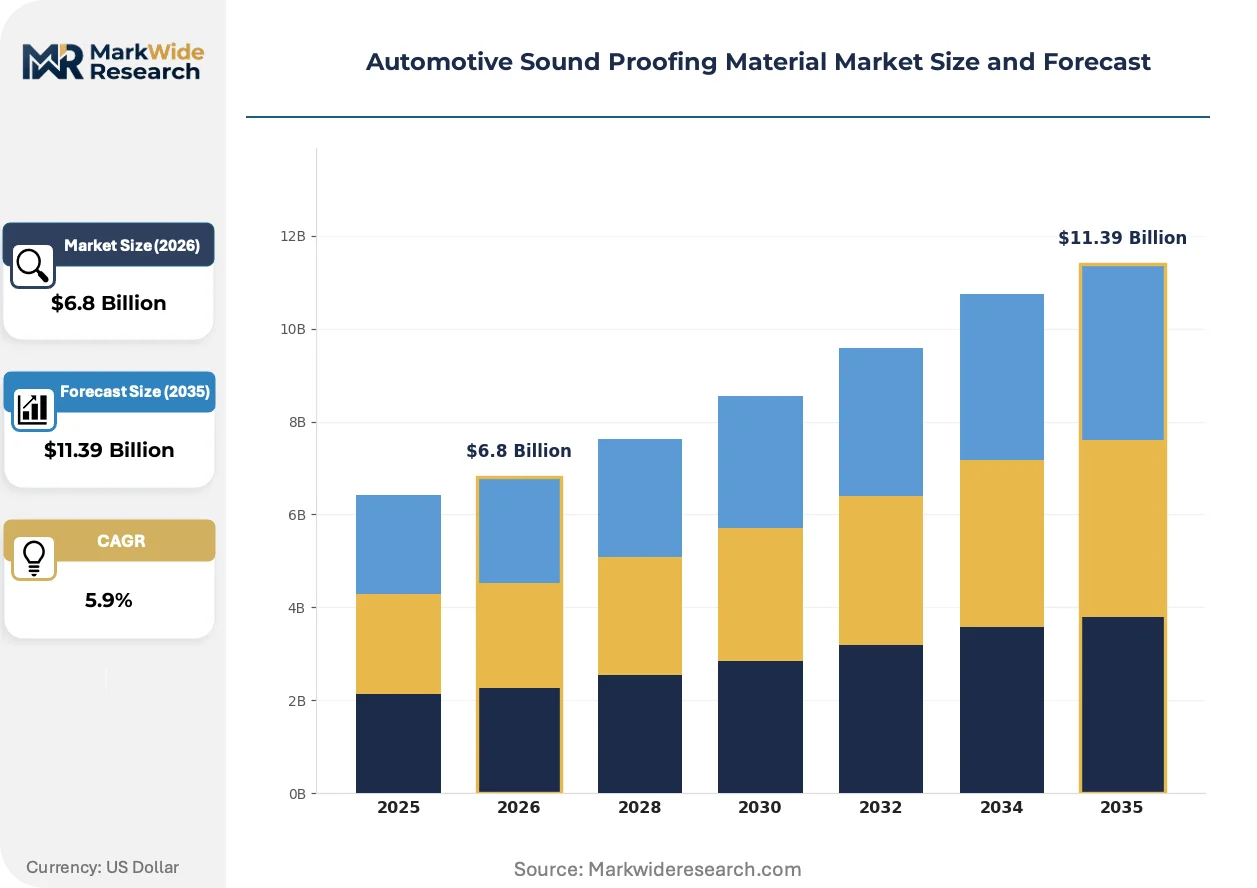
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.39 Billion |
| CAGR (2026 – 2036) | 5.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Foam, Mass Loaded Vinyl, Rubber, Fiberglass Application: Door Panels, Roof Liners, Floors, Engine Compartment End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Installation Method: Adhesive, Stapling, Mechanical Fastening, Injection Molding |
| Companies Covered | Autoneum Holding AG, Grupo Antolin, Auria Solutions, FORVIA, Adler Pelzer Group, Freudenberg Performance Materials, BASF, 3M, Armacell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Sound Proofing Material Market Strategic Shifts
Computational acoustic engineering is compressing development cycles while regulatory chemistry restrictions are forcing feedstock substitutions across major supply contracts.
Active noise cancellation hardware is digitizing material specification processes by enabling software-based frequency suppression that reduces physical insulation mass requirements. Tier-1 suppliers now integrate microphone arrays and counter-phase speakers alongside traditional foam layers. German and Korean OEMs are deploying this hybrid approach on flagship EV platforms, shrinking barrier material thickness by 30% without degrading cabin quietness targets.
EU F-Gas Regulation restrictions on hydrofluorocarbon blowing agents are mandating process chemistry overhauls across polyurethane foam supply chains. Water-blown and liquid CO₂ technologies require capital-intensive reactor modifications at manufacturing plants. European foam producers are absorbing these retrofit costs to maintain access to Volkswagen Group and Stellantis platform awards, while Asian competitors face export compliance barriers.
Fleet procurement centralization among ride-hailing operators is consolidating acoustic material specifications across high-mileage vehicle categories. Uber and Lyft vehicle supply programs in North American metropolitan markets now mandate standardized cabin noise thresholds that exceed retail consumer expectations. This specification elevation compresses supplier diversity as fleet managers prioritize single-source acoustic system integrators capable of warranty coverage across 300,000-mile duty cycles.
Automotive Sound Proofing Material Market Segmentation
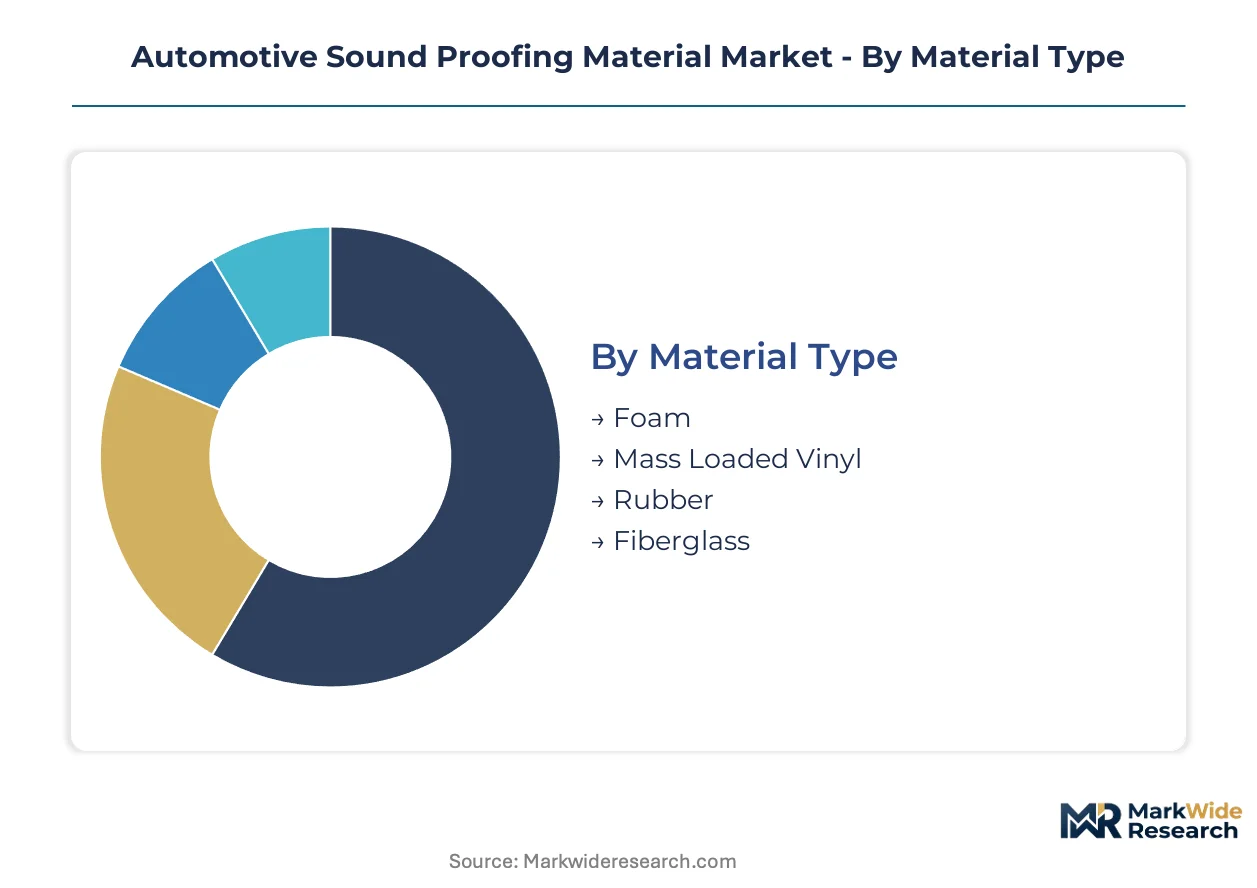
Acoustic material specifications diverge sharply across vehicle programs based on noise frequency targets, thermal load exposure, and assembly-line integration constraints. Segment-level procurement strategies determine which suppliers capture platform-level contracts versus component spot orders.
Material Type:
Polyurethane foam formulations turn over fastest as blowing agent regulations force chemistry pivots, while mass-loaded vinyl specifications remain locked for multi-year luxury platform cycles.
- Foam:Open-cell polyurethane structures with densities of 80-150 kg/m³ dominate door panel and headliner volumes. China's domestic EV brands specify lightweight foam composites to satisfy MIIT fuel consumption weight reduction mandates while maintaining 35 dB cabin targets.
- Mass Loaded Vinyl:Flexible PVC-barrier laminates with surface densities of 3-8 kg/m² deliver maximum low-frequency attenuation in luxury floor pan applications. REACH SVHC restrictions on plasticizer chemistries extend European qualification timelines to 18-24 months, freezing formulation changes mid-program.
- Rubber:EPDM and nitrile compounds provide compression-set resistance for engine compartment gaskets and isolation mounts. Thermal-acoustic combination shields displace discrete rubber components under hood-line packaging constraints.
- Fiberglass:Glass fiber nonwovens with thermoset binders serve high-temperature exhaust heat shield applications where foam degradation risks exceed acoustic benefits.
Foam dominates installed base. Mass loaded vinyl is where expansion concentrates in premium EV cabin architectures.
Application:
Cost tier stratification separates high-margin thermal-acoustic engine solutions from commodity door and roof treatments.
- Door Panels:Multi-layer foam-film laminates with integrated vapor barriers address water ingress and noise transmission simultaneously. European OEMs specify adhesive-backed configurations to reduce assembly-line fastening labor.
- Roof Liners:Headliner substrates combining PET nonwoven facings with polyurethane cores absorb broadband frequencies while supporting overhead console mounting loads.
- Floors:Mass-loaded vinyl barrier layers atop foam decouplers target tire noise frequencies below 500 Hz. Fleet procurement centralization among ride-hailing operators elevates floor acoustic specifications beyond retail consumer thresholds.
- Engine Compartment:Aluminum-faced foam composites with heat-reflective surfaces integrate thermal management with noise attenuation. This application is climbing the fastest as thermal-acoustic convergence doubles material value per installation site.
Door panels anchor current specification volumes. Engine compartment applications are where technology premiums concentrate.
End User:
Customer type determines contract duration, with OEM platform programs spanning 5-7 years versus aftermarket spot purchasing.
- OEMs:Vehicle manufacturers specify system-level acoustic performance targets, delegating material selection to Tier-1 integrators. Active noise cancellation hardware deployment on German and Korean flagship EV platforms reduces physical insulation mass requirements by 30%.
- Aftermarket Providers:Independent distributors serve collision repair and customization channels with cut-to-shape foam and barrier sheets. VOC compliance varies by U.S. state, fragmenting product lines.
- Tier-1 Suppliers:Autoneum and Freudenberg anchor major platform awards through integrated acoustic-thermal portfolios. Water-blown foam chemistry investments maintain European supply contract access under F-Gas Regulation phase-down timelines.
- Vehicle Assemblers:Contract manufacturers for emerging EV brands source pre-kitted acoustic modules to minimize in-house material handling.
Tier-1 suppliers dominate contract value. Aftermarket providers are where channel fragmentation concentrates.
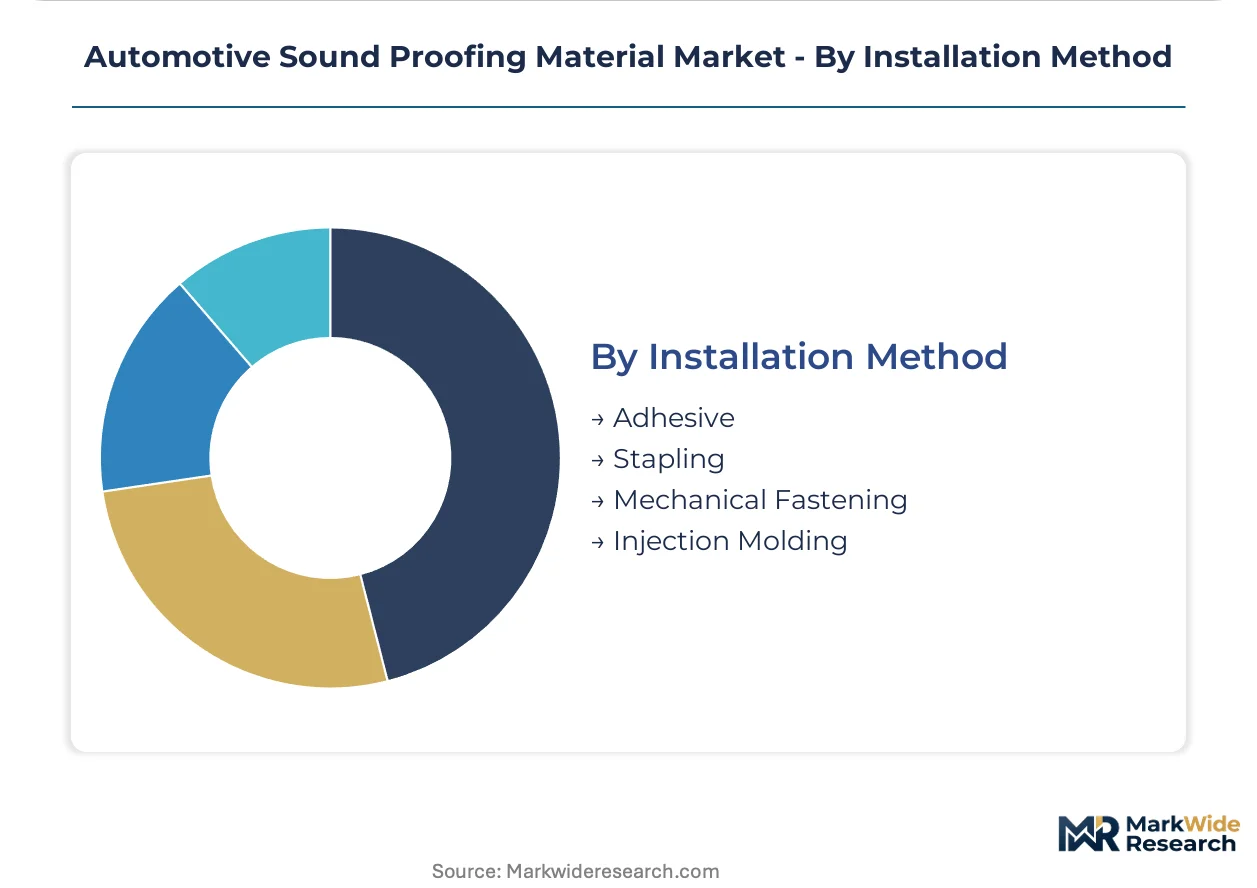
Installation Method:
Assembly automation compatibility separates high-volume adhesive and injection processes from labor-intensive mechanical fastening.
- Adhesive:Pressure-sensitive and heat-activated bonding systems enable robotic placement on body-in-white structures. 3M differentiates through adhesive-backed damping sheets that simplify OEM assembly-line installation.
- Stapling:Mechanical attachment of fabric-wrapped foam to metal stampings persists in low-volume truck and commercial vehicle programs.
- Mechanical Fastening:Clip and push-pin retention of pre-formed acoustic modules supports serviceability requirements in heavy-duty applications.
- Injection Molding:In-situ foam generation within cavity spaces delivers complex geometries without secondary assembly steps. Capital-intensive reactor modifications for water-blown chemistries favor integrated Tier-1 producers.
Adhesive methods dominate new platform specifications. Injection molding is where process technology premiums concentrate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for acoustic materials track closely with EV production localization. China runs a structural surplus in foam composites while European manufacturers import mass-loaded vinyl barriers from Asian suppliers to meet luxury platform deadlines.
China
Domestic EV brands NIO, XPeng, and Li Auto specify premium cabin quietness as a differentiation vector against Tesla and European incumbents. MIIT fuel consumption standards reward every kilogram of acoustic weight reduction, accelerating specification of sub-150 kg/m³ foam densities. Manufacturing clusters in Shanghai, Guangzhou, and Hefei anchor supply chain concentration for BYD and CATL-affiliated vehicle programs.
Germany
Volkswagen Group, BMW, and Mercedes-Benz platform architectures demand integrated acoustic-thermal management systems for electric drivetrains. ECHA's REACH SVHC candidate list extends material qualification cycles to 18-24 months, freezing mid-program formulation changes. Stuttgart and Munich engineering centers coordinate Tier-1 supplier selection for EU F-Gas Regulation compliance on blowing agent chemistries.
United States
Ford and General Motors EV platform investments in Michigan and Tennessee reshape acoustic material procurement toward adhesive-backed damping systems. NHTSA pedestrian safety alerts for quiet EVs intersect with EPA volatile organic compound limits on interior materials. Detroit-area assembly plants source foam composites from domestic suppliers to minimize cross-border logistics exposure.
India
Tata Motors and Mahindra expansion into premium electric portfolios generates localized acoustic material demand under the PLI scheme for automotive manufacturing. Domestic foam production capacity lags specification complexity, creating import dependency for multi-layer barrier composites. Chennai and Pune industrial corridors concentrate emerging EV supply chain investments from Korean and Japanese component suppliers.
South Korea
Hyundai Motor Group and Kia EV platform programs specify active noise cancellation hardware alongside traditional insulation, reducing physical material mass requirements by approximately 30%. MFDS chemical substance regulations align with REACH restrictions, favoring suppliers with dual-certification capabilities. Busan-Ulsan manufacturing complexes integrate acoustic module production with battery pack assembly lines.
Automotive Sound Proofing Material Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in material supply. The market structures around three to five dominant Tier-1 suppliers anchoring multi-year OEM contracts, with mid-scale chemical producers and regional fabricators occupying formulation and conversion niches. Competitive positioning splits between integrated acoustic-thermal portfolio holders and pure-play damping material suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves, as water-blown foam chemistry investments and thermal-acoustic convergence capabilities determine contract access.
Among Swiss and German-anchored platform integrators, Autoneum Holding AG exemplifies the integrated portfolio archetype spanning acoustic and thermal management. Freudenberg Performance Materials occupies a position among nonwoven technology specialists with lightweight fiber-reinforced capabilities. 3M represents the adhesive and materials science tier, leveraging damping sheet technologies to simplify OEM assembly processes. These three anchors illustrate how geographic origin and corporate structure correlate with strategic positioning across system-level and component supply tiers.
| Leading Market Players |
|---|
| Autoneum Holding AG |
| Grupo Antolin |
| Auria Solutions |
| FORVIA |
| Adler Pelzer Group |
| Freudenberg Performance Materials |
| BASF |
| 3M |
| Armacell International |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in Chinese polyurethane foam production is compressing spot pricing for standard-density materials while simultaneously accelerating supplier consolidation around water-blown chemistry capabilities. This utilization imbalance grants price leverage to OEM procurement teams specifying sub-150 kg/m³ foam densities for EV weight reduction targets.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that lock in volume commitments across 5-7 year platform cycles. Price differentiation stems from certification tier under REACH SVHC restrictions and geographic delivery cost to assembly plants. Cost compression in commodity foam grades is intensifying because European F-Gas Regulation compliance requires capital-intensive reactor retrofits. Fleet procurement managers at ride-hailing operators exhibit lowest price sensitivity due to warranty coverage requirements across 300,000-mile duty cycles.
Supply Chain Analysis
Upstream isocyanate and polyol feedstock production concentrates in China, Germany, and the United States, with BASF and Covestro anchoring European supply. Raw material sourcing draws from crude oil derivatives, castor oil bio-feedstocks, and recycled PET streams. Single-source vulnerability persists around specialized blowing agent chemistries facing regulatory phase-down. Distribution runs through Tier-1 system integrators that pre-kit acoustic modules for just-in-sequence delivery to vehicle assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment around REACH SVHC certification timelines creates switching costs that freeze incumbent supplier relationships across multi-year OEM programs.
For Market Incumbents: Build certification moats by accelerating ECHA pre-registration for next-generation bio-based polyol formulations ahead of authorization timeline extensions. Anchor capacity addition in Czech and Polish industrial corridors to service Volkswagen Group and Stellantis platform awards while absorbing water-blown chemistry retrofit costs that smaller competitors cannot finance. Lock in exclusive thermal-acoustic combination shield development contracts with German OEM engineering centers to preempt substitute technology displacement from active noise cancellation hardware deployment. For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme-supported EV manufacturing corridor where domestic foam production capacity lags specification complexity for Tata Motors and Mahindra premium electric portfolios. Target aftermarket collision repair channels with cut-to-shape barrier composites that bypass OEM certification bottlenecks. Pursue co-development partnerships with Korean battery pack integrators seeking acoustic-thermal management modules for Busan-Ulsan manufacturing complexes. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across water-blown foam chemistry manufacturing as European F-Gas Regulation compliance mandates reactor retrofit investments exceeding mid-scale producer balance sheet capacity. Five-to-ten year viability favors integrated acoustic-thermal portfolio holders with existing OEM platform relationships over pure-play damping material suppliers. Acquisition target archetype: regional foam converters with REACH dual-certification capabilities and established logistics contracts to German engineering centers. Monitor ECHA SVHC candidate list expansion velocity as inflection signal for qualification timeline extension severity.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Blown Chemistry Retrofit | European foam producers absorb reactor modification costs to maintain Volkswagen Group contract access under F-Gas Regulation timelines. |
| Thermal-Acoustic Convergence R&D | Integrated shield development doubles material value per engine compartment installation site for Tier-1 suppliers. |
| Bio-Based Feedstock Partnership | Castor oil and soybean-derived polyol supply agreements satisfy REACH substance restrictions while preserving acoustic performance coefficients. |
| India PLI Localization | Domestic manufacturing investments capture Tata Motors and Mahindra EV platform specifications under automotive production incentives. |
| Active Noise Cancellation Integration | Hybrid hardware-software systems deployed by Hyundai Motor Group reduce physical insulation mass requirements by approximately 30%. |
Study Parameters
A standing panel of Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distribution channel managers, and acoustic R&D technical directors provided ongoing calibration against secondary validation sources. Primary fieldwork combined structured interviews with customs and trade data, SEC 10-K filings from listed chemical producers, IHS Markit vehicle production databases, and ECHA REACH registration dossiers. Bottom-up segmentation modeling triangulated against top-down market sizing derived from OEM acoustic content-per-vehicle estimates across the analysis window.
Scenario-bracketing around regulatory authorization timelines and EV adoption velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled encompass material type, installation site, propulsion architecture, and regional production cluster. CAGRs were derived from curve-fitting against historical content-per-vehicle trajectories and OEM acoustic insulation budget disclosures. Industry-specific forecast inputs included MIIT fuel consumption standard weight reduction mandates and ECHA SVHC candidate list expansion schedules.
Stress conditions across petrochemical input volatility, REACH authorization delays, and active noise cancellation hardware penetration rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding OEM platform cycle timing and thermal-acoustic convergence adoption curves. Cross-checking against IHS Markit vehicle registration data and Tier-1 supplier order backlog disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Global Automotive Interiors Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Automotive Glove Compartment Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Auto Glass Encapsulation Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Global Luxury Car Coachbuilding Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market
Automotive Interior & Exterior
Automotive Seat Covers Market
Automotive Interior & Exterior
Reflective Air Bags Market
Automotive Interior & Exterior
Automotive Inside Rearview Mirrors (IRVM) Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Laser Lighting Market
Automotive Interior & Exterior
Railway Interior Lighting Market
Automotive Interior & Exterior
Automotive Heaters Market
Automotive Interior & Exterior
Global Headliner (OE) Market