
 Asia Pacific Automotive Interiors Market | 2026-2036
Asia Pacific Automotive Interiors Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Automotive Interiors Market Outlook
Aftermarket service revenue is narrowing as OEMs extend warranty-backed interior refurbishment programs and captive parts distribution. Toyota Boshoku Corporation anchors its position through deep integration with Toyota Motor's regional assembly footprint. Hyundai Mobis Co Limited leverages captive supply relationships with Hyundai-Kia Automotive Group to dominate Korean and Indian OEM channels. Lear Corporation competes on seating technology leadership, particularly in powered and climate-controlled seat architectures across Japanese and Chinese premium vehicle programs.
Asia Pacific automotive interiors encompass the complete cabin environment including seats, dashboard assemblies, door panels, and interior trim, manufactured through processes such as injection molding of thermoplastic polyolefins, polyurethane foam casting for cushioning, and vacuum-formed vinyl or leather surfacing, serving to provide occupant comfort, safety integration, and brand differentiation for vehicle manufacturers. Leather and vinyl material categories command premium margin pools in SUV and sedan segments where OEMs specify graded surface finishes and stitched detailing, while fabric maintains volume dominance in hatchback applications across India and Southeast Asia where cost positioning governs procurement decisions. Seating as a product component concentrates the largest value share given its structural complexity, embedded electronics, and direct ergonomic impact on consumer satisfaction scores.
China's GB standards for interior air quality and volatile organic compound emissions, administered by SAMR, compel material suppliers to reformulate adhesives and foam substrates. India's BIS certification requirements for seat strength and flammability resistance reshape Tier-1 supplier qualification timelines. Japan's METI energy efficiency guidelines for vehicle weight reduction indirectly pressure interior component mass optimization. Stakeholders must monitor regulatory divergence between China's mandatory VOC testing and India's emerging passenger safety standards to align regional product development roadmaps.
Market Dynamics
Electric vehicle OEMs across China and Southeast Asia are forcing a fundamental reconfiguration of interior supply chains, as premium cabin specifications displace the cost-minimized architectures that dominated internal combustion vehicle programs.
Growth Catalysts
- GB Standard 27630 VOC Limits:China's SAMR-mandated interior air quality testing is accelerating material reformulation investments among foam and adhesive suppliers serving Yangtze River Delta assembly plants.
- Powered Seat Electrification:Climate-controlled and massage-enabled seating architectures are penetrating mid-tier SUV segments in China and India, expanding addressable component value per vehicle.
- Co-location Clustering:Dashboard and seating suppliers are consolidating operations within 50 kilometers of Toyota, BYD, and Hyundai-Kia assembly facilities in Tianjin, Guangzhou, and Chennai.
Market Restraints
- Polyurethane Feedstock Volatility:TDI and MDI pricing fluctuations compress foam cushioning margins for seating suppliers locked into annual OEM supply agreements.
- Single-Source Leather Finishing:Premium grain hide processing concentrates among Italian and Korean tanners, exposing dashboard and seat cover suppliers to extended lead times and currency risk.
- Legacy Tooling Amortization:Injection mold investments for thermoplastic polyolefin interior panels carry 5-7 year depreciation cycles that resist rapid design refresh rates demanded by EV programs.
Strategic Opportunities
- India PLI Scheme for Auto Components:Component-level production incentives are attracting seating frame and mechanism suppliers to establish dedicated facilities in Gujarat and Tamil Nadu.
- Biobased Polyurethane Foams:Castor oil-derived polyols are converging with conventional petrochemical formulations to meet OEM sustainability scorecard requirements without sacrificing compression set performance.
- Direct-to-OEM Digital Sampling:Virtual reality material libraries are compressing design validation cycles, enabling Tier-2 textile and trim suppliers to bypass traditional Tier-1 design houses.
Industry Challenges
- Cross-Border Certification Parallelism:Suppliers must simultaneously navigate China's CQC mark, India's BIS Type Approval, and Thailand's TISI requirements for identical seat belt anchor and head restraint designs.
- Embedded Software Integration:Climate seat control modules require functional safety validation to OEM-specific cybersecurity standards, extending development timelines for mechanical-focused suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Automotive Interiors Market |
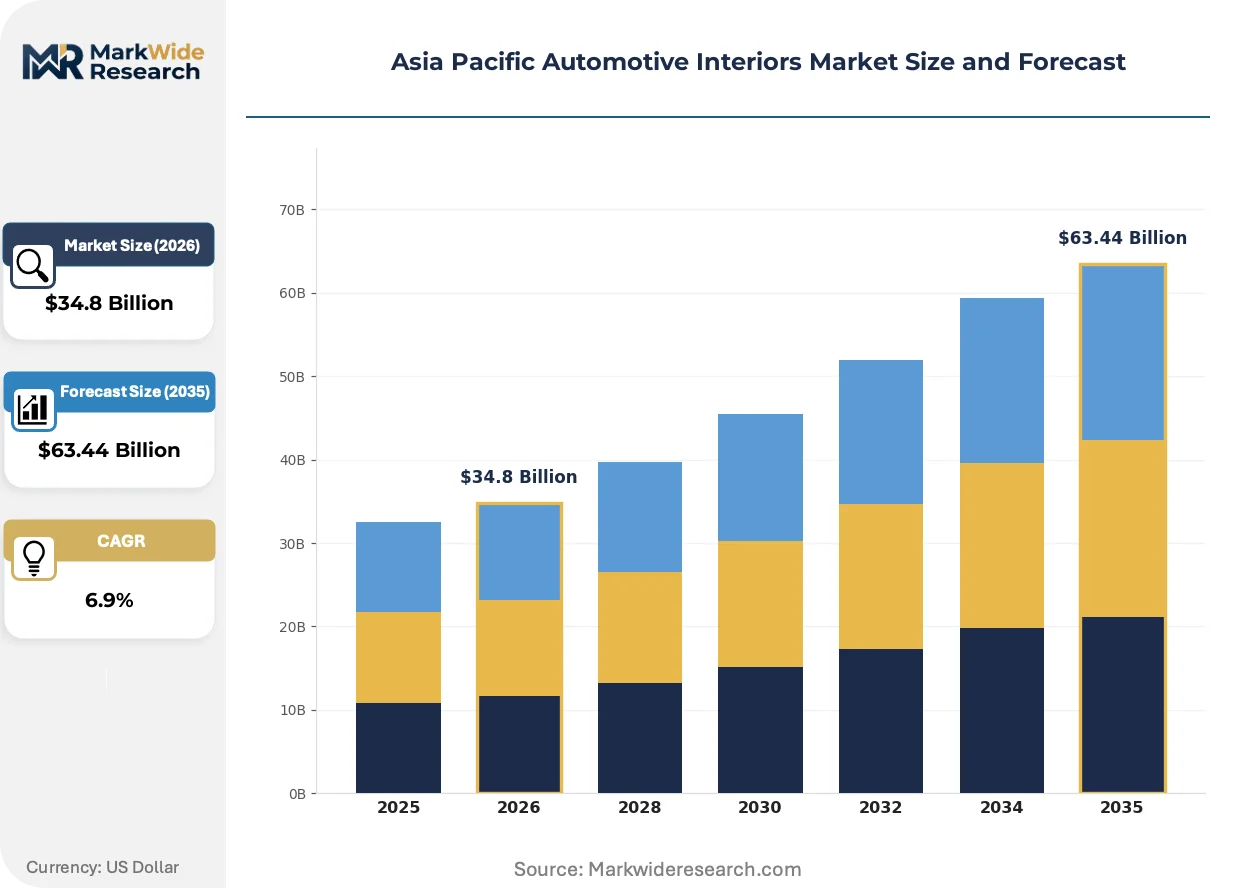
| Market Size in 2026 | $34.8 Billion |
| Market Size in 2035 | $63.44 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Leather, Fabric, Vinyl, Wood Product Component: Seats, Dashboard, Door Panels, Interior Trim Vehicle Type: SUV, Sedan, Hatchback, Coupe End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships |
| Companies Covered | Hyundai Mobis Co Limited, Toyota Boshoku Corporation, Panasonic Corporation, Continental AG, Calsonic Kansei Corporation, Tachi-S Company Ltd, Lear Corporation, Magna International Inc, Toyoda Gosei Co Ltd, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Automotive Interiors Market Strategic Shifts
Material science convergence and regulatory emissions testing are actively restructuring how interior components are specified, sourced, and validated across Asia Pacific vehicle programs.
Alcantara and microfiber suede alternatives are hybridizing with genuine leather in upper-trim seating and steering wheel applications. Chinese premium EV brands including NIO and Li Auto specify these materials for weight reduction and consistent surface aging. This hybridization is compressing traditional leather tannery order volumes while expanding synthetic substrate finishing capacity.
China's GB 18352.6-2016 emission standard and India's AIS-137 testing protocol for cabin air quality are forcing adhesive and foam suppliers to eliminate formaldehyde and benzene precursors from formulations. Tier-1 seating manufacturers in Shanghai and Pune are requalifying entire chemical supply chains. Japanese OEMs operating across both markets are harmonizing material specifications to avoid parallel inventory pools.
Fleet procurement of interior refurbishment services is fragmenting traditional aftermarket parts distribution. Leasing companies and ride-hail operators in Singapore and Jakarta now contract directly with seating specialists for periodic cushion replacement and surface restoration. This channel compression bypasses conventional dealer parts departments and compresses margin capture for legacy distribution networks.
Asia Pacific Automotive Interiors Market Segmentation
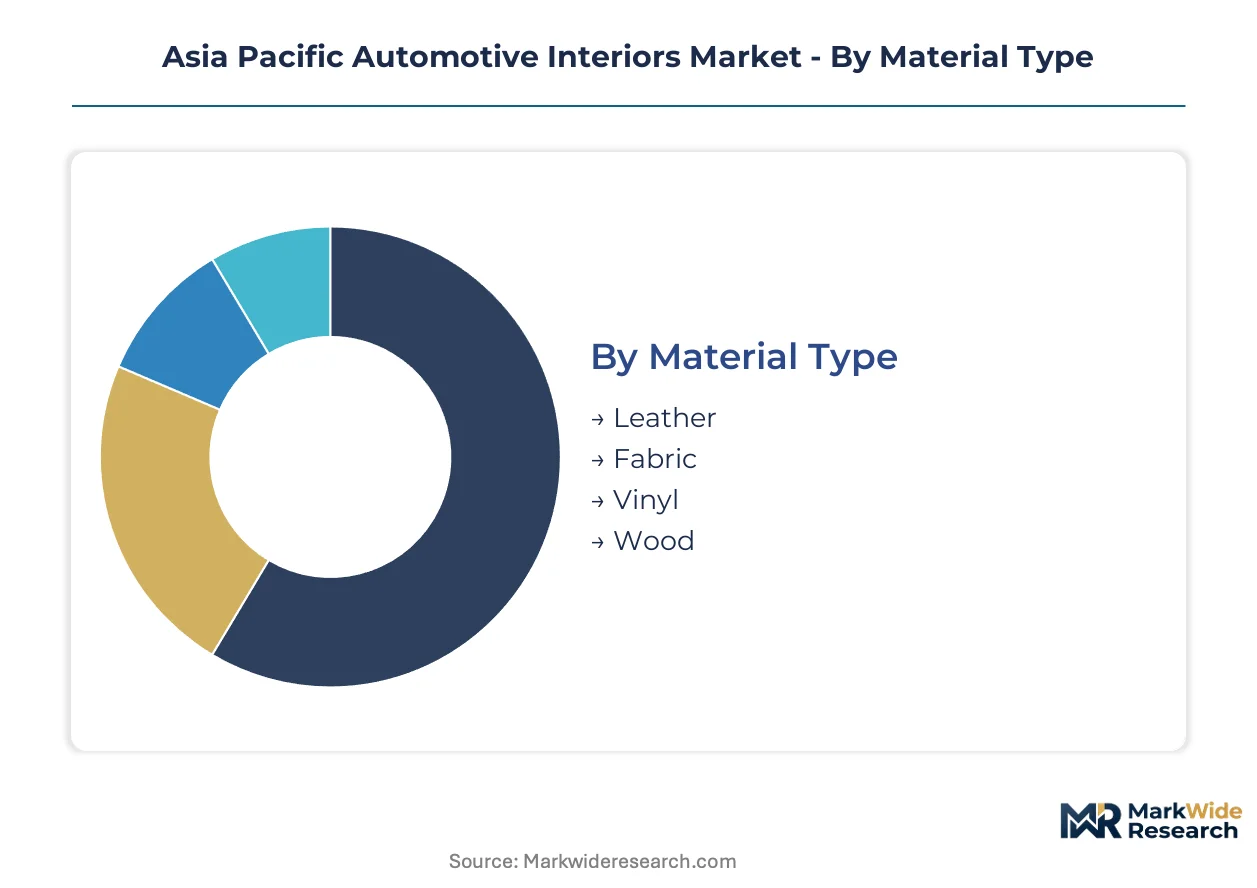
Segmentation in automotive interiors reveals how material specifications, component complexity, and vehicle positioning interact to determine supplier margins and warranty exposure across Asia Pacific assembly networks.
Material Type:
After-sales service intensity varies sharply across material categories, with leather and vinyl requiring specialized refurbishment protocols while fabric replacements flow through standard dealer parts channels.
- Leather:Premium grain hides with graded surface finishes dominate SUV and sedan upper trims across Chinese EV brands. NIO and Li Auto specify these materials for weight reduction and consistent aging profiles, though Italian and Korean tannery concentration exposes suppliers to currency risk and extended lead times.
- Fabric:Woven polyester and nylon blends maintain volume dominance in Indian and Southeast Asian hatchback applications where cost positioning governs procurement decisions. Maruti Suzuki and Hyundai Motor India specify these materials for entry-tier programs with compressed refurbishment cycles.
- Vinyl:Vacuum-formed PVC surfacing with stitched detailing serves mid-tier sedan and SUV segments across Thailand and Indonesia where humidity resistance outweighs premium tactile requirements.
- Wood:Veneer and synthetic woodgrain laminates concentrate in flagship sedan dashboards for Japanese premium brands, with suppliers in Aichi Prefecture controlling specialized pressing and finishing equipment.
By volume, Fabric leads. By growth pace, Leather is ahead.
Product Component:
Cost tier stratification separates powered seating architectures from passive trim panels, with climate-controlled modules commanding three to five times the per-vehicle value of door panel assemblies.
- Seats:Structural frames with embedded heating, ventilation, and massage mechanisms concentrate the largest value share given ergonomic impact on consumer satisfaction scores. Toyota Boshoku and Lear Corporation compete on powered seat electrification across Japanese and Chinese premium vehicle programs.
- Dashboard:Injection-molded thermoplastic polyolefin assemblies integrate instrument clusters and infotainment mounting points. Suppliers in China's Yangtze River Delta co-locate within 50 kilometers of BYD and SAIC assembly plants to minimize logistics friction.
- Door Panels:Multi-material assemblies combining structural substrates with decorative surfacing serve cost-optimized hatchback programs across India where BIS flammability standards reshape Tier-1 qualification timelines.
- Interior Trim:Pillar covers, headliners, and console surfacing complete cabin environments with lower engineering complexity but higher design refresh frequency demanded by EV programs.
Seats capture the highest revenue per vehicle. Dashboard assemblies are expanding most quickly as digital cockpit integration accelerates.
Vehicle Type:
Application-based demand splits between family-oriented architectures prioritizing durability and individual-use vehicles emphasizing aesthetic differentiation.
- SUV:Three-row seating configurations and panoramic roof cutouts drive specialized headliner and pillar trim specifications across Chinese and Australian markets. Premium cabin specifications in this segment displace cost-minimized architectures that dominated internal combustion programs.
- Sedan:Rear-seat comfort features including adjustable headrests and dedicated climate zones maintain procurement focus for fleet and executive transport operators in Singapore and Japan.
- Hatchback:Compact dimensions constrain material usage to fabric and vinyl surfacing for Indian and Southeast Asian volume manufacturers where price positioning governs supplier selection.
- Coupe:Two-door architectures with fixed rear seating prioritize aesthetic trim finishing over functional complexity, serving niche positioning for Korean and Japanese sport variants.
SUVs lead by installed value per vehicle. Sedans retain the steepest expansion trajectory as Chinese EV brands redefine premium cabin specifications.
End User:
Customer-type concentration determines whether interior components flow through captive supply agreements or contested aftermarket channels with diverging margin structures.
- OEMs:Vehicle manufacturers specify complete interior architectures through platform-based sourcing with multi-year volume commitments. BYD, Toyota, and Hyundai-Kia dominate procurement across their respective home markets with deep supplier integration.
- Aftermarket Providers:Independent refurbishment specialists capture leasing company and ride-hail operator contracts for periodic cushion replacement and surface restoration, bypassing conventional dealer parts departments in Singapore and Jakarta.
- Tier-1 Suppliers:Seating and dashboard manufacturers including Toyota Boshoku and Hyundai Mobis serve as system integrators managing Tier-2 material qualification and assembly logistics.
- Dealerships:Authorized service channels retain warranty-backed interior refurbishment programs that narrow traditional aftermarket parts distribution margins.
OEMs dominate by procurement volume. Aftermarket Providers are gaining share fastest as fleet operators fragment traditional distribution networks.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Asia Pacific automotive interior procurement. Indian and Southeast Asian hatchback buyers drive hard cost negotiations on fabric seating. Chinese EV purchasers absorb premiums for leather-trimmed cabins with climate-controlled architectures.
China
BYD and NIO specifications for Alcantara-wrapped steering wheels and massage-enabled seats are pulling material suppliers toward premium formulations. SAMR's GB Standard 27630 VOC emission limits compel foam and adhesive reformulation across Yangtze River Delta manufacturing zones. Dashboard suppliers co-locate within 50 kilometers of SAIC and BYD assembly plants in Shanghai and Guangzhou to compress logistics cycles.
India
Maruti Suzuki and Hyundai Motor India procurement for entry-tier hatchbacks sustains fabric volume dominance despite margin compression. BIS certification requirements for seat strength and flammability resistance extend Tier-1 supplier qualification timelines by four to six months. Seating frame manufacturers are establishing dedicated facilities in Gujarat and Tamil Nadu to capture PLI scheme production incentives.
Japan
Toyota and Honda premium sedan programs maintain demand for genuine leather with graded surface finishes and synthetic woodgrain dashboard laminates. METI energy efficiency guidelines for vehicle weight reduction pressure interior component mass optimization without sacrificing structural integrity. Specialized veneer pressing equipment in Aichi Prefecture controls flagship sedan finishing capacity.
South Korea
Hyundai-Kia Automotive Group captive supply relationships dominate domestic OEM channels and extend into Indian assembly operations. MFDS-aligned material safety protocols for embedded electronics in climate-controlled seating modules extend development timelines for mechanical-focused suppliers. Busan-Ulsan manufacturing corridors concentrate leather finishing and foam casting capacity for regional export programs.
Thailand
Japanese transplant assembly for ASEAN export markets sustains mid-tier vinyl and fabric specifications where humidity resistance governs material selection. TISI requirements for seat belt anchor and head restraint designs run parallel to Japanese JIS standards, simplifying supplier qualification for dual-market programs. Bangkok metropolitan corridor suppliers specialize in vacuum-formed PVC door panels for regional SUV programs.
Asia Pacific Automotive Interiors Market Competitive Environment
Capability concentration sits with integrated system architects; scale advantage sits with diversified global fabricators. The supplier base organizes around three tiers: captive OEM affiliates with exclusive assembly plant relationships, independent Tier-1 system integrators competing on technology leadership, and regional specialists capturing PLI-driven capacity expansion. Dominant competitive moves include co-location clustering within 50 kilometers of major assembly plants and backward integration into polyurethane foam casting to secure margin control.
Among Japan-based integrated suppliers, Toyota Boshoku Corporation and Toyoda Gosei Co Ltd exemplify the captive affiliate archetype, occupying positions tied to Toyota Motor's regional manufacturing footprint. Lear Corporation represents the independent technology leader archetype, competing on powered and climate-controlled seat architectures across premium vehicle programs. Hyundai Mobis Co Limited anchors the Korean chaebol-integrated tier, leveraging captive supply relationships that extend from domestic assembly into Indian OEM channels.
| Leading Market Players |
|---|
| Hyundai Mobis Co Limited |
| Toyota Boshoku Corporation |
| Panasonic Corporation |
| Continental AG |
| Calsonic Kansei Corporation |
| Tachi-S Company Ltd |
| Lear Corporation |
| Magna International Inc |
| Toyoda Gosei Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Shanghai-Nagoya freight corridors transmit polyurethane foam feedstock cost volatility directly into seating supplier margins, compressing profitability for manufacturers locked into annual OEM contracts while enabling price differentiation between climate-controlled premium architectures and passive fabric configurations.
Pricing Analysis
Long-term offtake agreements dominate procurement between Yangtze River Delta seating suppliers and Chinese EV OEMs, though spot-market leather hide purchases from Italian tanneries introduce currency-driven volatility. Price differentiation hinges on GB Standard 27630 VOC certification grade and embedded electronics complexity, with climate-controlled modules commanding substantial premiums over passive configurations. Cost compression in entry-tier fabric seating intensifies as Maruti Suzuki and Hyundai Motor India consolidate hatchback supplier bases. Fleet operators exhibit highest price sensitivity, while Chinese premium EV buyers absorb leather-trimmed cabin premiums.
Supply Chain Analysis
Tariff exposure between South Korea and India disrupts leather finishing equipment transfers for seating frame manufacturers establishing Gujarat facilities. Supply concentrates in China's Yangtze River Delta, South Korea's Busan-Ulsan corridor, and Japan's Aichi Prefecture. Raw material dependencies include TDI/MDI foam precursors, premium grain hides, and thermoplastic polyolefin resins. Single-source vulnerability concentrates in Italian tannery relationships. Distribution runs through captive OEM affiliate channels and Tier-1 system integrators with co-located assembly plant proximity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GB Standard 27630 VOC compliance deadlines are compressing material reformulation timelines across Asia Pacific, creating asymmetric capability gaps between qualified and unqualified suppliers.
For Market Incumbents: Entrench qualification advantages by accelerating backward integration into castor oil-derived polyurethane foam casting and securing CQC mark pre-approvals ahead of SAMR enforcement waves. Defend against emerging biobased material specialists by locking multi-year volume commitments with BYD and NIO platform engineering teams. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-eligible seating frame manufacturing by partnering with Tamil Nadu-based mechanism suppliers seeking finishing capability. Target aftermarket refurbishment contracts with Singapore ride-hail operators bypassing traditional dealer networks. Pursue direct-to-OEM digital sampling platforms to compress design validation cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with underperforming automotive interior divisions lacking EV program exposure. Long-term viability centers on suppliers with demonstrated GB Standard 27630 compliance and climate-controlled seating module validation. Monitor BIS certification backlog durations as inflection indicator for Tier-1 supplier margin stress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Foam Casting | Secures margin control over TDI/MDI volatility for Yangtze River Delta seating suppliers. |
| GB Standard 27630 Pre-Certification | Accelerates SAMR approval timelines for adhesive and substrate reformulation investments. |
| Co-Location Clustering Near BYD Plants | Compresses logistics friction for dashboard suppliers in Guangzhou manufacturing zones. |
| Digital Sampling Platform Launch | Enables Tier-2 textile suppliers to bypass traditional Tier-1 design house gatekeepers. |
| PLI-Aligned India Facility Buildout | Captures component-level production incentives in Gujarat and Tamil Nadu corridors. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, SAMR regulatory filings, and customs trade records. Interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and dealership operations managers informed demand-side validation. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across the analysis window.
Forecast inputs include vehicle class stratification, propulsion architecture mix shifts, content-per-vehicle trajectories, OEM tier positioning, and regional production cluster development. CAGRs were derived from regression analysis of historical production volumes against projected electrification penetration. Industry-specific variables encompass GB Standard 27630 compliance timelines and PLI scheme uptake rates in Indian states.
Stress conditions across polyurethane feedstock pricing, BIS certification delays, and leather tannery supply disruptions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding SAMR enforcement intensity and EV platform rollout schedules. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Automotive Door Latch Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Glove Box Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Automotive Exterior Trim Parts Market
Automotive Interior & Exterior
Global Automotive Roof Systems Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Railway Interiors Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Automotive Seating Systems Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Global Automotive Intelligent Seats Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Automotive Window Seals Market
Automotive Interior & Exterior
Automotive Encapsulated Glass Market