
 Brazil Automotive Flooring Market | 2026-2036
Brazil Automotive Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Automotive Flooring Market Insights
Southeastern Brazil is narrowing its supply deficit as Toyota Boshoku Corporation extends its regional molding footprint. Lear Corporation leverages vertical integration into resin compounding to secure raw material streams. Magna International Inc anchors its position through dedicated just-in-sequence delivery contracts with domestic OEMs.
Brazil automotive flooring encompasses interior surface materials engineered for abrasion resistance, acoustic dampening, and occupant safety compliance within vehicle cabins, typically manufactured through thermoforming, compression molding, or needle-punch processes to achieve specified wear ratings and flammability thresholds. The primary purpose is to protect vehicle substrates while enhancing cabin ergonomics and brand differentiation for manufacturers. Carpet and vinyl materials dominate OEM specifications due to their balance of cost efficiency and tactile performance, while foam-backed configurations are gaining traction in electric vehicle platforms where weight reduction commands premium positioning. Mats and custom-fit product forms capture higher margin pools in the aftermarket channel compared to bulk rolls consumed by vehicle assemblers.
ANVISA governs chemical emissions and material safety standards for automotive interiors, while Inovar-Auto framework provisions mandate local content thresholds and R&D investment commitments from suppliers operating in Brazil. These dual compliance layers elevate barriers for importers and incentivize domestic production scale-up by flooring manufacturers. Stakeholders must monitor evolving PROCONVE emission alignment rules and potential shifts in local content calculus as electrification programs reshape procurement priorities across Brazilian vehicle assembly networks.
Market Dynamics
Domestic OEMs in São Paulo and Minas Gerais are compressing supplier lead times for lightweight cabin materials, forcing flooring manufacturers to co-locate molding capacity near assembly plants. This geographic clustering is reshaping competitive positioning across southeastern Brazil.
Growth Catalysts
- Inovar-Auto framework:Local content thresholds and R&D investment mandates are pulling resin compounding and thermoforming operations into Brazilian states. Suppliers capture tax credits by meeting domestic value-add requirements.
- Electric vehicle platforms:Foam-backed carpet configurations are gaining specification share as weight reduction commands premium positioning in battery-electric cabins. OEMs prioritize acoustic dampening per kilogram saved.
- Southeastern cluster expansion:Toyota Boshoku Corporation and Lear Corporation are extending regional molding footprints to serve just-in-sequence delivery contracts with domestic assemblers.
Market Restraints
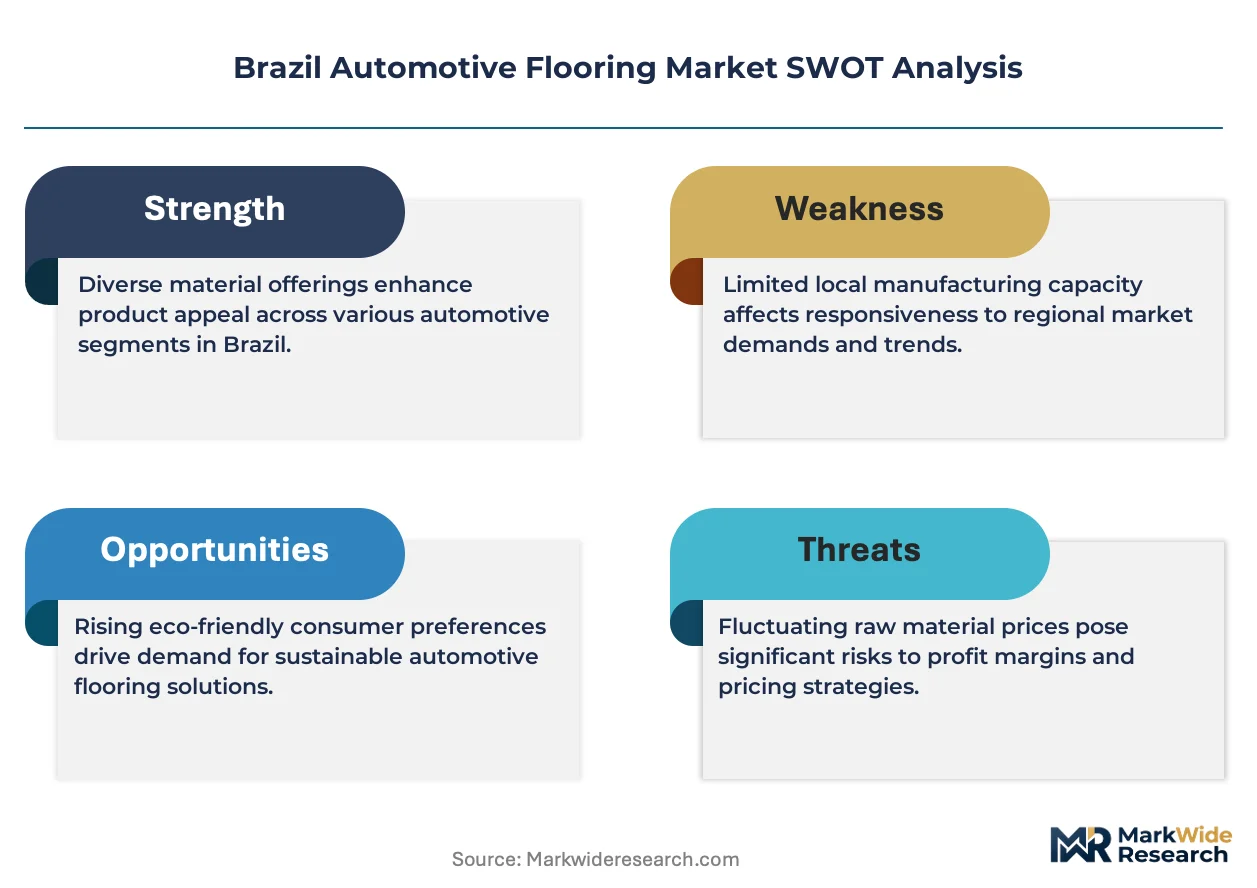
- Petrochemical feedstock volatility:Polypropylene and PVC resin prices fluctuate with international crude benchmarks, compressing margin predictability for compression-molding operations.
- Import dependency for specialty additives:Flame retardants and low-emission binders concentrate among Asian suppliers, exposing Brazilian compounders to currency and logistics risk.
- ANVISA compliance timeline:Extended certification cycles for chemical emissions testing delay new material introductions by 8-14 months versus non-regulated markets.
Strategic Opportunities
- Northeastern Brazil underpenetration:Ceará and Pernambuco vehicle assembly corridors lack dedicated flooring suppliers, creating first-mover advantage for domestic manufacturers with distribution reach.
- Recycled content mandates:Inovar-Auto provisions incentivize post-industrial carpet fiber integration, rewarding suppliers with captive recycling infrastructure.
- Aftermarket channel digitization:Custom-fit mat configurations are migrating from wholesale distributors to direct-to-installer platforms, capturing margin pools previously held by intermediaries.
Industry Challenges
- Thermoforming technician scarcity:Specialized die maintenance and CAD-driven mold adjustment skills concentrate among aging workforces in São Paulo state, constraining capacity expansion.
- Legacy ERP integration:Domestic flooring manufacturers face friction connecting just-in-sequence visibility systems to OEM enterprise platforms, delaying real-time production scheduling.
- Multi-standard certification burden:Suppliers must simultaneously satisfy ANVISA chemical protocols, PROCONVE emission alignment, and OEM-specific flammability testing, extending product development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Automotive Flooring Market |
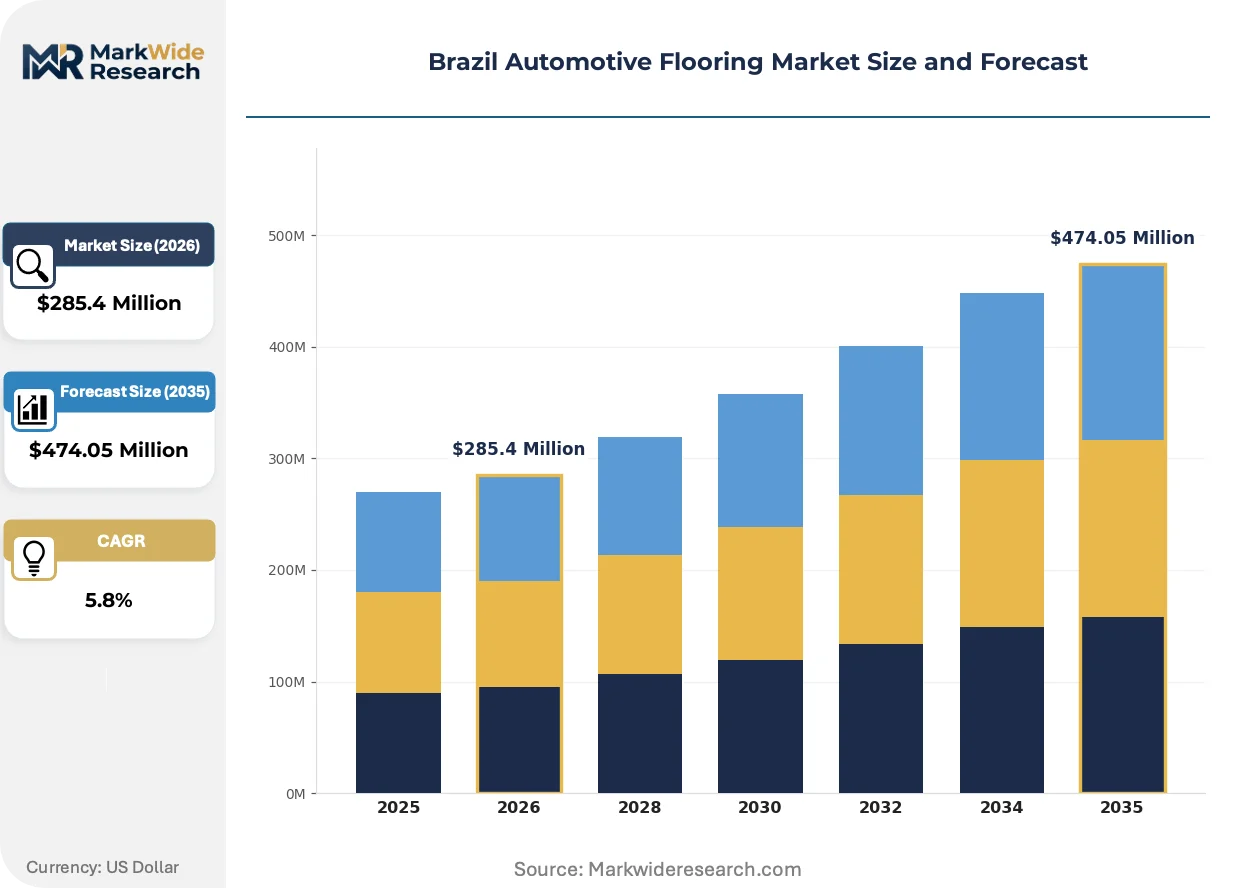
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Carpet, Vinyl, Rubber, Foam End User: OEMs, Aftermarket Providers, Dealerships, Vehicle Assemblers Product Form: Rolls, Tiles, Mats, Sheets Installation Type: Adhesive, Interlocking, Loose Lay, Custom Fit |
| Companies Covered | Lear Corporation, Magna International Inc, AGM Automotive, Toyota Boshoku Corporation, HP Pelzer Automotive Systems Inc, Corry Rubber Corporation, Auto Custom Carpets, Autofloors, Apache Mills, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Automotive Flooring Market Trends and Innovations
Material science and regulatory stringency are converging to redefine specification criteria across Brazilian vehicle cabins. Three developments are compressing traditional supplier hierarchies.
Needle-punch carpet construction is migrating from heavy-gauge polyester blends to lighter polypropylene formulations with integrated acoustic barriers. Volkswagen do Brasil and Stellantis are specifying these configurations for entry-level passenger platforms. The shift is compressing demand for traditional woven backing suppliers while elevating compounders with in-house fiber extrusion capability.
ANVISA is tightening volatile organic compound thresholds for interior materials through amended Resolução RDC protocols. The industrial consequence is a forced reformulation of adhesive binders and foam substrates across the supply base. Carpet manufacturers serving premium OEM segments are responding fastest, integrating water-based lamination processes ahead of mandatory compliance deadlines.
Fleet operators and rental channels are consolidating flooring procurement through multi-year supply agreements with performance guarantees. Tier-2 distributors are losing specification influence as direct OEM contracts capture volume previously fragmented across regional wholesalers. This concentration is most visible in São Paulo's corporate fleet market, where maintenance cost predictability now outweighs upfront material pricing in vendor selection criteria.
Brazil Automotive Flooring Market Segmentation
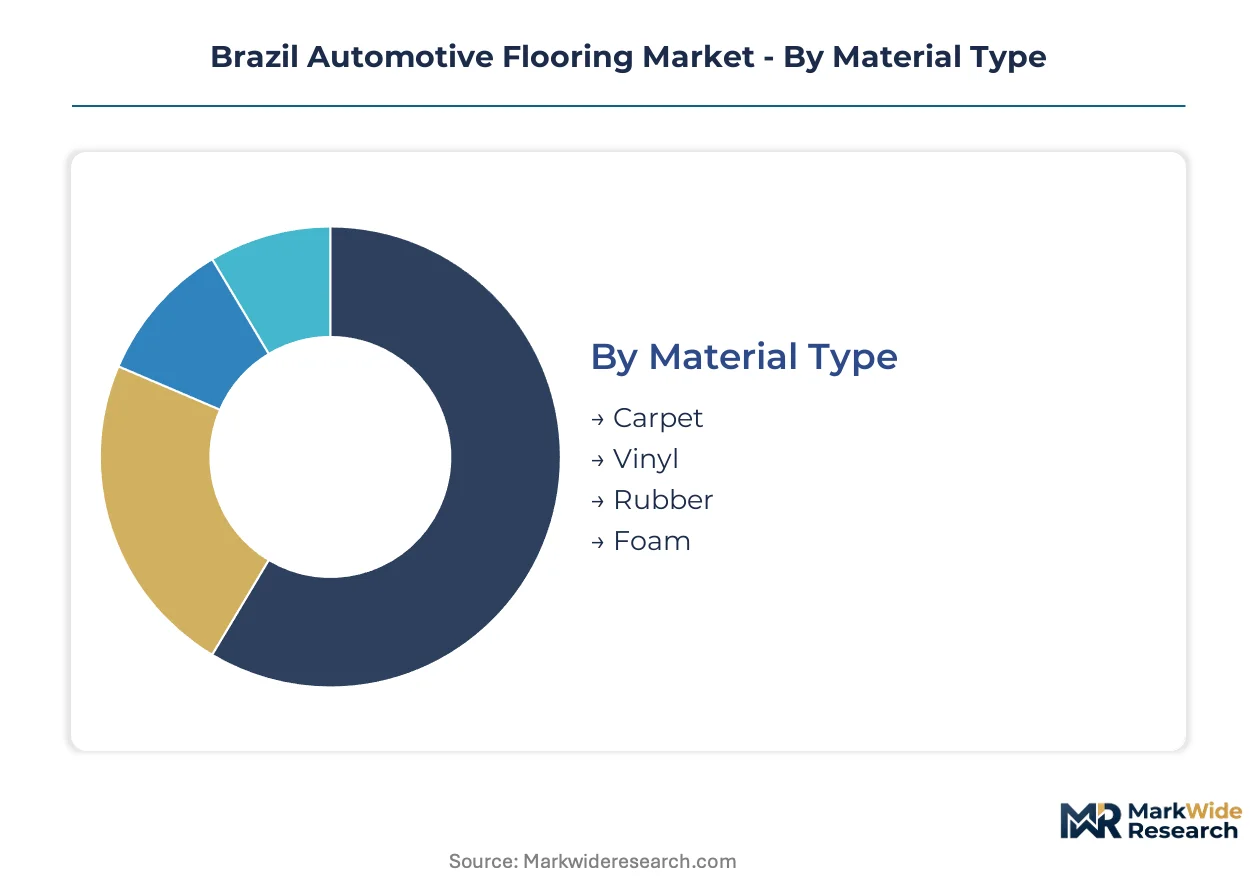
Segmentation in Brazilian automotive flooring reveals how material specifications, procurement channels, and installation methods fragment value capture across the supply chain. Understanding these divisions exposes where margin pools concentrate and which configuration shifts threaten incumbent positioning.
Material Type:
Mature thermoplastic formulations dominate OEM specifications while emerging bio-based alternatives test certification pathways under ANVISA protocols.
- Carpet:Needle-punch and tufted constructions using polypropylene fiber blends deliver acoustic dampening and wear resistance for passenger vehicle cabins. São Paulo assemblers specify these for mid-range platforms where cost-per-kilogram and tactile performance must balance.
- Vinyl:PVC-based sheet and tile formulations provide chemical resistance and simplified cleaning protocols for commercial fleet applications. Minas Gerais truck manufacturers favor vinyl for durability under heavy-use duty cycles.
- Rubber:SBR and EPDM compounds serve heavy-duty commercial segments requiring extreme abrasion resistance.
- Foam:Lightweight polyurethane and polyethylene substrates enable weight reduction targets in electric vehicle programs.
Carpet handles the majority of throughput; foam is climbing the fastest on specification share.
End User:
Procurement authority fragments across direct manufacturing relationships and fragmented aftermarket channels with diverging margin structures.
- OEMs:Original equipment manufacturers in São Paulo and Minas Gerais dictate material specifications through just-in-sequence contracts. Toyota Boshoku Corporation and Lear Corporation anchor supply relationships with dedicated molding capacity near assembly plants.
- Aftermarket Providers:Independent distributors and custom-fit specialists capture higher per-unit margins through direct-to-installer digital platforms, bypassing traditional wholesale intermediaries.
- Dealerships:Authorized service networks handle replacement flooring for warranty and maintenance programs.
- Vehicle Assemblers:Contract manufacturers and kit builders procure bulk rolls for integration into localized production.
OEMs command the volume base; aftermarket providers are expanding margin fastest through channel digitization.
Product Form:
Physical configuration determines manufacturing investment intensity and logistics cost structures across the value chain.
- Rolls:Continuous bulk material feeds high-volume thermoforming and die-cutting operations at vehicle assembly plants. São Paulo flooring manufacturers optimize roll widths for specific OEM press configurations.
- Mats:Pre-formed custom-fit configurations reduce installation labor for aftermarket channels. Digitization of measurement-to-delivery workflows is compressing lead times for replacement applications.
- Tiles:Modular interlocking systems serve niche commercial retrofit segments.
- Sheets:Flat stock material supports specialty vehicle and conversion markets.
Rolls absorb the production volume; mats are gaining share fastest through aftermarket channel restructuring.
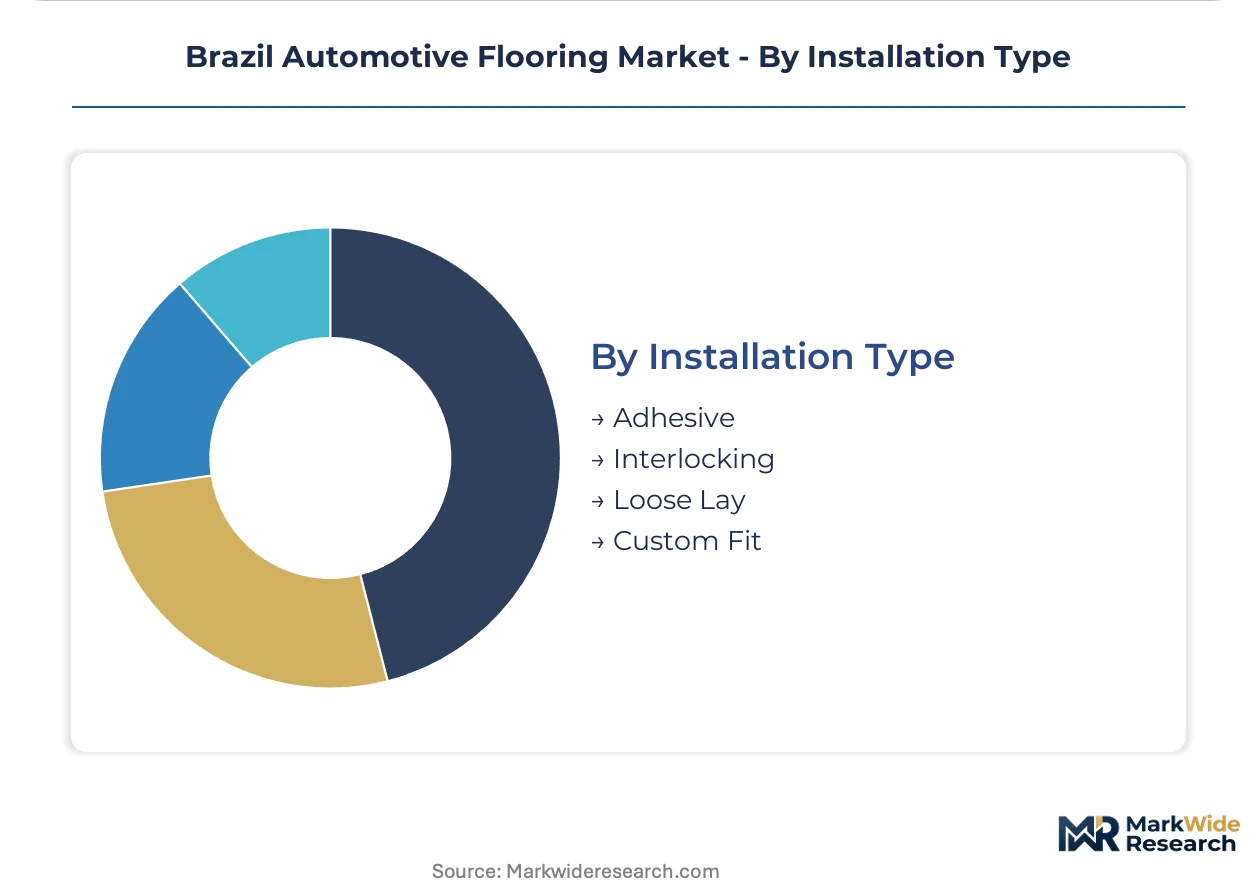
Installation Type:
Attachment methodology shapes labor allocation between manufacturing integration and field service deployment.
- Adhesive:Permanent bonding systems dominate OEM cabin integration where structural stability and acoustic sealing are non-negotiable. ANVISA-compliant low-VOC adhesive formulations are displacing solvent-based legacy products.
- Custom Fit:Precision-molded configurations clip or snap into vehicle-specific retention systems. Electric vehicle platforms favor these for serviceability and end-of-life material recovery.
- Interlocking:Mechanical connection systems serve modular aftermarket applications.
- Loose Lay:Non-permanent placement supports temporary fleet and rental vehicle configurations.
Adhesive installation carries the specification weight; custom fit is expanding most quickly on electric vehicle platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ANVISA governs chemical emissions and material safety standards across Brazil's automotive interior supply chain, while Inovar-Auto framework provisions mandate local content thresholds from flooring manufacturers operating in southeastern states.
São Paulo
Vehicle assemblers in São Paulo compress supplier lead times for lightweight cabin materials, forcing flooring manufacturers to co-locate molding capacity near assembly plants. Toyota Boshoku Corporation extends its regional molding footprint to serve just-in-sequence delivery contracts. The metropolitan corridor concentrates thermoforming operations and resin compounding facilities serving domestic OEMs.
Minas Gerais
Heavy-duty commercial vehicle manufacturers in Minas Gerais favor vinyl flooring formulations for durability under extreme duty cycles. PROCONVE emission alignment rules shape procurement priorities across truck and bus assembly networks. Belo Horizonte anchors a secondary cluster of compression-molding suppliers serving commercial OEM specifications.
Rio Grande do Sul
Specialty vehicle and agricultural equipment manufacturers in Rio Grande do Sul generate demand for modular tile configurations and custom-fit mat systems. State-level industrial incentives support flooring suppliers targeting niche commercial retrofit segments. Porto Alegre hosts distributors bridging aftermarket channels with southern Brazil's fleet operator base.
Paraná
Vehicle kit builders and contract manufacturers in Paraná procure bulk roll materials for localized production integration. Inovar-Auto tax credits pull resin compounding operations into the Curitiba industrial corridor. The state offers geographic diversification for suppliers seeking to reduce concentration risk in São Paulo-dominated networks.
Brazil Automotive Flooring Market Competitive Landscape
Vertically integrated multinationals and domestic specialists split the market between high-volume OEM contracts and flexible aftermarket configurations. Lear Corporation leverages in-house resin compounding to secure raw material streams, while Toyota Boshoku Corporation anchors supply relationships through dedicated molding capacity near assembly plants. The vendor base concentrates around three strategic archetypes: global tier-1 suppliers with captive manufacturing, regional compounders serving niche specifications, and aftermarket-focused fabricators with digital distribution reach. Dominant competitive moves include backward integration into polymer feedstocks and geographic co-location with OEM assembly networks.
Among North American-based tier-1 suppliers, Lear Corporation and Magna International Inc exemplify the scale-driven archetype with integrated manufacturing footprints. Toyota Boshoku Corporation represents the Asia-headquartered multinational model with regional molding capacity in southeastern Brazil. These three anchors occupy positions across the premium-OEM contract spectrum, with Lear Corporation and Magna International Inc sitting within the vertically integrated tier and Toyota Boshoku Corporation anchoring the just-in-sequence delivery specialist segment.
| Leading Market Players |
|---|
| Lear Corporation |
| Magna International Inc |
| AGM Automotive |
| Toyota Boshoku Corporation |
| HP Pelzer Automotive Systems Inc |
| Corry Rubber Corporation |
| Auto Custom Carpets |
| Autofloors |
| Apache Mills |
| Others |
Pricing and Supply Chain Analysis
Undercapacity in São Paulo thermoforming operations is compressing supplier margins while elevating pricing power for compounders with captive resin production. ANVISA compliance timelines and Inovar-Auto local content thresholds force flooring manufacturers to absorb certification costs or cede share to vertically integrated multinationals.
Pricing Analysis
Southeastern Brazil commands premium positioning against northeastern corridors where logistics costs inflate delivered pricing. Pricing stratifies across premium, standard, and economy tiers based on ANVISA certification grade and OEM volume commitment scale. Cost compression in standard-grade carpet runs through petrochemical feedstock volatility and currency exposure on imported specialty additives. Fleet procurement teams exhibit highest price sensitivity; premium OEM platform engineers prioritize acoustic performance per kilogram over unit cost.
Supply Chain Analysis
Export-control regimes on flame-retardant chemistry and low-emission binder technology constrain flows from Asian specialty chemical suppliers to Brazilian compounders. Manufacturing concentrates in China, South Korea, and Germany for needle-punch equipment and extrusion tooling. Raw material streams draw from Saudi Arabian polypropylene feedstock, domestic PVC resin from Braskem, and imported polyurethane foam substrates. Single-source vulnerability sits with Asian additive suppliers. Distribution runs through just-in-sequence contracts with São Paulo OEMs and wholesale aftermarket channels serving independent installers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized thermoforming technician pools are thinning across São Paulo state, creating bottlenecks that constrain capacity expansion regardless of capital deployment. This capability scarcity rewards suppliers with in-house training pipelines and CAD-driven mold adjustment expertise.
For Market Incumbents: Pre-empt northeastern Brazil penetration by establishing compounding capacity in Ceará or Pernambuco before competitors capture first-mover positioning. Secure captive recycling infrastructure to capture Inovar-Auto tax credits on post-industrial carpet fiber integration. Defend against aftermarket channel digitization by acquiring direct-to-installer platforms or building proprietary measurement-to-delivery workflows. For New Entrants and Emerging Players: Pursue electric vehicle platform specifications where foam-backed configurations command premium positioning and incumbent supplier relationships remain unsettled. Target Paraná kit builder networks for bulk roll supply contracts with lower certification barriers than São Paulo OEM direct relationships. Lead with water-based lamination processes that anticipate ANVISA volatile organic compound threshold tightening. For Investors and Strategic Acquirers: Capital is best deployed toward regional compounders with backward integration into resin production and established ANVISA certification pathways. Long-term viability hinges on suppliers capturing electric vehicle specification share before platform architectures standardize. The signal to watch is Inovar-Auto provision evolution on local content calculus as electrification programs reshape procurement priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Secures raw material streams against petrochemical price volatility and satisfies Inovar-Auto domestic value-add requirements. |
| Geographic Co-location with OEM Assembly Networks | Enables just-in-sequence delivery contracts that compress lead times and lock out distant competitors from São Paulo platforms. |
| Water-based Lamination Process Investment | Positions suppliers ahead of ANVISA Resolução RDC volatile organic compound threshold tightening in premium OEM segments. |
| Captive Recycling Infrastructure Buildout | Captures Inovar-Auto tax credits for post-industrial carpet fiber integration while reducing virgin material cost exposure. |
| Direct-to-Installer Digital Platform Launch | Bypasses wholesale intermediaries in aftermarket channels to capture margin pools previously fragmented across regional distributors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of vehicle production databases, customs and trade records, ANVISA regulatory filings, and OEM procurement disclosures. Primary interviews engaged Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, thermoforming plant managers, and resin compounding technical directors. Secondary validation drew from SEC 10-K filings of listed automotive suppliers, IHS Markit vehicle registration data, and Inovar-Auto program documentation. Bottom-up segmentation modeling triangulated against top-down macroeconomic scaling across the Brazilian automotive interior supply chain.
Forecast inputs span vehicle class, propulsion architecture, content per vehicle, OEM tier positioning, and regional production cluster concentration. Segmentation dimensions include material type, end user procurement authority, product form configuration, and installation methodology. CAGRs were derived through regression analysis of historical specification share shifts and forward projection of electric vehicle platform penetration. Industry-specific inputs incorporate ANVISA compliance timeline assumptions and Inovar-Auto local content threshold evolution across the analysis window.
Macroeconomic conditions sit as an overlay; deviation in Brazilian real exchange rates, international crude benchmarks, or automotive sector credit availability would shift the trajectory. Forecasts reflect assumptions on ANVISA protocol stability and Inovar-Auto framework continuity. Material shifts in electric vehicle platform architecture standardization or PROCONVE emission alignment rule changes would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Heated Windshield Market
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
Automotive Grab Handle Market
Automotive Interior & Exterior
Windscreen Washer System Market
Automotive Interior & Exterior
Global Car Air Purifier Market
Automotive Interior & Exterior
Global Automotive Windscreen Glazing Market
Automotive Interior & Exterior
Automotive Structural Steel Market
Automotive Interior & Exterior
Laser Headlight Market
Automotive Interior & Exterior
Automotive Steering Wheel Market
Automotive Interior & Exterior
Automotive Fascia Market
Automotive Interior & Exterior
Auto Ventilated Seats Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Automotive Pneumatic Seat System Market