
 Global Automotive Windscreen Glazing Market | 2026-2036
Global Automotive Windscreen Glazing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Automotive Windscreen Glazing Market Analysis
Software-defined head-up display calibration services are restructuring how windscreen value gets captured beyond the physical pane. Saint-Gobain leverages its integrated coating technology to dominate premium HUD-compatible glazing. Fuyao Glass anchors volume production through captive supply relationships with Chinese OEMs. AGC Inc. differentiates via specialized thin-laminate architectures for acoustic dampening.
Automotive windscreen glazing comprises laminated safety glass assemblies, typically two plies of annealed glass bonded by polyvinyl butyral interlayers measuring 0.76–1.52 mm, engineered for optical clarity, structural integrity, and occupant retention during impact events. Its primary commercial purpose is to maintain cabin integrity while enabling advanced driver assistance system sensor transparency. Laminated glass commands the dominant margin pool given HUD and embedded antenna integration requirements. Electric vehicles represent the fastest-expanding vehicle type segment due to expanded glass surface areas and weight-reduction priorities. The aftermarket installation channel faces margin compression from consolidated distributor networks.
The US NHTSA enforces Federal Motor Vehicle Safety Standard 205 for glazing materials, while the EU's F-Gas Regulation constrains manufacturing process emissions. Japan's METI promotes next-generation glass through industrial technology roadmaps. Stakeholders must monitor how sensor fusion requirements reshape interlayer specifications before committing to capacity investments.
Market Dynamics
Sensor fusion requirements for advanced driver assistance systems are compressing interlayer specifications and forcing glass manufacturers to coordinate optical properties with semiconductor suppliers before committing to capacity.
Growth Catalysts
- Panoramic roof proliferation:Electric vehicle OEMs are expanding laminated glass surface areas beyond traditional windscreen boundaries, creating pull-through demand for specialized interlayer formulations.
- Europe's F-Gas Regulation:Manufacturing process emission constraints are accelerating capital deployment into low-emissivity coating infrastructure, favoring early movers with integrated production capabilities.
- Head-up display integration:Windscreen-embedded projection systems require wedge-shaped glass architectures that command premium positioning in the laminated safety glass category.
Market Restraints
- PVB resin concentration:Polyvinyl butyral interlayer supply concentrates among a handful of chemical producers, exposing glass fabricators to input cost volatility and allocation risk during demand spikes.
- Optical certification timelines:HUD-compatible glazing requires extended validation cycles against distortion and ghosting metrics, extending new product introduction lead times by 18-24 months.
- Thin-glass substitution pressure:Chemically strengthened monolithic alternatives threaten share in specific vehicle segments where weight reduction outweighs occupant retention requirements.
Strategic Opportunities
- Acoustic dampening specialization:Thin-laminate architectures with specialized interlayer damping properties address NVH priorities in premium electric vehicle cabins, creating defensible technical positioning.
- Embedded antenna integration:Windscreen-mounted 5G and V2X communication modules enable glass suppliers to capture value previously retained by tier-one electronics integrators.
- India's PLI scheme for automotive components:Localized laminated glass production incentives are drawing capacity investments to serve domestic OEM expansion and export positioning.
Industry Challenges
- Optical metrology talent scarcity:Calibration of HUD-compatible windscreens requires specialized expertise in wavefront analysis and angular deviation measurement that outpaces current training pipeline output.
- Sensor fusion integration complexity:LiDAR and camera transparency requirements impose conflicting spectral transmission specifications that complicate interlayer formulation decisions.
- Cross-border certification fragmentation:Divergent approval processes between the US NHTSA, Japan's METI, and EU type-approval frameworks multiply compliance engineering overhead for global platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Automotive Windscreen Glazing Market |
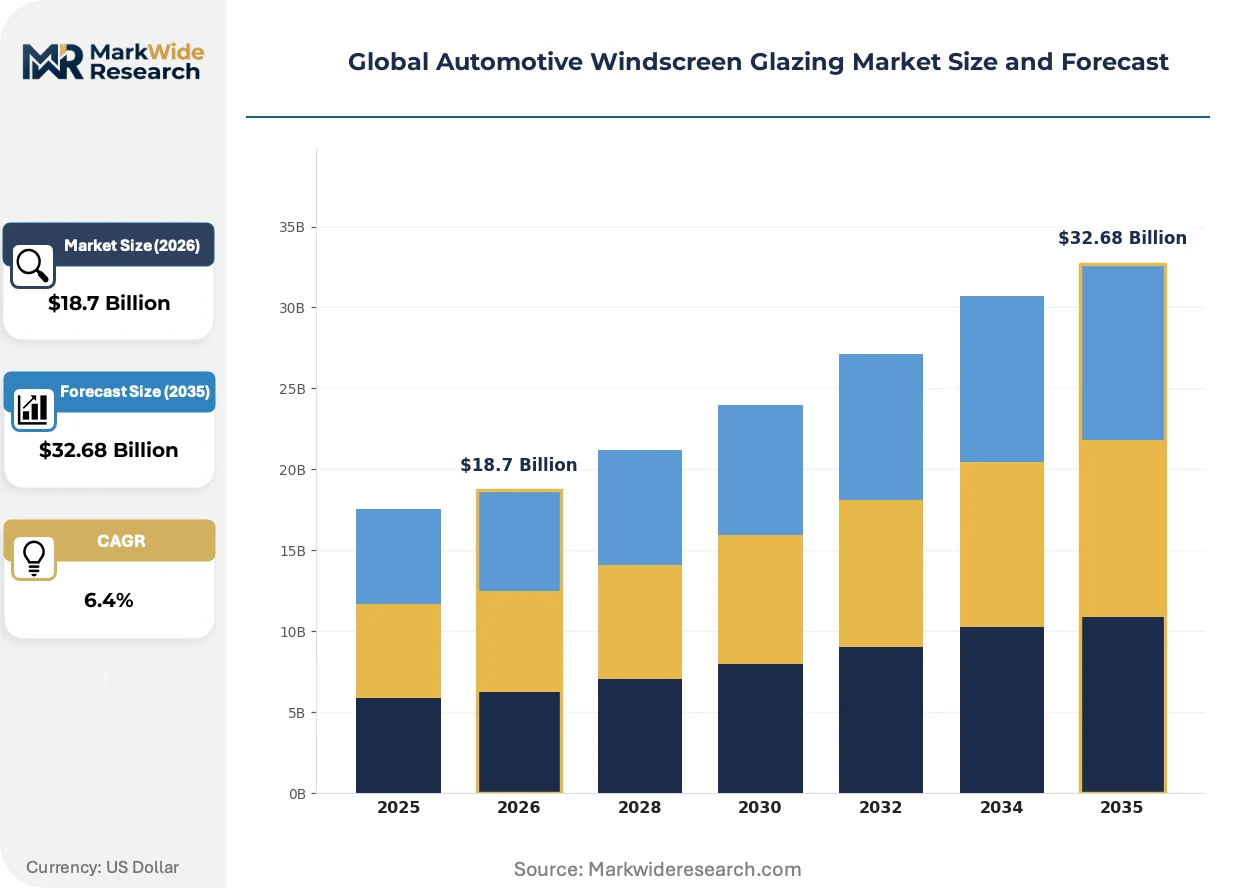
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $32.68 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tempered Glass, Laminated Glass, Polycarbonate, Others Vehicle Type: Passenger Cars, Commercial Vehicles, Electric Vehicles, SUVs Installation Type: Original Equipment Manufacturer, Aftermarket, Replacement, Custom Fit End User: Automotive Manufacturers, Repair Shops, Auto Glass Distributors, Fleet Operators |
| Companies Covered | Saint-Gobain, AGC Inc., Fuyao Glass Industry Group Co., Ltd., Nippon Sheet Glass Co., Ltd., Xinyi Glass Holdings Limited, Guardian Glass, PPG Industries, Inc., Sisecam, Central Glass Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Automotive Windscreen Glazing Market Emerging Trajectories
Software-defined functionality is migrating from electronic control units into glass substrates themselves, redefining how windscreen value gets captured and measured across the vehicle lifecycle.
Electrochromic interlayer technology is electrifying cabin thermal management by enabling dynamic tint adjustment without mechanical sunshades. Premium electric vehicle platforms in Germany and California are adopting these assemblies to reduce HVAC load and extend range. The technology is compressing traditional static glazing margins while opening recurring-revenue service models around calibration and replacement.
The EU's F-Gas Regulation is constraining fluorinated gas use in low-emissivity coating processes, forcing manufacturers to retool magnetron sputtering lines toward alternative deposition chemistries. Saint-Gobain's integrated coating facilities have absorbed these transition costs more readily than smaller competitors dependent on third-party coating services. Germany's KBA enforcement timeline is accelerating compliance investments ahead of the 2030 phase-down milestones.
Chinese OEMs are consolidating procurement decisions at the platform-architecture level rather than delegating to tier-one suppliers, compressing the traditional specification chain. This concentration is displacing distributor intermediaries in favor of direct manufacturer relationships with Fuyao Glass and AGC Inc. The shift is most visible in NEV platform launches from BYD and NIO, where windscreen suppliers negotiate directly with vehicle program executives.
Global Automotive Windscreen Glazing Market Segmentation
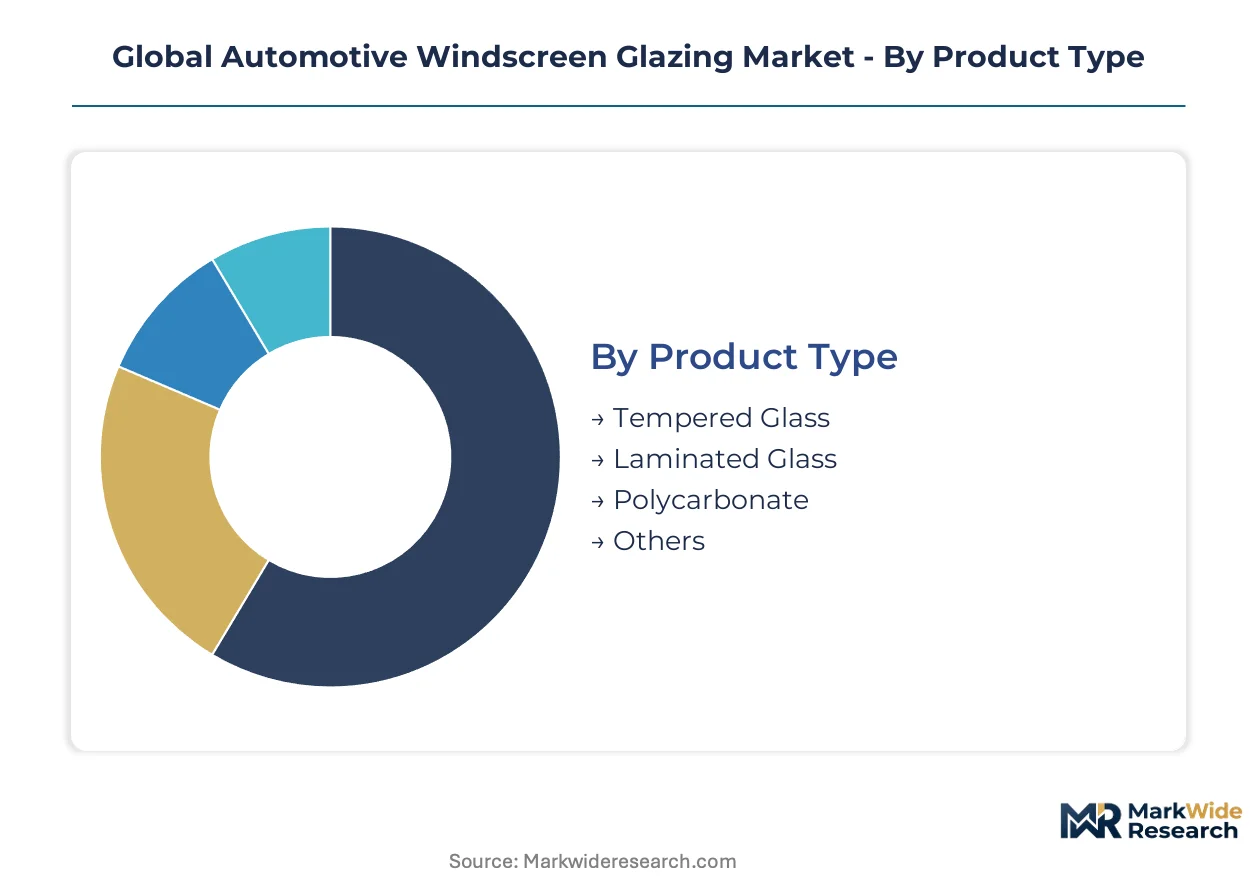
Segmentation in automotive windscreen glazing reveals how technical specifications, vehicle architectures, and channel economics partition margin capture. Understanding these divides exposes where coating technology investments concentrate and which customer relationships command pricing power.
Product Type:
Material selection pivots on optical clarity requirements, weight constraints, and regulatory compliance for occupant retention.
- Laminated Glass:Two plies of annealed glass bonded by polyvinyl butyral interlayers deliver structural integrity and sensor transparency for ADAS integration. Premium electric vehicle platforms in Germany and California specify these assemblies for panoramic roof and HUD-compatible windscreen applications.
- Tempered Glass:Thermally or chemically strengthened monolithic panels shatter into granular fragments upon failure, meeting side and rear window specifications where weight reduction outweighs laminated safety requirements. Japanese OEMs specify tempered architectures for kei-car segments.
- Polycarbonate:Lightweight polymer substrates address extreme weight-reduction mandates in specific racing and limited-production vehicle programs.
- Others:Emerging glass-ceramic and hybrid composite formulations serve niche optical and thermal management applications.
Mature deployment sits with Tempered Glass. Newer deployment is concentrated in Laminated Glass.
Vehicle Type:
Glass surface area per vehicle and sensor integration density determine specification intensity across platform categories.
- Electric Vehicles:Expanded glass surface areas for panoramic roofs and reduced structural pillars create pull-through demand for specialized interlayer formulations. BYD and NIO platform architectures specify direct manufacturer relationships rather than tier-one delegation.
- SUVs:Larger windscreen apertures and steeper rake angles impose complex optical distortion management requirements for HUD compatibility.
- Passenger Cars:Volume production programs standardize laminated safety glass with embedded antenna integration for 5G and V2X connectivity.
- Commercial Vehicles:Durability specifications prioritize chip resistance and extended service life over premium optical features.
Volume concentration remains with Passenger Cars. Specification complexity is climbing fastest in Electric Vehicles.
Installation Type:
Channel economics diverge sharply between captive OEM supply and fragmented aftermarket replacement.
- Original Equipment Manufacturer:Direct manufacturer relationships with vehicle program executives capture value from embedded sensor calibration and HUD wedge-angle specification. Saint-Gobain and AGC Inc. anchor supply through integrated coating capabilities.
- Replacement:Insurance-driven demand cycles and consolidated distributor networks compress margins for standardized laminated assemblies.
- Aftermarket:Customization programs for classic vehicle restoration and performance upgrades command premium positioning outside warranty channels.
- Custom Fit:Specialized fabrication for low-volume and specialty vehicle manufacturers requires flexible production scheduling.
Value capture concentrates in Original Equipment Manufacturer. Margin pressure is most severe in Replacement.
End User:
Procurement authority and technical specification involvement vary dramatically across customer types.
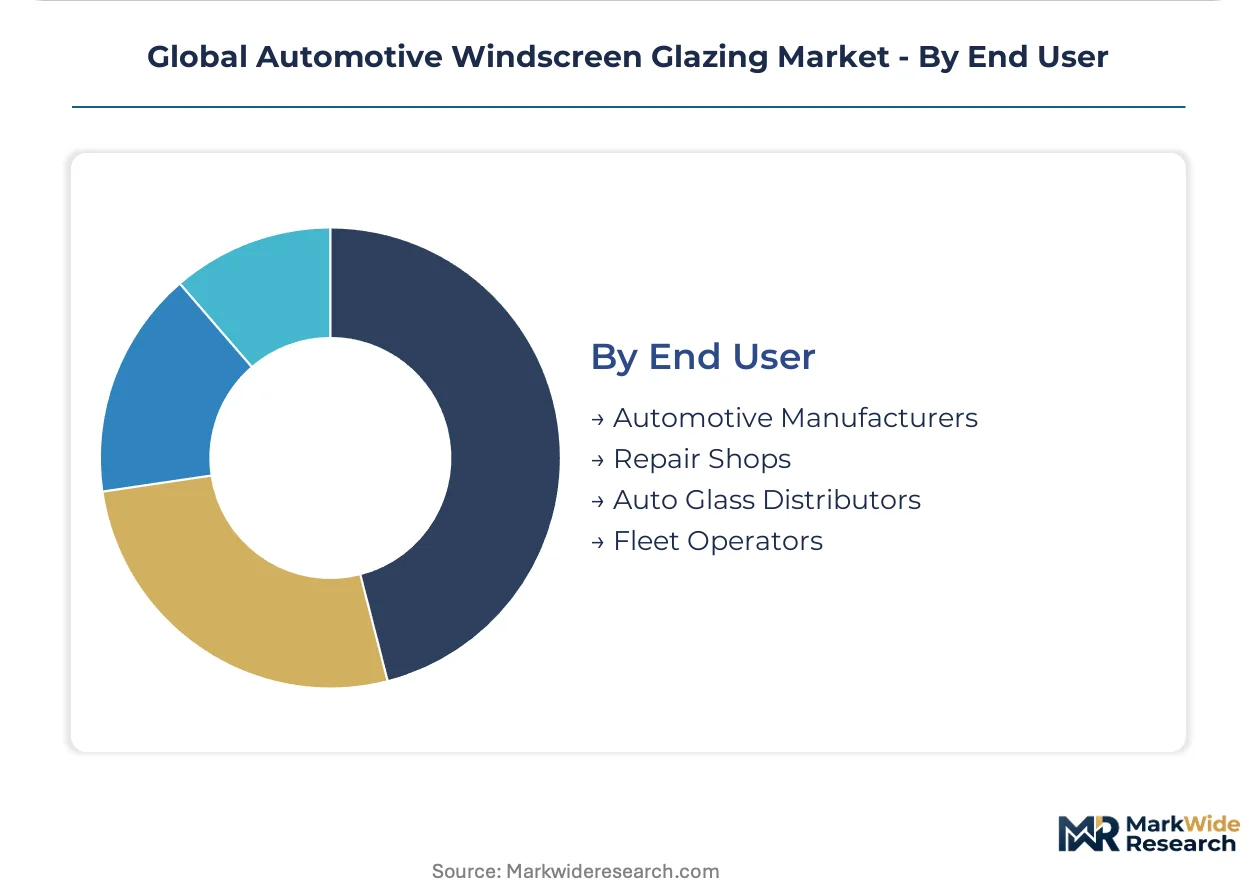
- Automotive Manufacturers:Platform-level architecture decisions consolidate windscreen specification authority with vehicle program executives, displacing traditional tier-one supplier intermediation. Fuyao Glass leverages captive supply relationships with Chinese OEMs.
- Auto Glass Distributors:Consolidated national networks in North America and Europe negotiate volume pricing for standardized replacement inventory.
- Repair Shops:Mobile installation services and same-day replacement programs compete on logistics speed rather than product differentiation.
- Fleet Operators:Total cost of ownership calculations prioritize durability and warranty terms over initial acquisition price.
Specification authority concentrates with Automotive Manufacturers. Price sensitivity is highest among Fleet Operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity clusters in Germany and China while consumption spreads across premium vehicle markets in North America and Europe. Manufacturing investments concentrate where OEM assembly plants and coating technology infrastructure overlap. Regulatory pressure on process emissions is accelerating geographic shifts in supplier footprints.
United States
Head-up display penetration in premium SUVs and electric trucks from Detroit manufacturers drives specification intensity for wedge-angle laminated assemblies. The NHTSA maintains Federal Motor Vehicle Safety Standard 205 enforcement while California's air quality regulations indirectly pressure coating process choices. Michigan's automotive corridor anchors laminated glass finishing operations serving domestic OEM platform launches.
Germany
Panoramic roof integration in electric vehicle architectures from Munich and Stuttgart-based manufacturers expands glass surface area per vehicle beyond traditional windscreen boundaries. The KBA enforces EU F-Gas Regulation timelines for low-emissivity coating process transitions ahead of 2030 phase-down milestones. Bavaria's industrial corridor concentrates magnetron sputtering investments and integrated coating facilities.
China
Domestic OEMs consolidate procurement authority at the platform-architecture level, displacing tier-one supplier intermediation in favor of direct manufacturer relationships. MIIT industrial policy supports next-generation automotive glass through technology roadmaps and domestic capability building. Yangtze River Delta manufacturing clusters anchor volume production for BYD and NIO platform specifications.
Japan
Kei-car segments sustain tempered glass demand for side and rear applications where weight reduction outweighs laminated safety requirements. METI promotes next-generation glazing through industrial technology roadmaps targeting sensor transparency standards. Aichi Prefecture's automotive cluster coordinates interlayer specification development with semiconductor suppliers for ADAS integration.
India
Domestic OEM expansion and export positioning draw laminated glass capacity investments toward serving Southeast Asian and Middle Eastern markets. The PLI scheme for automotive components incentivizes localized production with performance-linked subsidies. Tamil Nadu's manufacturing corridor hosts finishing operations targeting premium passenger car and electric vehicle platform supply.
Global Automotive Windscreen Glazing Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across a market structure that rewards integrated coating capabilities and captive OEM relationships. The vendor base splits between multinational integrated manufacturers with magnetron sputtering infrastructure and regional volume specialists serving single-country procurement consolidation. Three archetypes dominate: coating-integrated premium specialists, scale-driven volume fabricators, and acoustic-dampening niche players. Competitive moves concentrate on capacity expansion in India and China alongside strategic partnerships for sensor fusion calibration expertise.
Among integrated coating specialists, Saint-Gobain exemplifies the premium-tier archetype through European infrastructure depth, while AGC Inc. occupies a position bridging Japanese precision manufacturing with global platform supply. Fuyao Glass Industry Group Co., Ltd. anchors the volume-driven segment through Chinese OEM captive relationships. These three represent distinct strategic postures: European coating integration, Japanese thin-laminate specialization, and Chinese scale procurement consolidation.
| Leading Market Players |
|---|
| Saint-Gobain |
| AGC Inc. |
| Fuyao Glass Industry Group Co., Ltd. |
| Nippon Sheet Glass Co., Ltd. |
| Xinyi Glass Holdings Limited |
| Guardian Glass |
| PPG Industries, Inc. |
| Sisecam |
| Central Glass Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap glass fabricators across Central Europe anchor specialized coating capacity that commands pricing discipline against commodity imports. Their concentrated ownership structures enable long-term process investments that fragmented distributor networks cannot replicate, insulating premium laminated assemblies from spot-market volatility while exposing volume-tier suppliers to consolidated OEM procurement leverage.
Pricing Analysis
Margin tightening in replacement-grade laminated assemblies reflects consolidated distributor purchasing power across North American national networks. Three-tier pricing structure across premium, standard, and economy levels separates HUD-compatible wedge-angle specifications from basic safety-laminated inventory, with certification grade against NHTSA FMVSS 205 and EU type-approval frameworks driving differentiation. Cost compression accelerates in standardized passenger car windscreens as Chinese OEMs consolidate procurement at platform-architecture levels. Fleet operators exhibit highest price sensitivity through total cost of ownership calculations, while premium electric vehicle programs retain lowest sensitivity given sensor fusion integration requirements.
Supply Chain Analysis
Dual-sourcing mandates from German and US OEMs require qualified secondary suppliers for polyvinyl butyral interlayer feedstock, complicating procurement strategies for magnetron sputtering lines. Geographic concentration centers on Germany, China, and Japan for integrated coating infrastructure and volume lamination capacity. Raw material dependencies rest on PVB resin from chemical producers, soda-lime silica batch, and magnetron sputtering target metals. Single-source vulnerability concentrates in specialized interlayer damping formulations for acoustic applications. Distribution runs through captive OEM supply chains for original equipment, consolidated national networks for replacement, and direct manufacturer relationships for Chinese platform architectures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from F-Gas Regulation compliance costs and sensor fusion calibration complexity will eliminate coating-dependent specialists lacking integrated production infrastructure.
For Market Incumbents: Anticipate displacement risk from electrochromic interlayer technology by securing exclusive platform-architecture relationships with premium electric vehicle OEMs in Germany and California. Deepen backward integration into magnetron sputtering target production to absorb EU coating process transition costs ahead of 2030 phase-down milestones. Prioritize acoustic dampening specialization as defensible technical positioning against thin-glass substitution in weight-sensitive segments. For New Entrants and Emerging Players: Capture white-space opportunity in India's PLI scheme for automotive components by establishing localized laminated glass finishing operations serving domestic OEM expansion and Southeast Asian export positioning. Target acoustic dampening niche applications for premium electric vehicle cabins where NVH specifications outpace incumbent capacity expansion. Pursue direct manufacturer relationships with Chinese NEV platform executives as the dominant go-to-market channel, bypassing traditional tier-one supplier intermediation. For Investors and Strategic Acquirers: Distressed-cycle entries favor coating-integrated mid-cap specialists in Central Europe facing working capital constraints from F-Gas Regulation retooling requirements. Long-term viability across the five-to-ten year window hinges on captive relationships with sensor fusion calibration ecosystems and magnetron sputtering infrastructure ownership. Monitor LiDAR transparency specification finalization as the critical inflection signal for interlayer formulation investment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Magnetron Sputtering Capacity Expansion | Captures value from EU F-Gas Regulation compliance timelines ahead of German KBA enforcement. |
| Acoustic Dampening Interlayer Development | Addresses NVH priorities in premium electric vehicle cabins from Munich and Stuttgart manufacturers. |
| Direct OEM Platform Relationships | Bypasses tier-one supplier intermediation consolidating procurement at BYD and NIO architectures. |
| Embedded Antenna Integration Partnership | Captures electronics value previously retained by tier-one integrators for 5G and V2X modules. |
| India PLI Scheme Localization | Positions capacity to serve domestic OEM expansion and Southeast Asian export markets. |
Methodological Framework
Multi-period observation of PVB resin pricing volatility, magnetron sputtering capacity utilization, and HUD penetration rates anchored the trend analysis, supplemented by interviews with OEM platform engineers, tier-one supplier procurement leads, aftermarket distributors, and coating technology specialists. Secondary validation drew from NHTSA FMVSS 205 enforcement data, EU F-Gas Regulation implementation timelines, vehicle production databases, and customs records for laminated glass trade flows. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Input-output matrices modeled volume and value trajectories across product type, vehicle architecture, installation channel, and end-user procurement authority dimensions. CAGRs were derived from regression analysis of historical penetration patterns and projected specification intensity shifts. Industry-specific forecast inputs incorporated panoramic roof surface area expansion per electric vehicle platform and sensor fusion calibration certification timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to LiDAR transparency specification finalization and electrochromic interlayer adoption curves. Projections reflect assumptions around F-Gas Regulation enforcement consistency and Chinese OEM procurement consolidation momentum. A model refresh is warranted upon material change in ADAS sensor fusion requirements or coating process chemistry transitions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Convertible Top Market
Automotive Interior & Exterior
Railway Interiors Market
Automotive Interior & Exterior
Automotive Interior Trims Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Asia-Pacific Automotive Seat Market
Automotive Interior & Exterior
Weatherstrip Market
Automotive Interior & Exterior
Automotive Synthetic Leather Market
Automotive Interior & Exterior
Automotive Load Floors Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Automotive Center Console Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Automotive Advanced Seating System Market
Automotive Interior & Exterior
Automotive Door Seal Market