
 Green Ship Recycling Market | 2026-2036
Green Ship Recycling Market Size, Share, and Industry Trends Forecast 2026-2036
Green Ship Recycling Market Foresight
Market Context
South Asia's yard modernization push is rewriting competitive dynamics in green ship recycling. Leyal leverages its Turkish facility certifications to compete for EU-flagged vessel contracts. GMS anchors its trading desk in the Middle East to control vessel acquisition pipelines. Veolia extends its hazardous waste management expertise into ship recycling through specialized decontamination services.
Technical Definition and Segments
Green ship recycling denotes the environmentally sound dismantling of end-of-life vessels using contained methods that prevent toxic releases, with steel recovery rates typically exceeding ninety percent and strict polychlorinated biphenyl removal protocols. The primary purpose centers on recovering ferrous and non-ferrous metals while eliminating asbestos, heavy fuels, and ozone-depleting substances from marine structures. Beaching still dominates volume throughput across South Asian yards, yet dry docking commands premium pricing due to contained effluent management and faster turnaround cycles. Container ships generate the fastest-growing vessel feedstock as liner operators face accelerated fleet renewal deadlines under IMO decarbonization pathways.
Regulatory Frame
The EU Ship Recycling Regulation mandates certified yard lists for EU-flagged vessels, while the Basel Convention transboundary waste rules constrain OECD-to-non-OECD vessel movements. Hong Kong Convention ratification by Bangladesh, India, and Pakistan will reshape yard compliance investments and insurance requirements. Stakeholders must monitor flag-state enforcement divergence between EU-mandated recycling plans and emerging economy implementation timelines.
Market Dynamics
EU Ship Recycling Regulation compliance deadlines are forcing maritime operators to abandon open beaching yards and contract only certified facilities with enclosed containment systems and documented hazardous waste protocols.
Growth Catalysts
- EU Ship Recycling Regulation:Mandates certified yard lists for EU-flagged vessels, redirecting end-of-life tonnage toward compliant South Asian and Turkish facilities with proper gas-cutting infrastructure.
- Container fleet renewal:Liner operators face accelerated vessel retirement schedules under IMO decarbonization pathways, generating concentrated feedstock of large containerships requiring systematic dismantling.
- Bangladesh-India-Pakistan ratification:Hong Kong Convention adoption by these three dominant recycling geographies is unlocking insurance coverage and foreign capital for yard modernization investments.
Market Restraints
- Steel scrap price volatility:Ferrous metal recovery revenues fluctuate with Chinese construction demand cycles, compressing yard margins during downturns and destabilizing cash flows for facility upgrades.
- Beaching infrastructure lock-in:Existing tidal flat operations in Chittagong and Alang represent sunk capital that resists conversion to dry dock configurations requiring concrete quays and effluent collection systems.
- Basel Convention constraints:Transboundary waste rules complicate OECD-to-non-OECD vessel movements, creating documentation bottlenecks and legal exposure for cash buyers and trading desks.
Strategic Opportunities
- Turkish facility expansion:EU proximity and existing EU Ship Recycling Regulation certification position Aliaga yards to capture premium-priced Mediterranean and Black Sea flag-state tonnage.
- Decontamination service integration:Hazardous waste specialists can backward integrate into ship recycling through specialized asbestos and PCB removal contracts preceding steel cutting operations.
- Digital inventory platforms:Blockchain-based material tracking systems enable certified secondary steel sales to construction and automotive end-users requiring documented provenance.
Industry Challenges
- Welder certification gaps:Enclosed gas-cutting operations demand qualified technicians trained in confined-space safety and toxic fume management, scarce in traditional beaching labor pools.
- Hong Kong Convention alignment timelines:Yard operators must synchronize facility investments with uncertain flag-state enforcement schedules, risking stranded capital if implementation lags.
- Legacy asbestos documentation:Pre-1980s vessels lack complete hazardous material inventories, forcing costly pre-dismantling surveys that extend turnaround cycles and inflate project costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Ship Recycling Market |
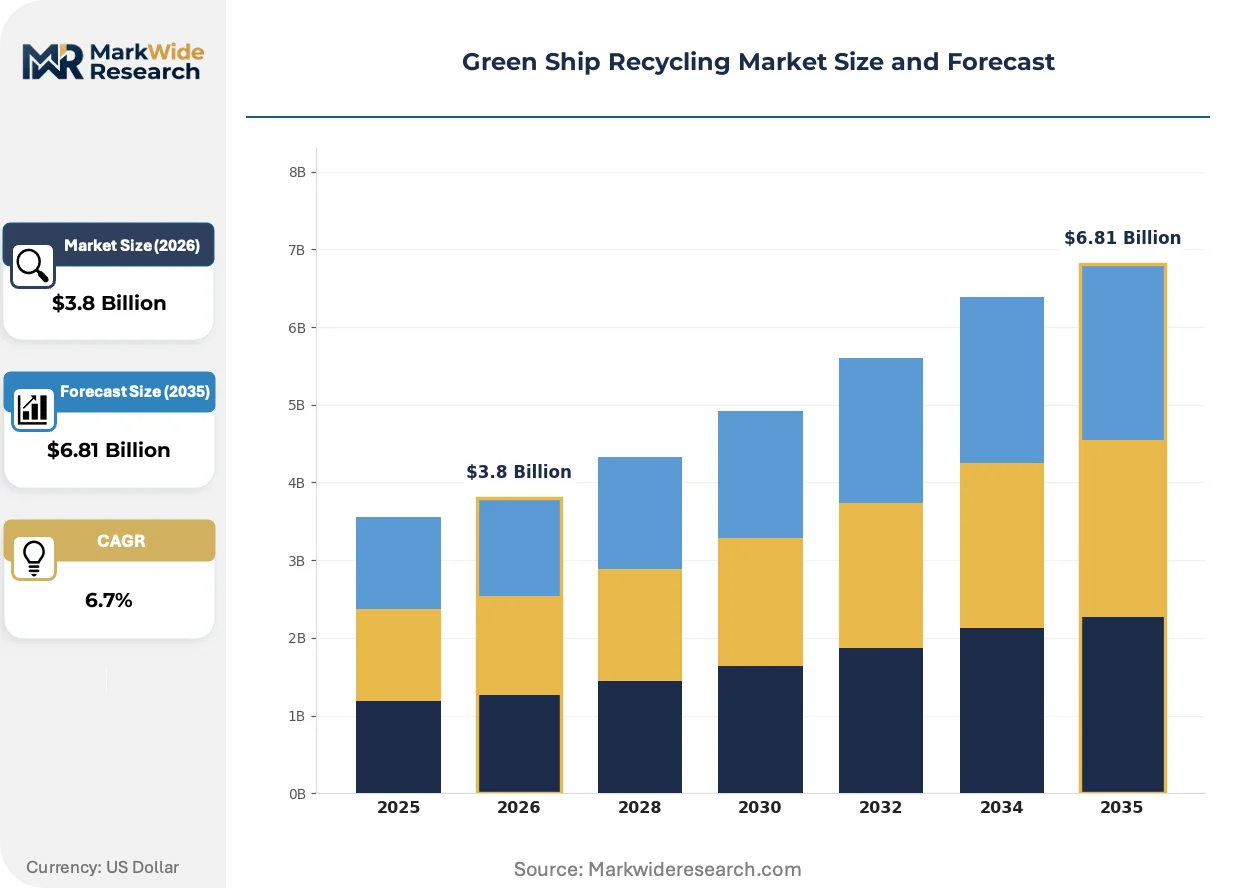
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Recycling Method: Dry Docking, Beaching, Wet Recycling, Dismantling Ship Type: Tankers, Bulk Carriers, Container Ships, Cruise Liners End-User: Shipowners, Shipbreaking Yards, Environmental Agencies, Salvage Operators Material Recovery: Metals, Plastics, Wood, Electronics |
| Companies Covered | Veolia, Zhejiang Huahang Industrial Co., Ltd., Green Wheel Recycling Middle East, Leyal, Changjiang Ship-breaking Yard, GMS, Boskalis, Zhoushan Ship Breaking, ALBA Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Ship Recycling Market Shifts & Advancements
Ship recycling is transitioning from tidal beaching toward contained industrial processes as regulatory enforcement tightens and buyer liability expands. Three forces are compressing the competitive window for conventional yards.
Plasma arc cutting technology is collapsing the cost gap between dry dock and beaching operations by eliminating oxy-fuel gas consumption and reducing steel oxidation losses. EU-flagged container operators are specifying plasma-cut steel recovery rates in recycling contracts. This compression is eroding the historical price advantage of tidal flat dismantling.
The EU Ship Recycling Regulation's certified facility list is redrawing competitive access for end-of-life tonnage. Non-listed South Asian yards are losing EU-flagged contracts regardless of price competitiveness. Indian facilities in Alang-Sosiya are responding with accelerated dry dock conversions and third-party auditing investments to secure list inclusion.
Certificate-of-recycling requirements are altering buyer-seller contracting structures. Shipowners now demand documented downstream liability transfer before final payment release, displacing traditional cash-buyer intermediation. This shift is most pronounced in German and Greek owner fleets with stringent internal ESG audit protocols.
Green Ship Recycling Market Segmentation
Segmentation in green ship recycling reveals how regulatory pressure and material recovery economics reshape competitive positioning across methods, vessel types, and downstream buyers. Understanding these divisions exposes where capital flows concentrate and which operational models capture premium pricing.
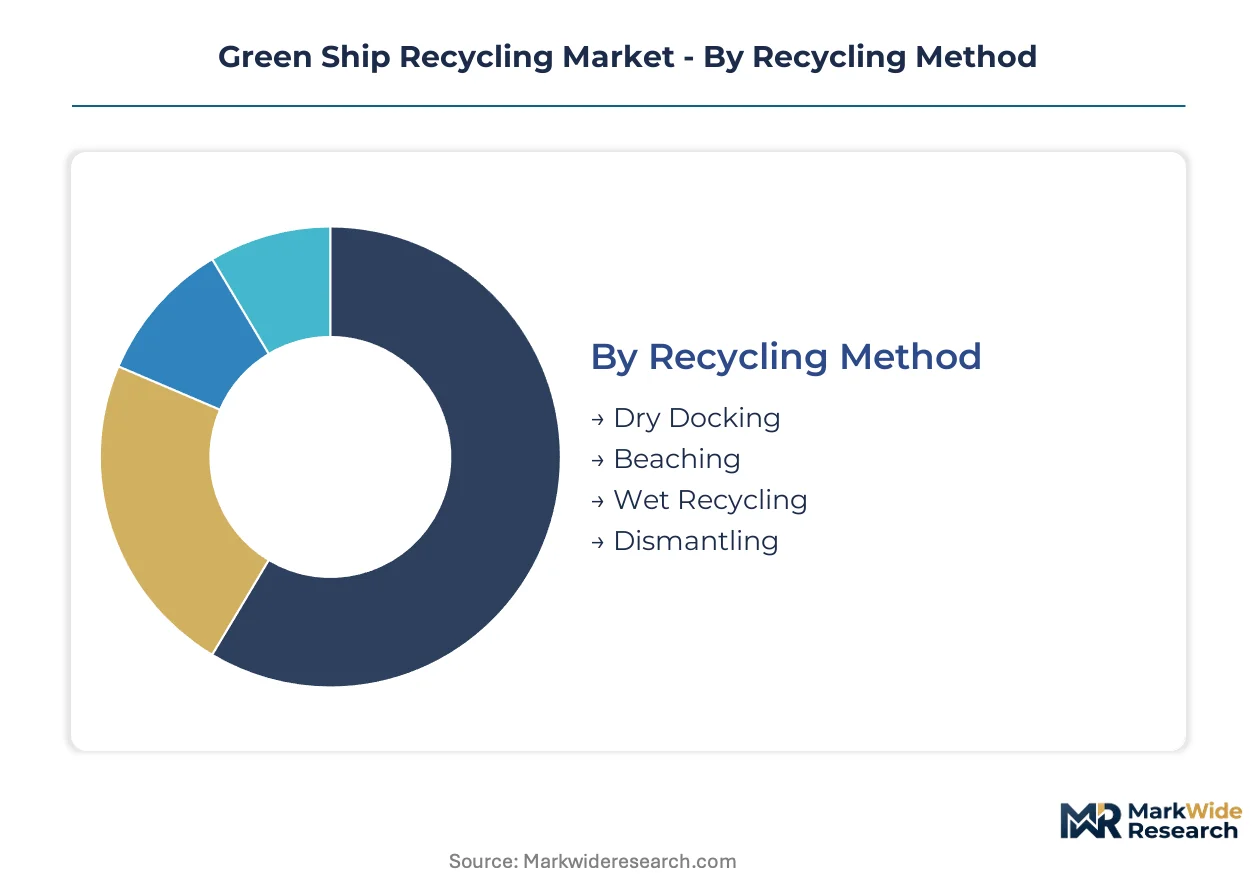
Recycling Method:
Cost tier differentiation separates contained industrial processes from legacy tidal operations, with capital intensity and certification status driving contract access.
- Dry Docking:Concrete quay configurations with integrated effluent collection and enclosed gas-cutting bays enable full EU Ship Recycling Regulation compliance. German and Greek container operators now mandate dry dock handling for end-of-life tonnage, paying premiums for documented hazardous waste containment and faster steel recovery cycles.
- Beaching:Tidal flat dismantling on Bangladesh and India coastlines persists through sunk infrastructure and labor arbitrage, though EU-flagged vessel access is narrowing. Chittagong yards face stranded asset risk as Hong Kong Convention ratification demands concrete quay investments they have deferred.
- Wet Recycling:Floating platform configurations allow partial containment in deep-water anchorages, serving flags with intermediate regulatory requirements.
- Dismantling:Land-based deconstruction at Aliaga and specialized Mediterranean facilities targets naval and offshore structures requiring precision segment removal.
Dry Docking holds installed capacity. Beaching is rotating up the share rankings only in non-EU flagged demolition.
Ship Type:
Application-driven segmentation aligns vessel retirement waves with steel quality and hazardous material load profiles.
- Container Ships:Post-Panamax and Ultra Large Container Vessels generate concentrated feedstock as IMO decarbonization deadlines force liner operator fleet renewal. These vessels yield high-grade shipbuilding steel with minimal asbestos legacy, attracting Turkish and Indian yard competition.
- Bulk Carriers:Capesize and Panamax demolition volumes fluctuate with freight rate cycles and Chinese steel scrap demand. Bangladesh yards specialize in these simpler hull structures with lower technical decontamination requirements.
- Tankers:Crude and product carriers demand extensive hydrocarbon cleaning and slop tank remediation, limiting eligible yards to those with specialized gas-freeing infrastructure.
- Cruise Liners:Complex interior fit-outs and extensive asbestos in older vessels create decontamination bottlenecks, extending turnaround cycles and requiring hazardous waste specialists.
Bulk Carriers hold installed capacity. Container Ships are climbing the fastest as fleet renewal accelerates.
End-User:
Customer type segmentation captures divergent purchasing power and liability transfer requirements across the value chain.
- Shipowners:German and Greek liner operators now contract directly with certified yards, displacing cash-buyer intermediation to secure certificate-of-recycling documentation for ESG audit trails.
- Shipbreaking Yards:Alang-Sosiya and Chittagong facilities compete for feedstock through EU list certification investments and steel scrap offtake agreements with Indian and Bangladeshi re-rolling mills.
- Environmental Agencies:National regulators in Bangladesh, India, and Pakistan enforce Hong Kong Convention alignment timelines, conditioning operating permits on dry dock conversion progress.
- Salvage Operators:Specialized contractors handle distressed vessels and wreck removal, requiring rapid mobilization capabilities and insurance relationships distinct from scheduled demolition.
Shipbreaking Yards hold installed capacity. Shipowners are rotating up the share rankings through direct contracting.
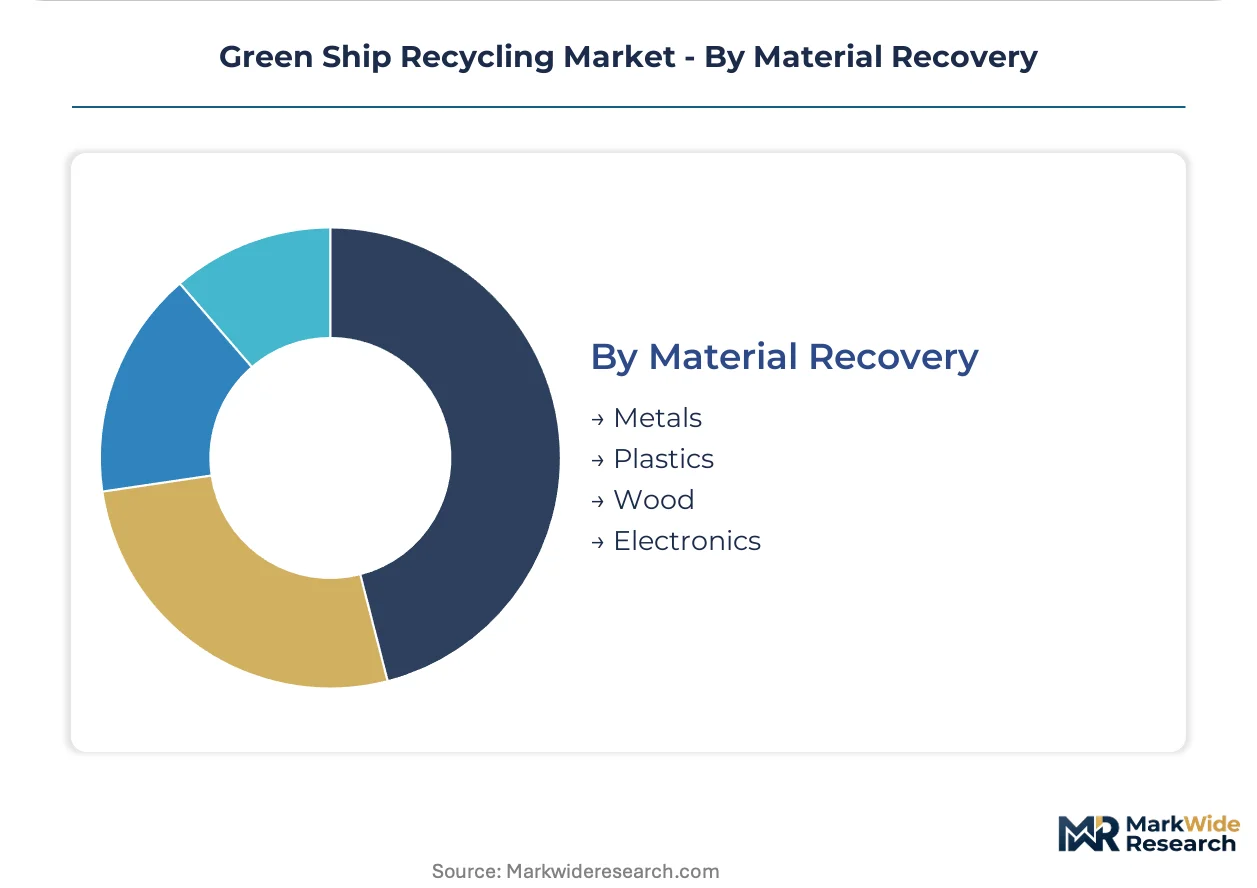
Material Recovery:
Volume concentration in ferrous recovery dominates revenue economics, with non-ferrous and specialized streams gaining attention as circular economy regulations tighten.
- Metals:Ferrous recovery from hull steel represents the primary revenue stream, with re-rolling mills in Bangladesh and India consuming demolished plate for construction reinforcement bars.
- Plastics:Interior fittings and insulation materials face emerging landfill restrictions under EU circular economy frameworks, creating demand for sorted polymer recovery.
- Wood:Teak decking and interior joinery from cruise and yacht demolition commands specialty furniture and marine restoration markets.
- Electronics:Navigation and communication equipment recovery requires e-waste handling certifications increasingly specified in EU Ship Recycling Regulation compliance documentation.
Metals hold installed capacity. Electronics are gaining share fastest as digital equipment density rises in modern fleets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangladesh consumes end-of-life tonnage through tidal beaching methods that diverge sharply from Turkey's contained dry dock protocols. India and Pakistan split the difference with hybrid yard configurations. The EU Ship Recycling Regulation has fragmented procurement patterns across these four dominant geographies.
Bangladesh
Chittagong yards process bulk carriers and tankers through beaching operations that minimize capital overhead. The country's Ministry of Industries enforces Hong Kong Convention alignment timelines that condition operating permits on concrete quay investments. Chittagong's shipbreaking zone faces stranded asset risk as EU-flagged vessel access narrows and financing for dry dock conversions remains scarce.
India
Alang-Sosiya facilities compete for container ship demolition contracts as liner operators accelerate fleet renewal under IMO decarbonization pathways. The Gujarat Maritime Board regulates yard certification progress under EU Ship Recycling Regulation compliance schedules. Alang's steel re-rolling mills consume demolished plate for construction reinforcement bars, anchoring regional ferrous metal recovery economics.
Turkey
Aliaga yards capture premium-priced Mediterranean and Black Sea flag-state tonnage through existing EU Ship Recycling Regulation certification. The Turkish Ministry of Environment and Urbanization encloses gas-cutting operations through environmental impact assessments. Izmir province's industrial cluster is expanding dry dock capacity to intercept EU-flagged vessels bypassing South Asian routes.
Pakistan
Gadani shipbreaking yards specialize in simpler hull structures with lower technical decontamination requirements than tanker or cruise segments. The country's national maritime regulator coordinates Hong Kong Convention ratification commitments with facility upgrade timelines. Balochistan province's coastal zone retains labor cost advantages that sustain beaching operations despite narrowing contract access.
China
Zhoushan and Changjiang yards handle domestic flag-state retirement and selective international contracts through enclosed dismantling protocols. The Ministry of Ecology and Environment restricts transboundary waste movements under Basel Convention alignment. Jiangsu province's ship recycling cluster is integrating plasma arc cutting technology to reduce steel oxidation losses and compress turnaround cycles.
Green Ship Recycling Market Competitive Landscape
Capability concentration sits with certified Turkish and Chinese yards possessing enclosed containment systems; scale advantage sits with South Asian beaching operations processing higher vessel throughput. The market structures around three tiers: EU-listed facilities commanding premium pricing, Hong Kong Convention-aligned yards in transition investments, and legacy beaching operators facing contract access erosion. Strategic moves center on dry dock conversion financing and hazardous waste management backward integration.
Among Turkey-based certified operators, Leyal occupies a position exemplifying EU Ship Recycling Regulation compliance through Aliaga facility investments. Within the trading and vessel acquisition tier, GMS anchors Middle East desk operations controlling feedstock pipelines to South Asian yards. On the hazardous waste specialization vector, Veolia represents environmental service extension into ship recycling through decontamination expertise. These three archetypes—certified yard operator, trading intermediary, and waste management specialist—map the competitive terrain.
| Leading Market Players |
|---|
| Veolia |
| Zhejiang Huahang Industrial Co., Ltd. |
| Green Wheel Recycling Middle East |
| Leyal |
| Changjiang Ship-breaking Yard |
| GMS |
| Boskalis |
| Zhoushan Ship Breaking |
| ALBA Group |
| Others |
Supply & Pricing Matrix
The Suez Canal route cost dynamics compress yard margins for EU-flagged vessels while amplifying price differentiation between certified dry dock facilities and legacy beaching operations. Supply concentration in South Asian tidal zones feeds into downstream pricing power held by Turkish and Chinese yards with enclosed containment systems.
Pricing Analysis
Long-term offtake contracts between German liner operators and Alang-Sosiya yards anchor premium pricing for EU Ship Recycling Regulation compliance, while spot transactions for non-EU flagged bulk carriers trade at discounts. Price differentiation hinges on certification tier and steel recovery rate guarantees, with plasma arc cutting commanding margins above oxy-fuel methods. Cost compression in beaching operations is intensifying because Bangladeshi yards face stranded asset risk from Hong Kong Convention alignment timelines. Cash buyers represent the most price-sensitive segment; German container operators with ESG audit protocols show least sensitivity.
Supply Chain Analysis
Alang-Sosiya cluster concentration in India, Chittagong corridor in Bangladesh, and Aliaga zone in Turkey control dismantling capacity for international feedstock. Raw material dependencies rest on Chinese construction steel demand, Indian re-rolling mill offtake agreements, and Turkish gas-cutting equipment imports. Single-source vulnerability concentrates in Bangladesh's beaching infrastructure lock-in. Distribution runs through cash-buyer intermediaries for non-EU flagged tonnage and direct owner-yard contracting for EU-mandated recycling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified welder shortages and enclosed gas-cutting bay deficits constrain yard expansion, creating acquisition premiums for facilities with certified technician pools and concrete quay infrastructure already in place.
For Market Incumbents: Harden EU Ship Recycling Regulation list positioning through accelerated dry dock conversions at Alang-Sosiya facilities before Hong Kong Convention enforcement tightens. Lock in long-term offtake agreements with German and Greek liner operators to defend against Turkish yard encroachment on Mediterranean feedstock. Vertical integration into hazardous waste decontamination services captures margin from asbestos and PCB removal bottlenecks. For New Entrants and Emerging Players: Establish a beachhead in wet recycling configurations serving flags with intermediate regulatory requirements between full EU compliance and beaching tolerance. Target Pakistani Gadani yards for modernization partnerships given lower capital barriers than Bangladeshi concrete quay investments. Lead with blockchain-based material tracking platforms to differentiate secondary steel sales to construction end-users requiring documented provenance. For Investors and Strategic Acquirers: Mid-scale Turkish facilities with existing EU certification and underutilized dry dock capacity represent the most defensible acquisition profile for capturing premium-priced Mediterranean tonnage. Monitor Hong Kong Convention ratification implementation timelines across Bangladesh, India, and Pakistan as the inflection signal for stranded asset risk realization in beaching-dependent yards.| Strategic Initiative | Industry Significance |
|---|---|
| Dry Dock Conversion Financing | Alang-Sosiya yard operators securing concrete quay investments capture EU-flagged container ship contracts from Chittagong competitors. |
| Plasma Arc Cutting Deployment | Chinese Zhoushan facilities reducing steel oxidation losses compress turnaround cycles and match Turkish premium pricing tiers. |
| Hazardous Waste Backward Integration | Veolia extending decontamination expertise into ship recycling captures margin from asbestos removal bottlenecks in cruise liner demolition. |
| Blockchain Material Tracking | Digital inventory platforms enabling certified secondary steel sales attract construction and automotive buyers requiring documented provenance. |
| Welder Certification Programs | Training initiatives in confined-space safety and toxic fume management address technician scarcity constraining enclosed gas-cutting expansion. |
Research Methodology
Two parallel data streams informed the analysis: structured interviews with shipbreaking yard operators, cash buyers, and EU maritime regulatory affairs officers, combined with secondary validation through EU Ship Recycling Regulation certified facility lists, Hong Kong Convention ratification documents, and IMO decarbonization pathway filings. Primary fieldwork captured facility investment timelines and labor pool constraints. Secondary sources included customs steel scrap trade data, Gujarat Maritime Board certification progress reports, and Bangladesh Ministry of Industries permit records. Bottom-up vessel retirement forecasts were triangulated against top-down steel recovery demand projections.
Forecast inputs considered recycling method adoption curves, flag-state enforcement divergence, and plasma arc cutting cost compression across the projection horizon. Segmentation dimensions modeled included vessel type, recycling method tier, end-user contracting structure, and geographic regulatory cluster. CAGRs were derived from interpolating certified yard capacity expansion against IMO fleet renewal deadlines. Industry-specific inputs incorporated EU Ship Recycling Regulation compliance cost trajectories and Hong Kong Convention insurance coverage unlock thresholds.
Stress conditions across Chinese construction demand cycles, Bangladeshi financing availability for dry dock conversions, and EU flag-state enforcement stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions on regulatory alignment timelines and technology adoption curves. Steel scrap price volatility, beaching infrastructure lock-in, and Basel Convention documentation bottlenecks represent specific risk factors that could revise projections. Quarterly review of EU certified facility list additions and Hong Kong Convention national implementation decrees is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Wire Mooring Ropes Market
Maritime Equipment
Global Maritime Safety Market
Maritime Equipment
Middle East Offshore Support Vessels Market
Maritime Equipment
Global Navigation Beacon Buoys Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
Ship Galley Equipment Market
Maritime Equipment
Integrated Bridge Systems (IBS) Market
Maritime Equipment
Global Shipbroking Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market
Maritime Equipment
China Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Europe Maritime Information Market
Maritime Equipment
Platform Supply Vessels (PSV) Market
Maritime Equipment
Marine Engine Monitoring System Market
Maritime Equipment
Hong Kong Stevedoring and Marine Cargo Handling Market
Maritime Equipment
Drill Ships Market