
 Automotive Chromium Finishing Market | 2026-2036
Automotive Chromium Finishing Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Chromium Finishing Market Intelligence
REACH is repositioning the cost-of-entry calculus for chromium finishers across Europe. Atotech leverages its trivalent chromium chemistry portfolio to anchor technology leadership in compliant decorative plating. Macdermid Enthone (Element Solutions, Inc.) sustains broad geographic coverage through integrated supply networks spanning North America and Asia. SRG Global dominates physical vapor deposition and chrome plating capacity for exterior trim programs at major OEMs.
Automotive chromium finishing applies thin metallic chromium layers onto substrates through electrochemical or physical deposition processes, typically achieving thicknesses of 0.1 to 1.0 microns for decorative applications and up to 500 microns for hard chromium wear resistance. The primary industrial purpose centers on delivering corrosion protection, aesthetic reflectivity, and surface hardness for visible and functional vehicle components. Electroplating occupies the largest process share due to established infrastructure and cost efficiency across high-volume exterior trim production. Trivalent chromium competes aggressively for regulatory-compliant decorative applications as OEMs phase hexavalent systems from their supply chains. Engine components and exterior trim concentrate margin pools where durability specifications and visual standards command premium pricing.
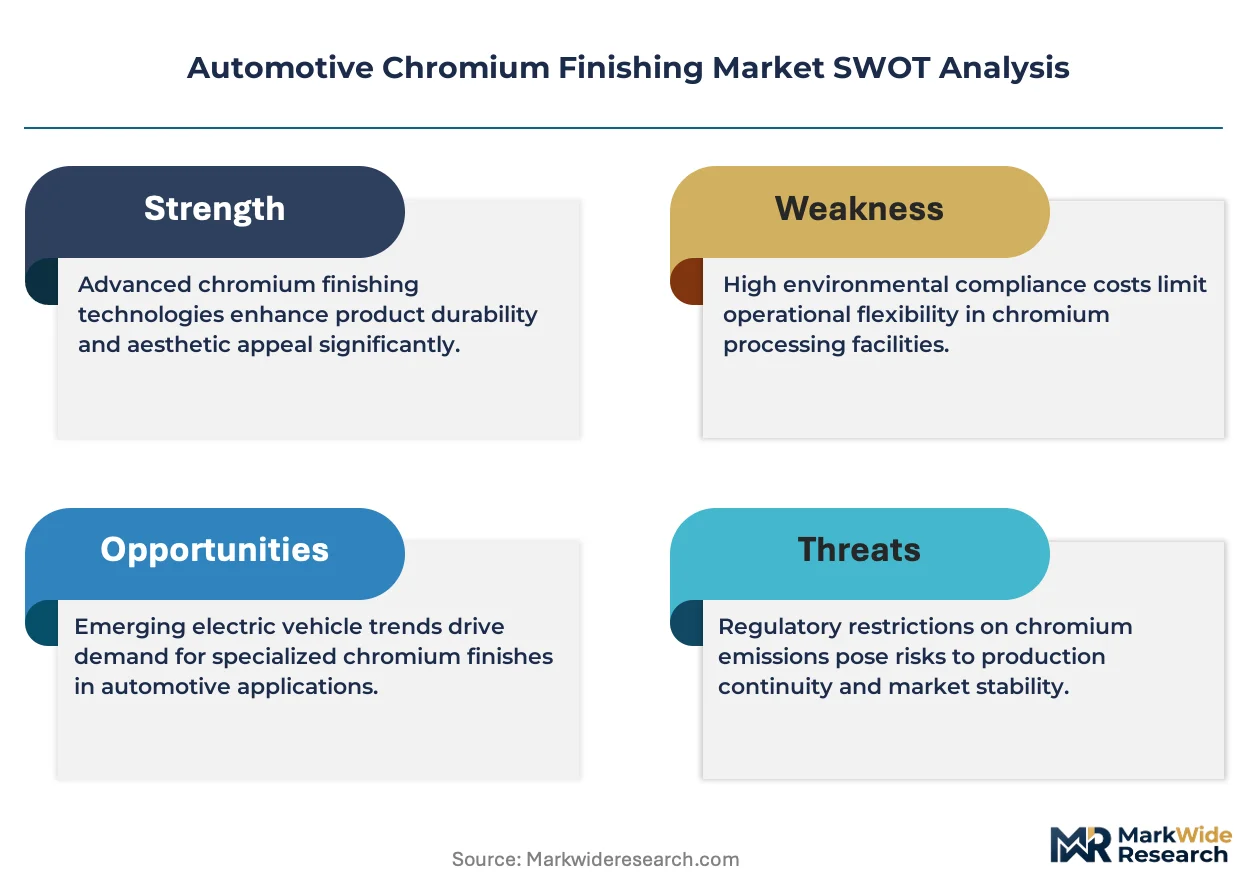
The EPA regulates hexavalent chromium emissions under Clean Air Act standards, while OSHA enforces permissible exposure limits in plating facilities that directly elevate capital requirements for air abatement and worker protection systems. ECHA's REACH authorization process continues restricting carcinogenic chromium VI compounds, compelling finishers to validate trivalent alternatives or exit European supply chains. China's MEE implements discharge standards for chromium-bearing wastewater that reshape plant location decisions and treatment technology investments. Stakeholders must monitor regulatory divergence between jurisdictions to avoid stranded process assets and misaligned capacity commitments.
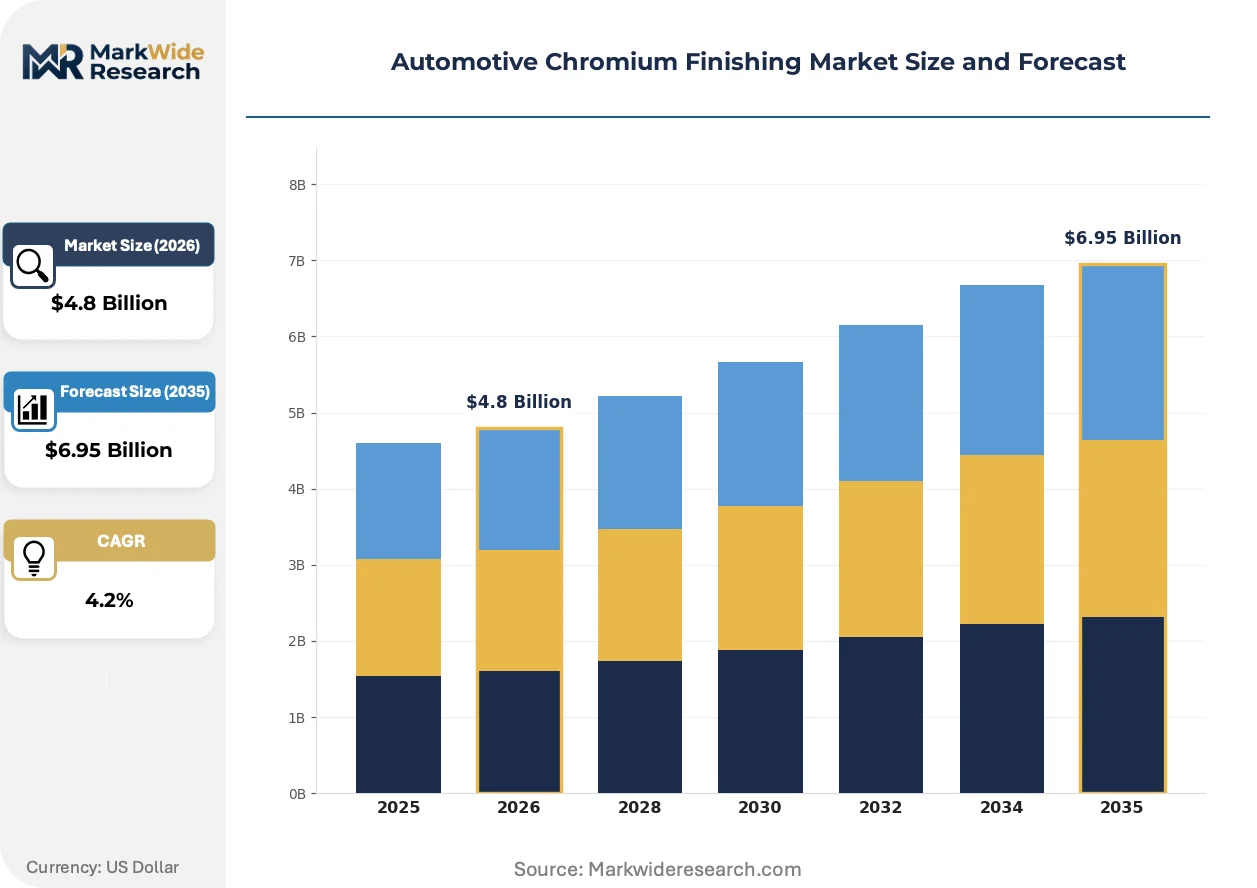
Market Dynamics
REACH authorization timelines for hexavalent chromium compounds are compressing technology transition windows across European supply chains, forcing finishers to validate trivalent process alternatives or surrender market position.
Growth Catalysts
- Luxury OEM Trim Programs:Premium vehicle manufacturers in Germany are expanding decorative chromium applications across exterior mirror housings, window surrounds, and grille assemblies.
- ECHA Authorization Pressure:REACH sunset dates for carcinogenic chromium VI compounds are accelerating voluntary conversion to compliant trivalent plating chemistries ahead of mandatory deadlines.
- Physical Vapor Deposition:PVD chromium nitride coatings are penetrating high-end wheel and badge applications where environmental credentials influence procurement scoring.
Market Restraints
- Capital Intensity:Trivalent chromium conversion requires fume extraction retrofitting, wastewater treatment upgrades, and air abatement systems that strain mid-tier finishing operations.
- Input Cost Volatility:Nickel sulfate and chromium metal pricing fluctuations compress margin predictability for decorative plating contractors serving volume exterior trim programs.
- Technical Limitation:Trivalent chromium deposits exhibit reduced throwing power compared to hexavalent systems, complicating uniform coverage on complex stamped substrate geometries.
Strategic Opportunities
- China MEE Discharge Standards:Stricter chromium-bearing wastewater limits are creating first-mover advantage for finishers deploying closed-loop ion exchange and membrane filtration systems in Jiangsu and Zhejiang manufacturing clusters.
- Electric Vehicle Differentiation:Battery-electric luxury platforms are specifying brushed or black chrome aesthetic variants to signal technological modernity against traditional bright finishes.
- Aftermarket Refinishing:Collision repair networks in the United States are consolidating purchasing power, creating channel leverage for certified trivalent process suppliers.
Industry Challenges
- Process Engineering Talent Scarcity:Qualified electroplating chemists and PVD technicians with cross-platform trivalent-hexavalent expertise command premium compensation in Germany's automotive corridor.
- Validation Timeline Compression:OEM corrosion and appearance specifications require 2,000+ hour neutral salt spray testing and accelerated weathering protocols that extend qualification cycles.
- Legacy Equipment Stranding:Hexavalent-dedicated tank lines and rectifier systems face accelerated depreciation as supply chain audits exclude non-compliant finishing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Chromium Finishing Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.95 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Process Type: Electroplating, Decorative Coating, Hard Chromium, Trivalent Chromium, Liquid Chrome Application: Engine Components, Interior Trim, Exterior Trim, Lighting Fixtures, Suspension Parts, Transmission Cases End User: OEMs, Aftermarket Suppliers, Tier-1 Manufacturers, Vehicle Assemblers Product Form: Plated Parts, Chromium Solutions, Coated Sheets, Powders, Pre-treated Components |
| Companies Covered | SRG Global, MICRO METAL FINISHING, Macdermid Enthone (Element Solutions, Inc.), Kakihara Industries Co., Ltd., American Electroplating Company, Atotech, Chem Processing, Inc., Custom Chrome Plating, Inc., Chromium Plating Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Chromium Finishing Market Strategic Shifts & Innovations
Process chemistry evolution and regulatory enforcement convergence are redefining competitive capability requirements across decorative and functional chromium applications.
Thin-film trivalent chromium deposits with nano-layered composite structures are absorbing decorative plating volume previously captured by hexavalent systems. Luxury OEMs in Germany and the United States are specifying these chemistries for exterior trim programs where corrosion resistance and optical clarity must match legacy performance. The technology is absorbing capital allocation from traditional plating line expansions as finishers prioritize compliance-ready capacity.
ECHA's REACH authorization process continues restricting chromium VI compounds through sunset clause enforcement and downstream user notification requirements. Plating contractors serving European automotive supply chains must demonstrate substitution feasibility or secure time-limited authorizations with stringent exposure controls. Decorative finishers with validated trivalent alternatives are capturing specification authority from hexavalent-dependent competitors.
Buyer consolidation among tier-one exterior trim suppliers is compressing supplier qualification cycles and elevating technical service expectations. Procurement teams at major German and Japanese automotive component manufacturers now require real-time process monitoring data and predictive maintenance integration. This pattern concentrates contract awards among finishers with digitized plating line controls and direct OEM technical relationships.
Automotive Chromium Finishing Market Segmentation
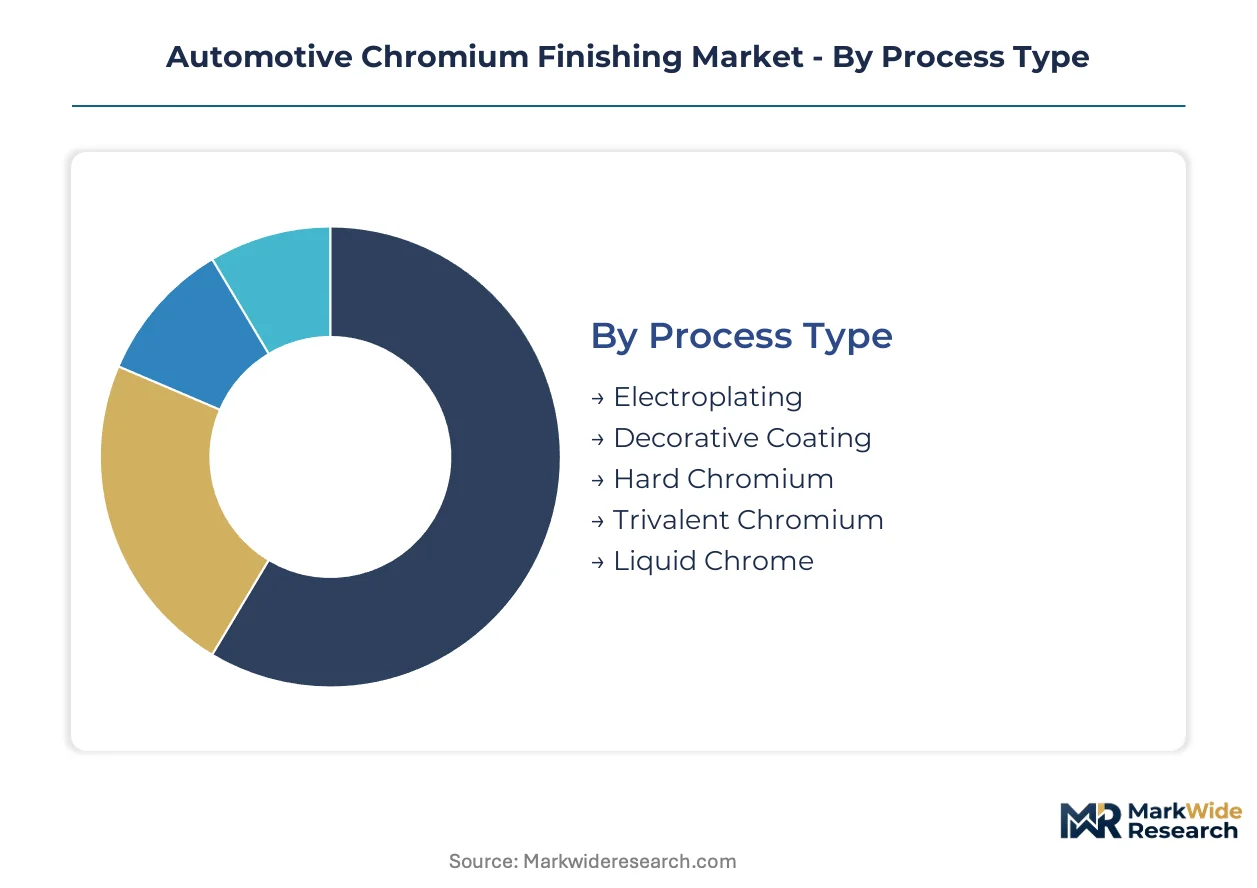
Automotive chromium finishing segments diverge sharply on capital requirements and regulatory exposure. Process type determines REACH compliance pathways. Application segments separate margin pools between visible aesthetics and functional durability.
Process Type:
Certification burdens cluster heavily on hexavalent-derived processes, with ECHA authorization timelines forcing validation documentation for chromium VI chemistries. Trivalent alternatives carry lighter authorization overhead but demand new equipment qualification.
- Electroplating:Established electrochemical deposition dominates high-volume exterior trim production with proven cost efficiency. German OEMs anchor specification authority here, though REACH sunset dates are compressing hexavalent-dependent line economics.
- Hard Chromium:Functional coatings achieving 500-micron thickness deliver wear resistance for suspension and transmission components. Demand concentrates in heavy-duty vehicle manufacturing corridors where durability specifications command premium pricing tiers.
- Trivalent Chromium:Regulatory-compliant decorative deposits with reduced toxicity profile.
- Decorative Coating:Thin-film aesthetic layers for visible interior and exterior surfaces.
- Liquid Chrome:Spray-applied metallic finishes for aftermarket refinishing applications.
Electroplating sits at the top of the volume ranking, with trivalent chromium climbing the fastest.
Application:
Margin structures separate sharply between cosmetic visibility and mechanical function. Exterior-facing applications carry stricter corrosion warranties and optical clarity specifications.
- Exterior Trim:Mirror housings, window surrounds, and grille assemblies demand 2,000+ hour neutral salt spray performance. German luxury OEMs are expanding bright chrome programs across electric vehicle platforms, though black chrome variants are penetrating battery-electric differentiation strategies.
- Engine Components:Piston rings, valve stems, and bearing surfaces require hard chromium for friction reduction and thermal tolerance. Demand clusters with commercial vehicle manufacturers specifying extended service intervals.
- Interior Trim:Decorative accents on dashboards, door handles, and control bezels.
- Lighting Fixtures:Reflective housings and bezel applications for headlamp and taillamp assemblies.
- Suspension Parts:Shock absorber rods and stabilizer links requiring wear resistance.
- Transmission Cases:Selective hard chromium on gear contact surfaces.
Exterior trim commands the steepest pricing tiers, while engine components deliver the most stable contract tenures.
End User:
Procurement sophistication varies dramatically across the value chain, with OEMs imposing real-time process monitoring requirements that strain mid-tier finishing operations.
- OEMs:Vehicle manufacturers specify chemistry systems and validate plating contractors through extended qualification cycles. German premium brands are consolidating supplier panels, favoring finishers with digitized line controls and direct technical relationships.
- Tier-1 Manufacturers:Exterior trim and lighting system integrators purchase finishing services as outsourced processing. These suppliers face compressed margins from OEM price-down schedules while absorbing capital costs for trivalent conversion.
- Aftermarket Suppliers:Collision repair networks and restoration specialists source refinished components.
- Vehicle Assemblers:Contract manufacturers with limited in-house finishing capability.
Tier-1 manufacturers transact the highest absolute volumes, with aftermarket suppliers expanding most quickly through US collision network consolidation.
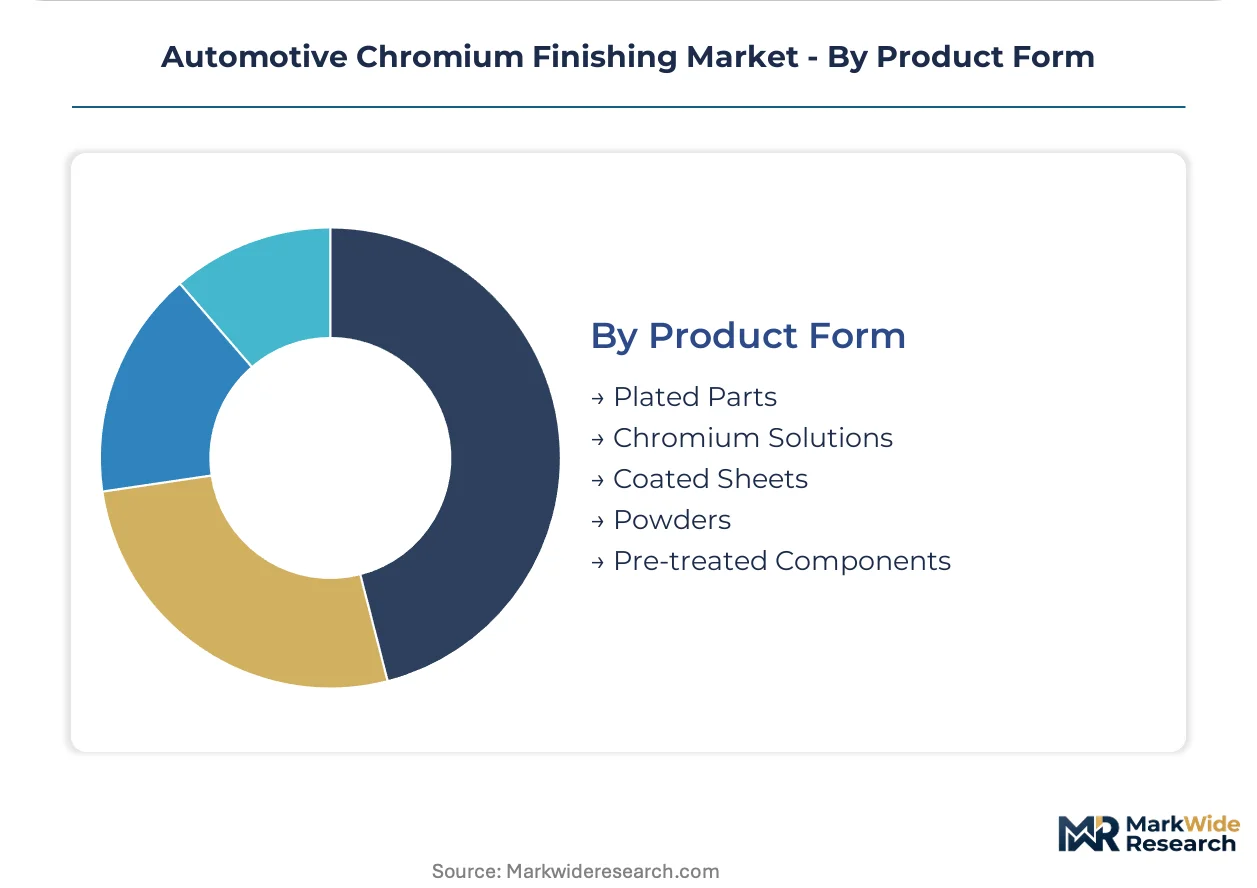
Product Form:
Supply chain configuration determines working capital intensity and logistics complexity across form factors.
- Plated Parts:Finished components ready for assembly integration dominate value capture. Stamped steel and zinc die-cast substrates move through dedicated tank lines at high-volume finishing facilities in Germany's automotive corridor.
- Pre-treated Components:Substrates with nickel underlayers awaiting final chromium deposition. These intermediate goods reduce lead times for assembly plants while concentrating technical risk at finishing specialists.
- Chromium Solutions:Proprietary plating chemistries and additive packages.
- Coated Sheets:Continuous coil-fed material for stamped trim applications.
- Powders:Thermal spray feedstock for specialized repair and refurbishment.
Plated parts represent the dominant value form, with pre-treated components gaining share fastest through just-in-sequence delivery contracts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled electroplating chemists and PVD technicians cluster in Germany's automotive corridor, anchoring Europe's decorative chromium finishing capacity. This workforce concentration shapes regional competitive dynamics as REACH deadlines compress conversion timelines. Demand patterns diverge sharply across major manufacturing geographies.
Germany
Luxury OEMs in Stuttgart and Munich are expanding bright chrome programs across electric vehicle platforms. ECHA's REACH sunset clauses for chromium VI compounds are forcing finishers in Baden-Württemberg and Bavaria to validate trivalent alternatives ahead of mandatory deadlines. The Neckar-Alb region hosts concentrated tank line capacity serving premium exterior trim programs.
United States
Collision repair network consolidation is driving aftermarket refinishing demand in Michigan and Ohio manufacturing belts. EPA Clean Air Act standards for hexavalent chromium emissions are elevating capital requirements for air abatement systems at plating facilities. Detroit-area finishers are absorbing tier-one exterior trim contracts as OEMs consolidate supplier panels.
China
Battery-electric luxury platforms in Shanghai and Shenzhen are specifying brushed chrome aesthetic variants for differentiation. MEE discharge standards for chromium-bearing wastewater are reshaping plant location decisions in Jiangsu and Zhejiang clusters. Yangtze River Delta finishers are deploying closed-loop ion exchange systems to capture first-mover advantage under stricter environmental enforcement.
Japan
PVD chromium nitride coatings are penetrating high-end wheel and badge applications from Nagoya-based component manufacturers. METI industrial standards are aligning with REACH-equivalent chemical management protocols for automotive suppliers. Kansai-region plating specialists are qualifying nano-layered trivalent deposits for export programs to European OEMs.
Mexico
Tier-one exterior trim suppliers in Nuevo León are expanding capacity to serve US-based OEM assembly operations. Mexican environmental regulators are adopting discharge standards modeled on EPA frameworks for border-region plating facilities. Monterrey-area finishers are capturing overflow demand as US contractors face compressed qualification cycles.
Automotive Chromium Finishing Market Key Industry Players
The competitive structure tilts toward chemistry specialists and integrated coating suppliers rather than fragmented job-shop operators. Three archetypes dominate: proprietary chemistry licensors with regulatory-compliant portfolios, high-volume electroplating contractors with OEM-direct relationships, and PVD technology specialists serving premium aesthetic programs. Consolidation is accelerating through chemistry-supplier acquisitions and tier-one supplier vertical integration into captive finishing capacity.
Among chemistry specialists, Atotech and Macdermid Enthone exemplify the regulatory-compliance archetype with trivalent chromium portfolios. SRG Global anchors the high-volume contracting tier with concentrated physical vapor deposition and chrome plating capacity for exterior trim programs. These three occupy positions spanning the technology-licensing-to-production-service spectrum, with each representing distinct capital intensity and customer integration models.
| Leading Market Players |
|---|
| SRG Global |
| MICRO METAL FINISHING |
| Macdermid Enthone (Element Solutions, Inc.) |
| Kakihara Industries Co., Ltd. |
| American Electroplating Company |
| Atotech |
| Chem Processing, Inc. |
| Custom Chrome Plating, Inc. |
| Chromium Plating Company |
| Others |
Cost & Logistics Intelligence
German luxury OEM procurement teams concentrate specification authority for exterior trim programs, compressing supplier margins through consolidated panel awards and real-time process monitoring mandates that favor integrated chemistry-to-coating providers over fragmented job-shop operators.
Pricing Analysis
Bundled trivalent chromium chemistry and finishing services command premium positioning against unbundled chemical supply and toll-plating arrangements. Pricing stratifies across REACH-compliant certification tiers, volume scale commitments, and direct OEM technical relationships. Cost compression in mid-tier decorative plating stems from nickel sulfate and chromium metal input volatility. Tier-1 exterior trim suppliers exhibit lowest price sensitivity due to pass-through mechanisms with OEMs, while aftermarket refinishing contractors face acute margin pressure from collision network consolidation.
Supply Chain Analysis
Freight costs for plated exterior trim components from Germany's Neckar-Alb region to Stuttgart and Munich assembly plants remain negligible against chemistry freight from North American specialty chemical producers. Supply concentrates in Germany, China, and Mexico, with raw material dependencies on nickel sulfate, chromium metal, and proprietary additive packages. Single-source vulnerability runs through Atotech and Macdermid Enthone chemistry licensing. Distribution runs through tier-1 exterior trim integrators with just-in-sequence delivery contracts to OEM assembly plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The automotive chromium finishing market represents a late-cycle quality story as battery-electric luxury platforms shift specification toward brushed and black chrome aesthetic variants that demand advanced trivalent process validation and nano-layered deposit expertise.
For Market Incumbents: Anchor market position through backward integration into proprietary trivalent chemistry licensing and captive PVD capacity expansion in Germany's automotive corridor. Defensive consolidation must address stranded hexavalent tank line assets as REACH sunset clauses accelerate depreciation. Priority investment rests on digitized plating line controls that satisfy OEM real-time monitoring requirements. For New Entrants and Emerging Players: Enter via certified trivalent process qualification for US collision repair network consolidation, where aftermarket refinishing demand outpaces compliant capacity. White-space targets include closed-loop ion exchange systems for China's Jiangsu and Zhejiang manufacturing clusters under stricter MEE discharge enforcement. Go-to-market positioning should emphasize environmental credential scoring for procurement evaluation frameworks. For Investors and Strategic Acquirers: Chemistry suppliers with validated REACH-compliant portfolios are the most active acquirer in this space, seeking captive finishing capacity to secure specification authority. Long-term viability hinges on trivalent process substitution completion and PVD technology maturation. Monitor ECHA authorization timeline compression as the critical inflection signal for stranded asset risk and consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Trivalent Chemistry Conversion | REACH sunset clauses for chromium VI compounds force capital reallocation toward compliant process validation. |
| PVD Capacity Expansion | Physical vapor deposition captures premium wheel and badge applications where environmental credentials influence procurement. |
| Closed-Loop Water Treatment | China's MEE discharge standards reward first-movers deploying ion exchange in Yangtze River Delta clusters. |
| Digital Line Control Integration | Real-time process monitoring satisfies tier-1 supplier technical service expectations from German and Japanese OEMs. |
| Aftermarket Network Certification | US collision repair consolidation creates channel leverage for trivalent-qualified refinishing contractors. |
Research Approach
Direct dialogue with tier-1 supplier procurement leads, OEM platform engineers, electroplating chemists, aftermarket distributors, and ECHA regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from SEC filings of listed chemistry suppliers, EPA Clean Air Act enforcement records, ECHA authorization databases, and vehicle production data from IHS Markit. Bottom-up plating line capacity assessments and top-down OEM trim program spend estimates were triangulated to anchor volume and value projections.
Bottom-up modeling of trivalent and hexavalent tank line capacity across Germany, the United States, China, Japan, and Mexico was cross-referenced against top-down OEM exterior trim program specifications and propulsion architecture shifts across the analysis window. Segmentation dimensions included process type, application visibility tier, end-user procurement sophistication, and product form factor. CAGRs were derived from regression analysis of historical plating chemistry volumes against vehicle production and regulatory enforcement milestones, with electric vehicle content-per-vehicle assumptions stress-tested against OEM platform announcements.
Inputs from ECHA authorization timelines and MEE discharge standard implementation schedules were available through the study window; gaps in proprietary chemistry pricing and tier-1 supplier contract tenures introduce uncertainty bands around margin structure projections. Forecasts reflect assumptions regarding REACH substitution feasibility and PVD cost curve progression. Stakeholders should weight assumptions against their own operating context and regulatory jurisdiction exposure.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Automotive Seat Climate Systems Market
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Automotive Windshield Market
Automotive Interior & Exterior
Automotive Mudguards Market
Automotive Interior & Exterior
Global Automotive Side Window Sunshades Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
China Automotive Sunroof Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Automotive Reconfigurable Body Panel Market
Automotive Interior & Exterior
Global Automotive Luggage Trim Market
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
Morocco Automotive Industry Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
North America Automotive Upholstery Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market