
 Automotive Shielding Market | 2026-2036
Automotive Shielding Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Shielding Market Intelligence
Aluminum-to-composite substitution in underbody thermal barriers is realigning cost structures across the supply base. Tenneco Inc. leverages its exhaust-system heritage to dominate high-temperature shielding architectures for internal combustion and hybrid platforms. Laird Performance Materials specializes in multi-layer electromagnetic interference solutions that anchor premium pricing in electric vehicle programs. Morgan Advanced Materials sustains technical differentiation through ceramic-fiber composites that tolerate sustained exposure above 1,000°C in exhaust-mounted applications.
Automotive shielding comprises engineered barriers—typically 0.1 to 3.0 millimeters thick, constructed from metallic foils, conductive polymers, or ceramic composites—that attenuate thermal flux, acoustic energy, or electromagnetic radiation from propagating into vehicle occupant zones or sensitive electronic systems. These assemblies protect battery enclosures from thermal runaway propagation, isolate cabin interiors from powertrain noise, and ensure electromagnetic compatibility between high-voltage drivetrains and infotainment architectures. Electromagnetic shielding for battery protection and wiring harnesses leads current demand as voltage architectures climb toward 800V in premium electric platforms. Acoustic shielding around engine components retains substantial volume in hybrid applications where internal combustion persistence creates dual-source noise challenges. Molded plastics and composite fabrics capture expanding share against traditional aluminum foil laminates as automakers pursue mass reduction targets without sacrificing attenuation performance.
The U.S. Federal Communications Commission enforces electromagnetic emissions limits that compel shielding upgrades in vehicles with advanced driver-assistance radar and V2X communication modules. The European Union's REACH regulation restricts certain halogenated flame retardants historically used in polymer-based shielding, accelerating reformulation investments across material suppliers. China's Ministry of Industry and Information Technology mandates GB-standard electromagnetic compatibility testing for all new energy vehicles prior to homologation. Stakeholders must monitor how divergent thermal-management requirements between solid-state and liquid-cooled battery chemistries reshape specification profiles for next-generation shielding architectures.
Market Dynamics
Electromagnetic compatibility mandates from EU and U.S. regulators are forcing wholesale redesigns of battery enclosure architectures as voltage platforms climb toward 800V, compressing development cycles and privileging suppliers with integrated thermal-EMI capabilities.
Growth Catalysts
- EU REACH Regulation:Restrictions on halogenated flame retardants in polymer-based shielding are accelerating reformulation investments, opening market share for ceramic-fiber and bio-based composite alternatives that meet flammability standards without restricted chemistries.
- China MIIT GB Standards:Mandatory electromagnetic compatibility testing for all new energy vehicles prior to homologation creates baseline demand for certified shielding assemblies across every battery-electric and plug-in hybrid platform sold in the world's largest automotive market.
- 800V Architectures:Premium electric vehicle programs migrating to high-voltage drivetrains require substantially upgraded electromagnetic shielding for battery enclosures and wiring harnesses, expanding specification scope and material intensity per vehicle.
Market Restraints
- Aluminum Price Volatility:Traditional foil-laminate shielding remains exposed to London Metal Exchange aluminum fluctuations, squeezing margins for suppliers without long-term smelter contracts or composite substitution strategies.
- Technical Ceiling on Polymer Conductivity:Carbon-filled polymer composites face intrinsic limits in attenuating high-frequency electromagnetic interference above 10 GHz, constraining their deployment in radar-rich autonomous vehicle platforms.
- REACH Compliance Friction:The European Chemicals Agency's substance evaluation timelines create 18-24 month certification delays for novel flame-retardant chemistries, freezing material innovation pipelines for shielding suppliers serving EU-bound vehicles.
Strategic Opportunities
- Solid-State Battery Thermal Profiles:Divergent thermal-management requirements between solid-state and liquid-cooled chemistries will reshape specification profiles, creating first-mover advantage for shielding architects with ceramic-fiber expertise rated above 1,000°C.
- U.S. IRA Domestic Content:Inflation Reduction Act battery component sourcing incentives are pulling shielding production toward North American manufacturing, rewarding localized supply base investments with federal tax credit eligibility.
- V2X Communication Modules:Vehicle-to-everything connectivity rollouts in Germany and Japan are generating incremental shielding demand for antenna isolation and radar coexistence, a specification layer absent from prior vehicle generations.
Industry Challenges
- Multiphysics Simulation Talent:Integrated thermal-acoustic-electromagnetic modeling requires scarce cross-functional engineers capable of coupling finite-element analyses across physics domains, elongating product development timelines.
- Legacy Platform Integration:Hybrid architectures retaining internal combustion powertrains demand dual-source noise isolation strategies that increase shielding complexity and part count without commensurate vehicle price premiums.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Shielding Market |
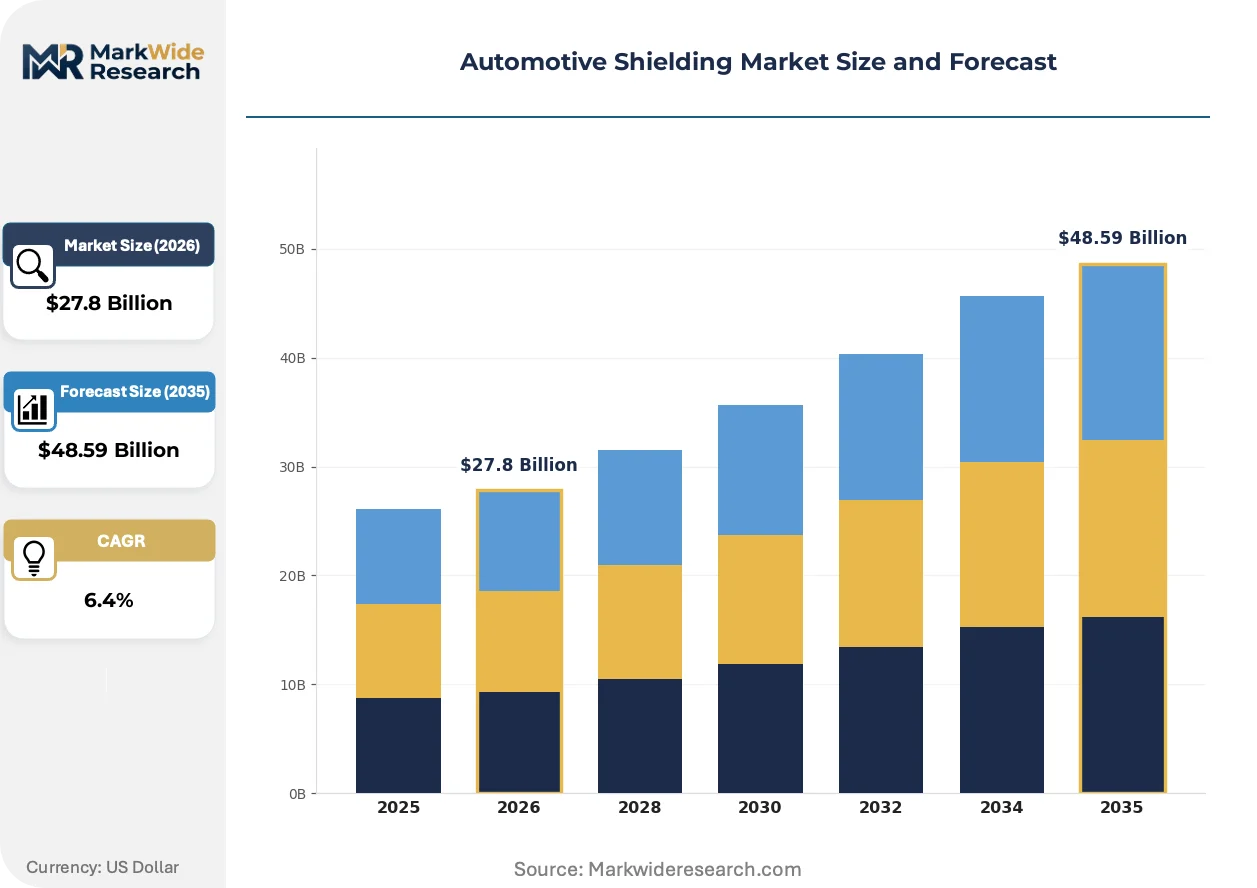
| Market Size in 2026 | $27.8 Billion |
| Market Size in 2035 | $48.59 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
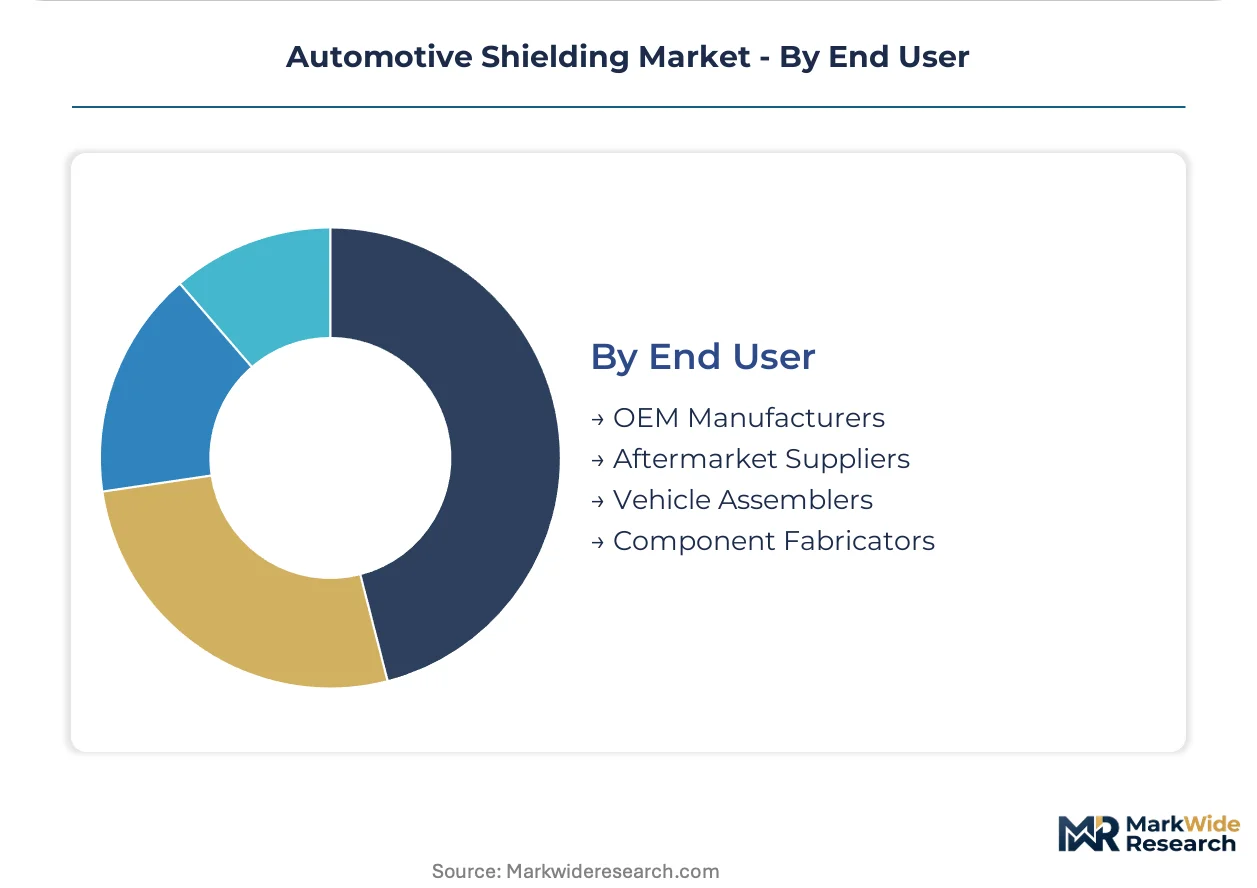
| Segmentation | Product Type: Thermal Shielding, Acoustic Shielding, Electromagnetic Shielding, Vibration Shielding Material: Foil Laminates, Molded Plastics, Composite Fabrics, Metallic Mesh, Polymer Films Application: Battery Protection, Engine Components, Exhaust Systems, Interior Cabin, Wiring Harnesses End User: OEM Manufacturers, Aftermarket Suppliers, Vehicle Assemblers, Component Fabricators |
| Companies Covered | Tenneco Inc., Laird Performance Materials, 3M Company, Dana Incorporated, Morgan Advanced Materials, Henkel AG & Co. KGaA, Autoneum Holding AG, ElringKlinger AG, Parker Hannifin Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Shielding Market Strategic Shifts & Innovations
Computational materials discovery and automated manufacturing are compressing the iteration cycle between shielding specification and validated production, collapsing traditional 36-month development programs into 18-month windows.
Multi-layer electromagnetic interference laminates are automating the qualification process for 800V battery enclosures. Tier-1 suppliers in Germany and South Korea are adopting these stacks at volume, replacing manual assembly of discrete aluminum-polymer-aluminum sandwiches. The technology is automating vendor selection criteria toward integrated material suppliers capable of co-developing thermal and electromagnetic architectures simultaneously.
REACH authorization requirements for medium-chain chlorinated paraffins are forcing reformulation of polymer-based acoustic shielding across EU-bound vehicle programs. The regulation is diverting R&D budgets toward halogen-free intumescent systems, with Spanish and Italian compounders capturing share from legacy suppliers slow to pivot. Battery-electric platforms with reduced engine noise signatures face the most acute substitution pressure, as cabin quietness expectations rise while traditional flame-retardant chemistries phase out.
Fleet procurement departments at European commercial vehicle operators are unbundling shielding specifications from powertrain supplier contracts, creating direct purchasing relationships with material specialists. This disintermediation is most visible in long-haul trucking electrification programs in Sweden and the Netherlands, where operators specify electromagnetic compatibility grades independently of battery pack integrators. Tier-2 shielding suppliers gain pricing leverage and technical dialogue access previously monopolized by system-level vendors.
Automotive Shielding Market Segmentation

Automotive shielding specifications diverge sharply across product categories, with thermal and electromagnetic variants commanding distinct certification pathways under EU REACH and China MIIT standards. Material selection and application placement determine whether suppliers pursue ECHA substance authorization or GB-standard electromagnetic compatibility testing.
Product Type:
Certification burdens cluster around electromagnetic and thermal variants, with EU REACH restricting halogenated flame retardants in polymer-based acoustic systems and China MIIT mandating GB-standard testing for all battery-adjacent electromagnetic shielding.
- Thermal Shielding:Ceramic-fiber and aluminum-foil laminates attenuate heat flux from exhaust systems and battery enclosures. OEMs in Germany and the United States specify these for hybrid powertrains where dual thermal sources complicate barrier design. REACH authorization timelines for medium-chain chlorinated paraffins are forcing reformulation of polymer-based thermal layers.
- Electromagnetic Shielding:Multi-layer conductive laminates and metallic meshes attenuate interference from 800V drivetrains and radar modules. China MIIT mandates GB-standard electromagnetic compatibility testing for all new energy vehicles, creating baseline demand across every battery-electric platform. Voltage architecture migration toward 800V expands material intensity per vehicle.
- Acoustic Shielding:Molded polymer composites and fiber-based absorbers isolate cabin interiors from powertrain noise. Engine noise persistence in hybrid applications sustains specification complexity.
- Vibration Shielding:Elastomeric isolators and constrained-layer dampers attenuate mechanical energy transmission. Battery pack mounting systems represent emerging specification territory.
Leading the category by volume: Thermal Shielding. Growing fastest: Electromagnetic Shielding.
Material:
Cost tiers separate foil laminates at the commodity end from composite fabrics commanding premium positioning, with aluminum price volatility squeezing margins on traditional metal-based solutions.
- Foil Laminates:Aluminum-polymer-aluminum sandwiches dominate exhaust-mounted thermal applications. London Metal Exchange aluminum fluctuations expose suppliers without long-term smelter contracts or composite substitution strategies.
- Composite Fabrics:Ceramic-fiber and bio-based matrices tolerate sustained exposure above 1,000°C while meeting REACH flammability standards without restricted chemistries. Spanish and Italian compounders capture share from legacy suppliers slow to pivot from halogenated systems.
- Molded Plastics:Carbon-filled polymers face intrinsic conductivity limits above 10 GHz, constraining deployment in radar-rich autonomous platforms. Halogen-free intumescent formulations are diverting R&D budgets.
- Metallic Mesh:Woven copper and nickel screens provide tunable electromagnetic attenuation across frequency bands. Wiring harness applications favor lightweight variants.
- Polymer Films:Thin conductive coatings on flexible substrates enable conformal shielding in space-constrained architectures. Roll-to-roll processing supports cost reduction at volume.
Volume concentrates in Foil Laminates. Margin expansion favors Composite Fabrics.
Application:
Application placement determines whether shielding integrates at Tier-1 system level or emerges as fleet-specified procurement, with European commercial vehicle operators increasingly unbundling specifications from powertrain contracts.
- Battery Protection:Enclosure-level thermal barriers and electromagnetic shields prevent thermal runaway propagation while ensuring high-voltage isolation. Solid-state and liquid-cooled chemistries impose divergent thermal-management requirements that reshape specification profiles.
- Engine Components:Acoustic and thermal barriers around internal combustion powertrains retain substantial volume in hybrid architectures. Dual-source noise isolation strategies increase part count without commensurate vehicle price premiums.
- Exhaust Systems:Ceramic-fiber composites tolerate sustained exposure above 1,000°C in exhaust-mounted applications. Tenneco Inc. leverages exhaust-system heritage to dominate this specification tier.
- Interior Cabin:Multi-layer acoustic treatments meet rising quietness expectations as battery-electric platforms eliminate engine noise masking. Cabin air quality regulations influence material selection.
- Wiring Harnesses:Electromagnetic shielding for high-voltage cabling ensures compatibility between drivetrains and infotainment architectures. 800V migration expands specification scope.
Revenue concentrates in Battery Protection. Specification innovation centers on Wiring Harnesses.
End User:
Procurement concentration varies by channel, with OEM manufacturers integrating shielding at platform design stage while aftermarket suppliers respond to collision repair and retrofit demand.
- OEM Manufacturers:Platform-level specification authority enables co-development of thermal and electromagnetic architectures. U.S. IRA domestic content incentives are pulling production toward North American manufacturing.
- Vehicle Assemblers:Final assembly integration of pre-validated shielding modules supports just-in-sequence delivery. German and South Korean volume producers automate vendor selection toward integrated material suppliers.
- Component Fabricators:Sub-tier specialists produce stamped, molded, or laminated shielding elements for system-level integrators. REACH compliance friction creates 18-24 month certification delays for novel chemistries.
- Aftermarket Suppliers:Collision repair and performance upgrade channels serve vehicle parc maintenance. Specification adherence to original homologation standards constrains product range.
Procurement volume concentrates with OEM Manufacturers. Channel expansion favors Vehicle Assemblers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in China's Yangtze River Delta and Germany's automotive corridors concentrate shielding manufacturing investments. These zones offer tax holidays and streamlined customs that attract composite material suppliers serving battery-electric platforms.
United States
Domestic battery assembly under the Inflation Reduction Act pulls shielding production toward Michigan and Ohio. The FCC enforces electromagnetic emissions limits that compel shielding upgrades in vehicles with advanced driver-assistance radar. Detroit-Warren-Dearborn anchors high-volume foil-laminate stamping for hybrid powertrains.
Germany
OEM platform engineering in Stuttgart and Munich drives specification authority for integrated thermal-EMI architectures. ECHA substance evaluation timelines for REACH compliance create certification bottlenecks for novel flame-retardant chemistries. Wolfsburg and Ingolstadt concentrate ceramic-fiber composite development for exhaust-mounted applications.
China
MIIT GB-standard electromagnetic compatibility testing mandates shielding across every new energy vehicle prior to homologation. Shanghai and Ningbo host automated multi-layer laminate production for 800V battery enclosures. Shenzhen suppliers specialize in conformal polymer-film shielding for space-constrained wiring harnesses.
Japan
METI-backed V2X communication rollouts in Kanto generate incremental shielding demand for antenna isolation and radar coexistence. Tokyo-Osaka corridor suppliers focus on thin metallic mesh variants for high-frequency electromagnetic attenuation. Nagoya-based fabricators serve Toyota and Honda hybrid programs with dual-source noise isolation systems.
South Korea
Seoul Capital Area battery pack integrators specify electromagnetic shielding for high-voltage cabling in 800V premium platforms. Domestic material suppliers automate vendor selection toward integrated thermal and electromagnetic co-development. Busan-Ulsan port infrastructure supports composite fabric imports for REACH-compliant halogen-free formulations.
Automotive Shielding Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with system-level integrators commanding premium pricing in battery protection while component fabricators compete on volume in acoustic applications. The market structures around three tiers: integrated material suppliers with co-development capabilities, legacy metal processors exposed to aluminum volatility, and emerging composite compounders capturing REACH-driven substitution. Consolidation pressure favors M&A between foil-laminate stampers and polymer compounders, alongside capacity expansion in North American free trade zones to capture IRA domestic content incentives.
Within the integrated material tier, Tenneco Inc., Laird Performance Materials, and Morgan Advanced Materials exemplify divergent specialization archetypes. Tenneco leverages exhaust-system heritage in high-temperature ceramic-fiber applications. Laird anchors premium positioning in multi-layer electromagnetic interference solutions for electric vehicle programs. Morgan sustains technical differentiation through composites rated above 1,000°C sustained exposure. These three represent the competitive spectrum from legacy thermal processing to next-generation electromagnetic architecture co-development.
| Leading Market Players |
|---|
| Tenneco Inc. |
| Laird Performance Materials |
| 3M Company |
| Dana Incorporated |
| Morgan Advanced Materials |
| Henkel AG & Co. KGaA |
| Autoneum Holding AG |
| ElringKlinger AG |
| Parker Hannifin Corporation |
| Others |
Cost & Logistics Intelligence
Fleet procurement departments unbundling shielding specifications from powertrain contracts are forcing suppliers to reconfigure fulfillment models, compressing lead times for certified electromagnetic assemblies while inflating premiums for REACH-compliant ceramic-fiber alternatives.
Pricing Analysis
Short-lead-time premiums for GB-standard certified electromagnetic shielding now command substantial markups over standard-cycle deliveries, while spot aluminum foil inventories trade at discounts reflecting London Metal Exchange volatility. Three-tier pricing structure across premium, standard, and economy levels separates integrated thermal-EMI co-development programs from commodity foil-laminate stamping, with OEM manufacturers least sensitive to price and aftermarket collision repair channels most vulnerable to cost compression. Pricing pressure stems from aluminum smelter contract scarcity squeezing legacy metal processors without composite substitution pathways.
Supply Chain Analysis
Dual-sourcing mandates from German OEM platform engineers require Tier-1 battery pack integrators to qualify electromagnetic shielding suppliers across at least two manufacturing regions, typically China and South Korea for automated multi-layer laminates. Raw material flows draw from aluminum smelters in Russia and Australia, ceramic-fiber precursors from Japanese specialty chemical producers, and conductive polymer resins from German compounders. Single-source vulnerability concentrates in high-purity copper mesh weaving capacity anchored in Japan. Distribution runs through just-in-sequence delivery to vehicle assembly plants in Michigan, Stuttgart, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GB-standard certification bottlenecks and REACH authorization timelines are constraining qualified supplier capacity, propping pricing power for shielding architects with pre-approved material platforms.
For Market Incumbents: Hedge aluminum price exposure through backward integration into composite fabric production or long-term smelter offtake agreements in Australia and Canada. Acquire ceramic-fiber compounders in Spain and Italy to capture REACH-driven substitution demand before ECHA evaluation timelines freeze competitor pipelines. Priority defensive moves center on securing MIIT pre-certification for 800V battery enclosure architectures. For New Entrants and Emerging Players: Direct-to-fleet digital procurement platforms offer the most penetrable route for electromagnetic shielding specialists targeting European commercial vehicle electrification programs in Sweden and the Netherlands. White-space exists in conformal polymer-film shielding for space-constrained wiring harness applications where Shenzhen suppliers currently dominate. Target V2X communication module isolation specifications in Germany and Japan as specification layers absent from prior vehicle generations. For Investors and Strategic Acquirers: The window for entry favors mid-cap composite material specialists with pre-validated REACH-compliant formulations and existing GB-standard certification. Long-term viability hinges on ceramic-fiber expertise rated above 1,000°C sustained exposure as solid-state battery thermal profiles diverge from liquid-cooled architectures. Watch ECHA substance evaluation timelines for medium-chain chlorinated paraffins as the inflection signal determining which compounders capture accelerated reformulation budgets.| Strategic Initiative | Industry Significance |
|---|---|
| REACH-Compliant Formulation Development | Halogen-free intumescent systems capture share from legacy suppliers facing ECHA authorization delays. |
| GB-Standard Pre-Certification Investment | MIIT electromagnetic compatibility mandates create baseline demand across every battery-electric platform sold in China. |
| North American Manufacturing Footprint Expansion | U.S. IRA domestic content incentives pull shielding production toward Michigan and Ohio battery assembly corridors. |
| Multi-Layer Laminate Automation | German and South Korean Tier-1 suppliers replace manual assembly with integrated material stacks for 800V enclosures. |
| Solid-State Battery Thermal Architecture Co-Development | Ceramic-fiber composites rated above 1,000°C secure first-mover advantage in next-generation battery protection specifications. |
Research Approach
Trade databases, regulatory filings with ECHA and MIIT, and automotive production statistics formed the secondary backbone, supplemented by primary interviews with Tier-1 supplier procurement directors, OEM platform engineers, aftermarket distributors, and ceramic-fiber compounder technical leads. Bottom-up and top-down triangulation validated segment-level estimates against vehicle production volumes and content-per-vehicle assumptions across thermal, electromagnetic, acoustic, and vibration shielding categories.
Bottom-up modeling built forecasts from individual application placements—battery enclosures, wiring harnesses, exhaust systems, engine components, and interior cabin treatments—aggregated across propulsion architectures and OEM tiers. Top-down cross-checks anchored aggregate market size to IHS Markit vehicle registration data and customs records of aluminum foil and conductive polymer trade flows. CAGRs were derived from regression analysis of historical specification intensity trends against voltage architecture migration timelines and regulatory mandate phase-in schedules across the analysis window.
Inputs from ECHA substance evaluation databases and MIIT homologation registries were available through the study window; gaps in solid-state battery thermal profile specifications introduce uncertainty bands around ceramic-fiber composite demand projections. Forecasts reflect assumptions regarding REACH authorization timelines, aluminum price corridor stability, and 800V platform adoption rates in premium electric vehicle programs. Deviation in ECHA medium-chain chlorinated paraffin evaluation outcomes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Safety and Security Systems
Automotive Black Boxes Market
Automotive Safety and Security Systems
Automotive Front-End Collision Warning System Market
Automotive Safety and Security Systems
India Airbag Systems Market
Automotive Safety and Security Systems
Brake System Market
Automotive Safety and Security Systems
Automotive Biometric Access System Market
Automotive Safety and Security Systems
Airbag Control Unit Sensor Market
Automotive Safety and Security Systems
Automatic Emergency Braking System (AEBS) Market
Automotive Safety and Security Systems
Car Safety Market
Automotive Safety and Security Systems
Collision Mitigation Technology Market
Automotive Safety and Security Systems
Automotive Blind Spot Monitors Market
Automotive Safety and Security Systems
Automotive Seat Belt Sensor Market
Automotive Safety and Security Systems
Automotive Keyless Entry Access Systems Market
Automotive Safety and Security Systems
Automotive Fire Suppression System Market
Automotive Safety and Security Systems
Asia Pacific Lane Departure Warning Systems Market
Automotive Safety and Security Systems
Park Assist System Market
Automotive Safety and Security Systems
Automotive Crash Barriers Market