
 Automotive Seat Recliners Market | 2026-2036
Automotive Seat Recliners Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Seat Recliners Market Analysis
Electrification of seat adjustment mechanisms is reshaping component architectures across the supply base. Toyota Boshoku Corporation anchors Japanese OEM relationships through integrated seat system capabilities. Hyundai Transys leverages captive demand from its parent automotive group while competing for external platform business. Magna International extends its recliner portfolio through modular designs that span multiple vehicle segments.
Automotive seat recliners are angular adjustment mechanisms, typically incorporating stamped steel housings, gear trains, and locking pawls, that enable controlled pivoting of seat backrests relative to cushion frames for occupant positioning and crash safety retention. Power recliners incorporate DC motors with position sensors and electronic control modules, while manual variants rely on cable-release or lever-actuated mechanical latching. Electric technology commands the dominant share of value generation as OEMs standardize memory-position and massage-integrated seating across mid-range trims, though mechanical recliners sustain volume leadership in emerging-market vehicle lines where cost minimization governs specification. Metal materials dominate structural load paths, yet plastic gear housings and fiber-reinforced levers are gaining specification in weight-sensitive electric vehicle programs.
NHTSA Federal Motor Vehicle Safety Standard 207 mandates seat back strength and recliner integrity thresholds for US-market vehicles, while EU CE marking under the Machinery Directive governs powered adjustment systems sold in Europe. China's MIIT enforces GB standards for automotive seat durability and electromagnetic compatibility of electric components. ECHA REACH restrictions on hexavalent chromium plating are forcing suppliers to convert to trivalent alternatives or zinc-nickel coatings across European supply chains. Stakeholders must monitor how battery-electric vehicle platform architectures, with their flat floor pans and extended wheelbases, are altering seat track and recliner packaging envelopes.
Market Dynamics
Electrification of seat adjustment mechanisms is collapsing traditional mechanical supply chains as OEMs consolidate electronic control module sourcing. Power recliner architectures now demand integrated motor-gearbox-sensor assemblies that displace discrete component procurement patterns.
Growth Catalysts
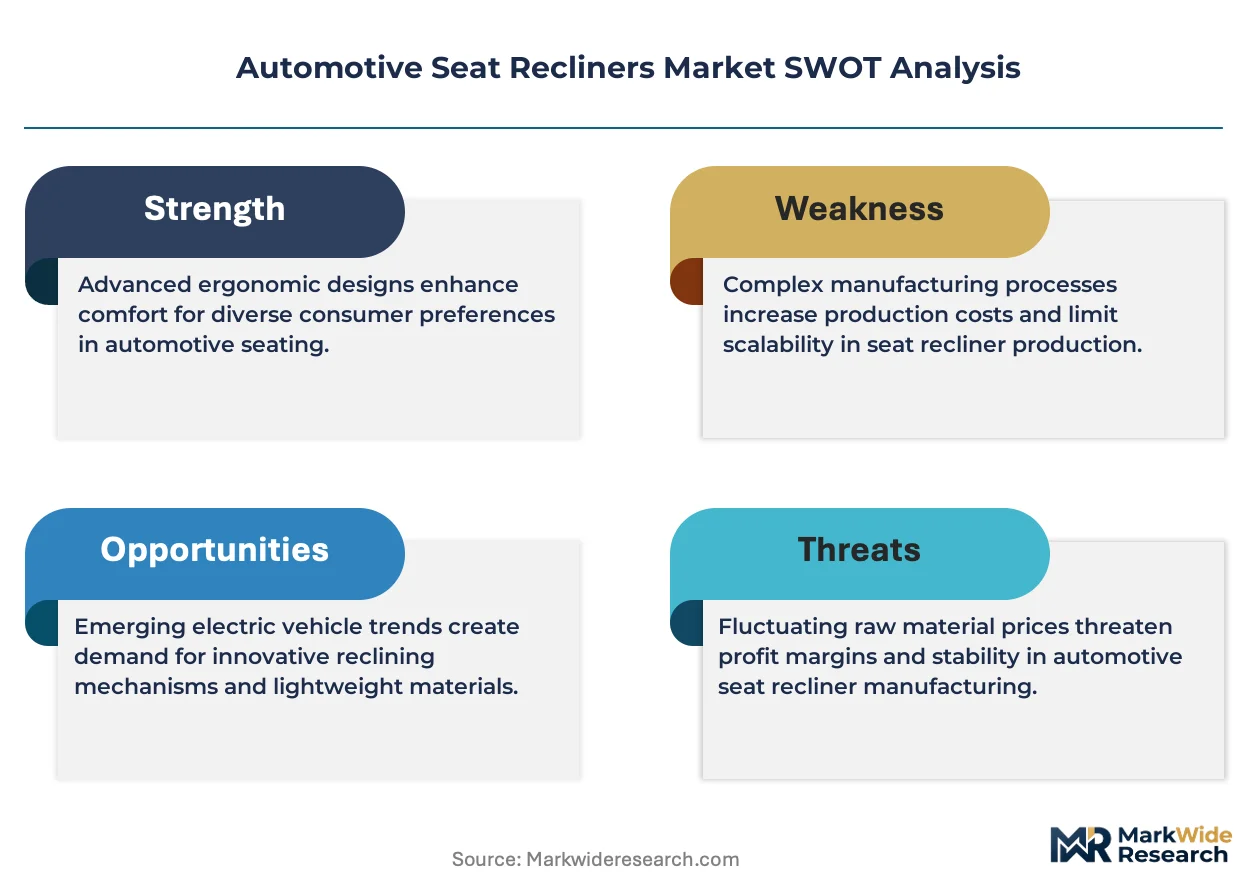
- EU Green Deal emissions standards:Accelerated lightweighting mandates are pulling fiber-reinforced polymer housings into premium electric vehicle seating programs across German OEM platforms.
- Memory-position functionality:Driver personalization features are standardizing across mid-range vehicle trims, expanding addressable component volumes beyond luxury segments.
- China:MIIT enforcement of GB standards for electromagnetic compatibility is formalizing supplier qualification barriers that favor established power seat system integrators.
Market Restraints
- Steel price volatility:Stamped metal housings remain dominant in cost-sensitive emerging-market vehicle lines, exposing margins to raw material input swings.
- Supplier concentration in East Asia:Gear train and motor subassembly capacity clusters in specific manufacturing regions, creating geographic risk exposure for Western OEMs.
- Trivalent chromium conversion costs:ECHA REACH restrictions on hexavalent plating are forcing capital expenditure on coating line retooling across European supply chains.
Strategic Opportunities
- India:PLI scheme incentives for automotive component manufacturing are opening localized sourcing pathways for seat mechanism suppliers targeting domestic OEM expansion.
- Massage-integrated seating:Convergence of pneumatic bladder systems with power recliner architectures is creating new content-per-vehicle expansion vectors.
- Recycled polymer specification:OEM sustainability procurement mandates are creating first-mover advantage for suppliers with validated post-consumer material feedstocks.
Industry Challenges
- Mechatronics engineering talent:Integration of DC motors, position sensors, and control firmware requires skill sets scarce in traditional mechanical component organizations.
- Homologation timeline compression:Parallel validation of electric recliners against NHTSA FMVSS 207 and EU Machinery Directive CE marking is extending program development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Seat Recliners Market |
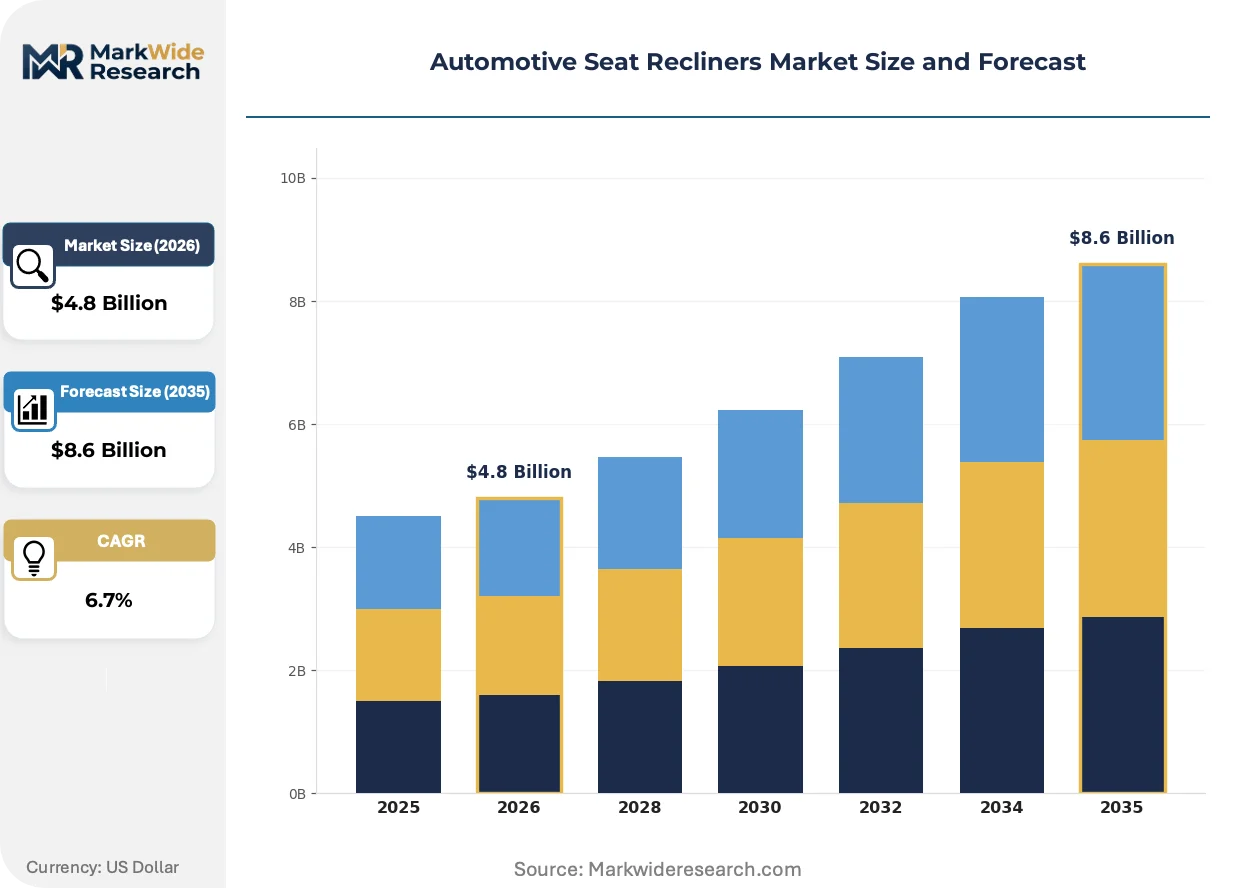
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
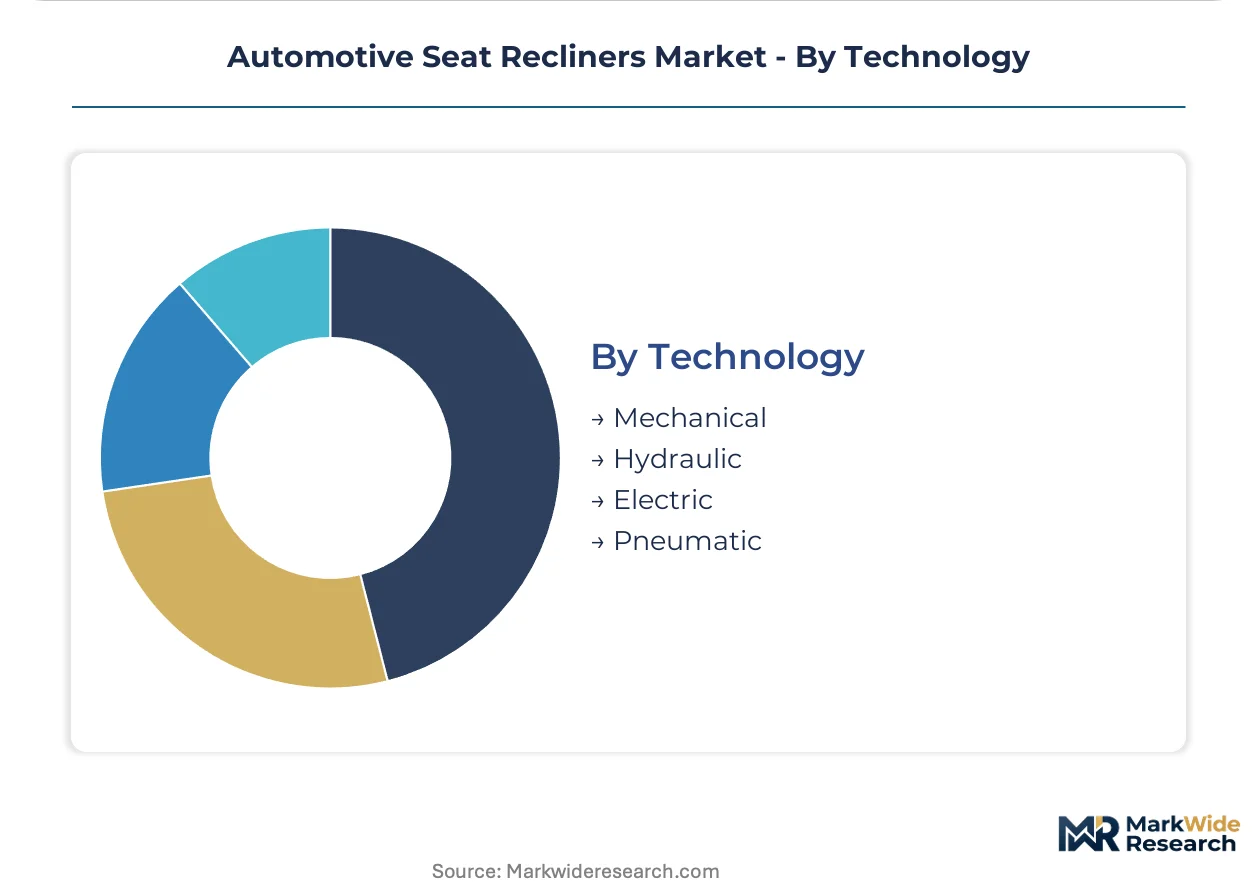
| Segmentation | Product Type: Manual Recliners, Power Recliners, Adjustable Recliners, Fixed Recliners End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers Material: Plastic, Metal, Leather, Fabric Technology: Mechanical, Hydraulic, Electric, Pneumatic |
| Companies Covered | Toyota Boshoku Corporation, Hyundai Transys, Adient, Fisher Dynamics, DAS Corporation, Lear Corporation, Magna International, Brose Fahrzeugteile, Faurecia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Seat Recliners Market Emerging Trajectories
Active safety integration and occupant sensing requirements are redefining recliner design specifications. Component architectures must now accommodate force-limiting functions and real-time position feedback that were absent from legacy mechanical systems.
Stamped steel gear housings are collapsing under pressure from die-cast aluminum and fiber-reinforced polymer alternatives that cut mass by thirty to forty percent. Premium electric vehicle programs at German and US OEMs are accelerating this material transition for range optimization. The structural consequence is compressing traditional metal stamping supplier margins while rewarding compounders with automotive thermoplastic qualifications.
REACH restrictions on hexavalent chromium are mandating coating chemistry conversions across European supply chains. Trivalent chromium and zinc-nickel alternatives now dominate new platform specifications, with qualification testing extending supplier development timelines. Power recliner mechanisms with exposed hardware are most affected, driving specification consolidation toward suppliers with proven alternative coating capabilities.
Fleet procurement of standardized seat architectures is compressing specification variety across rental and commercial vehicle channels. Bulk purchasing agreements now favor modular recliner designs that span multiple vehicle classes with minimal variant engineering. This concentration is most visible in North American fleet segments, where single-source supply contracts are displacing multi-supplier competitive bidding for seat system content.
Automotive Seat Recliners Market Segmentation
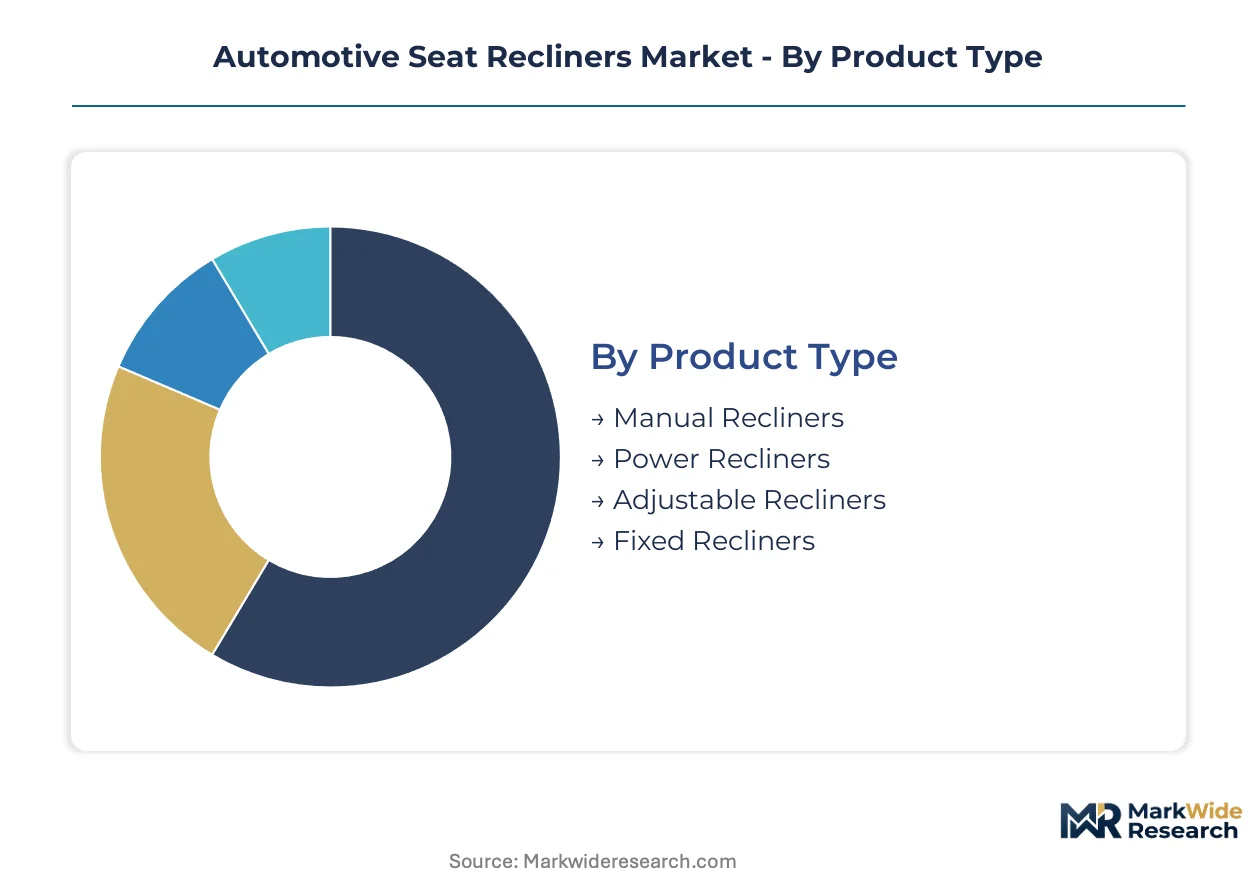
Seat recliner architectures fragment across powertrain integration levels, material specifications, and supply chain positions. Each segmentation axis reveals distinct margin structures and qualification barriers that shape supplier competitive positioning.
Product Type:
Powertrain sophistication spans cable-actuated mechanical systems through sensor-integrated electric architectures, with cost and functionality determining specification across vehicle tiers.
- Manual Recliners:Lever-actuated mechanical latching with stamped steel pawls and cable-release mechanisms dominate emerging-market vehicle lines. Cost minimization governs specification in India and Brazil where OEMs prioritize purchase price over feature content.
- Power Recliners:DC motor-gearbox-sensor assemblies with position memory and programmable stop points are standardizing across mid-range trims at German and US OEMs. Driver personalization features expand addressable component volumes beyond luxury segments.
- Adjustable Recliners:Multi-position detent systems with incremental angle locking serve commercial vehicle and fleet applications requiring durability under high-cycle use.
- Fixed Recliners:Welded-angle backrest structures without adjustment capability occupy entry-level economy vehicle lines and certain rear seating positions.
Established volume favors manual recliners; emerging adoption favors power recliners.
End User:
Supply chain position determines technical integration depth, with captive seat system divisions competing against independent component specialists for platform awards.
- OEMs:Vertical seat system divisions at Toyota, Hyundai, and Stellantis maintain in-house recliner sourcing for proprietary platform architectures. Captive production insulates against supply disruption while constraining external supplier market access.
- Tier-1 Suppliers:Independent specialists including Magna and Faurecia compete for platform business through modular designs spanning multiple vehicle segments. Component qualification against NHTSA FMVSS 207 and EU Machinery Directive CE marking creates barrier to entry.
- Aftermarket Providers:Replacement recliner mechanisms and repair kits serve vehicle aging populations in North American and European parc markets.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations procure seat systems on turnkey basis from integrated module suppliers.
Platform control concentrates with OEMs; modular sourcing expands through Tier-1 channels.
Material:
Mass reduction imperatives and coating chemistry regulations are restructuring material specifications across electric vehicle programs.
- Metal:Stamped steel housings and gear trains retain dominance in structural load paths. ECHA REACH restrictions on hexavalent chromium plating force conversion to trivalent alternatives or zinc-nickel coatings across European supply chains.
- Plastic:Fiber-reinforced polymer housings and glass-filled nylon levers cut mass thirty to forty percent versus steel equivalents. German OEM platforms specify these compounds for range optimization in battery-electric vehicles.
- Leather:Upholstery material selection affects recliner hardware packaging through thickness and friction coefficients in premium seating programs.
- Fabric:Textile coverings predominate in fleet and commercial vehicle specifications where durability and cleanability outweigh aesthetic considerations.
Structural duty retains metal dominance; weight-sensitive applications accelerate polymer substitution.
Technology:
Actuation mechanisms range from purely mechanical through electronically controlled, with integration complexity determining supplier capability requirements.
- Mechanical:Gear train and pawl-based latching without external power inputs sustains volume leadership in cost-sensitive vehicle lines. Stamped metal componentry and cable actuation minimize unit economics.
- Electric:Brushless DC motors with Hall-effect position sensing and CAN bus integration enable memory functions and active safety feedback. MIIT enforcement of GB standards for electromagnetic compatibility in China formalizes supplier qualification barriers.
- Hydraulic:Fluid-actuated positioning systems occupy niche applications requiring high force density in limited packaging envelopes.
- Pneumatic:Air bladder integration with recliner frames supports massage-integrated seating architectures at premium OEMs.
Mechanical systems anchor emerging-market volume; electric architectures climb fastest in technology-forward segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics in automotive seat recliners track closely with electric vehicle platform rollouts and regional regulatory divergence. Countries with integrated seat system manufacturing clusters dominate cross-border component flows, while regulatory fragmentation around chemical coatings and electromagnetic standards shapes sourcing patterns.
United States
NHTSA FMVSS 207 compliance requirements and domestic EV manufacturing expansion drive recliner specification volumes. The Inflation Reduction Act incentivizes localized component sourcing for battery-electric vehicle programs. Detroit-area automotive clusters anchor Tier-1 supplier engineering centers serving North American OEM platform development.
Germany
EU Green Deal lightweighting mandates and premium vehicle segment concentration elevate power-adjustable seating content per vehicle. ECHA REACH restrictions on hexavalent chromium plating force coating chemistry conversions across supplier networks. Stuttgart and Munich industrial corridors host recliner mechanism development centers for German OEM electric platforms.
China
MIIT enforcement of GB standards for electromagnetic compatibility and seat durability creates formalized supplier qualification barriers. Domestic electric vehicle platform proliferation expands addressable volumes for power recliner system integrators. Shanghai and Guangzhou manufacturing clusters concentrate gear train and motor subassembly capacity.
Japan
Captive seat system relationships at major domestic OEMs insulate internal supply chains while constraining external market access. METI industrial standards govern component durability testing protocols for automotive seating applications. Toyota City and Hiroshima production networks anchor vertically integrated recliner manufacturing for parent automotive groups.
India
PLI scheme incentives for automotive component manufacturing open localized sourcing pathways for seat mechanism suppliers. Cost-sensitive vehicle specifications sustain manual recliner volume leadership in domestic OEM lineups. Tamil Nadu and Gujarat automotive corridors attract foreign supplier joint ventures targeting export-oriented production.
Automotive Seat Recliners Market Vendor Landscape
On the supply side, the industry is consolidating around integrated seat system capabilities that collapse discrete component procurement patterns. Tier-1 suppliers compete through modular recliner architectures spanning multiple vehicle segments, while captive OEM divisions insulate against supply disruption. Three strategic archetypes dominate: vertically integrated seat system divisions, independent modular component specialists, and regional fabrication houses serving cost-sensitive markets. Competitive moves concentrate on coating chemistry qualification for regulatory compliance and mechatronics engineering capability acquisition.
Within the captive manufacturing tier, Toyota Boshoku Corporation and Hyundai Transys exemplify parent-group-aligned supply structures that internalize recliner production for proprietary platform architectures. Among independent specialists, Magna International occupies a position representing modular design capabilities that compete for external platform business across vehicle segments.
| Leading Market Players |
|---|
| Toyota Boshoku Corporation |
| Hyundai Transys |
| Adient |
| Fisher Dynamics |
| DAS Corporation |
| Lear Corporation |
| Magna International |
| Brose Fahrzeugteile |
| Faurecia |
| Others |
Supply Flow & Price Mechanics
Shanghai and Guangzhou manufacturing clusters concentrate gear train and motor subassembly capacity, concentrating pricing power with integrated power seat system suppliers who capture value from OEMs seeking electromagnetic compatibility pre-certification under MIIT GB standards.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that stratify across premium, standard, and economy tiers based on certification grade and volume scale. Pricing pressure stems from steel price volatility in stamped metal housings for emerging-market manual recliners, while electric architectures with memory-position functionality command premium positioning. Fleet procurement buyers exhibit highest price sensitivity, whereas German and US OEMs integrating massage-integrated seating demonstrate lowest sensitivity due to content-per-vehicle expansion mandates.
Supply Chain Analysis
Extended payment terms and supply-chain finance facilities from Tier-1 integrators draw from concentrated subassembly capacity in China, South Korea, and Japan. Raw material dependencies center on electrical-grade steel for gear housings, rare-earth magnets for DC motors, and glass-filled nylon compounds for lightweighting programs. Single-source vulnerability around Hall-effect position sensors creates structural risk exposure. Distribution runs through captive OEM seat system divisions and independent modular suppliers serving platform engineering centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechatronics engineering capability gaps separate suppliers qualified for power recliner integration from mechanical component specialists locked in emerging-market cost competition. The scarcity of firmware-integrated motor control talent concentrates margin capture with hybrid mechanical-electronic organizations.
For Market Incumbents: Pre-empt coating chemistry obsolescence by accelerating trivalent chromium and zinc-nickel qualification ahead of ECHA REACH enforcement timelines. Capture backward integration into rare-earth magnet sourcing to insulate against supply disruption from East Asian concentration. Defensive positioning requires modular recliner architectures that span battery-electric and internal combustion platforms without variant engineering penalties.
For New Entrants and Emerging Players: Establish a beachhead in India's PLI scheme corridors by partnering with domestic OEMs expanding electric vehicle lineups. White-space opportunity concentrates in fiber-reinforced polymer housing supply for German OEM lightweighting programs where validated post-consumer feedstocks create qualification barriers. Go-to-market positioning should emphasize coating chemistry conversion capabilities that compress European supplier development timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because power recliner architectures are collapsing discrete component procurement patterns into integrated motor-gearbox-sensor assemblies. Target acquisition profiles favor mechatronics-capable Tier-1 specialists with automotive thermoplastic qualifications and proven alternative coating capabilities. The signal to watch is MIIT GB standard enforcement intensity in China formalizing supplier qualification barriers that favor established integrators.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Modular recliner designs spanning multiple vehicle classes reduce variant engineering costs for OEMs. |
| Battery Supply Agreement | Electric vehicle platform rollouts expand addressable volumes for power seat system integrators. |
| Software-Defined Vehicle Investment | CAN bus integration and position sensing enable active safety feedback loops for NHTSA compliance. |
| Geographic Manufacturing Footprint | PLI scheme localization in India and Inflation Reduction Act incentives in the US reshape sourcing patterns. |
| Charging Infrastructure Partnership | Extended dwell times in electric vehicles elevate ergonomic seating priority and content-per-vehicle. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and Tier-1 supplier procurement patterns anchors the qualitative findings. Primary interviews with seat system program managers, recliner mechanism R&D directors, automotive thermoplastic compounders, and coating line operations supervisors combine with secondary validation from vehicle production databases, IHS Markit registration data, MIIT GB standard filings, and ECHA REACH restriction updates. Bottom-up component demand modeling triangulates against top-down OEM seating content analysis.
Calibration against historical platform rollout timelines and material substitution curves shapes the analytical framework across the projection horizon. Segmentation dimensions span propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs derive from fitted adoption curves for power recliner penetration by vehicle segment. Industry-specific inputs include ECHA coating chemistry conversion timelines and MIIT electromagnetic compatibility enforcement intensity.
Sensitivities concentrate around battery-electric vehicle platform rollout delays, steel price volatility impacts on manual recliner margins, and REACH restriction expansion beyond hexavalent chromium. Forecasts reflect documented assumptions regarding OEM lightweighting mandate adoption rates. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Expanded Polypropylene (EPP) Foam Market
Automotive Interior & Exterior
Automotive Air Purifier Market
Automotive Interior & Exterior
Automotive OE Bumper Cover Market
Automotive Interior & Exterior
Europe Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Cabin Insulation Material Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Automotive Auto Dimming Mirror Market
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Automotive Portable Refrigerator Market
Automotive Interior & Exterior
Automotive HVAC Market
Automotive Interior & Exterior
Automotive Cups and Glass Holder Market
Automotive Interior & Exterior
Automotive Pneumatic Seat System Market
Automotive Interior & Exterior
North America Automotive Upholstery Market
Automotive Interior & Exterior
Car Covers Market
Automotive Interior & Exterior
Global Automotive Windows and Exterior Sealing Market
Automotive Interior & Exterior
Japan Automotive Flooring Market