
 Smart Automotive Headlight Market | 2026-2036
Smart Automotive Headlight Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Automotive Headlight Market Analytics
Electric vehicle OEM procurement is shifting toward adaptive and matrix LED configurations as platform architectures integrate headlight control with ADAS sensor suites. Koito Manufacturing leverages its vertical integration into LED chip sourcing to sustain cost advantages across Japanese and North American supply chains. Valeo anchors European demand through specialized production of laser headlight modules for premium German automakers. Marelli competes on manufacturing scale, operating integrated lighting plants in Italy and Poland that serve multiple OEM platforms simultaneously.
Smart automotive headlights combine semiconductor light sources with real-time sensor feedback and electronic control units to dynamically adjust beam patterns, intensity, and direction based on traffic conditions, weather, and road geometry. These systems typically operate at color temperatures between 5,000K and 6,000K for LED variants, with matrix configurations employing 25 to 100 individually addressable segments for precise glare-free illumination of road surfaces. Factory-fitted installation dominates value capture given the complexity of integrating vision sensors, communication interfaces, and control algorithms with vehicle electrical architectures. Adaptive headlights represent the most mature product category with established regulatory homologation pathways, while laser headlights concentrate margin pools in ultra-premium segments where thermal management and optical precision justify substantial price premiums.
NHTSA in the United States, ECE under UN regulations in Europe, and Japan's MLIT collectively shape demand through divergent approval frameworks for adaptive driving beam technologies, with NHTSA's recent rulemaking permitting matrix beam systems creating regulatory momentum previously constrained by antiquated Federal Motor Vehicle Safety Standard 108. OEMs must navigate this fragmented compliance landscape where European type approval accepts broader functionality than current US interpretations, directly influencing product development roadmaps and regional launch sequencing. Stakeholders should monitor how pending harmonization discussions between NHTSA and UN-ECE working groups reshape the competitive viability of software-upgradable headlight platforms.
Market Dynamics
Matrix LED architectures are forcing a fundamental restructuring of supplier relationships as automakers demand real-time software control over beam patterns previously locked in hardware configurations. Tier-1 suppliers must now embed electronic control units with sufficient processing power to handle sensor fusion from camera, radar, and lidar inputs, compressing margins for component makers lacking semiconductor design capabilities.
Growth Catalysts
- NHTSA Rulemaking on Adaptive Driving Beams:The 2022 amendment to Federal Motor Vehicle Safety Standard 108 permits matrix beam systems in US vehicles, unlocking a regulatory pathway previously blocked by antiquated high-beam prescriptions.
- ADAS Sensor Suite Integration:Premium electric vehicle platforms now specify headlights as edge-computing nodes that preprocess visual data for central driver-assistance controllers, elevating lighting modules from passive components to active system participants.
- EU F-Gas Regulation Phase-Down:Tightening restrictions on fluorinated greenhouse gases used in headlamp sealing and thermal management are accelerating adoption of solid-state LED and laser configurations that eliminate gas-dependent components.
Market Restraints
- Silicon Carbide Substrate Shortage:High-brightness LED and laser diode production depends on SiC wafers where supply concentrates among Japanese and US substrate manufacturers, exposing lighting suppliers to input cost volatility and allocation rationing.
- Homologation Fragmentation:Divergent UN-ECE, NHTSA, and Japan MLIT approval frameworks for adaptive beam functionality force redundant engineering cycles and delay platform launches by 12-18 months in non-harmonized markets.
- Halogen Incumbency in Entry Segments:Cost-optimized vehicle platforms in emerging markets continue specifying conventional reflector headlights, capping addressable volume for smart lighting technologies below mass-market price thresholds.
Strategic Opportunities
- Software-Upgradable Headlight Platforms:Over-the-air update capability enables automakers to monetize beam-pattern enhancements post-sale, transforming lighting from a one-time component sale into a recurring revenue stream tied to feature activation.
- India PLI Scheme for Auto Components:Production-linked incentives for advanced automotive electronics manufacturing are attracting module assembly investments to serve domestic OEMs and export markets with localized cost structures.
- V2X Communication Integration:Vehicle-to-everything protocols allow headlights to broadcast intent signals to pedestrians and other road users, opening new functional domains beyond illumination into active safety communication.
Industry Challenges
- Optomechanical Design Talent Scarcity:The intersection of precision optics, thermal engineering, and embedded software requires specialists rarely produced by conventional automotive or electronics degree programs, inflating compensation costs in Germany and Japan.
- Legacy 12V Electrical Architecture Constraints:Smart headlight power demands for matrix switching and active cooling exceed the capacity of older vehicle platforms, forcing expensive dual-voltage redesigns or feature degradation in retrofit applications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Automotive Headlight Market |
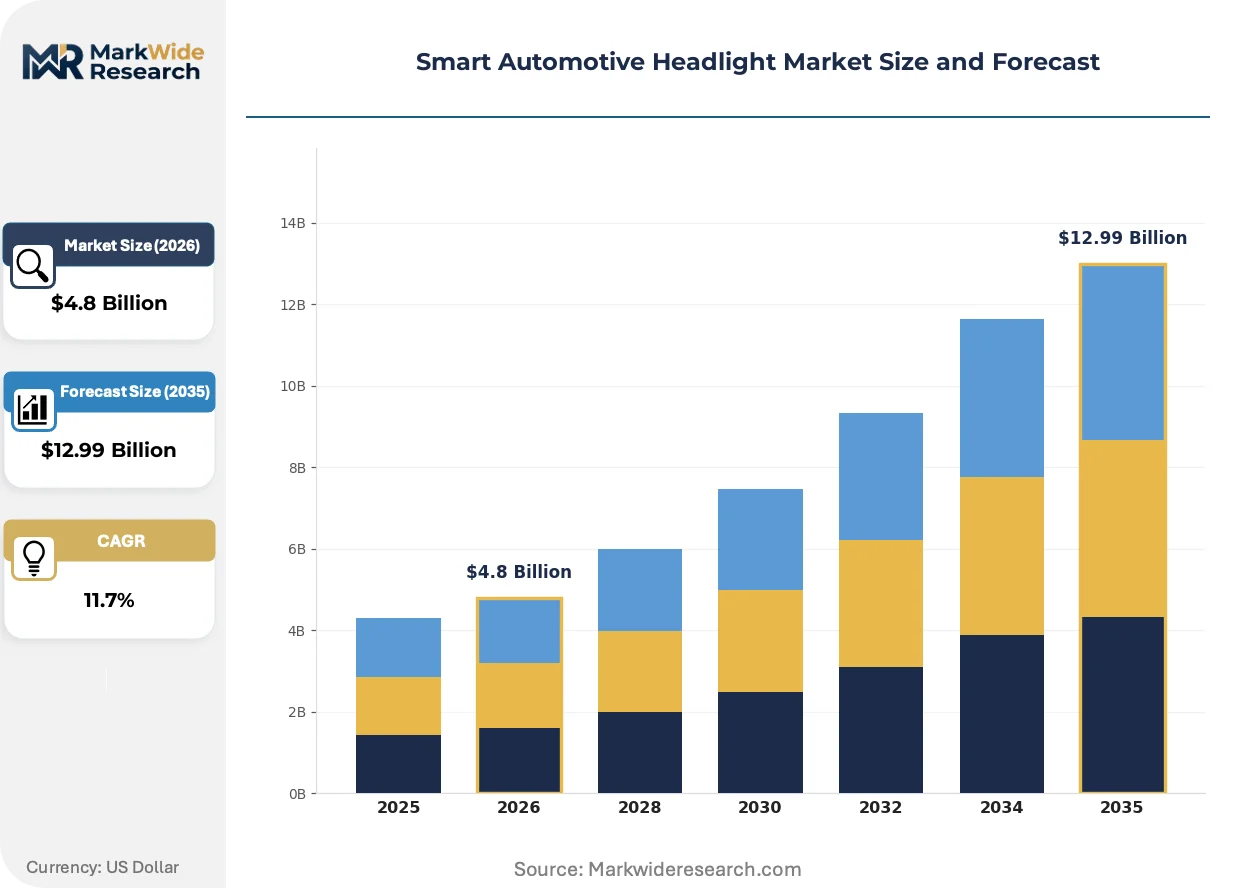
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adaptive Headlights, Matrix LED, Laser Headlights, Xenon Headlights Technology: Vision Sensors, Communication Interfaces, Control Algorithms, Power Management End User: OEMs, Aftermarket Suppliers, Vehicle Assemblers, Fleet Operators Installation: Factory-Fitted, Retro-Fit Solutions, DIY Kits, Integrated Units |
| Companies Covered | Marelli, ZKW Group, Koito Manufacturing, Hyundai Mobis, Varroc, Valeo, Stanley Electric, Forvia, Hella, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Automotive Headlight Market Evolving Landscape
Digital light processing is collapsing the traditional separation between lighting hardware and vehicle software stacks, enabling beam characteristics to evolve throughout a vehicle's operational life rather than remaining fixed at factory calibration.
Micro-LED arrays with individually addressable pixels are modularizing headlight construction by replacing monolithic projectors with tiled emitter matrices. Premium German automakers now specify 25,000+ pixel densities for glare-free high-beam masking. This granularity is modularizing supplier tiers, allowing semiconductor foundries to displace traditional lamp housing specialists in value capture.
Europe's ECE R48 revision and UN Regulation 149 are harmonizing type-approval requirements for adaptive driving beam systems across 56 contracting parties. The regulatory convergence is compressing homologation timelines for multinational platform launches. Asian OEMs targeting European export markets are accelerating matrix LED adoption to preempt compliance-driven redesign cycles.
Fleet procurement of smart lighting as a service component rather than capital equipment is emerging in commercial vehicle segments. Truck operators in North America now negotiate lighting performance guarantees bundled with maintenance contracts. This reconfiguration concentrates specification authority with fleet managers rather than OEM platform engineers, shifting technical requirements toward durability metrics and standardization across vehicle classes.
Smart Automotive Headlight Market Segmentation
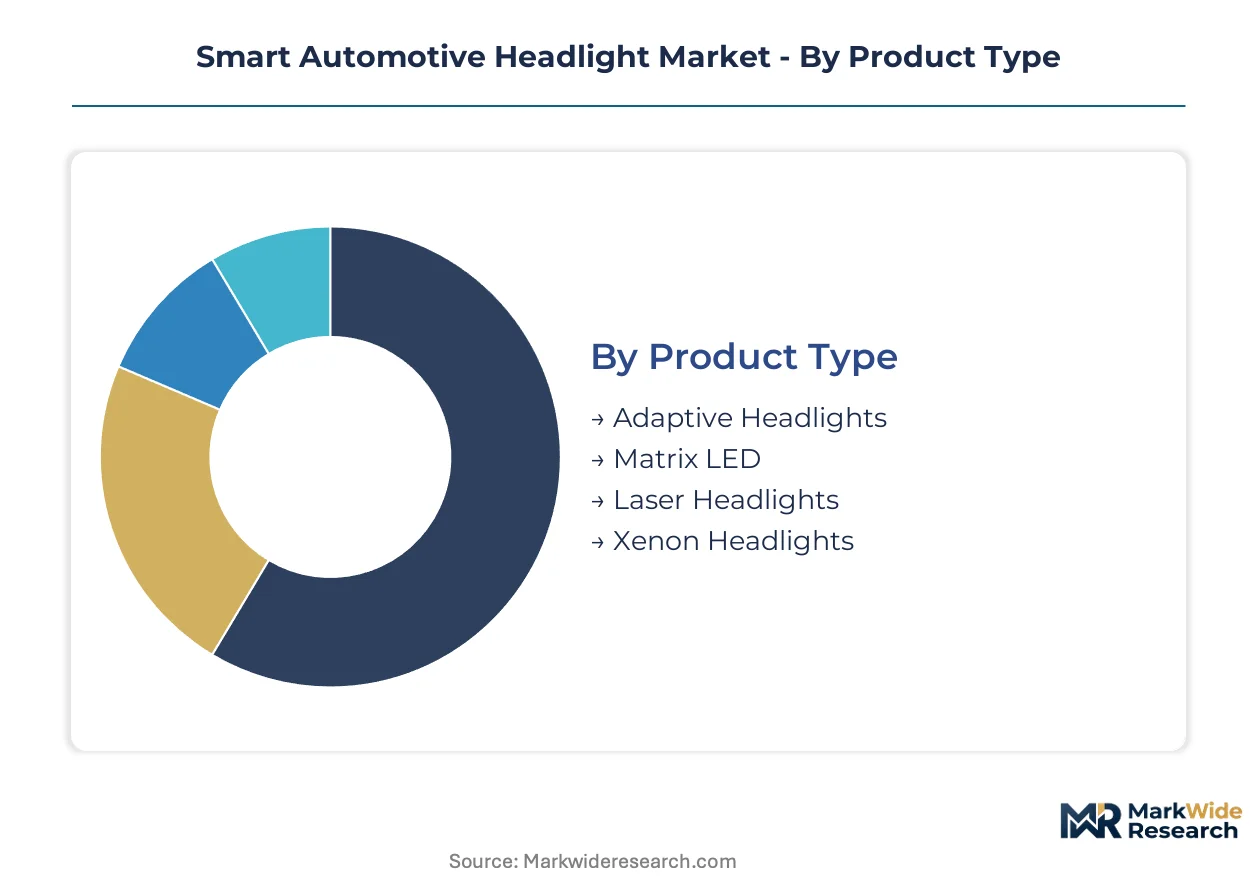
Smart automotive headlight segmentation reflects divergent technical maturity, regulatory acceptance, and integration complexity across vehicle platforms. Product type and installation method determine margin capture, while technology stack and end-user channel shape competitive positioning.
Product Type:
Cost tier and performance specification separate buyers, with thermal management capabilities and optical precision driving platform selection.
- Adaptive Headlights:Motorized reflector or projector units that pivot beam direction based on steering angle, vehicle speed, and suspension load. Demand concentrates among German and Japanese OEMs integrating these with entry-luxury sedans where regulatory homologation pathways are established. ECE R48 compliance requirements favor this category's deployment across European platforms.
- Matrix LED:Solid-state arrays with 25 to 100+ individually addressable segments enabling glare-free masking of oncoming vehicles. Premium electric vehicle platforms in South Korea and the United States specify these as edge-computing nodes preprocessing visual data for central ADAS controllers. NHTSA's amended Federal Motor Vehicle Safety Standard 108 recently unlocked US regulatory approval.
- Laser Headlights:Diode-pumped solid-state sources delivering 2,000+ meter throw distances with minimal thermal load. Ultra-premium German automakers dominate procurement for high-performance vehicle segments where optical precision justifies substantial price premiums.
- Xenon Headlights:High-intensity discharge arc lamps operating at 35W with 3,000+ lumen output. Emerging market vehicle assemblers in India and Brazil continue specifying these for cost-optimized platforms below smart lighting price thresholds.
Volume sits with Adaptive Headlights; growth tilts toward Matrix LED.
Technology:
Application complexity and semiconductor content differentiate supplier capabilities, with software-defined functionality displacing hardware-locked configurations.
- Vision Sensors:Camera modules capturing real-time traffic, weather, and road geometry data for beam pattern adjustment. OEMs in Germany and the United States demand preprocessing capability at the headlight node to reduce central controller latency.
- Communication Interfaces:CAN-FD and Ethernet protocols enabling sensor fusion between lighting modules and vehicle electrical architectures. Fleet operators in North America prioritize standardized interfaces across vehicle classes to simplify maintenance protocols.
- Control Algorithms:Embedded software determining beam intensity, direction, and masking logic based on fused sensor inputs. Over-the-air update capability is transforming this from factory-fixed code into monetizable post-sale feature activation.
- Power Management:DC-DC converters and active cooling systems handling 100W+ peak loads from high-brightness LED and laser configurations. Silicon Carbide substrate shortages among Japanese and US manufacturers expose lighting suppliers to input cost volatility.
Procurement weight rests with Power Management; algorithm differentiation is climbing fastest.
End User:
Customer type determines specification authority, with platform engineers, fleet managers, and individual owners imposing divergent technical requirements.
- OEMs:Original equipment manufacturers integrating headlights at vehicle design phase with full ADAS sensor suite coordination. German and South Korean automakers localize production near electric vehicle assembly plants to compress logistics costs.
- Aftermarket Suppliers:Independent distributors serving collision repair and vehicle customization channels. India's PLI scheme for auto components is attracting module assembly investments to serve domestic demand and export markets.
- Vehicle Assemblers:Contract manufacturers building vehicles under license for regional markets. These buyers prioritize standardization across multiple OEM platforms to achieve manufacturing scale.
- Fleet Operators:Commercial truck and bus owners negotiating lighting performance guarantees bundled with maintenance contracts. North American operators now concentrate specification authority away from OEM engineers toward durability-focused procurement.
Revenue concentrates with OEMs; fleet contracting is expanding most quickly.
Installation:
Integration depth and electrical architecture compatibility shape buyer trade-offs between feature completeness and retrofit feasibility.
- Factory-Fitted:Headlights installed during vehicle assembly with full sensor integration, calibration, and warranty coverage. This channel captures dominant value given the complexity of embedding vision sensors and control algorithms with vehicle electrical architectures.
- Retro-Fit Solutions:Professional installation of smart lighting onto existing platforms with adapter harnesses and controller modules. Legacy 12V electrical architecture constraints limit functionality for matrix switching and active cooling in older vehicles.
- DIY Kits:Consumer-installed LED bulb replacements and simplified controller units. These products sacrifice adaptive functionality for price accessibility in emerging market entry segments.
- Integrated Units:Pre-assembled headlight assemblies with embedded electronics reducing installation complexity. Aftermarket suppliers in Europe favor these for collision repair where ECE type approval simplifies regulatory compliance.
Factory-Fitted commands margin; Retro-Fit Solutions are gaining share fastest.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany manufactures smart headlight systems for export while South Korea and the United States concentrate consumption among domestic electric vehicle platforms. Production localizes near electric vehicle assembly plants to compress logistics costs and align with platform integration timelines.
Germany
Premium automakers in Stuttgart and Munich specify matrix LED and laser configurations for high-performance vehicle segments. ECE R48 standards under UN regulations establish type-approval pathways that German OEMs leverage for European platform launches. Supplier clusters in Bavaria and Baden-Württemberg host specialized production of laser headlight modules with precision optical engineering capabilities.
South Korea
Domestic electric vehicle manufacturers integrate adaptive beam technologies as standard equipment on flagship platforms. MFDS-equivalent automotive safety regulations align with UN-ECE frameworks to accelerate homologation for export markets. The Seoul Capital Area concentrates module assembly investments to serve Hyundai-Kia production networks and regional OEM supply contracts.
United States
NHTSA's amended Federal Motor Vehicle Safety Standard 108 now permits matrix beam systems, unlocking regulatory pathways previously blocked by antiquated high-beam prescriptions. Michigan and Tennessee assembly plants localize smart headlight procurement for domestic electric vehicle production. Tier-1 suppliers embed electronic control units with sensor fusion capabilities to meet ADAS integration requirements from Detroit-area platform engineers.
Japan
MLIT approval frameworks for adaptive driving beam technologies diverge from UN-ECE interpretations, forcing redundant engineering cycles for export-oriented platforms. Kanto and Chubu regions maintain LED chip sourcing advantages through substrate manufacturing relationships. Koito Manufacturing leverages captive supply of semiconductor components to sustain cost positions across Japanese and North American supply chains.
India
PLI scheme incentives for advanced automotive electronics attract module assembly investments to serve domestic OEM demand and export markets. Vehicle assemblers in Maharashtra and Tamil Nadu specify smart lighting for premium platforms while cost-optimized segments retain halogen configurations. Aftermarket suppliers concentrate in Delhi-NCR and Gujarat to address collision repair and customization channels with localized cost structures.
Smart Automotive Headlight Market Competitive Landscape
Top-tier vendors anchor premium platform supply, while mid-scale specialists compete on manufacturing flexibility and regional cost positioning. The market structure reflects consolidation among full-system integrators alongside fragmentation in component supply. Three archetypes dominate: vertically integrated lighting specialists with semiconductor capabilities, diversified automotive suppliers leveraging scale across multiple OEM platforms, and regional fabricators capturing aftermarket and emerging market volume. Competitive moves concentrate on backward integration into LED chip sourcing and strategic partnerships for ADAS sensor fusion software.
Within the integrated specialist tier, Koito Manufacturing and Valeo exemplify divergent geographic anchoring strategies. Koito represents Japanese supply chain integration with captive LED component production, while Valeo occupies a position as a European-centered full-system supplier. Marelli sits within the scale-driven diversified tier, operating integrated lighting plants serving multiple OEM platforms simultaneously. These three companies illustrate how competitive positioning splits between semiconductor-backed precision engineering and manufacturing scale advantages.
| Leading Market Players |
|---|
| Marelli |
| ZKW Group |
| Koito Manufacturing |
| Hyundai Mobis |
| Varroc |
| Valeo |
| Stanley Electric |
| Forvia |
| Hella |
| Others |
Value Network & Pricing Analysis
Silicon Carbide wafer costs cascade through smart headlight manufacturing, concentrating margin pressure on suppliers lacking captive substrate sourcing while OEMs exploit this asymmetry to compress module pricing across tiered procurement brackets.
Pricing Analysis
Cost-down pressure on matrix LED modules accelerates because semiconductor content now dominates bill-of-materials structures. Three-tier pricing structure across premium, standard, and economy levels separates laser configurations from matrix LED from adaptive motorized units, with certification grade under ECE R48 and NHTSA FMVSS 108 creating additional differentiation. Price erosion runs through entry-luxury segments as South Korean and German OEMs consolidate platform sourcing. Fleet operators in North America exhibit highest price sensitivity through performance-guarantee contracting, while ultra-premium German automakers remain least sensitive given optical precision requirements.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and US substrate manufacturers controlling Silicon Carbide wafer supply for high-brightness LED and laser diode production. Manufacturing concentrates in Germany, South Korea, and Japan for module assembly, with China expanding component fabrication capacity. Raw material dependencies encompass SiC substrates, precision optical glass, and rare-earth phosphors. Tariff exposure on semiconductor components threatens cost structures for European and North American assemblers. Distribution runs through Tier-1 integrators delivering directly to OEM assembly plants rather than aftermarket channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart automotive headlights are transitioning from hardware-defined to software-defined platforms, with digital light processing and micro-LED arrays displacing legacy projector architectures across premium vehicle segments.
For Market Incumbents: Deepen backward integration into LED chip sourcing to defend margin positions against SiC substrate allocation rationing. Secure sensor fusion software partnerships with ADAS platform providers to maintain specification authority as headlights become edge-computing nodes. Prioritize certification investment for ECE R48 and NHTSA FMVSS 108 harmonization to compress redundant engineering cycles. For New Entrants and Emerging Players: Micro-LED pixel control algorithms offer entry wedge against established lamp housing specialists lacking semiconductor design capabilities. Target India's PLI scheme for auto components to establish module assembly with localized cost structures serving domestic OEMs and export markets. Pursue fleet operator contracting channels in North American commercial vehicle segments where specification authority has shifted from OEM engineers. For Investors and Strategic Acquirers: NHTSA's amended Federal Motor Vehicle Safety Standard 108 is the leading indicator that matrix beam regulatory pathways will unlock substantial US market volume previously constrained by antiquated high-beam prescriptions. Over a multi-year horizon, acquisition targets should profile as semiconductor-capable lighting specialists with software-upgradable platform architectures. Monitor pending harmonization discussions between NHTSA and UN-ECE working groups as the signal for competitive viability of software-defined headlight platforms.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Chip Sourcing | Koito Manufacturing's captive supply of semiconductor components sustains cost advantages across Japanese and North American supply chains. |
| ADAS Sensor Suite Integration | Premium electric vehicle platforms now specify headlights as edge-computing nodes preprocessing visual data for central driver-assistance controllers. |
| Software-Upgradable Platform Development | Over-the-air update capability transforms lighting from one-time component sales into recurring revenue streams tied to feature activation. |
| Geographic Manufacturing Localization | German and South Korean automakers localize smart headlight production near electric vehicle assembly plants to compress logistics costs. |
| Regulatory Harmonization Investment | ECE R48 revision and UN Regulation 149 are compressing homologation timelines for multinational platform launches across 56 contracting parties. |
Research Methodology
Document review covered regulatory filings with NHTSA, ECE, and Japan's MLIT, complemented by interviews with Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and fleet operations managers. Secondary validation drew from vehicle production databases, IHS Markit registration data, customs records, and SEC filings of listed automotive suppliers. Bottom-up segment sizing triangulated against top-down market aggregation.
Output projections span product type, technology stack, end-user channel, and installation method dimensions across the analysis window. CAGRs were derived from regression analysis of historical adoption curves weighted by regulatory milestone timing and electric vehicle platform launch schedules. Inputs incorporated SiC substrate supply forecasts, ADAS penetration trajectories, and homologation timeline assumptions.
Several conditions sit outside the modeled scope, including abrupt tariff regime changes, semiconductor fabrication capacity disruptions, and unanticipated regulatory reversals. Forecasts reflect documented assumptions about technology cost curves and OEM platform standardization decisions. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Solar Film Market
Automotive Interior & Exterior
Mexico Automotive OEM Coatings Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Automotive Grill Guard Market
Automotive Interior & Exterior
LED-Based Exterior Navigation and Position Lighting Systems Market
Automotive Interior & Exterior
Global on Highway Vehicle Lighting Market
Automotive Interior & Exterior
Global Automotive Power Sliding Door Market
Automotive Interior & Exterior
Automotive Intelligent Rear-View Mirror Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Overhead Console Market
Automotive Interior & Exterior
Automotive Wooden Interior Decorative Market
Automotive Interior & Exterior
Brazil Automotive Flooring Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Automotive Headlamp Reflector Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market