
 United States Car Bumper Guard Market | 2026-2036
United States Car Bumper Guard Market Size, Share, and Industry Trends Forecast 2026-2036
United States Car Bumper Guard Market Analytics
Advanced polymer compounding is reshaping how car bumper guards achieve impact absorption without adding weight. 3M Company leverages its materials science portfolio to supply adhesive and film technologies that anchor guard attachment systems. Bumper Badger competes through specialized designs for urban parking environments. Lund International sustains manufacturing scale across multiple automotive accessory categories.
A car bumper guard is a protective accessory mounted to a vehicle's front or rear bumper, typically constructed from rubber, thermoplastic polymers, or steel-reinforced composites, designed to absorb low-speed impact energy and prevent cosmetic or structural damage during parking maneuvers. Its primary commercial purpose is to reduce repair costs for individual owners and fleet operators while preserving resale value. The Plastic segment leads volume due to moldability and cost efficiency, though Composite guards command premium positioning where lightweight performance matters. Aftermarket installation dominates channel flow as consumers replace worn or damaged units outside factory warranty periods. SUV applications occupy the largest vehicle-type share, reflecting higher bumper profiles and greater exposure to parking lot contact.
The NHTSA sets federal bumper integrity standards that guard manufacturers must navigate for OEM placement, while EPA guidelines on recyclable content influence material selection for sustainability-minded suppliers. State-level regulations in California through CARB add emissions-related compliance layers to manufacturing processes. Stakeholders must monitor how evolving federal safety ratings and state environmental mandates interact to determine which material platforms and distribution channels will carry the next generation of product development.
Market Dynamics
Fleet operators and ride-hailing services are compressing replacement cycles for bumper guards as they prioritize vehicle uptime over extended durability, creating a structural pull toward standardized, rapidly installable protection systems.
Growth Catalysts
- California CARB Emissions Standards:The state's manufacturing emissions mandates push suppliers toward recyclable polymer formulations, opening premium positioning for compliant producers.
- Ride-hailing fleet standardization:Uber and Lyft operator networks specify uniform guard specifications across vehicle classes to simplify maintenance protocols and reduce parts inventory.
- Thermoplastic vulcanizate compounding:Advanced TPV blends deliver superior impact recovery at reduced weight, displacing conventional rubber in high-performance applications.
Market Restraints
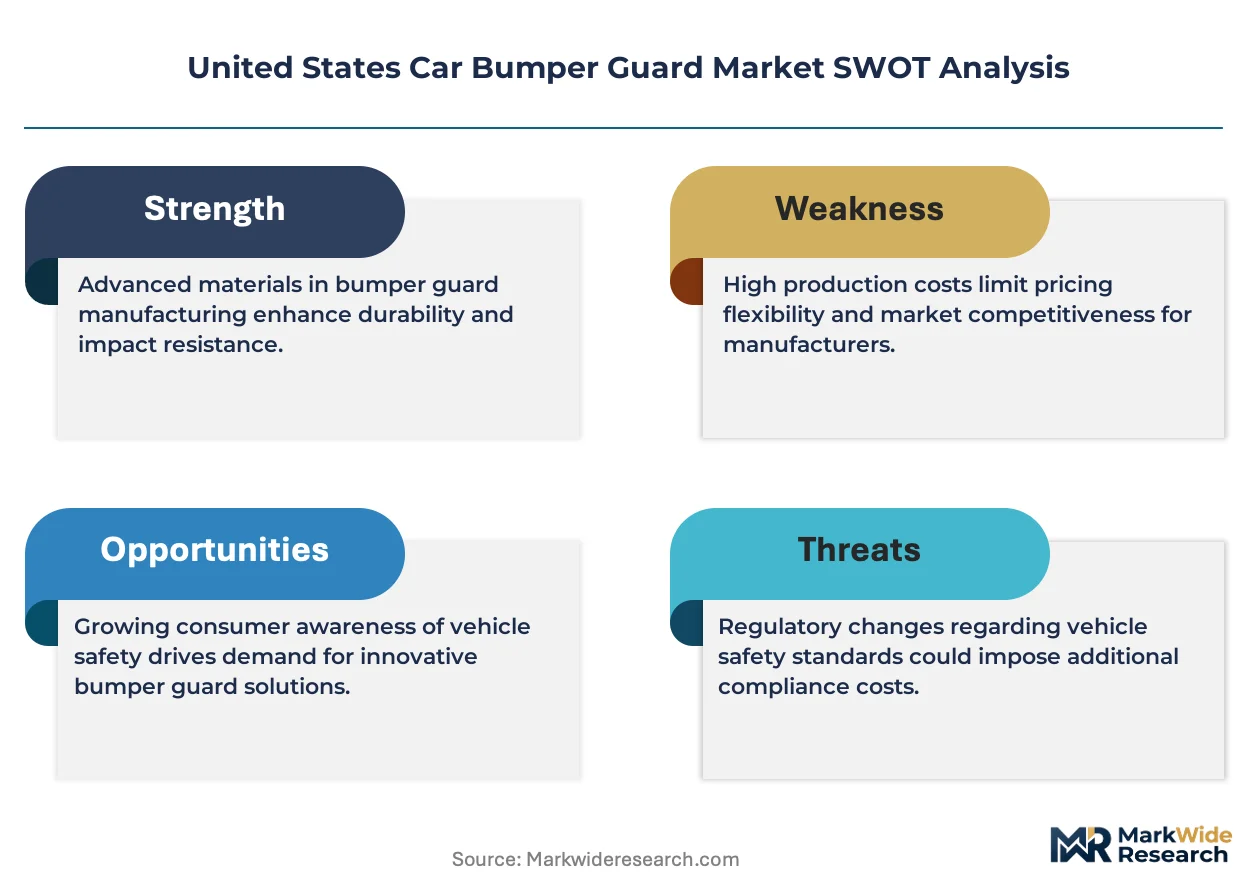
- Petrochemical feedstock volatility:Polypropylene and EPDM rubber prices fluctuate with crude oil benchmarks, compressing margin stability for molders without long-term supply contracts.
- Texas Gulf Coast concentration:Over 60% of domestic polymer resin production clusters in hurricane-exposed coastal zones, creating single-point supply vulnerability.
- NHTSA Federal Motor Vehicle Safety Standard No. 581:Bumper impact resistance testing adds 12-18 month certification timelines for OEM placement, freezing smaller suppliers out of factory-fit channels.
Strategic Opportunities
- Texas urban corridor expansion:Houston and Dallas-Fort Worth parking density growth outpaces national averages, driving replacement demand in high-contact metropolitan environments.
- IRA domestic content incentives:Clean vehicle tax credit domestic manufacturing bonuses reward U.S.-based guard production with qualifying recycled material thresholds.
- E-commerce direct-to-consumer channels:Amazon and specialty auto parts platforms bypass traditional distributor markups, capturing margin for branded manufacturers willing to manage fulfillment complexity.
Industry Challenges
- Polymer compounding talent scarcity:Experienced formulators capable of balancing impact absorption with UV stability command premium wages, constraining R&D throughput at mid-tier suppliers.
- California Proposition 65 compliance:Warning label requirements for chemical constituents add documentation burden and litigation exposure for products sold through retail channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Car Bumper Guard Market |
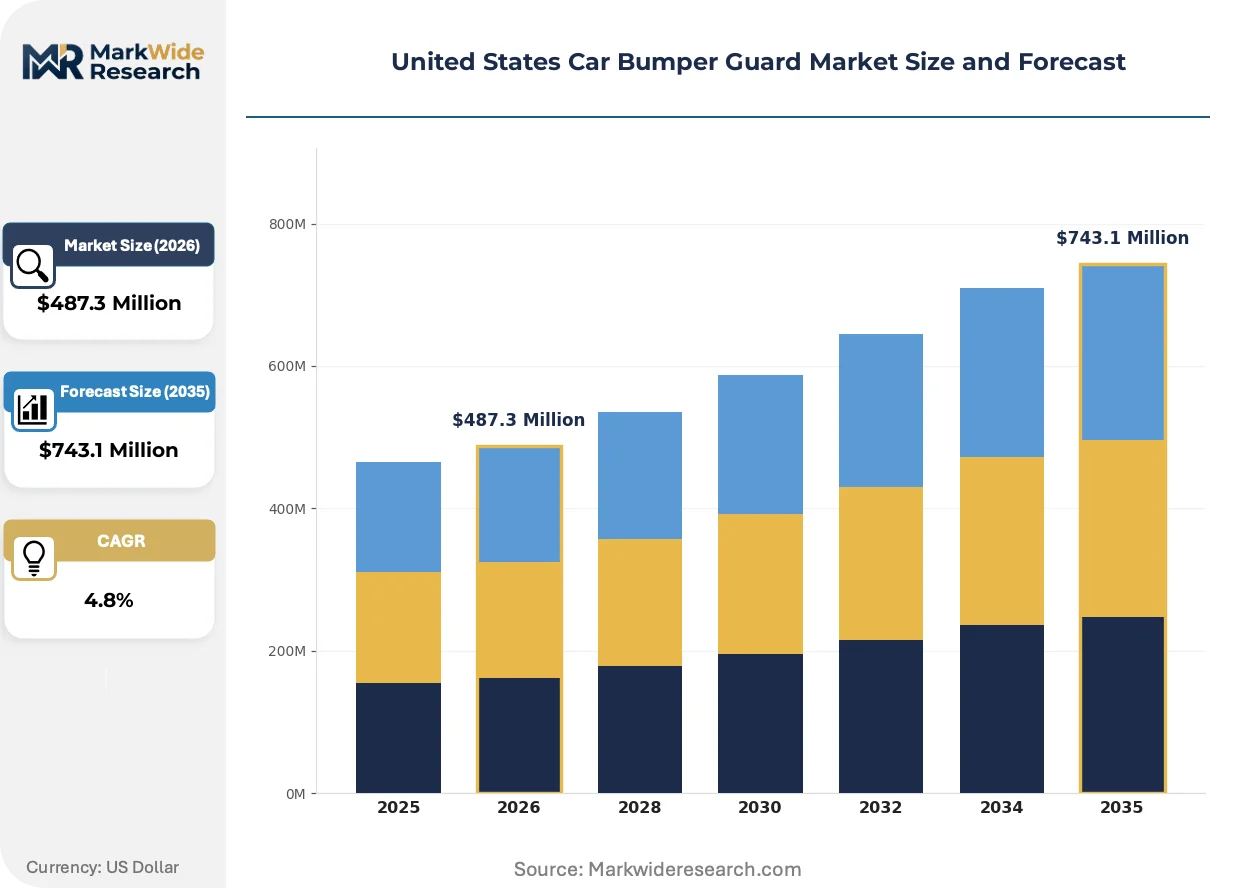
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel, Plastic, Rubber, Composite Installation Type: OEM, Aftermarket, DIY, Professional Vehicle Type: SUV, Sedan, Truck, Hatchback Distribution Channel: Retail, Online, Wholesale, Specialty Stores |
| Companies Covered | Luv-Tap, Bumper Badger, Parking Armor, Bumper Bully, Auto Metal Direct LLC, 3M Company, Lund International, Black Horse Off Road, BumperX, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Car Bumper Guard Market Evolving Landscape
Material science advances and regulatory pressure on vehicle lifecycle emissions are converging to redefine how bumper guards balance protection performance with environmental accountability.
Thermoplastic elastomer formulations with embedded phase-change materials are migrating from aerospace applications into automotive protection accessories. Fleet maintenance departments at enterprise rental companies specify these guards for their ability to absorb repeated low-speed impacts without permanent deformation. The technology is compressing replacement frequency expectations from 3-4 year cycles toward 18-24 month refresh intervals.
EPA guidelines on post-consumer recycled content in automotive plastics are tightening material sourcing requirements for suppliers seeking federal procurement eligibility. Manufacturers must now document chain-of-custody for recycled feedstocks through third-party certification. California-based molders face the steepest compliance burden as CARB regulations layer additional emissions tracking onto federal benchmarks.
Subscription-based vehicle protection packages are displacing traditional transactional guard purchases among commercial fleet operators. Enterprise customers bundle guard replacement into full-service leasing agreements, transferring inventory risk to suppliers. This model concentrates most visibly in Texas and Florida markets where high vehicle turnover and parking congestion accelerate wear rates.
United States Car Bumper Guard Market Segmentation
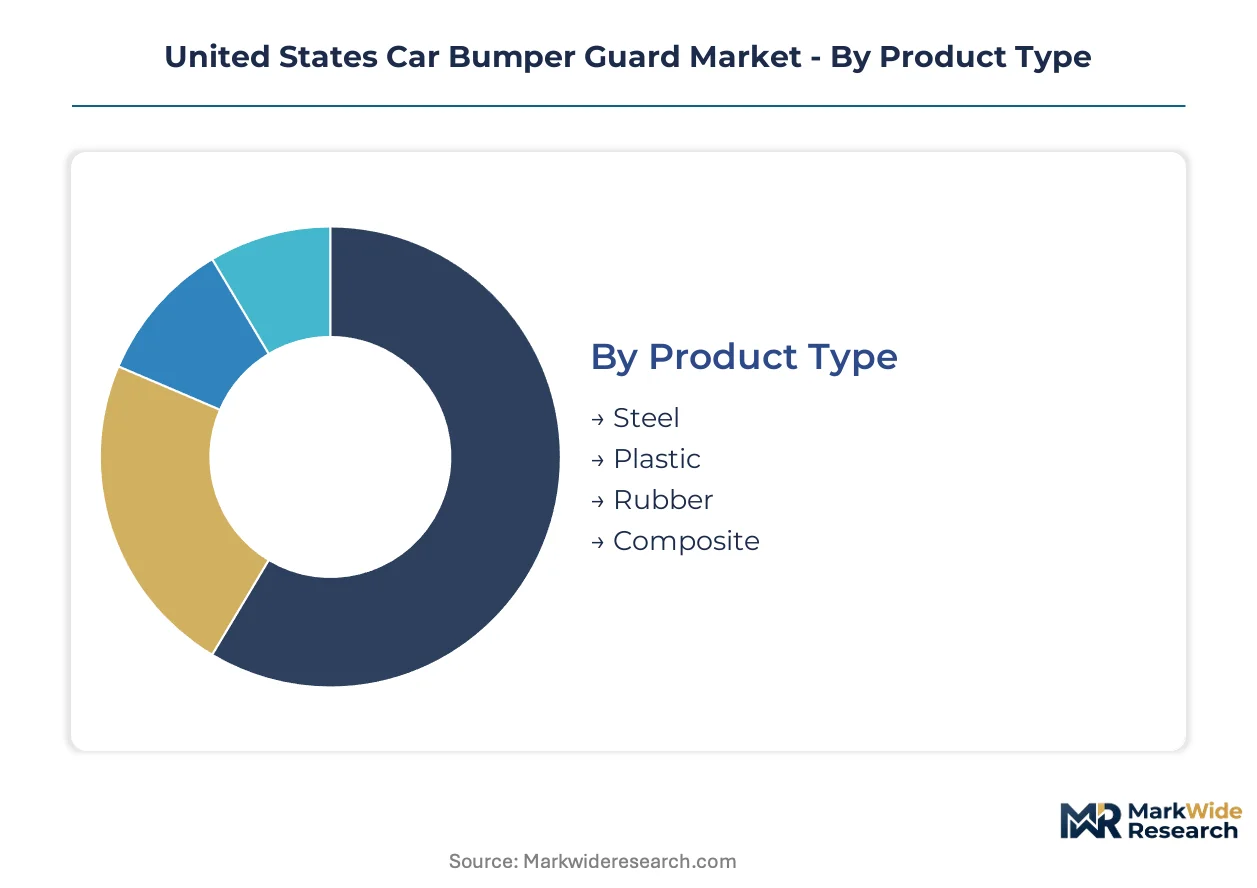
Car bumper guard demand fragments across material technologies, installation methods, and vehicle architectures. Each segmentation axis reveals distinct procurement patterns and margin structures that suppliers must navigate to capture volume or premium positioning.
Product Type:
Material selection spans impact absorption requirements, weight constraints, and regulatory compliance burdens across fleet and consumer applications.
- Plastic:Thermoplastic polyolefin and polypropylene compounds dominate manufacturing throughput due to injection moldability and cost efficiency. Fleet operators in Texas and California specify plastic guards for standardized replacement programs where unit economics outweigh extended durability.
- Composite:Glass-reinforced and carbon-fiber hybrid structures deliver strength-to-weight ratios critical for electric vehicle range preservation. NHTSA certification timelines for OEM placement favor composite suppliers with established crash-test documentation.
- Steel:Cold-rolled and stainless configurations persist in commercial truck applications requiring maximum impact resistance. Weight penalties limit penetration in passenger vehicle segments.
- Rubber:EPDM and natural rubber formulations absorb repeated low-speed contact without permanent deformation. Parking-intensive urban environments in Houston and Dallas-Fort Worth drive replacement demand.
Established volume favors Plastic; emerging adoption favors Composite.
Installation Type:
Channel economics separate factory-integrated placement from post-purchase attachment, with distinct margin and liability profiles.
- Aftermarket:Independent service centers and auto parts retailers handle the majority of guard replacements outside warranty periods. California's vehicle density supports the highest concentration of aftermarket installation volume nationally.
- OEM:Factory-fit placement requires NHTSA Federal Motor Vehicle Safety Standard No. 581 compliance, creating 12-18 month certification barriers. Secured OEM contracts deliver multi-year revenue visibility.
- DIY:Consumer self-installation concentrates in online-direct purchases through Amazon and specialty platforms. Installation simplicity determines product selection.
- Professional:Certified technician installation addresses fleet operator requirements for warranty preservation and liability documentation. Ride-hailing networks mandate professional attachment for insurance compliance.
Volume concentration sits with Aftermarket; margin expansion favors OEM.
Vehicle Type:
Bumper geometry and ride height dictate guard specification across passenger and commercial categories.
- SUV:Elevated bumper profiles and greater frontal surface area increase parking lot contact frequency. Suburban household penetration in Texas urban corridors sustains replacement demand.
- Sedan:Lower bumper positioning reduces impact severity but increases cosmetic damage visibility. Lease return preparation drives guard refresh cycles.
- Truck:Commercial and personal use applications require reinforced mounting systems for heavier guard structures. Fleet standardization programs specify uniform specifications across vehicle classes.
- Hatchback:Compact dimensions and urban parking exposure create concentrated demand in California metropolitan markets. Aftermarket channel dominance reflects price-sensitive owner demographics.
SUV commands current volume leadership; Hatchback shows steepest expansion trajectory in dense urban zones.
Distribution Channel:
Route-to-market strategies separate inventory-heavy retail from asset-light digital fulfillment.
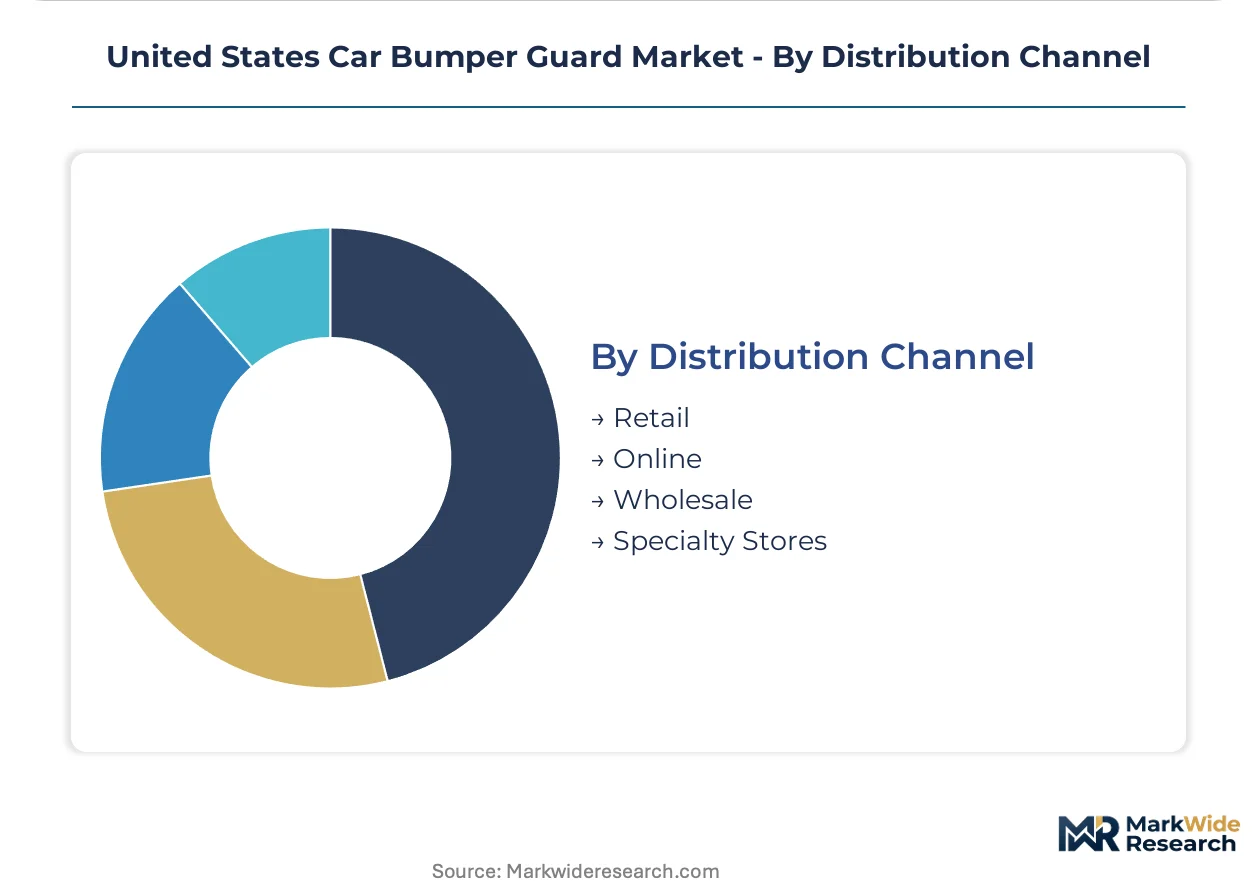
- Online:Amazon, eBay, and dedicated auto parts platforms capture direct-to-consumer volume with bypassed distributor markups. Search-driven discovery favors branded manufacturers with review density.
- Retail:AutoZone, O'Reilly, and Advance Auto Parts maintain physical inventory for immediate replacement needs. California and Texas store density correlates with vehicle registration concentration.
- Wholesale:Distributor networks supply independent repair shops and fleet maintenance depots with bulk pricing structures. Inventory risk transfer to distributors compresses manufacturer margins.
- Specialty Stores:Customization-focused retailers serve enthusiast segments with premium guard designs and installation services. Higher price tolerance supports composite and steel product placement.
Online gains share fastest; Retail retains immediacy advantage in replacement scenarios.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Car Bumper Guard Market operates as a net importer of specialized polymer resins while domestic molders capture value through finished goods distribution. Regional demand patterns track vehicle density, parking infrastructure constraints, and state-level regulatory differentiation.
California
Los Angeles and San Francisco parking congestion drives replacement rates above national averages. CARB manufacturing emissions mandates push suppliers toward recyclable polymer formulations. The Central Valley hosts injection molding clusters serving West Coast aftermarket channels.
Texas
Houston and Dallas-Fort Worth urban corridor expansion concentrates fleet operator demand for standardized guard specifications. State-level storm exposure creates supply chain vulnerability through Gulf Coast resin production concentration. Austin-San Antonio corridor attracts logistics providers for e-commerce fulfillment.
Midwest Manufacturing Belt
Ohio and Michigan automotive supplier ecosystems sustain OEM placement capabilities for NHTSA-certified producers. Chicago distribution hubs handle wholesale volume to independent repair networks. Detroit-area engineering talent pools support composite material development for electric vehicle applications.
Southeast Growth Corridor
Florida parking-intensive urban environments in Miami and Tampa generate elevated replacement frequency. Georgia and Carolinas logistics infrastructure supports port-based import distribution. Regional fleet operators standardize guard specifications across ride-hailing vehicle classes.
Northeast Urban Corridor
New York Metro and Boston parking density sustains premium aftermarket pricing for professional installation services. Philadelphia and Baltimore distribution centers supply retail chains along I-95 corridor. Regional regulations align with federal NHTSA standards without additional state environmental layering.
United States Car Bumper Guard Market Competitive Landscape
On the supply side, the industry is tiered between multinational material suppliers, specialized automotive accessory manufacturers, and direct-to-consumer brands. Three strategic archetypes dominate: integrated polymer compounders with captive resin supply, design-focused specialists serving urban parking environments, and diversified automotive parts conglomerates leveraging cross-category manufacturing scale. Competitive moves concentrate on e-commerce channel expansion and recycled content certification to capture IRA domestic manufacturing incentives.
Among diversified material science conglomerates, 3M Company anchors the adhesive and film technology layer that underpins guard attachment systems. Bumper Badger and Lund International occupy distinct positioning archetypes—the former exemplifying design specialization for parking-intensive use cases, the latter representing manufacturing scale across multiple automotive accessory categories. These three entities illustrate how material control, application-specific engineering, and production breadth define competitive separation in this market.
| Leading Market Players |
|---|
| Luv-Tap |
| Bumper Badger |
| Parking Armor |
| Bumper Bully |
| Auto Metal Direct LLC |
| 3M Company |
| Lund International |
| Black Horse Off Road |
| BumperX |
| Others |
Value Network & Pricing Analysis
The I-10 corridor linking Houston to Los Angeles carries polymer resin shipments whose freight volatility directly shapes tiered pricing structures for bumper guard manufacturers. Texas Gulf Coast concentration of feedstock production amplifies cost differentials between regional molders and national distributors serving California's aftermarket channels.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that compress spot-market exposure for certified suppliers. Three-tier pricing structure across premium, standard, and economy levels separates NHTSA-validated composite guards from injection-molded plastic units and basic rubber alternatives. Cost compression in the standard tier is intensifying because polypropylene feedstock draws from hurricane-exposed Gulf Coast infrastructure. Fleet operators exhibit highest price sensitivity through standardized procurement programs, while specialty retailers serving enthusiast segments tolerate premium positioning.
Supply Chain Analysis
Export-control regimes on carbon fiber precursor technologies limit composite material flows to domestic compounders with Department of Commerce licensing. Geographic supply concentration centers on Texas, Louisiana, and California for polymer resin production, with Ohio and Michigan anchoring finished goods manufacturing. Raw material dependencies rest on polypropylene, EPDM rubber, and glass-reinforced thermoplastics. Single-source vulnerability runs through Gulf Coast petrochemical complexes exposed to seasonal storm disruption. Distribution runs through wholesale distributor networks supplying independent repair shops, with e-commerce direct fulfillment gaining share fastest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Car Bumper Guard Market represents a high-growth disruption as IRA domestic content incentives restructure manufacturing location economics and recycled material thresholds become procurement gatekeepers.
For Market Incumbents: Insulate OEM placement contracts through accelerated NHTSA certification investment, compressing 12-18 month timelines for Federal Motor Vehicle Safety Standard No. 581 compliance. Deepen backward integration into polymer compounding capabilities to offset petrochemical feedstock volatility and capture CARB emissions compliance premiums. Threat concentration sits with ride-hailing fleet operators standardizing specifications across vehicle classes, eroding brand differentiation. For New Entrants and Emerging Players: Pursue e-commerce direct-to-consumer channels where Amazon and specialty auto parts platforms bypass traditional distributor markups. White-space concentration sits in composite guard applications for electric vehicle range preservation, where lightweight performance commands premium positioning. Texas urban corridor expansion in Houston and Dallas-Fort Worth offers the most penetrable geography for aftermarket volume capture. Go-to-market execution hinges on installation simplicity and review density for search-driven discovery. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified automotive accessory conglomerates with underperforming bumper guard divisions lacking recycled content certification infrastructure. Long-term viability favors suppliers with documented chain-of-custody for post-consumer feedstocks and qualifying thresholds for IRA domestic manufacturing bonuses. The signal to watch is CARB regulatory layering onto federal EPA guidelines, which would accelerate compliance burden differentiation between California-based and out-of-state molders.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Certification | Third-party chain-of-custody documentation unlocks IRA domestic manufacturing incentives for qualifying suppliers. |
| E-commerce Channel Expansion | Direct-to-consumer fulfillment through Amazon captures margin otherwise lost to wholesale distributor markups. |
| Thermoplastic Vulcanizate Compounding | Advanced TPV blend development displaces conventional rubber in high-performance fleet applications. |
| NHTSA Certification Acceleration | Federal Motor Vehicle Safety Standard No. 581 compliance timelines determine OEM placement access. |
| Subscription-Based Fleet Bundling | Full-service leasing agreements transfer inventory risk from operators to suppliers in Texas and Florida markets. |
Research Methodology
Desk research of customs trade records, NHTSA certification filings, and automotive accessory distributor databases preceded structured interviews with Tier 1 supplier procurement managers, aftermarket channel partners, fleet maintenance directors, and polymer compounding R&D leads. Primary fieldwork validated secondary findings through bottom-up volume estimation and top-down market sizing triangulation. SEC 10-K disclosures from diversified automotive parts conglomerates and EPA recycled content guidelines provided regulatory and financial context.
Assumption sets held federal safety standards and state emissions mandates constant while varying ride-hailing fleet penetration rates and e-commerce channel share across the projection horizon. Segmentation modeling spanned material technology, installation type, vehicle architecture, and distribution channel, with electric vehicle content per vehicle treated as a cross-cutting demand modifier. CAGRs derived from regression analysis against vehicle registration density and parking infrastructure constraints. Forecast inputs incorporated polymer resin price indices and Gulf Coast storm frequency patterns.
Sensitivities concentrate around NHTSA regulatory revision timelines and CARB manufacturing emissions threshold adjustments. Forecasts reflect documented assumptions regarding fleet operator standardization behavior and IRA domestic content bonus qualification rates. Material shifts in thermoplastic elastomer formulation adoption or composite material cost curves would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Auto Dimming Mirror Market
Automotive Interior & Exterior
Automotive Fabric Market
Automotive Interior & Exterior
Automotive Outside Rearview Mirrors (ORVM) Market
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Glove Box Market
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Global Automotive Windows and Exterior Sealing Market
Automotive Interior & Exterior
Exterior Automotive Plastics Market
Automotive Interior & Exterior
Automotive Door Panel Market
Automotive Interior & Exterior
Automotive Door Stabilizer Market
Automotive Interior & Exterior
Automotive Floor Mats Market
Automotive Interior & Exterior
Europe Automotive Upholstery Market
Automotive Interior & Exterior
North America Automotive Interior Materials Market
Automotive Interior & Exterior
Automotive Window and Exterior Sealing Systems Market
Automotive Interior & Exterior
Automotive Heated Steering Wheel Market