
 Auto Ventilated Seat Fan Market | 2026-2036
Auto Ventilated Seat Fan Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Ventilated Seat Fan Market Analysis
Aftermarket retrofit revenue is narrowing as OEMs bundle ventilated seating into higher-volume trim packages. Gentherm leverages its North American thermal seating dominance to supply integrated climate-controlled seat systems for premium pickup trucks. Ebm-Papst sustains engineering leadership in compact brushless DC blowers optimized for automotive NVH requirements. Toyota Boshoku Corporation anchors Japanese OEM supply chains with just-in-time seat assembly capabilities tied to domestic vehicle platforms.
An auto ventilated seat fan is a low-profile electromechanical air mover embedded within seat foam structures, typically operating at 12V or 48V with airflow rates between 15 and 40 CFM to reduce occupant back and thigh perspiration. The device employs axial or centrifugal impeller geometries housed in thermoplastic enclosures that integrate with seat heating elements and occupancy sensors for unified climate management. Built-in fan configurations command the dominant share of value as automakers eliminate portable alternatives from new vehicle programs. Thermoelectric technology segments are gaining traction fastest in electric vehicle architectures where waste heat recovery supports seat cooling without dedicated refrigerant loops. OEM end users represent the most concentrated margin pool due to multi-year platform contracts and qualification barriers that limit supplier switching.
NHTSA occupant comfort guidelines and EPA cabin air quality assessments shape blower efficiency and filtration requirements for US-bound vehicles. EU REACH substance restrictions and CE marking directives govern plasticizer content in fan housings and electrical insulation materials sold across European markets. China's MIIT new energy vehicle technical standards incorporate seat thermal management within whole-vehicle energy consumption calculations. Stakeholders must monitor how 48V electrical architecture migration and solid-state battery thermal profiles reshape blower power specifications and integration protocols.
Market Dynamics
The migration to 48V electrical architectures in premium vehicle platforms is compressing blower voltage compatibility requirements and forcing suppliers to redesign impeller motors for dual-voltage operation.
Growth Catalysts
- EU cabin air quality mandates:REACH substance restrictions and CE marking directives are accelerating factory-fit ventilation adoption as automakers preempt retrofit liability exposure.
- Thermoelectric cooling convergence:Solid-state heat pump integration with seat fans eliminates refrigerant loop dependency in electric vehicle thermal management.
- Yangtze River Delta cluster concentration:Domestic Chinese EV manufacturers specify ventilated seats across mid-trim configurations, expanding addressable volume beyond luxury segments.
Market Restraints
- Brushless DC motor cost volatility:Rare earth magnet supply concentration in processing facilities creates input price instability for compact blower assemblies.
- NVH qualification barriers:OEM platform contracts lock suppliers into multi-year validation cycles that freeze design flexibility.
- Seat heating element substitution:Resistive warming mats retain cost advantage in entry segments, limiting ventilation penetration below mid-tier trims.
Strategic Opportunities
- Aftermarket channel innovation:Mobile installation networks are capturing retrofit demand in regions where OEM bundle penetration remains incomplete.
- NHTSA occupant comfort guidelines:Anticipated test protocol tightening creates compliance-driven replacement cycles for legacy blower designs.
- 48V-12V dual architecture:Hybrid powertrain expansion enables premium thermal seating in mass-market pickup and SUV platforms.
Industry Challenges
- Embedded software certification:Functional safety validation for fan-speed algorithms tied to occupancy sensors extends development timelines.
- Foam integration complexity:Thermoplastic blower housing compatibility with varying seat cushion densities requires platform-specific tooling investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Ventilated Seat Fan Market |
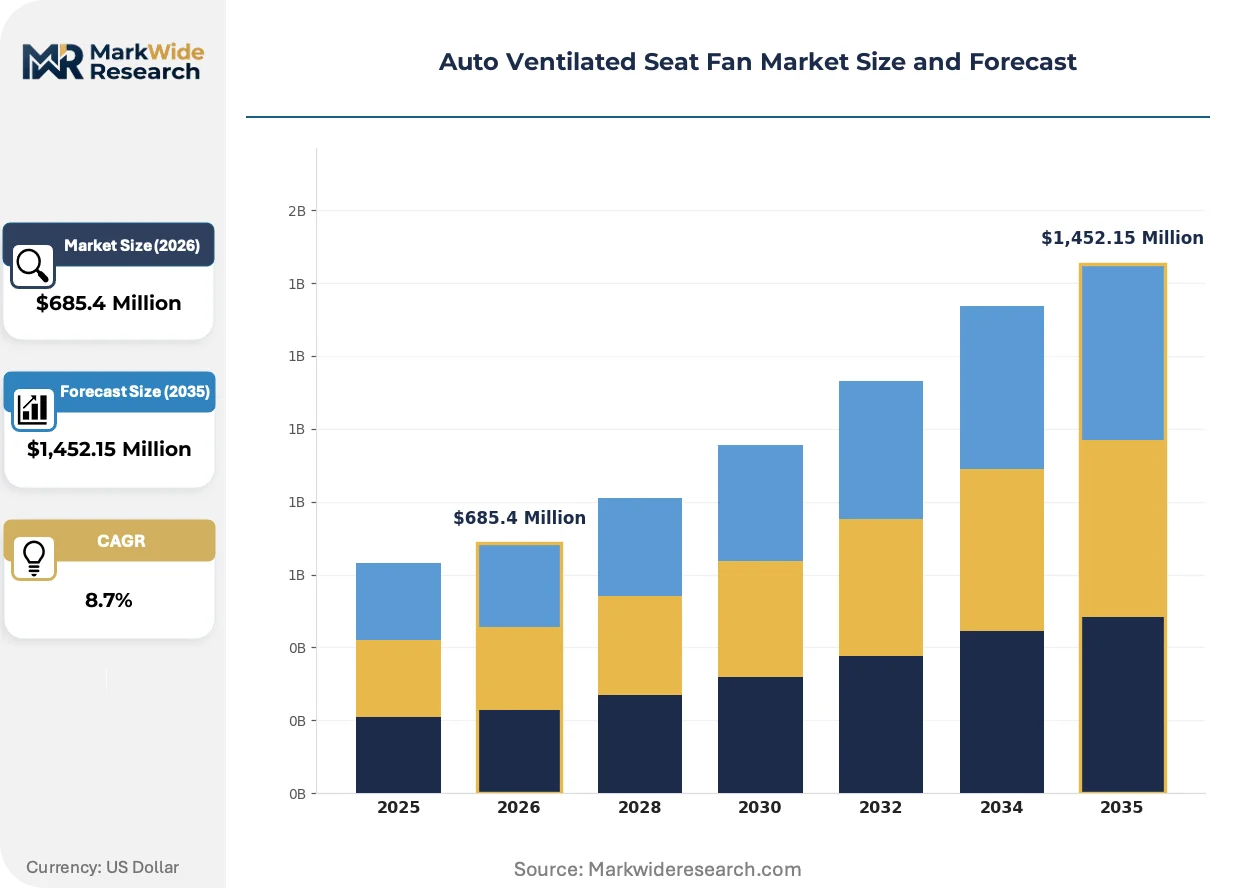
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,452.15 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Fans, Built-in Fans, Air Circulators, Seat Cushions End User: OEMs, Aftermarket Users, Vehicle Assemblers, Retrofitting Services Technology: Convection, Evaporative Cooling, Thermoelectric, Bladeless Designs Power Rating: Low Power, High Power, USB-Powered, Battery-Operated |
| Companies Covered | Gentherm, Ebm-Papst, Yen Sun Technology, Sunon, MinebeaMitsumi, Delta, Nidec, Toyota Boshoku Corporation, Faurecia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Ventilated Seat Fan Market Emerging Trajectories
Active noise cancellation integration and solid-state thermal management are reshaping how seat climate systems interface with vehicle electrical architectures.
Axial impeller geometries optimized for 48V operation are collapsing the performance gap between dedicated HVAC ducting and localized seat ventilation. Tier 1 suppliers in Germany and Japan are adopting these compact blowers for next-generation luxury platforms. The technology is collapsing legacy centrifugal designs from premium specifications.
China's MIIT new energy vehicle technical standards now incorporate seat thermal management within whole-vehicle energy consumption calculations. This policy compresses allowable blower power draw while mandating cooling efficacy benchmarks. Domestic EV manufacturers in the Yangtze River Delta are responding with integrated thermoelectric-fan modules.
Fleet procurement specifications for thermal comfort are displacing individual option selection in corporate vehicle acquisition. Rental and ride-hail operators now mandate ventilated seating as standard equipment. This pattern concentrates most visibly in China's domestic EV fleet deployment programs.
Auto Ventilated Seat Fan Market Segmentation
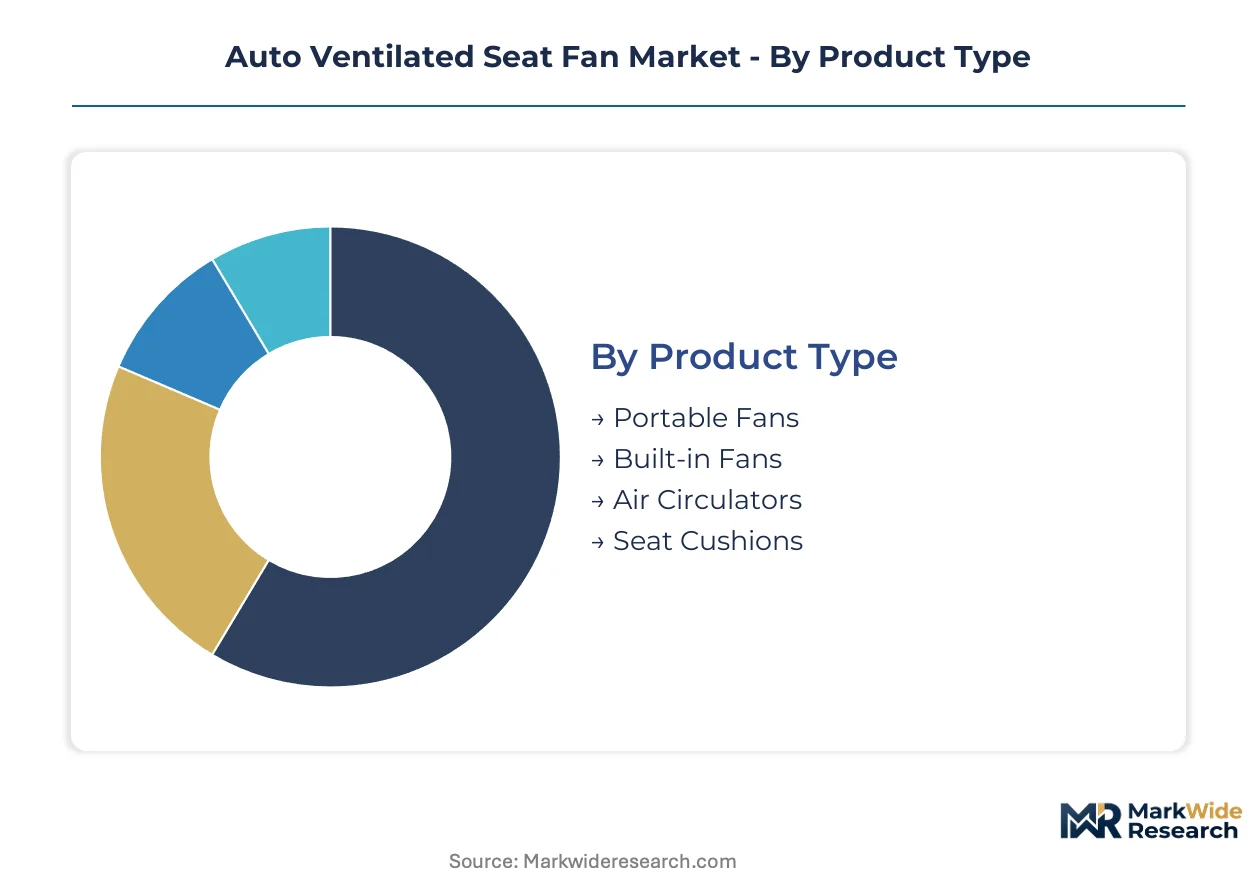
Seat ventilation architectures diverge sharply between factory-integrated systems and post-production modifications. Each segment category reflects distinct technical specifications, procurement channels, and margin structures that shape supplier positioning.
Product Type:
Vehicle thermal comfort spans aftermarket accessories to embedded electromechanical assemblies with varying degrees of OEM integration.
- Portable Fans:Battery-powered or 12V plug-in units attach to seat surfaces via straps or clips. Rental fleet operators in China's Yangtze River Delta specify these for rapid deployment across mixed vehicle pools where factory ventilation remains absent.
- Built-in Fans:Axial or centrifugal blowers embed directly within seat foam structures, operating at 12V or 48V with 15-40 CFM airflow rates. German luxury automakers specify these across premium pickup and SUV platforms as standard equipment.
- Air Circulators:Ducted airflow systems distribute conditioned air across broader seat surface areas. Japanese OEMs integrate these with heating elements for unified climate zones.
- Seat Cushions:Self-contained ventilation pads replace or overlay factory cushions. Mobile installation networks target these at ride-hail driver segments in regions with incomplete OEM bundle penetration.
Established volume favors Built-in Fans; emerging adoption favors Seat Cushions.
End User:
Procurement authority concentrates differently across direct manufacturing relationships versus post-vehicle-sale service channels.
- OEMs:Multi-year platform contracts with qualification barriers lock suppliers into validated blower designs. NHTSA occupant comfort guidelines shape specification requirements for US-bound vehicle programs.
- Aftermarket Users:Individual consumers purchase through retail channels for personal vehicle upgrades. China's domestic EV fleet deployment programs are compressing this segment as mid-trim ventilated seating becomes standard.
- Vehicle Assemblers:Contract manufacturers integrate seat systems under Tier 1 direction. Just-in-time assembly capabilities in Japan anchor regional supply chains.
- Retrofitting Services:Specialized installers modify existing seat structures with embedded ventilation hardware. Mobile service networks are capturing demand in markets where OEM penetration remains incomplete.
Margin concentration sits with OEMs; volume expansion favors Vehicle Assemblers.
Technology:
Thermal management approaches range from passive airflow to solid-state heat pumping with distinct electrical architecture implications.
- Convection:Forced air movement through seat foam channels without active cooling elements. Entry-segment vehicles in cost-sensitive markets retain this approach for its manufacturing simplicity.
- Evaporative Cooling:Moisture-wicking fabrics combined with airflow accelerate perspiration dissipation. Humid climate specifications in southern US states favor this configuration.
- Thermoelectric:Solid-state heat pumps integrated with seat fans eliminate refrigerant dependency. Electric vehicle architectures adopt these modules fastest for waste heat recovery compatibility.
- Bladeless Designs:Coanda-effect air multiplication reduces NVH signatures in luxury applications. German premium platforms specify these for acoustic refinement differentiation.
Technology maturity favors Convection; steepest expansion trajectory belongs to Thermoelectric.
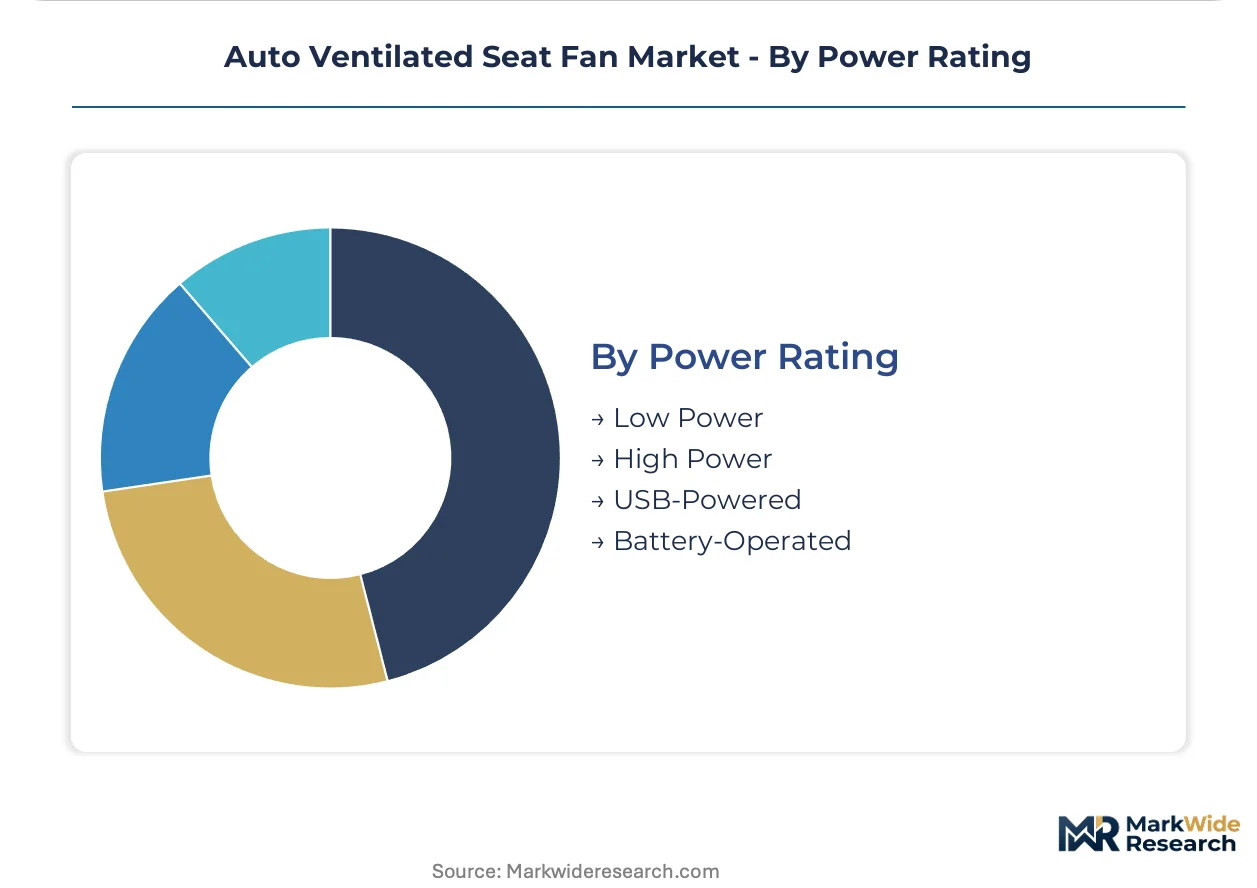
Power Rating:
Electrical system compatibility spans legacy 12V networks through emerging 48V architectures and portable power sources.
- Low Power:Sub-10W draw suits basic ventilation without thermoelectric augmentation. EU vehicle interior air quality standards constrain allowable power budgets within whole-vehicle energy calculations.
- High Power:25W+ ratings support integrated heating and cooling functions. 48V electrical migration in premium platforms enables these specifications without legacy wiring harness constraints.
- USB-Powered:5V draw from vehicle infotainment ports or portable battery packs. Aftermarket accessories targeting rental fleet flexibility dominate this category.
- Battery-Operated:Self-contained lithium-ion cells enable seat ventilation without vehicle electrical connection. Mobile installation services deploy these for rapid retrofit completion.
Platform standardization favors Low Power; architecture transition favors High Power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Component fabrication for auto ventilated seat fans clusters heavily in East Asian electronics manufacturing corridors and German automotive supplier networks. Tier 1 seat system integrators source blowers from these concentrated supply bases to serve final assembly plants across multiple continents.
China
Domestic EV manufacturers in the Yangtze River Delta specify ventilated seats across mid-trim configurations, compressing aftermarket retrofit potential. MIIT new energy vehicle technical standards incorporate seat thermal management within whole-vehicle energy consumption calculations. Shanghai and Suzhou anchor blower module production for both local brands and export-bound German OEM programs.
Germany
Luxury automakers expand factory-fit installations as cabin thermal comfort becomes priority specification for premium pickup and SUV platforms. KBA vehicle type approval protocols enforce rigorous NVH testing for embedded seat ventilation systems. Stuttgart and Munich supplier corridors concentrate engineering development for 48V-compatible dual-voltage blower architectures.
United States
NHTSA occupant comfort guidelines shape blower efficiency and filtration requirements for US-bound vehicle programs. EPA cabin air quality assessments extend to seated occupant ventilation system validation. Detroit-area Tier 1 seating suppliers integrate thermal management modules for domestic truck and SUV platforms.
Japan
Toyota Boshoku Corporation anchors OEM supply chains with just-in-time seat assembly capabilities tied to domestic vehicle platforms. METI industrial standards influence blower motor efficiency benchmarks for automotive applications. Nagoya and Tokyo manufacturing belts concentrate precision motor production for integrated climate-controlled seat systems.
South Korea
Hyundai-Kia vehicle platforms specify ventilated seating across expanding trim configurations to match Chinese EV competitor feature sets. MFDS automotive component quality frameworks apply to seat subsystem supplier qualification. Gyeonggi-do province hosts blower motor fabrication for both domestic consumption and export to Southeast Asian assembly plants.
Auto Ventilated Seat Fan Market Vendor Landscape
Integrated thermal system specialists and precision motor fabricators split the market along vertical capability lines. Supplier relationships consolidate around multi-year platform contracts with qualification barriers that limit switching. Three archetypes dominate: full-seat integrators with captive blower supply, dedicated blower motor specialists with automotive NVH expertise, and diversified electronics component houses leveraging scale. Competitive moves concentrate on dual-voltage motor architecture development and thermoelectric module integration partnerships.
Among precision motor specialists, Ebm-Papst and Nidec exemplify the engineering-intensive tier focused on compact brushless DC blowers. Gentherm occupies a position representing North American thermal seating dominance through integrated climate-controlled system supply. Toyota Boshoku Corporation anchors the full-seat integrator archetype with just-in-time assembly capabilities tied to Japanese OEM platforms. These three patterns illustrate how geographic proximity to major automotive clusters shapes competitive positioning.
| Leading Market Players |
|---|
| Gentherm |
| Ebm-Papst |
| Yen Sun Technology |
| Sunon |
| MinebeaMitsumi |
| Delta |
| Nidec |
| Toyota Boshoku Corporation |
| Faurecia |
| Others |
Supply Flow & Price Mechanics
Overcapacity in China's Yangtze River Delta blower motor fabrication corridors is compressing supplier margins while accelerating price competition for 12V and 48V seat fan modules. This utilization dynamic forces Tier 1 seating integrators to consolidate procurement volumes around dual-voltage capable suppliers, reshaping pricing power toward OEMs with multi-year platform contracts.
Pricing Analysis
Aftermarket service and retrofit installation revenue drives lifetime value capture more than initial hardware transactions for specialized ventilation installers. Three-tier pricing structure across premium, standard, and economy levels separates German luxury OEM bundled specifications from Chinese domestic EV mid-trim configurations and entry-level convection-only systems. Cost compression in the portable fan tier intensifies because rental fleet operators prioritize rapid deployment over thermal performance. Fleet procurement managers exhibit highest price sensitivity; luxury SUV platform engineers demonstrate lowest sensitivity due to NVH qualification barriers.
Supply Chain Analysis
Tariff exposure between China and Germany dominates supply chain risk calculus for brushless DC motor assemblies crossing automotive supplier networks. Component fabrication concentrates in China, Japan, and Germany, with precision impeller molding anchored in Suzhou and Stuttgart corridors. Rare earth magnet sourcing draws from concentrated processing facilities, creating single-source vulnerability for neodymium-dependent blower motors. Distribution runs through just-in-time seat assembly hubs tied to regional vehicle production clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet buyer consolidation across China's domestic EV deployment programs is shifting procurement power toward volume aggregators and away from individual option selection. This buyer-power concentration compresses aftermarket retrofit margins while elevating OEM platform contract value.
For Market Incumbents: Pre-empt thermoelectric module substitution by deepening captive supply of solid-state heat pump components before Chinese EV manufacturers integrate vertically. Secure dual-voltage motor qualification across 48V-12V hybrid architectures to lock out specialty blower competitors. Defend against bladeless design encroachment in German premium segments through acoustic refinement patents. For New Entrants and Emerging Players: Build out mobile installation service networks targeting ride-hail driver segments in Southeast Asian markets where OEM ventilated seating penetration remains incomplete. Capture white-space in battery-operated seat cushion retrofits for rental fleet flexibility requirements. Lead with rapid-deployment value proposition rather than thermal performance parity. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thermoelectric-integrated seat climate systems due to solid-state heat pump R&D requirements and 48V electrical architecture validation costs. Long-term viability favors suppliers with backward integration into rare earth magnet processing or captive thermoelectric chip fabrication. Monitor NHTSA occupant comfort guideline finalization timing as inflection signal for compliance-driven replacement cycle magnitude.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Voltage Motor Architecture Development | 48V-12V compatibility captures hybrid powertrain expansion across mass-market pickup and SUV platforms. |
| Thermoelectric Module Integration Partnership | Solid-state heat pump alliances eliminate refrigerant dependency for MIIT-compliant EV thermal management. |
| NVH Certification Investment | KBA and NHTSA test protocol compliance locks suppliers into multi-year German and US OEM platform contracts. |
| Just-in-Time Assembly Footprint Expansion | Regional proximity to Yangtze River Delta and Stuttgart production clusters reduces logistics cost exposure. |
| Aftermarket Mobile Service Network Buildout | Rapid-installation capabilities capture retrofit demand in markets with incomplete OEM bundle penetration. |
Methodological Framework
Cross-validation between OEM platform engineering disclosures and Tier 1 supplier procurement patterns anchors the qualitative findings. Primary interviews with thermal seating system architects, brushless DC motor R&D directors, automotive NVH test engineers, and fleet procurement managers combined with secondary validation from vehicle production databases, IHS Markit registration data, MIIT new energy vehicle technical filings, and KBA type approval records. Bottom-up segment sizing and top-down market reconciliation triangulate volume estimates.
Calibration against historical platform adoption curves and regulatory implementation timelines shaped projection reliability. The analytical framework segments across product type, end user, technology, and power rating dimensions throughout the forecast period. CAGRs derive from fitted adoption curves applied to vehicle production forecasts and content-per-vehicle assumptions. Key inputs include 48V electrical architecture migration pace and thermoelectric cooling module cost reduction trajectories.
Stress conditions across rare earth magnet price volatility, NHTSA guideline implementation timing, and Chinese EV fleet deployment rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about platform standardization timelines and supplier qualification barriers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Railway Interiors Market
Automotive Interior & Exterior
Automotive Cabin Air Filter Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market
Automotive Interior & Exterior
Global Automotive Window Power Sunshade Market
Automotive Interior & Exterior
Automotive Heaters Market
Automotive Interior & Exterior
Automotive Door Check Market
Automotive Interior & Exterior
Automotive Door Handles Market
Automotive Interior & Exterior
Automotive Exterior Materials Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
India Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Truck Parking Air Conditioner Market
Automotive Interior & Exterior
Automotive Panoramic Sunroof Market
Automotive Interior & Exterior
Automotive Mudguards Market
Automotive Interior & Exterior
Automotive Air Conditioning Market
Automotive Interior & Exterior
Global Automotive Interiors Market