
 Advanced Vehicle Side Mirror Market | 2026-2036
Advanced Vehicle Side Mirror Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Vehicle Side Mirror Market Outlook
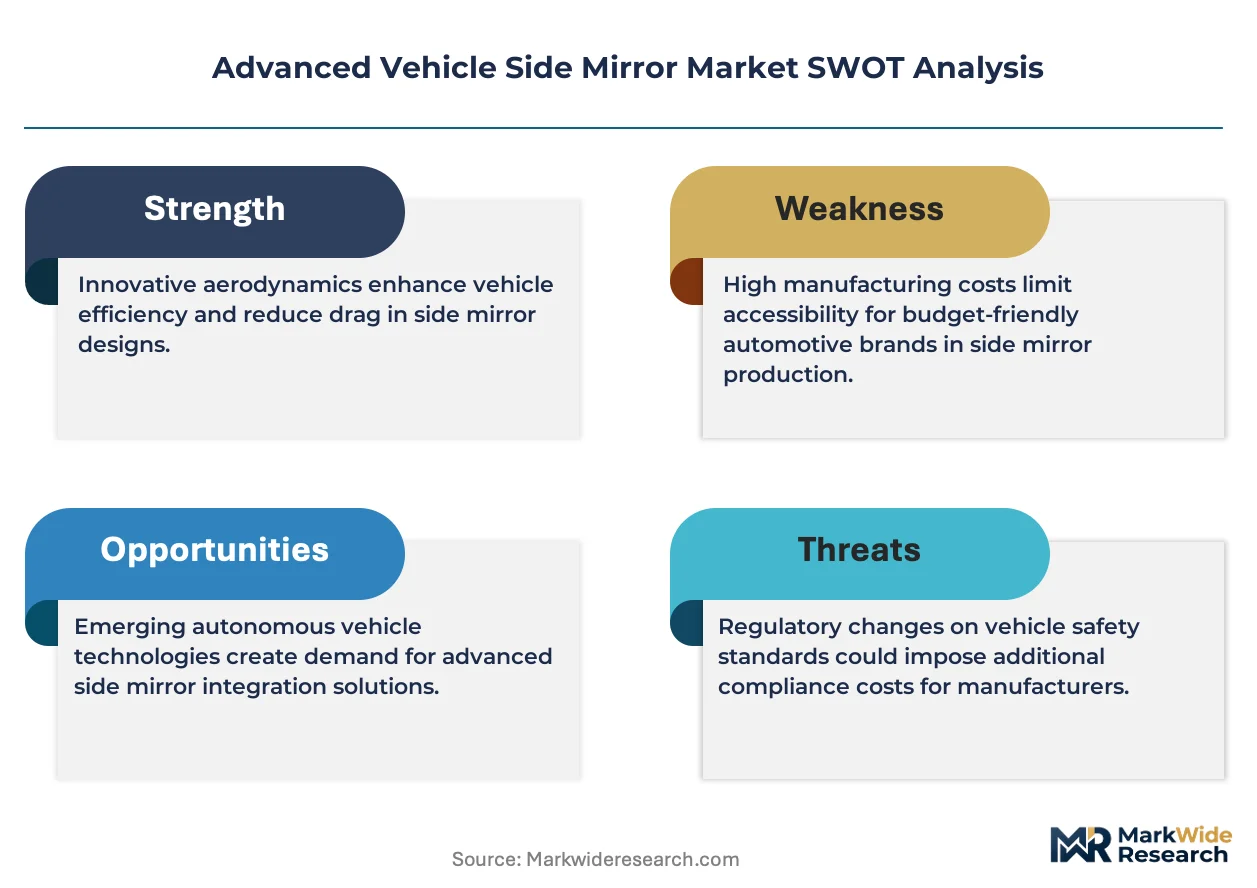
Polycarbonate is recalibrating cost and weight structures in advanced side mirror housings as OEMs pursue aerodynamic efficiency targets. Gentex Corporation leverages its electrochromatic expertise to sustain pricing power in the premium tier. Magna International Inc. anchors North American supply through integrated module assembly. Valeo SA competes on smart-mirror sensor fusion across European platforms.
Advanced vehicle side mirrors integrate optical substrates, heating elements, electronic actuators, and camera modules into aerodynamic housings designed to reduce drag coefficients below 0.30 Cd equivalents. These assemblies deliver rear-visibility compliance, blind-zone elimination, and real-time environmental feedback to driver-assistance controllers. Smart Mirrors and Camera-based systems are capturing margin pools as software-defined functionality replaces passive glass, while Heated mirrors retain volume dominance in mass-market OEM contracts across cold-climate manufacturing regions. Blind Spot Detection integration is expanding fastest among technology tiers as regulatory mandates harden.
NHTSA rear-visibility standards and EU General Safety Regulation requirements are forcing OEMs to embed camera or sensor-based alternatives to conventional mirror geometries. ISO 16505 and UN ECE R46 shape technical compliance pathways for camera-monitor systems replacing exterior mirrors in homologated vehicles. Stakeholders must resolve supply-chain dependencies in image-sensor procurement and validate cyber-secure data pipelines before regulatory deadlines eliminate grandfathered mirror configurations.
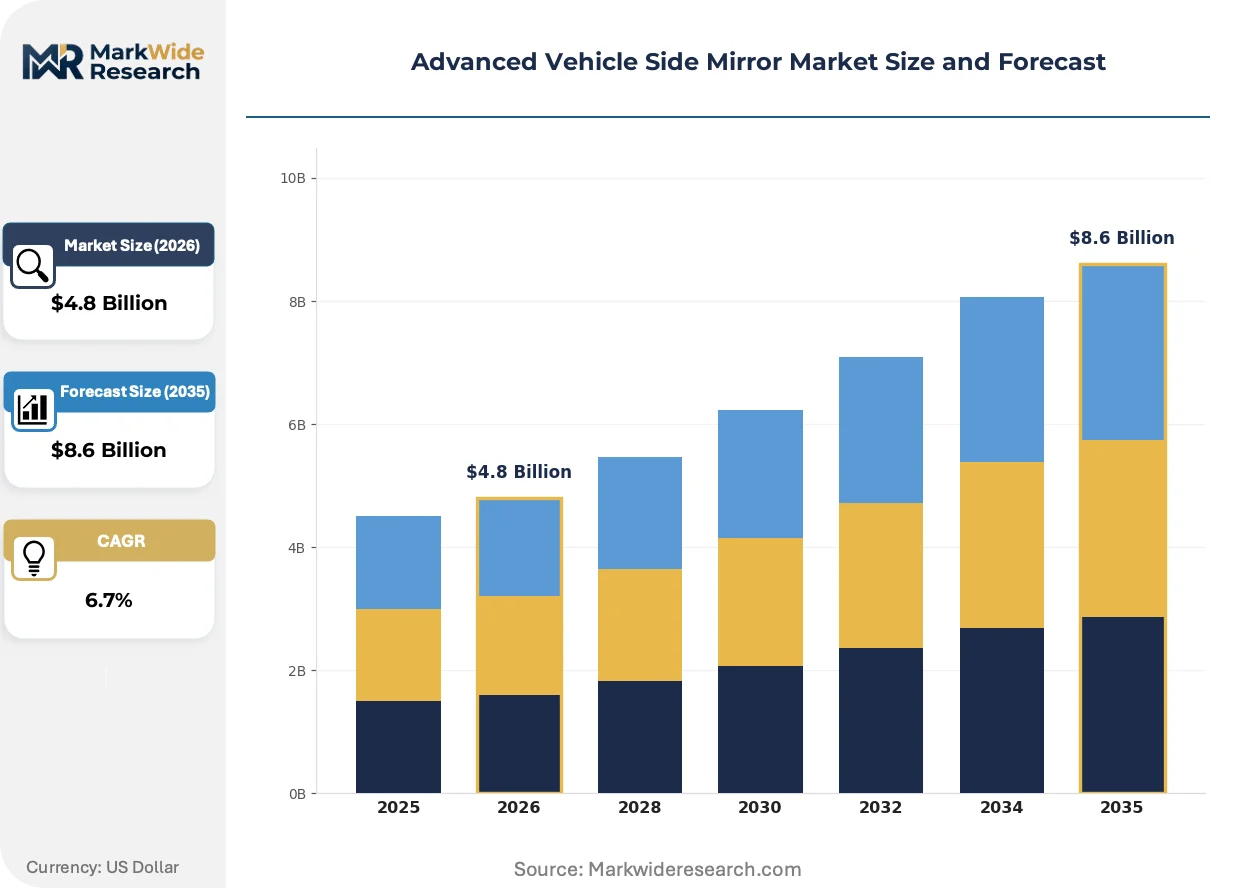
Market Dynamics
NHTSA and EU General Safety Regulation mandates are compressing the transition timeline from passive glass mirrors to integrated sensor architectures, forcing OEMs to redesign exterior mirror modules around camera-monitor systems and blind-zone detection electronics.
Growth Catalysts
- UN ECE R46 compliance pathways:Camera-monitor system homologation standards in Europe are accelerating OEM procurement of electrochromatic and digital mirror alternatives to conventional reflective glass.
- Blind Spot Detection mandates:Rear-visibility safety requirements across German and Japanese luxury passenger vehicle manufacturing are embedding radar and optical sensors directly into mirror housings.
- Aichi Prefecture manufacturing concentration:Toyota City and surrounding Nagoya industrial corridor suppliers are scaling integrated module assembly for camera-based mirror systems bound for export markets.
Market Restraints
- Image-sensor supply concentration:Sony and Samsung captive production of automotive-grade CMOS sensors creates procurement bottlenecks for tier-two mirror module assemblers.
- Polycarbonate resin price volatility:Feedstock fluctuations in benzene and propylene markets transmit directly to aerodynamic housing cost structures.
- Cybersecurity validation overhead:ISO/SAE 21434 compliance for camera data pipelines adds engineering cycles that extend program development timelines.
Strategic Opportunities
- Software-defined mirror functionality:Over-the-air updateable camera-monitor systems enable feature monetization through subscription-based field-of-view expansion and enhanced night-vision algorithms.
- Indian commercial vehicle retrofit demand:Bharat Stage VI compliance deadlines are driving fleet operator replacement of conventional mirrors with integrated blind-zone monitoring systems on existing truck platforms.
- Biometric driver monitoring convergence:Fusion of interior-facing cameras with exterior mirror sensor arrays creates unified cabin-environment perception architectures for Level 3 automation.
Industry Challenges
- Functional safety engineering scarcity:ISO 26262 ASIL-B qualified firmware developers remain concentrated at tier-one automotive electronics suppliers, constraining module vendor expansion.
- Legacy vehicle electrical architecture integration:Camera-based mirror systems require 100Mbit/s+ Ethernet backbone upgrades incompatible with 2015-2019 model year CAN-FD vehicle platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Vehicle Side Mirror Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chrome, Electrochromatic, Heated, Blind Spot Detection Technology: Smart Mirrors, LED Indicators, Cameras, Sensors End User: OEMs, Aftermarket Providers, Fleet Operators, Dealerships Installation Type: Factory Installed, Retrofit, Custom Fit, Standard Fit |
| Companies Covered | Magna International Inc., Gentex Corporation, Ficosa Internacional SA, Samvardhana Motherson Reflectec, SL Corporation, Ichikoh Industries Ltd., Murakami Corporation, Valeo SA, MEKRA Lang GmbH & Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Vehicle Side Mirror Market Strategic Shifts
Mirror module architecture is shifting from discrete component assembly to fused sensor-electronics-housing systems where software functionality determines competitive differentiation more than optical substrate quality.
Polycarbonate is consolidating its position in advanced side mirror housings as OEMs pursue drag coefficients below 0.30 Cd. German and Japanese luxury manufacturers are specifying glass-filled thermoplastic replacements for painted ABS housings. This material transition is consolidating supplier relationships around compounders with automotive lighting and exterior trim track records.
EU General Safety Regulation requirements are mandating blind-spot information systems on all new vehicle types from mid-decade. The regulation forces mirror module redesigns that integrate radar or ultrasonic sensors previously mounted in bumper fascias. Heavy commercial vehicle segments in Germany and France are experiencing the steepest compliance cost increases as they retrofit existing platforms.
Fleet procurement of integrated mirror-sensor modules is displacing aftermarket component sourcing for blind-zone detection. North American trucking operators are specifying factory-installed camera-monitor systems rather than retrofitting third-party electronics. This specification shift is most visible in long-haul route contracts where insurance underwriters now mandate OEM-certified visibility systems.
Advanced Vehicle Side Mirror Market Segmentation
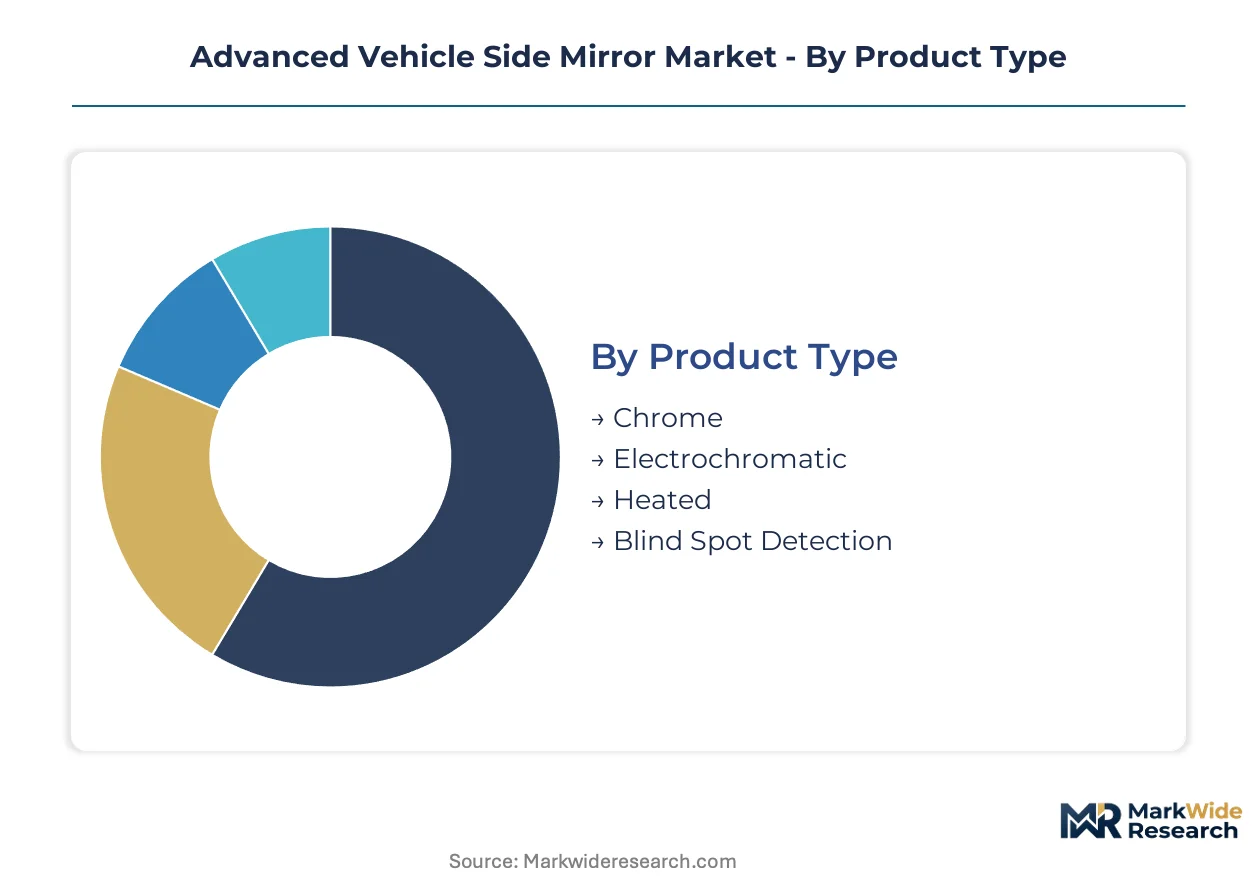
Advanced vehicle side mirror procurement splits across four distinct decision frameworks: material specification, electronic integration depth, supply channel preference, and installation timing. OEMs weight aerodynamic housing materials and sensor fusion capabilities differently than fleet operators prioritizing retrofit compliance and total cost of ownership.
Product Type:
Purchasing criteria center on climate exposure severity and regulatory visibility mandates, with cold-weather performance and electro-optical functionality commanding premium positioning.
- Electrochromatic:Auto-dimming glass substrates use gel-based electrochemical cells to reduce glare from trailing headlights. German luxury OEMs in Bavaria specify these for highway-speed night driving, with NHTSA glare-reduction guidelines accelerating North American adoption.
- Blind Spot Detection:Integrated radar or ultrasonic sensors embedded in mirror housings eliminate lateral collision risk. Japanese manufacturers in Aichi Prefecture embed these as standard on export-bound luxury sedans, driven by EU General Safety Regulation mandates for blind-spot information systems.
- Chrome:Vacuum-metallized reflective surfaces dominate cost-sensitive OEM contracts and aftermarket replacement channels. Aesthetic preference persists in commercial vehicle segments where durability outweighs electronic functionality.
- Heated:Resistive wire elements prevent ice accumulation on glass surfaces. Cold-climate manufacturing clusters specify these for mass-market volume, particularly in Michigan and Nagoya industrial corridors.
Volume sits with Heated mirrors across mass-market OEM contracts; growth tilts toward Blind Spot Detection as regulatory mandates harden in Europe and Japan.
Technology:
Module architecture decisions hinge on software-defined capability versus proven component reliability, with camera-monitor systems requiring electrical architecture upgrades that disqualify legacy platforms.
- Smart Mirrors:Integrated display surfaces combine reflective glass with embedded LCD or OLED panels for navigation overlay and rear-camera feeds. Valeo and Gentex compete on field-of-view algorithms and night-vision enhancement.
- Cameras:Exterior-mounted CMOS sensors replace optical mirrors entirely in homologated vehicles, requiring ISO 16505 and UN ECE R46 compliance validation. Sony image-sensor supply concentration creates procurement bottlenecks for tier-two assemblers.
- Sensors:Discrete radar and ultrasonic modules enable blind-zone monitoring without full camera-replacement architectures. Heavy commercial vehicles in Germany retrofit these to meet EU General Safety Regulation deadlines.
- LED Indicators:Surface-mounted turn-signal arrays improve side visibility for vulnerable road users. Standard fitment on European passenger vehicles, with regulatory pressure expanding specification to North American markets.
Cameras claim the steepest expansion trajectory as UN ECE R46 homologation pathways mature; LED Indicators retain volume dominance through regulatory baseline specification.
End User:
Contract structure and volume scale determine supplier engagement models, with captive production for OEMs contrasting against fragmented procurement for aftermarket channels.
- OEMs:Factory-integrated module assembly with 100% incoming quality inspection and just-in-sequence delivery. Magna International anchors North American supply through direct relationships with Detroit-area vehicle manufacturers.
- Fleet Operators:Specified procurement of camera-monitor systems for insurance compliance and driver liability reduction. North American long-haul trucking contracts now mandate OEM-certified visibility systems over third-party retrofit.
- Aftermarket Providers:Component-level distribution through automotive retail chains and independent repair networks. Price competition intensifies on heated mirror replacements and chrome housing assemblies.
- Dealerships:Dealer-installed accessory programs for premium feature upgrades on vehicle delivery. Limited to electrochromatic and LED indicator additions on existing mirror platforms.
OEMs concentrate module assembly volume; Fleet Operators drive fastest growth through regulatory-driven replacement cycles.
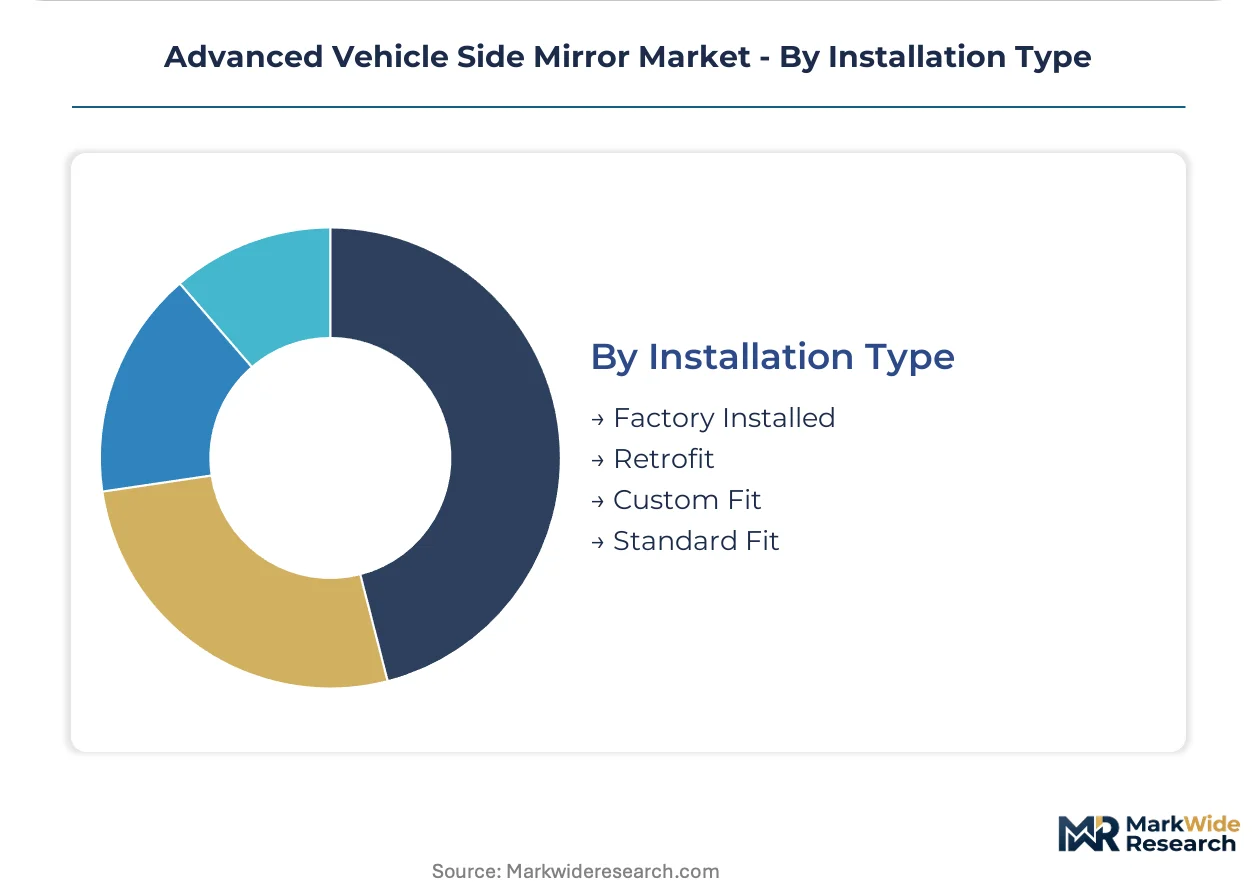
Installation Type:
Timing relative to vehicle production determines electrical architecture compatibility and validation burden, with factory installation enabling full sensor integration unavailable to retrofit channels.
- Factory Installed:Complete module assembly with validated cyber-secure data pipelines and ISO 26262 functional safety certification. Required for camera-monitor systems replacing exterior mirrors under UN ECE R46.
- Retrofit:Aftermarket installation of blind-zone monitoring electronics on existing mirror platforms. Indian commercial vehicle operators adopt these for Bharat Stage VI compliance deadlines on legacy truck fleets.
- Custom Fit:Bespoke housing geometries for low-volume specialty vehicles and commercial upfitters. Polycarbonate resin formulations enable rapid tooling changes for aerodynamic optimization.
- Standard Fit:Catalog replacement parts matching original equipment specifications. Dominates insurance-funded collision repair and independent service center procurement.
Standard Fit commands replacement volume; Factory Installed captures margin expansion through integrated sensor architectures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese luxury passenger vehicle OEMs concentrate procurement of electrochromatic and camera-based mirror systems, while NHTSA and EU regulatory mandates reshape supply chain geography across three continents.
United States
NHTSA rear-visibility standards and Michigan-based automotive manufacturing clusters drive factory-installed camera-monitor system adoption. Detroit-area OEMs source integrated modules from tier-one suppliers with validated cyber-secure data pipelines. Cold-climate specification of heated mirrors retains volume dominance in mass-market contracts.
Germany
EU General Safety Regulation mandates for blind-spot information systems compress redesign timelines for exterior mirror modules. Bavarian luxury manufacturers specify electrochromatic substrates for highway-speed night driving. KBA homologation requirements accelerate migration from passive glass to sensor-integrated architectures.
Japan
Aichi Prefecture manufacturing concentration around Toyota City anchors integrated module assembly for export-bound camera-based systems. METI industrial policy supports domestic image-sensor supply chain resilience. Nagoya industrial corridor suppliers scale production of radar-embedded mirror housings for EU-bound luxury sedans.
China
Domestic OEMs in the Yangtze River Delta and Pearl River Delta regions trial camera-monitor systems under GB standards alignment with UN ECE R46. MIIT regulations on intelligent connected vehicles create compliance pathways for digital mirror alternatives. Local module assemblers face procurement bottlenecks in automotive-grade CMOS sensors.
India
Bharat Stage VI compliance deadlines drive commercial vehicle fleet operators toward retrofit blind-zone monitoring systems on legacy truck platforms. Tamil Nadu and Maharashtra manufacturing hubs supply polycarbonate housings for aerodynamic efficiency targets. CDSCO-equivalent automotive component regulators validate aftermarket sensor integration protocols.
Advanced Vehicle Side Mirror Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium-tier electrochromatic suppliers commanding pricing power against scale-driven module assemblers. The vendor base organizes around three archetypes: integrated electronics-housing specialists, optical substrate technology holders, and regional contract manufacturers serving single OEM platforms. Dominant competitive moves include strategic partnerships for image-sensor procurement and capacity expansion in Aichi Prefecture and Bavaria industrial corridors.
Among North American tier-one suppliers, Magna International Inc. anchors factory-integrated module assembly relationships with Detroit-area vehicle manufacturers. Gentex Corporation occupies a position exemplifying electrochromatic technology specialization and premium-tier pricing power. Valeo SA represents the European sensor-fusion archetype, competing on smart-mirror architectures across homologated vehicle platforms.
| Leading Market Players |
|---|
| Magna International Inc. |
| Gentex Corporation |
| Ficosa Internacional SA |
| Samvardhana Motherson Reflectec |
| SL Corporation |
| Ichikoh Industries Ltd. |
| Murakami Corporation |
| Valeo SA |
| MEKRA Lang GmbH & Co. |
| Others |
Value Chain & Pricing Dynamics
Polycarbonate resin feedstock costs transmit directly from benzene and propylene markets through to aerodynamic housing price tiers, with German and Japanese OEMs absorbing premium-grade material premiums while mass-market contracts in Michigan and Nagoya industrial corridors negotiate volume-scale discounts on glass-filled thermoplastic specifications.
Pricing Analysis
Volume concentrates in heated mirror assemblies for cold-climate mass-market contracts, while margin pools accrue to electrochromatic and camera-monitor systems where ISO 16505 and UN ECE R46 certification creates scarcity value. Price differentiation separates OEM-certified factory installations from aftermarket retrofit channels, with fleet operators in North American long-haul trucking showing lowest sensitivity due to insurance mandate compliance requirements. Cost compression in standard-fit replacement parts is intensifying as polycarbonate compounders compete on automotive lighting and exterior trim track records.
Supply Chain Analysis
Workforce availability for ISO 26262 ASIL-B qualified firmware development concentrates in Aichi Prefecture, Bavaria, and Michigan automotive manufacturing clusters, constraining module vendor expansion outside tier-one automotive electronics suppliers. Image-sensor supply draws from Sony and Samsung captive production in Japan and South Korea, creating single-source vulnerability for tier-two mirror module assemblers. Raw material dependencies span polycarbonate resins, automotive-grade CMOS sensors, and radar substrates. Distribution runs through just-in-sequence OEM assembly lines, fleet operator specification channels, and fragmented aftermarket retail networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU General Safety Regulation mandates for blind-spot information systems erect a cost-of-compliance barrier that favors incumbent tier-one suppliers with validated cyber-secure data pipelines and KBA homologation experience, marginalizing unqualified assemblers.
For Market Incumbents: Anchor factory-integrated module assembly relationships through capacity addition in Aichi Prefecture and Bavaria industrial corridors. Defend against emerging camera-monitor specialists by deepening backward integration into image-sensor procurement partnerships and securing exclusive supply agreements with polycarbonate compounders holding automotive lighting track records.
For New Entrants and Emerging Players: Software-defined mirror functionality with over-the-air update capability offers the most penetrable wedge against entrenched hardware suppliers. Target Indian commercial vehicle retrofit demand for Bharat Stage VI compliance, where aftermarket blind-zone monitoring systems face lower certification barriers than factory-homologated camera-monitor architectures. Pursue fleet operator direct sales channels bypassing OEM specification gatekeepers.
For Investors and Strategic Acquirers: METI policy announcements on domestic image-sensor supply chain resilience are the leading indicator that Japanese government-backed consolidation will reshape tier-two vendor viability. Position for 5-10 year horizon around vertically integrated mid-cap specialists combining polycarbonate housing expertise with sensor fusion firmware capabilities. Watch for NHTSA rulemaking acceleration on rear-visibility standards as the inflection signal for North American camera-monitor system procurement velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | OEMs consolidate mirror module architectures across vehicle lines to reduce validation cycles under UN ECE R46. |
| Software-Defined Vehicle Investment | Over-the-air updateable camera-monitor systems enable subscription revenue from field-of-view expansion features. |
| Geographic Manufacturing Footprint | Capacity expansion in Aichi Prefecture and Bavaria secures proximity to Toyota City and German luxury OEM clusters. |
| Battery Supply Agreement | Power architecture upgrades for camera-monitor systems require validated electrical backbone partnerships with cell suppliers. |
| Charging Infrastructure Partnership | EV platform mirror integration demands coordination with high-voltage electrical system architects for thermal management. |
Study Parameters
Independent corroboration across OEM platform engineering directors, tier-one supplier procurement leads, and fleet operator specification managers underwrites the qualitative findings, supplemented by secondary validation through NHTSA regulatory filings, EU General Safety Regulation implementation guidance, vehicle production databases, and IHS Markit registration data. Bottom-up assembly cost modeling triangulates against top-down market sizing from mirror module shipment tracking.
Comparable-period anchoring to historical electrochromatic and camera-monitor adoption curves shaped the projection horizon, with segmentation modeling across vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derive from fitted growth curves against regulatory mandate timelines and OEM platform redesign cycles, incorporating image-sensor supply constraints and polycarbonate resin price volatility as industry-specific inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under image-sensor supply disruption or accelerated NHTSA rulemaking. Forecasts reflect documented assumptions on regulatory deadline adherence and OEM electrical architecture upgrade pacing. Material deviation in UN ECE R46 homologation pathway clarity or METI industrial policy implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Exterior LED Lighting Market
Automotive Interior & Exterior
Automotive Telescopic Mirror Market
Automotive Interior & Exterior
Automotive Air Conditioning Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Automotive Clear Coat Paint Market
Automotive Interior & Exterior
Asia-Pacific Automotive Interior Materials Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Blind Spot Mirror Market
Automotive Interior & Exterior
Heated Steering Wheel Market
Automotive Interior & Exterior
Automotive Insulation Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Automotive Seat Recliners Market
Automotive Interior & Exterior
Automotive Head Up Display (HUD) Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Automotive Heated Seat Market