
 Global on Highway Vehicle Lighting Market | 2026-2036
Global on Highway Vehicle Lighting Market Size, Share, and Industry Trends Forecast 2026-2036
Global on Highway Vehicle Lighting Market Intelligence
Advanced software engineering expertise for adaptive and matrix lighting systems is bifurcating the talent pool from traditional electrical component design. This shift benefits firms with strong software capabilities. KOITO MANUFACTURING CO., LTD. leverages its scale in LED and sensor integration to maintain a dominant position. Hella KGaA Hueck & Co. competes through its specialization in sophisticated electronic and software-driven lighting modules, while Valeo extends its reach by embedding lighting into broader advanced driver-assistance systems.
On-highway vehicle lighting encompasses all illumination and signaling devices mounted on vehicles designed for public roads. These systems, including headlights and taillights, must meet specific photometric performance standards for brightness, color, and beam pattern to ensure driver visibility and vehicle conspicuity. Within the technology segment, LED is displacing Halogen and Xenon sources due to its efficiency and design flexibility. OEM installation remains the primary channel, though the aftermarket installation segment sees activity in upgrades and replacements for older vehicles.
Regulatory frameworks from the US National Highway Traffic Safety Administration (NHTSA) and the United Nations Economic Commission for Europe (UNECE), such as UN Regulation No. 48, define mandatory performance and safety specifications. Compliance with these evolving standards, including recent approvals for adaptive driving beam systems in the United States, is essential for market access. Stakeholders must now navigate the integration of lighting with broader ADAS sensor suites and vehicle-to-everything (V2X) communication protocols.
Market Dynamics
The central structural force shaping the market is the regulatory-driven mandate for active safety, transforming vehicle lighting from a passive component into an intelligent, software-controlled system. This shift necessitates deep integration with vehicle sensor suites and advanced electronic control units.
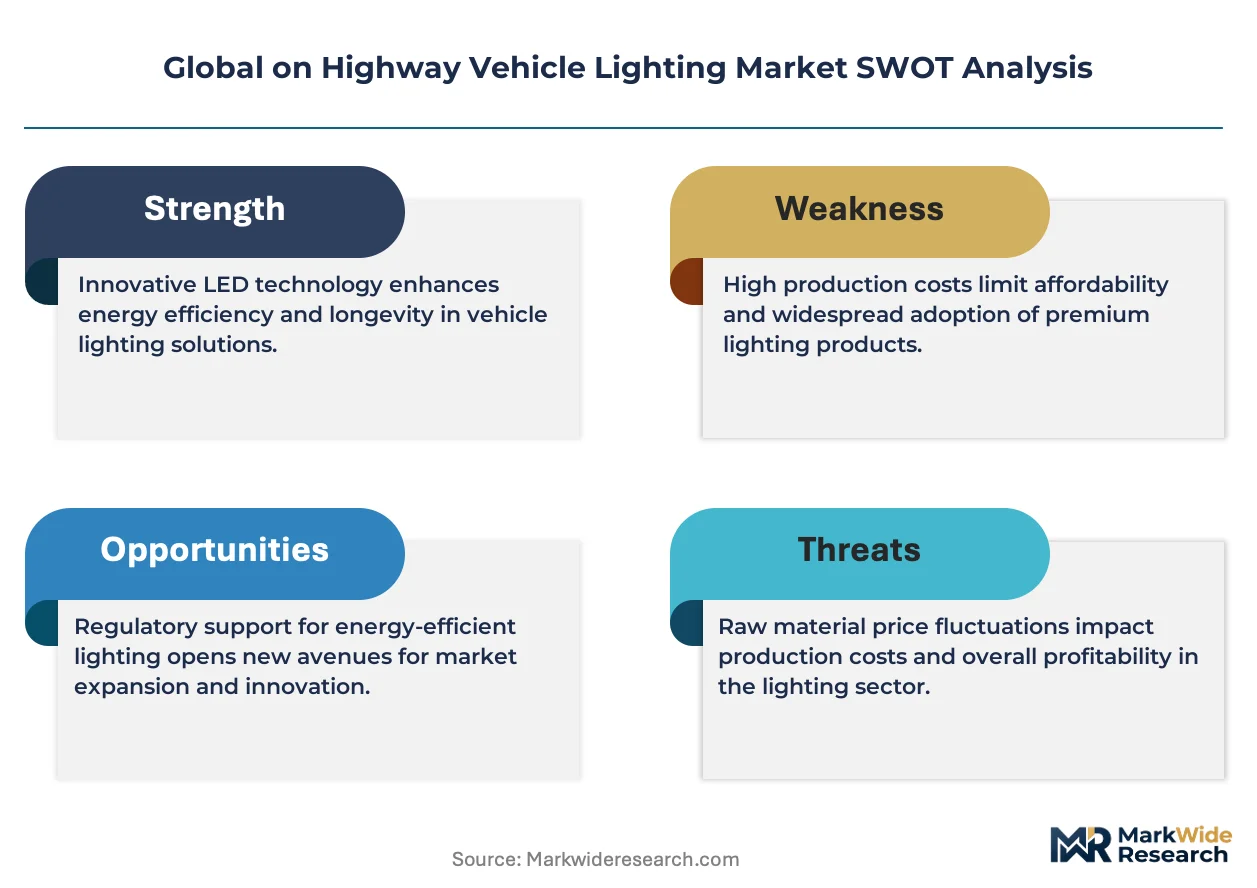
Growth Catalysts
- Regulatory Mandates:The final rule from the US NHTSA permitting adaptive driving beam (ADB) systems, aligning with established UNECE Regulation No. 48, compels automakers to adopt more advanced lighting technology to meet new safety standards and maintain market access.
- LED Technology Adoption:The superior energy efficiency, longer lifespan, and significant design flexibility of LED and OLED technologies are driving their rapid replacement of halogen and xenon sources, particularly within the high-volume new passenger vehicle segment.
- Manufacturing Concentration:China's role as the world's largest automotive producer creates immense, concentrated demand for advanced lighting systems, fostering a localized ecosystem of component suppliers and assembly plants to serve both domestic and export-oriented OEMs.
Market Restraints
- Cost Structure:The significantly higher bill-of-materials for adaptive and matrix LED headlamps, including costs for semiconductors, sensors, and control units, restricts their application in budget and economy-class vehicles, slowing mass-market penetration.
- Supply Chain Dependency:The industry's reliance on a concentrated global supply of specialized automotive-grade semiconductors and microcontrollers for lighting control modules creates vulnerability to shortages, price volatility, and geopolitical trade friction.
- Technical Complexity:The calibration and validation of camera-based ADB systems to ensure they perform reliably without causing glare in all weather and road conditions is technically complex, increasing development time and cost for vehicle manufacturers.
Strategic Opportunities
- Lighting as Communication:The convergence of high-resolution digital lighting with vehicle-to-everything (V2X) communication protocols opens opportunities to project warning symbols, pedestrian crosswalks, or navigation cues directly onto the road surface.
- Commercial Vehicle Upgrades:The heavy-duty truck and bus segments represent a significant opportunity for advanced lighting, as fleet operators seek to improve nighttime visibility, reduce driver fatigue, and enhance safety with durable, high-performance LED systems.
- Aftermarket Modernization:A substantial opportunity exists in the aftermarket to develop and market certified, plug-and-play LED conversion kits for the large global fleet of older vehicles equipped with legacy halogen headlamps, catering to owners seeking improved performance and aesthetics.
Industry Challenges
- Talent Bifurcation:A critical challenge is the growing gap between the need for software engineers skilled in machine vision and real-time embedded systems and the traditional talent pool of electrical hardware designers, creating hiring bottlenecks for suppliers and OEMs.
- Integration and Interoperability:Ensuring seamless, error-free communication between sophisticated lighting control modules and a vehicle's central domain controllers is a major integration hurdle, particularly across diverse vehicle architectures and supplier systems.
- Standardization Gaps:While core functions like ADB are becoming standardized, the lack of global consensus on next-generation features like road projection symbols creates development inefficiencies, forcing manufacturers to create market-specific versions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global on Highway Vehicle Lighting Market |
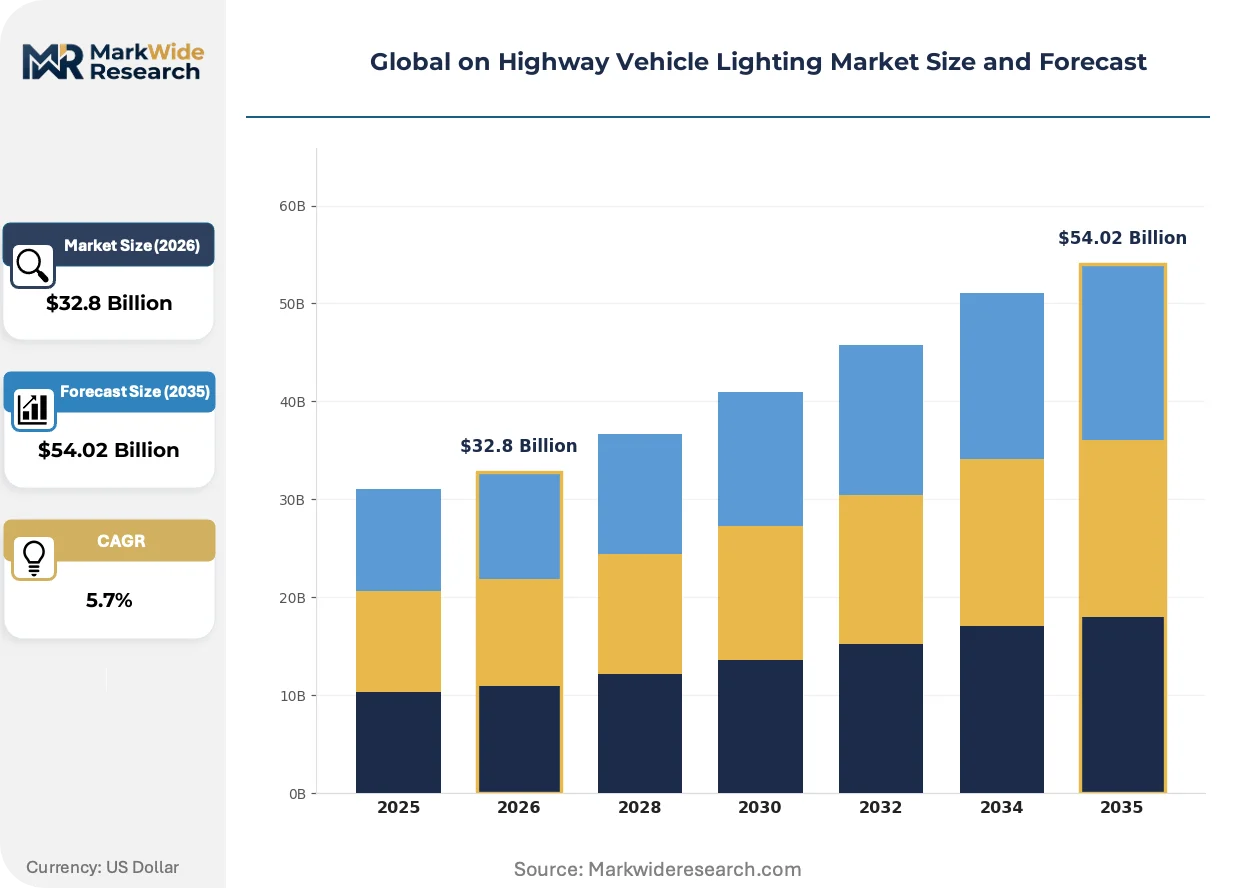
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $54.02 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Headlights, Taillights, Fog Lights, Interior Lighting Technology: Halogen, LED, Xenon, OLED End User: Automobile Manufacturers, Aftermarket Providers, Fleet Operators, Dealers Installation Type: OEM Installation, Aftermarket Installation, DIY Kits, Replacement Parts |
| Companies Covered | KOITO MANUFACTURING CO., LTD., Valeo, Marelli Automotive Lighting, Koninklijke Philips N.V., Stanley Electric Co., Ltd., Hella KGaA Hueck & Co., Osram Licht AG, ZKW Group, Varroc Lighting Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global on Highway Vehicle Lighting Market Strategic Shifts & Innovations
The evolution of on-highway vehicle lighting is defined by its transformation into an intelligent, communicative, and customizable system. Lighting is no longer just about illumination; it is becoming a key element of vehicle-to-environment interaction and brand differentiation, driven by advances in digital light processing and software.
Digital micromirror device (DMD) and micro-LED technologies enable the projection of high-resolution, dynamic light patterns. Premium automotive brands are the primary adopters, using this capability for advanced, glare-free high beams and animated welcome sequences. This technology is miniaturizing the physical optics required, allowing for ultra-slim headlamp profiles and integrating millions of controllable light points into a single, compact lighting module.
China's evolving GB standards for automotive lighting increasingly influence global product development cycles. While aligning with international UNECE norms, these standards include specific national requirements that necessitate design adaptations for market access. This dynamic most directly affects the new energy vehicle (NEV) segment, where manufacturers leverage distinctive and compliant lighting as a competitive feature to attract consumers in a crowded marketplace.
A notable behavioral shift is the consumer demand for personalization in vehicle lighting, from selectable daytime running light signatures to animated turn signals. This trend disrupts the static, one-size-fits-all model, compelling OEMs to offer software-defined lighting features that can be configured at purchase or upgraded over-the-air. This customization is most pronounced in the premium electric vehicle sectors of Europe and Asia, where visual identity is a critical part of brand appeal.
Global on Highway Vehicle Lighting Market Segmentation
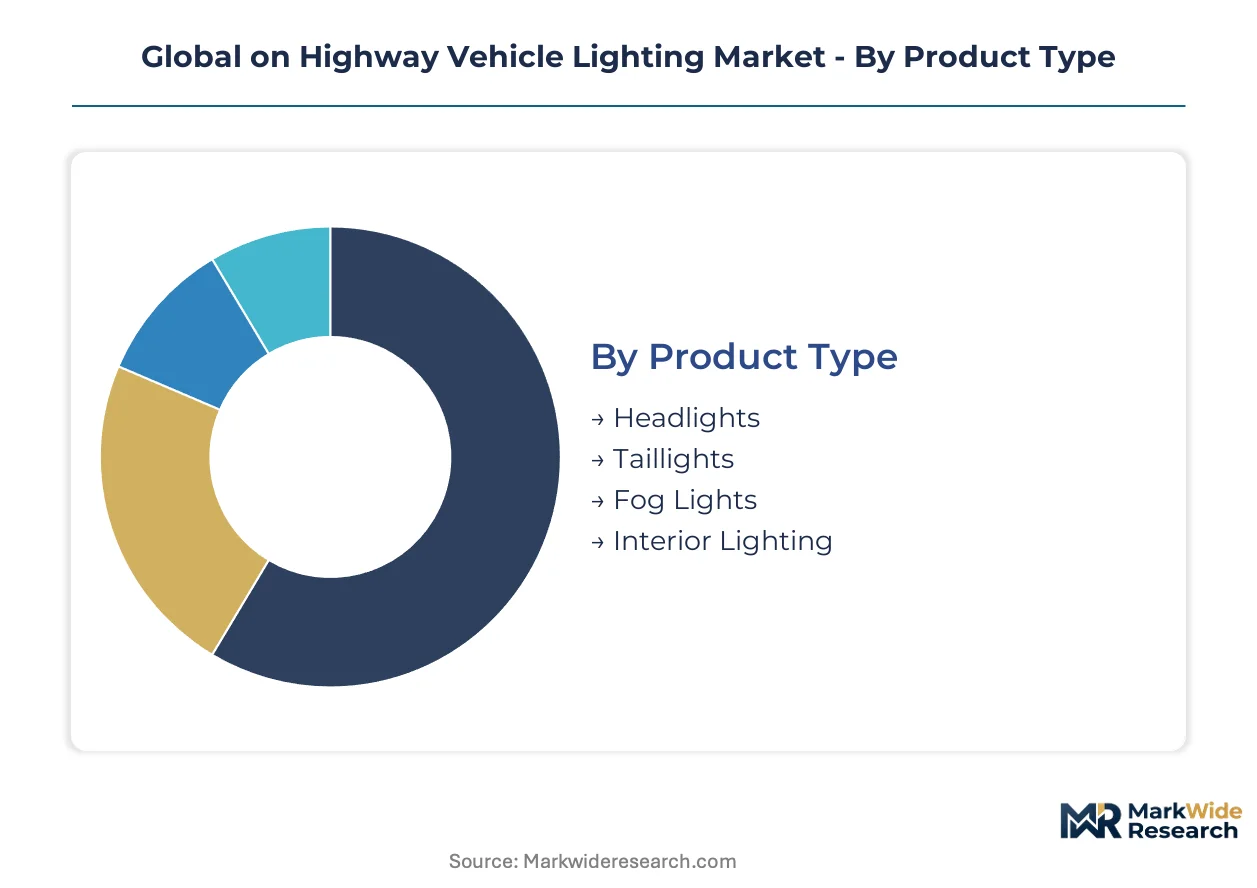
The global on highway vehicle lighting market exhibits diverse characteristics across its various segments. Understanding these distinctions is crucial for stakeholders to identify specific growth vectors and address unique market demands. This segmentation highlights the varying technological adoption rates and end-user requirements influencing product development and distribution strategies.
Product Type:
Product type segmentation reveals how core lighting components are distributed, with advanced headlamps seeing higher demand in regulated markets like the United States and Europe, while basic taillights maintain universal global presence.
- Headlights:These primary forward-facing illumination units incorporate complex optical systems and advanced features such as adaptive driving beams. Demand concentrates in developed automotive markets like Germany and Japan, driven by stringent safety regulations and consumer preference for premium features.
- Taillights:Rear-facing signaling devices provide braking, turn, and positional indications, often integrating LED arrays for design flexibility and energy efficiency. China's expansive automotive manufacturing sector drives significant volume for these components, serving both domestic new energy vehicles and export markets.
- Fog Lights:These auxiliary lights enhance visibility in adverse weather conditions, typically mounted lower. European countries often mandate their inclusion for passenger vehicle safety.
- Interior Lighting:Encompassing cabin illumination, ambient lighting, and dashboard backlighting, this segment enhances occupant comfort and vehicle aesthetics. Premium vehicle brands in South Korea prioritize customizable schemes.
Headlights command the established base. The steepest expansion runs through Taillights.
Technology:
Technology segmentation illustrates a clear cost hierarchy, with traditional halogen systems representing the entry-level, while advanced OLED solutions occupy the premium tier.
- LED:Light-emitting diode systems offer superior energy efficiency, extended lifespan, and compact form factors, enabling intricate design possibilities. Their adoption is accelerating in new passenger vehicles across all major automotive production hubs, including Mexico and India, due to regulatory push for efficiency.
- OLED:Organic light-emitting diode technology provides ultra-thin, flexible, and homogeneously illuminated surfaces, allowing for highly distinctive and customizable lighting signatures. European luxury car manufacturers, particularly in Germany, integrate OLEDs for brand differentiation and advanced signaling functions.
- Halogen:These incandescent lamps remain a cost-effective option for basic illumination, primarily in economy-class vehicles and aftermarket replacements. Emerging markets still rely on halogen systems for affordability.
- Xenon:Also known as High-Intensity Discharge (HID) lamps, xenon systems offer brighter light output but are phased out by LED technology. Their use persists in older premium vehicle models globally.
Halogen technology dominates the legacy segment. LED technology defines the future growth trajectory for the market.
End User:
End user segmentation highlights distinct purchasing behaviors, from initial vehicle integration by manufacturers to ongoing maintenance and upgrades by fleet operators.
- Automobile Manufacturers:These OEMs integrate lighting systems directly into new vehicle production lines, requiring high-volume supply and strict compliance with design and performance specifications. China's vast automotive industry represents the largest end-user segment for these integrated components.
- Fleet Operators:Companies managing commercial vehicles, such as heavy-duty trucks and buses, prioritize durable, high-performance lighting for improved safety and reduced downtime. North American fleet operators are increasingly investing in advanced LED systems to enhance nighttime visibility for drivers.
- Aftermarket Providers:These entities supply replacement parts and upgrade kits for vehicle owners seeking improved performance or aesthetics. The United States aftermarket for lighting components is substantial due to its large vehicle base.
- Dealers:Vehicle dealerships offer genuine replacement parts and accessories, often at the point of sale or during routine service. Dealership networks across Europe provide certified lighting solutions for brands.
Automobile Manufacturers drive primary demand. Fleet Operators are expanding their share with performance-driven upgrades.
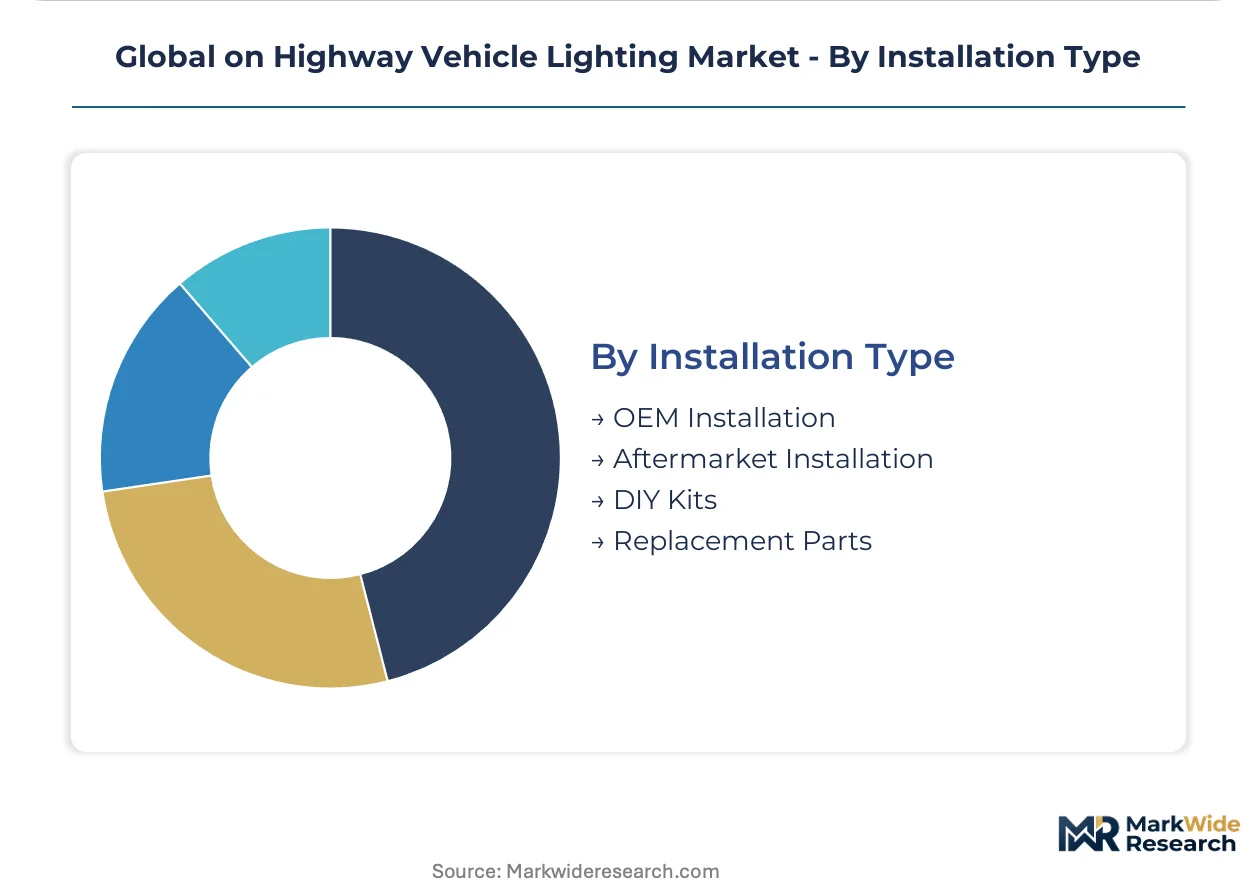
Installation Type:
Installation type segmentation reflects varying margin structures, with OEM installations characterized by high volume and competitive pricing, contrasted with the higher per-unit margins in specialized aftermarket segments.
- OEM Installation:Lighting systems are factory-fitted during the vehicle assembly process, requiring close collaboration between suppliers and automotive manufacturers. This segment accounts for the largest volume of lighting units, particularly in major production centers like Japan and South Korea.
- Aftermarket Installation:Consumers or service centers install lighting components post-purchase, typically for upgrades, repairs, or customization. This segment sees significant activity in Australia and Canada, where vehicle owners often seek performance enhancements for older models.
- DIY Kits:These consumer-friendly packages allow vehicle owners to install lighting upgrades themselves, often for aesthetic enhancements or minor performance. Online retail channels in the United States support a robust DIY lighting market.
- Replacement Parts:This category includes individual components sold to replace damaged or worn-out lighting units, supporting the longevity of the existing vehicle fleet. Global demand for replacement parts remains consistent.
OEM Installation remains the foundational volume driver. Aftermarket Installation is experiencing rapid growth as consumers seek customization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power for on-highway vehicle lighting exhibits asymmetry, with manufacturing hubs in China driving volume and competitive cost structures, while markets like Germany command higher prices for advanced, software-defined systems. This geographic divergence reflects differing regulatory pressures and consumer expectations. Demand for intelligent lighting systems continues to expand globally.
China
China's vast automotive production drives immense demand for advanced lighting systems, particularly for its new energy vehicle segment. The evolving GB standards for automotive lighting increasingly influence global product development cycles. Concentrated manufacturing in regions like the Yangtze River Delta fuels a localized ecosystem for component suppliers and assembly plants.
Germany
German luxury car manufacturers integrate OLEDs for brand differentiation and advanced signaling functions, driving demand for premium lighting solutions. Compliance with UNECE Regulation No. 48 is essential for market access across European vehicle platforms. Automotive lighting innovation clusters in cities like Stuttgart and Munich, focusing on digital light processing.
United States
The United States market sees significant demand for advanced headlamps, driven by the US NHTSA's final rule permitting adaptive driving beam systems. A substantial aftermarket exists for lighting components due to its large vehicle base. Online retail channels support a robust DIY lighting market across states like California and Texas.
Japan
Japanese automotive manufacturers prioritize OEM installation of lighting systems, requiring high-volume supply and strict compliance with design specifications. Japan's national safety regulations emphasize photometric performance standards for driver visibility. Major automotive production centers in regions like Kanto and Chubu integrate advanced LED and sensor technologies.
India
India's expanding automotive market accelerates LED adoption in new passenger vehicles, driven by efficiency and design flexibility. The country's regulatory push for efficiency influences the displacement of traditional halogen sources. Manufacturing hubs in Maharashtra and Tamil Nadu are increasingly integrating advanced lighting components into locally produced vehicles.
Global on Highway Vehicle Lighting Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the global on-highway vehicle lighting market. The industry exhibits a tiered structure, with established automotive lighting specialists and diversified electronics conglomerates competing across various segments. Key strategic archetypes include integrated system providers, specialized module manufacturers, and emerging software-centric innovators. Companies pursue strategic partnerships to integrate advanced sensor technologies and engage in targeted M&A activities to acquire software capabilities.
Integrated system providers, leveraging extensive scale and R&D, anchor the market's premium segment. KOITO MANUFACTURING CO., LTD. exemplifies this archetype, maintaining a dominant position through LED and sensor integration. Hella KGaA Hueck & Co. occupies a strong position as a specialized module manufacturer, focusing on sophisticated electronic and software-driven lighting. Valeo, a diversified automotive supplier, extends its reach by embedding lighting into broader advanced driver-assistance systems, representing a strategic move towards comprehensive vehicle integration.
| Leading Market Players |
|---|
| KOITO MANUFACTURING CO., LTD. |
| Valeo |
| Marelli Automotive Lighting |
| Koninklijke Philips N.V. |
| Stanley Electric Co., Ltd. |
| Hella KGaA Hueck & Co. |
| Osram Licht AG |
| ZKW Group |
| Varroc Lighting Systems |
| Others |
Cost & Logistics Intelligence
US NHTSA's final rule permitting adaptive driving beams gates both component supply qualification and price differentiation. Compliance with these evolving standards drives demand for advanced, higher-priced lighting systems.
Pricing Analysis
Configured-to-order pricing for advanced lighting systems contrasts with standard transactional pricing for basic units. Price differentiation stems from the customization level of software-defined features and the certification level for adaptive driving beams. Cost compression in the economy-class segment intensifies due to the high bill-of-materials for advanced components. Luxury vehicle manufacturers exhibit lower price sensitivity, while budget vehicle producers are highly sensitive to unit costs.
Supply Chain Analysis
Inbound logistics costs for specialized automotive lighting components are affected by port congestion in major manufacturing hubs. Geographic supply concentration centers on China, Japan, and Germany for complex assemblies. The industry relies on specialized automotive-grade semiconductors and microcontrollers for lighting control modules, creating single-source vulnerability. Distribution runs through OEM installation for new vehicles and aftermarket channels for upgrades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The on-highway vehicle lighting market presents a defensive moat story, primarily due to regulatory entrenchment. Evolving safety standards like those from US NHTSA create high barriers to entry and ensure sustained demand for compliant technologies.
For Market Incumbents: Shield core market share by investing heavily in advanced software engineering for adaptive systems. Pursue strategic partnerships to integrate lighting with broader ADAS sensor suites, mitigating talent bifurcation. Leverage existing OEM channel control and certification investments to maintain compliance leadership.
For New Entrants and Emerging Players: Anchor in underserved segments like aftermarket modernization, offering certified LED conversion kits for older vehicles. Target the commercial vehicle sector with durable, high-performance LED systems. Focus go-to-market strategies on plug-and-play solutions that simplify installation for vehicle owners.
For Investors and Strategic Acquirers: US NHTSA's ADB approval reshapes the acquisition landscape, favoring firms with robust software and integration capabilities. The market demonstrates long-term viability as lighting evolves into an intelligent, communicative system over the next 5-10 years. Target specialized module manufacturers and software-centric innovators. Increased adoption of V2X communication protocols in lighting serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Lighting R&D | Advances adaptive driving beam capabilities and enables new personalization features for OEMs. |
| ADAS Integration Partnerships | Ensures seamless communication between lighting modules and vehicle sensor suites, enhancing active safety. |
| Global Regulatory Compliance Investments | Secures market access in regions with evolving standards like China's GB standards and UNECE Regulation No. 48. |
| Micro-LED Technology Development | Enables higher-resolution projection capabilities and miniaturizes physical optics for premium automotive brands. |
| Aftermarket LED Conversion Kits | Captures demand from vehicle owners seeking improved performance and aesthetics for legacy halogen headlamps. |
Research Approach
Findings reconcile primary fieldwork against secondary review of vehicle production databases, IHS Markit registration data, and government safety reports. Primary interviews with OEM platform engineers, Tier 1 supplier procurement leads, and aftermarket distributors provided qualitative insights. This approach employed both bottom-up market sizing and top-down validation to ensure data integrity. Triangulation across these sources strengthened the quantitative and qualitative analysis.
Segmentation dimensions modeled included product type, technology, end-user, installation type, and regional production clusters. The analytical framework projected market growth across the analysis window, with compound annual growth rates derived from historical trends and anticipated technology adoption. Forecast inputs incorporated global vehicle production volumes and evolving regulatory compliance timelines. This provided a robust basis for market projections.
Material uncertainties — such as unforeseen geopolitical trade friction or prolonged semiconductor supply disruptions — sit outside the modeled envelope. Forecasts reflect assumptions regarding technology adoption and regulatory stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Smart Dashboard Display Market
Automotive Interior & Exterior
Advanced Vehicle Side Mirror Market
Automotive Interior & Exterior
PVC and PU Leather for Automotive Market
Automotive Interior & Exterior
Automotive Smart Faceplate Market
Automotive Interior & Exterior
Automotive Door Panel Market
Automotive Interior & Exterior
Germany Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Seating Systems Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Automotive Foam Market
Automotive Interior & Exterior
Automotive Cowl Screen Market
Automotive Interior & Exterior
Automotive Underbody Coatings Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Seat Comfort and Lumbar Actuator Systems Market
Automotive Interior & Exterior
Interior Materials for Pet-Friendly Vehicle Cabins Market
Automotive Interior & Exterior
Automotive Cabin Insulation Market
Automotive Interior & Exterior
Japan Automotive Flooring Market