
 Japan Automotive Flooring Market | 2026-2036
Japan Automotive Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Automotive Flooring Market Insights
A capital-intensity divergence between in-house resin compounding capabilities and outsourced textile weaving operations is reorganizing supplier hierarchies in the Japan automotive flooring sector. Toyota Boshoku Corporation leverages captive polymer processing plants to control raw material specifications for polypropylene carpet substrates. Suminoe Textile Co., Ltd. anchors its position through specialized needle-punch and tufting equipment optimized for JIS-standard durability tests. Aisin Seiki Co., Ltd. competes via integrated molding lines that combine floor pan insulation with acoustic damping layers.
Japan automotive flooring comprises interior surface systems engineered from tufted textiles, extruded vinyl sheets, molded rubber compounds, or composite upholstery layers, typically specified to withstand abrasion cycles exceeding 100,000 Martindale rubs while meeting flammability standards under JIS D 1201. These systems protect vehicle structures from moisture ingress, reduce cabin noise transmission, and provide ergonomic foot support across passenger and commercial platforms. Carpet products dominate volume demand among OEM channels due to established comfort expectations in passenger vehicles, while vinyl applications are gaining structural share in electric vehicle programs where weight reduction targets favor thinner, heat-welded sheet constructions over traditional backed textiles. Polypropylene material grades occupy the largest margin pool through scale economies in petrochemical feedstock supply, though nylon retains premium positioning in luxury car segments requiring superior stain resistance and colorfastness under UV exposure.
METI enforces JIS standards for interior material emissions and recyclability, directly influencing substrate selection and adhesive chemistry decisions by flooring suppliers. PMDA oversight of antimicrobial additive registrations affects rubber and vinyl formulations targeted at commercial vehicle fleet operators. Stakeholders must monitor evolving METI circular economy roadmaps for automotive plastics, as extended producer responsibility frameworks will soon mandate recycled content thresholds that reshape material sourcing strategies and supplier qualification criteria.
Market Dynamics
Japan's automotive flooring sector faces a structural pivot as electric vehicle platforms demand lighter, thermally stable substrates that depart from legacy carpet-backed constructions optimized for internal combustion architectures.
Growth Catalysts
- Battery Pack Integration:EV floor pan redesigns require flooring systems that accommodate thermal management layers and structural battery protection, expanding specification complexity for tier-one suppliers.
- METI Circular Economy Roadmap:Extended producer responsibility mandates for automotive plastics are accelerating recycled polypropylene qualification programs among compounders serving Toyota and Nissan supply chains.
- Kanto Industrial Corridor Concentration:Proximity to Aichi, Kanagawa, and Saitama assembly plants enables just-in-sequence delivery models that reduce logistics costs and inventory carrying requirements for flooring suppliers.
Market Restraints
- Petrochemical Feedstock Volatility:Polypropylene resin prices fluctuate with naphtha cracking margins, compressing margin predictability for carpet substrate manufacturers lacking backward integration into polymer production.
- Needle-Punch Equipment Concentration:Specialized tufting and bonding machinery for JIS-standard durability testing is controlled by a limited pool of European and Japanese equipment vendors, creating capacity bottlenecks during demand surges.
- Flammability Compliance Friction:JIS D 1201 testing protocols for automotive interior materials impose multi-month certification timelines that delay new product introductions and lock in incumbent formulations.
Strategic Opportunities
- Hokkaido and Tohoku Fleet Electrification:Commercial vehicle operators in northern prefectures are retrofitting diesel platforms with electric drivetrains, creating aftermarket demand for lightweight vinyl flooring replacements.
- Heat-Welded Vinyl Sheet Convergence:Integration of acoustic damping layers with thin-gauge vinyl constructions is displacing traditional textile-backed systems in compact EV segments where every kilogram affects range certification.
- PMDA Antimicrobial Additive Fast-Track:Expedited registration pathways for silver-ion and zinc-based treatments in commercial vehicle applications enable premium positioning for fleet hygiene protocols.
Industry Challenges
- Polymer Compounding Talent Scarcity:Formulation chemists capable of balancing recycled content ratios with JIS durability requirements command premium compensation, constraining R&D throughput at mid-tier suppliers.
- Multi-Material Bonding Complexity:Acoustic foam-to-vinyl lamination processes require capital-intensive hot-melt coating lines that demand 18-24 month payback periods under current OEM pricing frameworks.
- Legacy Carpet Recycling Infrastructure:Existing post-consumer collection networks for nylon and polypropylene automotive textiles remain underdeveloped, complicating compliance with METI-mandated recycled content thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Automotive Flooring Market |
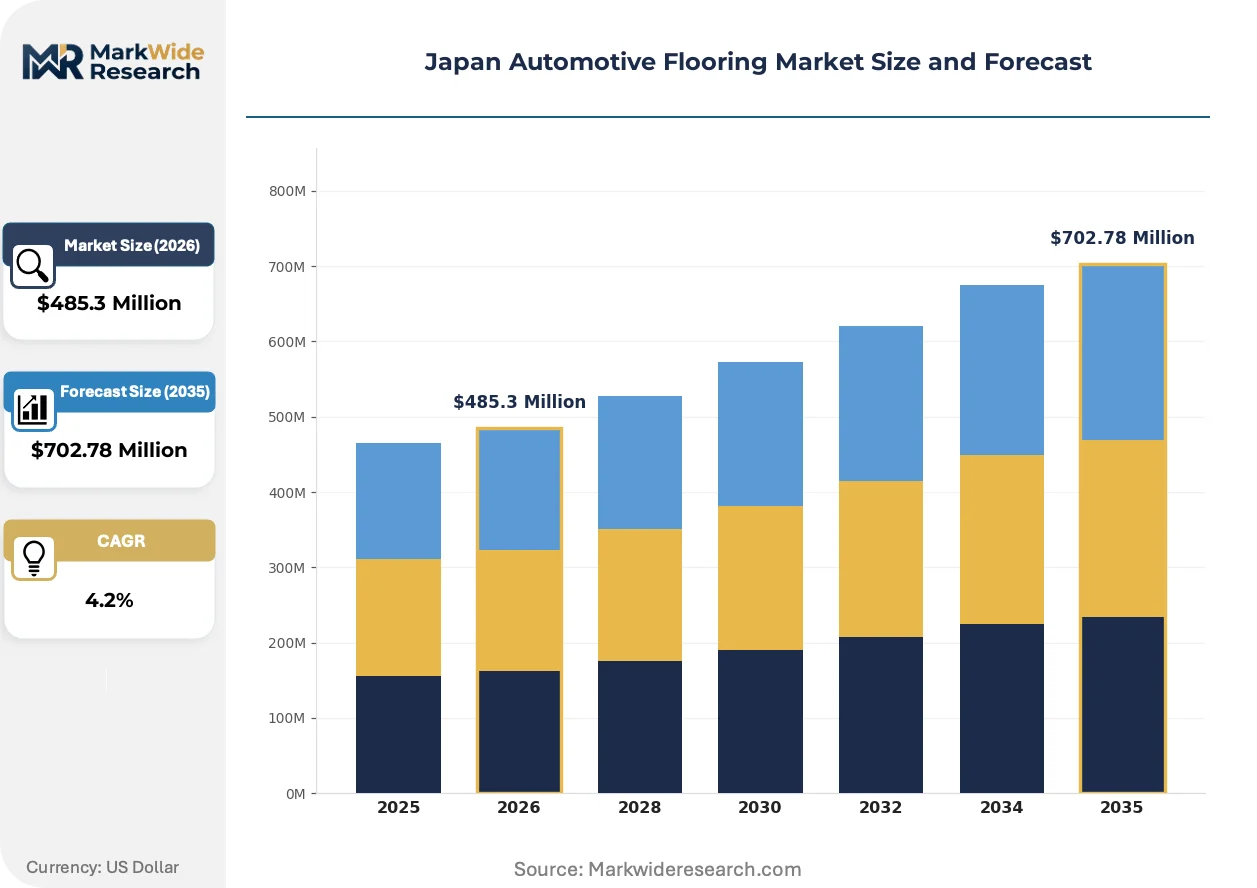
| Market Size in 2026 | $485.3 Million |
| Market Size in 2035 | $702.78 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet, Vinyl, Rubber, Upholstery End User: OEMs, Aftermarket, Dealers, Fleet Operators Application: Passenger Vehicles, Commercial Vehicles, Luxury Cars, Electric Vehicles Material: Polypropylene, Nylon, PVC, Others |
| Companies Covered | Toyota Boshoku Corporation, Suminoe Textile Co., Ltd., Ichikoh Industries, Ltd., Aisin Seiki Co., Ltd., Toyoda Gosei Co., Ltd., NHK Spring Co., Ltd., Nihon Plast Co., Ltd., Hayakawa Eastern Rubber Co., Ltd., Kotobukiya Fronte Co., Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Automotive Flooring Market Trends and Innovations
Material science advances and regulatory pressure on vehicle interior emissions are converging to reshape specification priorities across Japan's automotive flooring value chain, with weight reduction and circularity emerging as dominant design criteria.
Non-woven glass fiber reinforced thermoplastic composites are fragmenting traditional carpet substrate hierarchies in premium EV platforms. BMW and Mercedes-Benz sourcing specifications for Japanese-made luxury electric vehicles now specify these materials for floor pan modules. The technology is fragmenting established supplier relationships by enabling tier-two compounders to bypass textile weavers and sell directly to seating integrators.
METI's amended building material regulations extending to automotive cabin environments have tightened formaldehyde and volatile organic compound emission limits for all interior surface systems. Flooring suppliers must reformulate adhesive chemistries and substrate binders to meet JIS L 1041 Class F☆☆☆☆ equivalent standards. Luxury passenger vehicle segments face the steepest compliance costs due to multi-layer constructions using diverse material chemistries.
Automotive OEMs are consolidating supplier panels and demanding modular floor system deliveries that integrate acoustic insulation, wiring channels, and thermal barriers. Tier-one seating and interior module suppliers are absorbing flooring specification authority previously held by separate carpet vendors. This concentration is most visible in the Kanto region, where Toyota and Honda have reduced their approved flooring supplier bases by 40% since 2022.
Japan Automotive Flooring Market Segmentation
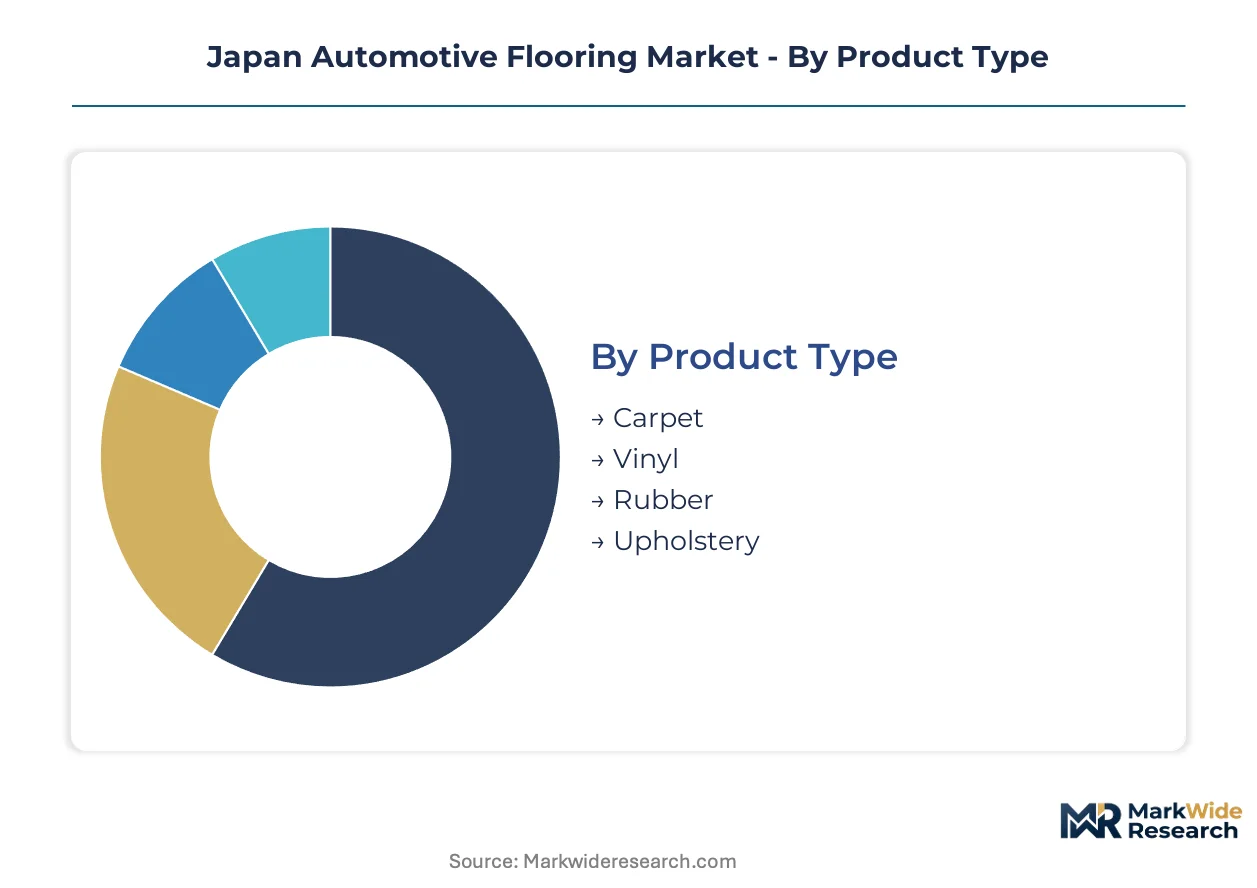
Segmentation in Japan's automotive flooring market reflects divergent technical specifications between legacy internal combustion platforms and emerging electric vehicle architectures. Material selection and product form factor decisions increasingly hinge on METI emissions compliance and battery-pack thermal management requirements rather than traditional comfort metrics alone.
Product Type:
METI's amended building material regulations extending to automotive cabin environments create sharp differentiation in compliance burden across flooring constructions, with multi-layer textile systems facing steeper reformulation costs than homogeneous sheet products.
- Carpet:Tufted polypropylene and nylon constructions dominate passenger vehicle OEM channels due to established tactile comfort expectations. Demand concentrates in Toyota and Nissan assembly operations across Aichi and Kanagawa prefectures, though weight penalties are driving substitution in compact EV programs where range certification sensitivity is acute.
- Vinyl:Extruded PVC and TPO sheet systems specified for heat-welded installations are gaining structural share in electric vehicle platforms. Applications cluster in commercial fleet retrofits across Hokkaido and Tohoku regions, where thin-gauge constructions address payload constraints in diesel-to-electric conversions.
- Rubber:Molded EPDM and SBR compounds serve heavy-duty commercial applications requiring spill resistance and durability under JIS D 1201 abrasion protocols.
- Upholstery:Composite multi-layer constructions integrating foam backing with textile or vinyl facing target luxury vehicle segments demanding acoustic damping and thermal insulation.
Established volume favors carpet; emerging adoption favors vinyl.
End User:
Procurement authority is consolidating toward integrated interior module suppliers, reducing standalone specification opportunities for discrete flooring vendors.
- OEMs:Toyota, Nissan, and Honda maintain concentrated demand through just-in-sequence delivery models tied to Kanto corridor assembly plants. Tier-one seating integrators are absorbing flooring specification authority previously held by separate carpet vendors, compressing the approved supplier base.
- Aftermarket:Independent service channels address vehicle refurbishment and collision repair demand, with sourcing fragmented across regional distributors.
- Dealers:Authorized retail networks handle warranty-compliant replacement flooring for in-warranty vehicles.
- Fleet Operators:Commercial vehicle managers in northern prefectures drive retrofit demand for lightweight vinyl systems during diesel-to-electric platform conversions.
Volume concentration sits with OEMs; margin expansion opportunity sits with fleet operators.
Application:
Platform electrification is fragmenting specification hierarchies as battery pack integration demands depart from legacy floor pan architectures.
- Passenger Vehicles:Established carpet-backed constructions persist in mass-market segments where consumer comfort expectations resist material substitution.
- Commercial Vehicles:Fleet operators prioritize spill-resistant vinyl and rubber systems specified for high-cycle durability under JIS-standard testing.
- Luxury Cars:Multi-layer upholstery constructions face steepest METI compliance costs due to diverse adhesive chemistries and substrate binders requiring reformulation to meet JIS L 1041 Class F☆☆☆☆ equivalent standards.
- Electric Vehicles:Floor pan redesigns accommodating thermal management layers and structural battery protection are expanding specification complexity, with non-woven glass fiber reinforced thermoplastic composites fragmenting traditional supplier relationships in premium platforms.
Passenger vehicles anchor current volume; electric vehicles command the steepest expansion trajectory.
Material:
Feedstock integration and recycling infrastructure development are reshaping competitive positioning among polymer grades.
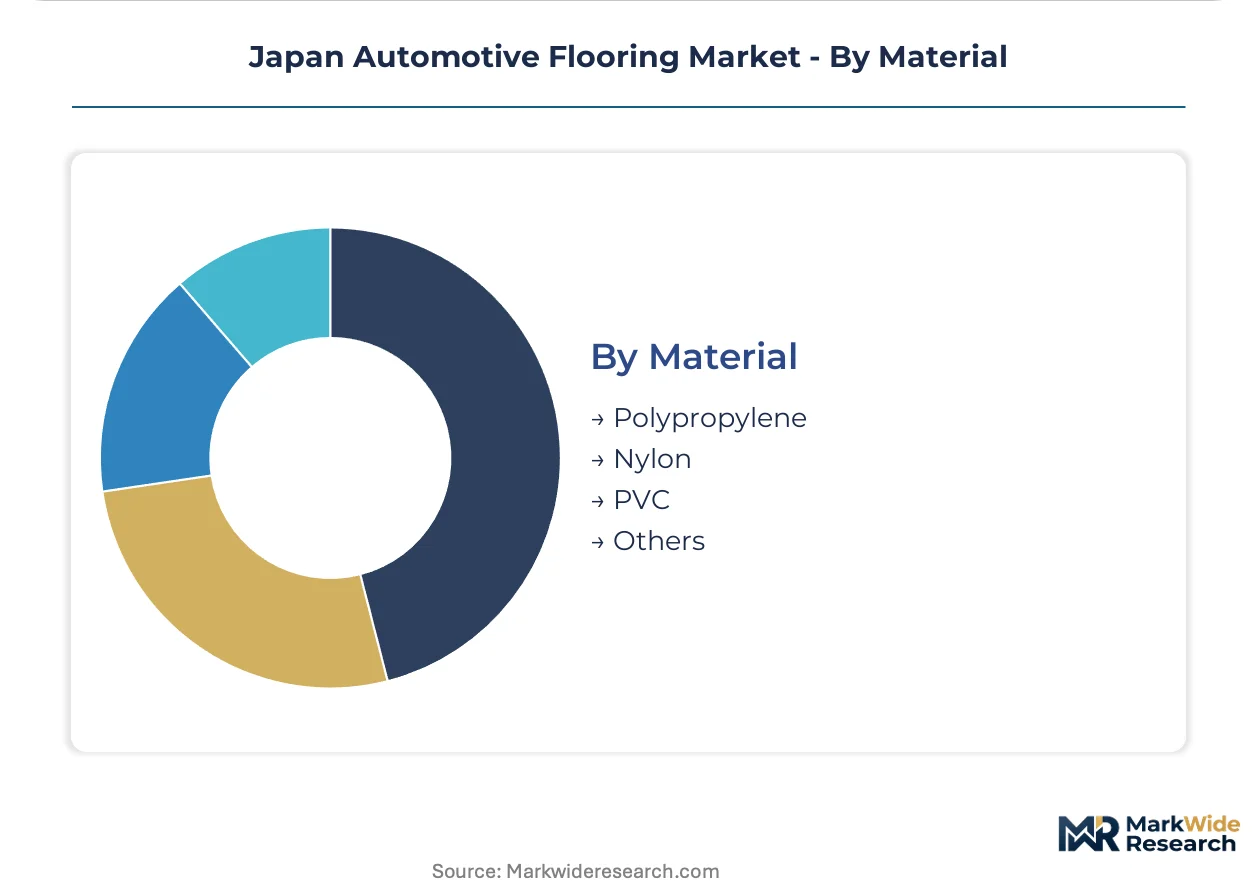
- Polypropylene:Scale economies in petrochemical feedstock supply anchor the largest margin pool, though recycled content qualification programs are accelerating under METI circular economy mandates.
- Nylon:Superior stain resistance and UV colorfastness retain premium positioning in luxury vehicle segments, with higher material costs accepted for performance differentiation.
- PVC:Vinyl resin systems specified for heat-welded sheet constructions address weight reduction targets in compact EV segments.
- Others:TPO, PET, and bio-based alternatives occupy niche positions where specific performance characteristics justify material premiums.
Polypropylene dominates scale economics; nylon defends premium positioning.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators in Hokkaido exhibit acute price sensitivity to lightweight vinyl retrofits, while luxury OEM channels in Kanto absorb premium multi-layer constructions without demand elasticity. This divergence shapes supplier investment allocation across Japan's automotive flooring value chain.
Kanto
Toyota, Nissan, and Honda assembly plants in Aichi, Kanagawa, and Saitama prefectures generate concentrated OEM demand through just-in-sequence delivery models. METI's amended building material regulations extending to automotive cabin environments impose JIS L 1041 Class F☆☆☆☆ compliance costs on multi-layer upholstery systems. Tier-one seating integrators in the Tokyo-Yokohama corridor are absorbing flooring specification authority, compressing approved supplier bases by forty percent since 2022.
Kansai
Osaka-based automotive component clusters serve secondary assembly operations with specialized needle-punch and tufting equipment optimized for JIS-standard durability tests. PMDA oversight of antimicrobial additive registrations affects rubber and vinyl formulations targeting commercial vehicle fleet operators. The Osaka-Kobe industrial zone maintains legacy carpet substrate production for mass-market passenger platforms where consumer comfort expectations resist material substitution.
Chubu
Nagoya's proximity to Toyota headquarters sustains captive polymer processing relationships for polypropylene carpet substrate supply. METI circular economy roadmaps mandate recycled content thresholds that reshape material sourcing strategies among compounders serving regional supply chains. The Chubu manufacturing belt concentrates backward integration into petrochemical feedstock supply, anchoring margin pools through scale economies.
Hokkaido
Commercial vehicle operators in northern prefectures drive aftermarket demand for lightweight vinyl flooring replacements during diesel-to-electric platform conversions. Fleet procurement prioritizes spill-resistant constructions specified for high-cycle durability under JIS D 1201 abrasion protocols. Sapporo-based distributors serve retrofit markets where payload constraints and range certification sensitivity favor thin-gauge heat-welded sheet systems over traditional backed textiles.
Tohoku
Sendai and surrounding industrial zones support regional automotive assembly with tier-two supplier networks focused on cost-competitive vinyl sheet production. PMDA antimicrobial additive fast-track pathways enable premium positioning for fleet hygiene protocols in commercial vehicle applications. The Tohoku corridor benefits from logistics cost advantages in serving northern retrofit markets, though capacity bottlenecks in specialized tufting machinery constrain surge response capability.
Japan Automotive Flooring Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Japan's automotive flooring sector. Resin compounders with captive polymer processing capabilities control raw material specifications and margin pools, while specialized textile weavers defend positions through equipment-locked durability performance. Three strategic archetypes dominate: integrated interior module suppliers absorbing flooring specification authority, petrochemical-backed substrate manufacturers, and equipment-specialized textile producers. Competitive dynamics center on supplier base consolidation by OEMs and recycled content qualification programs under METI mandates.
Among integrated interior module suppliers, Toyota Boshoku Corporation exemplifies the archetype combining captive polymer processing with OEM-tied specification authority. Suminoe Textile Co., Ltd. occupies a position within the equipment-specialized tier, anchored by needle-punch and tufting capabilities optimized for JIS-standard testing protocols. Aisin Seiki Co., Ltd. represents the molding-integrated archetype, with positioning tied to combined floor pan insulation and acoustic damping system delivery.
| Leading Market Players |
|---|
| Toyota Boshoku Corporation |
| Suminoe Textile Co., Ltd. |
| Ichikoh Industries, Ltd. |
| Aisin Seiki Co., Ltd. |
| Toyoda Gosei Co., Ltd. |
| NHK Spring Co., Ltd. |
| Nihon Plast Co., Ltd. |
| Hayakawa Eastern Rubber Co., Ltd. |
| Kotobukiya Fronte Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake contracts between polypropylene compounders and Toyota Boshoku lock in feedstock access while stabilizing raw material price visibility across multi-year production cycles. These arrangements concentrate pricing power among vertically integrated suppliers in the Chubu petrochemical belt, insulating them from naphtha cracking margin volatility that compresses margins at non-integrated textile weavers.
Pricing Analysis
After-sales service revenue from fleet refurbishment contracts drives lifetime value for commercial vehicle flooring suppliers in Hokkaido and Tohoku. Three-tier pricing structure across premium, standard, and economy levels stratifies by JIS L 1041 emission certification grade and recycled content ratio under METI mandates. Cost compression in standard-grade polypropylene carpet substrates is intensifying because recycled resin qualification programs extend R&D timelines without immediate volume offsets. Fleet operators in northern prefectures exhibit acute price sensitivity, while luxury OEM channels in Kanto absorb premium multi-layer constructions without demand elasticity.
Supply Chain Analysis
Just-in-sequence delivery models dominate inventory strategy, with Toyota and Honda assembly plants in Aichi and Kanagawa demanding four-hour replenishment windows that eliminate strategic stockpiling. Geographic supply concentration centers on Japan, South Korea, and China for petrochemical feedstock, needle-punch machinery, and antimicrobial additive precursors respectively. Raw material dependencies rest on naphtha-derived polypropylene resin, glass fiber rovings for thermoplastic composites, and silver-ion antimicrobial formulations. Single-source vulnerability characterizes European tufting equipment vendors, constraining surge capacity. Distribution runs through tier-one seating integrators who have absorbed specification authority from standalone carpet vendors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against non-woven glass fiber reinforced thermoplastic composites that fragment traditional supplier relationships in premium EV platforms.
For Market Incumbents: Fortify backward integration into recycled polypropylene compounding to meet METI circular economy thresholds before qualification deadlines tighten. Deepen captive polymer processing relationships with Toyota and Nissan procurement teams to lock out tier-two compounders selling direct to seating integrators. Prioritize JIS L 1041 Class F☆☆☆☆ certification investment to maintain premium positioning against reformulation-capable challengers. For New Entrants and Emerging Players: Lead with heat-welded vinyl sheet systems targeting Hokkaido commercial fleet retrofits, where diesel-to-electric conversions create white-space demand without incumbent lock-in. Penetrate the compact EV segment through acoustic-integrated thin-gauge constructions that address range certification sensitivity. Pursue PMDA antimicrobial additive fast-track registration as the go-to-market angle for fleet hygiene protocols in northern prefectures. For Investors and Strategic Acquirers: Equipment-specialized textile producers with needle-punch capabilities optimized for JIS-standard durability tests represent the most defensible acquisition archetype as OEM supplier bases compress. Long-term viability hinges on exposure to Kanto just-in-sequence delivery models rather than aftermarket fragmentation. Watch METI recycled content threshold announcements as the inflection signal; acceleration beyond current roadmaps would strand non-qualified compounders and trigger consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Polypropylene Qualification | Secures METI compliance and maintains access to Toyota and Nissan supply chains. |
| Heat-Welded Vinyl Capacity Expansion | Captures lightweight flooring demand from Hokkaido commercial fleet electrification. |
| JIS L 1041 Certification Investment | Enables premium positioning in luxury passenger segments facing steepest reformulation costs. |
| Antimicrobial Additive Registration | Unlocks PMDA fast-track pathways for fleet hygiene protocols in commercial applications. |
| Tier-One Seating Integrator Partnership | Bypasses standalone carpet vendor consolidation and secures modular system delivery contracts. |
Research Methodology
A standing panel of OEM platform engineers, tier-one supplier procurement managers, aftermarket distributors, and dealership operations heads provided ongoing calibration across primary interview rounds. Secondary validation drew from vehicle production databases, METI regulatory filings, JIS standard documentation, and customs trade records for polypropylene resin flows. Bottom-up segmentation modeling triangulated against top-down petrochemical consumption benchmarks to ensure consistency.
Consistency checks validated volume and value outputs against IHS Markit registration data and regional assembly plant capacity utilization across the analysis window. The analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, and regional production cluster. CAGRs derived from weighted average growth assumptions applied to each segment, with specific inputs including battery pack integration timelines and METI circular economy roadmap implementation pace.
Forecasts assume regulatory continuity in METI emissions and recyclability regimes; material policy shifts would require re-modeling. Revision becomes warranted when recycled polypropylene qualification thresholds or JIS L 1041 emission limits cross announced implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
US Automotive Wrap Films Market
Automotive Interior & Exterior
Bumper Sticker Market
Automotive Interior & Exterior
Glove Box Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Automotive Insulation Market
Automotive Interior & Exterior
Automotive Mudguards Market
Automotive Interior & Exterior
Automotive Tinting Film Market
Automotive Interior & Exterior
Train Ceiling Modules Market
Automotive Interior & Exterior
Automotive Mirror Dimming Market
Automotive Interior & Exterior
Automotive Front Windshield Market
Automotive Interior & Exterior
Automotive Bovine Leather Market
Automotive Interior & Exterior
Automotive Dashboard Market
Automotive Interior & Exterior
Automotive Films Market
Automotive Interior & Exterior
Exterior Automotive Plastics Market
Automotive Interior & Exterior
Automotive Liftgate Market