
 Automotive Soft Trim Interior Materials Market | 2026-2036
Automotive Soft Trim Interior Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Soft Trim Interior Materials Market Analysis
Premium-grade surface specifications is reorganizing procurement priorities across vehicle interior programs. Yanfeng Automotive Interiors leverages integrated design-to-manufacture capabilities across multiple continents. Lear Corp anchors North American seating and electrical distribution scale. TOYOTA BOSHOKU CORPORATION dominates Japanese OEM captive supply relationships and just-in-sequence delivery systems.
Automotive soft trim interior materials encompass surface-layer components including fabric, vinyl, leather, and synthetic textiles engineered for tactile performance, durability, and aesthetic integration within passenger compartments, typically specified to meet flammability resistance, abrasion cycles, and volatile organic compound emission thresholds. Interior upholstery applications command the largest volume allocation, while synthetic textiles represent the fastest-growing material category as OEMs pursue weight reduction and sustainability credentials. Dashboard covering and headliner segments concentrate margin pools where acoustic performance and haptic quality differentiate supplier selection.
EPA oversees volatile organic compound limits affecting adhesive and coating formulations in US-based manufacturing, while REACH restricts hazardous substance content across European supply chains, and China's GB standards govern interior air quality metrics for domestically assembled vehicles. Regulatory convergence on recycled content mandates and chemical disclosure requirements is elevating compliance costs for Tier-1 and Tier-2 material converters. Stakeholders must monitor evolving certification schemes and raw material traceability protocols to preserve program access across major automotive production regions.
Market Dynamics
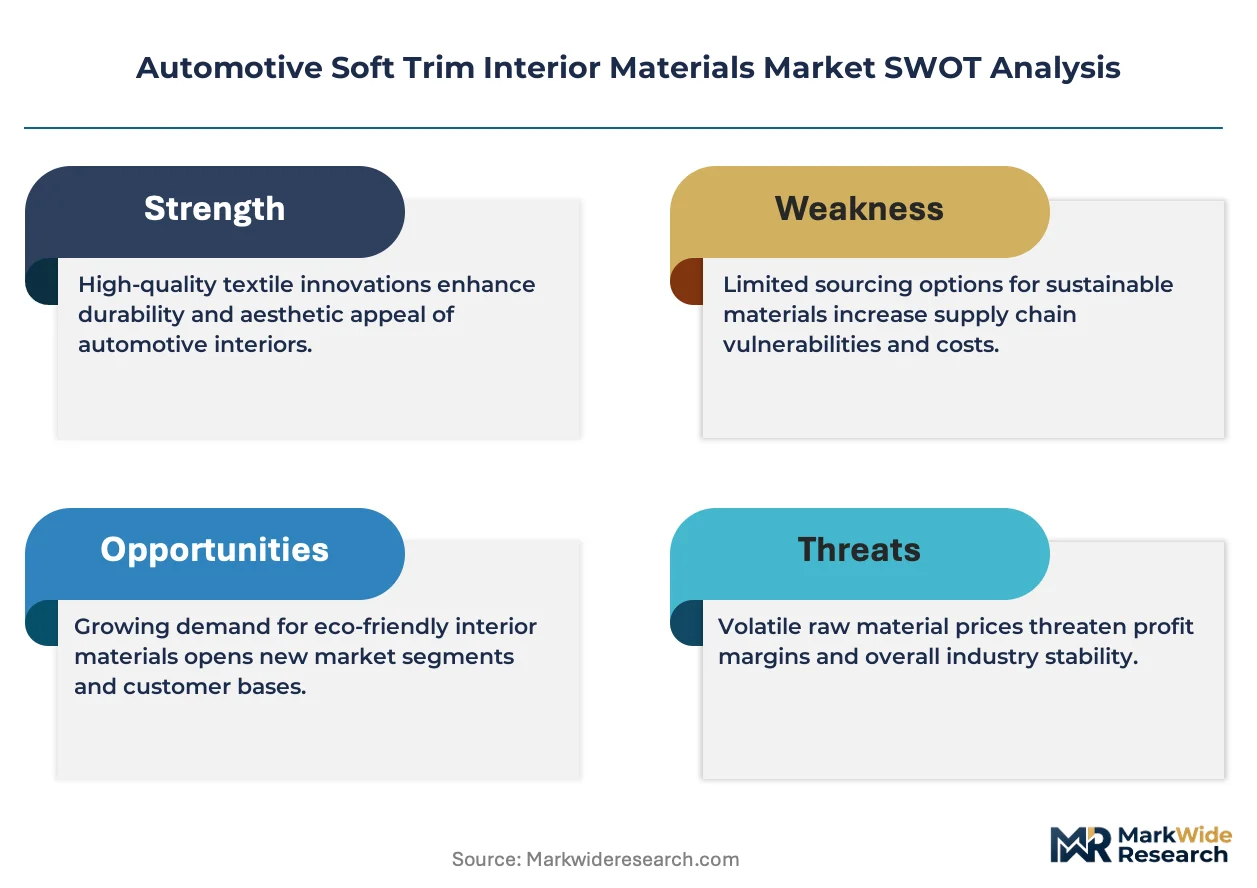
REACH chemical restrictions and EU Green Deal mandates are forcing material substitutions across soft trim supply chains, compressing lead times for bio-based alternatives while elevating compliance costs for incumbent petrochemical formulations.
Growth Catalysts
- EU Green Deal recycled content mandates:Binding thresholds for post-consumer material integration are pulling rPET and ocean-bound plastics into dashboard and door panel specifications.
- Luxury EV platform expansion:Premium electric vehicle architectures specify suede-like microfibers and natural fiber composites to differentiate cabin experiences and reduce mass.
- China GB standards enforcement:Stricter interior air quality testing protocols for formaldehyde and VOC emissions are accelerating adoption of low-emission adhesives and water-based coatings.
Market Restraints
- Petrochemical feedstock volatility:Polyurethane foam and synthetic leather producers face margin compression from propylene oxide and adipic acid price swings.
- German supplier concentration:Premium acoustic felt and needle-punch carpet backing capacity clusters in Baden-Württemberg and Bavaria, creating single-source exposure for global programs.
- Flammability standard divergence:FMVSS 302 in the United States, ECE R118 in Europe, and GB 8410 in China impose incompatible testing protocols, fragmenting material qualification costs.
Strategic Opportunities
- India PLI scheme for auto components:Production-linked incentives for advanced automotive textiles are attracting stitching and cut-and-sew operations away from traditional East Asian hubs.
- Repair and refurbishment channels:Independent upholstery shops and certified collision centers represent underdeveloped demand for aftermarket soft trim kits and color-matched vinyl.
- Digital textile printing convergence:Combination of inkjet deposition and laser perforation enables mass customization of seat patterns without tooling changeover penalties.
Industry Challenges
- Color matching across substrates:Coordinating hue consistency between leather hides, synthetic vinyl, and woven fabrics requires spectrophotometry expertise that supplier quality teams struggle to staff.
- Legacy ERP integration:Tier-2 converters deploying traceability software for recycled content documentation face data interoperability failures with OEM just-in-sequence platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Soft Trim Interior Materials Market |
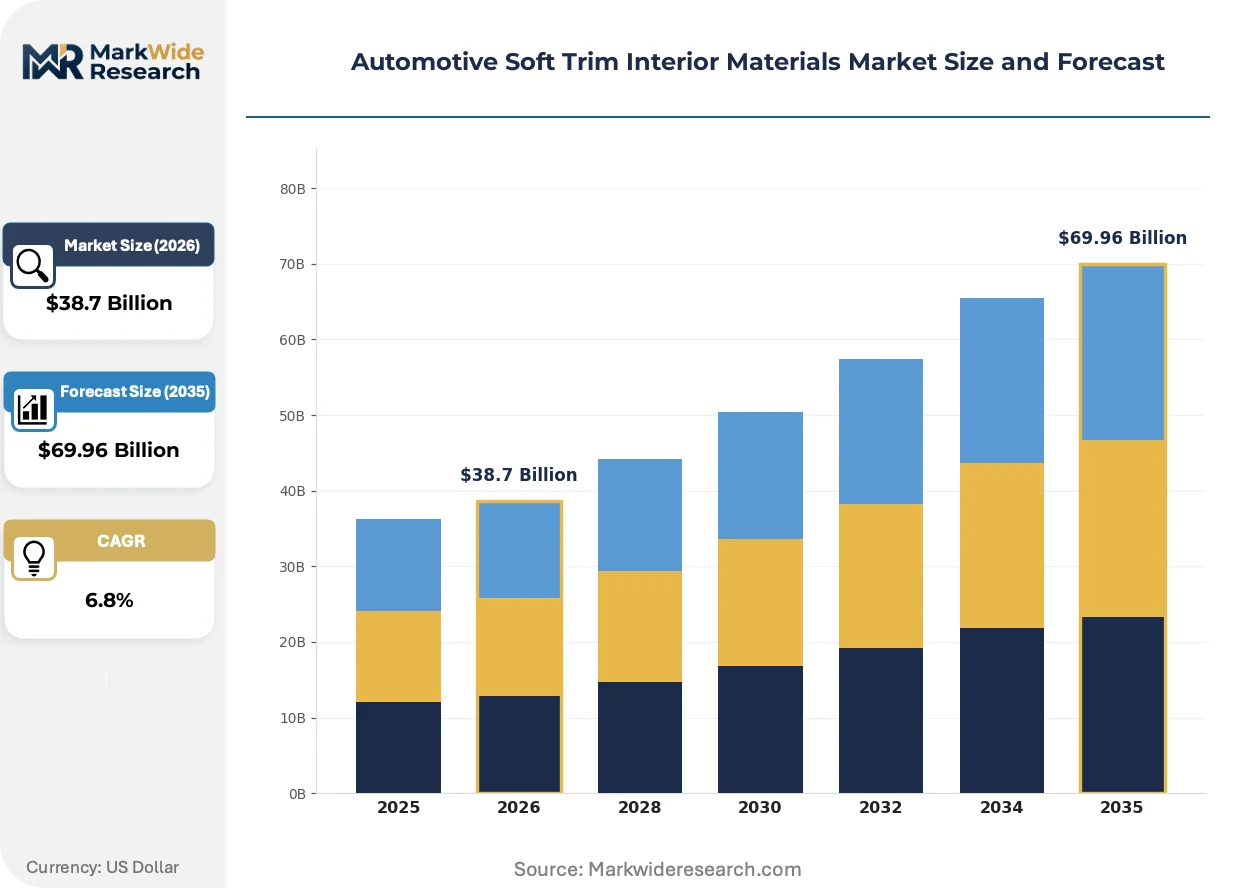
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $69.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fabric, Vinyl, Leather, Synthetic Textiles End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Interior Upholstery, Dashboard Covering, Door Paneling, Headliner Configuration: Seating, Trim Components, Consoles, Pillars |
| Companies Covered | DK SCHWEIZER, TOYOTA BOSHOKU CORPORATION, Asahi Kasei Corporation, SEIREN CO. LTD., Yanfeng Automotive Interiors, Lear Corp, Antolin, TOYODA GOSEI CO., LTD., DRÄXLMAIER Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Soft Trim Interior Materials Market Emerging Trajectories
Material science breakthroughs and regulatory chemistry restrictions are converging to reshape specification priorities across passenger vehicle interiors, with sustainability credentials now carrying equal weight to haptic performance in sourcing decisions.
Algae-based polyurethane foam is displacing conventional petroleum-derived cushioning in seat and headliner applications. BMW and Mercedes-Benz have qualified the material for 2026 model year production. The shift is compressing demand for MDI and TDI feedstocks while opening supply contracts to biotechnology firms outside traditional petrochemical channels.
REACH SVHC candidate list expansion is restricting phthalate plasticizers and certain flame retardants in synthetic leather formulations. European converters must reformulate PVC and TPU compounds ahead of sunset dates. Dashboard covering suppliers in Italy and Spain are accelerating water-based coating line conversions to maintain OEM program access.
Direct-to-tier procurement consolidation is compressing material converter margins. Volkswagen Group and Stellantis have reduced approved supplier lists for seat fabric by forty percent since 2022. Sourcing teams in Wolfsburg and Turin now mandate recycled content certificates and carbon footprint disclosures as gate criteria for request-for-quote participation.
Automotive Soft Trim Interior Materials Market Segmentation
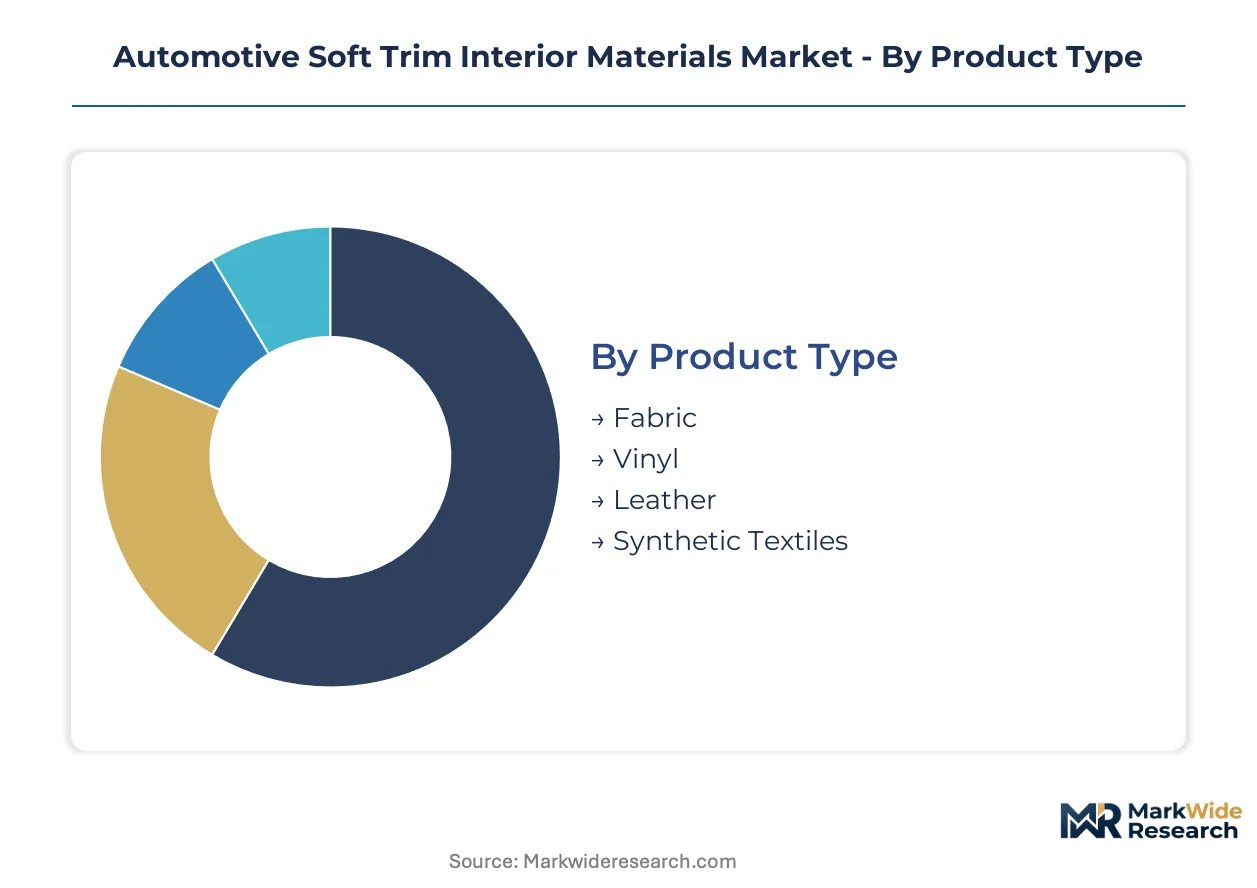
Soft trim procurement flows through distinct channel configurations that reshape how material converters prioritize volume commitments versus margin capture. Specification authority varies dramatically across these pathways, with direct OEM relationships demanding different compliance portfolios than Tier-1 mediated supply.
Product Type:
Fabric and leather dominate premium vehicle programs flowing through direct OEM channels, while vinyl and synthetics concentrate in high-volume Tier-1 supply chains serving mass-market assemblers.
- Fabric:Woven and knitted textile constructions specified for durability cycles exceeding 50,000 Martindale rubs. Demand concentrates in European OEM seating programs where REACH chemical restrictions have accelerated substitution away from synthetic alternatives.
- Leather:Full-grain and corrected-grain hides processed through chromium or vegetable tanning protocols. Premium electric vehicle architectures in Germany and China specify natural leather for steering wheel and seat bolster applications despite sustainability scrutiny.
- Vinyl:PVC and TPU-based surfaces dominate aftermarket refurbishment channels due to cost-positioning and color-matching feasibility across aging vehicle fleets.
- Synthetic Textiles:Microfiber suede and rPET woven constructions engineered for weight reduction targets in headliner and pillar trim applications.
Fabric dominates installed base. Synthetic textiles are where expansion concentrates.
End User:
Cost tier stratification separates specification authority, with OEMs and vehicle assemblers commanding premium material access while Tier-1 suppliers and aftermarket providers compete on conversion efficiency.
- OEMs:Direct material qualification through captive design studios in Wolfsburg, Stuttgart, and Shanghai dictates haptic performance thresholds and chemical compliance baselines for global vehicle platforms.
- Aftermarket Providers:Independent upholstery shops and certified collision centers source color-matched vinyl and fabric kits for vehicle refurbishment, with demand clustering in North American and European markets with aging fleet demographics.
- Tier-1 Suppliers:Yanfeng, Lear, and TOYOTA BOSHOKU consolidate procurement leverage across multiple OEM programs, compressing converter margins through volume aggregation.
- Vehicle Assemblers:Contract manufacturers and regional assembly operations in India and Mexico source soft trim through approved supplier lists with simplified qualification protocols.
Tier-1 suppliers dominate installed base. OEM direct procurement is where margin expansion concentrates.
Application:
Volume distribution skews heavily toward seating surfaces, while acoustic and thermal performance requirements in overhead and frontal applications command specialized material specifications.
- Interior Upholstery:Seat facings, bolsters, and inserts representing the largest material volume allocation across passenger vehicle programs. Specifications prioritize abrasion resistance and seam fatigue performance under cyclic loading conditions.
- Dashboard Covering:Soft-touch surfaces requiring low-gloss aesthetics and UV stability for instrument panel top pads and glove box facings. German and Italian converters specialize in slush-molded PVC and TPO skin constructions.
- Door Paneling:Armrest and insert surfaces integrating decorative stitching and ambient lighting elements, with acoustic foam backing specified for NVH performance.
- Headliner:Multi-layer composite constructions combining decorative fabric facing with polyurethane foam core and thermoplastic backing for overhead module integration.
Interior upholstery dominates installed base. Dashboard covering is where technology differentiation concentrates.
Configuration:
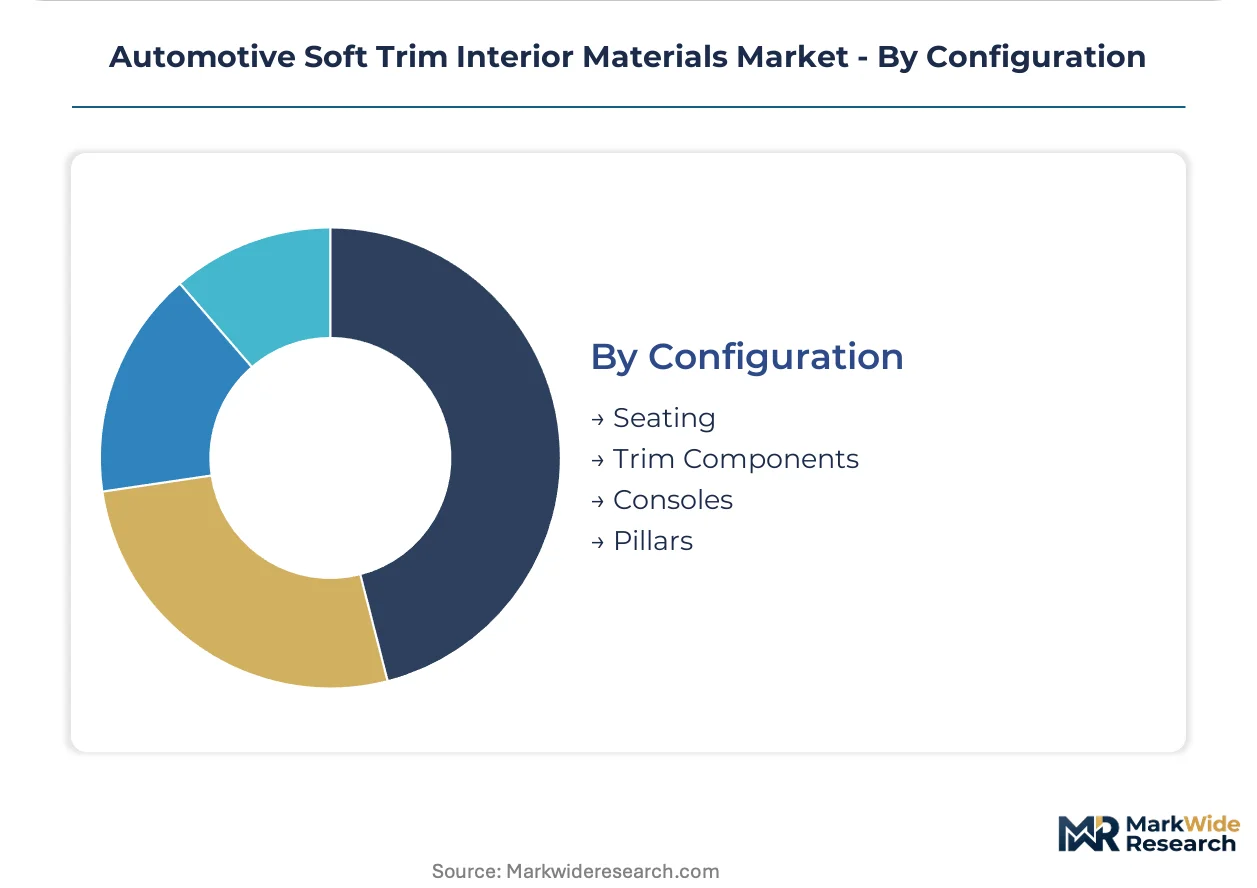
Supply concentration varies by assembly complexity, with seating systems requiring the most sophisticated cut-and-sew operations while pillar and console components tolerate higher automation levels.
- Seating:Complete seat trim assemblies including facings, foams, and suspension elements delivered through just-in-sequence systems to vehicle assembly lines. Complexity resides in multi-material coordination across leather, fabric, and synthetic zones.
- Trim Components:Door panels, instrument panels, and console side panels requiring decorative surface integration with structural substrates. Indian PLI scheme incentives are attracting stitching capacity for these subassemblies.
- Consoles:Center console armrests and side trim surfaces with integrated wireless charging pads and storage compartments demanding precise material forming around electronic modules.
- Pillars:A, B, and C-pillar trim panels with lower specification complexity but high volume repetition across vehicle variants.
Seating dominates installed base. Console integration is where electronics convergence concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import dependence for premium leather hides and specialized acoustic felts shapes procurement strategies across major automotive production zones, while export-oriented converters in East Asia and Central Europe capture value from finished soft trim component shipments.
China
Domestic EV platform launches by NIO, XPeng, and Li Auto are specifying Alcantara-style microfibers and natural fiber composites for cabin differentiation. GB standards enforcement through MEE mandates stricter formaldehyde emission thresholds for interior air quality certification. Yangtze River Delta clusters around Shanghai concentrate slush-molding capacity for instrument panel skins serving Volkswagen and Tesla assembly operations.
Germany
Mercedes-Benz, BMW, and Porsche design studios in Stuttgart and Munich dictate global haptic performance benchmarks for seat leather and dashboard surfacing. REACH SVHC restrictions through ECHA are accelerating water-based coating conversions at Italian and Spanish converter subsidiaries. Baden-Württemberg hosts DRÄXLMAIER and specialized needle-punch felt producers supplying acoustic backing for premium vehicle programs.
United States
Detroit Three OEMs are consolidating approved supplier lists for seat fabric while mandating recycled content documentation through EPA-aligned sustainability scorecards. NHTSA maintains FMVSS 302 flammability testing protocols that diverge from European ECE R118 standards. Southeast Michigan and Ohio corridor clusters concentrate cut-and-sew operations for just-in-sequence delivery to F-150 and Silverado assembly lines.
Japan
TOYOTA BOSHOKU and TOYODA GOSEI anchor captive supply relationships with Toyota, Honda, and Nissan through just-in-sequence delivery systems refined over decades. METI carbon neutrality roadmaps are pushing material substitutions toward bio-based polyurethanes for seat cushioning. Aichi Prefecture and Kyushu production bases integrate textile facing, foam molding, and metal frame subassembly within single-site configurations.
India
Maruti Suzuki and Hyundai Motor India expansion is pulling stitching and cut-and-sew capacity away from traditional East Asian hubs. PLI scheme incentives for advanced automotive textiles are attracting Tier-2 converters to Tamil Nadu and Gujarat. Chennai and Pune industrial corridors are developing supplier park ecosystems for door panel and seat trim subassembly exports to Southeast Asian vehicle assembly operations.
Automotive Soft Trim Interior Materials Market Vendor Landscape
Concentration sits with integrated Tier-1 seating and interior module suppliers that consolidate procurement leverage across multiple OEM programs. Three strategic archetypes dominate: Japanese keiretsu-affiliated captive suppliers, European family-owned automotive specialists with deep OEM design relationships, and Chinese state-linked fabricators scaling on domestic EV platform demand. Competitive moves center on M&A for recycled material technology access and geographic expansion into India PLI scheme zones.
Among Japanese keiretsu structures, TOYOTA BOSHOKU CORPORATION and TOYODA GOSEI CO., LTD. exemplify the captive supply archetype through multi-decade just-in-sequence relationships with Toyota Motor Corporation. German specialists including DRÄXLMAIER Group and DK SCHWEIZER occupy positions within the European premium-tier supply base, where design-to-manufacture proximity to Stuttgart and Munich OEM studios carries specification authority. These named entities represent distinct governance models—keiretsu affiliation versus family ownership—rather than interchangeable competitive positioning.
| Leading Market Players |
|---|
| DK SCHWEIZER |
| TOYOTA BOSHOKU CORPORATION |
| Asahi Kasei Corporation |
| SEIREN CO. LTD. |
| Yanfeng Automotive Interiors |
| Lear Corp |
| Antolin |
| TOYODA GOSEI CO., LTD. |
| DRÄXLMAIER Group |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at slush-molding operations in Shanghai and Stuttgart shapes both supply concentration and price floors for dashboard skin materials, compressing margins for Tier-2 converters while elevating procurement leverage for integrated seating suppliers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across soft trim procurement, with premium-mid-economy pricing differentiation driven by certification grade against REACH SVHC restrictions and volume scale commitments. Cost compression in synthetic leather tiers is intensifying because MDI and TDI feedstock volatility erodes converter margins. Aftermarket providers exhibit highest price sensitivity due to fragmented demand and color-matching service bundling, while German premium OEM studios show lowest sensitivity given haptic performance mandates.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes shapes inbound logistics costs for raw hide shipments from South America and rPET flake movements from Southeast Asia. Manufacturing concentrates in China, Germany, and Mexico, with production drawing from chromium-tanned leather, polyurethane foam, and needle-punch felt inputs. Single-source vulnerability clusters in Baden-Württemberg acoustic felt capacity. Distribution runs through just-in-sequence platforms delivering seat trim assemblies directly to vehicle assembly lines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through REACH certification and OEM qualification protocols creates switching costs that protect incumbent positions.
For Market Incumbents: Compound design-to-manufacture proximity advantages by deepening captive supply relationships with Stuttgart and Munich OEM studios, while adding water-based coating capacity ahead of ECHA sunset dates. Algae-based foam substitution from biotechnology entrants threatens petrochemical-derived cushioning margins.
For New Entrants and Emerging Players: Aftermarket refurbishment service gaps where incumbents under-serve independent upholstery shops in North American aging fleet markets represent the most penetrable white-space. Target certified collision center networks with color-matched vinyl kit offerings and digital spectrophotometry tools.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors converters with recycled content certification infrastructure and bio-based material partnerships. Long-term viability hinges on traceability software integration with OEM just-in-sequence platforms. Watch for ECHA SVHC list expansion as inflection indicator for reformulation cost spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Recycled Content Certification Investment | REACH and EU Green Deal mandates pull rPET and ocean-bound plastics into dashboard specifications. |
| Water-Based Coating Line Conversion | Italian and Spanish converters maintain OEM program access ahead of phthalate plasticizer restrictions. |
| India PLI Scheme Manufacturing Footprint | Tamil Nadu and Gujarat attract stitching capacity for door panel subassembly exports. |
| Bio-Based Polyurethane Partnership | BMW and Mercedes-Benz qualification opens supply contracts to biotechnology firms outside petrochemical channels. |
| Digital Textile Printing Capability | Inkjet deposition and laser perforation enable mass customization without tooling changeover penalties. |
Methodological Framework
The analysis maps fabric, leather, vinyl, and synthetic textile sub-sectors, each validated through Tier-1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations. Primary interviews combined with secondary validation from vehicle production databases, IHS Markit registration data, customs/trade records, and SEC filings. Bottom-up and top-down triangulation reconciles converter capacity data against OEM program volumes.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. The analytical framework modeled segmentation across vehicle class, propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions. CAGRs derived from regression analysis of historical penetration rates and forward projection of regulatory compliance cost trajectories. Forecast inputs incorporate REACH SVHC expansion schedules and GB standards enforcement intensity.
Underlying assumptions cover sustained EV platform launch cadence and recycled content mandate adherence, with deviation risk concentrated in petrochemical feedstock price volatility and flammability standard divergence between FMVSS 302, ECE R118, and GB 8410 protocols. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
North America Automotive Interiors Market
Automotive Interior & Exterior
Automotive Fuel Tank Covers Market
Automotive Interior & Exterior
Automotive Body-In-White Market
Automotive Interior & Exterior
Automotive Wooden Interior Decorative Market
Automotive Interior & Exterior
Automotive Racing Seats Market
Automotive Interior & Exterior
Automotive Roof Liners Market
Automotive Interior & Exterior
Automotive Decorative Exterior Trim Market
Automotive Interior & Exterior
Automotive Solar Sunroof Market
Automotive Interior & Exterior
Global Smart Tailgate Market
Automotive Interior & Exterior
Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Interior Leather Market
Automotive Interior & Exterior
Float Glass for Automotive Market
Automotive Interior & Exterior
Overhead Console Market
Automotive Interior & Exterior
Automotive Smart Seating Systems Market
Automotive Interior & Exterior
Automotive Seat Covers Market
Automotive Interior & Exterior
Automotive Interior Ambient Lighting Market