
 Car Oxygen Bar Market | 2026-2036
Car Oxygen Bar Market Size, Share, and Industry Trends Forecast 2026-2036
Car Oxygen Bar Market Analytics
HEPA-grade filtration integration is rotating the Car Oxygen Bar Market toward medical-adjacent cabin air standards. Mann-Hummel leverages its automotive filtration heritage to anchor supply relationships with European OEMs. Daikin competes through its climate-system expertise, extending its indoor air-quality portfolio into vehicle environments. Bosch specializes in sensor-driven oxygen delivery, differentiating via real-time cabin monitoring capabilities.
A car oxygen bar is an in-vehicle device that concentrates ambient oxygen through pressure swing adsorption or membrane separation, typically delivering 30-60% oxygen concentration at flow rates of 1-5 liters per minute to enhance occupant alertness and comfort during transit. Portable units lead volume sales among aftermarket buyers seeking plug-and-play wellness upgrades, while built-in systems command premium positioning through OEM integration and warranty coverage. The wellness enhancements application segment is expanding fastest as rental services and fleet operators adopt oxygen bars to differentiate passenger experience and justify rate premiums.
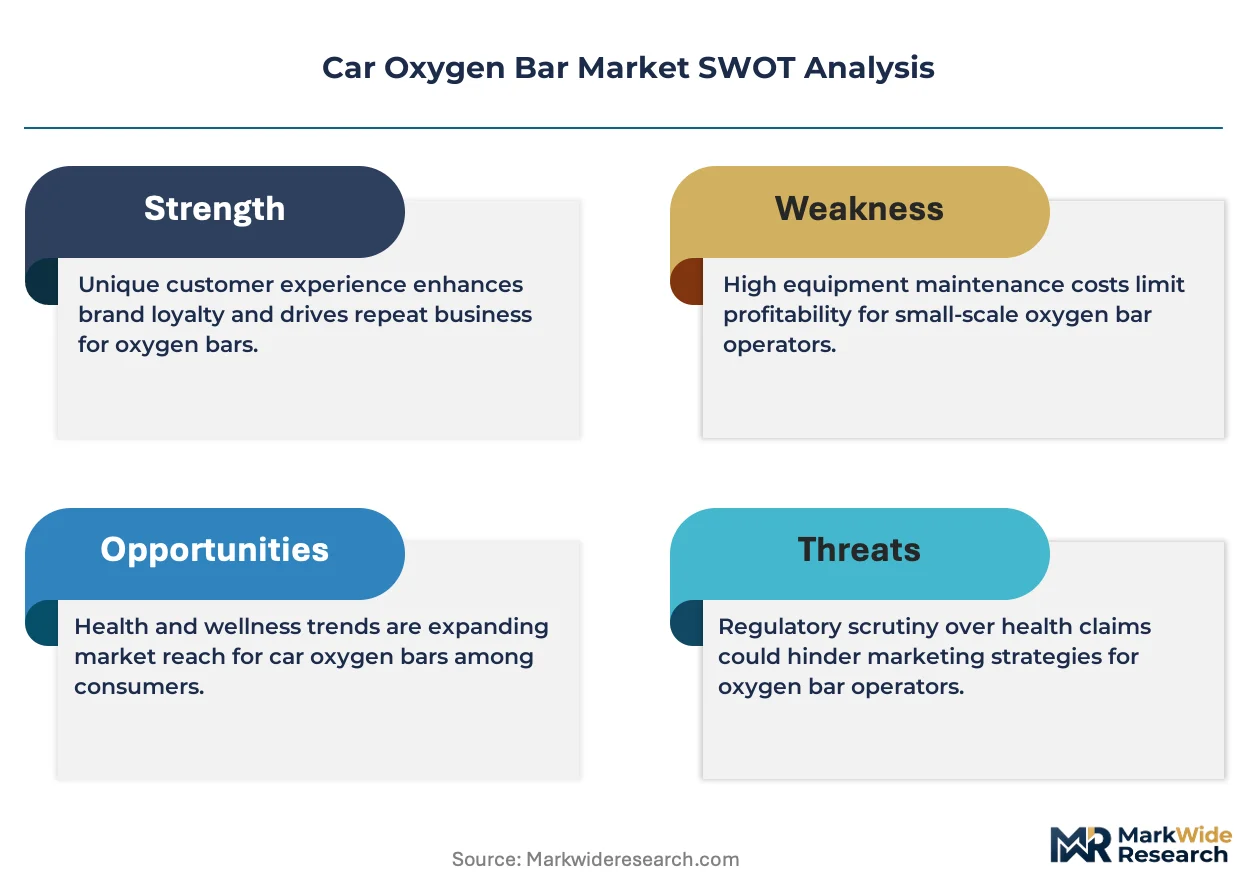
The US FDA classifies high-flow vehicle oxygen concentrators as medical devices when therapeutic claims appear in marketing, tightening compliance thresholds for manufacturers targeting health-improvement positioning. China's MIIT and SAMR jointly oversee in-vehicle electronic air-quality systems under GB standards for electromagnetic compatibility and passenger safety. Europe's REACH and RoHS frameworks restrict certain materials in cabin electronics, pushing suppliers toward halogen-free plastics and recyclable filter media. Stakeholders must monitor how medical-device classification thresholds in key markets reshape product positioning and channel strategy.
Market Dynamics
OEM integration of cabin wellness systems is compressing aftermarket margins while elevating technical specifications for pressure swing adsorption modules. Tier-one automotive suppliers now demand medical-grade oxygen purity thresholds that previously served only therapeutic device markets.
Growth Catalysts
- MIIT Draft Guidelines:China's proposed in-vehicle air quality standards legitimize supplemental oxygen devices as factory-installed safety equipment, accelerating OEM adoption timelines.
- Fleet Wellness Differentiation:Premium ride-hailing operators in Shanghai and Beijing deploy portable oxygen bars to justify 15-20% rate premiums over standard vehicle classes.
- Membrane Separation Advances:Hollow-fiber membrane technology reduces concentrator weight below 800 grams, enabling dashboard-integrated designs without structural vehicle modifications.
Market Restraints
- Zeolite Supply Concentration:Pressure swing adsorption systems depend on lithium-exchanged zeolite 13X, with 70% of pharmaceutical-grade supply originating from three Henan Province refiners.
- FDA Medical Device Classification:Therapeutic marketing claims trigger 510(k) clearance requirements, adding 18-24 month compliance timelines for US market entry.
- Lithium Battery Thermal Runaway:Portable units face NHTSA scrutiny after incidents involving oxygen concentrator battery packs in parked vehicles during summer conditions.
Strategic Opportunities
- India's PLI Scheme for Automotive Electronics:Component manufacturing incentives cover cabin air-quality systems, attracting oxygen bar module assembly to Tamil Nadu and Gujarat.
- Sensor-Oxygen Convergence:Integration of SpO2 monitoring with automated flow adjustment creates closed-loop wellness systems for autonomous vehicle passenger monitoring.
- Subscription Hardware Models:Fleet operators in Shenzhen pilot monthly oxygen service fees rather than capital purchase, reducing upfront deployment barriers.
Industry Challenges
- Cross-Functional Talent Scarcity:Product development requires combined expertise in automotive EMC compliance and medical device quality systems, with fewer than 200 qualified engineers across East Asia.
- GB Standard Certification Delays:SAMR electromagnetic compatibility testing queues extend to 14 months for novel oxygen delivery architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Car Oxygen Bar Market |
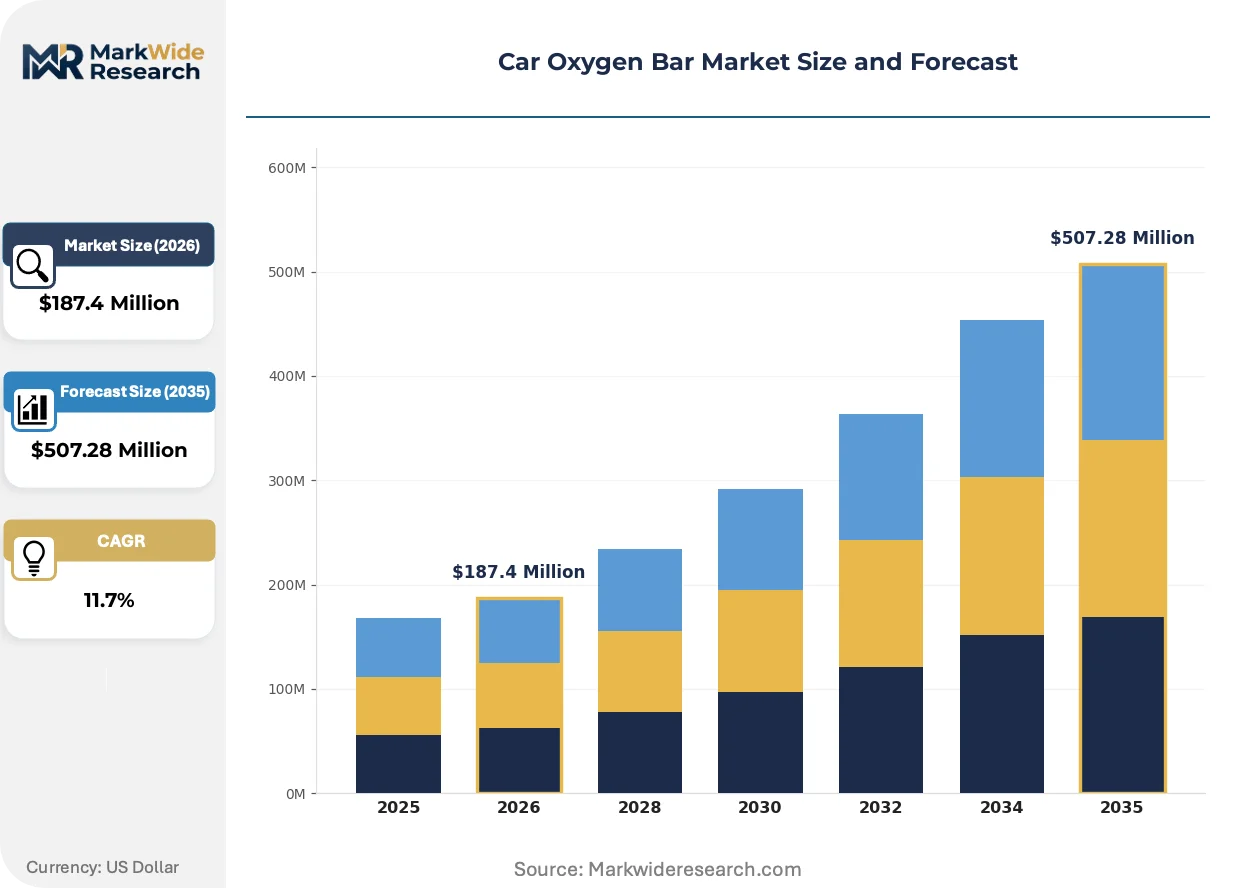
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Built-in Systems, Accessories, Filters End User: Automobile Owners, Rental Services, Fleet Operators, Luxury Car Manufacturers Sales Channel: Online Retail, Automotive Dealerships, Specialty Stores, Trade Shows Application: Personal Use, Wellness Enhancements, Travel Experience, Health Improvement |
| Companies Covered | Camfil, Mann-Hummel, DENSO, Daikin, Mahle, Atmus Filtration Technologies Inc., Freudenberg Filtration Technologies, BOSCH, UFI Filters, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Car Oxygen Bar Market Evolving Landscape
Convergence between automotive cabin electronics and medical device engineering is dissolving traditional category boundaries. Suppliers now compete on dual-use platform architectures that serve both wellness positioning and clinical-grade performance claims.
Membrane-based oxygen separation is displacing pressure swing adsorption in aftermarket portable units. The technology operates silently without compressor vibration, appealing to luxury vehicle owners seeking non-invasive cabin upgrades. Chinese electronics manufacturers are adopting membrane modules at twice the rate of zeolite-based systems, compressing the addressable market for traditional concentrator specialists.
REACH and RoHS material restrictions are forcing filter media redesigns across European supply chains. ECHA substance evaluations now cover halogenated flame retardants in cabin electronics housings, compelling suppliers to validate alternative chemistries. German OEMs have advanced their compliance deadlines by 18 months, creating a two-tier certification landscape between early adopters and laggards.
Wellness-as-a-service contracting is fragmenting traditional equipment procurement. Corporate fleet managers in Guangzhou and Hangzhou now specify oxygen availability per passenger-mile rather than device ownership, unbundling hardware from maintenance obligations. This consumption-based model concentrates purchasing authority with mobility platform operators rather than individual vehicle owners.
Car Oxygen Bar Market Segmentation
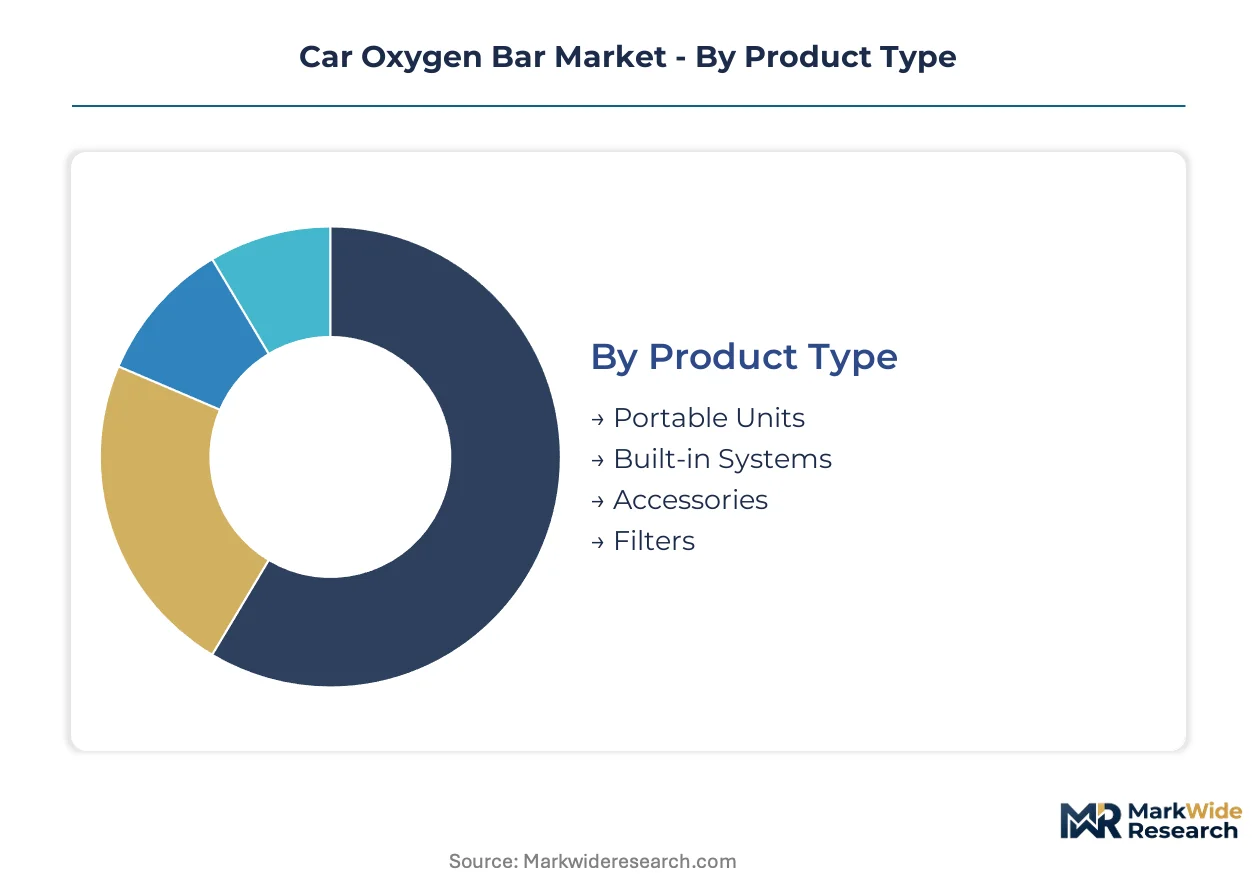
Segmentation in the Car Oxygen Bar Market reveals divergent supply chain configurations across product architectures and customer procurement patterns. Understanding these divisions exposes where margin pools concentrate and which channels warrant prioritized technical investment.
Product Type:
Portable units dominate export flows to North American and European aftermarket channels, while built-in systems anchor domestic OEM supply relationships in China.
- Portable Units:Self-contained devices utilizing hollow-fiber membrane or pressure swing adsorption technology, typically powered via 12V vehicle outlets or lithium battery packs. Aftermarket demand concentrates in the United States and Germany where direct-to-consumer wellness positioning circumvents medical device classification thresholds.
- Built-in Systems:Factory-integrated modules engineered to OEM electromagnetic compatibility and crash safety specifications, delivering oxygen enrichment through dashboard-embedded diffusers. Procurement concentrates with Chinese luxury marques seeking cabin wellness differentiation against European competitors.
- Accessories:Replacement tubing, nasal cannulas, and mounting brackets supporting device deployment across vehicle classes.
- Filters:HEPA-grade and activated carbon media for inlet air pretreatment, subject to REACH material restrictions in European supply chains.
Portable units hold the largest share; momentum sits with built-in systems.
End User:
Cost tier stratification separates capital-intensive OEM procurement from recurring aftermarket purchases by individual owners.
- Automobile Owners:Individual consumers acquiring devices through retail channels for personal vehicle installation, prioritizing plug-and-play deployment and silent operation.
- Rental Services:Premium ride-hailing operators in Shanghai and Beijing deploying portable units as per-vehicle amenities to justify rate premiums over standard service tiers.
- Fleet Operators:Corporate mobility managers specifying oxygen availability across passenger-mile contracts rather than capital ownership, unbundling hardware from maintenance obligations.
- Luxury Car Manufacturers:OEM engineering teams integrating oxygen enrichment into cabin climate architectures, demanding medical-grade purity thresholds and GB standard electromagnetic compliance.
Automobile owners represent the volume base; fleet operators are expanding most quickly through subscription contracting models.
Sales Channel:
Volume concentration tilts toward digital commerce for portable units, while built-in systems flow through captive OEM supply agreements.
- Online Retail:E-commerce platforms and direct-to-consumer storefronts capturing aftermarket demand, particularly for membrane-based portable units where technical specifications are standardized.
- Automotive Dealerships:Authorized service centers offering factory-integrated systems as new vehicle options or retrofit upgrades, leveraging warranty coverage as a competitive anchor.
- Specialty Stores:Wellness and automotive accessory retailers providing hands-on product demonstration and installation support.
- Trade Shows:Industry exhibitions serving as launch platforms for new membrane technologies and OEM partnership announcements.
Online retail commands the greatest transaction velocity; automotive dealerships carry the premium margin profile.
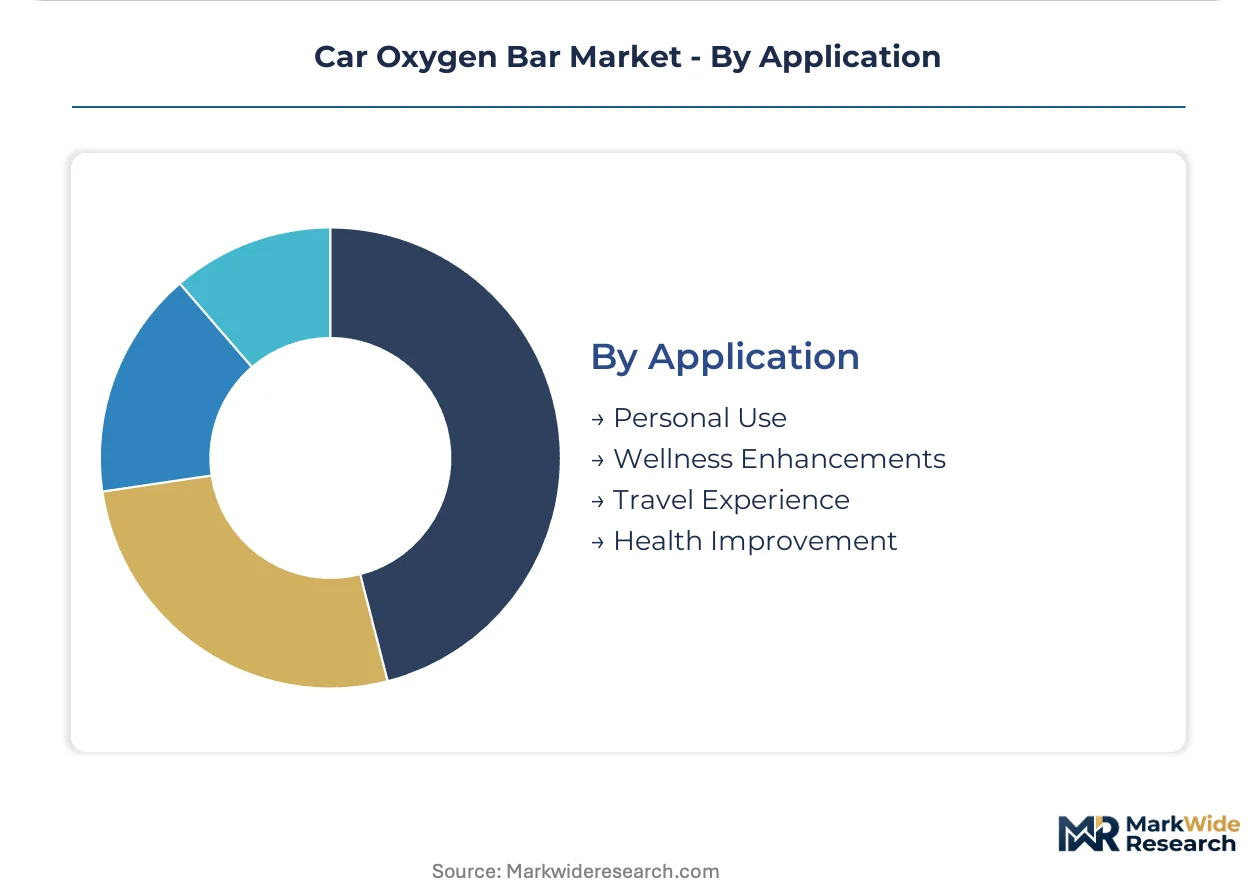
Application:
Customer maturity separates established personal use cases from emerging wellness positioning in commercial mobility services.
- Personal Use:Individual drivers seeking alertness enhancement during long-distance transit, typically deploying portable units without clinical therapeutic claims to avoid FDA medical device classification.
- Wellness Enhancements:Fleet and rental operators differentiating passenger experience through oxygen availability, now the steepest expansion trajectory as mobility platforms compete on cabin amenities.
- Travel Experience:Tourism vehicle operators in plateau regions deploying high-flow concentrators to address altitude-related discomfort.
- Health Improvement:Positioning toward respiratory support applications, triggering regulatory scrutiny when marketing implies therapeutic benefit.
Personal use retains the installed base; wellness enhancements are gaining share fastest through fleet procurement scaling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pressure swing adsorption module fabrication concentrates in China's Henan Province, where three refiners control pharmaceutical-grade zeolite supply. OEM integration timelines vary sharply by regulatory environment and fleet operator procurement sophistication.
China
MIIT draft guidelines legitimize supplemental oxygen as factory-installed safety equipment, compressing adoption timelines for domestic luxury marques. SAMR electromagnetic compatibility testing queues extend 14 months for novel architectures. Tier-one cities Shanghai and Beijing anchor fleet wellness differentiation, where ride-hailing operators deploy portable units to justify rate premiums.
United States
FDA medical device classification triggers 510(k) clearance requirements when therapeutic claims appear in marketing, adding 18-24 month compliance timelines. NHTSA scrutiny of lithium battery thermal runaway in parked vehicles constrains portable unit deployment. Aftermarket demand concentrates in direct-to-consumer wellness positioning that circumvents clinical regulatory thresholds.
Germany
REACH and RoHS frameworks restrict halogenated flame retardants in cabin electronics housings, compelling suppliers to validate alternative chemistries. German OEMs advanced compliance deadlines 18 months ahead of regulatory mandates. Bavaria and Baden-Württemberg host filtration specialists leveraging automotive heritage for OEM supply relationships.
India
PLI scheme incentives for automotive electronics cover cabin air-quality systems, attracting oxygen bar module assembly to Tamil Nadu and Gujarat. CDSCO oversight applies when devices carry therapeutic positioning. Fleet operators in Delhi-NCR pilot subscription hardware models, unbundling capital purchase from maintenance obligations.
Japan
METI standards for in-vehicle electronic systems intersect with PMDA oversight when oxygen delivery claims imply clinical benefit. Kanto region automotive suppliers integrate membrane separation modules into climate-system architectures. Hollow-fiber technology adoption proceeds at measured pace given established zeolite supply relationships.
Car Oxygen Bar Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated competitive structure. Automotive filtration heritage distinguishes incumbents with OEM supply relationships, while electronics manufacturers compete on membrane module miniaturization. Three archetypes dominate: established filtration multinationals, climate-system specialists extending indoor portfolios, and sensor-integrated platform developers. Strategic moves concentrate on GB standard pre-certification partnerships and membrane technology licensing arrangements.
Among filtration-focused multinationals, Mann-Hummel and Freudenberg Filtration Technologies exemplify automotive heritage players anchoring European OEM supply channels. Daikin occupies a position bridging climate-control expertise with cabin air-quality extension. Bosch represents the sensor-integrated archetype, differentiating through real-time monitoring capabilities rather than core separation technology. These three companies illustrate how competitive positioning fragments across technical specialization rather than consolidating around unified platform approaches.
| Leading Market Players |
|---|
| Camfil |
| Mann-Hummel |
| DENSO |
| Daikin |
| Mahle |
| Atmus Filtration Technologies Inc. |
| Freudenberg Filtration Technologies |
| BOSCH |
| UFI Filters |
| Others |
Value Network & Pricing Analysis
Long-term offtake agreements for lithium-exchanged zeolite 13X lock in supply access for pressure swing adsorption module producers while anchoring price visibility across volatile raw material cycles. Chinese luxury marques leverage these contracts to secure medical-grade oxygen purity thresholds ahead of MIIT guideline finalization, compressing procurement timelines for built-in cabin wellness systems.
Pricing Analysis
GB standard electromagnetic compliance certification dictates the pricing tier structure across the Car Oxygen Bar Market, separating factory-integrated modules from aftermarket portable units. Three-tier pricing structure across premium OEM-integrated, standard aftermarket membrane, and economy zeolite-based portable levels reflects certification investment differentials. Cost compression in the portable segment intensifies as Chinese electronics manufacturers adopt hollow-fiber membrane modules at accelerated rates. Fleet operators exhibit lowest price sensitivity through subscription contracting models, while individual automobile owners in direct-to-consumer channels drive transactional volume at compressed margins.
Supply Chain Analysis
China and Germany anchor oxygen bar module fabrication and filtration component production respectively, with India emerging as an alternative assembly jurisdiction through PLI scheme incentives. Zeolite 13X supply draws from three Henan Province refiners controlling pharmaceutical-grade output, while hollow-fiber membrane technology sources from Japanese and South Korean polymer specialists. Single-source vulnerability concentrates in lithium-exchanged zeolite for pressure swing adsorption architectures, exposing OEM procurement to regional production disruptions. Distribution runs through captive automotive dealership networks for built-in systems and direct-to-consumer e-commerce platforms for portable aftermarket units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers including filter replacement subscriptions and oxygen purity monitoring subscriptions are expanding faster than hardware sales, reframing the Car Oxygen Bar Market as a recurring-revenue opportunity rather than equipment transaction business.
For Market Incumbents: Shield OEM supply relationships by accelerating GB standard pre-certification partnerships before SAMR testing queues extend further. Backward integration into hollow-fiber membrane production mitigates zeolite supply concentration risk from Henan Province refiners. Capture fleet operator subscription contracts through integrated maintenance offerings that unbundle hardware from service obligations. For New Entrants and Emerging Players: CDSCO fast-track certification for therapeutic positioning in India opens white-space access before established players consolidate PLI scheme manufacturing incentives. Target Delhi-NCR fleet operator pilots with membrane-based portable units that circumvent lengthy electromagnetic compliance timelines. Pursue direct-to-consumer wellness positioning in United States channels to bypass FDA 510(k) clearance requirements. For Investors and Strategic Acquirers: Capital is best deployed toward sensor-integrated platform developers bridging automotive EMC compliance and medical device quality systems, an archetype with scarcity value across East Asia. Long-term viability hinges on convergence between autonomous vehicle passenger monitoring and closed-loop wellness system architectures. Watch for MIIT guideline finalization as inflection signal accelerating OEM adoption timelines and compressing aftermarket addressable market.| Strategic Initiative | Industry Significance |
|---|---|
| GB Standard Pre-Certification Partnership | Secures SAMR electromagnetic compliance queue position ahead of 14-month testing backlogs. |
| Membrane Technology Licensing Arrangement | Enables Chinese electronics manufacturers to displace zeolite-based concentrator incumbents. |
| Subscription Hardware Model Pilot | Aligns fleet operator procurement with passenger-mile oxygen availability contracting. |
| Sensor-Oxygen Convergence R&D Investment | Positions for autonomous vehicle closed-loop wellness monitoring integration requirements. |
| PLI Scheme Manufacturing Footprint Expansion | Captures Indian automotive electronics incentives covering Tamil Nadu and Gujarat assembly. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement managers, aftermarket distributor operations heads, and fleet mobility platform executives converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against MIIT draft guideline documentation, SAMR electromagnetic compatibility testing protocols, FDA 510(k) clearance databases, and REACH substance restriction evaluations. Bottom-up unit economics across portable and built-in product architectures triangulated with top-down market sizing from vehicle production databases and wellness equipment trade flows.
Segmentation dimensions modeled include product type architecture, end user procurement pattern, sales channel configuration, and application use case across the projection horizon. CAGRs derived from installed base growth trajectories, replacement cycle assumptions, and fleet penetration scaling curves. Industry-specific forecast inputs incorporated membrane technology adoption rates in Chinese electronics manufacturing and OEM integration timeline compression under MIIT regulatory momentum.
Underlying assumptions cover zeolite supply stability, SAMR testing queue durations, and membrane module cost reduction curves, with deviation risk concentrated in FDA medical device reclassification and lithium battery thermal runaway regulatory responses. Recalibration cycles align with material shifts in MIIT guideline finalization, PLI scheme incentive revisions, and autonomous vehicle wellness system integration mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Interior & Exterior
North America Automotive Flooring Market
Automotive Interior & Exterior
Global Headliner (OE) Market
Automotive Interior & Exterior
Ventilated Seats Market
Automotive Interior & Exterior
Door Panel Market
Automotive Interior & Exterior
Automotive Door Seal Market
Automotive Interior & Exterior
Automotive Foam Market
Automotive Interior & Exterior
Automotive Insulation Market
Automotive Interior & Exterior
France Automotive Adaptive Lighting System Market
Automotive Interior & Exterior
Automotive Door Impact Bars Market
Automotive Interior & Exterior
Automotive Intake Manifold Cover Market
Automotive Interior & Exterior
Automotive Airbag Fabric Market
Automotive Interior & Exterior
Automotive Windshield Market
Automotive Interior & Exterior
Automotive Woven Upholstery Market
Automotive Interior & Exterior
Europe Automotive Upholstery Market
Automotive Interior & Exterior
Automotive Seat Climate Systems Market
Automotive Interior & Exterior
Smart Automotive Headlight Market