
 Electric Vehicle Helmet Market | 2026-2036
Electric Vehicle Helmet Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Vehicle Helmet Market Insights
East Asian composite materials suppliers is consolidating around high-performance carbon fiber and expanded polystyrene liner production for premium headgear. Shoei Co., Ltd. leverages proprietary multi-ply fiber matrix technology to sustain premium positioning in full-face protection. HJC Helmets anchors volume production through vertically controlled manufacturing facilities in South Korea. Bell Helmets competes across modular and open-face categories with broad retail channel coverage in North America.
An electric vehicle helmet is a protective headgear system engineered with impact-absorbing expanded polystyrene liners, rigid outer shells of polycarbonate or carbon fiber composite, and integrated ventilation channels designed to mitigate collision forces for riders of electric two-wheelers and light electric vehicles. Full-face configurations dominate safety-critical applications where jaw and facial coverage prove essential, while modular designs attract delivery riders seeking convenience without sacrificing protection. Carbon fiber material segments command premium pricing due to strength-to-weight advantages, whereas polycarbonate variants occupy mass-market positioning through cost-efficient thermoforming processes. Bluetooth connectivity features are gaining traction among commuters requiring navigation and communication integration during urban transit.
Europe's ECE 22.06 standards and the EU's General Product Safety Regulation shape baseline impact absorption and retention system requirements for helmet manufacturers accessing member states. India's BIS certification mandates and the country's Motor Vehicles Act enforcement create compliance thresholds for imported and domestically produced headgear alike. The United States DOT FMVSS 218 standard and NHTSA oversight govern minimum performance criteria for helmets sold through American distribution channels. Stakeholders must track evolving material disclosure rules under REACH and emerging smart-helmet electromagnetic compatibility protocols to preserve market access across jurisdictions.
Market Dynamics
The transition from polycarbonate to carbon fiber composite shells is compressing manufacturing margins while forcing mid-tier suppliers toward backward integration into expanded polystyrene liner production. This material upgrade cycle, accelerated by ECE 22.06 impact absorption standards, is restructuring competitive positioning across all price tiers.
Growth Catalysts
- FAME II subsidy scheme:India's two-wheeler electrification program is accelerating helmet demand among electric scooter commuters in Mumbai, Bangalore, and Delhi.
- Bluetooth integration:Navigation and communication features are pulling urban delivery fleets toward smart-helmet procurement in Southeast Asian megacities.
- Carbon fiber manufacturing:East Asian composite suppliers are scaling high-performance fiber matrix capacity to serve premium full-face protection segments.
Market Restraints
- Raw material concentration:Toray Industries and Teijin Limited control 70% of aerospace-grade carbon fiber supply, creating input cost volatility for helmet shell producers.
- REACH compliance burden:Material disclosure rules for polycarbonate additives and liner foams are extending certification timelines for European market entry.
- Modular design limitations:Chin-bar pivot mechanisms in convertible helmets face durability testing failures under repeated impact cycles.
Strategic Opportunities
- Indian tier-2 cities:Lucknow, Indore, and Coimbatore show underpenetrated electric two-wheeler helmet penetration relative to subsidized vehicle sales growth.
- 5G-V2X convergence:Vehicle-to-everything communication modules are creating white space for helmets with integrated antenna arrays and low-latency connectivity.
- BIS certification acceleration:India's streamlined testing protocols for domestically manufactured headgear are reducing import dependency windows.
Industry Challenges
- Composite engineering talent scarcity:Multi-ply fiber matrix design expertise concentrates within Japanese and Italian specialist firms, constraining R&D scaling.
- Electromagnetic compatibility testing:Smart-helmet Bluetooth and antenna systems face prolonged certification cycles under evolving EU radio equipment directives.
- Retention system integration:Quick-release mechanisms for emergency medical access must reconcile with impact stability requirements, complicating product development roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Vehicle Helmet Market |
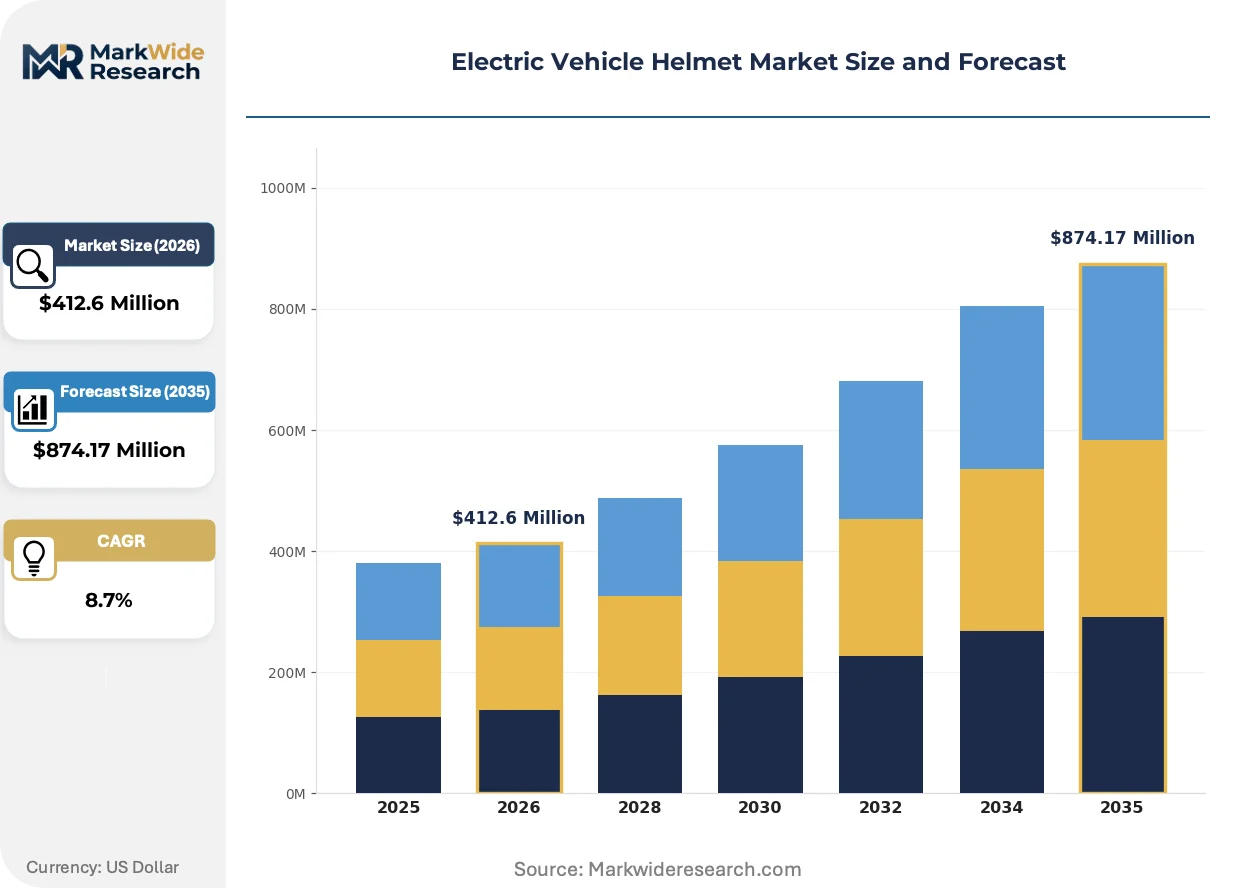
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Full-Face, Open-Face, Modular, Half-Shell Material: Polycarbonate, Carbon Fiber, Fiberglass, Expanded Polystyrene Feature: Bluetooth Connectivity, Ventilation System, Anti-fog Visor, Impact Resistance End User: Commuters, Delivery Riders, Motorcyclists, Sports Enthusiasts |
| Companies Covered | Shoei Co., Ltd., Arai Helmet, Ltd., HJC Helmets, Bell Helmets, Schuberth GmbH, AGV, Nolan Helmets, Shark Helmets, Sena Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Vehicle Helmet Market Trends and Innovations
Helmet architecture is fragmenting along connectivity and material axes as urban mobility electrification forces simultaneous upgrades in impact protection and rider information systems. This dual-track evolution is compressing product lifecycles and reshaping supplier relationships.
Embedded antenna arrays and mesh networking chipsets are decentralizing communication hardware from vehicles into rider-worn equipment. Food delivery platforms in Ho Chi Minh City and Jakarta are piloting fleet-wide smart-helmet deployment for real-time order coordination. This shift is compressing standalone Bluetooth accessory sales while elevating integrated system suppliers.
Europe's ECE 22.06 standard and its rotational acceleration testing protocols are forcing redesigns of expanded polystyrene liner densities and shell geometries. Manufacturers serving Germany, France, and Italy must retool impact absorption systems to meet angled-impact performance criteria. Premium full-face configurations are absorbing the bulk of compliance costs, while open-face variants face market exit pressures.
Urban commuters are consolidating helmet purchases with vehicle acquisition as bundled safety packages through electric two-wheeler dealerships. Direct-to-rider online channels are losing share to OEM-integrated distribution in Indian and Southeast Asian markets. This bundling behavior is most pronounced among first-time electric vehicle buyers in subsidy-eligible purchase cohorts.
Electric Vehicle Helmet Market Segmentation
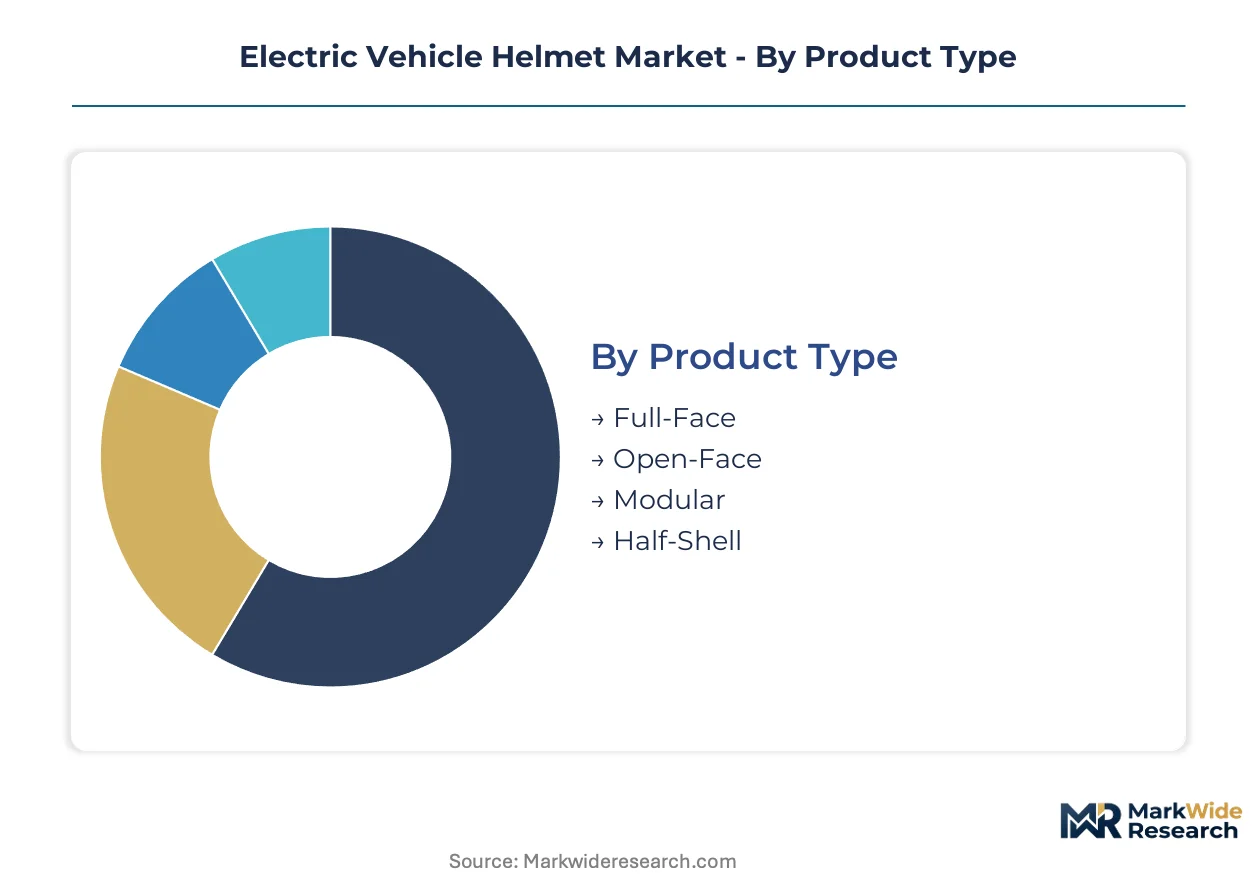
Segmentation in the electric vehicle helmet market reveals divergent paths between standalone protective equipment and embedded smart systems. Material choices and connectivity features increasingly determine pricing power and distribution channel access across commuter and commercial fleets.
Product Type:
Standalone protection dominates mass-market procurement, while embedded modular systems serve fleet operators requiring rapid donning protocols.
- Full-Face:Rigid shell architecture encloses the entire cranium and jaw with integrated chin bars and multi-density expanded polystyrene liners. Demand concentrates among delivery riders in Mumbai and Jakarta where ECE 22.06-equivalent protection is becoming fleet procurement standard.
- Modular:Convertible chin-bar mechanisms pivot upward for convenience without full helmet removal. Southeast Asian logistics platforms in Ho Chi Minh City are piloting fleet-wide deployment where rider efficiency during frequent stops drives specification.
- Open-Face:Three-quarter coverage leaves facial area exposed while reducing weight and thermal burden.
- Half-Shell:Minimal coverage configuration protects crown and forehead with abbreviated shell geometry.
Full-face configurations lead volumes today; modular designs are gaining share fastest among commercial fleet operators.
Material:
Cost tier stratification separates aerospace-grade composites from thermoplastic mass production, with margin compression most acute in mid-tier fiberglass positioning.
- Carbon Fiber:Multi-ply fiber matrix construction delivers superior strength-to-weight ratios through aerospace-grade precursor materials. Premium full-face segments in Germany and Italy absorb compliance-driven redesign costs while maintaining retail price premiums.
- Polycarbonate:Injection-molded thermoplastic shells enable high-volume production at cost points accessible to first-time electric vehicle buyers in Indian tier-2 cities. BIS certification acceleration is reducing import dependency for domestically manufactured variants.
- Fiberglass:Woven glass fiber reinforcement balances impact resistance with moderate weight penalties.
- Expanded Polystyrene:Impact-absorbing liner material forms the energy-management core across all shell types.
Polycarbonate leads volumes today; carbon fiber is climbing the fastest as ECE 22.06 angled-impact protocols force material upgrades.
Feature:
Application context determines feature bundling, with navigation integration essential for delivery logistics and ventilation priority for tropical commuting.
- Bluetooth Connectivity:Embedded chipsets enable hands-free communication, GPS navigation prompts, and music streaming without peripheral accessories. Food delivery platforms across Southeast Asian megacities are mandating fleet-wide deployment for real-time order coordination.
- Ventilation System:Channelled airflow architecture with adjustable intake and exhaust ports manages thermal comfort in high-humidity environments.
- Anti-fog Visor:Hydrophobic coating and dual-pane insulation prevent vision obstruction during temperature differentials.
- Impact Resistance:Reinforced shell zones and enhanced liner densities address specific collision vectors beyond baseline certification.
Ventilation systems lead volumes today; Bluetooth connectivity shows the steepest expansion trajectory as fleet digitization accelerates.
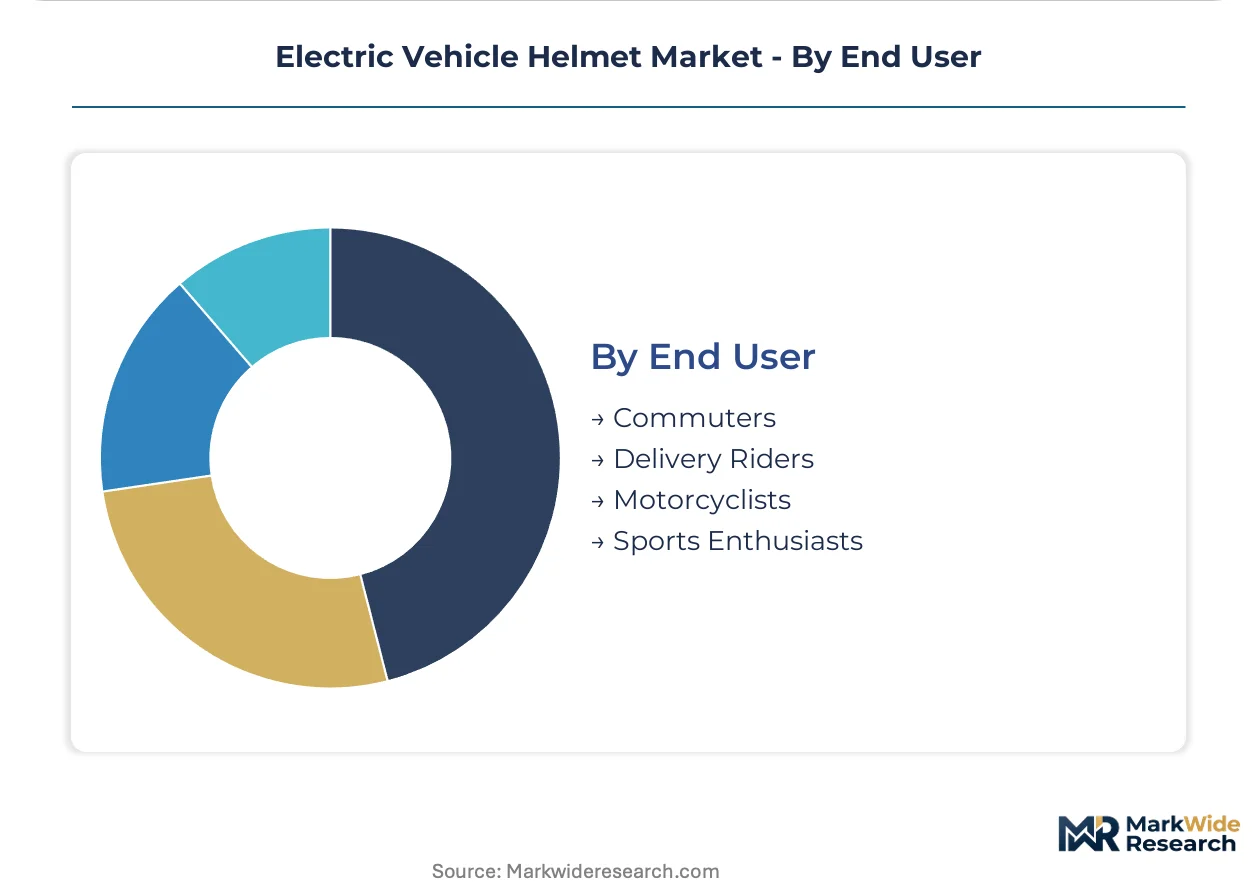
End User:
Customer type segmentation aligns procurement channels, with OEM bundling dominating commuter acquisition and direct fleet sales capturing delivery rider volume.
- Commuters:Urban electric scooter riders in Bangalore and Delhi purchase through dealership-bundled safety packages subsidized under FAME II schemes. First-time vehicle buyers show pronounced preference for integrated helmet-vehicle transactions over aftermarket selection.
- Delivery Riders:Platform-employed logistics workers across Indonesian and Vietnamese cities generate concentrated demand for modular and full-face configurations with connectivity integration. Fleet procurement managers prioritize durability testing and electromagnetic compatibility certification.
- Motorcyclists:Recreational and touring riders specify premium protection independent of electric vehicle purchase.
- Sports Enthusiasts:Track and off-road competitors demand specialized aerodynamic and impact-management geometries.
Commuters lead volumes today; delivery riders are expanding most quickly as platform logistics scale across emerging markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Helmet production migrates toward jurisdictions with streamlined certification pathways and subsidized raw material access. The cost-of-compliance gap between ECE 22.06 jurisdictions and emerging manufacturing hubs is accelerating facility relocation decisions among mid-tier suppliers.
India
FAME II subsidies have electrified two-wheeler fleets across Mumbai, Bangalore, and Delhi, creating concentrated helmet demand from first-time EV buyers. BIS certification mandates and Motor Vehicles Act enforcement establish compliance thresholds for both imported and domestically produced headgear. Tamil Nadu and Gujarat host expanding manufacturing clusters where streamlined testing protocols reduce import dependency windows.
Germany
ECE 22.06 rotational acceleration testing protocols force redesigns of expanded polystyrene liner densities and shell geometries among suppliers accessing member states. KBA enforcement and EU General Product Safety Regulation shape baseline impact absorption requirements. Bavaria and Baden-Württemberg concentrate R&D facilities where premium full-face configurations absorb compliance-driven redesign costs.
United States
DOT FMVSS 218 standards and NHTSA oversight govern minimum performance criteria for helmets distributed through American retail channels. Recreational motorcyclists and emerging electric scooter commuters generate bifurcated demand across protection tiers. California and Texas anchor volume consumption where dealership-bundled safety packages gain traction among first-time EV adopters.
Japan
METI industrial policy and JIS standards certification create structured pathways for domestic manufacturers serving premium protection segments. Multi-ply fiber matrix design expertise concentrates within specialist engineering firms constraining R&D scaling for entrants. The Kanto region around Tokyo hosts composite materials innovation clusters where aerospace-grade carbon fiber precursor technology transfers into headgear applications.
Vietnam
Ho Chi Minh City food delivery platforms pilot fleet-wide smart-helmet deployment for real-time order coordination, generating concentrated commercial demand. Rapid urban electrification of two-wheeler fleets outpaces dedicated helmet retail infrastructure development. Southern manufacturing zones near the Mekong Delta attract assembly operations leveraging regional expanded polystyrene liner supply chains.
Electric Vehicle Helmet Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue connectivity integration and material specialization as differentiation vectors. The vendor base stratifies across three tiers: premium composite specialists, volume thermoplastic manufacturers, and smart-system integrators. Two dominant competitive moves define current positioning: backward integration into liner production to compress input costs, and strategic partnerships with electric two-wheeler OEMs for bundled distribution access.
Among Japanese specialists, Shoei Co., Ltd. and Arai Helmet, Ltd. exemplify the premium composite archetype through proprietary fiber matrix positioning. HJC Helmets anchors the volume-manufacturing tier with South Korean production scale. Bell Helmets occupies the North American distribution-focused segment with broad retail channel coverage across modular and open-face categories.
| Leading Market Players |
|---|
| Shoei Co., Ltd. |
| Arai Helmet, Ltd. |
| HJC Helmets |
| Bell Helmets |
| Schuberth GmbH |
| AGV |
| Nolan Helmets |
| Shark Helmets |
| Sena Technologies, Inc. |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in South Korea and Japan anchor supply discipline through captive liner production, compressing procurement costs while sustaining premium positioning against polycarbonate mass-market entrants. This ownership pattern insulates ECE 22.06-compliant producers from raw material volatility while forcing price competition onto import-dependent distributors.
Pricing Analysis
Distributor margin layers absorb the steepest compression as OEM bundling displaces aftermarket retail across Indian and Southeast Asian markets. Three-tier pricing structure across premium carbon fiber, standard fiberglass, and economy polycarbonate levels stratifies by certification grade and volume scale. Pricing pressure stems from Toray Industries' aerospace-grade carbon fiber oligopoly, tightening shell production economics. First-time electric vehicle buyers in subsidized purchase cohorts exhibit highest price sensitivity; fleet procurement managers prioritize electromagnetic compatibility certification over unit cost.
Supply Chain Analysis
Certification gating through ECE 22.06, BIS, and DOT FMVSS 218 standards fragments supplier access by jurisdictional testing capacity. Manufacturing concentrates in South Korea, Japan, and coastal Chinese provinces where composite precursor technology and expanded polystyrene liner molding scale coexist. Raw material dependencies center on Toray and Teijin carbon fiber precursors, polycarbonate resin feedstocks, and liner-grade polystyrene. Single-source vulnerability in aerospace-grade fiber supply creates input cost volatility. Distribution runs through electric two-wheeler OEM bundling channels and direct fleet sales to logistics platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market hinges on carbon fiber cost-down curves and fleet-digitization premiums shifting procurement toward integrated smart systems. Composite engineering scarcity and certification concentration create defendable positioning for incumbents with backward liner integration.
For Market Incumbents: Anchor premium positioning through proprietary multi-ply fiber matrix R&D and captive expanded polystyrene liner production. Deepen certification moats by accelerating electromagnetic compatibility testing ahead of EU radio equipment directive evolution. Defend against modular-design specialists by controlling chin-bar pivot mechanism durability IP. For New Entrants and Emerging Players: Enter via BIS-certified domestic manufacturing in Tamil Nadu and Gujarat to capture Indian tier-2 city demand outside OEM bundling channels. Target underpenetrated Lucknow, Indore, and Coimbatore markets through direct-to-rider online distribution with ventilation-optimized tropical configurations. Pursue 5G-V2X antenna integration partnerships with telematics providers as fleet differentiation wedge. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier fiberglass specialists lacking carbon fiber upgrade pathways or smart-system integration capabilities. Long-term viability favors aerospace-grade composite suppliers with METI or KBA certification relationships and liner production backward integration. Watch for inflection in food delivery platform fleet standardization mandates across Vietnamese and Indonesian markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Liner Production | Captive expanded polystyrene supply compresses input costs for ECE 22.06-compliant manufacturers. |
| Smart-Helmet Fleet Certification | Electromagnetic compatibility pre-qualification unlocks Ho Chi Minh City and Jakarta logistics platform procurement. |
| Carbon Fiber Precursor Partnership | Long-term Toray or Teijin supply agreements hedge aerospace-grade fiber cost volatility. |
| OEM Bundling Channel Access | FAME II-subsidized dealership integration captures first-time electric scooter buyers in Bangalore and Delhi. |
| 5G-V2X Antenna Array Development | Vehicle-to-everything module integration creates white space for low-latency connected rider equipment. |
Research Methodology
Bottom-up commuter and delivery rider demand modeling reconciled against top-down helmet production and carbon fiber supply tracking forms the analytical core. Primary interviews with composite engineering directors, BIS certification laboratory managers, fleet procurement officers at Southeast Asian logistics platforms, and electric two-wheeler OEM product planners combined with secondary validation against ECE 22.06 testing protocols, FAME II subsidy disbursement records, and Toray Industries precursor supply disclosures. Triangulation across stakeholder inputs and regulatory filings grounds volume estimates.
Historical trendline analysis of polycarbonate-to-carbon fiber material transitions and Bluetooth integration adoption curves informed projection frameworks. Segmentation modeling spanned product type, material grade, connectivity feature, and end-user archetype across the projection horizon. CAGRs derived from weighted average of material cost trajectories, certification timeline compression, and fleet digitization penetration curves. Industry-specific inputs included ECE 22.06 redesign cycle timing and BIS testing protocol streamlining effects.
Inputs from KBA enforcement records and METI industrial policy filings were available through the study window; gaps in real-time fleet procurement contract terms introduce uncertainty bands around commercial segment forecasts. A model refresh is warranted upon material change in EU radio equipment directive implementation timelines or FAME II subsidy extension decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electric Vehicles
US Automotive High Performance Electric Vehicle Market
Electric Vehicles
Right Hand Drive Electric Vehicle Market
Electric Vehicles
Solar Vehicle Market
Electric Vehicles
Electric Vehicle Air Conditioning Market
Electric Vehicles
New Energy Vehicle (NEV) Market
Electric Vehicles
Germany Electric Bus Battery Pack Market
Electric Vehicles
Electric Axle Drive Systems Market
Electric Vehicles
India Solar E-Bike Market
Electric Vehicles
Electric Vehicle Reducer Market
Electric Vehicles
Compact E-Scooter Market
Electric Vehicles
Commercial Electric Vehicle Dynamic Braking Resistors Market
Electric Vehicles
Belgium E-Bike Market
Electric Vehicles
Vietnam E-Bike Market
Electric Vehicles
UK Electric Commercial Vehicle Battery Pack Market
Electric Vehicles
Electric Vehicle Sound Generators Market
Electric Vehicles
China Electric Bus Market